
 Dietary Supplements Market | 2026-2036
Dietary Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Dietary Supplements Market Intelligence
Modular subscription bundling is recalibrating how consumers assemble personalized supplement regimens from discrete single-ingredient SKUs. Nestlé Health Science leverages its pharmaceutical-grade manufacturing infrastructure to anchor premium positioning in medical nutrition channels. Amway Corp sustains its direct-selling network as a proprietary distribution moat across Asian markets. NOW Foods differentiates through vertical control over raw material testing and in-house capsule production.
Dietary supplements comprise biologically active compounds—vitamins, minerals, botanical extracts, and live microbial cultures—formulated in standardized doses to augment nutritional intake beyond conventional food sources. These products undergo tableting, encapsulation, or lyophilization to achieve specified dissolution profiles and shelf-stability parameters for oral delivery. Vitamins and probiotics capture the dominant margin pools due to recurring purchase frequency and clinical validation investments, while herbal extracts occupy faster-growth niches as adaptogenic positioning gains traction in stress-management applications. Sports Performance and Immunity applications lead volume expansion as post-exercise recovery and preventive health protocols drive repeat buying behavior across athlete and general-public end-user segments.
The FDA enforces Current Good Manufacturing Practice regulations and New Dietary Ingredient notifications that elevate compliance costs and barrier thresholds for market entry. EFSA's health claims authorization process in Europe restricts permissible marketing language and necessitates substantiation dossiers for functional positioning. China's SAMR and NMPA coordinate dual-track oversight of both traditional health food filings and novel ingredient registrations, creating a bifurcated approval pathway. Stakeholders must monitor evolving substantiation requirements across jurisdictions to determine whether to consolidate regulatory affairs capabilities or pursue geography-specific product line segmentation.
Market Dynamics
Modular subscription bundling is compressing traditional retail shelf space as fitness enthusiasts assemble personalized regimens from discrete single-ingredient SKUs. The FDA's updated New Dietary Ingredient notification requirements are elevating compliance thresholds for domestic manufacturers while China's SAMR tightens dual-track oversight of traditional health food filings.
Growth Catalysts
- Preventive health protocols:Post-exercise recovery regimens among amateur athletes drive repeat purchase frequency for protein and adaptogenic formulations.
- EFSA health claims authorization:Substantiation dossiers for functional positioning enable premium pricing in European medical nutrition channels.
- China's tier-one city concentration:Traditional medicine-informed supplement regimens blend with modern wellness retail formats in Beijing and Shanghai.
Market Restraints
- Raw material testing costs:Vertical control over botanical sourcing requires captive laboratory infrastructure that mid-tier entrants cannot replicate.
- Dual carbon goals compliance:China's MEE mandates on manufacturing emissions intensity compress margin structures for domestic contract manufacturers.
- Lyophilization equipment scarcity:Probiotic shelf-stability parameters demand specialized freeze-drying capacity concentrated among pharmaceutical-grade facilities.
Strategic Opportunities
- Stress-management adaptogens:Ashwagandha and rhodiola positioning in herbal extracts captures faster-growth niches as consumer anxiety indicators rise.
- Direct-to-consumer subscription bundles:Sports nutrition brands bypass pharmacy retail markups through proprietary app-based replenishment algorithms.
- SAMR novel ingredient registrations:Traditional medicine derivatives gain accelerated approval pathways distinct from conventional health food filings.
Industry Challenges
- Clinical validation talent scarcity:Nutraceutical firms compete with pharmaceutical recruiters for biostatisticians capable of designing substantiation trials.
- Legacy encapsulation line retrofitting:Vegetarian capsule demand forces capital allocation toward starch-based shell production equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dietary Supplements Market |
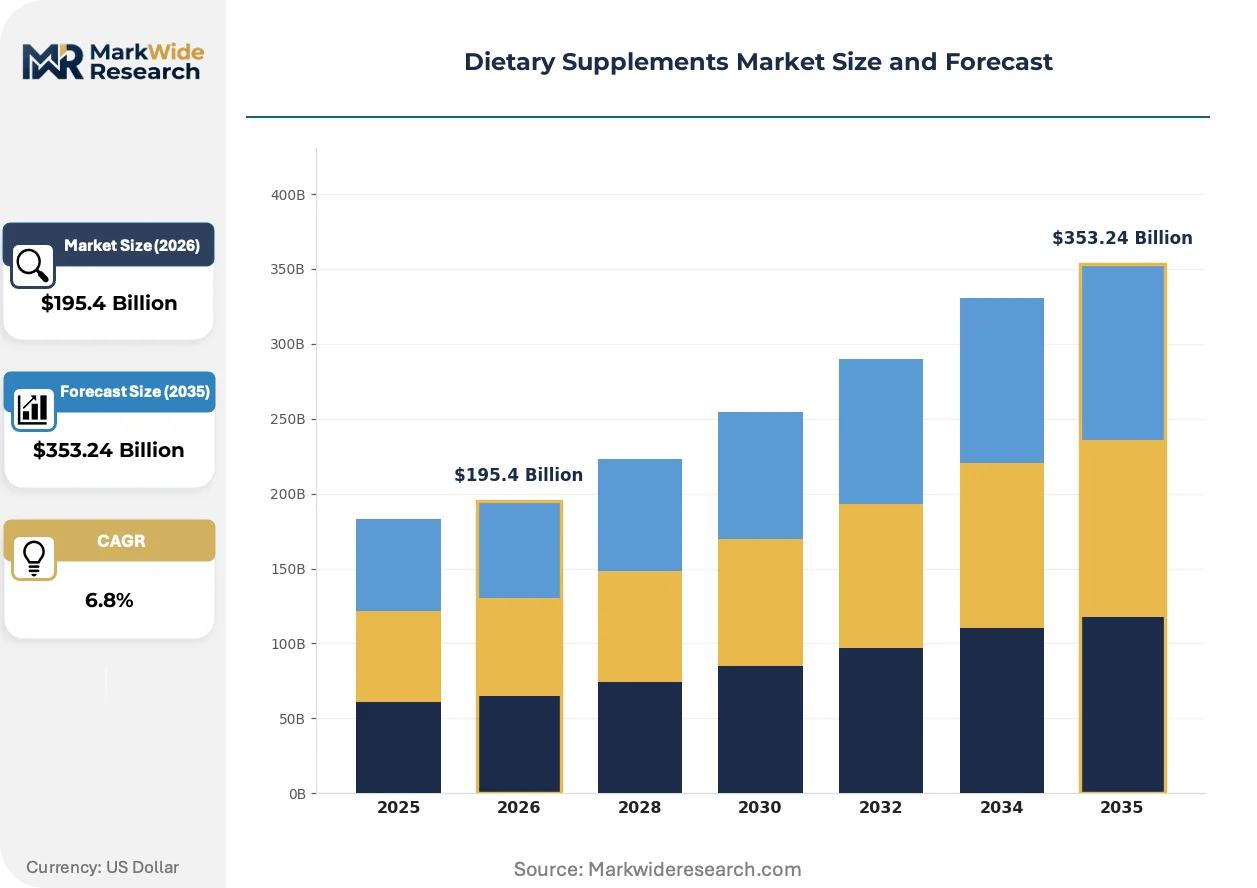
| Market Size in 2026 | $195.4 Billion |
| Market Size in 2035 | $353.24 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Extracts, Probiotics Application: Nutrition, Weight Management, Immunity, Sports Performance Form: Tablets, Powders, Capsules, Liquids End User: Athletes, General Public, Seniors, Women |
| Companies Covered | Nestlé Health Science, Abbott Laboratories, Amway Corp, Herbalife Nutrition Ltd, Glanbia PLC, Bayer AG, GNC Holdings, Otsuka Holdings Co., Ltd, NOW Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dietary Supplements Market Strategic Shifts & Innovations
Live microbial culture stabilization technologies are compressing cold-chain dependency while AI-driven personalization engines reshape how consumers discover ingredient combinations. Regulatory divergence between FDA notification requirements and EFSA health claims processes forces product line segmentation.
Microencapsulation via spray-drying and fluid-bed coating is electrifying probiotic viability extension, enabling ambient distribution for strains previously requiring refrigeration. Functional beverage manufacturers adopt these stabilized cultures at accelerated pace, collapsing the traditional dairy-dominant delivery format. Shelf-stable synbiotic formulations are electrifying new channel access for direct-to-consumer brands previously excluded from pharmacy cold cases.
EFSA's health claims authorization process restricts permissible marketing language for botanical extracts across European member states. Substantiation dossiers now require human intervention studies rather than mechanistic data, extending time-to-market for adaptogenic positioning. German and French regulators enforce divergent interpretation timelines, fragmenting launch synchronization for pan-European portfolios.
Subscription-based replenishment algorithms now displace pharmacy retail as the primary discovery channel for millennial and Gen-Z supplement users. Fitness app integrations bundle biometric data with personalized micronutrient recommendations, capturing purchase intent at the point of workout completion. This behavior concentrates visibly in China's tier-one cities where WeChat mini-programs dominate wellness commerce.
Dietary Supplements Market Segmentation
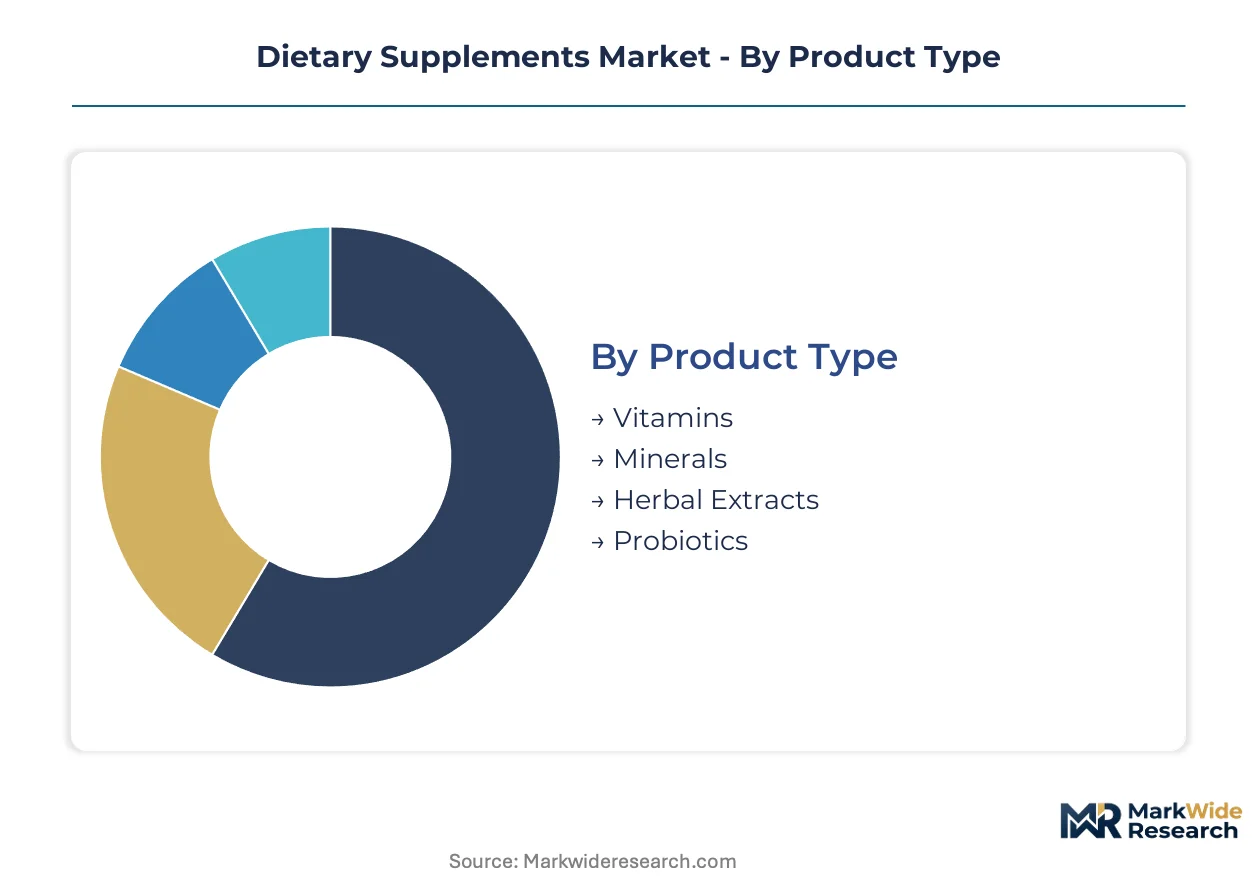
Segmentation in dietary supplements reveals divergent margin structures and channel strategies across product chemistry and consumer physiology. Manufacturers calibrate formulation investments and regulatory dossier priorities based on which segments command recurring purchase frequency versus one-time trial behavior.
Product Type:
Buyers in this category separate by clinical validation requirements and raw material sourcing complexity.
- Vitamins:Synthetic and bio-identical compounds deliver standardized potencies for micronutrient gap-filling. Demand concentrates among amateur athletes in China's tier-one cities where post-exercise recovery protocols drive monthly replenishment cycles. FDA Current Good Manufacturing Practice compliance elevates barrier thresholds for synthetic vitamin entrants.
- Probiotics:Live microbial cultures require lyophilization for shelf-stability and specified CFU counts at expiration. Sports nutrition brands in direct-to-consumer channels capture repeat purchases through app-based replenishment algorithms tied to workout completion data. Lyophilization equipment scarcity concentrates production among pharmaceutical-grade facilities.
- Minerals:Chelated and inorganic salt forms address bioavailability variation across absorption pathways.
- Herbal Extracts:Botanical concentrates with standardized marker compounds serve adaptogenic and traditional medicine applications.
Volume sits with Vitamins; growth tilts toward Probiotics.
Application:
Application segments diverge by purchase trigger — acute symptom response versus preventive habit formation.
- Sports Performance:Protein, creatine, and adaptogenic formulations target post-exercise recovery and power output optimization. Demand concentrates among subscription-bundle users assembling personalized regimens from discrete single-ingredient SKUs. EFSA health claims authorization enables premium positioning in European medical nutrition channels.
- Immunity:Vitamin C, D, zinc, and botanical combinations address seasonal prevention protocols. China's SAMR dual-track oversight of traditional health food filings creates bifurcated approval pathways for elderberry and astragalus derivatives. SAMR novel ingredient registrations accelerate for traditional medicine derivatives.
- Nutrition:General wellness formulations address baseline micronutrient adequacy across demographic cohorts.
- Weight Management:Fiber, protein, and thermogenic compounds target satiety and metabolic support claims.
Revenue concentrates in Sports Performance; steepest expansion trajectory belongs to Immunity.
Form:
Form selection reflects swallowability preferences, dose precision needs, and stability requirements for active compounds.
- Capsules:Gelatin and starch-based shells enable taste-masking and controlled release kinetics. Vegetarian capsule demand forces capital allocation toward starch-based shell production equipment among legacy manufacturers. NOW Foods differentiates through in-house capsule production and vertical control over raw material testing.
- Powders:Bulk formats allow dose titration and flavor customization in functional beverages. Functional beverage manufacturers adopt microencapsulated stabilized cultures at accelerated pace, collapsing dairy-dominant delivery formats. Microencapsulation via spray-drying extends probiotic viability for ambient distribution.
- Tablets:Compressed formulations achieve specified dissolution profiles through granulation and coating technologies.
- Liquids:Solutions and suspensions address pediatric and geriatric swallowability constraints.
Manufacturing complexity peaks with Capsules; channel expansion favors Powders.
End User:
End user segments separate by information sourcing behavior and price elasticity for substantiated claims.
- Athletes:Amateur and professional competitors prioritize batch-tested formulations with banned-substance certification. Fitness app integrations bundle biometric data with personalized micronutrient recommendations, capturing purchase intent at workout completion. Modular subscription bundling compresses traditional pharmacy retail shelf space for this cohort.
- General Public:Broad demographic seeking preventive health protocols without specific performance targets. China's tier-one cities concentrate demand where traditional medicine-informed regimens blend with modern wellness retail formats. WeChat mini-programs dominate discovery and replenishment for millennial and Gen-Z users.
- Seniors:Aging cohorts prioritize bone health, cognitive support, and polypharmacy interaction safety.
- Women:Life-stage specific needs span prenatal, perimenopausal, and beauty-from-within positioning.
Subscription penetration is deepest among Athletes; demographic scale favors General Public.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in pharmaceutical-grade facilities across Switzerland and Germany, while consumption concentrates in China's tier-one cities and the United States where fitness-oriented subscription models drive replenishment velocity.
United States
Fitness enthusiasts assemble personalized regimens through direct-to-consumer subscription bundles, displacing traditional pharmacy retail. FDA Current Good Manufacturing Practice regulations and updated New Dietary Ingredient notification requirements elevate compliance costs for domestic entrants. Greater Boston anchors contract manufacturing for lyophilized probiotics, with pharmaceutical-grade facilities serving both sports nutrition and medical nutrition channels.
China
Traditional medicine-informed supplement regimens blend with modern wellness retail formats in Beijing and Shanghai, where WeChat mini-programs dominate discovery. SAMR and NMPA coordinate dual-track oversight of health food filings and novel ingredient registrations, creating bifurcated approval pathways. The Yangtze River Delta concentrates pharmaceutical-grade manufacturing capacity serving both domestic demand and export markets.
Germany
EFSA health claims authorization enables premium positioning in medical nutrition channels, with substantiation dossiers requiring human intervention studies. German regulators enforce interpretation timelines that diverge from French counterparts, fragmenting pan-European launch synchronization. Bavaria hosts encapsulation equipment manufacturers retrofitting legacy lines toward starch-based vegetarian capsule production.
Japan
Aging demographics drive demand for bone health and cognitive support formulations among seniors prioritizing polypharmacy interaction safety. PMDA oversight maintains stringent stability parameters for live microbial cultures. The Kanto region around Tokyo concentrates functional beverage manufacturing adopting microencapsulated probiotics for ambient distribution.
India
FSSAI regulations govern traditional Ayurvedic derivative positioning alongside modern supplement formats in urban wellness retail. CDSCO oversight of novel ingredient registrations accelerates for botanical extracts with established traditional use documentation. Maharashtra and Gujarat host contract manufacturers serving both domestic tier-one city demand and export markets to the Middle East.
Dietary Supplements Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Nestlé Health Science and Abbott Laboratories anchor the medical nutrition channel through pharmaceutical-grade manufacturing infrastructure, while direct-selling networks and subscription-native brands capture fitness-oriented consumers. Three archetypes dominate: conglomerate health science divisions, direct-selling multinationals with Asian network density, and vertically integrated pure-plays controlling raw material testing. Competitive moves concentrate on regulatory dossier consolidation across FDA, EFSA, and SAMR jurisdictions, plus captive supply integration for botanical sourcing.
Among conglomerate health science divisions, Nestlé Health Science and Abbott Laboratories exemplify pharmaceutical-grade manufacturing anchoring. Amway Corp occupies a position within the direct-selling archetype, sustaining proprietary distribution networks across Asian markets. NOW Foods represents the vertically integrated pure-play model, with in-house capsule production and upstream control over raw material testing differentiating its positioning.
| Leading Market Players |
|---|
| Nestlé Health Science |
| Abbott Laboratories |
| Amway Corp |
| Herbalife Nutrition Ltd |
| Glanbia PLC |
| Bayer AG |
| GNC Holdings |
| Otsuka Holdings Co., Ltd |
| NOW Foods |
| Others |
Cost & Logistics Intelligence
Biostatistician talent concentration in the Greater Boston corridor connects labor-cost differentials to pricing-tier spreads, as pharmaceutical-grade facilities compete for clinical validation expertise against Big Pharma recruiters. This workforce scarcity compresses margins for mid-tier entrants unable to fund captive laboratory infrastructure while enabling premium capture among vertically integrated pure-plays.
Pricing Analysis
Cost-down pressure on standard-grade vitamin formulations accelerates because China's MEE mandates on manufacturing emissions intensity compress margin structures for domestic contract manufacturers. Three-tier pricing structure across pharmaceutical-grade, certified-standard, and economy levels separates products by FDA Current Good Manufacturing Practice compliance tier and batch-tested certification status. Subscription-native brands with proprietary app-based replenishment algorithms command least price sensitivity among fitness enthusiasts, while general-public consumers in pharmacy retail channels exhibit highest price elasticity.
Supply Chain Analysis
Direct-to-consumer channels handle fitness enthusiast demand through proprietary replenishment algorithms, while pharmacy retail and medical nutrition channels serve clinical validation requirements. Raw material sourcing draws from India's botanical cultivation regions, China's synthetic vitamin precursor facilities, and Switzerland's pharmaceutical-grade excipient manufacturers. Lyophilization equipment scarcity creates single-source vulnerability for probiotic shelf-stability capacity concentrated among Greater Boston and Yangtze River Delta facilities. Distribution runs through direct-selling networks in Asian markets, subscription platforms in the United States, and WeChat mini-programs in China's tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where upstream control over raw material testing and in-house capsule production separates margin leaders from contract-manufacturing dependents.
For Market Incumbents: Hedge against FDA New Dietary Ingredient notification escalation by consolidating regulatory affairs capabilities across FDA, EFSA, and SAMR jurisdictions into unified dossier teams. Deepen backward integration into botanical sourcing through captive laboratory infrastructure that mid-tier entrants cannot replicate, defending against pure-play specialists with starch-based vegetarian capsule production retrofitting. For New Entrants and Emerging Players: Direct-to-consumer subscription bundles offer the most penetrable route for bypassing pharmacy retail markups and capturing fitness enthusiast replenishment velocity. Target stress-management adaptogens in herbal extracts as the fastest-growth niche, leveraging AI-driven personalization engines for ingredient combination discovery without legacy encapsulation line capital requirements. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated pure-plays given captive supply integration for botanical sourcing and in-house production of pharmaceutical-grade formulations. Long-term viability favors archetypes controlling raw material testing infrastructure over contract-manufacturing dependents exposed to lyophilization equipment scarcity. Watch SAMR novel ingredient registration acceleration for traditional medicine derivatives as inflection signal for China market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Consolidation | Unified FDA, EFSA, and SAMR compliance teams reduce time-to-market for novel botanical extracts. |
| Backward Integration into Botanical Sourcing | Captive laboratory infrastructure for raw material testing replicates NOW Foods' differentiation model. |
| Direct-to-Consumer Subscription Launch | Proprietary app-based replenishment algorithms bypass pharmacy retail markups for fitness enthusiasts. |
| Vegetarian Capsule Production Retrofit | Starch-based shell equipment addresses legacy encapsulation line obsolescence amid sustainability demand. |
| AI-Driven Personalization Engine | Biometric data integration from fitness apps captures purchase intent at workout completion moments. |
Research Approach
FDA filings, EFSA health claims authorization databases, and SAMR health food registration records formed the secondary backbone, cross-referenced with customs data on botanical extract trade flows and pharmaceutical-grade facility certifications. Primary interviews with regulatory affairs directors at dietary supplement manufacturers, procurement leads at sports nutrition brands, and formulary managers at medical nutrition channels validated secondary findings. Bottom-up SKU-level demand modeling and top-down market sizing triangulated volume and value outputs across the analysis window.
Historical trendline analysis of vitamin, probiotic, and herbal extract pricing trajectories informed growth rate derivation, with segmentation modeling across product chemistry, application use case, delivery form, and end-user physiology. The analytical framework incorporated regulatory approval pathway timelines, lyophilization capacity utilization rates, and subscription penetration velocity by geography throughout the forecast period. CAGRs reflect compound trajectory assumptions calibrated against clinical validation investment cycles and traditional medicine derivative registration momentum.
The model holds under stable regulatory substantiation requirements; deviation in FDA New Dietary Ingredient notification enforcement intensity or SAMR dual-track oversight bifurcation would shift competitive positioning toward geography-specific product line segmentation. Forecasts reflect assumptions on lyophilization equipment capacity expansion, AI personalization engine adoption curves, and China tier-one city wellness retail format evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
South America Nutraceuticals Market
Nutritional Supplements
Italy Whey Protein Market
Nutritional Supplements
Europe Nutritional Beverages Market
Nutritional Supplements
India Personalized Nutrition Market
Nutritional Supplements
Krill Oil Phospholipid Market
Nutritional Supplements
Health Supplements Market
Nutritional Supplements
Isoleucine Market
Nutritional Supplements
Nutrition Therapy Market
Nutritional Supplements
Europe Beta-Glucan Market
Nutritional Supplements
Hair Growth Supplements Market
Nutritional Supplements
Red Yeast Rice Market
Nutritional Supplements
Middle East and Africa Amino Acid in Dietary Supplements Market
Nutritional Supplements
Native Whey Protein Market
Nutritional Supplements
Fatty Acid Supplements Market
Nutritional Supplements
Health Supplementary Food OEM and ODM Market
Nutritional Supplements
Natural Vitamin E Product Market