
 Vegan Baking Ingredients Market | 2026-2036
Vegan Baking Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Baking Ingredients Market Outlook
Commercial bakeries and foodservice operators is reorganizing demand away from traditional home bakers as the dominant buyer archetype in the vegan baking ingredients space. Cargill leverages its global supply chain infrastructure to secure consistent availability of specialty flours and plant-based oils across multiple continents. Kerry Group differentiates through R&D intensity in clean-label egg replacer formulations, sustaining technical partnerships with European artisan bakeries. Bakels Group anchors its competitive position in the Asia-Pacific region through localized production facilities and region-specific product portfolios.
Vegan baking ingredients comprise plant-derived flours, sweeteners, lipid systems, and functional binders formulated to replicate the structural and sensory properties of conventional baking components without animal-derived inputs. Egg replacers typically incorporate protein isolates from chickpea or mung bean combined with hydrocolloids to achieve emulsification and aeration performance comparable to whole eggs in cake and pastry applications. The ingredient type dimension shows egg replacers capturing the fastest growth trajectory as technical performance gaps narrow against conventional eggs, while flours and oils constitute the mature volume base where margin compression is most acute. Within application segments, breads and cakes absorb the majority of current ingredient volumes, though cookies represent an emerging margin pool as premium positioned vegan cookie brands command shelf-space premiums in specialty retail channels.
The EU Green Deal and REACH frameworks in Europe impose stringent sustainability and chemical safety requirements on food ingredient manufacturing, compelling suppliers to document carbon footprints and eliminate palm oil derivatives from certified product lines. In the United States, FDA labeling standards for plant-based claims and USDA organic certification requirements create compliance thresholds that filter market access for smaller ingredient producers. Stakeholders must monitor evolving regulatory definitions of clean-label and vegan claims across jurisdictions, as divergent standards threaten to fragment formulation strategies and complicate cross-border product registration for multinational ingredient portfolios.
Market Dynamics
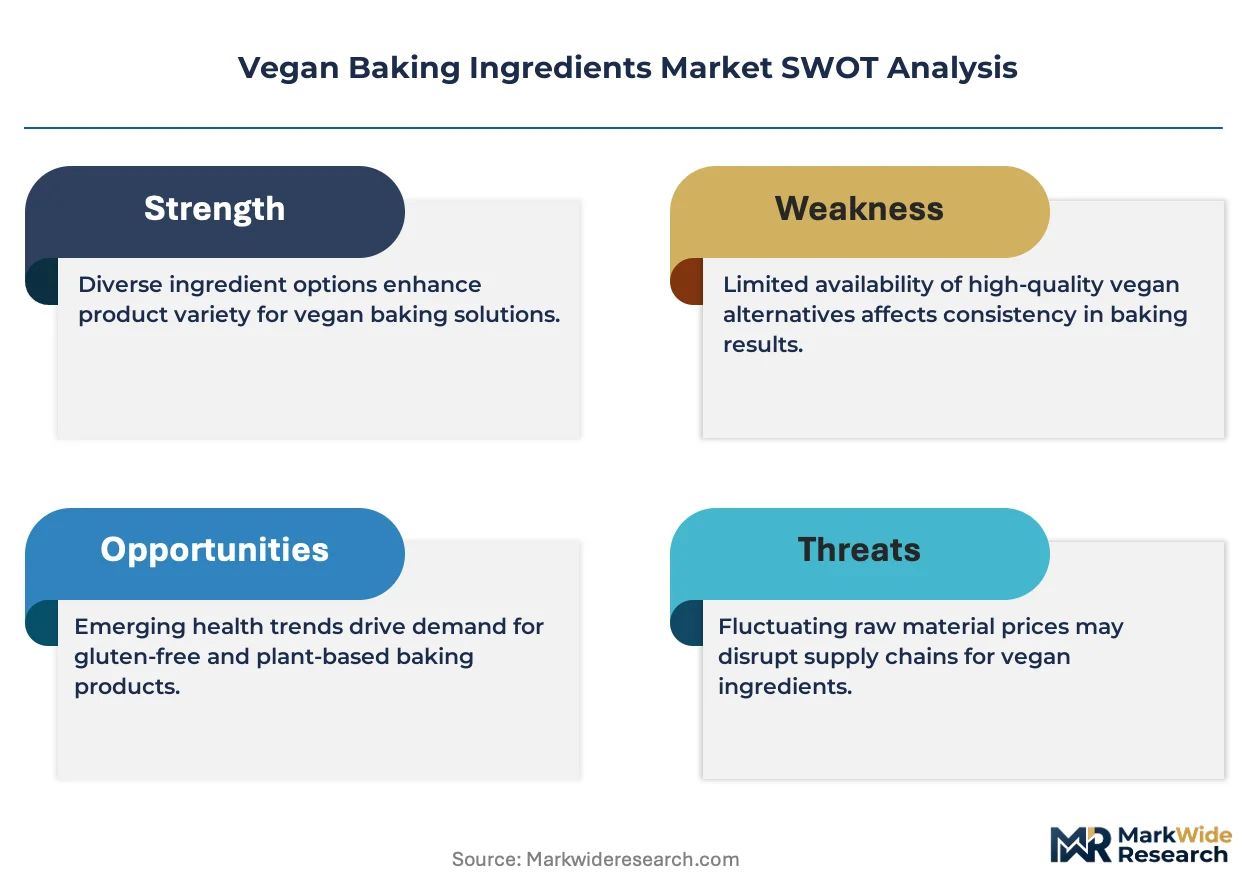
Artisan bakeries and commercial foodservice operations are reorganizing procurement patterns around plant-based egg replacers and dairy-free shortenings as EU emissions standards tighten under the F-Gas Regulation and Green Deal frameworks.
Growth Catalysts
- EU Green Deal mandates:The EU Green Deal and F-Gas Regulation compel food manufacturers to document carbon footprints and eliminate palm oil derivatives from certified product lines.
- Commercial foodservice pivot:Bakeries supplying retail chains across Western Europe accelerate purchases of functional binders and lipid systems to meet vegan certification requirements.
- Berlin-Munich cluster density:Germany hosts concentrated networks of vegan-certified commercial bakeries that anchor regional supply contracts and technical partnerships.
Market Restraints
- Input cost volatility:Chickpea and mung bean protein isolates face price instability tied to agricultural yield fluctuations and climate-driven crop stress.
- Technical performance gaps:Hydrocolloid-based aeration systems in high-moisture cake applications still underperform conventional eggs on volume retention and crumb structure.
- Regulatory fragmentation:Divergent FDA and EFSA definitions of clean-label and vegan claims complicate cross-border product registration for multinational portfolios.
Strategic Opportunities
- Cookie segment premiumization:Specialty retail channels allocate expanded shelf space to positioned vegan cookie brands, creating margin pools above commoditized bread and cake ingredients.
- Clean-label egg replacer convergence:Protein isolate and hydrocolloid formulation advances narrow performance differentials against conventional eggs in pastry applications.
- Asia-Pacific localization:Region-specific production facilities and product portfolios address underpenetrated demand in artisan bakery segments outside established Western European markets.
Industry Challenges
- Formulation talent scarcity:Food science expertise bridging plant protein functionality and traditional baking rheology remains concentrated at specialized R&D centers.
- REACH compliance timelines:Chemical safety documentation requirements for novel hydrocolloids extend product development cycles and delay market entry.
- Legacy equipment incompatibility:Existing bakery production lines require retrofitting to handle altered hydration profiles and mixing parameters of plant-based lipid systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Baking Ingredients Market |
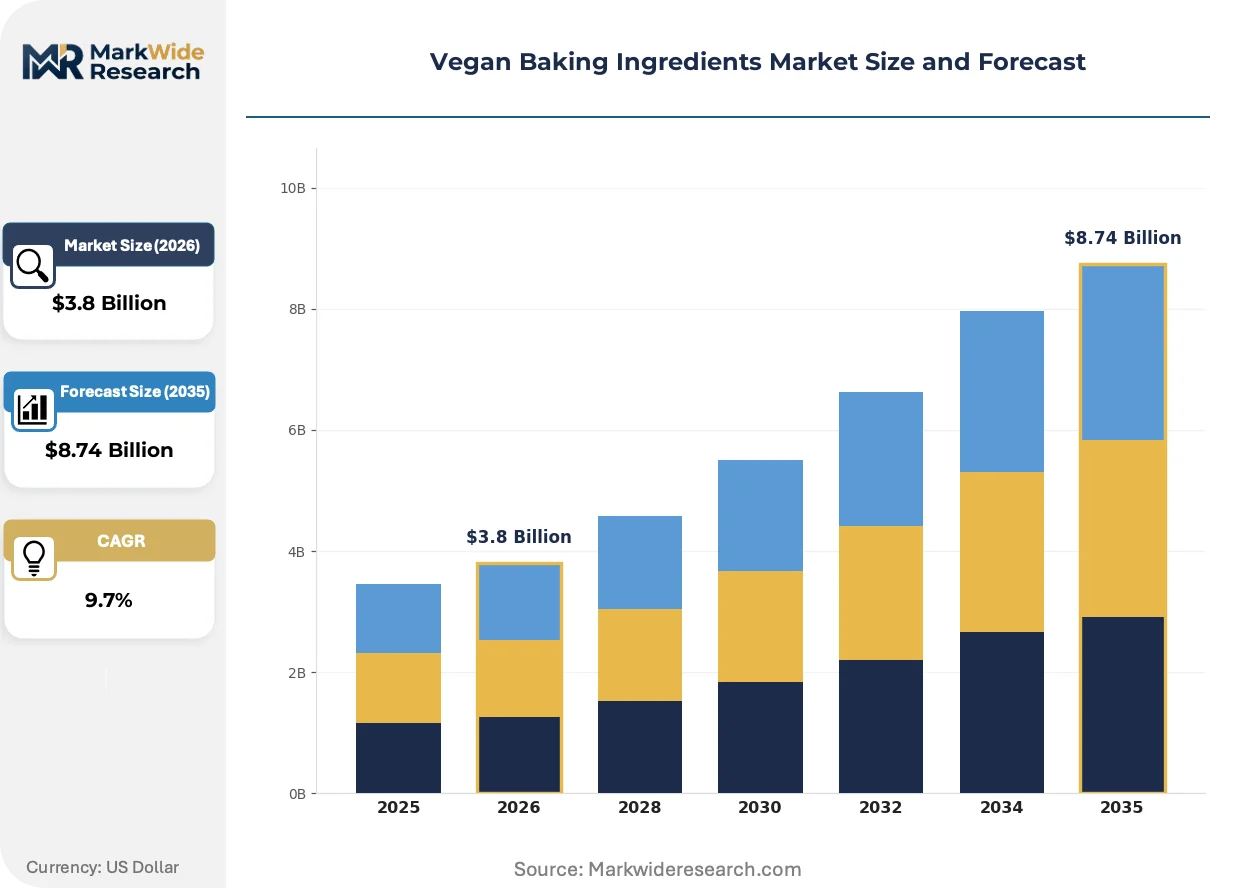
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Flours, Sugars, Egg Replacers, Oils Application: Breads, Cakes, Cookies, Pastries Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers Consumer Type: Health-Conscious Consumers, Vegans, Bakers, Restaurants |
| Companies Covered | Cargill, Associated British Foods, Ingredion Incorporated, Archer Daniels Midland Company, Dawn Food Products, Tate & Lyle, Bakels Group, Kerry Group, IFF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Baking Ingredients Market Strategic Shifts
Ingredient functionality is splitting along performance-grade lines as technical specifications diverge between artisan craft applications and industrial-scale foodservice production.
Precision fermentation-derived proteins are bifurcating the egg replacer category. These biomolecules replicate ovalbumin's gelation and foam-stabilizing properties at molecular fidelity. Artisan bakeries in Germany and France adopt them for premium patisserie lines, while industrial manufacturers delay conversion pending cost curve movement. The technology is bifurcating supplier tiers into performance-certified premium channels and commodity hydrocolloid segments.
REACH chemical safety frameworks and the EU Green Deal's carbon accounting requirements impose documentation burdens on ingredient manufacturers. Suppliers must eliminate unsustainable palm oil derivatives from certified product lines to maintain market access. European artisan bakeries and retail chain suppliers face the steepest compliance costs, driving consolidation toward vertically integrated ingredient portfolios with captive sustainability certification.
Buying committees at commercial bakery chains now mandate vegan certification as a procurement gate, displacing ingredient-by-ingredient substitution approaches. This compresses supplier qualification timelines and elevates technical partnership expectations. The pattern concentrates most visibly in Germany, where Berlin-based bakery cooperatives supply retail chains across Western Europe with unified certification standards.
Vegan Baking Ingredients Market Segmentation
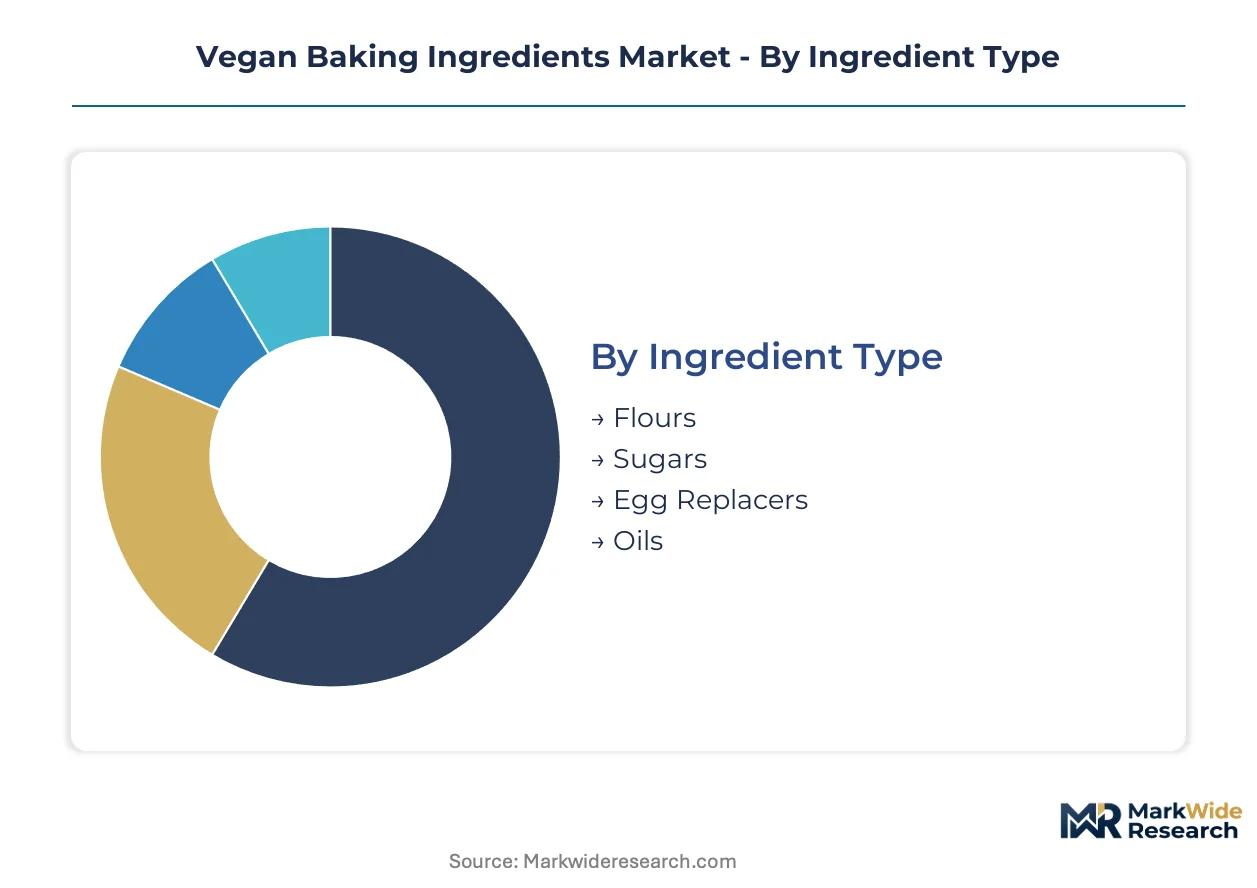
Ingredient categorization in vegan baking reflects divergent regulatory pressures across jurisdictions. REACH documentation requirements and EU Green Deal carbon accounting favor suppliers with vertically integrated certification systems, while FDA labeling standards in the United States filter market access for specialized producers.
Ingredient Type:
REACH chemical safety frameworks and the EU Green Deal's emissions standards impose distinct compliance burdens on each ingredient class, reshaping supplier qualification timelines and documentation requirements for multinational portfolios.
- Flours:Wheat, oat, and rice flours form the volume foundation of vegan baking formulations. Specialty milling operations in Germany and France now document carbon footprints to satisfy EU Green Deal procurement mandates from Berlin-based bakery cooperatives.
- Sugars:Cane, beet, and coconut sugars provide sweetness and browning reactions. Demand concentrates among artisan bakeries in Munich supplying retail chains across Western Europe, where clean-label certification gates market access.
- Egg Replacers:Protein isolates from chickpea or mung bean combined with hydrocolloids replicate emulsification and aeration properties. Precision fermentation-derived alternatives are gaining share fastest in premium patisserie segments as technical performance gaps narrow against conventional eggs.
- Oils:Palm-free shortenings and plant-based lipid systems face acute margin compression. Suppliers must eliminate unsustainable palm oil derivatives to maintain certification under EU Green Deal frameworks.
Flours handle the majority of throughput; egg replacers are expanding most quickly on share as commercial foodservice operations accelerate procurement of functional binders.
Application:
Margin concentration varies sharply across end-use segments, with premium-positioned categories commanding shelf-space premiums in specialty retail channels.
- Breads:High-volume applications absorb mature ingredient flows with compressed margins. Industrial manufacturers in Germany supply standardized vegan-certified loaves to retail chains under unified procurement standards.
- Cakes:High-moisture formulations demand precise aeration from hydrocolloid systems. Technical performance gaps in volume retention persist, delaying conversion from conventional eggs in mass-market production lines.
- Cookies:Premium vegan cookie brands capture expanded shelf space in specialty retail channels. This segment offers the steepest margin pools above commoditized bread and cake ingredients.
- Pastries:Laminated dough applications require specialized lipid systems with precise melting profiles. Artisan bakeries in France adopt precision fermentation-derived proteins for premium product lines.
Breads dominate current volume absorption; cookies are climbing the fastest as buying committees at commercial bakery chains mandate vegan certification.
Distribution Channel:
Channel selection determines supplier qualification intensity, with commercial bakery chains imposing unified certification standards that compress onboarding timelines.
- Online Retail:Direct-to-consumer platforms serve health-conscious home bakers with specialized ingredient kits. EFSA and FDA labeling divergence complicates cross-border product registration for direct-ship formulations.
- Supermarkets:Mass retail chains in Germany anchor regional supply contracts through centralized procurement. Vegan certification now operates as a procurement gate, displacing ingredient-by-ingredient substitution approaches.
- Specialty Stores:Curated channels allocate premium shelf space to positioned vegan cookie and pastry brands. These outlets prioritize suppliers with captive sustainability certification under REACH frameworks.
- Wholesalers:Foodservice distributors supply restaurant and commercial bakery operations across Western Europe. Technical partnership expectations elevate as buyers demand documented carbon footprints and palm-free supply chains.
Supermarkets and wholesalers handle the majority of throughput; specialty stores are gaining share fastest as premiumization concentrates in curated retail formats.
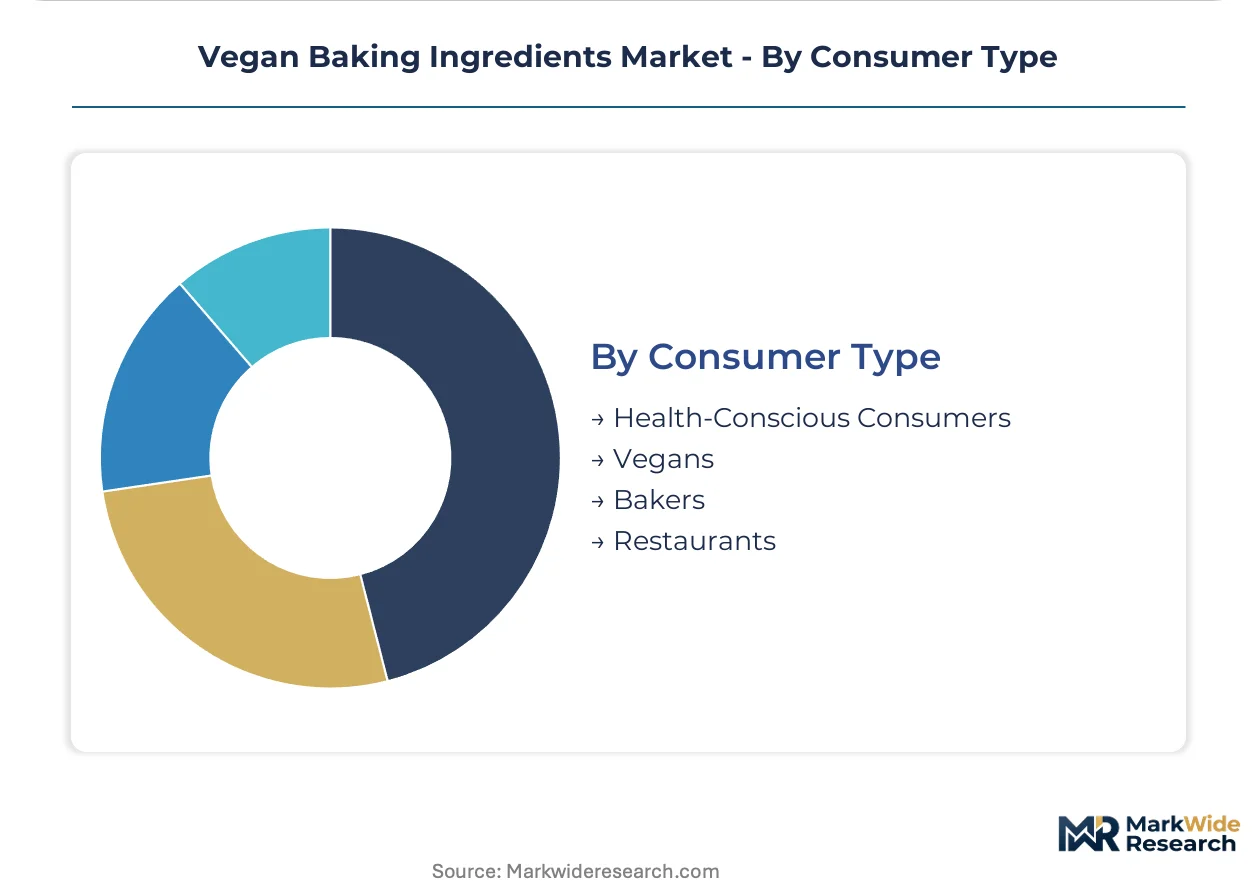
Consumer Type:
Demand reorganization favors commercial operators over traditional home bakers, with procurement patterns splitting along certification and scale requirements.
- Health-Conscious Consumers:Home bakers seeking clean-label alternatives drive online retail volumes. FDA organic certification requirements filter product access for smaller ingredient producers in the United States.
- Vegans:Ethical consumption mandates shape purchasing decisions across all channels. EU Green Deal frameworks align with this segment's sustainability priorities, accelerating adoption of certified product lines.
- Bakers:Artisan and commercial bakery operations constitute the reorganizing demand center. REACH compliance timelines for novel hydrocolloids extend product development cycles for this technical buyer segment.
- Restaurants:Foodservice operators accelerate purchases of plant-based egg replacers and dairy-free shortenings. Legacy equipment incompatibility requires retrofitting to handle altered hydration profiles of plant-based lipid systems.
Bakers and restaurants handle the majority of throughput; vegans are expanding most quickly as ethical consumption aligns with tightening regulatory certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites Western Europe's dominance in plant-based ingredient distribution, while the Yangtze River Delta's integrated food processing zones anchor Asian supply consolidation.
Germany
Berlin-based bakery cooperatives and Munich artisan clusters drive procurement of certified vegan ingredients. The EU Green Deal and F-Gas Regulation compel suppliers to document carbon footprints and eliminate palm oil derivatives. The Berlin-Munich corridor hosts dense networks of vegan-certified commercial bakeries supplying retail chains across Western Europe.
United States
Commercial foodservice operators and health-conscious home bakers sustain dual demand channels for plant-based egg replacers. FDA labeling standards for plant-based claims and USDA organic certification create compliance thresholds that filter market access. California's Bay Area and Pacific Northwest metro clusters concentrate specialty retail distribution and clean-label ingredient innovation.
France
Artisan patisserie houses accelerate adoption of precision fermentation-derived proteins for premium laminated dough applications. REACH chemical safety frameworks impose documentation burdens on hydrocolloid suppliers entering the market. The Île-de-France region anchors technical partnerships between ingredient innovators and heritage bakery operations.
United Kingdom
Supermarket buying committees mandate vegan certification as a procurement gate, compressing supplier qualification timelines. EFSA definitions of clean-label claims diverge from FDA standards, complicating cross-border product registration. Greater London and the Midlands concentrate commercial bakery operations serving national retail chains.
China
Domestic food manufacturers expand plant-based lipid system production to serve underpenetrated artisan bakery segments. SAMR and GB standards govern food ingredient safety and labeling requirements. The Yangtze River Delta's integrated processing zones concentrate specialty flour milling and plant oil refining capacity.
Vegan Baking Ingredients Market Competitive Environment
Concentration sits with diversified ingredient conglomerates and specialized clean-label formulators. The supplier base organizes into tiered performance segments: global supply chain operators, regional R&D-intensive specialists, and Asia-Pacific localized producers. Strategic moves center on sustainability certification integration and precision fermentation technology licensing.
Within the diversified supply chain tier, Cargill and Archer Daniels Midland Company represent global infrastructure operators securing consistent availability of specialty flours and plant-based oils. Kerry Group and Bakels Group exemplify R&D-intensive and Asia-Pacific localized archetypes respectively. Associated British Foods and Tate & Lyle occupy positions bridging commodity scale and specialty formulation capabilities.
| Leading Market Players |
|---|
| Cargill |
| Associated British Foods |
| Ingredion Incorporated |
| Archer Daniels Midland Company |
| Dawn Food Products |
| Tate & Lyle |
| Bakels Group |
| Kerry Group |
| IFF |
| Others |
Value Chain & Pricing Dynamics
Chickpea and mung bean protein isolates displacing conventional egg inputs simultaneously redraws procurement geography toward India and Canada while compressing margin structures across hydrocolloid-blend tiers. This substitution dynamic concentrates buying power with Berlin-based bakery cooperatives and Munich artisan clusters that now mandate unified vegan certification as a procurement gate.
Pricing Analysis
Volume-discount tiering separates precision fermentation-derived egg replacers from commodity hydrocolloid blends from basic starch-based systems. Certification grade under EU Green Deal frameworks and REACH documentation intensity drive price differentiation most sharply. Cost compression in palm-free shortenings is intensifying because EU F-Gas Regulation compliance adds traceability overhead. Industrial foodservice operators exhibit highest price sensitivity; artisan patisserie houses in France show lowest.
Supply Chain Analysis
Rotterdam cold-chain infrastructure underwrites Western European distribution while Yangtze River Delta processing zones and Canadian prairie pulse-growing regions anchor upstream concentration. Specialty milling operations draw from German and French wheat belts; hydrocolloid suppliers rest on Indian seaweed harvesting and Thai tapioca processing. Single-source vulnerability concentrates in precision fermentation capacity. Distribution runs through wholesaler networks serving commercial bakery chains and specialty retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against precision fermentation-derived proteins that threaten to bifurcate supplier tiers into premium biomolecule channels and commoditized plant-protein segments.
For Market Incumbents: Fortify sustainability certification integration under EU Green Deal and REACH frameworks to lock in Berlin-Munich supply contracts. Deepen captive supply of palm-free lipid systems to neutralize margin erosion from traceability requirements. Precision fermentation licensing deals represent the critical defensive lever against technical obsolescence. For New Entrants and Emerging Players: Differentiate on clean-label egg replacer formulation for cookie segment premiumization where shelf-space premiums exceed commoditized bread ingredients. Asia-Pacific artisan bakery segments outside established Western European markets offer the most penetrable white space. Technical partnership positioning with regional milling cooperatives provides the strongest go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated ingredient portfolios with captive EU Green Deal certification and precision fermentation technology access. Long-term viability over the coming decade hinges on defensible sustainability documentation capabilities. The signal to watch is conversion cost curves for fermentation-derived proteins crossing threshold parity with plant-isolate systems.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Licensing | Secures molecular-fidelity protein supply for premium patisserie lines in France and Germany. |
| REACH Compliance Integration | Accelerates supplier qualification timelines with Berlin-based bakery cooperatives. |
| Asia-Pacific Localization | Captures underpenetrated artisan demand through Yangtze River Delta production facilities. |
| Palm-Free Supply Chain Certification | Maintains market access under EU Green Deal procurement mandates from retail chains. |
| Clean-Label R&D Partnership | Narrows technical performance gaps against conventional eggs in high-moisture cake applications. |
Study Parameters
A spread of perspectives from R&D directors at ingredient formulators, procurement leads at German commercial bakery chains, sustainability officers at multinational food conglomerates, and regulatory affairs specialists at hydrocolloid suppliers converged on the working assumptions. Primary fieldwork combined with secondary validation from EFSA guidance documents, FDA plant-based labeling standards, EU Green Deal implementation texts, and customs trade data covering specialty flour and plant protein flows. Bottom-up volume modeling and top-down value triangulation anchored the analytical framework.
Segmentation dimensions modeled include ingredient type, application end-use, distribution channel, and consumer archetype across the projection horizon. CAGRs derived from trend extrapolation of procurement volumes at Berlin-Munich bakery clusters and technical adoption curves for precision fermentation proteins. Forecast inputs incorporated REACH compliance timeline assumptions and F-Gas Regulation emissions standard phase-in schedules.
Material uncertainties — agricultural yield fluctuations in Canadian pulse crops, regulatory divergence between FDA and EFSA clean-label definitions, and precision fermentation cost curve movement — sit outside the modeled envelope. Forecasts reflect documented assumptions on substitution elasticities and certification adoption rates. Practitioners should keep alternative scenarios live as EU Green Deal enforcement intensity and precision fermentation scale-up timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Canola Oil Market
Ingredients
Lime Seed Oils Market
Ingredients
India Olive Oil Market
Ingredients
Global Autolyzed Yeast Extract Market
Ingredients
Middle East and Africa Fruit and Vegetable Ingredients Market
Ingredients
Food Amino Acids Market
Ingredients
Europe Plant Protein Ingredients Market
Ingredients
Cheese Cultures Market
Ingredients
Dry Mixes Market
Ingredients
Commercial Flour Market
Ingredients
Carica Papaya Seed Oil Market
Ingredients
Asia-Pacific Bakery Ingredients Market
Ingredients
Asia-Pacific Plant Protein Ingredients Market
Ingredients
Sunflower Meal Market
Ingredients
Bouillon Cubes Market
Ingredients
Proteose Peptone Market