
 Small Molecule Drug Discovery Market | 2026-2036
Small Molecule Drug Discovery Market Size, Share, and Industry Trends Forecast 2026-2036
Small Molecule Drug Discovery Market Outlook
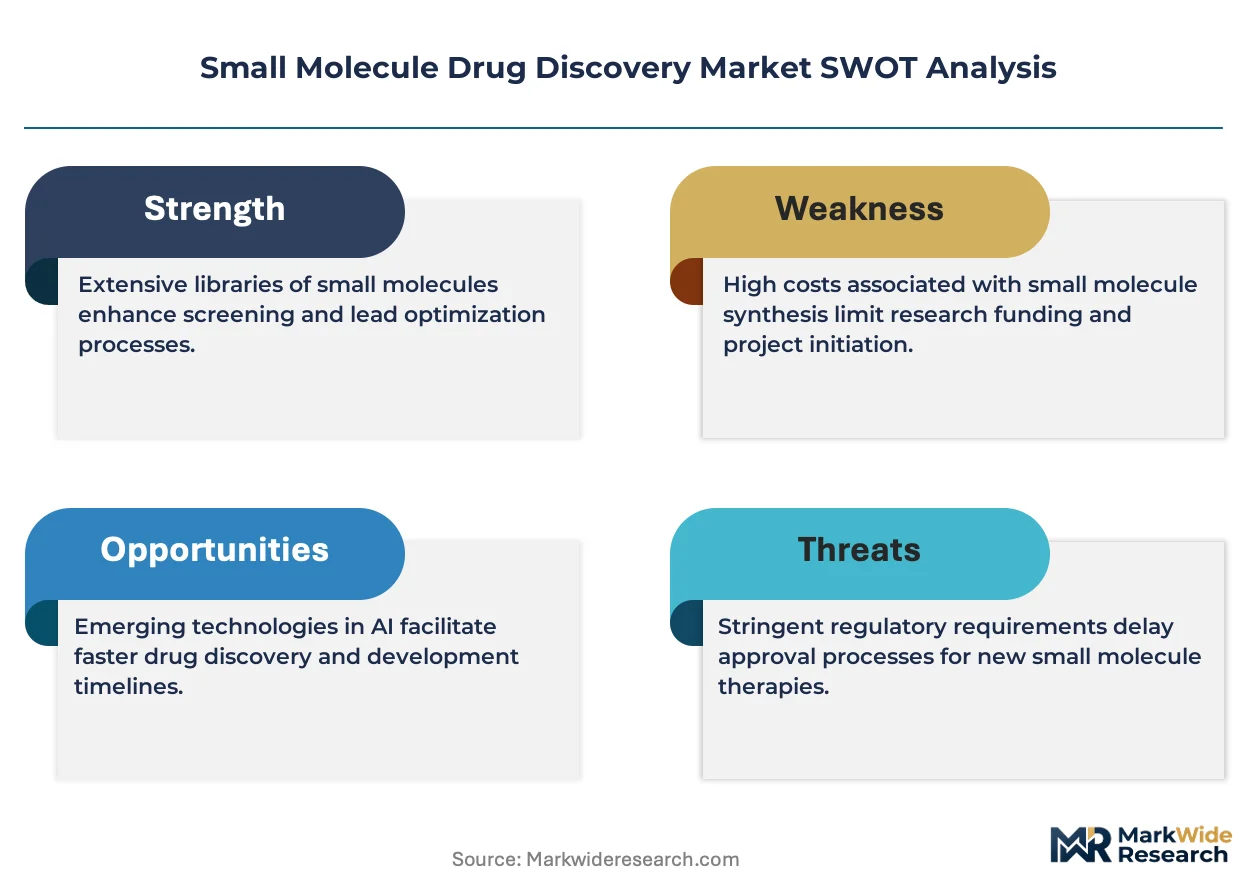
Project finance and milestone-based venture structures is tilting competitive access toward platform biotechs with de-risked capital stacks. Evotec leverages its integrated R&D infrastructure across multiple therapeutic partnerships. Insilico Medicine anchors its position through generative chemistry platforms that reduce synthesis cycles. XtalPi competes by combining quantum physics algorithms with cloud-scale computing for molecular property prediction.
Small molecule drug discovery encompasses the identification and optimization of low molecular weight organic compounds, typically under 900 daltons, that modulate biological targets through defined structure-activity relationships and physicochemical properties enabling oral bioavailability. These compounds serve as the dominant therapeutic modality for modulating intracellular enzymes, receptors, and ion channels with precise pharmacokinetic control. High-throughput screening maintains the largest installed base across pharmaceutical pipelines, though fragment-based lead discovery captures expanding margin pools as target complexity rises. Structure-based drug design occupies the fastest-growing technology position, driven by cryo-EM resolution improvements and AlphaFold-derived protein models. Cancer applications command the deepest clinical investment, while central nervous system disorders represent the most underserved structural opportunity due to blood-brain barrier penetration challenges.
FDA breakthrough therapy designation and EMA PRIME eligibility reshape demand by compressing Phase I-to-approval timelines and rewarding platforms with predictive toxicology capabilities. REACH chemical registration requirements in Europe and China's NMPA pharmacovigilance reforms elevate the cost of compound attrition, favoring organizations with integrated ADMET prediction engines. Stakeholders must monitor which regulatory convergence patterns between FDA, EMA, and NMPA standardize around platform-derived evidence packages versus traditional randomized controlled trials.
Market Dynamics
Structure-based drug design is compressing lead optimization cycles as cryo-EM resolution improvements and AlphaFold-derived protein models enable atomic-level target visualization that was previously unattainable.
Growth Catalysts
- FDA breakthrough therapy designation:The pathway compresses Phase I-to-approval timelines for qualifying oncology candidates, rewarding platforms with predictive toxicology capabilities.
- Generative chemistry platforms:AI-driven molecular generation reduces synthesis cycles by predicting structure-activity relationships before laboratory validation.
- Boston and San Francisco biotech clusters:Concentrated demand in these metropolitan innovation hubs accelerates partnership formation and talent acquisition.
Market Restraints
- REACH chemical registration:European compound documentation requirements elevate the cost of attrition for novel chemical entities.
- Blood-brain barrier penetration:Central nervous system applications face fundamental physicochemical limitations that restrict addressable target space.
- Specialized medicinal chemists:Talent scarcity in structure-based design and computational chemistry constrains platform expansion.
Strategic Opportunities
- Quantum physics algorithms:Convergence with cloud-scale computing enables molecular property prediction for previously intractable targets.
- Fragment-based lead discovery:Expanding margin pools as target complexity rises beyond high-throughput screening capabilities.
- China NMPA pharmacovigilance reforms:Regulatory modernization creates pathways for platform-derived evidence packages in the world's second-largest pharmaceutical market.
Industry Challenges
- Cryo-EM infrastructure:Capital intensity of electron microscopy facilities limits structural biology capacity at mid-tier research institutions.
- ADMET prediction standardization:Absence of harmonized validation frameworks across FDA, EMA, and NMPA complicates regulatory submission strategies.
- Legacy high-throughput screening:Depreciating asset bases require integration with AI-guided compound prioritization to maintain relevance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Molecule Drug Discovery Market |
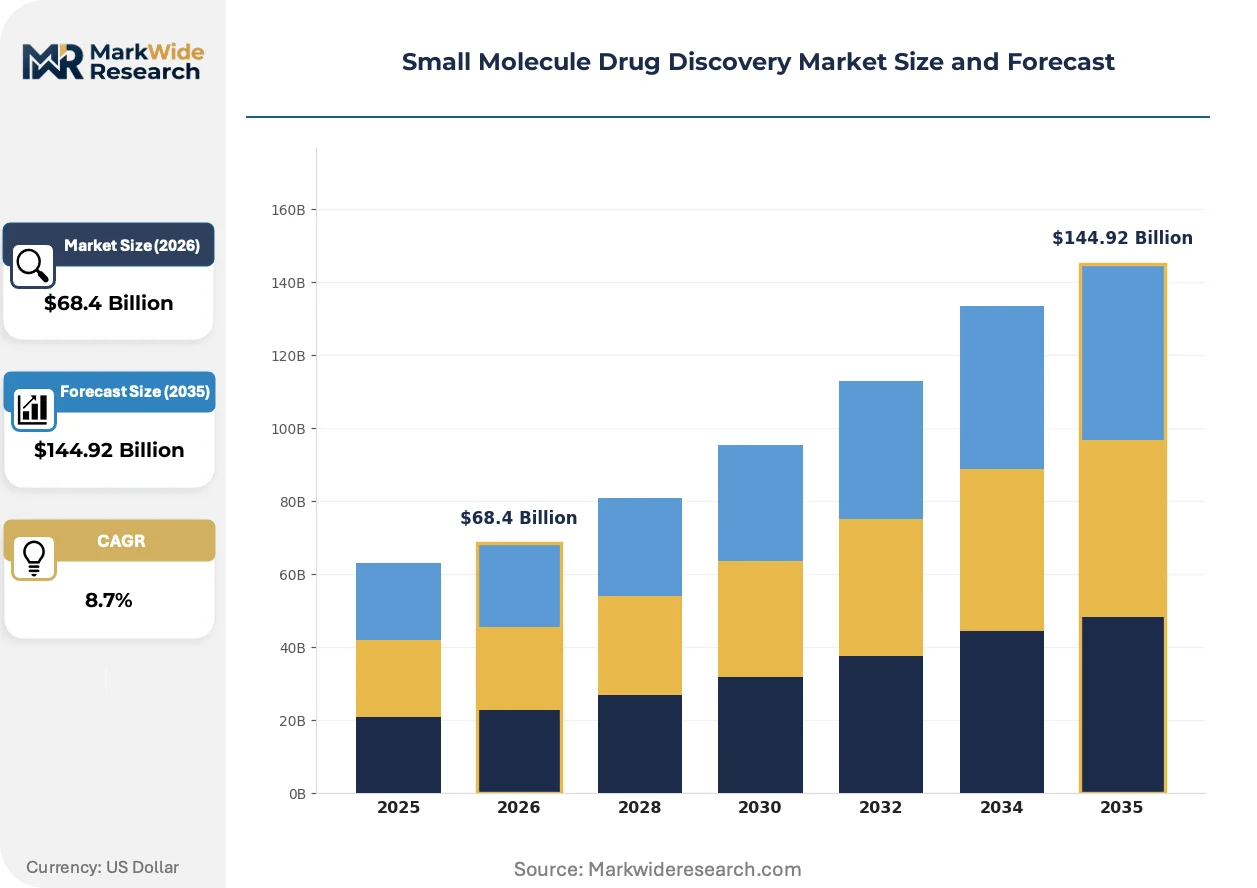
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead Compounds, Clinical Candidates, High-Throughput Screening, Chemical Libraries Technology: Fragment-Based Lead Discovery, Structure-Based Drug Design, In Silico Screening, High-Content Screening Application: Cancer, Cardiovascular Disorders, Infectious Diseases, Central Nervous System Disorders End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Research Organizations |
| Companies Covered | Nimbus Therapeutics, Ascentage Pharma, Recursion Pharmaceuticals, Iktos, 858 Therapeutics, Insilico Medicine, Evotec, XtalPi, Atomwise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Molecule Drug Discovery Market Strategic Shifts
Generative AI is restructuring how molecular candidates progress from virtual screening to synthesis, compressing the traditional multi-year lead identification phase into months.
AlphaFold-derived structural predictions are hybridizing with experimental cryo-EM data to enable target validation for previously undruggable protein classes. Oncology departments at academic medical centers are adopting these hybrid workflows fastest, integrating computational predictions with laboratory confirmation. The structural consequence is a collapse in the time required to establish druggability hypotheses for novel targets.
EMA PRIME eligibility is accelerating access to scientific advice and accelerated assessment for medicines addressing unmet medical needs. The framework rewards sponsors demonstrating robust pharmacokinetic modeling and predictive safety data. Oncology and rare disease developers are prioritizing PRIME qualification to compress regulatory timelines across European markets.
Buyer concentration around platform biotechs is displacing traditional fee-for-service contract research arrangements. Large pharmaceutical sponsors now demand integrated R&D infrastructure spanning target identification through candidate nomination. The United States exhibits this procurement evolution most acutely, with milestone-based venture structures tilting competitive access toward de-risked capital stacks.
Small Molecule Drug Discovery Market Segmentation
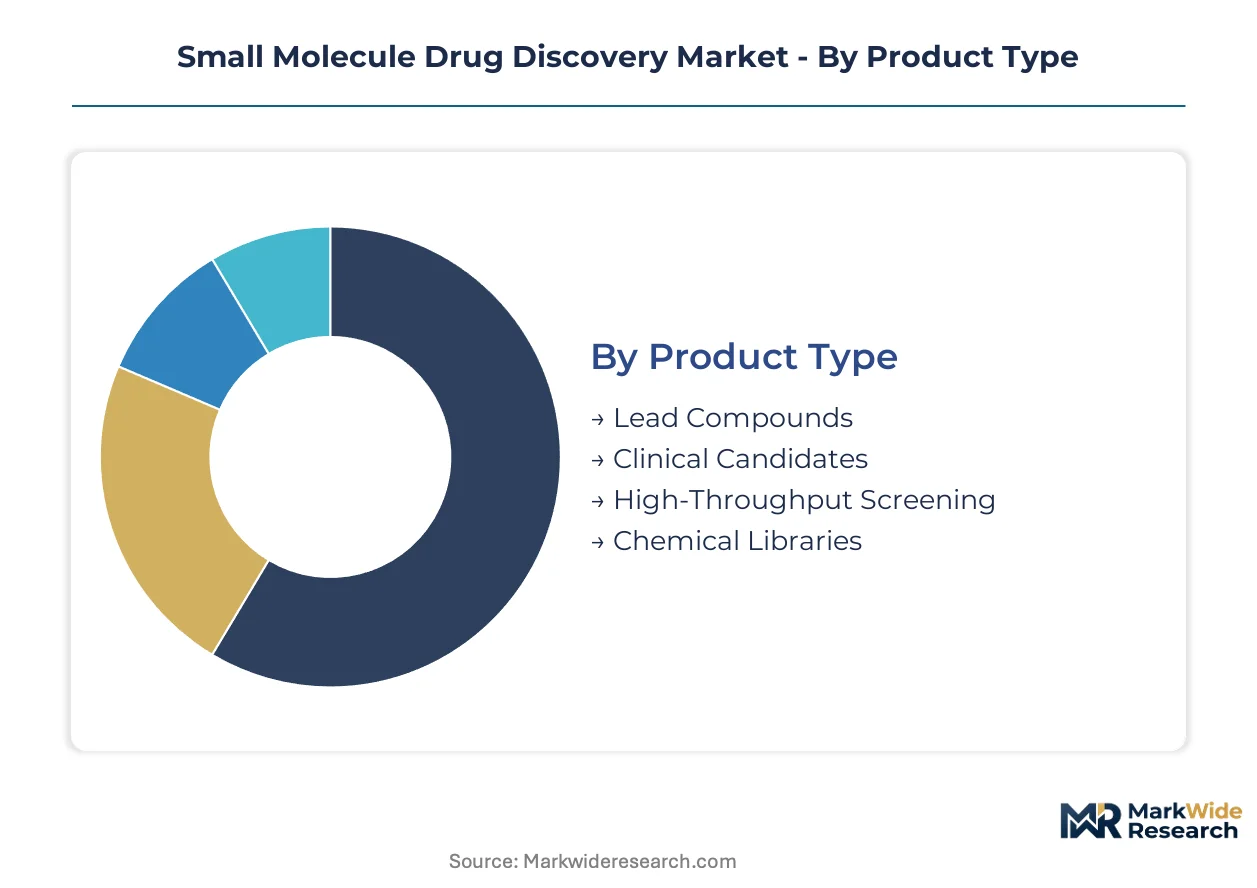
Segmentation in small molecule drug discovery reveals divergent capital intensity and cycle-time economics across the value chain. Lead identification platforms turn over fastest while clinical-stage assets lock up capital longest, reshaping how sponsors allocate R&D budgets and partnership structures.
Product Type:
Cycle times vary dramatically across this category, with screening infrastructure turning over in months versus clinical candidates requiring multi-year development horizons.
- Lead Compounds:Early-stage molecular scaffolds with demonstrated target binding but unoptimized pharmacokinetic profiles. Demand concentrates among Boston and San Francisco biotech clusters where platform biotechs pursue milestone-based venture structures with pharmaceutical sponsors.
- Clinical Candidates:Optimized small molecules with completed IND-enabling studies and defined Phase I protocols. Sponsors in the United States prioritize these assets for FDA breakthrough therapy designation pathways, compressing Phase I-to-approval timelines for qualifying oncology programs.
- High-Throughput Screening:Automated compound testing against biological targets using robotics and detection systems. Legacy installed bases require AI-guided prioritization to maintain relevance against newer discovery modalities.
- Chemical Libraries:Curated collections of diverse small molecules for screening campaigns. Academic medical centers and contract research organizations maintain the largest physical collections.
High-Throughput Screening dominates installed base. Clinical Candidates is where expansion concentrates.
Technology:
Cost tiers separate capital-light computational approaches from infrastructure-heavy experimental methods, with hybrid workflows emerging as the margin-maximizing middle ground.
- Fragment-Based Lead Discovery:Screening of low molecular weight compounds against targets to identify starting points for optimization. Oncology applications at academic medical centers capture expanding margin pools as target complexity rises beyond traditional screening capabilities.
- Structure-Based Drug Design:Atomic-level target visualization using cryo-EM and computational modeling to guide compound optimization. Cryo-EM resolution improvements and AlphaFold-derived protein models enable visualization previously unattainable, compressing lead optimization cycles.
- In Silico Screening:Computational prediction of compound-target interactions without physical synthesis. Generative chemistry platforms reduce synthesis cycles by predicting structure-activity relationships before laboratory validation.
- High-Content Screening:Automated microscopy-based analysis of cellular phenotypes across compound libraries. Cell-based assays with multiparametric readouts support predictive toxicology capabilities rewarded by accelerated regulatory pathways.
Structure-Based Drug Design commands the steepest expansion trajectory. Fragment-Based Lead Discovery captures the highest margins per successful program.
Application:
Customer type and funding source differentiate segments, with oncology commanding venture capital and CNS disorders relying more heavily on academic and government investment.
- Cancer:Oncology programs targeting kinases, epigenetic regulators, and protein-protein interactions. FDA breakthrough therapy designation and EMA PRIME eligibility reshape demand by compressing development timelines for qualifying candidates.
- Cardiovascular Disorders:Small molecules targeting ion channels, GPCRs, and metabolic enzymes for heart failure and dyslipidemia. Large pharmaceutical sponsors maintain internal capabilities for these established therapeutic areas.
- Infectious Diseases:Antibacterial, antiviral, and antifungal programs addressing resistant pathogens. Public-private partnerships and government funding offset commercial risk in this segment.
- Central Nervous System Disorders:Programs for neurodegeneration, psychiatric conditions, and pain management. Blood-brain barrier penetration challenges restrict addressable target space, making this the most underserved structural opportunity.
Cancer absorbs the deepest clinical investment. Central Nervous System Disorders offers the largest unmet need relative to current pipeline density.
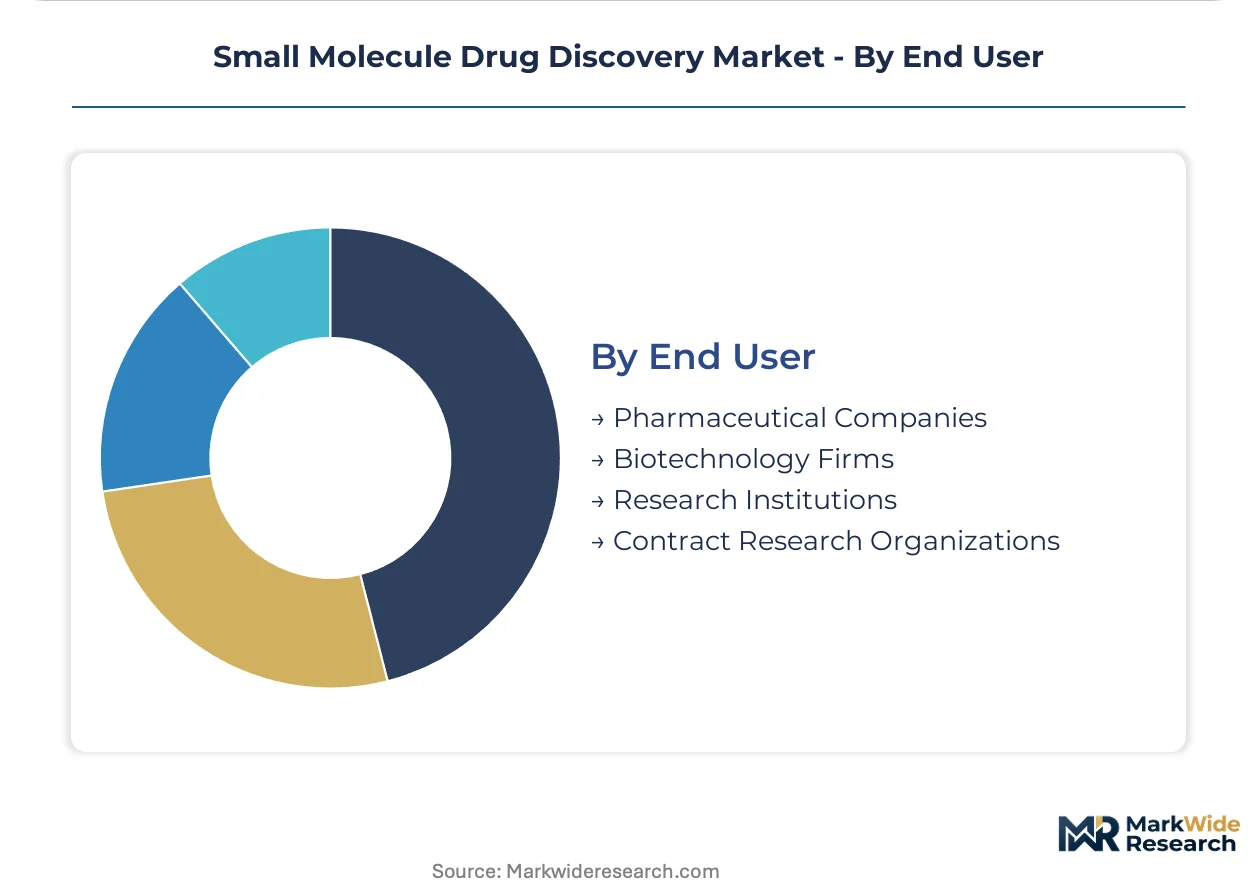
End User:
Supply concentration tilts toward integrated platform providers, displacing traditional fee-for-service arrangements across all customer categories.
- Pharmaceutical Companies:Large sponsors with internal medicinal chemistry and clinical development infrastructure. These organizations now demand integrated R&D infrastructure spanning target identification through candidate nomination rather than discrete service contracts.
- Biotechnology Firms:Platform biotechs with de-risked capital stacks and specialized therapeutic focus. Milestone-based venture structures tilt competitive access toward these entities in the United States.
- Research Institutions:Academic medical centers and universities conducting fundamental discovery research. Oncology departments at these institutions are expanding medicinal chemistry capabilities fastest.
- Contract Research Organizations:External providers of discovery chemistry, biology, and ADMET services. Procurement evolution favors organizations with integrated R&D infrastructure over discrete service offerings.
Pharmaceutical Companies retain the largest internal capacity. Biotechnology Firms is where partnership formation accelerates most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform biotechs with de-risked capital stacks cluster around metropolitan innovation hubs where FDA breakthrough therapy pathways compress development timelines. Venture formation concentrates where medicinal chemistry talent pools intersect with cloud-scale computing infrastructure.
United States
Pharmaceutical sponsors demand integrated R&D infrastructure spanning target identification through candidate nomination. FDA breakthrough therapy designation rewards platforms with predictive toxicology capabilities. Boston and San Francisco biotech clusters accelerate partnership formation through milestone-based venture structures.
China
NMPA pharmacovigilance reforms elevate the cost of compound attrition for novel chemical entities. Regulatory modernization creates pathways for platform-derived evidence packages in the world's second-largest pharmaceutical market. Shanghai and Beijing house expanding medicinal chemistry capabilities at academic medical centers.
Germany
REACH chemical registration requirements constrain small-molecule pipeline expansion through elevated documentation burdens. EMA PRIME eligibility accelerates access to scientific advice for medicines addressing unmet medical needs. Munich and Heidelberg anchor structural biology infrastructure serving European pharmaceutical sponsors.
Switzerland
Swissmedic maintains alignment with EMA accelerated assessment frameworks while preserving national regulatory autonomy. Basel and Zurich host concentrated medicinal chemistry expertise serving global pharmaceutical headquarters. Federal innovation incentives support fragment-based lead discovery platform development.
United Kingdom
Medicines and Healthcare products Regulatory Agency convergence with FDA evidentiary standards streamlines multinational trial design. London and Cambridge biotech clusters specialize in generative chemistry platform commercialization. UK Research and Innovation funding prioritizes structure-based drug design infrastructure.
Small Molecule Drug Discovery Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered service and platform segments. Large pharmaceutical sponsors now procure integrated R&D infrastructure rather than discrete contract research arrangements. Three archetypes dominate: platform biotechs with de-risked capital stacks, AI-native discovery engines, and legacy high-throughput screening providers modernizing through computational integration. Competitive moves center on strategic partnerships with academic medical centers and technology licensing for molecular property prediction capabilities.
Among AI-native discovery specialists, Insilico Medicine, XtalPi, and Evotec exemplify divergent technical approaches to compressing synthesis cycles. Insilico Medicine anchors the generative chemistry archetype through structure-activity relationship prediction. XtalPi occupies a position combining quantum physics algorithms with cloud-scale computing infrastructure. Evotec represents the integrated R&D platform model spanning multiple therapeutic partnerships. These three entities sit within a competitive set where computational differentiation determines partnership access with pharmaceutical sponsors.
| Leading Market Players |
|---|
| Nimbus Therapeutics |
| Ascentage Pharma |
| Recursion Pharmaceuticals |
| Iktos |
| 858 Therapeutics |
| Insilico Medicine |
| Evotec |
| XtalPi |
| Atomwise |
| Others |
Value Chain & Pricing Dynamics
Specialized medicinal chemist talent pools in Switzerland and Germany anchor upstream capability concentration, directing margin capture toward integrated platform providers rather than discrete service vendors downstream. This concentration pattern rewards organizations with captive ADMET prediction engines and cryo-EM infrastructure, compressing pricing power for traditional fee-for-service contract research arrangements.
Pricing Analysis
Certification level creates the primary spread between premium FDA-grade IND-ready candidates and standard research-grade lead compounds. Project-based milestone structures dominate oncology partnerships, while subscription-tiered platform access governs early discovery relationships with biotechnology firms. Pricing pressure stems from REACH documentation burdens elevating European attrition costs, with contract research organizations exhibiting highest price sensitivity and integrated platform biotechs demonstrating lowest sensitivity due to de-risked capital stacks.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk calculations for chemical library sourcing and intermediate manufacturing. Active pharmaceutical ingredient synthesis concentrates in India and China, while specialized cryo-EM equipment and computational hardware draw from Germany, Japan, and the United States. Single-source vulnerability persists for ultra-high-resolution electron microscopy components. Distribution runs through milestone-based partnership structures rather than transactional procurement, with pharmaceutical sponsors directly integrating platform capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across therapeutic modalities and geographic regulatory clusters creates multiple viable entry positions. FDA breakthrough therapy pathway compression and EMA PRIME eligibility standardization reward specialized capabilities over generalized service breadth.
For Market Incumbents: Insulate core platform relationships through exclusive target identification partnerships with academic medical centers in Boston and San Francisco. Deepen backward integration into generative chemistry infrastructure to offset margin pressure from AI-native discovery engines. Prioritize predictive toxicology certification investments that accelerate regulatory timelines. For New Entrants and Emerging Players: Central nervous system disorders with blood-brain barrier penetration challenges represent the most penetrable entry point, given structural undersupply relative to unmet medical need. Fragment-based lead discovery for complex protein-protein interactions offers secondary white-space opportunity. Position through scientific co-founder relationships with cryo-EM-equipped institutions rather than capital-intensive infrastructure buildout. For Investors and Strategic Acquirers: Capital is best deployed toward platform biotechs with demonstrated FDA breakthrough therapy designations and de-risked capital stacks spanning multiple pharmaceutical partnerships. Long-term viability hinges on regulatory convergence between FDA, EMA, and NMPA around platform-derived evidence packages. Watch for harmonized ADMET validation frameworks as the inflection signal for accelerated M&A activity.| Strategic Initiative | Industry Significance |
|---|---|
| Generative Chemistry Platform Integration | Insilico Medicine's structure-activity prediction capability compresses synthesis cycles for pharmaceutical sponsors. |
| Cryo-EM Infrastructure Partnership | Academic medical centers in Boston expand medicinal chemistry capabilities through shared electron microscopy facilities. |
| FDA Breakthrough Therapy Designation Pathway | Oncology developers with predictive toxicology data accelerate Phase I-to-approval timelines under compressed regulatory review. |
| REACH Compliance Certification Program | European compound registration requirements elevate documentation standards for novel chemical entity attrition costs. |
| Quantum Physics Algorithm Licensing | XtalPi's cloud-scale molecular property prediction enables previously intractable target classes for partnership expansion. |
Study Parameters
A spread of perspectives from medicinal chemistry directors, regulatory affairs leads at FDA and EMA, formulary access specialists, and platform biotech executives converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through FDA breakthrough therapy designation filings, EMA PRIME eligibility submissions, ClinicalTrials.gov protocol registrations, and SEC 10-K R&D expenditure disclosures. Bottom-up triangulation across partnership announcement databases and top-down reconciliation against pharmaceutical sponsor pipeline disclosures anchored the analytical framework.
Demand-supply balance dynamics shaped the forecast architecture across the analysis window. Segmentation dimensions modeled include therapeutic application, technology modality, development stage, and regional regulatory cluster. CAGRs derived from historical partnership value trajectories and projected milestone payment schedules. Forecast inputs incorporated cryo-EM resolution improvement curves and AlphaFold structural prediction accuracy advances as technology-specific variables.
Macroeconomic conditions sit as an overlay; deviation in venture capital deployment rates or pharmaceutical R&D budget reallocations would shift the trajectory. Forecasts reflect assumptions around regulatory pathway convergence and platform-derived evidence acceptance. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Furosemide Market
Pharmaceutical Ingredients
Celecoxib API Market
Pharmaceutical Ingredients
Global Cephalosporin Drugs Market
Pharmaceutical Ingredients
Topical Drugs Market
Pharmaceutical Ingredients
Mitotic Inhibitors Market
Pharmaceutical Ingredients
Pharmaceutical Excipients for Taste Masking Market
Pharmaceutical Ingredients
Tiapride Hydrochloride API Market
Pharmaceutical Ingredients
Pharmaceuticals Grade Sodium Bicarbonate Market
Pharmaceutical Ingredients
Fipronil Market
Pharmaceutical Ingredients
Pharmaceutical Grade Amino Acid Market
Pharmaceutical Ingredients
Lipids Active Pharmaceutical Ingredient Market
Pharmaceutical Ingredients
Pharma-Grade Magnesium Trisilicate Market
Pharmaceutical Ingredients
Pharmaceutical Grade Magnesium Hydroxide Market
Pharmaceutical Ingredients
Pharmaceutical Fine Chemicals Market
Pharmaceutical Ingredients
Metformin Hydrochloride API Market
Pharmaceutical Ingredients
Pharmaceutical Hot Melt Extrusion Market