
 Polymer Testing Equipment Market | 2026-2036
Polymer Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Testing Equipment Market Outlook
Software-defined analytics subscriptions is expanding the attach rate for polymer testing platforms beyond hardware-only transactions. Thermo Fisher Scientific leverages its chromatography software ecosystem to lock in recurring revenue from polymer labs. ZwickRoell Group anchors its European installed base with predictive maintenance contracts that reduce unplanned downtime. Shimadzu Corporation differentiates through integrated thermal analysis suites that bundle hardware with perpetual license upgrades.
Polymer testing equipment comprises instruments that measure mechanical, thermal, and chemical properties of macromolecular materials under controlled conditions, typically operating across temperature ranges from cryogenic to 600°C and load capacities from millinewtons to kilonewtons to certify material performance for industrial use. Tensile testing machines and dynamic mechanical analyzers capture the majority of capital expenditure as manufacturers validate modulus and viscoelastic response for automotive and aerospace grades. Fourier transform infrared spectroscopy and differential scanning calorimetry command premium pricing in failure analysis workflows where chemical fingerprinting and thermal transition detection determine root cause.
REACH in Europe, FDA biocompatibility guidance in the United States, and GB standards under China's SAMR collectively mandate batch-level material traceability that forces polymer producers to upgrade from manual to automated testing protocols. ISO 527 and ASTM D638 tensile standards create compliance baselines that equipment vendors must embed to qualify for tender participation. Stakeholders should monitor how dual carbon goals in China and the EU Green Deal recalibrate polymer recyclability testing requirements before committing to platform refresh cycles.
Market Dynamics
Software-defined analytics subscriptions are compressing traditional hardware-only transaction cycles, forcing vendors to restructure revenue models around recurring platform access rather than capital equipment sales.
Growth Catalysts
- Automotive lightweighting mandates:Germany and Japan are expanding rheometry and dynamic mechanical analysis adoption as OEMs validate modulus performance for structural polymer grades.
- REACH compliance deadlines:ECHA batch-level traceability requirements are compelling European polymer producers to automate manual testing protocols.
- Domestic polymer production scaling:China, India, and South Korea are concentrating demand for tensile and impact testing infrastructure.
Market Restraints
- High-precision sensor import dependence:Load cell and extensometer supply concentrates in German and Japanese specialty manufacturers, exposing buyers to currency and logistics volatility.
- Capital intensity of thermal analysis suites:Fourier transform infrared spectroscopy and differential scanning calorimetry systems require substantial upfront investment with payback periods exceeding five years for mid-tier labs.
- Regulatory fragmentation:Divergent ISO 527, ASTM D638, and GB standard certification requirements force equipment vendors to maintain multiple firmware and calibration variants.
Strategic Opportunities
- Recyclability testing protocols:Dual carbon goals in China and the EU Green Deal are recalibrating polymer certification requirements, creating demand for thermal and mechanical property validation of recycled feedstocks.
- Predictive maintenance service contracts:European installed bases are anchoring long-term revenue through uptime guarantees and remote diagnostics.
- Biocompatibility validation workflows:FDA polymer biocompatibility rules are tightening material certification requirements for medical device manufacturers.
Industry Challenges
- Rheology specialist talent scarcity:Polymer physics and viscoelastic characterization expertise remains concentrated in academic and national metrology institutes, constraining lab expansion timelines.
- Legacy system integration friction:Automated testing protocols must interface with existing laboratory information management systems, extending deployment cycles.
- Multi-standard calibration complexity:Equipment vendors must embed simultaneous compliance with ISO, ASTM, and GB frameworks, increasing firmware development and field service costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Testing Equipment Market |
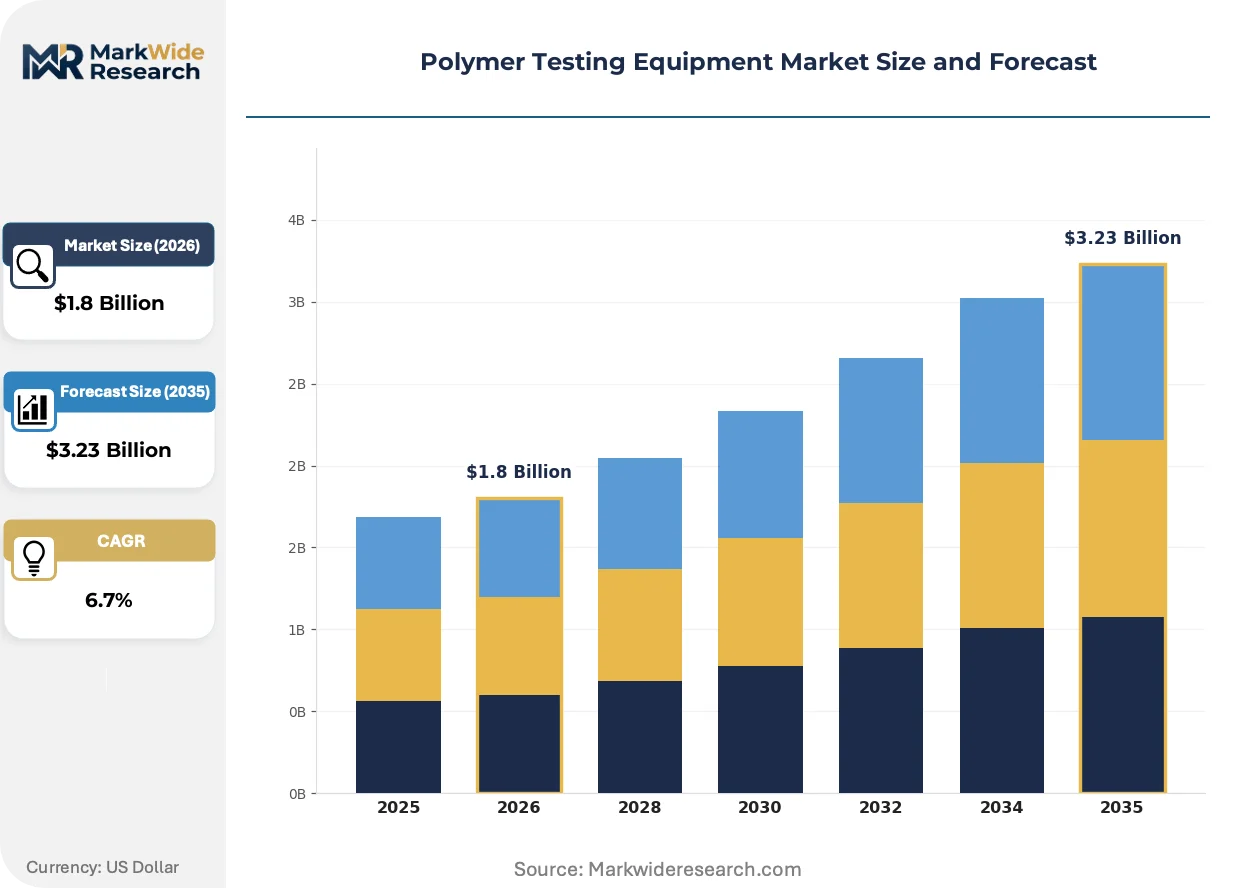
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tensile Testing Machines, Hardness Testers, Impact Testers, Dynamic Mechanical Analyzers Technology: Thermogravimetric Analysis, Fourier Transform Infrared Spectroscopy, Differential Scanning Calorimetry, Rheometry End User: Research Institutions, Polymer Manufacturers, Quality Control Labs, Educational Institutions Application: Material Characterization, Quality Assurance, Failure Analysis, Product Development |
| Companies Covered | Agilent Technologies, Illinois Tool Works Inc., Thermo Fisher Scientific, Dynisco, Tinius Olsen, AMETEK Inc, ZwickRoell Group, Aimil Ltd., Shimadzu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Testing Equipment Market Strategic Shifts
Cloud-native analytics platforms are displacing on-premise data processing, compressing the boundary between instrument hardware and computational interpretation.
Artificial intelligence-driven defect prediction is integrating with dynamic mechanical analyzers to flag anomalous viscoelastic responses in real-time during testing sequences. Automotive Tier-1 suppliers in Germany are adopting these systems to compress validation cycles for interior trim and underhood polymer grades. This convergence is integrating predictive algorithms directly into quality control workflows, reducing reliance on post-test manual review.
REACH authorization list expansions are tightening restrictions on phthalate plasticizers and brominated flame retardants, forcing polymer compounders to reformulate and revalidate entire product lines. Equipment vendors must now certify that thermal and mechanical testing protocols can detect trace additive concentrations below regulatory thresholds. European compounders are responding by upgrading from single-property testers to integrated thermal-mechanical-chemical analysis suites.
Subscription-based software access is displacing perpetual license purchases for chromatography and spectroscopy data interpretation. Polymer labs in the United States are unbundling hardware procurement from analytics platform commitments, compressing switching costs between vendors. This model shift is most visible among contract testing organizations serving medical device and packaging verticals, where regulatory audit trails demand continuous software updates.
Polymer Testing Equipment Market Segmentation
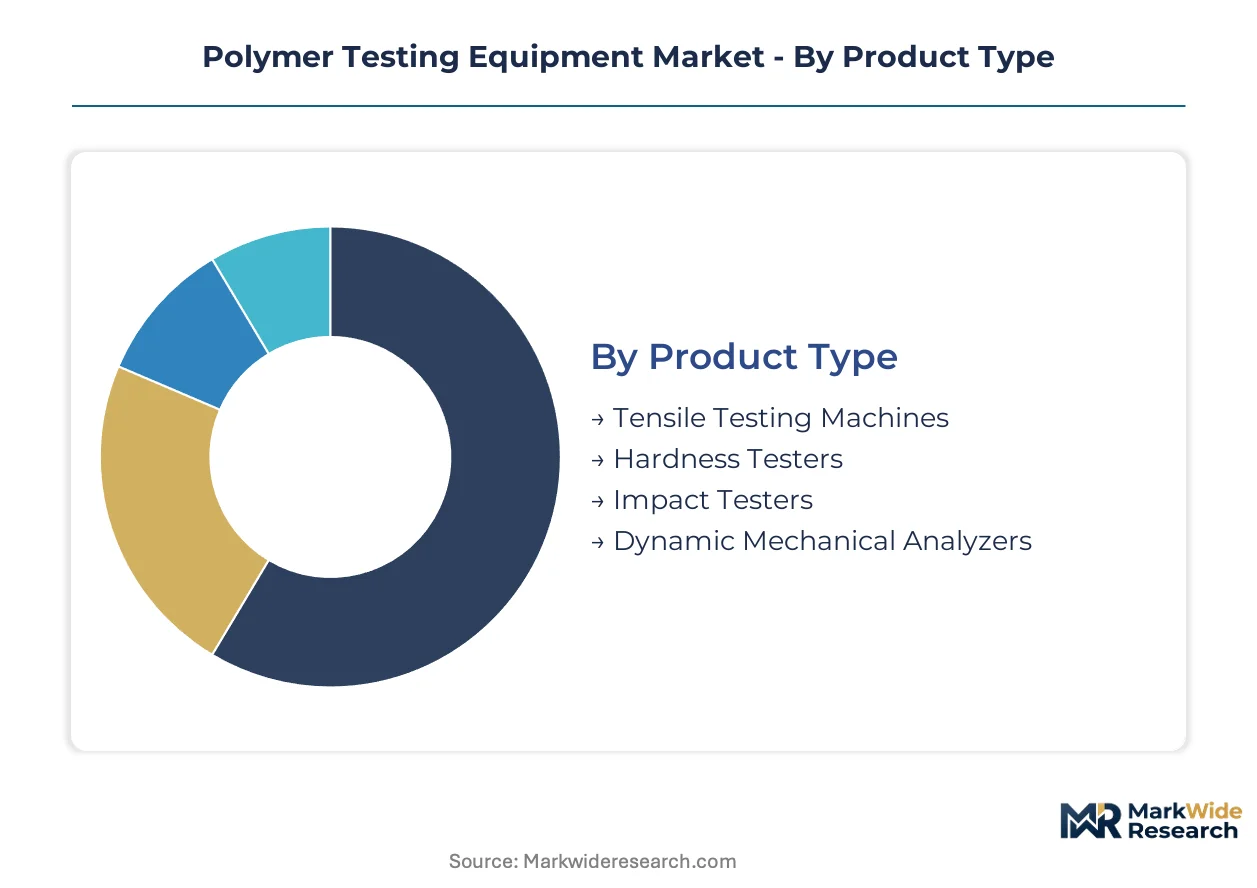
Polymer testing equipment procurement cycles diverge sharply across product categories, with mechanical testers commanding replacement every 7-10 years while spectroscopy platforms extend to 12-15 year lifespans. Understanding these upgrade rhythms enables vendors to time platform launches and service contract renewals against predictable capital refresh windows.
Product Type:
Replacement urgency varies by instrument complexity, with high-throughput mechanical systems facing shorter depreciation schedules than specialized thermal analyzers.
- Tensile Testing Machines:Electromechanical and hydraulic load frame systems apply controlled tension to polymer specimens to measure modulus, yield strength, and elongation at break. Automotive Tier-1 suppliers in Germany and Japan are refreshing these systems to validate structural polymer grades for lightweighting programs. REACH batch-level traceability mandates are compressing replacement cycles as European compounders automate manual protocols.
- Dynamic Mechanical Analyzers:These instruments characterize viscoelastic behavior across temperature and frequency sweeps, capturing storage modulus, loss modulus, and tan delta parameters. Aerospace material qualification workflows in the United States and France are concentrating demand for high-precision DMA configurations. FDA biocompatibility rules for medical device polymers are tightening validation requirements for viscoelastic property documentation.
- Hardness Testers:Shore and Rockwell durometers measure indentation resistance for elastomer and thermoset grades.
- Impact Testers:Charpy and Izod pendulum systems quantify fracture energy for quality control pass-fail determination.
Tensile Testing Machines sit at the top of the volume ranking, with Dynamic Mechanical Analyzers climbing the fastest.
Technology:
Capital allocation tilts toward integrated thermal-chemical analysis suites as compounders consolidate multiple testing protocols onto single platforms.
- Fourier Transform Infrared Spectroscopy:FTIR systems identify functional groups and additive concentrations through molecular vibration spectroscopy, operating across mid-infrared wavelengths. Failure analysis laboratories in the United States are prioritizing these systems for root-cause determination of polymer degradation and contamination events. REACH authorization list expansions for phthalate plasticizers are forcing detection sensitivity upgrades below regulatory thresholds.
- Rheometry:Rotational and capillary rheometers measure viscosity and viscoelastic response under shear deformation, critical for processing simulation. Automotive lightweighting mandates in Germany are accelerating adoption of high-torque rheometer configurations for structural polymer validation. Talent scarcity in polymer physics is extending deployment timelines for rheology-specialized labs.
- Thermogravimetric Analysis:TGA platforms quantify thermal stability and filler content through controlled mass loss measurement.
- Differential Scanning Calorimetry:DSC instruments detect glass transition, melting, and crystallization temperatures through heat flow differential.
FTIR commands premium pricing per installation, while rheometry is expanding most quickly among Tier-1 automotive suppliers.
End User:
Procurement authority concentrates with quality control functions as regulatory audit trail requirements tighten across medical device and packaging verticals.
- Polymer Manufacturers:Integrated compounders and resin producers operate high-throughput testing floors for batch release certification. Domestic production scaling in China, India, and South Korea is concentrating infrastructure investment for tensile and impact testing capacity. SAMR GB standards compliance is mandating automated protocol upgrades.
- Quality Control Labs:Contract testing organizations serve medical device, packaging, and automotive clients with certified ISO 17025 workflows. FDA polymer biocompatibility rules are tightening material certification requirements for device manufacturers. Subscription-based software access is displacing perpetual license purchases among these organizations.
- Research Institutions:University and national laboratory facilities prioritize method development and fundamental polymer physics investigation.
- Educational Institutions:Technical training programs require entry-level mechanical testers for student instruction.
Polymer Manufacturers represent the largest installed base, with Quality Control Labs gaining share fastest through outsourcing trends.
Application:
Workflow automation priorities differ by application, with quality assurance functions prioritizing throughput while failure analysis demands analytical depth.
- Quality Assurance:Statistical process control workflows require high-repeatability testing with automated specimen handling and data logging. ECHA REACH compliance deadlines are compelling European producers to upgrade from manual to automated batch certification. Cloud-native analytics platforms are displacing on-premise data processing in these high-volume environments.
- Failure Analysis:Root-cause investigation workflows integrate thermal, mechanical, and chemical characterization to determine degradation mechanisms. Aerospace and medical device sectors in the United States and Switzerland are concentrating demand for multi-technique analysis suites. AI-driven defect prediction is integrating with DMA systems to flag anomalous responses in real-time.
- Material Characterization:Fundamental property documentation supports grade qualification and customer specification compliance.
- Product Development:R&D workflows prioritize method flexibility and exploratory testing protocols.
Quality Assurance dominates capital deployment, with Failure Analysis showing the steepest expansion trajectory among high-value verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive lightweighting programs generate steeper equipment refresh cycles than Japan's materials qualification workflows, though both markets concentrate demand for rheometry and dynamic mechanical analysis systems. Domestic polymer production scaling across Asia-Pacific is redistributing capital expenditure toward tensile and impact testing infrastructure.
United States
Medical device manufacturers in Massachusetts and Minnesota are tightening biocompatibility validation workflows under FDA polymer guidance. The agency's material certification rules now mandate traceable thermal and mechanical property documentation for implantable grades. Boston-area contract testing labs are upgrading to integrated analysis suites to serve orthopedic and cardiovascular device clusters.
Germany
Automotive Tier-1 suppliers in Baden-Württemberg and Bavaria are expanding rheometry adoption for structural polymer validation. ECHA REACH batch-level traceability deadlines are compelling compounders to automate manual testing protocols. Stuttgart's automotive materials corridor is concentrating demand for high-torque rheometer configurations and predictive maintenance service contracts.
China
Domestic resin producers in Jiangsu and Zhejiang provinces are scaling tensile and impact testing capacity for batch release certification. SAMR GB standards compliance is mandating automated protocol upgrades from manual methods. The Yangtze River Delta polymer manufacturing belt is driving infrastructure investment for quality control automation.
Japan
Automotive OEMs in Aichi and Kanagawa prefectures are validating modulus performance for interior trim and underhood polymer grades. METI industrial standards frameworks align with international ISO protocols for material qualification. Nagoya's automotive supply chain cluster is adopting AI-integrated dynamic mechanical analyzers to compress validation cycles.
India
Domestic compounders in Gujarat and Maharashtra are building tensile testing floors for batch certification as polymer production scales. BIS national standards adoption is accelerating equipment procurement for quality assurance workflows. The Mumbai-Pune industrial corridor is concentrating demand for entry-level mechanical testers serving packaging and automotive verticals.
Polymer Testing Equipment Market Competitive Environment
Top-tier vendors anchor premium thermal-chemical analysis suites, while mid-tier specialists populate mechanical testing segments with standardized load frame configurations. The vendor base stratifies across three archetypes: diversified analytical instrumentation conglomerates, precision mechanical testing specialists, and regional fabrication houses serving emerging markets. Consolidation pressure is intensifying through strategic technology licensing arrangements and geographic distribution partnerships.
Within the diversified instrumentation tier, Thermo Fisher Scientific and Agilent Technologies exemplify platform-centric positioning through chromatography and spectroscopy ecosystems. ZwickRoell Group anchors the European mechanical testing segment with German-engineered load frame systems. Shimadzu Corporation occupies a position bridging thermal analysis and mechanical characterization for Asia-Pacific industrial labs. These three vendors represent distinct strategic postures: software-defined recurring revenue, predictive maintenance service anchoring, and integrated suite bundling respectively.
| Leading Market Players |
|---|
| Agilent Technologies |
| Illinois Tool Works Inc. |
| Thermo Fisher Scientific |
| Dynisco |
| Tinius Olsen |
| AMETEK Inc |
| ZwickRoell Group |
| Aimil Ltd. |
| Shimadzu Corporation |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal carbon neutrality mandates gate qualified supply access for thermal analysis suites and compress premium-tier pricing power to vendors with certified recyclability testing protocols. German and Japanese sensor manufacturers extract rent from this qualification bottleneck, while mid-tier labs in India and China face exclusion from high-margin aftermarket service contracts.
Pricing Analysis
Capacity additions in South Korea and China are reshaping price floors for electromechanical tensile testers, compressing margins on standardized load frame configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by calibration certification grade and predictive maintenance bundling. Price differentiation hinges on ISO 17025 accreditation status and firmware multi-standard compatibility. Cost compression in economy-tier mechanical testers is intensifying because domestic fabrication houses in Gujarat and Jiangsu replicate basic specifications without thermal-chemical integration.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese specialty manufacturers for high-precision load cells and extensometers. Component sourcing draws from Bavaria precision engineering clusters, Nagoya sensor fabrication corridors, and Stuttgart metrology institutes. Quartz force transducers, infrared detector arrays, and high-torque rheometer motors constitute critical input dependencies. Tariff exposure on precision sensor imports exposes mid-tier Asian labs to currency volatility. Distribution runs through authorized technical service partnerships rather than direct OEM sales, anchoring long-term revenue in maintenance contract renewals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH compliance costs in Europe run three to five times higher than SAMR GB standards administration in China, redirecting capital deployment toward Yangtze River Delta automation infrastructure.
For Market Incumbents: Lock in European installed bases through predictive maintenance contracts that reduce unplanned downtime for automotive Tier-1 suppliers. Deepen backward integration into chromatography software ecosystems to capture recurring revenue from polymer labs facing FDA biocompatibility documentation mandates. Defend against mid-tier Asian fabrication houses by embedding ISO 527, ASTM D638, and GB standard compliance into unified firmware architectures. For New Entrants and Emerging Players: Capture quality control lab outsourcing demand in Massachusetts and Minnesota medical device corridors where FDA polymer guidance tightens material certification requirements. Target entry-level mechanical tester segments in the Mumbai-Pune industrial corridor serving packaging and automotive verticals with BIS national standards compliance. Lead with cloud-native analytics platform unbundling to compress switching costs between vendors. For Investors and Strategic Acquirers: Roll-up economics work for precision mechanical testing specialists because regulatory fragmentation across ISO, ASTM, and GB frameworks forces equipment vendors to maintain multiple calibration variants, favoring consolidated firmware development scale. Focus acquisition screening on regional fabrication houses with SAMR certification access and installed base density in Jiangsu and Zhejiang provinces. Watch for inflection when dual carbon goals in China and EU Green Deal recyclability mandates trigger platform refresh cycles for thermal-mechanical-chemical analysis suites.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Analytics Subscription | Thermo Fisher Scientific locks recurring revenue from polymer labs through chromatography platform access. |
| Predictive Maintenance Service Contract | ZwickRoell Group anchors European automotive materials corridor with uptime guarantees and remote diagnostics. |
| Integrated Thermal-Mechanical Suite Bundling | Shimadzu Corporation differentiates Asia-Pacific positioning through perpetual license upgrade pathways. |
| AI-Driven Defect Prediction Integration | Nagoya automotive supply chain cluster compresses validation cycles for underhood polymer grades. |
| Multi-Standard Firmware Certification | Equipment vendors embed simultaneous ISO 527, ASTM D638, and GB compliance to qualify for tender participation. |
Study Parameters
Bottom-up polymer manufacturer and quality control lab modeling reconciled against top-down equipment vendor shipment tracking forms the analytical core of this study. Primary interviews with plant engineers at resin producers, procurement leads at automotive Tier-1 suppliers, maintenance directors at contract testing organizations, and aftermarket service heads at distribution partners supplied demand-side validation. Secondary triangulation drew from customs and trade data, SEC 10-K instrument segment disclosures, ECHA REACH authorization list updates, and SAMR GB standards bulletins.
Input-output matrices map installed base depreciation schedules against capital expenditure cycles across mechanical, thermal, and chemical analysis platforms. Segmentation dimensions span product type complexity tiers, technology integration depth, end-user procurement authority concentration, and application workflow automation intensity. CAGRs derive from replacement urgency differentials between 7-10 year mechanical tester cycles and 12-15 year spectroscopy platform lifespans, cross-referenced against regulatory compliance deadline clustering.
REACH authorization list expansions, FDA polymer biocompatibility guidance revisions, and dual carbon goal implementation pacing are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions on batch-level traceability mandate enforcement intensity and talent scarcity constraints on rheology lab deployment timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Fugitive Emissions Detection and Quantification Test Systems Market
Testing Equipment
Abrasion Tester Market
Testing Equipment
Corrosion Testing Services Market
Testing Equipment
Gas Chromatography Columns Market
Testing Equipment
Chromatography Accessories and Consumables Market
Testing Equipment
Global Laboratory Analytical Instruments and Consumables Market
Testing Equipment
Low-Pressure Liquid Chromatography Market
Testing Equipment
Ultrasonic Testing Market
Testing Equipment
Laboratory Accessories Market
Testing Equipment
Japan Material Testing Market
Testing Equipment
Supercritical Fluid Chromatography Market
Testing Equipment
Melting Point Apparatus Market
Testing Equipment
Liquid Analytical Instrument Market
Testing Equipment
High Performance Liquid Chromatography-Tandem Mass Spectrometry System Market
Testing Equipment
Chloride Reagents Kits Market
Testing Equipment
Sand Testing Equipments Market