
 Electrical Testing Equipment Market | 2026-2036
Electrical Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Testing Equipment Market Foresight
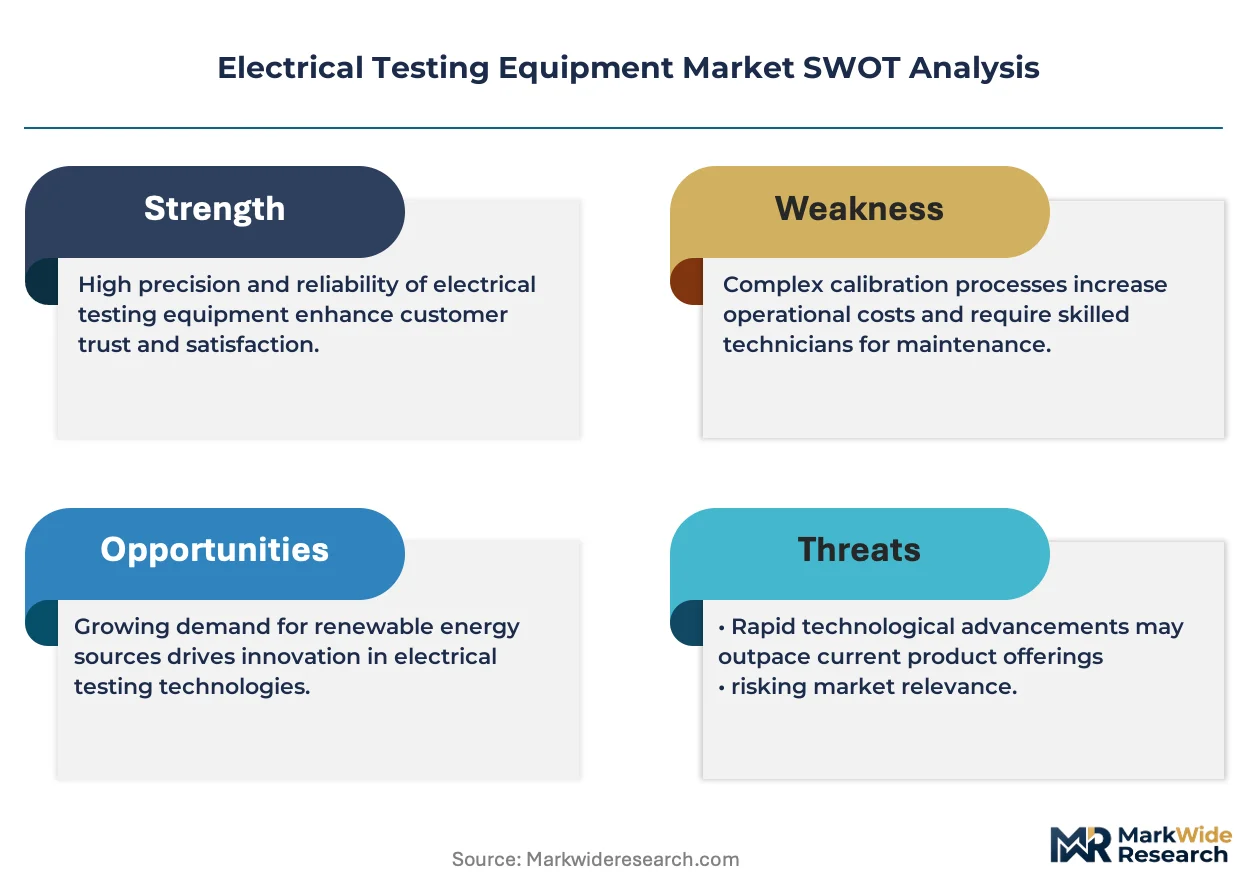
The EU Green Deal is restructuring procurement criteria across European utilities, mandating lifecycle emissions disclosure for electrical testing equipment. Fluke Corporation leverages its brand strength in portable diagnostic tools to sustain channel dominance across North American contractor networks. Yokogawa Test & Measurement Corporation anchors its position in precision power measurement through deep calibration expertise in Asian industrial markets. Keysight Technologies Inc. competes on R&D intensity, dominating high-frequency test applications for semiconductor validation.
Electrical testing equipment comprises instruments designed to measure voltage, current, resistance, insulation integrity, and signal characteristics across power and electronic systems, typically operating from millihertz to gigahertz frequencies with precision tolerances of 0.01% or tighter. These devices serve critical functions in verifying safety compliance, diagnosing faults, and certifying performance across generation, transmission, and end-use equipment. Multimeters and oscilloscopes occupy mature, high-volume positions where margin pools concentrate in calibration services and software-enabled analytics. Power quality analyzers represent the fastest-growing product category as industrial facilities deploy distributed energy resources requiring continuous harmonic monitoring. Smart testing technology is displacing analog architectures in utility applications where remote diagnostics and predictive maintenance protocols reduce field crew deployment costs.
IEC 61010 safety standards and the EU F-Gas Regulation shape product design requirements, compelling manufacturers to redesign thermal management systems and eliminate prohibited refrigerants from environmental test chambers. The EPA and OSHA enforce complementary frameworks in the United States, with the EPA targeting electromagnetic interference containment and OSHA mandating lockout-tagout verification procedures that drive recurrent instrument replacement cycles. Stakeholders must monitor how the EU AI Act and emerging cybersecurity mandates for grid-connected equipment will rewrite firmware certification requirements and reshape competitive barriers for non-European suppliers.
Market Dynamics
Grid modernization mandates across developed economies are compressing replacement cycles for legacy testing infrastructure while forcing interoperability between analog field instruments and digital asset management platforms.
Growth Catalysts
- EU F-Gas Regulation:Mandatory refrigerant containment in environmental test chambers drives replacement demand for thermal cycling equipment across European calibration laboratories.
- Power utilities:Distributed energy resource integration requires continuous harmonic monitoring, expanding deployment of power quality analyzers at substation and industrial interconnection points.
- Silicon carbide semiconductors:Wide-bandgap device proliferation in electric vehicle inverters and renewable inverters necessitates higher-voltage, higher-frequency validation protocols.
Market Restraints
- Precision resistor networks:Thin-film and wire-wound resistor supply concentrates among Japanese and German specialty component manufacturers, creating input cost volatility for high-accuracy multimeter producers.
- IEC 61010-2-030 compliance:Evolving safety standards for measurement category ratings impose redesign costs and certification delays for handheld instrument portfolios.
- Software-defined instrumentation:General-purpose computing platforms with modular ADC/DAC hardware threaten dedicated test equipment in lower-frequency applications.
Strategic Opportunities
- India:Bureau of Indian Standards mandatory certification for electrical safety testing equipment creates first-mover advantage for pre-qualified suppliers as domestic manufacturing scales under PLI schemes.
- Predictive maintenance protocols:Machine learning-enabled anomaly detection in transformer dissolved gas analysis opens subscription revenue models for instrument vendors.
- EU AI Act:Conformity assessment requirements for AI-enabled diagnostic functions will privilege European vendors with established notified body relationships.
Industry Challenges
- Metrology talent scarcity:Calibration technician shortages in North America and Western Europe extend turnaround times for accredited laboratories and raise service delivery costs.
- Firmware certification complexity:Cybersecurity mandates for grid-connected equipment require ongoing security patch validation, fragmenting engineering resources across multiple national certification tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Testing Equipment Market |
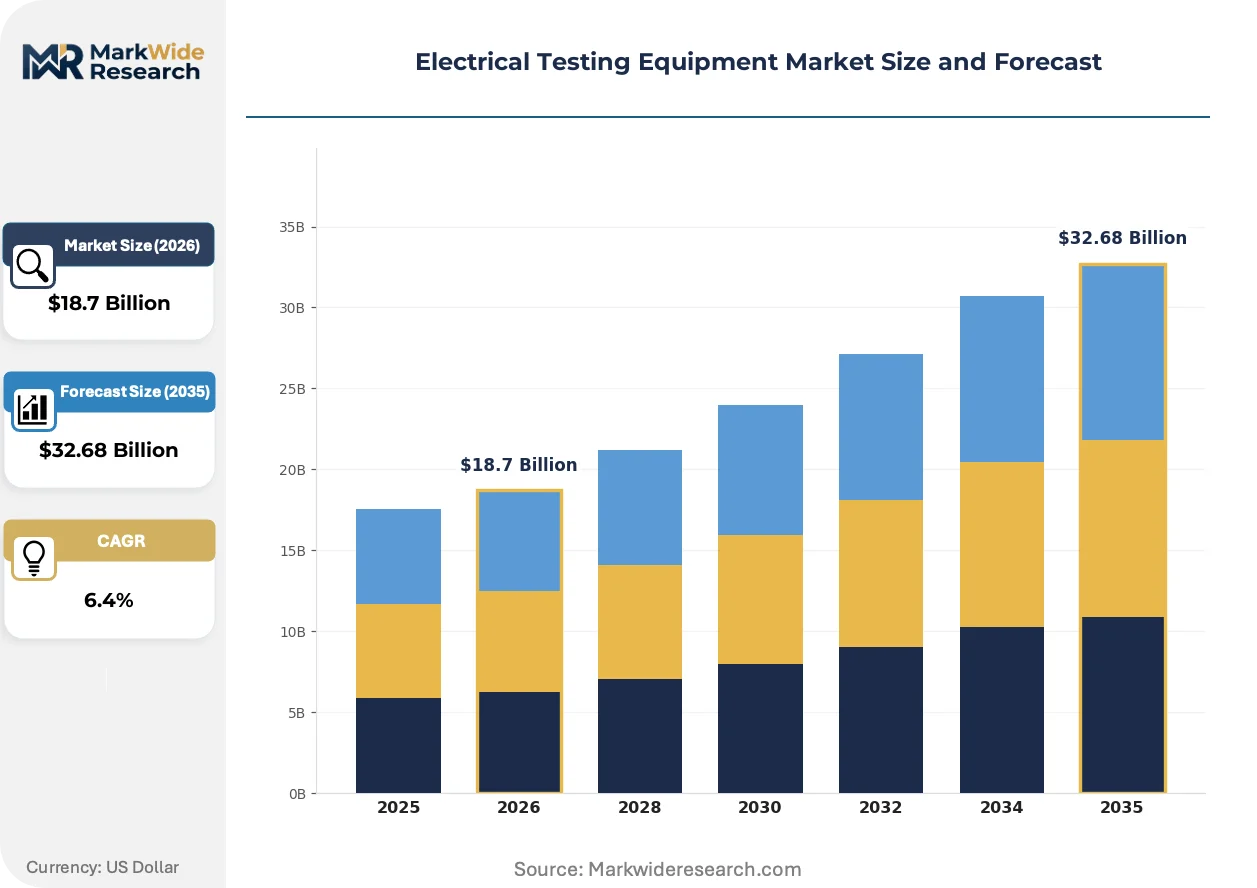
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multimeters, Oscilloscopes, Insulation Testers, Power Quality Analyzers End User: Utilities, Manufacturing, Construction, Telecommunications Technology: Digital, Analog, Hybrid, Smart Testing Application: Electrical Maintenance, Research & Development, Quality Control, Safety Testing |
| Companies Covered | Rohde & Schwarz GmbH & Co. KG, Yokogawa Test & Measurement Corporation, Fluke Corporation, Chroma ATE Inc., National Instruments Corporation, Keysight Technologies Inc., Megger Group Limited, Hioki E.E. Corporation, Tektronix Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Testing Equipment Market Shifts & Advancements
Electrical testing equipment architecture is converging around software-defined measurement cores with cloud-native analytics layers, compressing the traditional boundary between field instrumentation and enterprise asset management systems.
Modular instrument platforms with FPGA-based signal processing cores are unifying previously discrete instrument categories—oscilloscopes, spectrum analyzers, and power analyzers—into reconfigurable hardware substrates. Automotive electrification test labs in Germany and China are adopting these platforms to reduce capital footprint while accommodating evolving validation protocols for 800V architectures. This unification is compressing vendor margins in standalone instrument categories while expanding attach rates for software licenses and calibration service contracts.
The EU AI Act's risk classification framework for diagnostic equipment is mandating explainability requirements for automated fault detection algorithms deployed in utility settings. European notified bodies are developing sector-specific conformity assessment procedures that extend certification timelines by six to twelve months for AI-enabled products. Power quality analyzer manufacturers are responding by segregating AI and non-AI product lines to maintain market access during transitional periods.
Industrial facility operators are unbundling after-sales service contracts from initial equipment purchases, preferring third-party calibration providers with multi-vendor accreditation. This pattern is most visible in German automotive supplier networks and US data center operators, where procurement teams negotiate equipment and service separately to optimize total cost of ownership metrics. Instrument vendors are countering with captive financing arrangements and outcome-based uptime guarantees to retain service revenue attachment.
Electrical Testing Equipment Market Segmentation
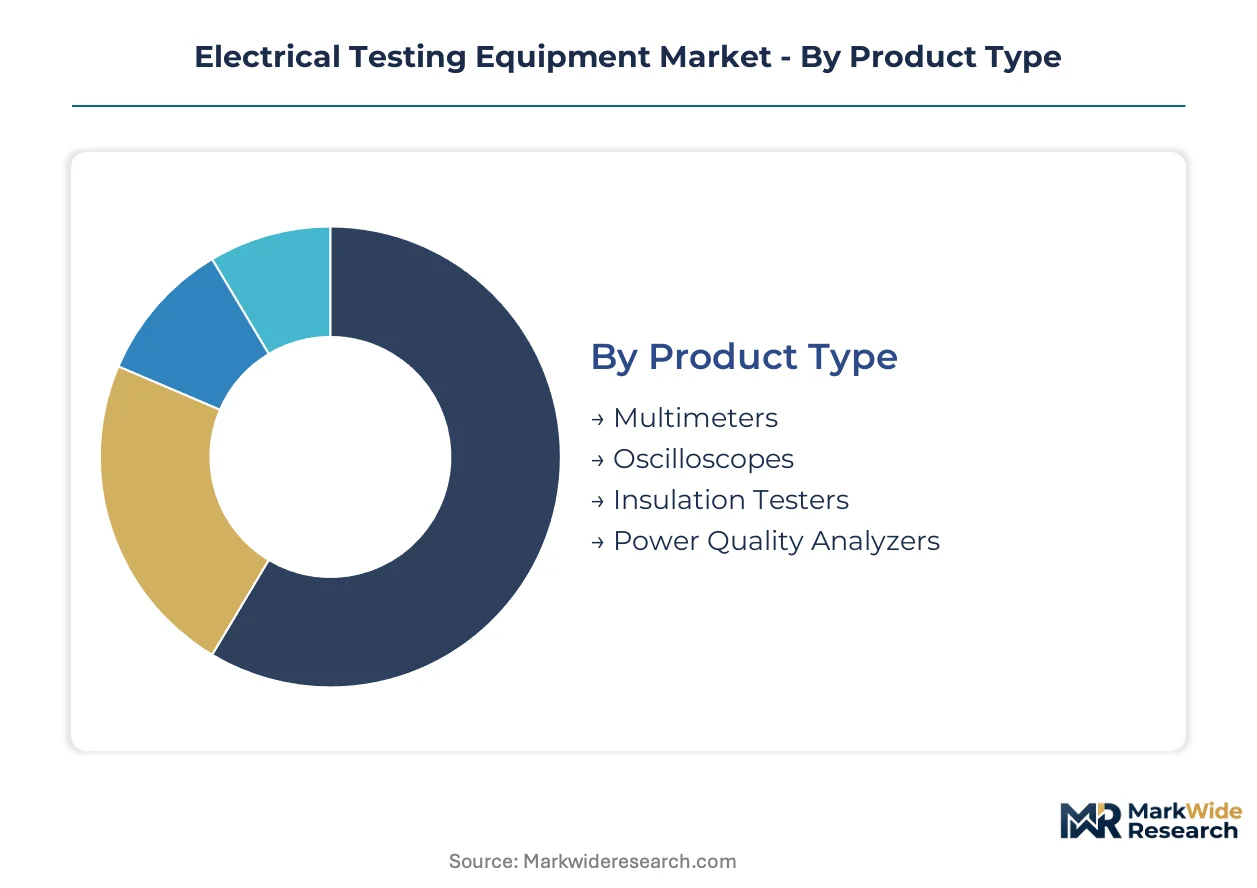
Segmentation in electrical testing equipment reveals divergent capital requirements and margin profiles across product architectures. Procurement patterns vary sharply between utilities prioritizing ruggedized field instruments and semiconductor fabs demanding sub-nanosecond precision.
Product Type:
Capital intensity concentrates in environmental test chambers and precision power analyzers, while handheld multimeters operate on lean manufacturing models with high inventory velocity.
- Multimeters:Handheld and benchtop instruments measuring voltage, current, and resistance with 0.1% to 0.01% accuracy tiers. Demand clusters in German automotive supplier networks where IEC 61010 CAT III/IV ratings are mandatory for production line verification.
- Oscilloscopes:Time-domain instruments capturing signal transients from millihertz to gigahertz bandwidths. China-based EV inverter manufacturers are driving 12-bit vertical resolution adoption for silicon carbide switching characterization.
- Insulation Testers:Megohmmeters verifying dielectric integrity across medium-voltage cable networks. Utilities in the United States deploy these for predictive maintenance on aging underground distribution infrastructure.
- Power Quality Analyzers:Multi-parameter instruments monitoring harmonics, flicker, and voltage sags. These units are expanding most quickly as distributed solar and battery storage proliferate at industrial interconnection points.
Multimeters absorb the bulk of installed capacity; power quality analyzers are expanding most quickly.
End User:
Customer archetypes span from price-sensitive construction contractors to specification-driven semiconductor fabs, with procurement authority residing in distinct organizational functions.
- Utilities:Transmission and distribution operators requiring IEC 61850-compliant instruments for substation automation integration. FERC reliability standards mandate recurrent calibration cycles that anchor service revenue streams.
- Manufacturing:Industrial facilities deploying in-line test systems for motor drives, robotics, and power electronics. German automotive OEMs specify power analyzers with CAN bus logging for production traceability.
- Construction:Electrical contractors purchasing CAT IV-rated multimeters and ground resistance testers for code compliance verification. OSHA lockout-tagout procedures drive replacement demand following field damage incidents.
- Telecommunications:Data center operators and network infrastructure providers sourcing DC power test equipment for battery backup validation. Hyperscale facilities in Virginia and Frankfurt prioritize rack-mountable form factors for density.
Manufacturing commands the largest equipment budget; telecommunications is climbing the fastest as data center construction accelerates.
Technology:
Architecture migration from analog to software-defined cores is rewriting competitive moats and service attach economics across all price tiers.
- Digital:Microprocessor-based instruments with LCD displays and automated ranging. These dominate mid-market procurement in India where BIS certification requirements favor established digital platforms.
- Analog:Electromechanical meter movements with needle indicators. Niche demand persists in educational institutions and explosive atmosphere environments where spark-free operation is critical.
- Hybrid:Analog front ends with digital signal processing backends. Japanese industrial markets favor these for motor testing applications requiring both waveform fidelity and computational analysis.
- Smart Testing:Cloud-connected instruments with predictive analytics and remote firmware updates. The EU AI Act's conformity assessment timelines are slowing European deployment relative to Asian markets.
Digital platforms retain the widest installed base; smart testing is gaining share fastest among grid modernization programs.
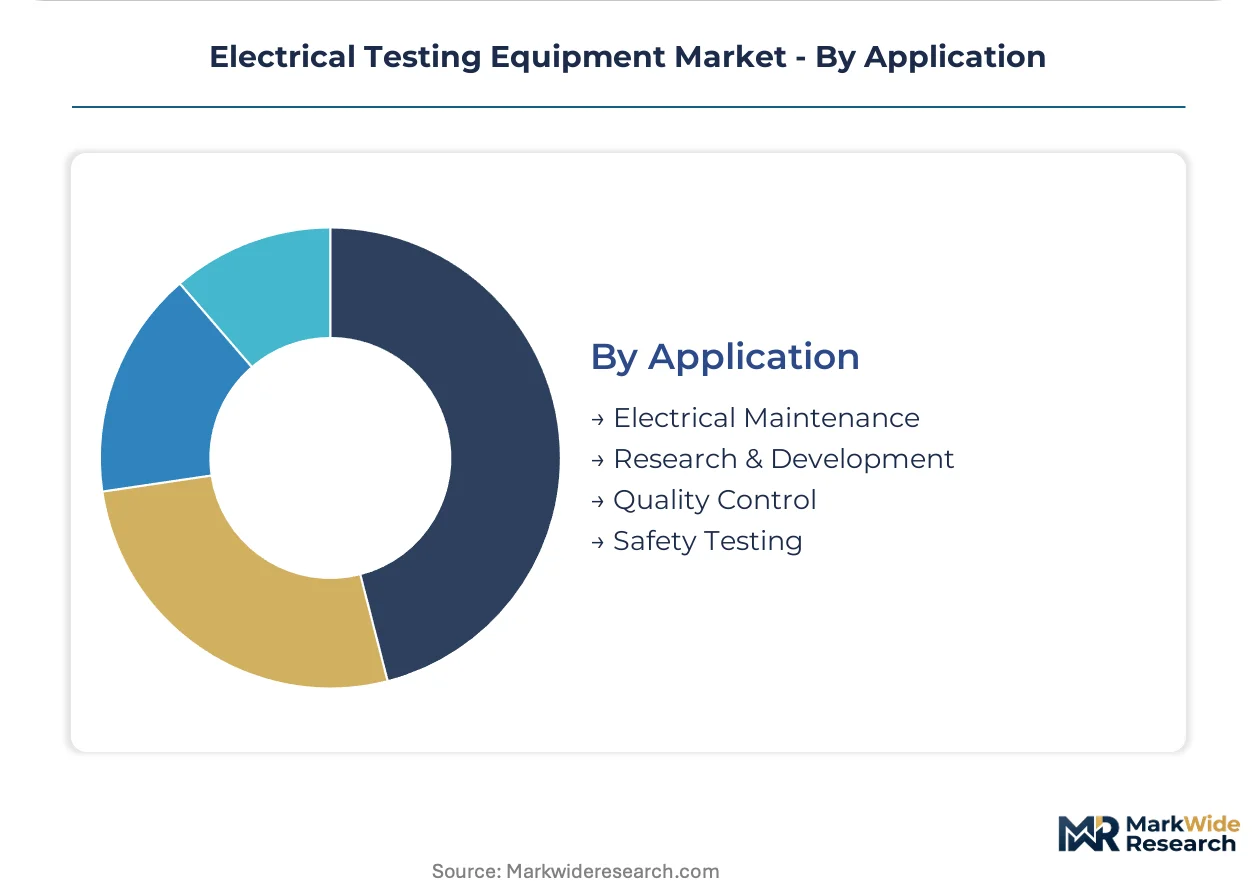
Application:
Use case segmentation determines performance specifications, with safety-critical applications mandating accredited calibration chains that alter vendor selection criteria.
- Electrical Maintenance:Routine troubleshooting and preventive inspection across industrial and commercial facilities. Utilities in Texas and California are expanding predictive maintenance contracts that bundle instrument provision with technician training.
- Research & Development:Characterization of novel semiconductor devices and power converter topologies. Wide-bandgap device proliferation is forcing 10kV probe and 100MHz bandwidth upgrades in German automotive electronics labs.
- Quality Control:Production-line verification of electrical safety and performance parameters. Chinese contract manufacturers are automating insulation resistance testing to reduce manual labor content.
- Safety Testing:Certification of equipment compliance with IEC 61010 and national electrical codes. Third-party test houses in the United States require NIST-traceable calibration certificates that concentrate demand on accredited suppliers.
Electrical maintenance represents the largest application segment; research and development shows the steepest expansion trajectory as EV and renewable inverter development intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of precision electrical testing equipment concentrates in Germany, Japan, and the United States, while consumption spreads across industrializing markets where grid modernization and manufacturing electrification accelerate instrument deployment.
United States
Data center construction in Virginia and Texas drives demand for DC power test equipment and power quality analyzers. FERC reliability standards mandate recurrent calibration cycles that anchor service revenue for instrument vendors. The EPA enforces electromagnetic interference containment rules that shape product design for domestic suppliers.
Germany
Automotive electrification test labs in Stuttgart and Munich adopt modular instrument platforms for 800V architecture validation. The EU F-Gas Regulation compels redesign of thermal management systems in environmental test chambers. Bavarian industrial clusters favor hybrid analog-digital instruments for motor testing applications.
China
EV inverter manufacturers in Shenzhen and Shanghai drive 12-bit oscilloscope adoption for silicon carbide switching characterization. MIIT standards for grid-connected equipment cybersecurity fragment firmware certification requirements. Yangtze River Delta contract manufacturers automate insulation resistance testing to reduce labor content.
Japan
Precision resistor network supply concentrates among specialty component manufacturers serving high-accuracy multimeter producers. METI promotes smart testing technology adoption through industrial digitalization incentives. Nagoya-area industrial markets favor calibration expertise embedded in power measurement instruments.
India
Bureau of Indian Standards mandatory certification for electrical safety testing equipment creates first-mover advantage for pre-qualified suppliers. PLI schemes accelerate domestic manufacturing scale-up in Gujarat and Maharashtra. Telangana-based utilities expand predictive maintenance contracts bundling instrument provision with technician training.
Electrical Testing Equipment Market Competitive Landscape
The competitive structure tilts toward precision instrumentation specialists with deep calibration expertise and software-enabled service platforms. Market concentration varies by product tier: handheld multimeters support numerous mid-tier suppliers, while high-frequency test equipment for semiconductor validation consolidates around R&D-intensive players. Two strategic archetypes dominate: diversified electronics conglomerates leveraging cross-divisional technology transfer, and focused test-and-measurement pure-plays building moats through metrology talent retention. Competitive moves center on modular hardware platforms that compress standalone instrument margins while expanding software attach rates, plus captive financing arrangements to counter third-party calibration unbundling.
Among diversified electronics conglomerates, Rohde & Schwarz GmbH & Co. KG exemplifies the precision instrumentation archetype with its German engineering heritage. Yokogawa Test & Measurement Corporation and Hioki E.E. Corporation occupy positions within the Asian industrial specialist tier, where deep calibration relationships anchor customer retention. These three represent contrasting geographic centers of metrology expertise that shape competitive dynamics across regional procurement patterns.
| Leading Market Players |
|---|
| Rohde & Schwarz GmbH & Co. KG |
| Yokogawa Test & Measurement Corporation |
| Fluke Corporation |
| Chroma ATE Inc. |
| National Instruments Corporation |
| Keysight Technologies Inc. |
| Megger Group Limited |
| Hioki E.E. Corporation |
| Tektronix Inc. |
| Others |
Supply & Pricing Matrix
Calibration technician concentration in Bavaria and Nagoya creates labor-cost differentials that widen pricing-tier spreads between premium metrology-grade instruments and economy digital multimeters. Japanese and German specialty component manufacturers command input premiums for thin-film resistor networks, compressing margins for mid-tier producers while insulating precision instrument vendors from price erosion.
Pricing Analysis
Margin tightening in economy handheld multimeters reflects software-defined instrumentation substitution, while premium power analyzers sustain pricing power through IEC 61850 certification requirements. Three-tier pricing structure across premium, standard, and economy levels separates NIST-traceable calibration bundles from bare-hardware transactions. Price differentiation hinges on measurement category ratings and embedded firmware analytics. Construction contractors exhibit highest price sensitivity; semiconductor fabs prioritize specification compliance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale data center demand for rack-mountable DC power test equipment, while distributor networks serve fragmented electrical contractor procurement. Component supply concentrates in Japan, Germany, and the United States for precision resistor networks, FPGA signal processing cores, and ADC/DAC modules. Manufacturing draws from specialty thin-film substrate foundries and wire-wound resistor coil suppliers. Single-source vulnerability in Japanese precision component supply creates exposure to logistics disruption. Distribution runs through authorized calibration laboratories and industrial distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electrical testing equipment market is consolidating around software-enabled service platforms, with firmware certification complexity forcing weaker analog-focused players toward exit or acquisition.
For Market Incumbents: Acquire cloud-native analytics capabilities to counter third-party calibration unbundling. Consolidate metrology talent pools in Germany and Japan before competitors lock in calibration technician pipelines. Software-defined instrumentation substitution threatens standalone oscilloscope margins; modular FPGA-based platforms with attach-rate software licensing defend position. For New Entrants and Emerging Players: Capture BIS pre-qualification status in India before PLI scheme manufacturing scale-up closes the certification window. Target predictive maintenance subscription models for US utility transformer dissolved gas analysis, where incumbent service bundling remains weak. Lead with technician training partnerships to bypass entrenched calibration relationships. For Investors and Strategic Acquirers: Re-rating potential sits with smart testing pure-plays given EU AI Act conformity assessment timelines privileging established notified body relationships. Five-to-ten year viability favors vendors with captive metrology expertise and recurring service revenue attachment. Watch for inflection when cybersecurity patch validation requirements fragment engineering resources across multiple national certification tracks.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Calibration Service Networks | Captures recurring revenue streams from FERC-mandated utility calibration cycles. |
| Modular Instrument Platform Development | Unifies oscilloscope, spectrum analyzer, and power analyzer functions for 800V EV validation labs. |
| AI-Enabled Diagnostic Firmware Investment | Positions for EU AI Act explainability requirements in utility fault detection applications. |
| Backward Integration into Precision Resistor Supply | Reduces exposure to Japanese and German specialty component manufacturer pricing volatility. |
| Geographic Expansion into India BIS Certification | Secures first-mover advantage before PLI scheme domestic manufacturing scale-up accelerates. |
Research Methodology
SEC filings, IEC standards documentation, and utility procurement databases formed the secondary backbone, supplemented by customs records for precision component trade flows. Primary interviews with calibration laboratory directors, utility maintenance planners, semiconductor test engineers, and industrial distributor procurement heads validated demand assumptions. Bottom-up instrument shipment analysis and top-down electrification capex aggregation provided triangulation across the analysis window.
Historical trendline analysis of multimeter, oscilloscope, and power quality analyzer deployment patterns informed projection modeling across product type, end user, technology architecture, and application segments. CAGRs derived from segment-level growth rate reconciliation against grid modernization investment trajectories and silicon carbide semiconductor adoption curves. Forecast inputs incorporated EU F-Gas Regulation replacement cycle timing and MIIT cybersecurity compliance cost estimates.
The model holds under stable regulatory certification timelines; deviation in EU AI Act enforcement intensity or BIS mandate acceleration would shift competitive positioning. Forecasts reflect base-case assumptions for metrology talent availability and precision component supply continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Chemical Detector Market
Testing Equipment
Global Rheometer and Viscometer Market
Testing Equipment
Geochemical Services Market
Testing Equipment
Water Test Kits Market
Testing Equipment
PFAS Ultra-Trace Water Analysis Test Instruments Market
Testing Equipment
Global Chromatography Columns Market
Testing Equipment
Global Lab Automation in Analytical Chemistry Market
Testing Equipment
Sand Testing Equipments Market
Testing Equipment
Europe Process Analytics Market
Testing Equipment
Gas Calorimeter Market
Testing Equipment
Viscometer Market
Testing Equipment
Magnesium Testing Reagents Market
Testing Equipment
Dynamic Vapor Sorption Analyzer Market
Testing Equipment
Laboratory Centrifuge and Accessories Market
Testing Equipment
Rubber Testing Equipment Market
Testing Equipment
Paper Tester Market