
 Pharmaceutical Grade Sodium Carbonate Market | 2026-2036
Pharmaceutical Grade Sodium Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Grade Sodium Carbonate Market Outlook
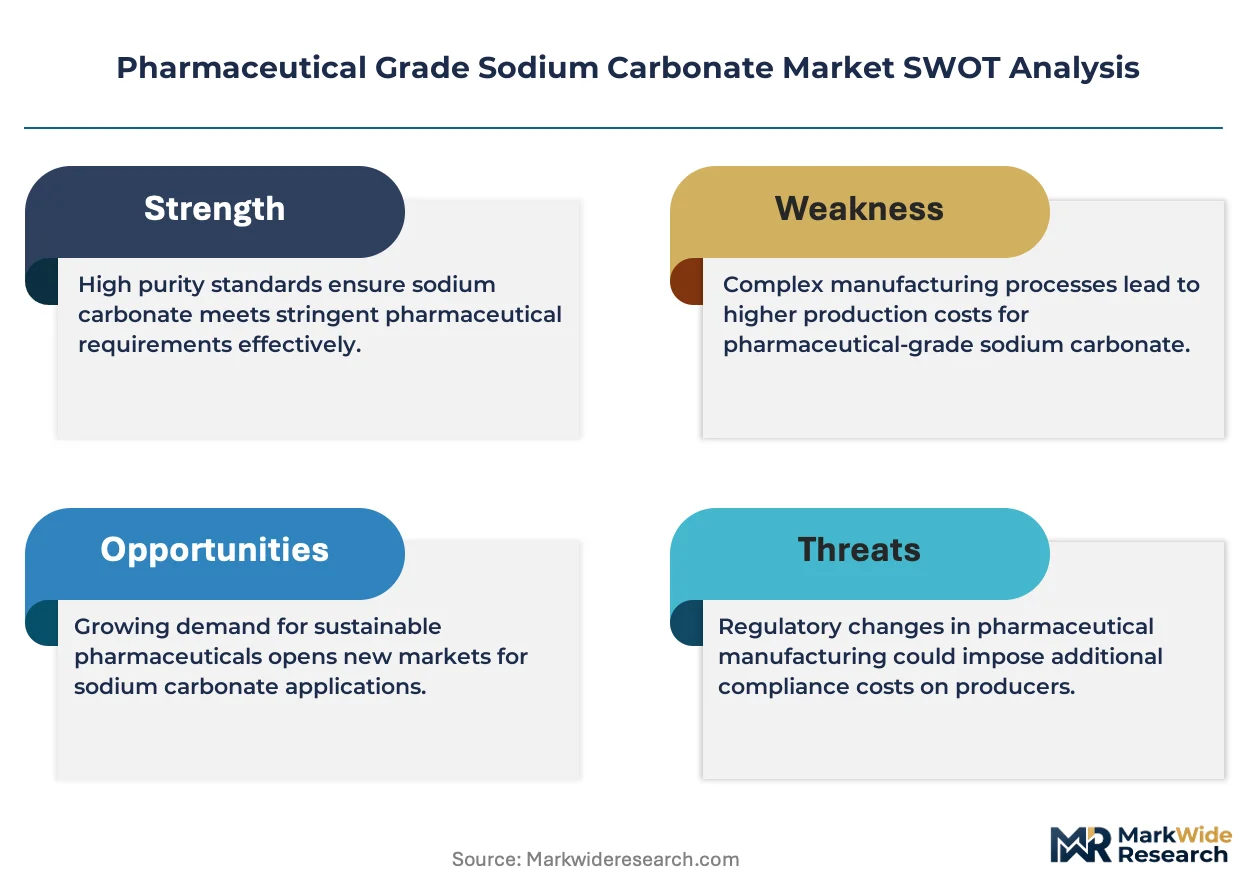
The EU Green Deal's chemical sustainability benchmarks are recalibrating pharmaceutical excipient sourcing across Europe. Solvay SA leverages its integrated trona-to-soda ash chain to secure feedstock consistency for high-purity grades. Novacarb (Novacap Group) anchors production in France with dedicated pharmaceutical lines certified under EMA guidelines. Dr. Paul Lohmann GmbH KG specializes in ultra-low heavy-metal specifications that differentiate its carbonate for injectable applications.
Pharmaceutical grade sodium carbonate is a high-purity alkali salt meeting pharmacopeial standards for identity, assay, and impurity profiles, typically manufactured via the Solvay process or purification of natural trona followed by crystallization and drying to achieve specified particle size and moisture content. It functions primarily as a pH regulator, buffering agent, and alkalizing excipient in oral and parenteral drug formulations. Powder dominates current volume due to its dissolution kinetics in tablet compression and granulation workflows, while granules command premium positioning in direct-compression formulations where flowability governs batch uniformity. The excipients application segment leads value contribution as biologic formulations require tighter endotoxin and particulate control than conventional antacid applications.
EMA's revised excipient risk assessment guidelines and USP-NF monograph updates are tightening elemental impurity limits, forcing suppliers to validate purification trains against ICH Q3D thresholds. FDA inspection protocols for active pharmaceutical ingredient and excipient facilities now prioritize continuous process verification over periodic testing, reshaping capital allocation toward in-line analytics. REACH registration requirements in Europe add compliance layers for imported material, favoring regional producers with established dossiers. Stakeholders must weigh backward integration against specialized tolling partnerships as purity thresholds diverge between generic oral solids and novel biologic delivery systems.
Market Dynamics
The pharmaceutical grade sodium carbonate market is tightening around purity verification infrastructure as biologic drug pipelines multiply and FDA inspection protocols shift toward continuous process verification rather than batch testing.
Growth Catalysts
- Biologic formulation expansion:Monoclonal antibody and cell therapy production requires endotoxin-controlled excipients, pulling pharmaceutical grade material into parenteral applications previously served by lower-purity grades.
- EMA excipient risk assessment guidelines:Updated dossier requirements for imported material favor European producers with established REACH registrations and validated purification trains.
- Trona-to-soda ash integration:Wyoming-sourced natural trona offers feedstock consistency advantages over synthetic Solvay process material for heavy metal-sensitive applications.
Market Restraints
- Energy cost volatility:Natural gas and electricity account for substantial production cost share in thermal processing stages, compressing margins for non-integrated producers.
- Supply concentration in Western Europe:Germany and France host the majority of certified pharmaceutical lines, creating geographic vulnerability to regional logistics disruptions.
- Potassium carbonate substitution:Some oral solid formulations tolerate potassium carbonate as alkalizing agent, limiting sodium carbonate pricing power in non-injectable segments.
Strategic Opportunities
- India CDMO expansion:Contract development and manufacturing organizations in Hyderabad and Bangalore are building biologic capacity requiring import substitution of high-purity excipients.
- Continuous manufacturing adoption:Direct compression tableting lines favor granule morphology over powder, opening premium positioning for specialized particle engineering.
- US FDA quality agreements:Formalized excipient supplier qualification programs create stickiness for early-movers with validated analytical packages.
Industry Challenges
- Analytical chemistry talent scarcity:ICP-MS and endotoxin testing expertise is concentrated among aging specialists, slowing method transfer for new production lines.
- Capital intensity of in-line PAT:Process analytical technology for real-time purity verification requires substantial upfront investment with payback periods extending across multiple product cycles.
- Multi-compendial harmonization:Divergent USP-NF, EP, and JP monograph requirements force redundant testing protocols for global suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Grade Sodium Carbonate Market |
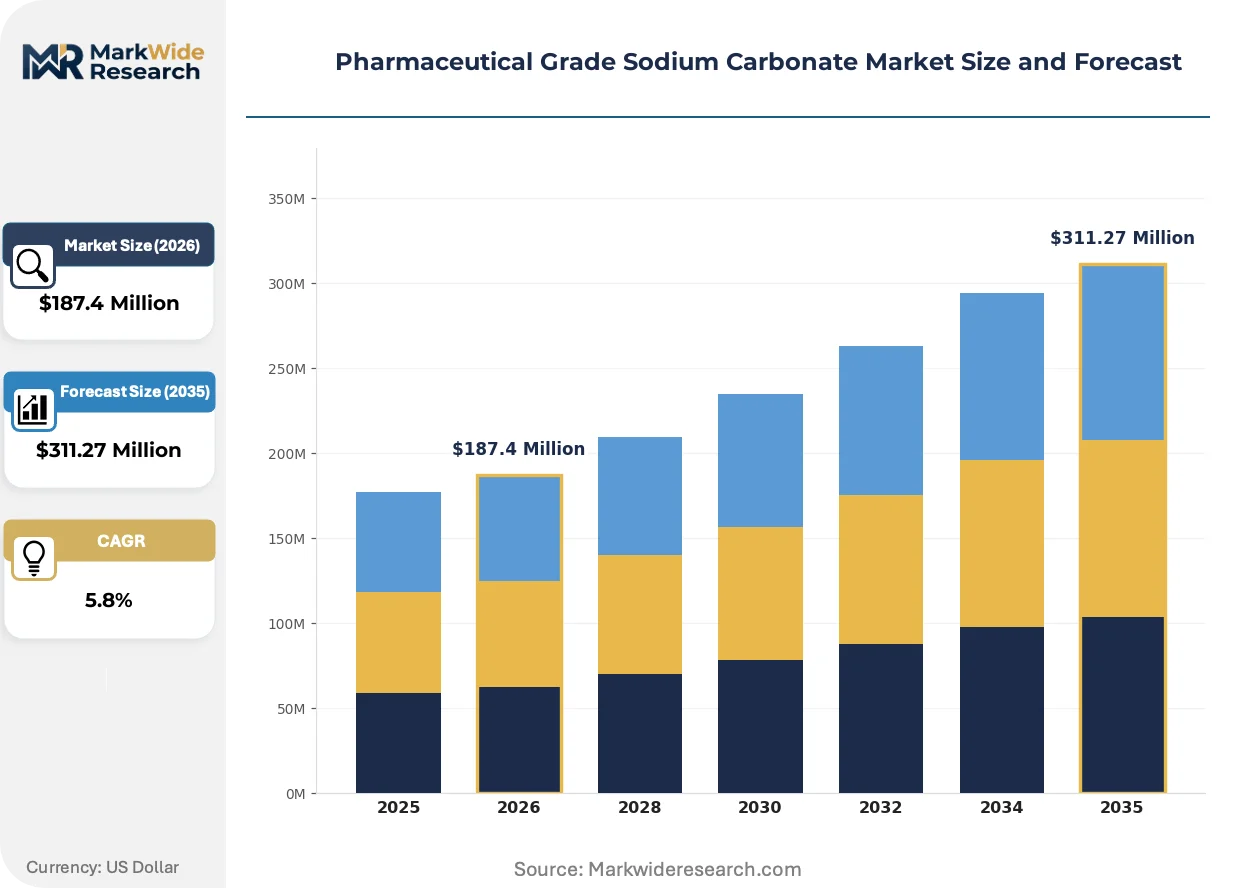
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Liquid, Tablets Application: Antacid, pH Regulator, Drug Formulation, Excipients End User: Pharmaceutical Companies, Contract Manufacturing Organizations, Research Laboratories, Hospitals Distribution Channel: Direct Sales, Online Retail, Distributors, Pharmacy Chains |
| Companies Covered | Solvay SA, Novacarb (Novacap Group), Dr. Paul Lohmann GmbH KG, CIECH S.A., Natural Soda LLC, Jost Chemical Co., Tianjin Chengyuan Chemical Co. Ltd., Weifang Hongyuan Chemical Co. Ltd., Tronox Alkali Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Grade Sodium Carbonate Market Strategic Shifts
Process analytical technology and digital batch records are compressing quality assurance timelines while regulatory convergence around ICH Q3D elemental impurity limits standardizes validation protocols across major markets.
Membrane filtration and crystallization control systems are decentralizing quality assurance from centralized QC laboratories to production-floor decision points. Biologic drug manufacturers are adopting these in-line analytics fastest, driven by batch release urgency for temperature-sensitive therapeutics. Real-time heavy metal detection is compressing holding times and reducing quarantine inventory carrying costs.
REACH registration requirements for imported sodium carbonate are tightening documentation burdens on non-European suppliers. The European Chemicals Agency's extended safety data sheet obligations now cover pharmaceutical excipients previously exempt under downstream user provisions. Asian exporters are responding by establishing tolling partnerships with European converters rather than direct importation.
Procurement consolidation among top-ten pharmaceutical manufacturers is compressing supplier rosters and extending contract durations. Single-source agreements now span five-to-seven years with embedded price adjustment mechanisms, displacing spot-market purchasing for strategic excipients. This concentration is most visible in Germany, where three multinational drugmakers account for substantial pharmaceutical grade sodium carbonate offtake.
Pharmaceutical Grade Sodium Carbonate Market Segmentation
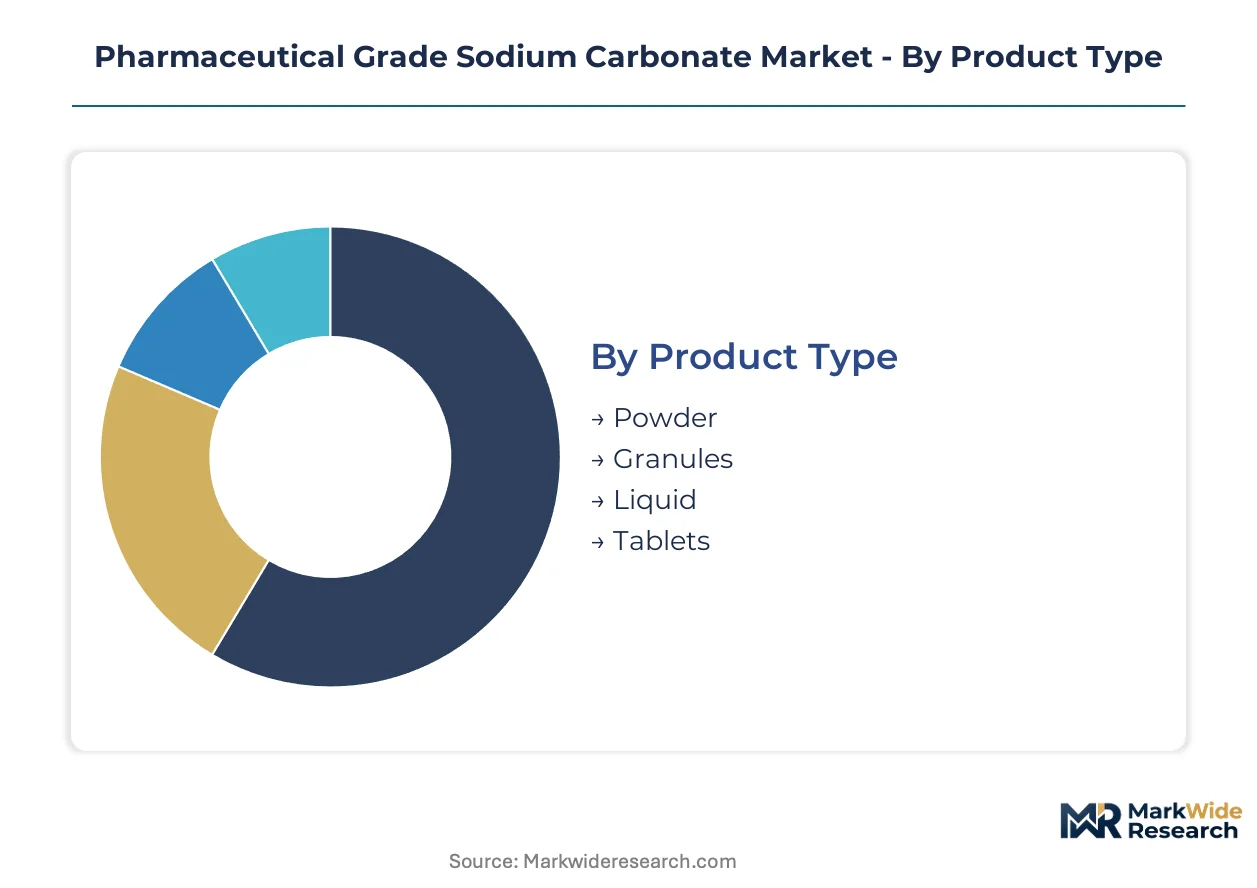
Purity specifications diverge sharply across pharmaceutical grade sodium carbonate segments, with endotoxin limits and heavy metal thresholds determining eligibility for parenteral versus oral applications. Buyers segment procurement by formulation risk class, not commodity pricing, creating tiered qualification barriers that reshape competitive dynamics.
Product Type:
Formulation workflow determines powder versus granule selection, with dissolution kinetics and flowability governing equipment compatibility and batch uniformity.
- Powder:Fine particulate morphology accelerates dissolution in wet granulation and tablet compression workflows. Demand concentrates in high-volume generic oral solid facilities across India and China, where rapid wetting reduces processing cycle times.
- Granules:Engineered particle size distribution enables direct-compression tableting without intermediate granulation steps. German and Swiss manufacturers of biologic co-formulations pay premiums for flowability-certified grades that minimize weight variation in high-speed rotary presses.
- Liquid:Aqueous solutions or slurries for parenteral buffer preparation, typically supplied in sterile containers for compounding pharmacies.
- Tablets:Pre-compressed alkali tablets for laboratory and small-batch alkalization, common in research settings.
Powder leads on scale; granules lead on momentum.
Application:
Regulatory risk stratification separates excipient-grade material from industrial applications, with ICH Q3D compliance costs filtering supplier participation.
- Excipients:High-purity sodium carbonate functions as pH regulator and buffering agent in oral and parenteral drug formulations. US FDA inspection protocols for excipient facilities now prioritize continuous process verification, favoring suppliers with validated in-line analytics over batch-testing operations.
- pH Regulator:Alkalizing agent for active pharmaceutical ingredient synthesis and final formulation adjustment. EMA's revised risk assessment guidelines tighten documentation for imported material, benefiting European producers with established REACH dossiers.
- Drug Formulation:Direct incorporation into finished dosage forms including tablets, capsules, and injectable solutions.
- Antacid:Lower-specification grades for over-the-counter gastrointestinal products with less stringent endotoxin requirements.
Excipients command the steepest expansion trajectory as biologic pipelines multiply; antacid applications face substitution pressure from magnesium and calcium salts.
End User:
Procurement sophistication varies dramatically across buyer types, with pharmaceutical multinationals imposing supplier qualification programs that smaller laboratories bypass.
- Pharmaceutical Companies:Integrated drug manufacturers with dedicated excipient qualification teams and multi-year supply agreements. Top-ten global manufacturers now consolidate supplier rosters into single-source five-to-seven-year contracts with embedded price adjustment mechanisms.
- Contract Manufacturing Organizations:CDMOs in Hyderabad and Bangalore are building biologic capacity requiring import substitution of high-purity excipients previously sourced from European converters.
- Research Laboratories:Academic and commercial R&D facilities with lower volume requirements and broader specification tolerance.
- Hospitals:Compounding pharmacies preparing patient-specific parenteral formulations under USP 797 and 800 guidelines.
Pharmaceutical companies dominate procurement volume; CDMOs are climbing fastest as biologic outsourcing accelerates.
Distribution Channel:
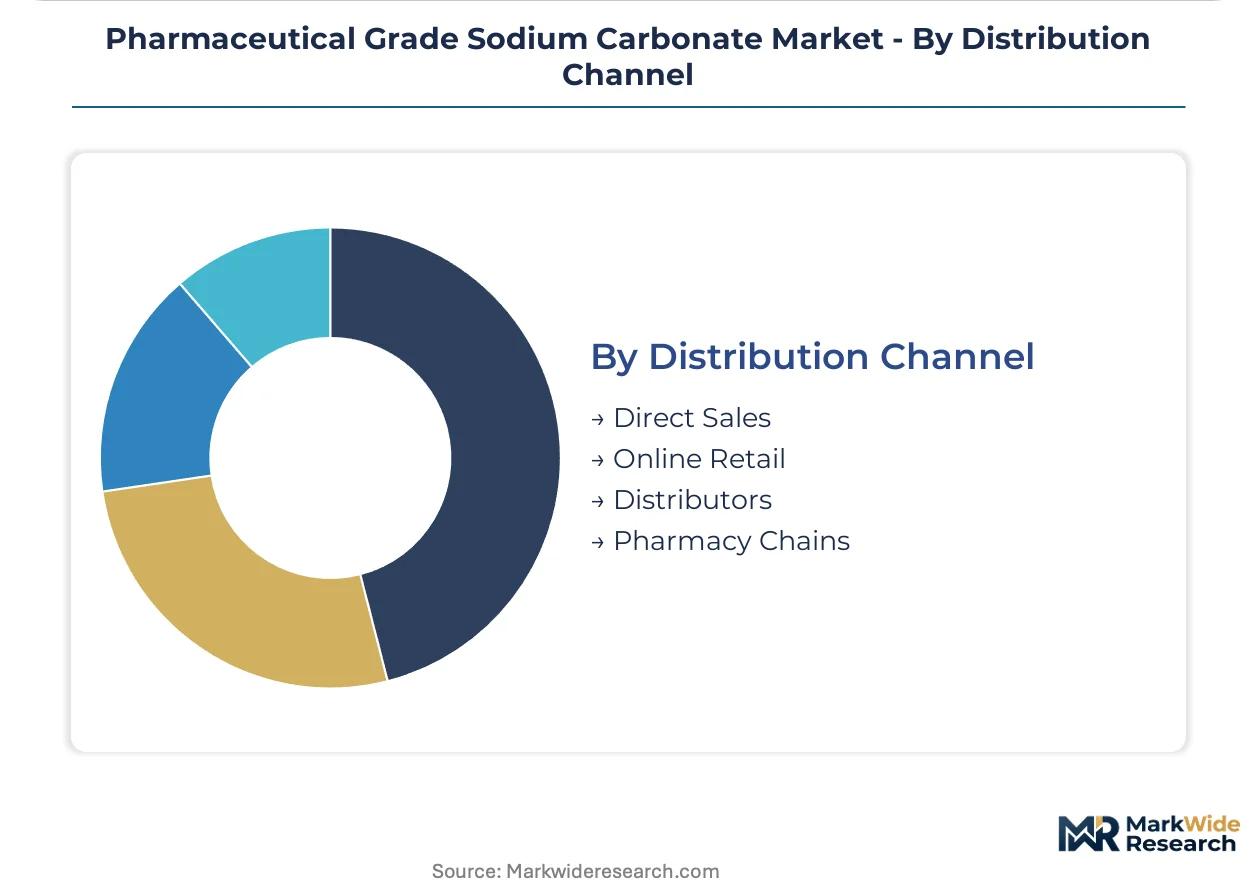
Channel selection reflects buyer scale and regulatory documentation requirements, with direct relationships reserved for qualified strategic suppliers.
- Direct Sales:Manufacturer-to-manufacturer relationships for qualified pharmaceutical grade material with full regulatory dossiers. Solvay SA and Dr. Paul Lohmann GmbH KG anchor this channel through dedicated account management for top-tier drugmakers.
- Distributors:Regional chemical distributors with excipient handling certification and temperature-controlled warehousing, serving mid-tier manufacturers without direct supplier relationships.
- Online Retail:E-commerce platforms for laboratory-scale quantities and research-grade material with expedited fulfillment.
- Pharmacy Chains:Limited channel for pre-formulated antacid products and compounding supplies at retail level.
Direct sales capture the premium tier; distributors expand most quickly among emerging manufacturers in Asia-Pacific markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's chemical industry pioneered pharmaceutical-grade alkali purification in the early twentieth century, establishing quality protocols that now govern endotoxin-controlled excipient production worldwide. Solvay SA and Dr. Paul Lohmann GmbH KG trace their pharmaceutical carbonate lineages to this industrial heritage, anchoring specialized production clusters that still set purity benchmarks for parenteral applications.
Germany
Biologic drug manufacturing expansion in Frankfurt-Rhine-Main and Munich clusters drives demand for ultra-low heavy-metal carbonate specifications. EMA's revised excipient risk assessment guidelines tighten documentation requirements for imported material, favoring domestic producers with established REACH registrations. Solvay SA operates integrated pharmaceutical lines in Bernburg, leveraging captive trona feedstock to secure batch-to-batch consistency for injectable-grade output.
United States
Wyoming's Green River Basin supplies natural trona feedstock for heavy metal-sensitive parenteral formulations, displacing synthetic Solvay process material in premium applications. FDA inspection protocols now prioritize continuous process verification over periodic batch testing, reshaping capital allocation toward in-line analytics at domestic facilities. Natural Soda LLC and Tronox Alkali Corporation anchor production clusters serving West Coast biologic drug manufacturers.
France
Novacarb's dedicated pharmaceutical lines in Dombasle-sur-Meurthe supply carbonate certified under EMA guidelines for European biologic formulators. The EU Green Deal's chemical sustainability benchmarks recalibrate sourcing decisions, with French producers leveraging nuclear-powered electrolysis to reduce carbon intensity in thermal processing stages. Paris-Saclay biotech corridor demand concentrates procurement among producers with validated ICH Q3D elemental impurity protocols.
India
CDMO expansion in Hyderabad and Bangalore biotech corridors requires import substitution of high-purity excipients previously sourced from European converters. CDSCO's alignment with ICH Q3D guidelines accelerates local qualification of pharmaceutical-grade material for parenteral applications. Domestic chemical manufacturers are establishing tolling partnerships with German specialists to transfer endotoxin-controlled production expertise.
China
Tianjin and Weifang chemical clusters supply powder-grade carbonate for high-volume generic oral solid facilities serving domestic and export markets. NMPA's pharmacopeial updates tighten elemental impurity limits, forcing purification train upgrades at legacy soda ash producers. Yangtze River Delta biologic drug manufacturers are qualifying local excipient suppliers to reduce import dependency for parenteral buffer applications.
Pharmaceutical Grade Sodium Carbonate Market Competitive Environment
Premium-margin players sit above commodity-margin players across purification capability and regulatory dossier depth, with endotoxin-controlled production lines commanding pricing multiples over oral-grade material. The market structures around three tiers: integrated trona-to-pharmaceutical producers with captive feedstock, specialized tolling converters with validated analytical packages, and commodity soda ash suppliers attempting upstream qualification. Consolidation pressures favor backward integration into feedstock control and multi-compendial certification investments over geographic expansion.
Within the integrated producer tier, Solvay SA exemplifies the trona-anchored archetype with Wyoming-sourced feedstock consistency, while Dr. Paul Lohmann GmbH KG occupies the specialist position in ultra-low heavy-metal specifications for injectable applications. Novacarb represents the regional converter model with EMA-certified pharmaceutical lines serving European biologic formulators. These three anchors illustrate the competitive divergence between feedstock-integrated, specialty-purity, and regionally-focused qualification strategies.
| Leading Market Players |
|---|
| Solvay SA |
| Novacarb (Novacap Group) |
| Dr. Paul Lohmann GmbH KG |
| CIECH S.A. |
| Natural Soda LLC |
| Jost Chemical Co. |
| Tianjin Chengyuan Chemical Co. Ltd. |
| Weifang Hongyuan Chemical Co. Ltd. |
| Tronox Alkali Corporation |
| Others |
Value Chain & Pricing Dynamics
Continuous process verification technology adoption simultaneously compresses production economics and consolidates supply authority among German and US producers with validated in-line analytics, leaving batch-testing operators exposed to margin erosion from FDA inspection protocol shifts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates endotoxin-controlled parenteral grades from oral-solid excipients and antacid applications. Certification tier and volume scale drive price differentiation, with biologic-grade material commanding substantial premiums over generic oral formulations. Cost compression in standard-grade segments is intensifying because Indian and Chinese generic manufacturers negotiate aggressive supply agreements. Pharmaceutical multinationals show least price sensitivity due to single-source contract stickiness, while research laboratories and compounding pharmacies exhibit highest elasticity.
Supply Chain Analysis
EMA's revised excipient risk assessment guidelines and CDSCO's ICH Q3D alignment are reshaping sourcing toward domestic-content validation and regional tolling partnerships. Supply concentrates in Germany, the United States, and France, with Wyoming trona and European synthetic lines feeding purification trains. Feedstock draws from natural trona deposits and synthetic Solvay process outputs, with energy inputs and analytical chemistry talent constraining capacity expansion. Single-source vulnerability runs through the concentrated German pharmaceutical cluster, where three multinational drugmakers anchor substantial offtake. Distribution runs through direct manufacturer relationships for qualified material and regional distributors for mid-tier buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pharmaceutical grade sodium carbonate market functions as a stable compounder anchored by biologic drug pipeline expansion and tightening pharmacopeial purity requirements that sustain pricing power across economic cycles.
For Market Incumbents: Lock in multi-year quality agreements with top-ten pharmaceutical manufacturers before CDMO procurement consolidation advances further. Defend against potassium carbonate substitution in oral solid segments by certifying additional parenteral-grade capacity under EMA and FDA protocols. Prioritize backward integration into Wyoming trona feedstock to secure batch-to-batch consistency for heavy metal-sensitive applications. For New Entrants and Emerging Players: Enter via tolling partnerships with established European converters to access validated endotoxin-controlled production expertise without capital-intensive greenfield investment. Target Hyderabad and Bangalore CDMO corridors where biologic capacity expansion outpaces local excipient qualification. Pursue analytical chemistry talent acquisition as primary go-to-market differentiator against legacy batch-testing operators. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap specialty chemical converters because regulatory dossier depth creates sticky customer relationships and high switching costs for pharmaceutical buyers. The 5-10 year viability window favors producers with multi-compendial certification spanning USP-NF, EP, and JP monographs. Watch for ICP-MS and endotoxin testing specialist acquisitions as early inflection signals of consolidation intent.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Trona Feedstock | Wyoming-sourced natural trona secures heavy metal consistency for parenteral-grade output. |
| Multi-Compendial Certification Investment | USP-NF, EP, and JP alignment reduces redundant testing for global pharmaceutical suppliers. |
| Continuous Manufacturing Partnership | Direct-compression granule supply agreements capture premium positioning in high-speed tableting. |
| Analytical Chemistry Talent Acquisition | ICP-MS and endotoxin expertise concentration accelerates method transfer for new production lines. |
| CDMO Corridor Supply Agreement | Hyderabad and Bangalore biologic capacity expansion drives import substitution demand for high-purity excipients. |
Study Parameters
Direct dialogue with pharmaceutical manufacturing executives, excipient procurement leads, regulatory affairs directors, and CDMO operations managers grounded the qualitative foundation, cross-referenced with FDA inspection databases, EMA submission records, USP-NF monograph updates, and REACH registration filings. Bottom-up and top-down triangulation validated volume estimates against customs trade data and pharmaceutical production statistics.
Bottom-up modeling aggregated grade-specific demand across formulation applications, while top-down analysis cross-checked against regional biologic drug pipeline capacity and excipient intensity assumptions. Segmentation dimensions included purity tier, particle morphology, end-use application, and regional regulatory cluster. CAGRs derived from regression analysis of historical consumption patterns and projected biologic formulation expansion across the analysis window, with ICH Q3D implementation timelines and EMA excipient guideline revisions as key forecast inputs.
Inputs from primary interviews and secondary regulatory databases were available through the study window; gaps in real-time CDMO procurement data and confidential contract pricing introduce uncertainty bands around volume projections. Forecasts reflect documented assumptions regarding biologic pipeline advancement and pharmacopeial harmonization progress. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Pharma Grade Ibuprofen API Market
Pharmaceutical Ingredients
Cetrorelix Acetate API Market
Pharmaceutical Ingredients
Global High Potency Active Pharmaceutical Ingredient (HPAPI) Market
Pharmaceutical Ingredients
Mitotic Inhibitors Market
Pharmaceutical Ingredients
Flurbiprofen Market
Pharmaceutical Ingredients
Acetaminophen API Market
Pharmaceutical Ingredients
Diosmin API Market
Pharmaceutical Ingredients
Transdermal Drugs Market
Pharmaceutical Ingredients
Oridonin Market
Pharmaceutical Ingredients
Global Pharmaceutical Excipients Market
Pharmaceutical Ingredients
Oxycodone Drugs Market
Pharmaceutical Ingredients
Calcium Folinate for Injection Market
Pharmaceutical Ingredients
Pharma Grade Sodium Bicarbonate Market
Pharmaceutical Ingredients
France Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Alpha Lipoic Acid API Market
Pharmaceutical Ingredients
Citicoline Market