
 Liquid Chromatography Mass Spectrometry (LCMS) Market | 2026-2036
Liquid Chromatography Mass Spectrometry (LCMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Chromatography Mass Spectrometry (LCMS) Market Insights
A shortage of trained mass spectrometrists is unwinding capacity expansion plans at several instrument manufacturers. Thermo Fisher Scientific leverages its captive consumables stream to sustain recurring revenue per installed system. Waters Corporation anchors its competitive position through proprietary column chemistries that lock in method transfer costs for pharmaceutical clients. Agilent Technologies competes by extending service contracts that reduce instrument downtime in high-throughput clinical laboratories.
Liquid chromatography mass spectrometry combines physical separation via liquid chromatography with mass-based detection, typically achieving mass accuracies below 5 ppm in high-resolution configurations and operating at flow rates from nanoliters to milliliters per minute depending on ion source design. Its primary commercial purpose centers on identifying and quantifying compounds in complex matrices for pharmaceutical development, environmental monitoring, and clinical diagnostics. Triple quadrupole systems dominate routine quantitative workflows in regulated pharmaceutical laboratories due to their selectivity and reproducibility, while quadrupole-time of flight platforms capture expanding demand in metabolomics and biopharma characterization where exact mass measurements prove essential. Electrospray ionization remains the most broadly deployed interface technology, though atmospheric pressure chemical ionization retains critical utility for nonpolar analytes in environmental and food safety applications.
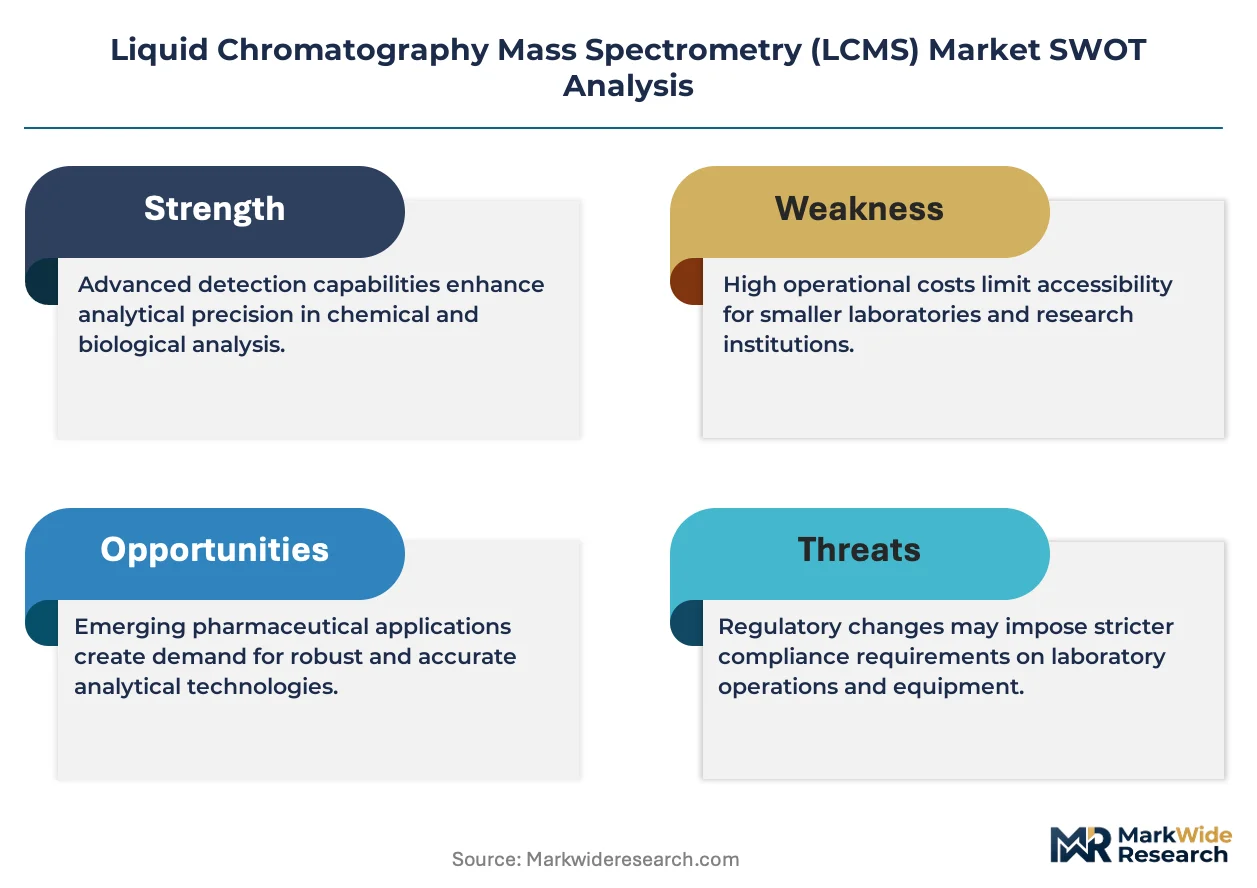
FDA bioanalytical guidance, EPA methods for drinking water contaminants, and ISO 17025 accreditation requirements collectively shape instrument specifications, software validation protocols, and service documentation standards across end-user laboratories. The European Medicines Agency's evolving quality guidelines for biosimilars and complex generics further tighten methodological rigor, pushing pharmaceutical companies toward higher-sensitivity platforms with enhanced reproducibility. Stakeholders must monitor how regulatory convergence between FDA and EMA on mass spectrometry-based bioanalytical methods reshapes instrument purchasing criteria and vendor qualification processes.
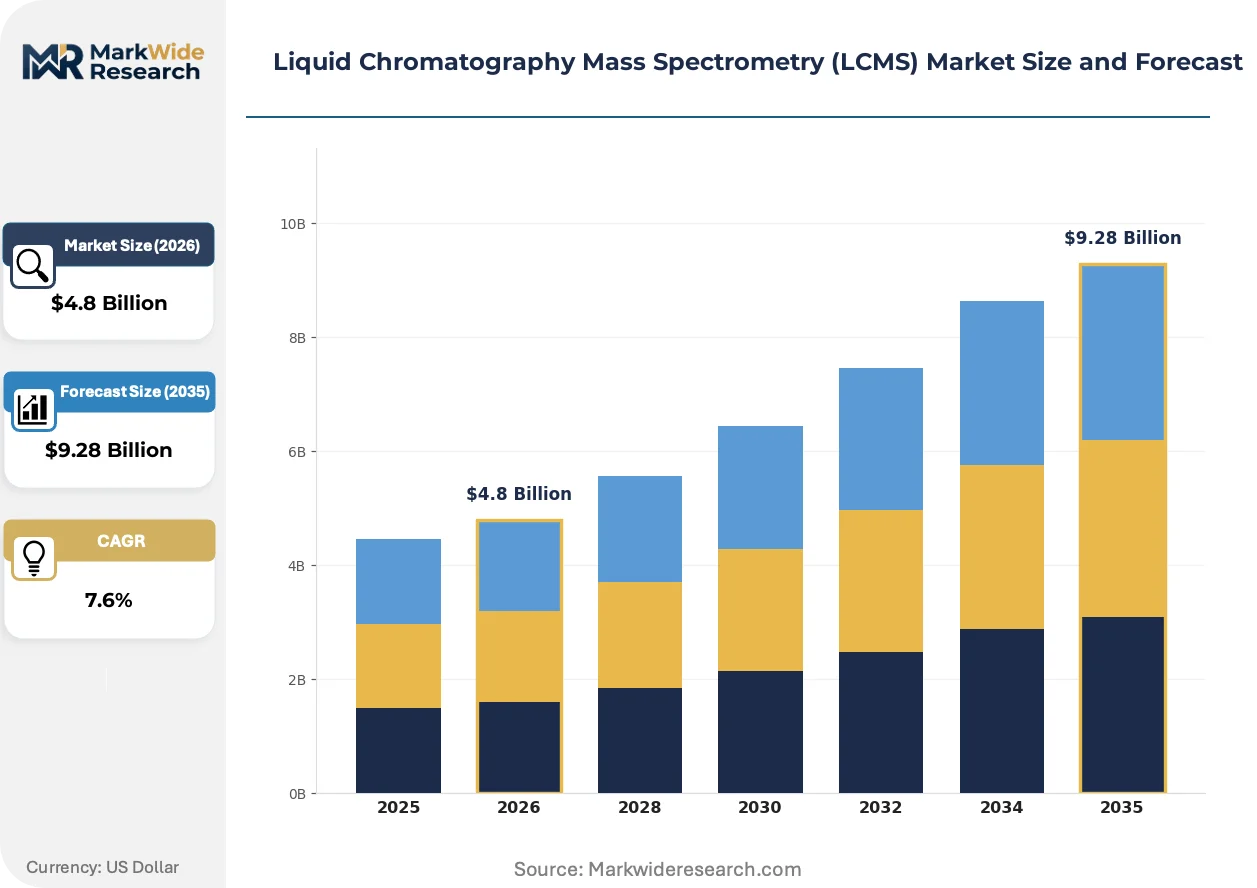
Market Dynamics
The FDA's tightened bioanalytical method validation guidance is compressing instrument replacement cycles and forcing pharmaceutical laboratories toward higher-resolution platforms with enhanced reproducibility specifications. This regulatory pressure is reshaping vendor qualification processes and tightening performance standards across regulated workflows.
Growth Catalysts
- EMA Biosimilar Quality Guidelines:The European Medicines Agency's evolving standards for complex generics are pushing pharmaceutical manufacturers toward exact-mass measurement capabilities in biopharma characterization workflows.
- Environmental Monitoring Mandates:EPA methods for drinking water contaminants are expanding installed base requirements for triple quadrupole systems in contract testing laboratories across the United States.
- Metabolomics Research Expansion:Academic institutions in Germany and Japan are accelerating quadrupole-time of flight platform procurement for untargeted analysis applications.
Market Restraints
- Helium Supply Volatility:Price instability for this carrier gas essential to mass spectrometry operations is elevating operating cost uncertainty for high-throughput laboratories.
- Trained Specialist Scarcity:The shortage of qualified mass spectrometrists is constraining capacity expansion at instrument manufacturers and limiting utilization rates at installed sites.
- Method Transfer Friction:Proprietary column chemistries from dominant vendors lock pharmaceutical clients into elevated switching costs and extended validation timelines.
Strategic Opportunities
- Clinical Diagnostics Penetration:Underdeveloped LCMS adoption in hospital-based clinical laboratories in India presents expansion potential for standardized, FDA-cleared assay platforms.
- Service Contract Unbundling:Modular maintenance offerings are creating new revenue channels for third-party service providers in high-throughput United States laboratory clusters.
- ISO 17025 Accreditation Tailwind:Expanding third-party certification requirements for food safety testing in Brazil are mandating instrument upgrades with enhanced software validation protocols.
Industry Challenges
- Software Validation Burden:FDA 21 CFR Part 11 compliance timelines for computerized systems are extending qualification periods and elevating documentation overhead for regulated pharmaceutical sites.
- Integration Complexity:Legacy laboratory information management systems at established contract research organizations resist seamless connectivity with modern high-resolution data acquisition platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Chromatography Mass Spectrometry (LCMS) Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Triple Quadrupole, Quadrupole-Time of Flight, Single Quadrupole, Ion Trap Technology: Electrospray Ionization, Matrix-Assisted Laser Desorption Ionization, Atmospheric Pressure Chemical Ionization, Gas Chromatography Coupling End User: Pharmaceutical Companies, Academic Research Institutions, Clinical Laboratories, Environmental Agencies Application: Drug Development, Environmental Analysis, Clinical Diagnostics, Food Safety Testing |
| Companies Covered | Thermo Fisher Scientific, Waters Corporation, Agilent Technologies, Shimadzu Corporation, Bruker Corporation, PerkinElmer, Danaher Corporation, SCIEX, JEOL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Chromatography Mass Spectrometry (LCMS) Market Trends and Innovations
Workflow automation and miniaturization are compressing sample-to-answer timelines while elevating throughput requirements for integrated LCMS platforms. These shifts are reshaping competitive differentiation around software integration and consumables lock-in rather than hardware specifications alone.
Microflow liquid chromatography is supplanting conventional analytical-scale separations in quantitative bioanalysis workflows. Pharmaceutical quality control laboratories in Massachusetts and North Carolina are adopting 1-10 µL/min flow rates to reduce solvent consumption and enhance ionization efficiency. This transition is supplanting legacy 4.6 mm column formats and compressing per-sample operating costs while demanding redesigned ion source architectures.
REACH authorization requirements for persistent organic pollutants are mandating sub-ppb detection capabilities in European environmental testing laboratories. The European Chemicals Agency's substance restriction timelines are accelerating replacement of single quadrupole systems with tandem mass spectrometry platforms. German and Dutch contract laboratories are responding through phased procurement programs aligned with 2025-2027 compliance deadlines.
Consolidated procurement by multi-site pharmaceutical conglomerates is compressing vendor negotiation cycles and elevating total cost of ownership transparency requirements. Purchasing decisions at merged entities now centralize around standardized platforms with global service footprint rather than site-specific preferences. This concentration is most visible across merged United States and Switzerland-based biopharma operations with integrated quality control networks.
Liquid Chromatography Mass Spectrometry (LCMS) Market Segmentation
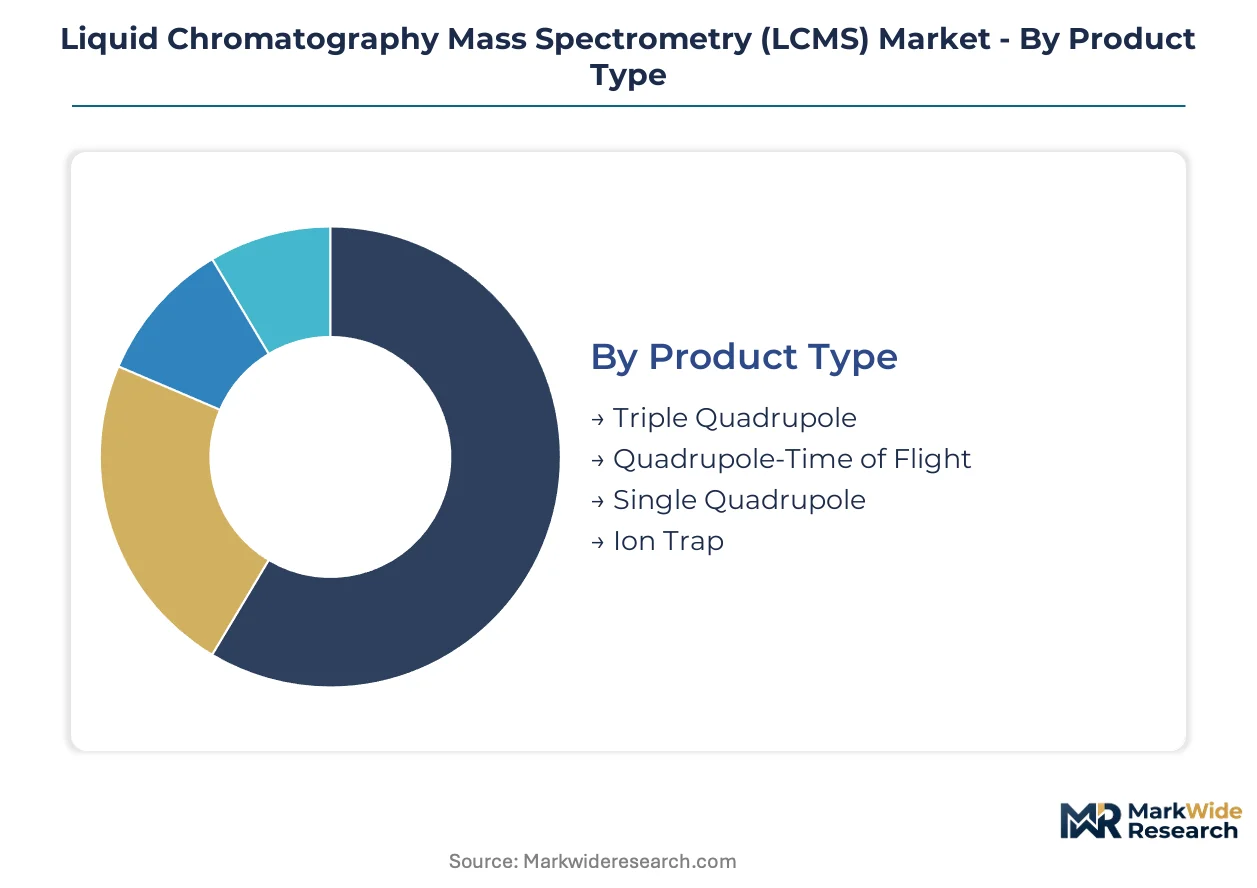
Segmentation in the LCMS market reveals how regulatory requirements fragment purchasing criteria across end-use environments. Pharmaceutical laboratories prioritize reproducibility specifications that satisfy FDA bioanalytical guidance, while environmental agencies respond to EPA method mandates with different performance thresholds.
Product Type:
FDA and EMA validation standards differentiate instrument selection, with regulated pharmaceutical workflows demanding specific mass accuracy and selectivity benchmarks.
- Triple Quadrupole:Tandem mass spectrometry configuration employing multiple quadrupole mass filters for targeted quantitative analysis. Pharmaceutical quality control laboratories in the United States and Germany concentrate procurement here, driven by FDA bioanalytical method validation requirements for reproducible quantitative assays. Established volume favors Triple Quadrupole; emerging adoption favors Quadrupole-Time of Flight.
- Quadrupole-Time of Flight:Hybrid architecture combining quadrupole precursor selection with time-of-flight exact mass measurement. Academic metabolomics programs in Japan and biopharma characterization facilities in Switzerland are accelerating deployment, responding to EMA biosimilar quality guidelines demanding exact-mass capabilities for complex generics.
- Single Quadrupole:Entry-level mass filter configuration for routine screening applications. Environmental monitoring stations in Brazil and food safety laboratories in India maintain installed bases for cost-constrained compliance workflows.
- Ion Trap:Three-dimensional or linear trapping geometry enabling multi-stage fragmentation for structural elucidation. Specialized proteomics research centers in France and forensic toxicology units in Australia retain niche applications requiring MSn capabilities.
Cost tiering separates premium tandem systems from entry-level configurations, with mid-range hybrids capturing biopharma expansion budgets.
Technology:
Application chemistry dictates ionization interface selection, with polar analyte profiles concentrating demand in electrospray architectures.
- Electrospray Ionization:Atmospheric pressure interface generating charged droplet aerosols for polar and ionic compound analysis. Dominates pharmaceutical bioanalysis and proteomics workflows in Massachusetts and Basel-region laboratories, where biologics characterization demands soft ionization for fragile biomolecules. Ionization interface selection concentrates in electrospray for polar analytes; atmospheric pressure chemical ionization retains critical utility for nonpolar matrices.
- Atmospheric Pressure Chemical Ionization:Corona discharge-based ionization for neutral, nonpolar compounds. Environmental testing laboratories in the Netherlands and food safety agencies in Italy deploy for pesticide residue and persistent organic pollutant detection under REACH authorization timelines.
- Matrix-Assisted Laser Desorption Ionization:Solid-phase ionization using laser energy transfer through crystalline matrix. Academic imaging mass spectrometry facilities in Germany and polymer characterization centers in Japan maintain specialized installations for spatially resolved analysis.
- Gas Chromatography Coupling:Interface enabling volatile and semi-volatile compound analysis via combined GC-MS workflows. Petrochemical laboratories in Texas and fragrance analysis facilities in France retain demand for thermally stable, low-molecular-weight analytes incompatible with liquid phase separation.
Customer sophistication separates routine analytical laboratories from research-grade facilities requiring multi-modal ionization flexibility.
End User:
Procurement authority and validation burden fragment purchasing patterns across institutional categories with divergent compliance obligations.
- Pharmaceutical Companies:Integrated drug development and quality control operations with mandatory FDA 21 CFR Part 11 software validation requirements. Multi-site conglomerates in the United States and Switzerland centralize procurement around standardized platforms with global service footprint, compressing vendor negotiation cycles.
- Academic Research Institutions:Untargeted analysis and fundamental methodology development with flexible performance specifications. German and Japanese universities are accelerating quadrupole-time of flight platform procurement for metabolomics expansion, prioritizing exact mass measurement over quantitative reproducibility.
- Clinical Laboratories:Hospital-based diagnostic testing with emerging LCMS adoption for standardized assays. Underpenetrated hospital networks in India present expansion potential for FDA-cleared platforms, constrained by capital budget limitations and specialist training requirements.
- Environmental Agencies:Regulatory compliance monitoring with method-defined detection thresholds. EPA drinking water mandates in the United States and ECHA substance restrictions in Europe are elevating triple quadrupole requirements for sub-ppb contaminant quantification.
Volume concentration favors pharmaceutical conglomerates; steepest expansion trajectory favors clinical diagnostics penetration in emerging markets.
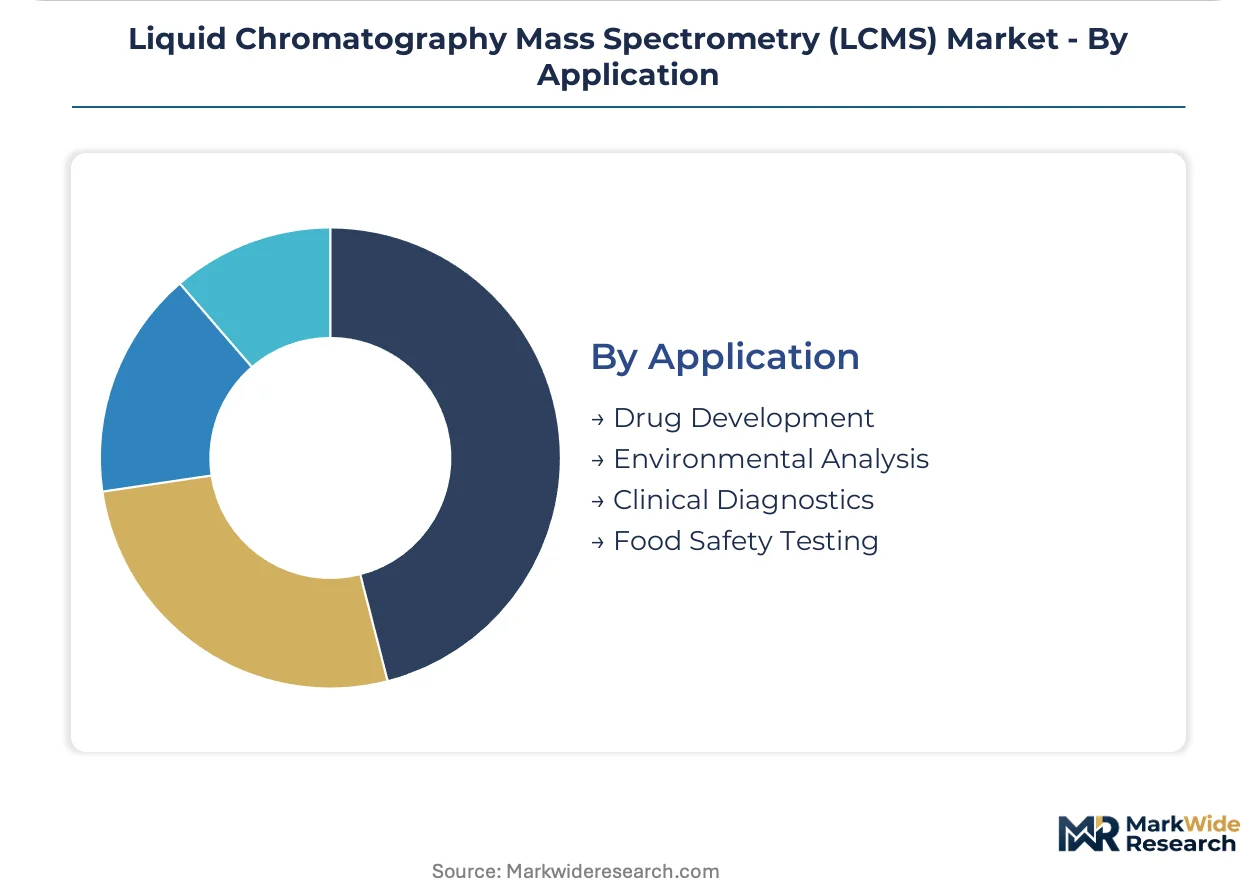
Application:
Workflow standardization and regulatory filing requirements differentiate method development rigor across analytical purposes.
- Drug Development:Bioanalytical support for pharmacokinetic studies and biologics characterization with mandatory regulatory submission packages. Contract research organizations in North Carolina and Massachusetts face compressed timelines from tightened FDA guidance, forcing platform upgrades with enhanced reproducibility specifications.
- Environmental Analysis:Contaminant monitoring for regulatory compliance and ecological risk assessment. German and Dutch contract laboratories are executing phased procurement programs aligned with 2025-2027 REACH authorization deadlines for persistent organic pollutant detection.
- Clinical Diagnostics:Therapeutic drug monitoring and endocrinology testing with emerging mass spectrometry displacement of immunoassay methods. Standardization challenges and reimbursement coding complexities constrain adoption velocity in United States hospital systems.
- Food Safety Testing:Residue and contaminant screening for import certification and domestic surveillance. ISO 17025 accreditation expansion in Brazil and mycotoxin regulation in the European Union are mandating instrument upgrades with validated software protocols.
Maturity gradient separates established pharmaceutical workflows from emerging clinical applications navigating reimbursement and regulatory pathway uncertainties.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA bioanalytical guidance anchors United States demand, while EMA quality standards and REACH authorization timelines concentrate procurement across Germany, Switzerland, and the Netherlands. Academic metabolomics expansion in Japan and emerging clinical adoption in India complete the geographic distribution.
United States
Pharmaceutical quality control laboratories in Massachusetts and North Carolina drive triple quadrupole procurement for FDA bioanalytical method validation compliance. EPA drinking water mandates expand contract testing laboratory requirements for sub-ppb contaminant detection. The Greater Boston biopharma cluster sustains the densest installed base of high-resolution quadrupole-time of flight systems.
Germany
Academic metabolomics programs and environmental contract laboratories accelerate platform replacement aligned with ECHA substance restriction deadlines. REACH authorization requirements for persistent organic pollutants mandate tandem mass spectrometry upgrades through 2027. The Rhine-Main and Bavarian research corridors concentrate quadrupole-time of flight deployment for exact-mass measurement workflows.
Switzerland
Multi-site biopharma conglomerates centralize procurement around standardized platforms with global service footprint. Swissmedic quality guidelines for biosimilars tighten methodological rigor and elevate reproducibility specifications. The Basel-region pharmaceutical cluster maintains integrated quality control networks with captive consumables streams.
Japan
Academic institutions accelerate quadrupole-time of flight platform procurement for untargeted metabolomics analysis. PMDA evolving standards for complex generics push manufacturers toward exact-mass measurement capabilities. The Kanto and Kansai research corridors prioritize exact mass measurement over quantitative reproducibility in platform selection.
India
Underdeveloped LCMS adoption in hospital-based clinical laboratories presents expansion potential for standardized assay platforms. CDSCO regulatory pathway complexities and capital budget limitations constrain adoption velocity. The Maharashtra and Karnataka pharmaceutical manufacturing belts concentrate quality control instrument procurement for export compliance.
Liquid Chromatography Mass Spectrometry (LCMS) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the LCMS market. The upper tier commands premium positioning through captive consumables streams and proprietary column chemistries that elevate switching costs. Specialist competitors differentiate through modular ion source architectures and regional service density. Strategic moves concentrate on consumables lock-in mechanisms and service contract bundling to sustain recurring revenue per installed system.
Within the integrated instrumentation tier, Thermo Fisher Scientific and Waters Corporation occupy positions defined by recurring revenue architectures. Agilent Technologies exemplifies the service-centric archetype with extended maintenance offerings. Shimadzu Corporation and Bruker Corporation anchor the specialist tier with differentiated mass analyzer configurations. These five entities collectively represent the competitive spectrum from full-platform integration to targeted technology specialization.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Waters Corporation |
| Agilent Technologies |
| Shimadzu Corporation |
| Bruker Corporation |
| PerkinElmer |
| Danaher Corporation |
| SCIEX |
| JEOL |
| Others |
Pricing and Supply Chain Analysis
ISO 17025 accreditation requirements gate both vendor qualification timelines and price differentiation across the LCMS market, compressing procurement cycles for laboratories seeking certified platforms while elevating premium positioning for suppliers with pre-validated software ecosystems. This certification barrier simultaneously constrains supply-side entrants and segments pricing power between established integrated vendors and modular specialists.
Pricing Analysis
United States-based pharmaceutical laboratories pay 15-25% premiums over Indian academic institutions for equivalent triple quadrupole configurations, reflecting divergent regulatory validation burdens and service bundling intensity. Pricing stratifies across premium, standard, and economy tiers anchored by mass accuracy specifications, software validation depth, and consumables lock-in mechanisms. Cost compression in the economy tier intensifies as Chinese manufacturers expand regional distribution networks. Contract research organizations exhibit highest price sensitivity due to margin pressure from compressed client timelines, while multi-site biopharma conglomerates prioritize total cost of ownership transparency over unit pricing.
Supply Chain Analysis
Strategic stockpiling of precision-machined mass analyzer components dominates inventory strategy among tier-one manufacturers, buffering against lead time volatility for ion source assemblies and detector subsystems. Manufacturing concentration centers on Massachusetts, Switzerland, and Japan for high-resolution platforms, while consumables production draws from China and India for cost-optimized column chemistries. Single-source vulnerability persists for specialized vacuum pump technologies and rare-earth magnet materials essential to time-of-flight architectures. Distribution runs through authorized service networks with captive spare parts inventories, supplemented by third-party refurbishment channels for end-of-life systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LCMS market is entering a cyclical recovery phase as pharmaceutical capital expenditure budgets rebound from post-pandemic retrenchment and biologics pipeline expansion accelerates replacement demand. This recovery is underpinned by FDA bioanalytical guidance tightening that forces instrument refresh cycles regardless of macroeconomic conditions.
For Market Incumbents: Fortify recurring revenue architectures through captive consumables streams and extended service contracts that embed switching costs. Expand backward integration into precision-machined ion optic components to reduce exposure to single-source suppliers. Prioritize certification pre-validation investments that compress client qualification timelines and defend margin position against modular specialists. For New Entrants and Emerging Players: ISO 17025 fast-track partnerships with Brazilian and Indian food safety laboratories offer the most penetrable entry vector, bypassing entrenched relationships in saturated pharmaceutical clusters. Target hospital-based clinical diagnostics in Maharashtra and Karnataka where capital budget limitations favor mid-range quadrupole configurations over premium tandem systems. Pursue white-label ion source manufacturing agreements with established platform vendors to build reference installations. For Investors and Strategic Acquirers: FDA bioanalytical guidance convergence with EMA standards reshapes the acquisition landscape toward platforms with dual-validation software architectures and global service footprints. Long-term viability over a 5-10 year horizon favors targets with installed base density in United States pharmaceutical corridors and recurring revenue ratios above 60%. Monitor helium supply contract renegotiations as an inflection signal for operating cost pressure and potential vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Consumables Lock-In Program | Captive column chemistry supply chains elevate switching costs for pharmaceutical quality control laboratories. |
| Microflow Platform Launch | Reduced solvent consumption aligns with Massachusetts and North Carolina sustainability mandates while enhancing ionization efficiency. |
| ISO 17025 Pre-Certification | Accelerated validation timelines capture Brazilian food safety testing procurement aligned with third-party accreditation expansion. |
| Service Contract Unbundling | Modular maintenance offerings create third-party revenue channels in high-throughput United States laboratory clusters. |
| Helium Recovery System Deployment | On-site carrier gas recycling mitigates supply volatility for high-throughput environmental testing laboratories. |
Research Methodology
Cross-validation between primary interviews with instrument manufacturer product managers, pharmaceutical quality control directors, and academic core facility managers anchors the qualitative findings, supplemented by secondary validation against FDA 510(k) filings, EMA quality guideline drafts, and EPA method update releases. Bottom-up triangulation aggregates installed base estimates from service contract disclosures and consumables shipment data, while top-down verification benchmarks against capital expenditure patterns reported in SEC filings from publicly traded biopharma conglomerates.
Sensitivity analysis across helium price scenarios, regulatory timeline acceleration assumptions, and biologics pipeline success rates tests forecast robustness over the projection horizon. Segmentation modeling incorporates product type, ionization interface technology, end-user institutional category, and application workflow rigor. CAGRs derive from logistic diffusion curves fitted to historical replacement cycles and adjusted for regulatory mandate acceleration effects. Industry-specific inputs include mass accuracy specification trajectories and software validation burden indices.
Decision-makers should treat outputs as directional under assumptions of sustained FDA-EMA regulatory convergence and stable helium supply contracting; material deviation would warrant model refresh. Forecasts reflect these base conditions and acknowledge that trained specialist scarcity, tariff exposure on precision components, or abrupt REACH deadline shifts could revise trajectory. Revision becomes warranted when biopharma capital expenditure intentions cross below replacement-cycle maintenance thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Rheometer Market
Testing Equipment
Global Life Science and Chemical Instrumentation Market
Testing Equipment
Brittleness Tester Market
Testing Equipment
In Vitro Toxicity Testing Market
Testing Equipment
Reagent Filling Systems Market
Testing Equipment
Melting Point Apparatus Market
Testing Equipment
Global Oxidative Stress Assay Market
Testing Equipment
Ambient Temperature Gel Permeation Chromatography Market
Testing Equipment
Global Liquid Process Analyzer Market
Testing Equipment
Material Tester Market
Testing Equipment
Paper Moisture Meter Market
Testing Equipment
Binary High Pressure Gradient Liquid Chromatography System Market
Testing Equipment
Gold Purity Tester Market
Testing Equipment
Total Hydrocarbon Analyzers Market
Testing Equipment
Flammability Test Chamber Market
Testing Equipment
U-Tube Viscometer Market