
 Global Electronic Grade Phosphoric Acid Market | 2026-2036
Global Electronic Grade Phosphoric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electronic Grade Phosphoric Acid Market Foresight
Buyer concentration among semiconductor fabricators is realigning procurement leverage toward top-tier foundries and integrated device manufacturers. Arkema leverages its European fluorochemical heritage to supply high-purity wet chemicals for advanced node etching. Solvay sustains a differentiated position through integrated phosphorus value chains and semiconductor-grade certification depth. Hubei Xingfa Chemicals Group anchors volume supply for Chinese PCB producers navigating domestic substitution mandates.
Electronic grade phosphoric acid denotes ultra-high-purity phosphoric acid with metallic impurity levels below 100 parts per billion, produced via thermal or wet-process refinement followed by multi-stage filtration and distillation; it functions primarily as a silicon nitride etchant and surface cleaner in wafer fabrication. Semiconductor etching applications dominate value capture due to stringent purity requirements at 3nm and below nodes. PCB manufacturing represents a mature, volume-driven segment where price sensitivity constrains margin expansion. Chemical synthesis applications for pharmaceutical and specialty electronic intermediates are growing fastest among non-semiconductor verticals.
REACH and RoHS frameworks in Europe restrict hazardous substance thresholds in electronic components, while China's GB standards and MEE emissions rules enforce cleaner production protocols for phosphoric acid refiners. The EPA and OSHA in the United States impose workplace exposure limits and environmental release controls that shape plant siting and capital allocation decisions. Stakeholders must monitor regulatory divergence between Asian purity specifications and European chemical safety registrations to anticipate compliance-driven supply chain reconfigurations.
Market Dynamics
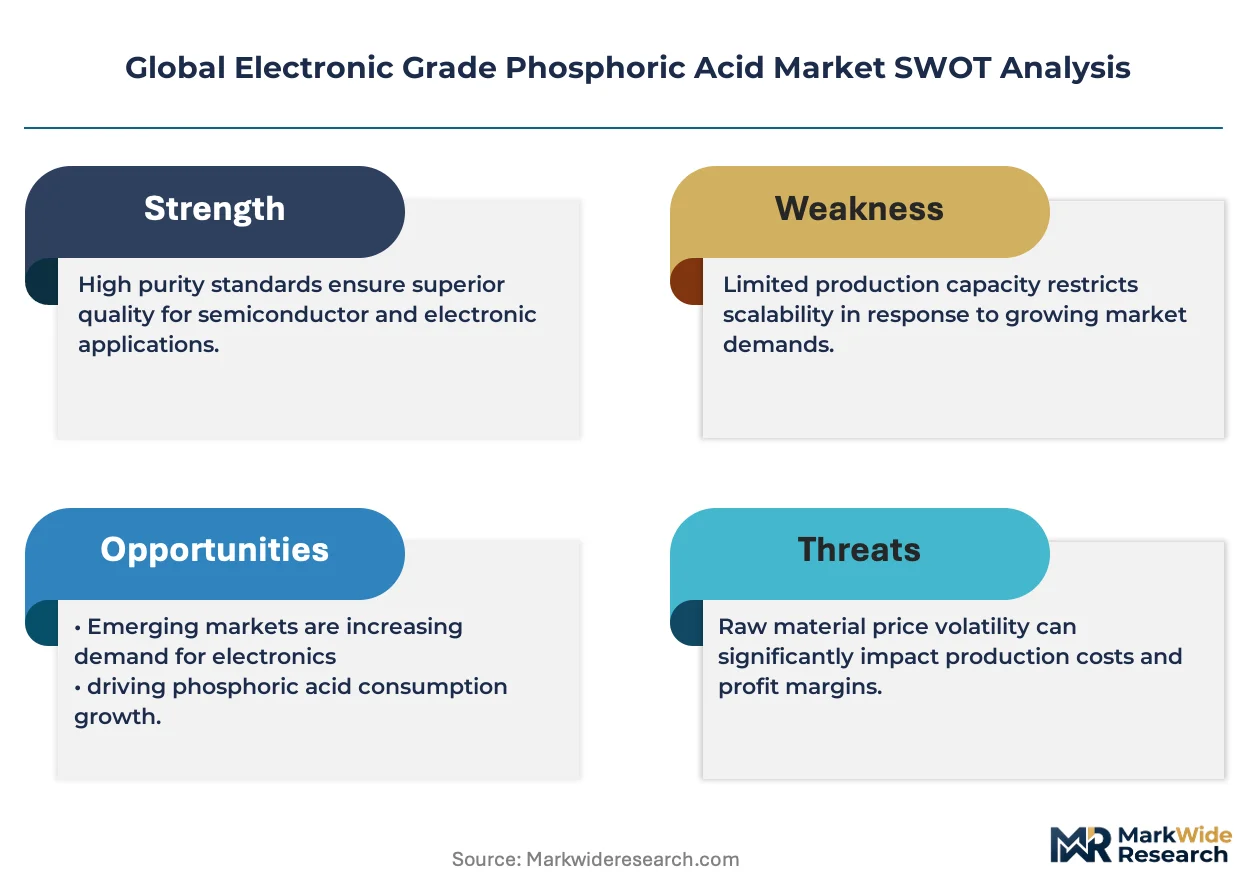
Semiconductor node shrinkage below 5nm is compressing metallic impurity tolerances from parts-per-billion to parts-per-trillion thresholds, forcing phosphoric acid refiners to retool thermal process lines and filtration sequences. Taiwan's TSMC and Samsung Foundry are now specifying sub-10ppb iron and copper ceilings that legacy wet-process plants cannot meet without capital-intensive distillation upgrades.
Growth Catalysts
- China's dual carbon mandates:Beijing's NMPA purity benchmarks and MEE emissions protocols are shuttering low-grade wet-process capacity, redirecting procurement toward certified thermal-process suppliers capable of 3nm node qualification.
- Advanced packaging proliferation:Fan-out wafer-level packaging and 3D-IC stacking are multiplying etch-clean cycles per wafer, expanding phosphoric acid consumption per unit of semiconductor output.
- HBM memory fabrication:High-bandwidth memory stacks require repeated silicon nitride etching for through-silicon vias, concentrating demand among South Korean and Taiwanese DRAM manufacturers.
Market Restraints
- Yellow phosphorus supply concentration:Over 70% of global elemental phosphorus originates from Chinese producers subject to export quota volatility and electricity rationing during peak demand seasons.
- Substitution by fluorinated chemistries:Buffered oxide etchants and hydrofluoric acid blends are displacing phosphoric acid in select nitride removal steps at mature nodes where purity requirements relax.
- REACH registration burdens:European ECHA substance dossier requirements impose multi-year compliance timelines and toxicology testing costs that exclude mid-scale Asian refiners from EU semiconductor supply chains.
Strategic Opportunities
- Indian semiconductor subsidy corridors:India's PLI scheme and Gujarat Dholera fab complex are creating first-mover openings for phosphoric acid suppliers willing to co-locate purification plants near emerging foundry sites.
- Pharmaceutical-grade synthesis crossover:Electronic-grade purification infrastructure can be dual-purposed for active pharmaceutical ingredient production, capturing margin premiums from CDMO outsourcing trends.
- Closed-loop recycling systems:On-site acid regeneration and spent-etchant recovery are integrating into fab water management contracts, creating recurring revenue streams independent of virgin acid sales.
Industry Challenges
- Metrology technician scarcity:ICP-MS and GFAA spectroscopy operators capable of validating sub-ppb impurity profiles command salaries exceeding standard chemical plant wage structures by 40-60%.
- Fab qualification timelines:Semiconductor customer audits and three-to-six-month purity validation cycles delay revenue recognition for new production lines, straining working capital during ramp-up phases.
- Legacy wet-process asset stranding:Chinese domestic producers face write-down pressure on billion-yuan wet-process plants that cannot be retrofitted to meet 3nm node specifications without complete rebuilds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electronic Grade Phosphoric Acid Market |
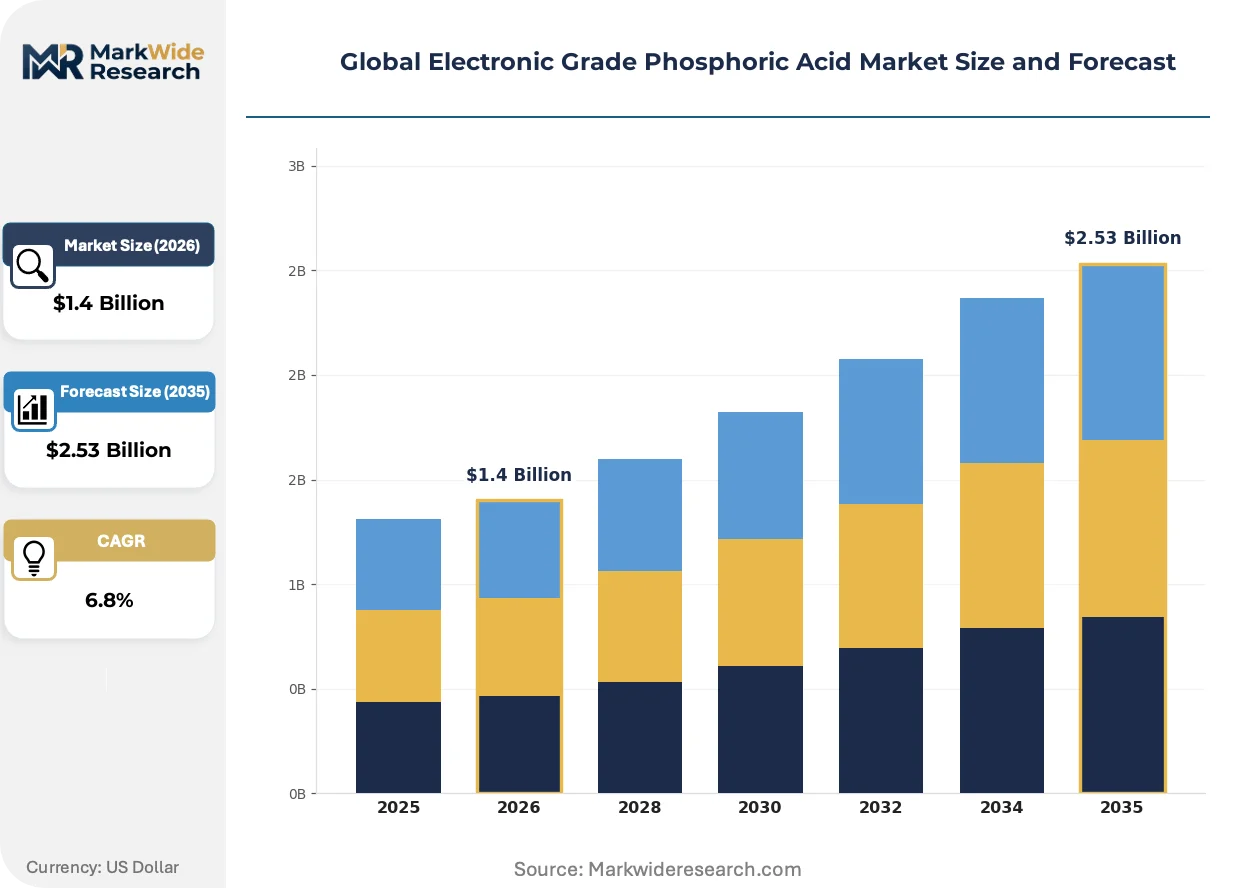
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrated, Diluted, Stabilized, Anhydrous, Reagent Application: Semiconductor Etching, PCB Manufacturing, Chemical Synthesis, Surface Treatment, Electroplating End User: Semiconductor Fabricators, Electronics Assembly, Printed Circuit Board Producers, Chemical Manufacturers Packaging Type: Drums, IBC Totes, Bulk Containers, Bottles, Tankers |
| Companies Covered | Arkema, Solvay, ICL Performance Products, Honeywell, OCI Company, Hubei Xingfa Chemicals Group, RIN KAGAKU KOGYO, Merck KGaA, Chengxing Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electronic Grade Phosphoric Acid Market Shifts & Advancements
Continuous flow thermal processing is displacing batch refinement as the dominant production architecture, enabling real-time impurity monitoring and reducing lot-to-lot variation that disrupts fab etch-rate consistency. This shift is compressing capital efficiency gaps between established European suppliers and Asian challengers.
Membrane distillation-crystallization hybrids are integrating into phosphoric acid finishing trains, replacing energy-intensive multiple-effect evaporators with polymer hollow-fiber modules that achieve 99.999% metal rejection at 40% lower steam consumption. Samsung Foundry and Intel are qualifying these systems for their Arizona and Pyeongtaek greenfield sites. The technology is integrating capital-light modularity into purification plant design, allowing 2,000-ton annual capacity increments rather than 10,000-ton block investments.
China's GB 38508-2020 volatile organic compound limits and MEE wastewater discharge rules are forcing domestic refiners to install scrubber-condenser networks and zero-liquid-discharge crystallizers that add 15-20% to unit production costs. Plants in Hubei and Guizhou provinces are responding by consolidating into integrated chemical parks with shared effluent treatment infrastructure, raising barriers for independent operators lacking scale.
Long-term supply agreements with fixed purity escalators are displacing spot-market purchasing among Taiwan's top-three foundries, compressing supplier margins during phosphorus feedstock price spikes but guaranteeing volume offtake through node transition cycles. This contractual shift is most visible in Hsinchu Science Park procurement patterns, where TSMC and UMC now contract 70-80% of phosphoric acid requirements on three-to-five-year terms with annual price reopeners tied to yellow phosphorus indices.
Global Electronic Grade Phosphoric Acid Market Segmentation
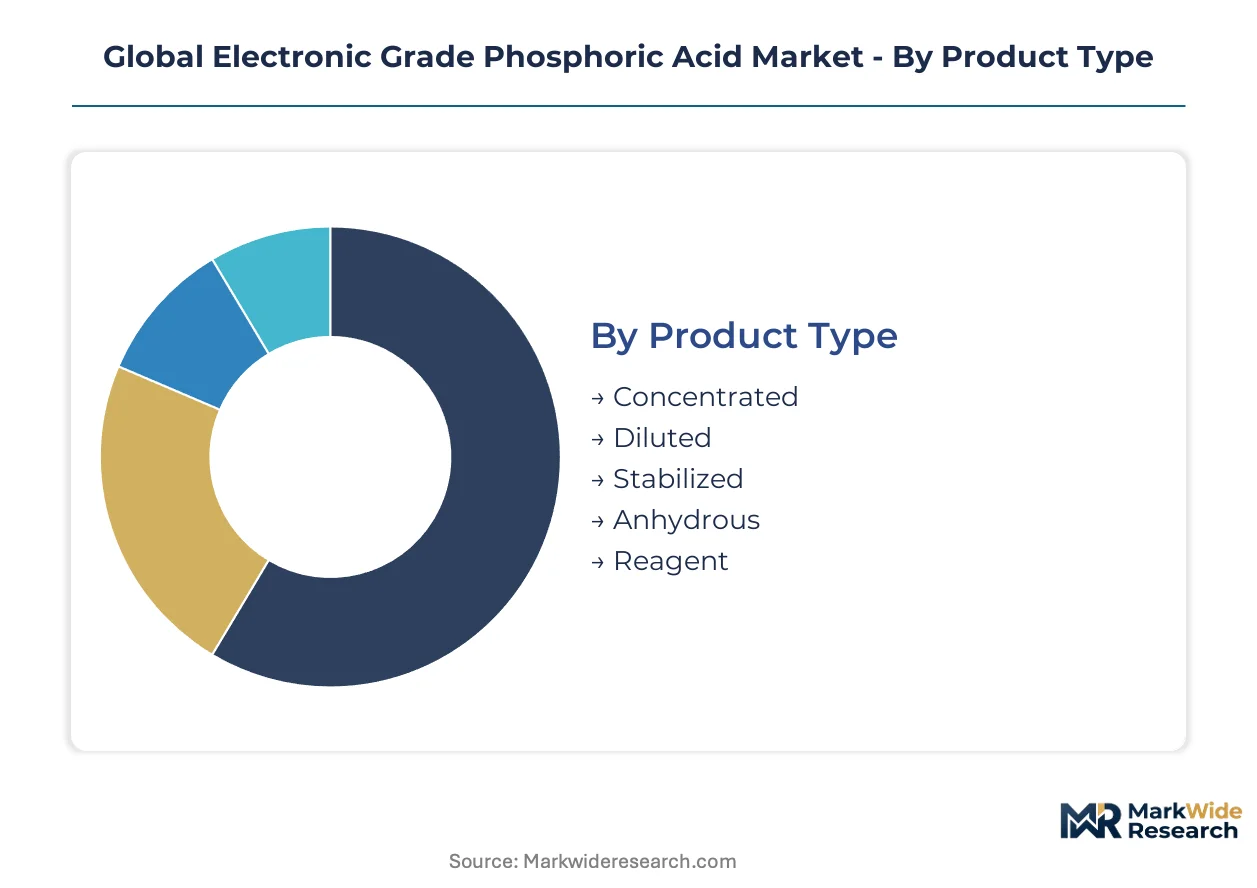
Segmentation in electronic grade phosphoric acid reveals how capital intensity, purity thresholds, and logistics constraints stratify supply economics. Thermal-process purification infrastructure and fab qualification timelines create divergent margin profiles across product grades and customer tiers.
Product Type:
Concentrated grades demand the heaviest thermal-process capital outlays, with multi-stage distillation trains requiring 40-60 million dollar investments for sub-10ppb metallic impurity certification.
- Concentrated:85-90% H3PO4 content produced via electric furnace thermal reduction followed by crystallization and membrane filtration. Taiwan's TSMC and Samsung Foundry specify concentrated grades for silicon nitride etching at 3nm nodes where iron and copper tolerances compress below 10ppb.
- Diluted:Pre-mixed aqueous solutions at 30-50% concentration for direct-use surface cleaning applications. South Korean DRAM manufacturers favor diluted formats to reduce on-site chemical handling infrastructure and accelerate fab qualification cycles.
- Stabilized:Additive-inhibited formulations preventing precipitation during extended storage. Chemical manufacturers in pharmaceutical synthesis applications source stabilized grades for batch process consistency.
- Anhydrous:Ultra-low water content variants requiring phosphorus pentoxide dehydration stages. Semiconductor fabricators in Japan's Kyushu region deploy anhydrous grades for specialized nitride passivation etching.
- Reagent:Laboratory-scale volumes with documented traceability for analytical method validation. Electronics assembly quality control laboratories constitute the primary demand anchor.
Most installed capacity flows through concentrated grades. Expansion is steepest in diluted formats.
Application:
Application segmentation tracks how purity requirements scale with device complexity, with semiconductor etching commanding 3-5x price premiums over mature-node alternatives.
- Semiconductor Etching:Silicon nitride removal at advanced nodes requires sub-ppb metallic impurity profiles validated via ICP-MS and GFAA spectroscopy. Taiwan's Hsinchu Science Park and South Korea's Pyeongtaek complex concentrate global demand for this application tier.
- PCB Manufacturing:Surface preparation and copper foil treatment at relaxed purity thresholds. Chinese PCB producers in Guangdong and Jiangsu provinces drive volume consumption with price-sensitive procurement patterns.
- Chemical Synthesis:Pharmaceutical and specialty electronic intermediate production leveraging electronic-grade purification infrastructure. India's emerging CDMO sector is expanding fastest in this vertical.
- Surface Treatment:Metal finishing and passivation for electronic component housings. Japanese automotive electronics suppliers anchor regional demand.
- Electroplating:High-purity electrolyte preparation for semiconductor interconnect deposition. Intel's Arizona and Ohio greenfield sites are qualifying domestic suppliers for this application.
Semiconductor etching captures the dominant revenue share. Chemical synthesis is climbing the fastest.
End User:
End-user segmentation exposes how customer scale and qualification rigor fragment pricing power, with top-tier foundries consolidating procurement leverage through long-term supply agreements.
- Semiconductor Fabricators:Integrated device manufacturers and pure-play foundries specifying node-specific purity certificates. Taiwan, South Korea, and the United States concentrate the most stringent procurement requirements.
- Electronics Assembly:Contract manufacturers and OEM assembly operations with standardized grade acceptance. Southeast Asian electronics manufacturing services clusters drive regional volume.
- Printed Circuit Board Producers:Multi-layer and HDI board fabricators prioritizing cost efficiency over extreme purity. China's domestic substitution mandates are reshaping supplier qualification pathways.
- Chemical Manufacturers:Specialty chemical and pharmaceutical compounders sourcing electronic-grade feedstock for downstream synthesis. European REACH registration requirements constrain supplier eligibility.
Semiconductor fabricators command the tightest supplier relationships. Chemical manufacturers are gaining share fastest.
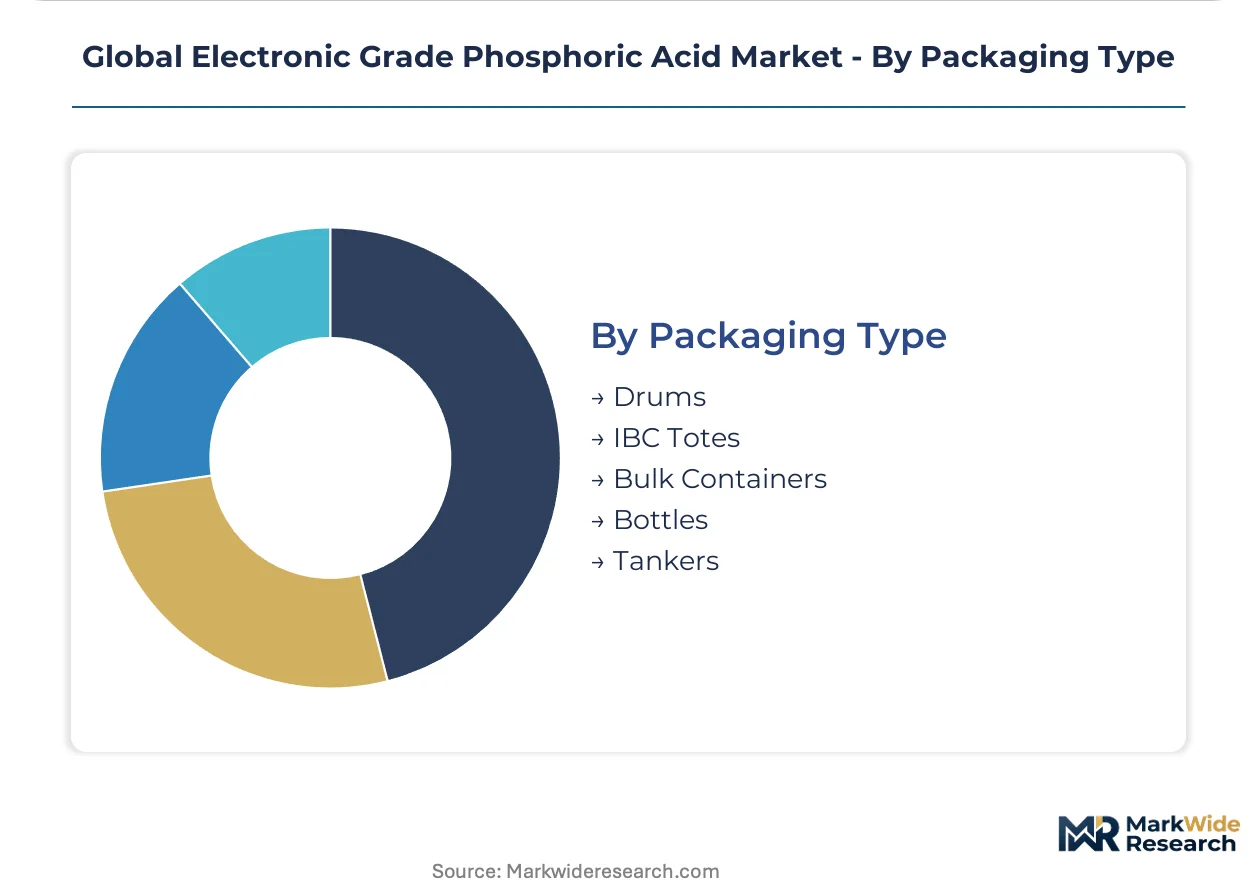
Packaging Type:
Packaging segmentation reflects logistics economics and contamination risk tradeoffs, with bulk formats requiring dedicated fleet investments and specialized handling protocols.
- Drums:200-250 liter steel or polyethylene containers for mid-volume fab deliveries. Japanese and Taiwanese foundries prefer drum formats for flexibility across multiple production lines.
- IBC Totes:Intermediate bulk containers at 1,000 liter capacity balancing handling efficiency with lot traceability. South Korean memory manufacturers standardize on IBC formats for HBM fabrication sites.
- Bulk Containers:Dedicated stainless steel vessels for high-volume continuous consumption. Intel's Arizona facility operates bulk container supply chains.
- Bottles:Laboratory and pilot-scale volumes with nitrogen headspace preservation. Electronics assembly quality labs constitute the primary demand segment.
- Tankers:Dedicated chemical transport trailers for direct-to-fab delivery eliminating intermediate storage. TSMC's Hsinchu and Taichung sites receive concentrated grades via tanker.
Most product moves through IBC totes. Tanker deployment is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan and South Korea concentrate the most stringent phosphoric acid procurement requirements, while China's domestic substitution mandates and Japan's advanced packaging specialization create divergent demand profiles across East Asia.
Taiwan
TSMC and UMC drive specifications for sub-10ppb metallic impurity ceilings at 3nm nodes. The National Communications Commission and Industrial Development Bureau enforce chemical traceability protocols for semiconductor supply chains. Hsinchu Science Park and Taichung's Central Taiwan Science Park receive concentrated grades via dedicated tanker fleets serving continuous etch-clean cycles.
South Korea
Samsung Foundry and SK Hynix multiply phosphoric acid consumption through HBM memory stacking and 3D-IC architectures. The Ministry of Environment enforces wastewater discharge rules that favor suppliers with zero-liquid-discharge crystallizers. Pyeongtaek's semiconductor cluster and Yongin's Giheung complex anchor regional demand for diluted format deliveries.
China
Domestic PCB producers in Guangdong and Jiangsu provinces drive volume consumption amid NMPA purity benchmarks and MEE emissions protocols. The dual carbon goals and GB 38508-2020 VOC limits shutter low-grade wet-process capacity. Hubei and Guizhou provinces consolidate refiners into integrated chemical parks with shared effluent infrastructure.
Japan
Kioxia and Tokyo Electron sustain demand for anhydrous grades in specialized nitride passivation etching. METI's chemical substance management frameworks align with REACH-equivalent purity documentation requirements. Kyushu's Kumamoto and Hiroshima prefectures concentrate DRAM and NAND fabrication sites with legacy supplier relationships.
United States
Intel's Arizona and Ohio greenfield sites qualify domestic suppliers for electroplating electrolyte preparation. EPA and OSHA impose workplace exposure limits and environmental release controls that shape plant siting decisions. Phoenix metropolitan area and Columbus region emerge as consumption anchors for advanced packaging and logic fabrication expansion.
Global Electronic Grade Phosphoric Acid Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across thermal-process and wet-process purification tiers. The vendor base stratifies into three archetypes: European heritage suppliers with semiconductor-grade certification depth, Chinese volume producers serving domestic substitution mandates, and Japanese precision specialists anchored to device manufacturer relationships. Competitive moves concentrate on fab qualification timelines and long-term supply agreements with fixed purity escalators.
European heritage suppliers exemplify the premium-tier vector, with Arkema and Solvay occupying positions defined by integrated phosphorus value chains and REACH registration depth. Arkema leverages fluorochemical heritage for wet chemical supply to advanced node etching. Solvay sustains differentiation through thermal-process refinement infrastructure and multi-stage distillation certification. Hubei Xingfa Chemicals Group anchors the volume-driven segment, representing Chinese domestic producers navigating NMPA benchmarks and export quota volatility.
| Leading Market Players |
|---|
| Arkema |
| Solvay |
| ICL Performance Products |
| Honeywell |
| OCI Company |
| Hubei Xingfa Chemicals Group |
| RIN KAGAKU KOGYO |
| Merck KGaA |
| Chengxing Group |
| Others |
Supply & Pricing Matrix
China's dual carbon mandates and MEE emissions protocols are gating qualified supply access for thermal-process phosphoric acid while compressing premium-tier pricing premiums against legacy wet-process alternatives. Semiconductor fabricators in Taiwan and South Korea now contract 70-80% of requirements on multi-year terms with annual price reopeners tied to yellow phosphorus indices, embedding feedstock volatility into supplier margins.
Pricing Analysis
Capacity additions in China's Hubei and Guizhou provinces are reshaping price floors for standard-grade material while premium thermal-process supply tightens. Three-tier pricing structure across semiconductor-grade, PCB-grade, and reagent-grade levels separates sub-10ppb certified product commanding 3-5x premiums from mature-node alternatives. Cost compression in PCB-grade tiers is intensifying because Chinese domestic substitution mandates redirect volume procurement toward certified thermal-process suppliers. Electronics assembly contract manufacturers exhibit the highest price sensitivity, while Taiwan's top-three foundries accept purity-escalated premiums for node qualification security.
Supply Chain Analysis
Regional distribution centers in Kaohsiung, Busan, and Yokohama operate hub-and-spoke patterns feeding just-in-time tanker deliveries to Hsinchu Science Park, Pyeongtaek, and Kyushu fabrication clusters. Supply concentrates in China, Taiwan, and South Korea, with over 70% of elemental phosphorus feedstock originating from Chinese producers subject to export quota volatility. Raw material dependencies rest on yellow phosphorus, electric furnace electrodes, and membrane filtration modules. Single-source vulnerability runs through concentrated yellow phosphorus supply, with electricity rationing during peak demand seasons disrupting refinery operations. Distribution runs through dedicated chemical transport fleets with nitrogen-purged vessels eliminating intermediate storage contamination risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between European REACH-registered premium supply and Chinese domestic-grade volume production, with regulatory compliance cost differentials exceeding 15-20% in unit production economics.
For Market Incumbents: Deploy long-term supply agreements with fixed purity escalators to lock in offtake from Taiwan's top-three foundries through node transition cycles. Arkema and Solvay should deepen backward integration into phosphorus value chains to offset yellow phosphorus price volatility, while accelerating fab qualification timelines to outpace emerging Asian challengers facing REACH registration burdens. For New Entrants and Emerging Players: The 40-60% price-point gap between semiconductor-grade and PCB-grade product creates entry space for mid-scale thermal-process refiners targeting India's Gujarat Dholera fab complex and emerging packaging substrates. Chemical synthesis applications for pharmaceutical intermediates represent the most penetrable vertical, with CDMO outsourcing trends enabling dual-purification infrastructure utilization. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap thermal-process specialists with existing 3nm node qualifications because fab audit timelines and purity validation cycles create acquisition premiums for pre-certified assets. Platform consolidation targets European heritage suppliers with REACH dossier depth and Asian challengers with zero-liquid-discharge crystallizer installations. Watch HBM memory capacity announcements from South Korean DRAM manufacturers as the signal indicating inflection in sub-10ppb grade demand intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yellow Phosphorus | Captive supply from Guizhou and Hubei producers insulates margins against Chinese export quota volatility. |
| Zero-Liquid-Discharge Crystallizer Installation | MEE wastewater compliance enables continued access to China's domestic PCB procurement corridors. |
| Fab Co-Location in India | Gujarat Dholera proximity reduces logistics costs for emerging foundry sites under PLI subsidy schemes. |
| Membrane Distillation-Crystallization Hybrid Deployment | Samsung Foundry and Intel qualification creates reference customer anchor for 40% steam consumption reduction. |
| Dual-Purpose Pharmaceutical-Grade Certification | CDMO outsourcing trends capture margin premiums from active pharmaceutical ingredient production crossover. |
Research Methodology
Bottom-up semiconductor etching consumption modeling reconciled against top-down phosphoric acid refinery capacity tracking forms the analytical core of this study. Primary interviews with thermal process plant managers, foundry procurement leads at TSMC and Samsung, wet chemical distribution channel partners, and ICP-MS metrology technicians combined with secondary validation from customs and trade data, ACC and Cefic chemical industry reports, SEC 10-K filings of diversified materials suppliers, and GB standard documentation from China's Standardization Administration.
Input-output matrices map yellow phosphorus feedstock availability through thermal-process refinement stages to end-use consumption across node-specific purity tiers. Segmentation dimensions modeled include concentration grade, application vertical, end-user archetype, and packaging format across regional production hubs. CAGRs were derived from elasticity-adjusted demand projections incorporating semiconductor capital expenditure cycles and phosphorus supply constraints. Forecast inputs center on HBM memory stacking intensity and 3nm node ramp schedules.
The model assumes a particular technology adoption path; alternative pathways for continuous flow thermal processing versus batch refinement would alter the outlook for capital efficiency comparisons between European and Asian suppliers. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and feedstock supply stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Iso Nonanol Market
Chemicals
Thioacetic Acid Market
Chemicals
Hexafluorosilicic Acid Market
Chemicals
Benzoyl Alcohol Market
Chemicals
Potassium Hydrogen Phthalate Market
Chemicals
Insect Repellent Active Ingredients Market
Chemicals
4-Methyl-2-Pentanone Market
Chemicals
2-(4-(Bromomethyl)phenyl)propionic Acid (BMPPA) Market
Chemicals
Global P-Phenylenediamine Market
Chemicals
Europe Tertiary Amines Market
Chemicals
Flame Retardants Chemicals Market
Chemicals
6 Hexanediol Market
Chemicals
Non-Halogenated Flame Retardant Chemicals Market
Chemicals
1-Methylimidazole Market
Chemicals
Sodium Fluorosilicate Market
Chemicals
RDX and HMX Market