
 Glass Testing Equipment Market | 2026-2036
Glass Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Testing Equipment Market Analysis
Software-defined analytics subscriptions is decoupling hardware sales from recurring revenue in the Glass Testing Equipment Market. Instron leverages its Bluehill platform to sustain instrument attach rates through cloud-based data pipelines. ZwickRoell anchors European demand with testXpert III licensing that extends calibration intervals and reduces downtime for automotive clients. Shimadzu Corporation dominates Asian laboratory procurement through localized service contracts that control spare parts logistics and field engineer dispatch.
Glass testing equipment comprises instruments that measure optical transmission, mechanical strength, thermal shock resistance, and chemical durability against defined thresholds such as ASTM C1048 or EN 572. These systems verify that soda-lime, borosilicate, or tempered glass meets specifications for safety-critical installations. Optical testing commands the largest installed base due to mandatory haze and luminous transmittance verification in automotive windshields, though laser-based thermal analysis represents the fastest-expanding technology segment as thin-film coated architectural glass proliferates. Quality control facilities concentrate margin pools through high-throughput automated inspection lines that integrate dimensional and strength protocols in single-pass configurations.
FDA oversight of medical-grade glass packaging, EPA leachate testing protocols for recycled glass aggregates, and ISO 1288 mechanical testing standards collectively shape equipment specification sheets and procurement checklists. The EU Green Deal's embodied carbon tracking requirements are forcing manufacturers to document energy consumption per test cycle in equipment tenders. Stakeholders must weigh capital expenditure against subscription-enabled upgrade paths as regulatory test protocols tighten and instrument obsolescence accelerates.
Market Dynamics
Electrified vehicle architectures are forcing automotive glass suppliers to validate optical clarity and impact resistance under tighter tolerances, compressing test cycles and pushing laboratories toward automated multi-axis verification systems.
Growth Catalysts
- REACH chemical compliance mandates:European laboratories must document chemical resistance against SVHC candidate lists, accelerating procurement of automated titration and leachate analysis platforms.
- Thin-film coated architectural glass proliferation:Laser-based thermal analysis systems verify coating adhesion and thermal shock thresholds for energy-efficient building envelopes.
- German automotive OEM validation clusters:TÜV-certified testing houses in Stuttgart and Munich anchor regional procurement volumes for strength verification systems serving windshield and sunroof supply chains.
Market Restraints
- High-purity optical reference standards:Calibration-grade borosilicate and fused silica reference samples face supply concentration from specialized German and Japanese manufacturers, creating input cost volatility.
- F-Gas Regulation refrigerant phase-down:Thermal shock chambers using conventional cooling chemistries face retrofit costs or replacement cycles, extending capital recovery timelines for testing facilities.
- Manual inspection throughput ceilings:Human-operator haze and luminous transmittance verification cannot match automated line speeds, capping capacity expansion without full system replacement.
Strategic Opportunities
- India's PLI scheme for solar glass:Domestic manufacturing incentives for photovoltaic module substrates create demand for thermal cycling and hail impact verification equipment.
- EU Green Deal embodied carbon tracking:Equipment tenders now require documented energy consumption per test cycle, favoring suppliers with integrated power monitoring and reporting modules.
- Cloud-based predictive maintenance convergence:Edge sensors on mechanical test frames feed anomaly detection algorithms, enabling subscription revenue streams that decouple service income from hardware shipments.
Industry Challenges
- ISO 1288 mechanical testing certification timelines:Third-party accreditation for four-point bending and impact resistance protocols extends 12-18 months, delaying commercial deployment of new equipment lines.
- Multi-protocol integration complexity:Single-pass inspection lines must synchronize optical, dimensional, and strength verification subsystems without cross-interference, demanding specialized control engineering talent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Testing Equipment Market |
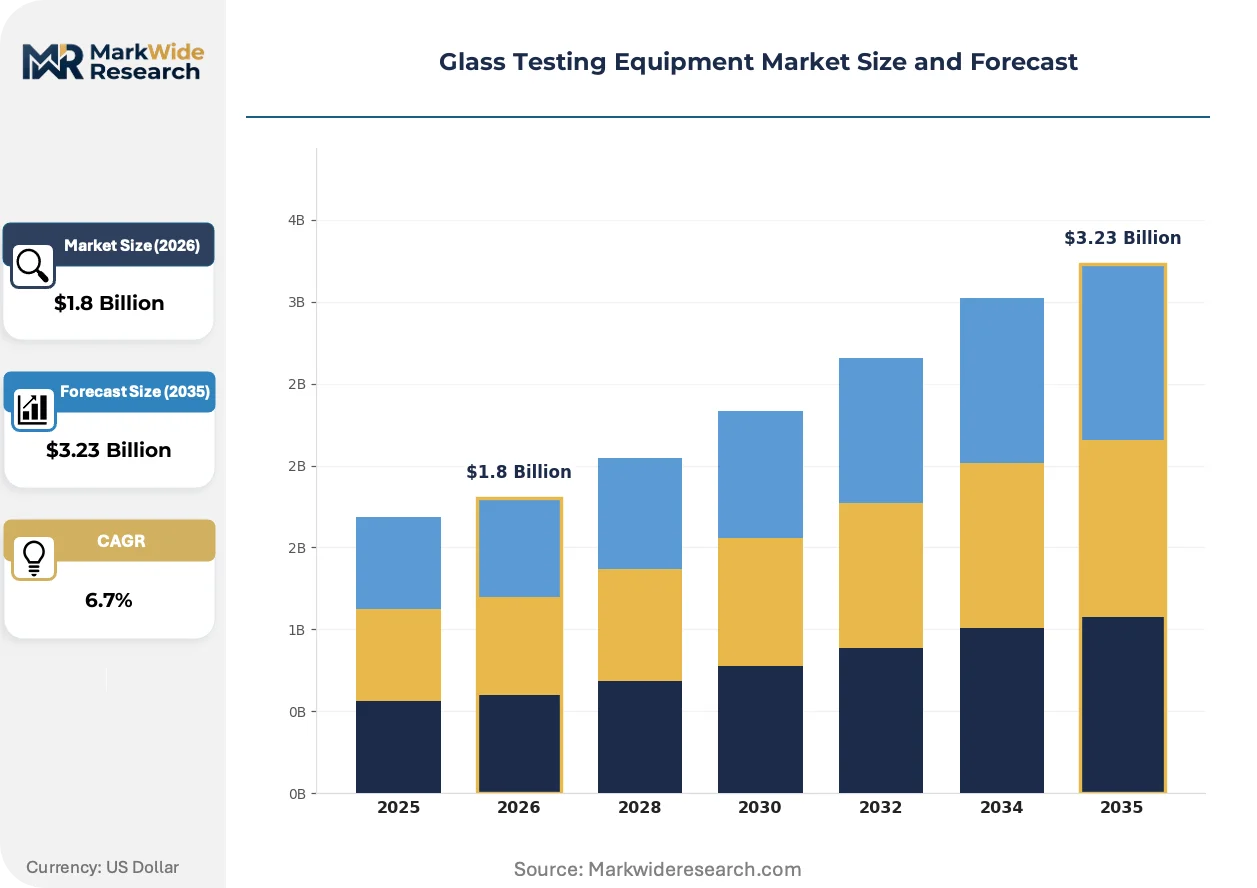
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Testing, Strength Testing, Chemical Resistance Testing, Dimensional Testing Technology: Laser, Ultrasound, Mechanical, Thermal Application: Automotive, Construction, Aerospace, Electronics End User: Manufacturers, Laboratories, Research Institutions, Quality Control Facilities |
| Companies Covered | Instron, ZwickRoell, Shimadzu Corporation, MTS Systems Corporation, Merlin Laser, GSR Laser Tools, Tinius Olsen, AMETEK, Glass Technology Services Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Testing Equipment Market Emerging Trajectories
Software-defined analytics architectures are unbundling data processing from physical instrumentation, enabling remote diagnostics and protocol updates without hardware replacement cycles.
Laser-induced breakdown spectroscopy (LIBS) is decentralizing elemental analysis capabilities previously confined to centralized laboratory facilities. Automotive glass suppliers in the Czech Republic and Slovakia are deploying handheld LIBS units for in-line silicon and sodium verification, compressing quality feedback loops from hours to minutes. This diffusion is decentralizing analytical capacity across tiered supply networks and reducing dependency on external laboratory outsourcing.
EPA leachate testing protocols for recycled glass aggregates are tightening contaminant thresholds for heavy metals and pH stability. Construction material recyclers in Texas and California face expanded documentation requirements for crushed glass destined for road base and drainage applications. Testing houses are responding with automated digestion and ICP-MS workflows that batch-process samples against Method 1311 and 1312 extraction procedures.
Subscription-enabled upgrade paths are displacing capital-intensive replacement cycles for optical inspection platforms. Japanese automotive glass manufacturers now license annual software tiers that unlock higher-resolution haze algorithms and expanded ASTM/EN protocol libraries without hardware modification. This model concentrates most visibly in Nagoya and Hiroshima manufacturing corridors where multi-site operators prioritize operational flexibility over asset ownership.
Glass Testing Equipment Market Segmentation
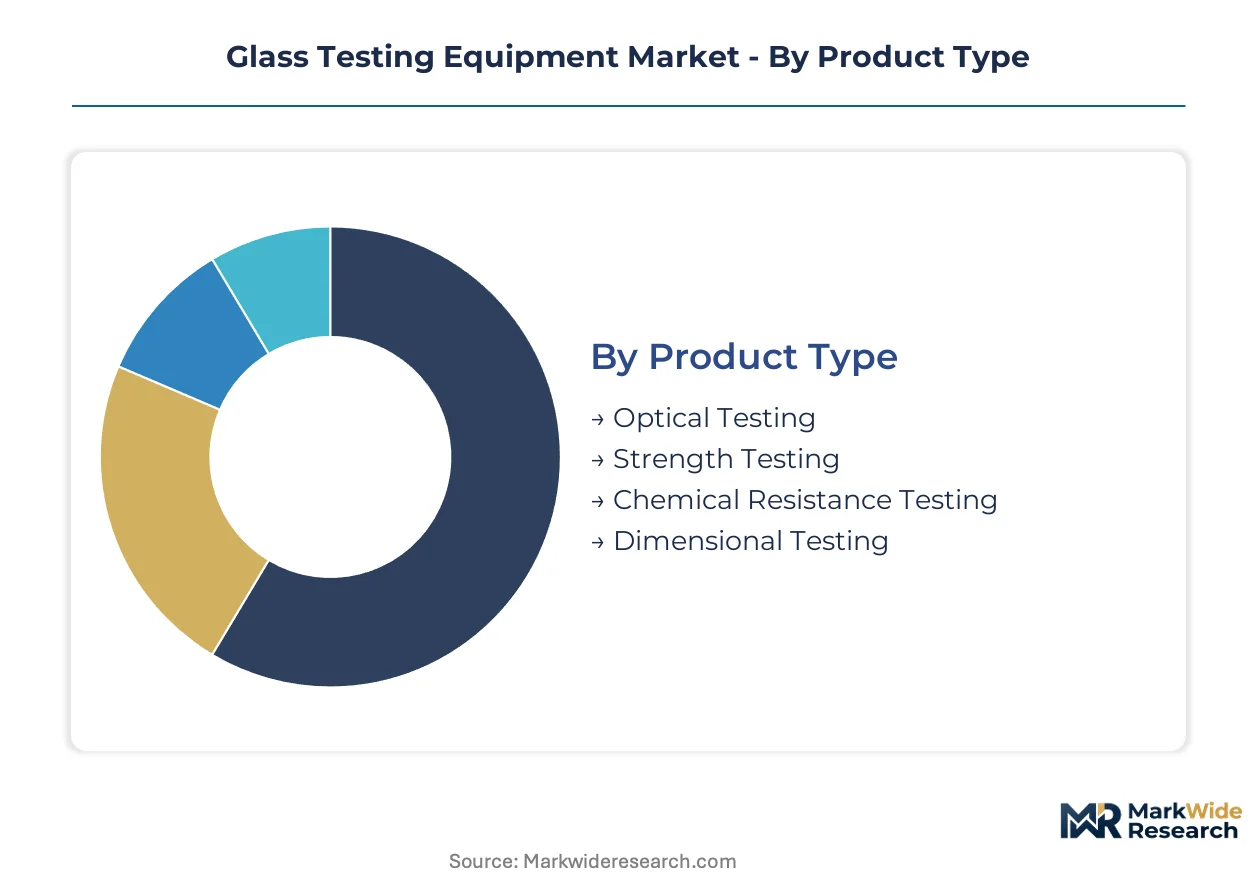
Glass testing equipment procurement patterns diverge sharply between standalone laboratory installations and embedded production-line systems. Understanding these integration depths reveals where capital concentrates versus where subscription-enabled upgrades capture recurring revenue.
Product Type:
Standalone optical and chemical resistance platforms dominate laboratory procurement budgets, while embedded dimensional and strength verification systems integrate directly into manufacturing lines.
- Optical Testing:Systems measuring haze, luminous transmittance, and refractive index against ASTM C1048 and EN 572 specifications. Demand concentrates in German automotive glass manufacturing corridors where TÜV certification mandates govern windshield and sunroof supply chains.
- Chemical Resistance Testing:Automated titration and leachate analysis platforms documenting SVHC compliance under ECHA REACH candidate lists. European laboratories in Stuttgart and Munich anchor procurement volumes as F-Gas Regulation phase-downs force equipment refreshes.
- Strength Testing:Four-point bending and impact resistance verification against ISO 1288 protocols.
- Dimensional Testing:Automated coordinate measurement and thickness verification for architectural glass production.
Volume placements concentrate in Optical Testing; the faster expansion belongs to Chemical Resistance Testing.
Technology:
Cost tiering separates premium laser systems from standardized mechanical platforms, with ultrasound and thermal technologies occupying intermediate price-performance positions.
- Laser:LIBS and thermal analysis systems enabling in-line elemental verification and coating adhesion testing. Thin-film coated architectural glass proliferation across Czech Republic and Slovakia manufacturing clusters drives fastest adoption.
- Mechanical:Conventional load-frame and pendulum impact systems serving established ASTM and EN mechanical protocols. German TÜV-certified testing houses sustain installed base through calibration contract renewals.
- Ultrasound:Non-destructive flaw detection for laminated safety glass verification.
- Thermal:Shock chambers and dilatometry systems facing retrofit pressure from F-Gas Regulation refrigerant phase-downs.
Mechanical technology retains the largest installed base; laser platforms are climbing the fastest.
Application:
Application maturity varies from automotive's protocol-heavy validation requirements to electronics' emerging thin-film substrate testing needs.
- Automotive:Electrified vehicle architectures demand stricter optical clarity and impact resistance validation under compressed test cycles. German OEM validation clusters in Stuttgart and Munich anchor regional procurement.
- Construction:EPA leachate testing protocols for recycled glass aggregates and EU Green Deal embodied carbon tracking reshape equipment specifications. Texas and California recyclers face expanded documentation requirements.
- Aerospace:High-altitude pressure differential and thermal cycling validation for cabin glazing systems.
- Electronics:Display glass and semiconductor substrate verification emerging from photovoltaic module manufacturing expansion.
Automotive application commands current procurement volume; construction compliance mandates show steepest expansion trajectory.
End User:
Customer type determines procurement rhythm, with manufacturers favoring embedded systems and laboratories prioritizing standalone analytical platforms.
- Manufacturers:In-line inspection integration prioritizing throughput and single-pass verification. Japanese automotive glass corridors in Nagoya and Hiroshima concentrate subscription-enabled software tier licensing.
- Laboratories:TÜV-certified and third-party testing houses requiring multi-protocol accreditation flexibility. ISO 1288 certification timelines extending 12-18 months shape equipment selection criteria.
- Research Institutions:Exploratory protocol development and reference standard creation.
- Quality Control Facilities:High-throughput automated inspection lines integrating dimensional and strength protocols.
Quality Control Facilities dominate current placements; Research Institutions gain share fastest as LIBS decentralization spreads analytical capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany produces the majority of high-precision strength verification systems, while consumption spreads across automotive manufacturing corridors in multiple continents. Equipment exports from Stuttgart and Munich testing clusters supply windshield validation lines in North America and Asia. Regional procurement patterns diverge sharply between F-Gas-driven replacement cycles in Europe and solar glass expansion in South Asia.
Germany
TÜV-certified testing houses in Stuttgart and Munich anchor European procurement volumes for multi-axis strength verification systems. REACH compliance mandates from ECHA accelerate automated chemical resistance platform adoption across Baden-Württemberg laboratories. Automotive OEM validation clusters concentrate in Bavaria, where electrified vehicle architectures demand compressed optical clarity test cycles.
United States
EPA leachate testing protocols for recycled glass aggregates drive equipment demand in Texas and California construction material recyclers. NHTSA automotive safety standards govern windshield impact resistance validation at Detroit-area manufacturing facilities. Quality control facilities in the Midwest integrate high-throughput automated inspection lines serving architectural glass producers.
China
Photovoltaic module substrate manufacturing expansion creates demand for thermal cycling verification equipment in Jiangsu and Zhejiang provinces. MIIT industrial standards for display glass substrates tighten dimensional tolerance requirements. Yangtze River Delta manufacturing clusters deploy laser-based coating adhesion systems for energy-efficient building envelope glass.
India
PLI scheme incentives for domestic solar glass manufacturing accelerate procurement of hail impact and thermal cycling equipment in Gujarat and Rajasthan. BIS certification requirements for construction glass tighten quality control protocols at emerging manufacturing facilities. Maharashtra-based testing laboratories expand capacity to serve automotive glass suppliers entering electrified vehicle supply chains.
Japan
METI energy efficiency standards for building materials drive laser thermal analysis adoption in Osaka and Nagoya manufacturing corridors. JIS certification protocols govern mechanical strength verification for automotive safety glass. Subscription-enabled software tier licensing concentrates in Aichi Prefecture, where multi-site operators prioritize operational flexibility over asset ownership.
Glass Testing Equipment Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the equipment spectrum. The market structure concentrates around precision instrumentation specialists with embedded software platforms and regional service networks. Three archetypes dominate: integrated multi-physics platform vendors, laser-based analytical specialists, and subscription-enabled service providers. Competitive moves center on cloud-based data pipeline integration and calibration contract bundling rather than pure hardware differentiation.
Among precision instrumentation specialists, Instron and ZwickRoell exemplify the integrated platform archetype with software-defined analytics architectures. Shimadzu Corporation anchors the Asia-Pacific service network model through localized maintenance contracts. These three occupy positions that emphasize recurring revenue attachment over standalone equipment sales, reflecting broader industry decoupling of hardware from data processing value.
| Leading Market Players |
|---|
| Instron |
| ZwickRoell |
| Shimadzu Corporation |
| MTS Systems Corporation |
| Merlin Laser |
| GSR Laser Tools |
| Tinius Olsen |
| AMETEK |
| Glass Technology Services Ltd. |
| Others |
Supply Flow & Price Mechanics
Captive calibration-grade borosilicate and fused silica reference sample production anchors pricing power for German and Japanese precision instrument manufacturers, insulating tier-one suppliers from input cost volatility while forcing tier-two assemblers toward spot-market sourcing. This integration choice concentrates margin capture upstream and fragments pricing discipline downstream.
Pricing Analysis
Cost-down pressure on mid-tier mechanical test frames accelerates as Indian and Chinese solar glass manufacturers prioritize capital efficiency over brand premium. Three-tier pricing structure across premium laser systems, standard mechanical platforms, and economy ultrasound units separates buyers by certification tier and after-sales bundling intensity. ISO 1288-accredited laboratories show lowest price sensitivity due to 12-18 month recertification timelines, while emerging photovoltaic substrate producers in Gujarat and Rajasthan drive hardest bargain on thermal cycling equipment.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Shanghai, and Nagoya orchestrate hub-and-spoke patterns for spare parts logistics and field engineer dispatch. Manufacturing concentrates in Germany, Japan, and the United States, with high-purity optical reference standards drawing from specialized borosilicate foundries in Bavaria and fused silica processors in Hokkaido. Single-source vulnerability sits with refrigerant-dependent thermal shock chambers facing F-Gas Regulation retrofit mandates. Distribution runs through TÜV-certified service networks that bundle calibration contracts with hardware placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calibration-grade reference sample scarcity props pricing for integrated platform vendors, constraining capacity expansion for testing houses dependent on external supply.
For Market Incumbents: Cement service contract bundling as the primary retention mechanism against emerging laser-based analytical specialists. Deepen backward integration into borosilicate reference standard production to neutralize Japanese supply concentration. Prioritize cloud-based predictive maintenance modules that lock in recurring revenue before hardware refresh cycles accelerate. For New Entrants and Emerging Players: TÜV-certified third-party laboratories in Central Europe present the most penetrable channel, given 12-18 month ISO 1288 recertification timelines that delay incumbent displacement. Target India's PLI-scheme solar glass corridors with thermal cycling equipment positioned on total-cost-of-ownership rather than upfront capital metrics. Pursue white-label partnerships with established German service networks to bypass direct sales infrastructure requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by precision instrumentation conglomerates seeking software-defined analytics capabilities. Long-term viability hinges on subscription revenue attach rates exceeding hardware replacement cycle compression. Watch for EPA leachate protocol tightening in Texas and California as the signal for construction compliance testing equipment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Analytics Platform Launch | Instron's Bluehill cloud architecture decouples recurring revenue from hardware refresh cycles. |
| Backward Integration into Reference Standards | Captive borosilicate production neutralizes supply concentration from Hokkaido and Bavaria foundries. |
| TÜV Certification Partnership Program | Accelerated ISO 1288 accreditation timelines lock in laboratory procurement decisions. |
| Laser Thermal Analysis Geographic Expansion | Czech and Slovak automotive clusters adopt LIBS for in-line elemental verification. |
| Predictive Maintenance Subscription Tier | Edge sensor anomaly detection converts service income to recurring software revenue. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated with primary interviews involving equipment procurement managers at automotive glass manufacturers, laboratory directors at TÜV-certified testing houses, aftermarket service heads at precision instrument vendors, and regulatory affairs leads at construction material recyclers. ECHA REACH candidate list updates, EPA Method 1311 and 1312 extraction protocols, and F-Gas Regulation phase-down schedules provided compliance-driven demand signals. Bottom-up equipment shipment analysis and top-down end-use industry sizing were reconciled across methodology approaches.
Granularity-level modeling proceeded at product-type, technology, application, and end-user dimensions, with additional segmentation by regional regulatory cluster and certification tier across the projection horizon. CAGRs were derived from equipment replacement cycle analysis, protocol update frequency, and solar glass manufacturing capacity buildout trajectories. Test cycle compression rates for electrified vehicle architectures and embodied carbon documentation requirements under EU Green Deal tenders informed automotive and construction application forecasts.
Several conditions sit outside the modeled scope, including geopolitical trade restrictions on precision optical components, abrupt refrigerant chemistry bans beyond F-Gas Regulation schedules, and laboratory accreditation body strike or restructuring events. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
In Vitro Toxicity Testing Market
Testing Equipment
Paint Tester Market
Testing Equipment
Nitrogen Tester Market
Testing Equipment
Hydrogen Peroxide Measurement Market
Testing Equipment
Drop Weight Tear Tester Market
Testing Equipment
Magnesium Testing Reagents Market
Testing Equipment
Clean-Up Gel Permeation Chromatography Market
Testing Equipment
Paper Tester Market
Testing Equipment
Analytical Gel Permeation Chromatography Market
Testing Equipment
Global Life Science and Chemical Instrumentation Market
Testing Equipment
Materials Testing Equipment Market
Testing Equipment
Chemisorption Analyzer Market
Testing Equipment
Reagent Filling Systems Market
Testing Equipment
Test Point Hoses Market
Testing Equipment
Global Chromatography Instruments Market
Testing Equipment
Automated Solid Phase Extraction Systems Market