
 Supercritical Fluid Chromatography (SFC) System Market | 2026-2036
Supercritical Fluid Chromatography (SFC) System Market Size, Share, and Industry Trends Forecast 2026-2036
Supercritical Fluid Chromatography (SFC) System Market Analytics
Pharmaceutical quality control is expanding its share of SFC system procurement as drug developers replace normal-phase HPLC with supercritical CO2-based methods for chiral separations and impurity profiling. Thermo Fisher Scientific leverages its chromatography software ecosystem to lock in pharmaceutical accounts with integrated LIMS compatibility. Shimadzu Corporation anchors its position in Asia-Pacific through localized service networks and preparative SFC configurations tailored to generic API manufacturers. Agilent Technologies differentiates by competing on detector sensitivity, offering mass spectrometry coupling that extends SFC utility into metabolomics and natural products research.
Supercritical Fluid Chromatography (SFC) systems employ carbon dioxide above its critical point as the primary mobile phase, often modified with polar co-solvents such as methanol or acetonitrile to elute compounds across a polarity range spanning lipophilic analytes to moderately polar pharmaceuticals. Operating pressures typically range from 100 to 400 bar with precise temperature control at 31-60°C, enabling rapid separation with solvent consumption roughly one-tenth of traditional liquid chromatography. Analytical SFC dominates installed base volumes in quality control environments where throughput and solvent reduction drive purchasing decisions, while preparative SFC captures disproportionate margin pools in pharmaceutical purification workflows where gram-to-kilogram scale chiral resolution commands premium pricing. Integrated SFC configurations are gaining traction in contract research organizations seeking single-platform flexibility across method development, analytical validation, and scale-up purification.
FDA guidelines on process analytical technology and green chemistry metrics shape pharmaceutical SFC adoption by rewarding solvent reduction in regulatory submissions, while EPA methods for semivolatile organic compound analysis direct environmental testing laboratories toward CO2-based alternatives to hexane and dichloromethane. REACH restrictions on chlorinated solvent use in the European Union further constrain conventional chromatography options and expand compliant SFC addressable markets. Stakeholders must monitor evolving pharmacopeial monograph acceptance of SFC methods and calibrate R&D investments against the pace at which regulatory bodies formally recognize supercritical fluid separations in official compendia.
Market Dynamics
Supercritical Fluid Chromatography system procurement is pivoting toward integrated platforms as pharmaceutical contract manufacturers consolidate analytical and preparative workflows under single-vendor ecosystems to reduce method transfer friction and validation overhead.
Growth Catalysts
- REACH solvent restrictions:ECHA's tightening limits on chlorinated solvents in European Union member states are forcing analytical laboratories to replace hexane and dichloromethane separations with CO2-based SFC methods.
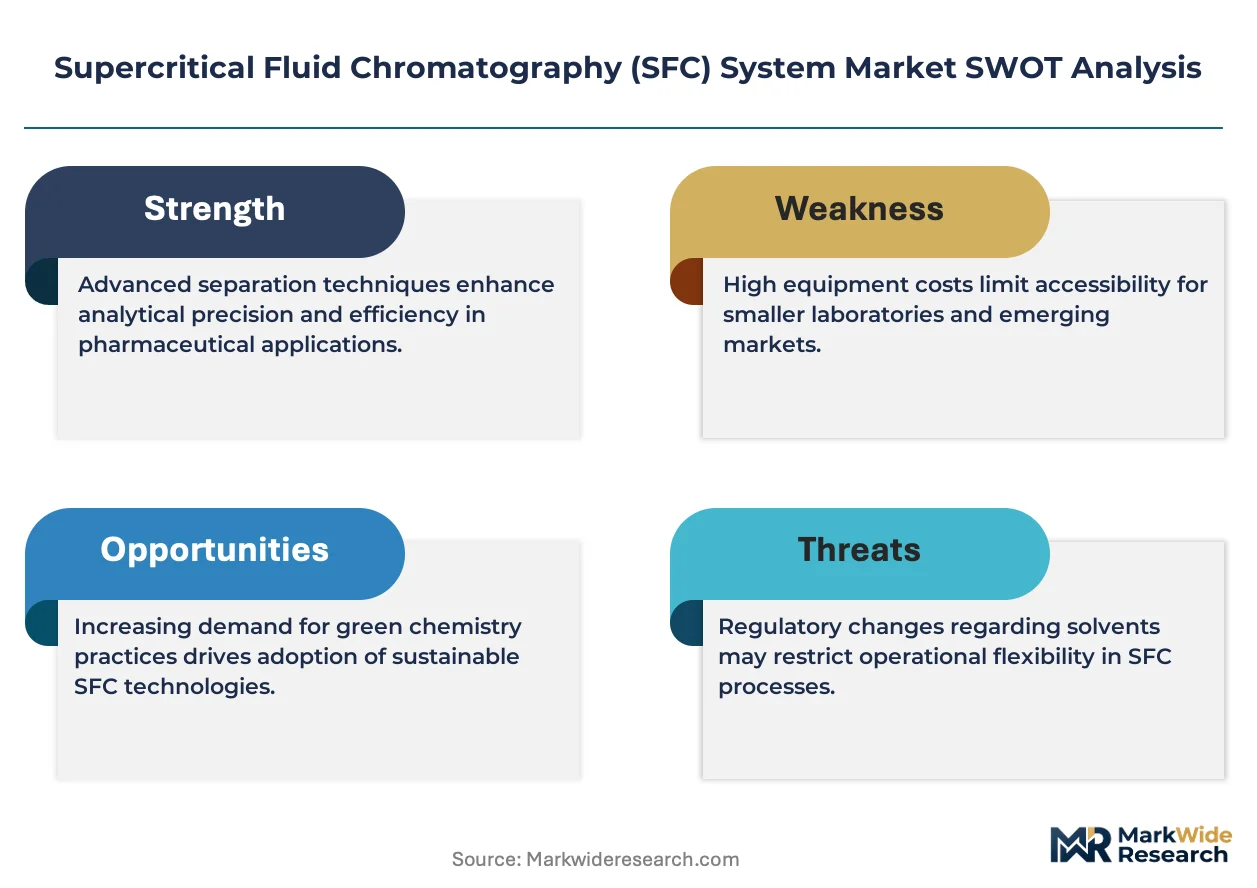
- Chiral API manufacturing:Pharmaceutical developers are scaling preparative SFC capacity to resolve enantiomers for blockbuster drug candidates, particularly in oncology and central nervous system therapeutic areas.
- Green chemistry mandates:FDA guidance on process analytical technology rewards solvent reduction metrics in regulatory submissions, creating compliance-driven procurement pull from quality control departments.
Market Restraints
- High-pressure infrastructure costs:SFC systems require specialized pumps, back-pressure regulators, and safety-rated enclosures that carry 40-60% capital premiums over conventional HPLC platforms.
- Limited co-solvent flexibility:Supercritical CO2 mobile phases demand polar modifiers like methanol or acetonitrile, restricting method development for highly polar or ionizable analytes without derivatization.
- Service network concentration:Maintenance and technical support capabilities concentrate in Germany, Japan, and the United States, leaving secondary markets dependent on extended response times.
Strategic Opportunities
- Biopharmaceutical characterization:SFC-MS coupling is penetrating monoclonal antibody and lipid nanoparticle analysis workflows, displacing size-exclusion chromatography for aggregate and excipient profiling.
- India generic API sector:CDSCO's alignment with ICH quality guidelines is creating regulatory tailwinds for SFC adoption in export-oriented manufacturing facilities serving regulated markets.
- Natural products research:Academic and government laboratories in Brazil and Australia are deploying analytical SFC for complex botanical extract screening, leveraging the technology's orthogonal selectivity to reversed-phase methods.
Industry Challenges
- Pharmacopeial method validation:USP and EP monograph recognition of SFC separations lags behind HPLC, forcing laboratories to conduct extensive equivalency studies for regulatory acceptance.
- Cross-training requirements:Analytical chemists require specialized competencies in compressible fluid behavior, back-pressure regulation, and modifier gradient optimization distinct from liquid chromatography expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Supercritical Fluid Chromatography (SFC) System Market |
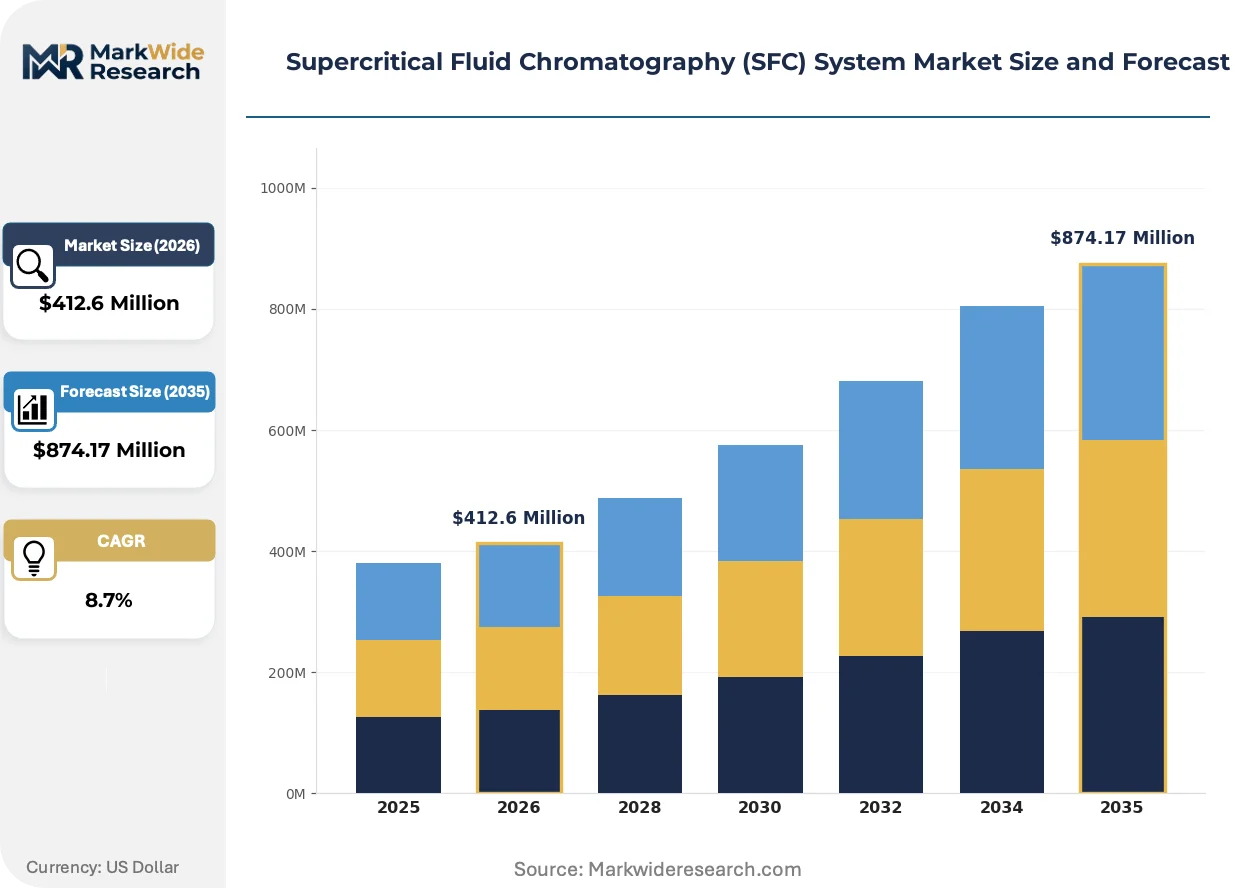
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analytical SFC, Preparative SFC, Integrated SFC, Accessories End User: Pharmaceuticals, Food & Beverage, Chemicals, Environmental Testing Technology: Gradient Elution, Batch Processing, Continuous Processing, Automated Solutions Application: Chiral Separations, Natural Products, Polymer Analysis, Environmental Monitoring |
| Companies Covered | Thermo Fisher Scientific, Thar Process, Shimadzu Corporation, BÜCHI Labortechnik AG, Supercritical Fluid Technologies (SFT), Agilent Technologies, JASCO Corporation, Fluitron, Inc., Waters Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Supercritical Fluid Chromatography (SFC) System Market Evolving Landscape
Instrument manufacturers are converging hardware architectures with software ecosystems to capture recurring revenue streams, while regulatory pressure on solvent emissions accelerates platform substitution cycles in quality control environments.
Compact benchtop SFC-MS configurations are electrifying access to supercritical separations for resource-constrained laboratories. Academic core facilities and mid-sized contract research organizations are adopting these integrated systems at twice the pace of standalone analytical SFC purchases. This democratization is compressing the addressable market for high-end modular platforms while expanding total instrument penetration.
EPA Method 1664 revision and associated state-level implementation timelines are mandating CO2-based alternatives to liquid-liquid extraction for oil and grease determinations in wastewater monitoring. Environmental testing laboratories in California, Texas, and New York are reconfiguring sample preparation workflows to maintain compliance. This regulatory vector is pulling SFC technology into municipal and industrial compliance markets previously served by gravimetric methods.
Service contract unbundling is fragmenting vendor-customer relationships in the installed base. Large pharmaceutical manufacturers are negotiating à la carte maintenance agreements and third-party validation support, displacing traditional comprehensive service packages. Germany's chemical manufacturing cluster exhibits the most aggressive procurement stance, with BASF and Bayer facilities leading multi-vendor service aggregation pilots.
Supercritical Fluid Chromatography (SFC) System Market Segmentation
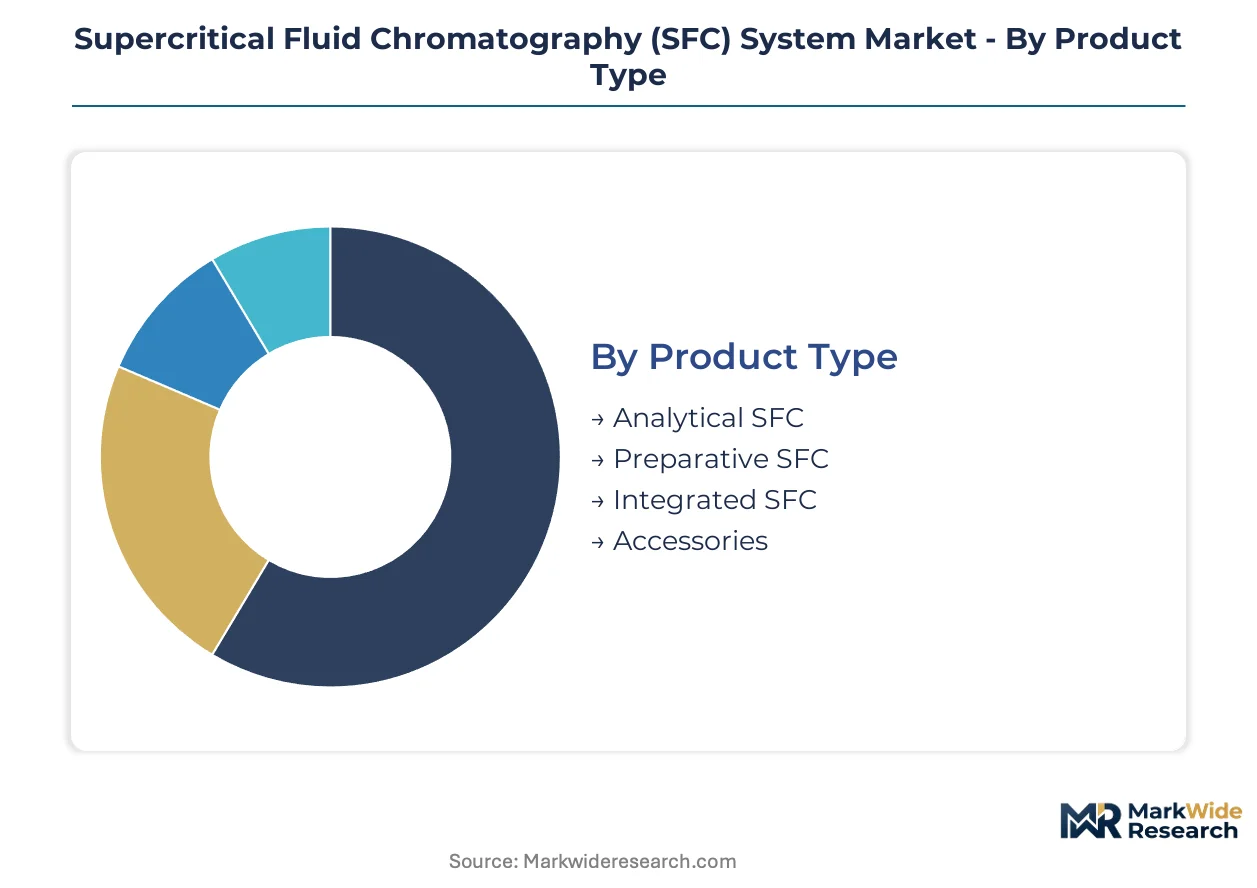
Segmentation in the SFC system market reveals divergent equipment requirements across pharmaceutical purification workflows, analytical quality control, and environmental compliance testing. Each dimension—product configuration, end-user industry, separation technology, and application focus—carries distinct procurement criteria and margin structures.
Product Type:
Analytical configurations dominate unit volumes while preparative platforms command premium pricing per installation.
- Analytical SFC:Systems designed for high-throughput quality control and method development operate at smaller column diameters with UV or MS detection. Pharmaceutical QC laboratories in Germany and the United States deploy these for chiral purity assays and impurity profiling under FDA process analytical technology guidelines.
- Preparative SFC:Large-diameter column platforms with fraction collection capabilities enable gram-to-kilogram scale enantiomer resolution. CDSCO-registered generic API manufacturers in India are expanding preparative capacity to serve regulated export markets.
- Integrated SFC:Single-platform flexibility spanning analytical method development through scale-up purification attracts contract research organizations seeking reduced validation overhead.
- Accessories:Back-pressure regulators, automated sample handlers, and specialized detectors extend functional utility of installed base systems.
Mature deployment sits with analytical SFC in established pharmaceutical QC environments. Newer deployment is concentrated in integrated configurations at multi-service contract research organizations.
End User:
Regulatory stringency and solvent restriction timelines create divergent adoption velocities across customer verticals.
- Pharmaceuticals:Chiral API development and impurity profiling drive the largest equipment procurement volumes. EMA guidelines on quality by design and FDA green chemistry metrics reward CO2-based separations in regulatory submissions.
- Food & Beverage:Natural product characterization and contaminant screening applications leverage SFC's orthogonal selectivity to conventional HPLC methods.
- Chemicals:Specialty chemical manufacturers in Germany prioritize supercritical CO2 separations to satisfy REACH compliance and reduce hazardous solvent inventory.
- Environmental Testing:EPA Method 1664 implementation timelines are mandating CO2-based alternatives to liquid-liquid extraction for oil and grease determinations in wastewater monitoring.
Procurement concentration rests with pharmaceutical quality control departments. Steepest expansion trajectory is appearing in environmental testing laboratories responding to revised federal and state-level compliance methods.
Technology:
Automation intensity and method transfer complexity separate premium system configurations from standard analytical platforms.
- Gradient Elution:Modifier programming capabilities enable separation of complex mixtures across broad polarity ranges. Academic core facilities deploy gradient-capable systems for natural product screening workflows.
- Batch Processing:Discrete sample loading and fraction collection suit pharmaceutical purification of high-value chiral intermediates.
- Continuous Processing:Steady-state operation with inline detection supports high-throughput quality control in large-volume manufacturing environments.
- Automated Solutions:Robotic sample handling and method scheduling reduce operator intervention for unattended overnight runs.
Batch processing retains dominance in preparative pharmaceutical applications. Continuous processing is gaining share fastest in high-volume generic API manufacturing facilities.
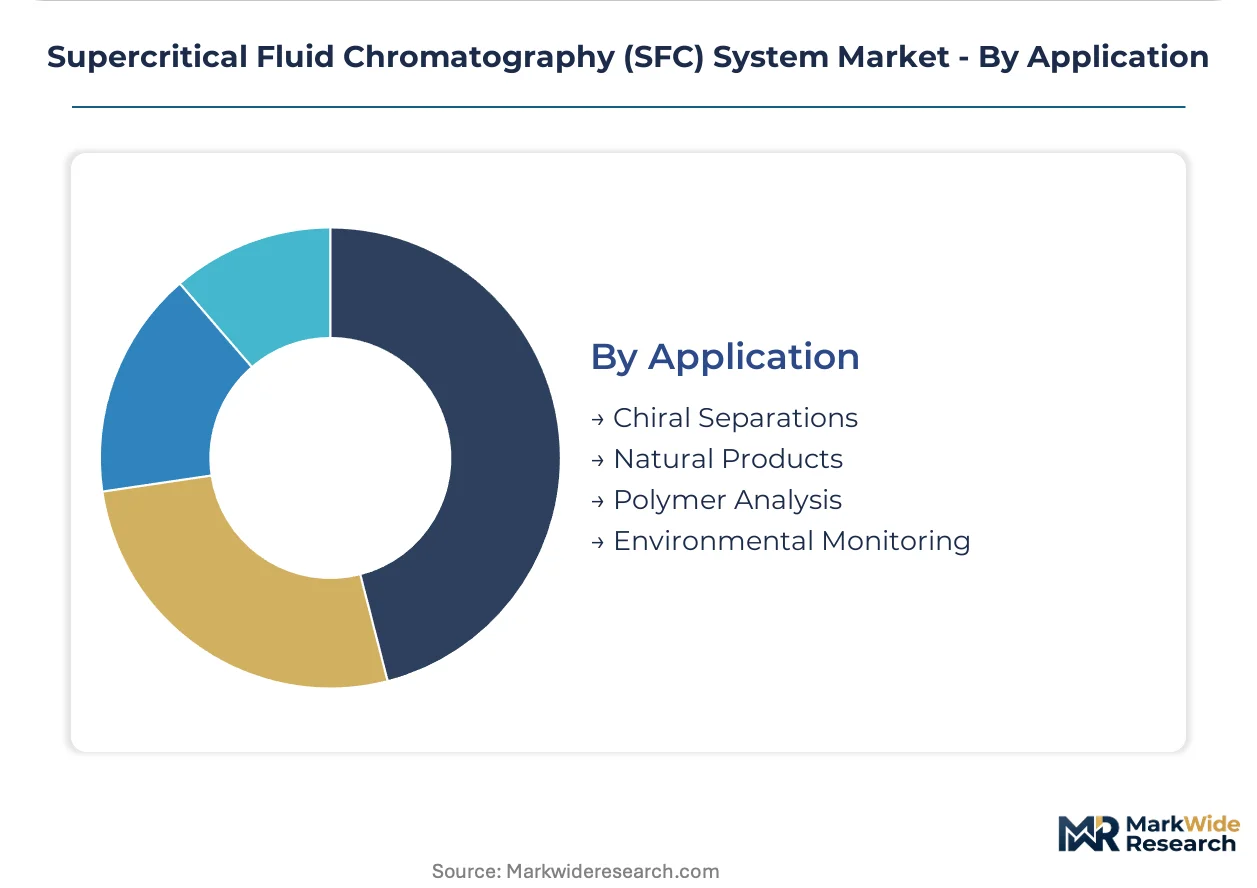
Application:
Method complexity and regulatory recognition levels shape equipment specification requirements across use cases.
- Chiral Separations:Enantiomeric resolution for drug substance purity and natural product stereochemistry represents the core commercial application. Pharmacopeial monograph acceptance for SFC chiral methods continues expanding.
- Natural Products:Botanical extract screening and complex mixture characterization leverage SFC's rapid separation speed and reduced solvent consumption.
- Polymer Analysis:Molecular weight distribution and additive profiling applications exploit supercritical CO2's solvation characteristics for synthetic macromolecules.
- Environmental Monitoring:Semivolatile organic compound analysis and oil and grease determinations align with EPA method revisions.
Established application depth sits with chiral separations in pharmaceutical development. Emerging application intensity is concentrating in environmental monitoring workflows driven by regulatory method mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of SFC systems concentrates in Germany, Japan, and the United States, while consumption spreads across pharmaceutical manufacturing clusters responding to solvent restriction timelines. The geographic mismatch between equipment fabrication and end-use deployment shapes service network economics and method validation protocols.
United States
FDA process analytical technology guidelines reward CO2-based separations in regulatory submissions, pulling procurement from quality control departments at Merck and Pfizer facilities. EPA Method 1664 revision mandates CO2 alternatives to liquid-liquid extraction for oil and grease determinations, forcing environmental testing laboratories in California and Texas to reconfigure workflows. The Boston-Cambridge biotech corridor deploys compact SFC-MS configurations for monoclonal antibody characterization.
Germany
REACH restrictions on chlorinated solvents constrain conventional chromatography options for BASF and Bayer analytical laboratories. ECHA enforcement timelines accelerate platform substitution cycles in chemical manufacturing facilities. The Rhine-Ruhr industrial cluster leads multi-vendor service aggregation pilots, unbundling traditional comprehensive maintenance agreements.
Japan
PMDA quality by design guidelines align with ICH standards, creating regulatory tailwinds for SFC adoption in export-oriented pharmaceutical manufacturing. METI green chemistry initiatives subsidize solvent reduction technologies for domestic generic API producers. The Kansai region hosts concentrated preparative SFC capacity serving oncology and central nervous system therapeutic development.
India
CDSCO alignment with ICH quality guidelines drives SFC procurement in CDSCO-registered generic API facilities serving regulated export markets. The country's national pharmaceutical regulator tightens impurity profiling requirements for abbreviated new drug applications. Maharashtra and Gujarat pharmaceutical manufacturing clusters expand preparative SFC capacity for gram-to-kilogram scale chiral resolution.
China
NMPA pharmacopeial method validation standards gradually incorporate SFC separations for traditional medicine and synthetic API quality control. The national medical products administration incentivizes green analytical chemistry adoption through regulatory fast-track provisions. Yangtze River Delta contract research organizations deploy integrated SFC platforms to reduce method transfer friction across analytical and preparative workflows.
Supercritical Fluid Chromatography (SFC) System Market Competitive Landscape
Top-tier vendors anchor the analytical-preparative integrated platform segment, while mid-scale specialists occupy modular configurations and regional service markets. The vendor base stratifies across chromatography conglomerates with software ecosystem lock-in, precision engineering houses with back-pressure regulator specialization, and emerging Asian fabricators competing on capital cost. Two strategic archetypes dominate: integrated platform providers capturing recurring revenue through LIMS compatibility, and preparative specialists commanding premium pricing for chiral purification scale-up. Competitive moves concentrate on geographic service network expansion and detector sensitivity differentiation.
Among diversified analytical instrumentation conglomerates, Thermo Fisher Scientific, Agilent Technologies, and Waters Corporation exemplify the integrated platform archetype. These entities occupy positions where chromatography software ecosystems anchor pharmaceutical accounts through method transfer friction reduction. Shimadzu Corporation anchors the Asia-Pacific regional specialist tier, with localized service networks representing its competitive positioning against Western conglomerates. Thar Process and Supercritical Fluid Technologies exemplify the preparative specialization archetype, sitting within segments where gram-to-kilogram scale chiral resolution commands premium pricing.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Thar Process |
| Shimadzu Corporation |
| BÜCHI Labortechnik AG |
| Supercritical Fluid Technologies (SFT) |
| Agilent Technologies |
| JASCO Corporation |
| Fluitron, Inc. |
| Waters Corporation |
| Others |
Value Network & Pricing Analysis
REACH solvent restrictions gate qualified supply and premium-tier pricing access for SFC system vendors, as ECHA compliance certification separates Tier 1 suppliers from economy-tier competitors serving price-sensitive academic laboratories. Buyers in Germany's chemical manufacturing cluster pay structural premiums for validated back-pressure regulators and safety-rated enclosures that satisfy hazardous substance directives.
Pricing Analysis
Margin tightening in economy-tier analytical SFC reflects aggressive Asian fabricators compressing capital premiums for compact benchtop configurations. Three-tier pricing structure across premium, standard, and economy levels separates integrated platform providers with LIMS compatibility from modular specialists and commodity pump suppliers. Price differentiation hinges on detector sensitivity specifications and after-sales service bundling. CDSCO-registered generic API manufacturers in India exhibit highest price sensitivity, while Merck and Pfizer facilities absorb premium pricing for preparative scale-up systems.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States anchor hub-and-spoke patterns for precision-engineered back-pressure regulators and specialized pump assemblies. Manufacturing concentration in these three countries draws from stainless steel forgings, ceramic piston seals, and supercritical-grade CO2 compressors as critical inputs. Single-source vulnerability concentrates in Japanese ceramic seal suppliers serving high-pressure pump modules. Distribution runs through authorized service partners with factory-trained technicians, though Germany's Rhine-Ruhr cluster pilots multi-vendor aggregation disrupting traditional comprehensive contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH solvent restrictions erect barrier-to-entry moats for vendors with ECHA-certified component supply chains and validated pharmacopeial method libraries.
For Market Incumbents: Extend software ecosystem lock-in through LIMS compatibility investments that increase method transfer friction for pharmaceutical accounts facing FDA process analytical technology deadlines. Deepen backward integration into back-pressure regulator manufacturing to defend margin position against Asian pump specialists. Anchor service network density in Maharashtra and Gujarat pharmaceutical clusters before CDSCO impurity profiling requirements accelerate procurement. For New Entrants and Emerging Players: The price-point gap between premium integrated platforms and economy analytical SFC creates entry space for mid-tier vendors offering gradient-elution capabilities without mass spectrometry coupling. Target environmental testing laboratories in California and Texas responding to EPA Method 1664 revision timelines with compact CO2-based oil and grease determination systems. Pursue à la carte service contract unbundling as the go-to-market angle, mirroring BASF and Bayer procurement pilots in Germany. For Investors and Strategic Acquirers: CDSCO's alignment with ICH quality guidelines is the leading indicator that preparative SFC capacity expansion in India will accelerate acquisition multiples for regional service-capable vendors. Long-term viability favors platform providers with recurring software revenue streams over hardware-only specialists exposed to capital cycle volatility. Monitor EPA state-level implementation timelines as the inflection signal for environmental testing laboratory reconfiguration demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Back-Pressure Regulator Manufacturing | Captive supply of critical high-pressure components reduces dependency on Japanese ceramic seal suppliers and compresses cost structures. |
| LIMS Compatibility Certification Investment | Thermo Fisher Scientific's pharmaceutical account retention demonstrates software ecosystem lock-in value against modular competitors. |
| Regional Service Network Expansion in India | Maharashtra and Gujarat pharmaceutical clusters require localized maintenance capabilities as CDSCO registration drives SFC adoption. |
| Compact SFC-MS Platform Launch | Academic core facilities and mid-sized CROs adopt integrated configurations at twice the pace of standalone analytical purchases. |
| Multi-Vendor Service Aggregation Pilot | BASF and Bayer facilities in Germany's Rhine-Ruhr cluster unbundle traditional comprehensive contracts, fragmenting vendor-customer relationships. |
Research Methodology
Independent corroboration across primary interviews with pharmaceutical quality control directors, environmental testing laboratory managers, and chromatography instrument procurement officers underwrites the qualitative findings. Secondary validation draws from FDA guidance documents on process analytical technology, ECHA REACH restriction timelines, EPA Method 1664 revision notices, and SEC filings of diversified analytical instrumentation conglomerates. Bottom-up equipment procurement modeling and top-down market sizing triangulate volume and value estimates.
Comparable-period anchoring to historical pharmaceutical capital expenditure cycles and environmental compliance method implementation timelines shapes the projection framework. Segmentation dimensions span product configuration, end-user industry vertical, separation technology type, and application focus across the modeling period. CAGRs derive from regression analysis of installed base substitution rates and preparative capacity expansion trajectories, with inputs including CDSCO registration trends and METI green chemistry subsidy disbursements.
Inputs from ECHA enforcement databases and EPA state-level implementation schedules were available through the study window; gaps in real-time pharmaceutical procurement pipeline data introduce uncertainty bands around near-term volume forecasts. Forecasts reflect documented assumptions regarding regulatory recognition timelines for SFC methods in USP and EP monographs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Global Dynamic Mechanical Analyzers Market
Testing Equipment
Global Online Coal Ash Analyzers Market
Testing Equipment
Flammability Test Chamber Market
Testing Equipment
Microplastics Particle Size and Shape Characterization Systems Market
Testing Equipment
Liquid Analytical Instrument Market
Testing Equipment
Chemisorption Analyzer Market
Testing Equipment
Global Film Thickness Measurement Market
Testing Equipment
Reagent Filling Systems Market
Testing Equipment
Global Life Science and Chemical Instrumentation Market
Testing Equipment
Fugitive Emissions Detection and Quantification Test Systems Market
Testing Equipment
Global Liquid Chromatography Systems Market
Testing Equipment
Americas Testing, Inspection and Certification (TIC) Market
Testing Equipment
Low-Pressure Liquid Chromatography Market
Testing Equipment
Water Test Kits Market
Testing Equipment
Supercritical Fluid Chromatography Market
Testing Equipment
Pellistor Bead Chemical Sensor Market