
 Viscometer Market | 2026-2036
Viscometer Market Size, Share, and Industry Trends Forecast 2026-2036
Viscometer Market Outlook
Equipment leasing and performance-based contracting is narrowing the competitive field for viscometer procurement. Anton Paar GmbH leverages its Austrian manufacturing base to sustain premium positioning in rotational instruments. Thermo Fisher Scientific anchors North American demand through extensive service networks and integrated laboratory workflows. TA Instruments differentiates via high-sensitivity oscillatory rheometry for polymer research.
A viscometer measures fluid resistance to flow under controlled shear conditions, typically reporting viscosity in centipoise or Pascal-seconds using calibrated capillary tubes, rotating spindles, or oscillating plates at specified temperatures and shear rates. The instrument ensures batch consistency in coatings, drug formulations, and petrochemical refining. Rotational viscometers dominate installed base revenue due to versatility across Newtonian and non-Newtonian fluids, while portable units capture fastest growth from at-line deployment in food processing plants. Digital technology segments command margin premiums through automated data logging and LIMS integration that reduces manual transcription errors.
FDA process analytical technology guidance and EMA quality-by-design frameworks mandate real-time viscosity verification for sterile injectable manufacturing, compelling upgrades from manual to automatic systems. ISO 17025 laboratory accreditation requirements in Germany and Switzerland further tighten calibration traceability standards. Stakeholders must weigh capital deployment between benchtop precision and in-line process integration as regulatory scrutiny intensifies on continuous manufacturing transitions.
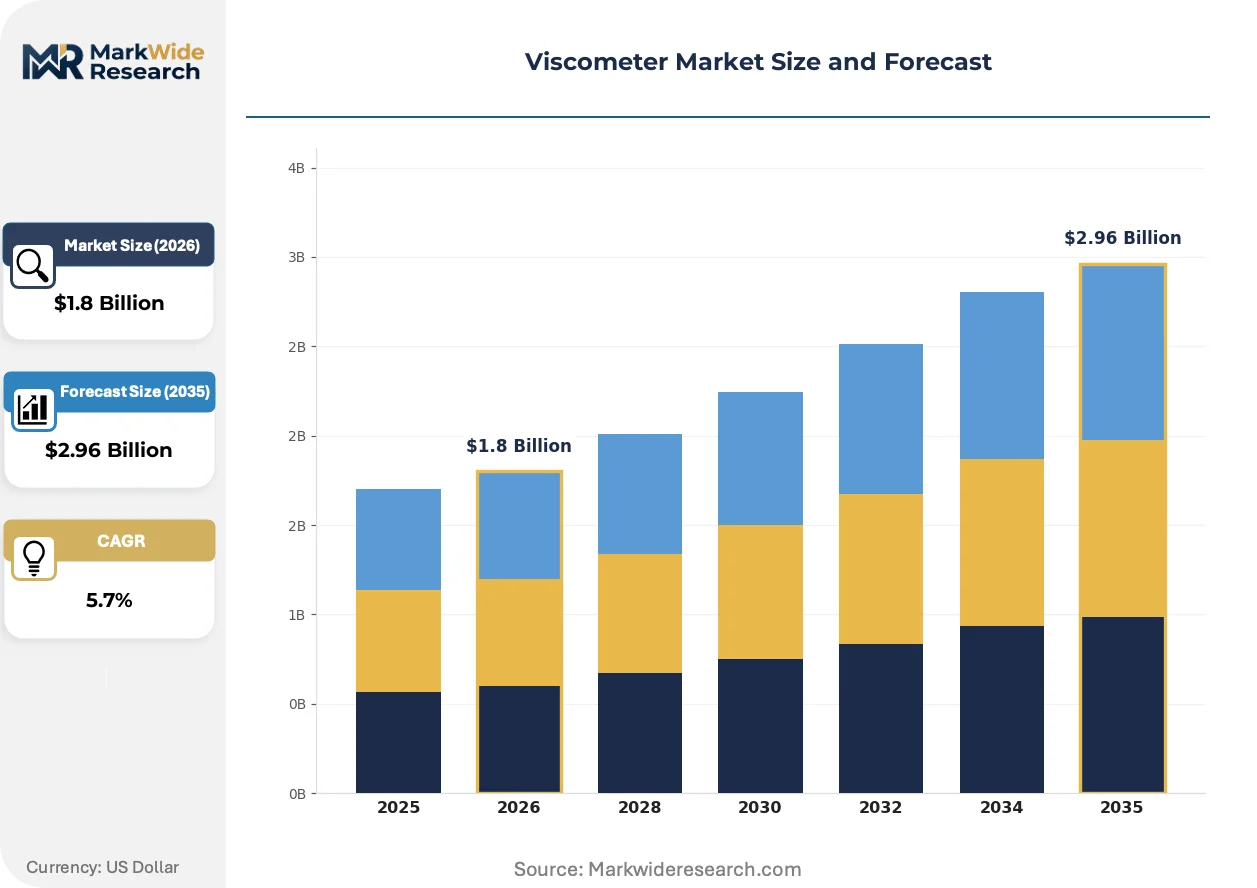
Market Dynamics
Pharmaceutical manufacturers in Germany and the United States are expanding quality control laboratories that require precise rheological measurement, while FDA process analytical technology guidance and EMA quality-by-design frameworks mandate real-time viscosity verification for sterile injectable manufacturing.
Growth Catalysts
- EMA Quality-by-Design Guidelines:European pharmaceutical manufacturers must implement continuous manufacturing with automated in-line viscosity monitoring, replacing manual sampling protocols.
- Germany's Chemical Corridor:Concentrated demand around Ludwigshafen and Leverkusen drives specialized viscometer procurement for polymer and coating quality control.
- Digital Technology Integration:Automated data logging and LIMS integration reduces manual transcription errors, compelling laboratory upgrades across regulated industries.
Market Restraints
- Calibration Traceability Costs:ISO 17025 laboratory accreditation requirements in Germany and Switzerland impose recurring calibration expenses that burden mid-sized laboratories.
- Capital Deployment Tension:Stakeholders must weigh investment between benchtop precision instruments and in-line process integration systems with divergent payback timelines.
- Portable Unit Limitations:At-line deployment in food processing plants sacrifices measurement sensitivity compared to laboratory-grade rotational systems.
Strategic Opportunities
- Continuous Manufacturing Transition:FDA process analytical technology initiative creates demand for real-time viscosity sensors in biologics and sterile injectable production.
- Service Network Expansion:Performance-based contracting and equipment leasing models open recurring revenue streams beyond instrument sales.
- Food Processing Automation:Portable viscometer deployment at-line in dairy and beverage plants addresses batch consistency requirements with minimal infrastructure.
Industry Challenges
- Rheology Specialist Shortage:Interpretation of non-Newtonian fluid behavior requires trained personnel scarce in contract manufacturing organizations.
- Legacy System Integration:Digital viscometers must interface with existing laboratory information management systems through proprietary protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Viscometer Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotational, Capillary, Oscillatory, Portable Technology: Digital, Mechanical, Semi-Automatic, Automatic End User: Food & Beverage, Pharmaceuticals, Chemicals, Oil & Gas Application: Quality Control, Research & Development, Process Control, Formulation |
| Companies Covered | Thermo Fisher Scientific, Anton Paar GmbH, TA Instruments, AMETEK, Cannon Instrument Company, Hydramotion, Brabender GmbH, Lamy Rheology, Shimadzu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Viscometer Market Strategic Shifts
Viscometer technology is converging with process analytical technology and laboratory informatics, creating instruments that function as nodes within integrated quality systems rather than standalone measurement devices.
Microelectromechanical systems viscometry is hybridizing capillary and oscillatory measurement principles into single compact sensors. Biotechnology firms in Massachusetts and North Carolina are piloting these devices for real-time cell culture media monitoring. The technology is hybridizing quality control workflows by collapsing offline laboratory analysis into continuous bioprocess verification.
EMA's quality-by-design framework now mandates design space verification with multivariate process data including viscosity. Sterile injectable manufacturers must demonstrate real-time release capability, forcing integration of in-line sensors with distributed control systems. German pharmaceutical facilities face the tightest compliance timelines as notified bodies prioritize inspections for continuous manufacturing transitions.
Equipment leasing with embedded calibration services is displacing capital purchase models among mid-sized contract development and manufacturing organizations. Third-party service providers now bundle instrument provision with ISO 17025-compliant maintenance, transferring compliance risk from laboratory operators. This restructuring concentrates most visibly in Switzerland's pharmaceutical cluster around Basel, where facility consolidation has reduced internal metrology staffing.
Viscometer Market Segmentation
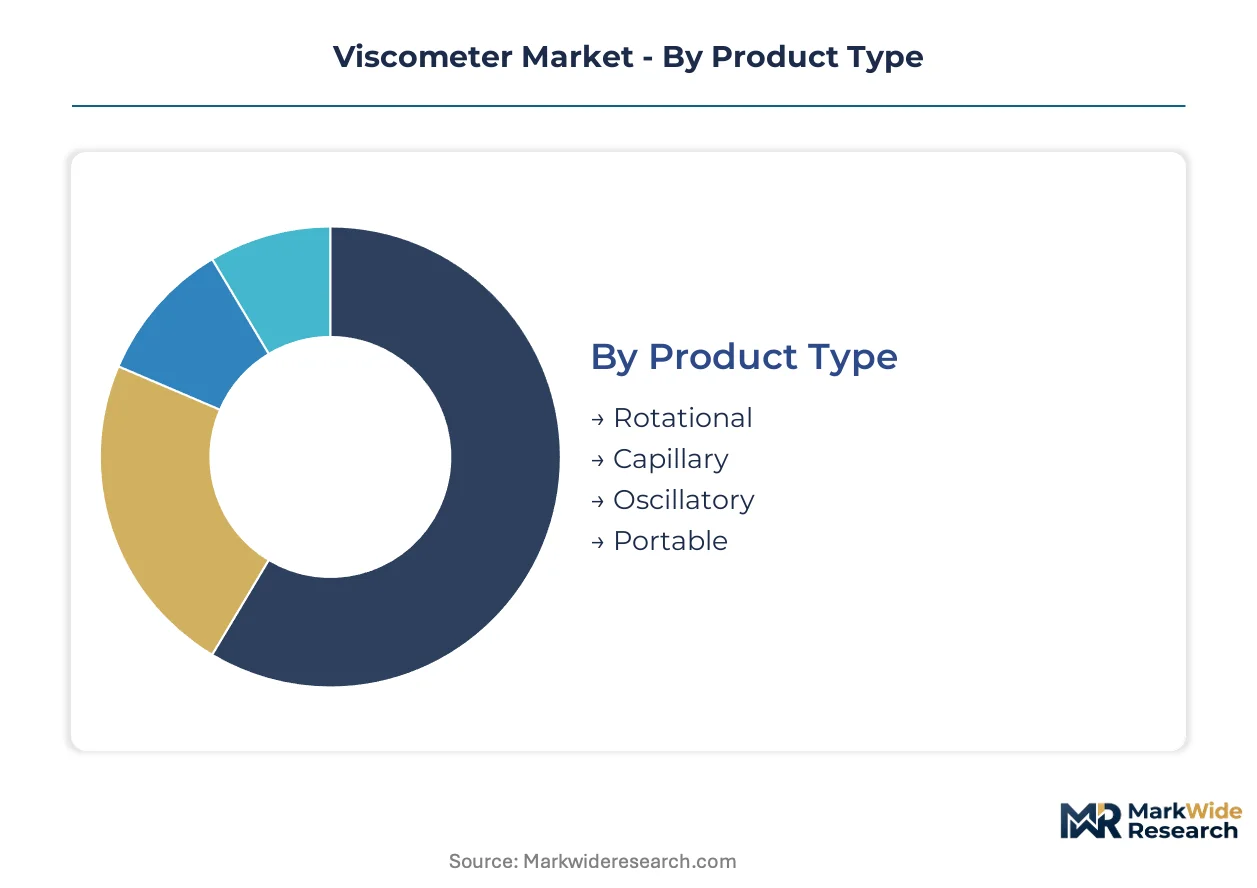
Viscometer procurement patterns diverge sharply across measurement principles, automation levels, and regulatory environments. Pharmaceutical quality control demands precision instruments with full traceability, while food processing prioritizes rapid at-line deployment.
Product Type:
Measurement principle determines instrument versatility across Newtonian and non-Newtonian fluid characterization.
- Rotational:Spindle-based systems measure torque resistance across variable shear rates, accommodating both simple and complex rheological behaviors. German chemical manufacturers around Ludwigshafen deploy these for polymer melt characterization under EMA quality-by-design protocols.
- Portable:Handheld units sacrifice laboratory precision for deployment flexibility at production lines. Dairy processors in Switzerland and beverage plants across the United States adopt these for batch release decisions without laboratory infrastructure.
- Capillary:Glass tube systems rely on timed flow through calibrated orifices for kinematic viscosity determination.
- Oscillatory:Plate-and-cone configurations apply sinusoidal strain for viscoelastic property mapping.
The dominant share belongs to Rotational instruments, while Portable units are closing the gap fastest.
Technology:
Automation tier shapes capital deployment and compliance risk for regulated manufacturers.
- Automatic:Self-calibrating systems with embedded temperature control and LIMS connectivity eliminate manual transcription errors. FDA process analytical technology guidance drives pharmaceutical adoption for real-time release of sterile injectables.
- Digital:Microprocessor-based instruments store measurement protocols and export timestamped data directly to quality systems. Swiss and German laboratories pursuing ISO 17025 accreditation favor these for audit trail completeness.
- Mechanical:Analog dial-readout devices persist in legacy installations and educational settings.
- Semi-Automatic:Hybrid systems require manual sample loading but automate measurement sequences.
Automatic systems command the premium tier, with Digital technology expanding most quickly through mid-sized contract laboratories.
End User:
Industry-specific fluid characteristics dictate instrument specification and service intensity.
- Pharmaceuticals:Sterile injectable and biologics manufacturers require validated systems with 21 CFR Part 11-compliant software. EMA quality-by-design mandates and FDA process analytical technology initiatives compel continuous manufacturing upgrades with in-line viscosity verification.
- Chemicals:Polymer and coating producers in Germany's chemical corridor demand high-temperature rotational systems for quality control.
- Food & Beverage:Dairy, sauce, and beverage processors prioritize rapid at-line measurement for batch consistency.
- Oil & Gas:Refinery laboratories and lubricant blenders measure kinematic viscosity for product certification.
Pharmaceuticals anchor the highest-value segment, though Chemicals maintains the broadest installed base.
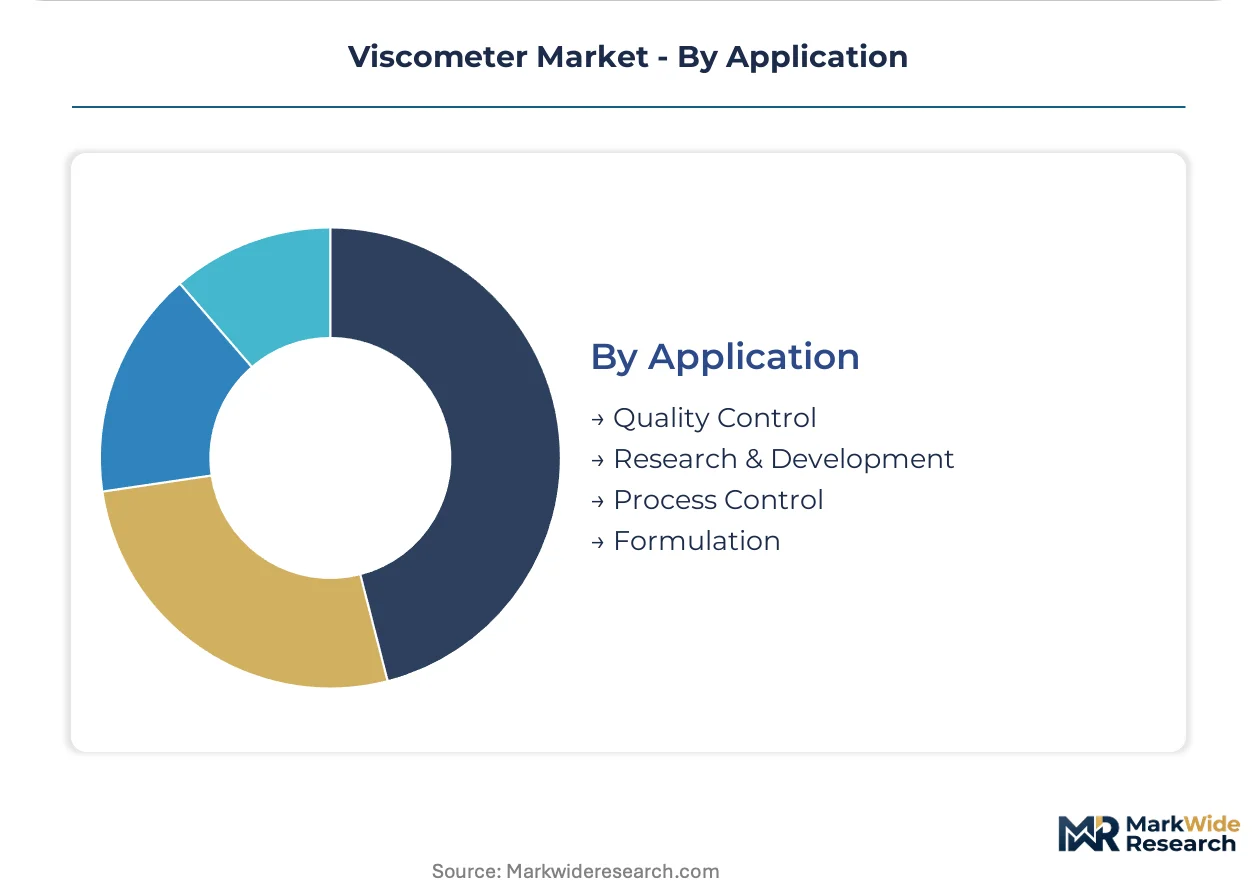
Application:
Workflow position determines integration depth and regulatory scrutiny intensity.
- Quality Control:Batch release testing demands full calibration traceability and documented measurement uncertainty. German and Swiss pharmaceutical facilities face tightened ISO 17025 requirements for viscosity verification of final product.
- Process Control:In-line sensors enable real-time adjustment of manufacturing parameters. Biotechnology firms in Massachusetts pilot microelectromechanical systems for continuous cell culture media monitoring.
- Research & Development:Formulation scientists characterize novel fluid behaviors across temperature and shear profiles.
- Formulation:Product development teams optimize viscosity for application properties and stability.
Quality Control generates the largest instrument revenue pool, with Process Control showing the steepest expansion trajectory as continuous manufacturing adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor established manufacturing bases in Europe and North America, while import-dependent markets in Asia-Pacific accelerate localized assembly partnerships to reduce lead times and currency exposure.
United States
FDA process analytical technology guidance drives pharmaceutical manufacturers in Massachusetts and North Carolina toward automated in-line viscosity monitoring for sterile injectable production. Biotechnology clusters around Boston and Research Triangle Park pilot microelectromechanical systems for real-time cell culture media verification. Equipment leasing models concentrate among mid-sized contract development organizations seeking to transfer calibration compliance risk.
Germany
EMA quality-by-design mandates compel continuous manufacturing upgrades across pharmaceutical facilities in Ludwigshafen and Leverkusen. ISO 17025 accreditation requirements tighten calibration traceability standards for chemical corridor laboratories serving polymer and coating producers. Notified bodies prioritize inspections for manufacturing transitions, accelerating replacement of manual sampling protocols with automated systems.
Switzerland
Facility consolidation around Basel reduces internal metrology staffing, pushing contract manufacturers toward third-party service providers bundling instrument provision with compliant maintenance. Swissmedic oversight of sterile manufacturing reinforces demand for validated systems with full audit trail capabilities. Pharmaceutical quality control laboratories face compressed timelines for design space verification.
China
NMPA alignment with international quality standards drives upgrades in domestic pharmaceutical manufacturing, though import substitution policies favor local assembly partnerships over direct equipment purchases. Chemical producers in Jiangsu and Zhejiang provinces expand quality control capacity for polymer and coating exports. Joint ventures with European instrument manufacturers accelerate technology transfer for rotational viscometer production.
Japan
PMDA emphasis on real-time release testing for biologics creates demand for integrated viscosity sensors in continuous manufacturing lines. Pharmaceutical producers in Kanto and Kansai regions invest in automated data logging systems to eliminate manual transcription errors. METI support for process analytical technology adoption reduces regulatory friction for technology upgrades.
Viscometer Market Competitive Environment
On the supply side, the industry is consolidating around three strategic tiers distinguished by automation depth and service integration. Premium positioned manufacturers anchor through proprietary sensor technology and embedded calibration protocols. Mid-tier competitors compete on lease-based contracting and regional service density. Value-oriented fabricators concentrate on portable units for at-line deployment with simplified feature sets. Competitive moves center on performance-based contracting restructuring and backward integration into sensor component manufacturing.
Within the premium instrumentation tier, Anton Paar GmbH and TA Instruments exemplify archetypes built on precision manufacturing heritage and application-specific specialization respectively. Thermo Fisher Scientific occupies a position bridging premium technology with extensive North American service infrastructure. These three entities represent distinct competitive vectors: Austrian manufacturing base leverage, high-sensitivity oscillatory rheometry focus, and integrated laboratory workflow anchoring.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Anton Paar GmbH |
| TA Instruments |
| AMETEK |
| Cannon Instrument Company |
| Hydramotion |
| Brabender GmbH |
| Lamy Rheology |
| Shimadzu Corporation |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in precision sensor manufacturing across Austria and Germany tightens supply discipline, pushing rotational viscometer producers toward premium positioning and extended lead times for validated systems.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on ISO 17025 certification grade and embedded calibration service bundling. Cost compression in the economy tier intensifies because Asian fabricators are scaling portable unit assembly. Mid-sized contract laboratories exhibit highest price sensitivity, while sterile pharmaceutical manufacturers show lowest sensitivity due to compliance risk transfer priorities.
Supply Chain Analysis
Precision temperature sensors and microelectromechanical strain gauges draw from specialized component networks in Japan, Germany, and Switzerland. Borosilicate glass capillary tubing and high-torque stepper motors constitute critical input dependencies. Single-source vulnerability concentrates in MEMS foundry capacity for oscillatory plate sensors. Distribution runs through authorized service partnerships that bundle installation validation with ISO-compliant maintenance protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among mid-sized contract development organizations pursuing equipment leasing, fragmenting procurement authority away from centralized capital committees.
For Market Incumbents: Harden calibration service lock-in by embedding ISO 17025-compliant maintenance into multi-year contracts, transferring compliance risk from laboratory operators. Deepen backward integration into MEMS sensor component manufacturing to secure supply against Asian foundry competition. Prioritize channel control through exclusive service territory arrangements in Switzerland's Basel cluster.
For New Entrants and Emerging Players: China's Jiangsu province offers underpenetrated white-space for portable viscometer assembly partnerships serving domestic chemical exporters. Target food processing automation in Brazil's dairy corridor through distributor relationships that bypass incumbent service infrastructure. Lead with at-line deployment value propositions emphasizing minimal infrastructure requirements.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because FDA and EMA mandates for continuous manufacturing create irreversible upgrade cycles. Acquisition targets should combine proprietary oscillatory rheometry IP with established service networks in Germany or Switzerland. Watch for inflection when notified bodies publish definitive inspection protocols for real-time release testing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Sensors | Captive supply of strain gauge components reduces exposure to Japanese foundry bottlenecks. |
| Performance-Based Equipment Leasing | Recurring revenue models align with Basel facility consolidation and reduced internal metrology staffing. |
| ISO 17025 Embedded Calibration Services | Compliance risk transfer appeals to mid-sized contract manufacturers facing tightened accreditation timelines. |
| Continuous Manufacturing Sensor Integration | In-line viscosity verification addresses FDA process analytical technology mandates for sterile injectables. |
| Joint Venture for China Local Assembly | NMPA alignment pressures favor technology transfer partnerships over direct import competition. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across pharmaceutical quality control laboratories, chemical manufacturing facilities, and food processing plants. Primary interviews captured procurement directors, calibration service managers, and regulatory affairs leads at sterile injectable manufacturers. Secondary validation drew from FDA guidance documents, EMA quality-by-design frameworks, ISO 17025 accreditation records, and customs trade data for precision instrument imports. Bottom-up and top-down triangulation reconciled instrument shipment volumes with end-user capacity expansion announcements.
Calibration against historical replacement cycles and regulatory compliance deadlines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include measurement principle, automation tier, end-use industry, and application workflow position. CAGRs were derived from elasticity-adjusted demand curves incorporating EMA inspection timeline acceleration and FDA process analytical technology adoption curves. Industry-specific forecast inputs captured biotechnology facility buildout in Massachusetts and polymer capacity expansion in Germany's chemical corridor.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian portable unit fabricators or MEMS sensor specialists would shift outcomes beyond modeled ranges. Cross-checking against notified body inspection queue data and pharmaceutical capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Liquid Analytical Instrument Market
Testing Equipment
Combustion Testing Equipment Market
Testing Equipment
Total Reflection X Ray Fluorescence (TXRF) Spectrometer Market
Testing Equipment
Low-Pressure Liquid Chromatography Market
Testing Equipment
Micro Carbon Residue Tester Market
Testing Equipment
Salt Spray Chamber Market
Testing Equipment
Sand Testing Equipments Market
Testing Equipment
Global Liquid Process Analyzer Market
Testing Equipment
Global Rheometer and Viscometer Market
Testing Equipment
Chemisorption Analyzer Market
Testing Equipment
Rubber Testing Equipment Market
Testing Equipment
Global Chromatography Instrumentation Market
Testing Equipment
Membrane Osmometer Market
Testing Equipment
Lactose Assay Kit Market
Testing Equipment
Grease Analyzer Market
Testing Equipment
Flash Point Apparatus Market