
 Flammability Test Chamber Market | 2026-2036
Flammability Test Chamber Market Size, Share, and Industry Trends Forecast 2026-2036
Flammability Test Chamber Market Foresight
Direct sales from manufacturers to certification agencies is reconfiguring as third-party testing laboratories consolidate procurement across multi-site networks. Thermo Fisher Scientific Inc. leverages its analytical instrumentation footprint to bundle flammability systems with broader materials characterization workflows. UL LLC sustains channel control through captive certification demand that locks in specification authority. Hochiki Corporation competes from its fire-detection heritage, extending sensor integration into chamber monitoring subsystems.
A flammability test chamber is an enclosed, instrumented apparatus designed to expose specimens to controlled ignition sources under standardized temperature, airflow, and flame-impingement conditions to quantify burn rate, self-extinguishment, and smoke-generation characteristics. Horizontal test chambers dominate volume for textile and building-material screening where large-format samples require uniform radiant exposure, while microenvironment chambers command premium pricing from pharmaceutical and electronics clients demanding precise oxygen-index determination in confined volumes. Conveyorized chambers represent the fastest-growing technology segment as automotive and aerospace manufacturers integrate inline flame testing into production quality loops.
FAA regulations govern aircraft interior material flammability, EASA enforces parallel certification standards across European aerospace supply chains, and OSHA workplace-safety directives mandate periodic validation of protective equipment using standardized flame protocols. These overlapping compliance frameworks create sustained replacement demand as test standards incrementally tighten ignition-energy and toxicity thresholds. Stakeholders must track harmonization gaps between regional certification regimes to anticipate specification divergence that fragments chamber design requirements.
Market Dynamics
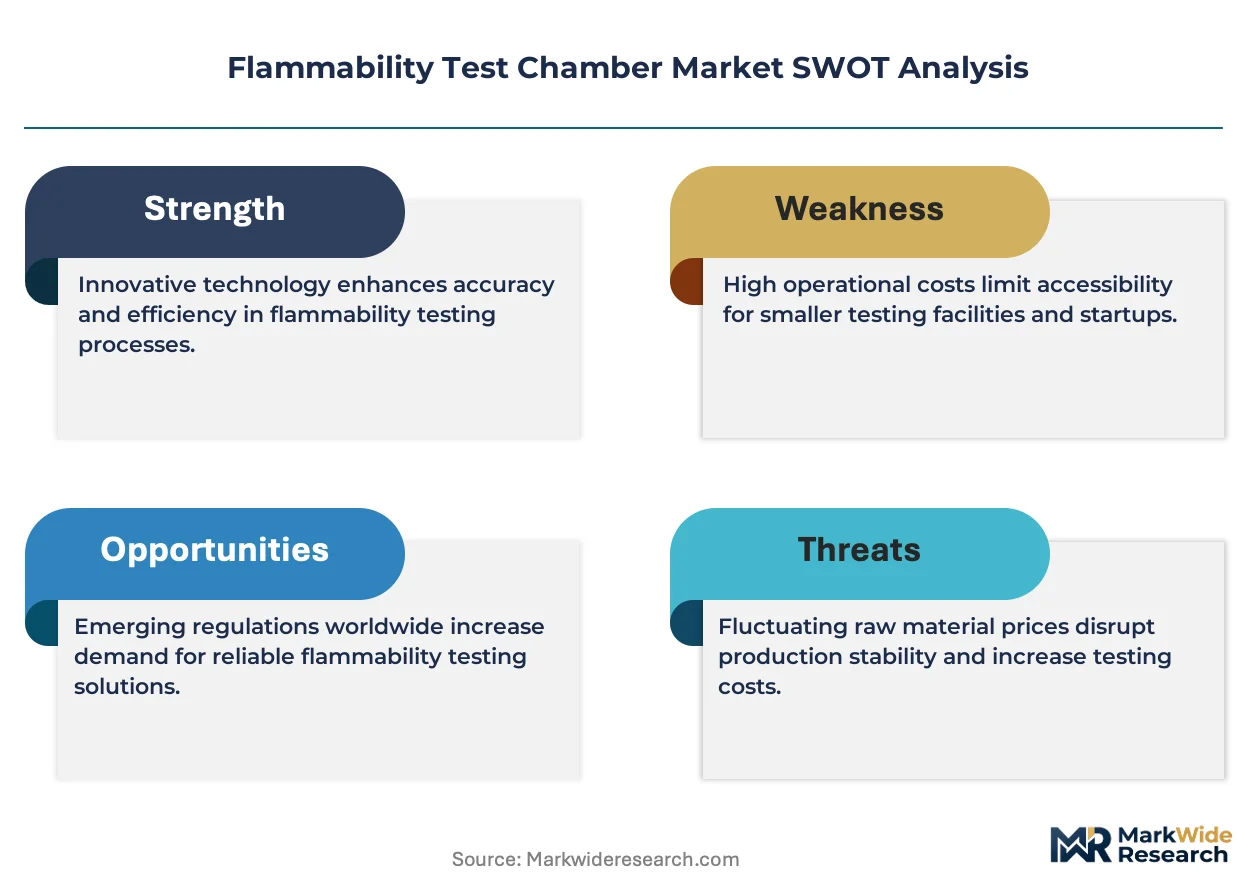
Stringent FAA and EASA flame-resistance mandates for aircraft cabin materials are compressing procurement cycles and forcing aerospace suppliers to upgrade testing infrastructure ahead of regulatory deadlines, creating a sustained replacement wave across North American and European manufacturing bases.
Growth Catalysts
- FAA 14 CFR Part 25.853:Mandated flame-resistance testing for aircraft interior materials drives aerospace manufacturers in the United States to expand vertical test chamber procurement.
- Building material screening protocols:Horizontal test chambers capture volume from textile and construction sectors requiring uniform radiant exposure for large-format samples.
- Automotive inline integration:Conveyorized chambers enable production-quality-loop flame testing as vehicle manufacturers embed validation directly into assembly lines.
Market Restraints
- Specialized sensor costs:Precision oxygen-index sensors and radiant heat flux calibration equipment inflate capital outlay for microenvironment chamber configurations.
- European supply concentration:EASA-aligned certification bodies and chamber component suppliers cluster in Germany and France, creating geographic dependency risk.
- Technical limitation in smoke toxicity:Existing chamber architectures struggle to simultaneously measure particulate density and gas-phase toxicity under dynamic combustion conditions.
Strategic Opportunities
- India industrial corridor expansion:BIS fire-safety standards for electrical equipment in Maharashtra and Gujarat industrial zones redirect capital toward automated testing infrastructure.
- Battery material validation:Lithium-ion cell housing and separator materials require novel flammability protocols as electric vehicle production scales.
- Third-party laboratory networks:Multi-site testing consolidation creates bundled procurement demand for standardized chamber fleets with centralized data management.
Industry Challenges
- Calibration technician scarcity:Specialized expertise in ASTM E662 and ISO 5659 smoke density calibration commands premium wages and extends deployment timelines.
- Legacy system integration:Existing laboratory information management systems require custom middleware to ingest real-time chamber telemetry from modern IoT-enabled units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flammability Test Chamber Market |
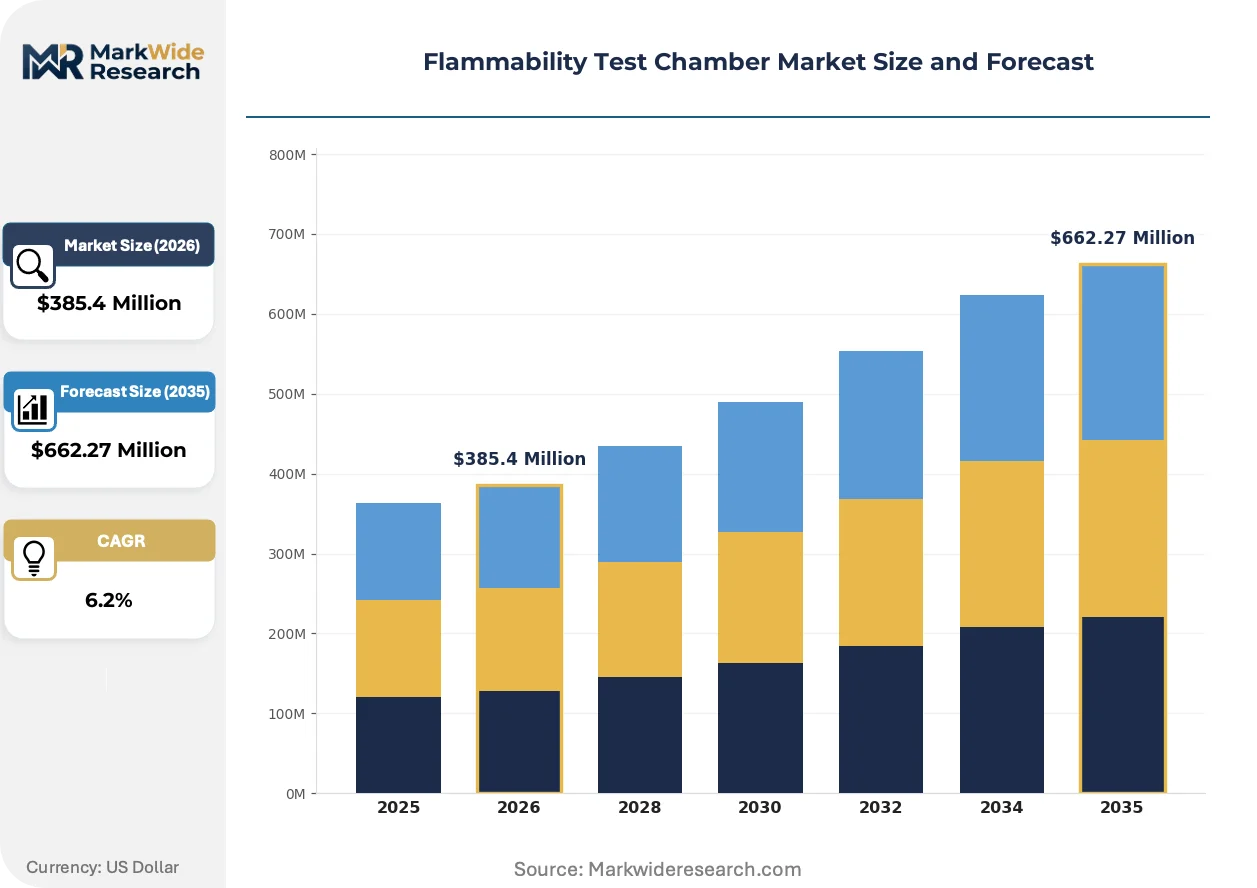
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Test Chambers, Vertical Test Chambers, Horizontal Vertical Combined Chambers, Microenvironment Chambers, Conveyorized Chambers Technology: Gas Flammability, Electric Arc, Thermal Radiation, Infrared, Chemical Flame Application: Electrical Equipment, Electronic Components, Building Materials, Textile Products, Aerospace Components End User: Research Laboratories, Quality Control Units, Manufacturing Plants, Certification Agencies, Material Testing Facilities |
| Companies Covered | Thermo Fisher Scientific Inc., Hochiki Corporation, AMETEK ATLAS, Aegis Scientific, Karg Industrietechnik, Wewon Environmental Chambers, Fire Testing Technology, UL LLC, Intertek Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flammability Test Chamber Market Shifts & Advancements
Testing infrastructure is migrating toward inline automation and predictive analytics, compressing the gap between material validation and production release while regulatory bodies tighten harmonization requirements across aerospace and electronics supply chains.
Conveyorized flame testing systems are migrating from standalone laboratory configurations to embedded production-line nodes. Automotive tier-1 suppliers in Stuttgart and Detroit deploy these units at mold-injection and textile lamination stations. This migration from offline sampling to 100% inline validation eliminates batch quarantine delays and reduces warranty exposure from material non-conformance.
REACH Annex XVII restrictions on flame retardant substances are forcing reformulation of plastics and foams used in consumer electronics housings. Chamber operators must validate new halogen-free chemistries against legacy brominated benchmarks. Electronics contract manufacturers in Dongguan and Penang expand testing capacity to cover expanded oxygen-index and glow-wire protocol matrices.
Certification-driven procurement now favors chambers with pre-loaded ASTM, ISO, and UL test method libraries over custom-programmable units. Third-party laboratories in the United States and Germany consolidate vendor relationships to reduce protocol validation overhead. This preference shift compresses sales cycles for standardized platforms while marginalizing bespoke chamber builders lacking method-library depth.
Flammability Test Chamber Market Segmentation
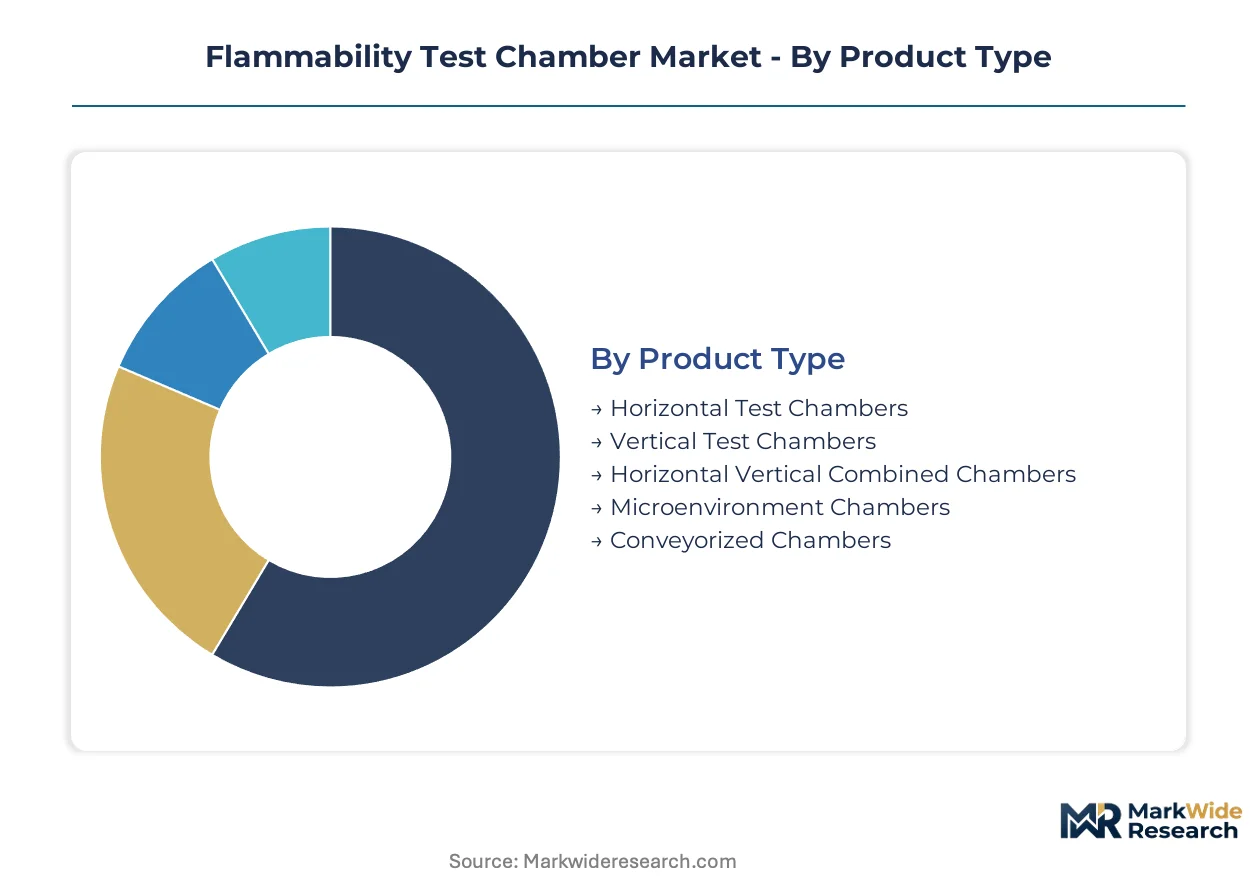
Flammability test chamber procurement patterns diverge sharply across product architectures and end-use requirements. Aerospace manufacturers prioritize vertical configurations for FAA compliance, while automotive integrators drive conveyorized adoption for inline quality loops.
Product Type:
Mature horizontal formats anchor textile and construction screening volumes, while emerging conveyorized architectures capture the steepest technology investment curves.
- Horizontal Test Chambers:These units expose large-format specimens to uniform radiant heat flux across planar surfaces. Building material laboratories in Germany and textile certification centers in the United States deploy these for ASTM E84 and ISO 9239 protocols. Horizontal configurations retain cost advantages for high-throughput screening where sample orientation remains fixed.
- Vertical Test Chambers:Upright flame impingement geometries satisfy FAA 14 CFR Part 25.853 and EASA CS-25 cabin material mandates. Aerospace suppliers in Seattle and Toulouse expand procurement of these units to validate seat covers, wall panels, and insulation blankets against 12-second vertical burn criteria.
- Horizontal Vertical Combined Chambers:Dual-orientation systems accommodate laboratories serving multiple industry verticals without dedicated floor space for separate units.
- Microenvironment Chambers:Confined-volume precision systems enable oxygen-index determination for pharmaceutical packaging and electronics housings.
- Conveyorized Chambers:Inline flame testing modules embed directly into automotive and aerospace production lines for 100% validation.
Horizontal test chambers retain volume leadership; conveyorized chambers hold the steepest expansion curve.
Technology:
Cost tier differentiation separates precision thermal radiation systems from commodity gas flame configurations, with electric arc methods occupying a narrow specialty niche.
- Gas Flammability:Propane and methane pilot flame systems dominate standard compliance testing for textiles and building materials. Certification agencies in India and Brazil specify these for BIS and ABNT protocol execution due to operational simplicity and lower calibration overhead.
- Thermal Radiation:Controlled radiant heat panels replicate smoldering ignition scenarios for upholstered furniture and mattress testing. Laboratories in the United Kingdom and California deploy these for BS 5852 and TB 117 compliance where radiant pre-heating precedes direct flame exposure.
- Electric Arc:High-energy electrical discharge sources simulate fault-condition ignition for wire insulation and circuit breaker housings.
- Infrared:Tungsten-halogen and ceramic emitter arrays provide rapid thermal ramp rates for accelerated aging studies.
- Chemical Flame:Specialized reactant-fed combustion sources enable exotic atmosphere testing for space and defense applications.
Gas flammability systems capture the broadest installed base; thermal radiation platforms command the highest average selling prices.
Application:
Customer type concentration varies by material class, with aerospace and electronics applications demanding the most intensive certification documentation.
- Electrical Equipment:Switchgear, cable assemblies, and junction boxes require glow-wire and needle-flame testing under IEC 60695 series standards. Industrial clusters in Maharashtra and Guangdong expand testing capacity as BIS and GB standards tighten fire-safety requirements for distribution infrastructure.
- Aerospace Components:Cabin interior materials face the most stringent flame-resistance mandates globally. Suppliers to Boeing, Airbus, and COMAC programs maintain dedicated vertical chamber fleets for 12-second and 60-second burn rate validation with attendant smoke density measurement.
- Electronic Components:Printed circuit boards and connector housings require small-scale flammability screening under UL 94 protocols.
- Building Materials:Insulation, roofing membranes, and facade systems undergo large-scale reaction-to-fire classification.
- Textile Products:Upholstery, drapery, and protective garments face regional variations in cigarette and match ignition testing.
Building materials generate the highest unit volumes; aerospace components sustain the most rigorous specification requirements.
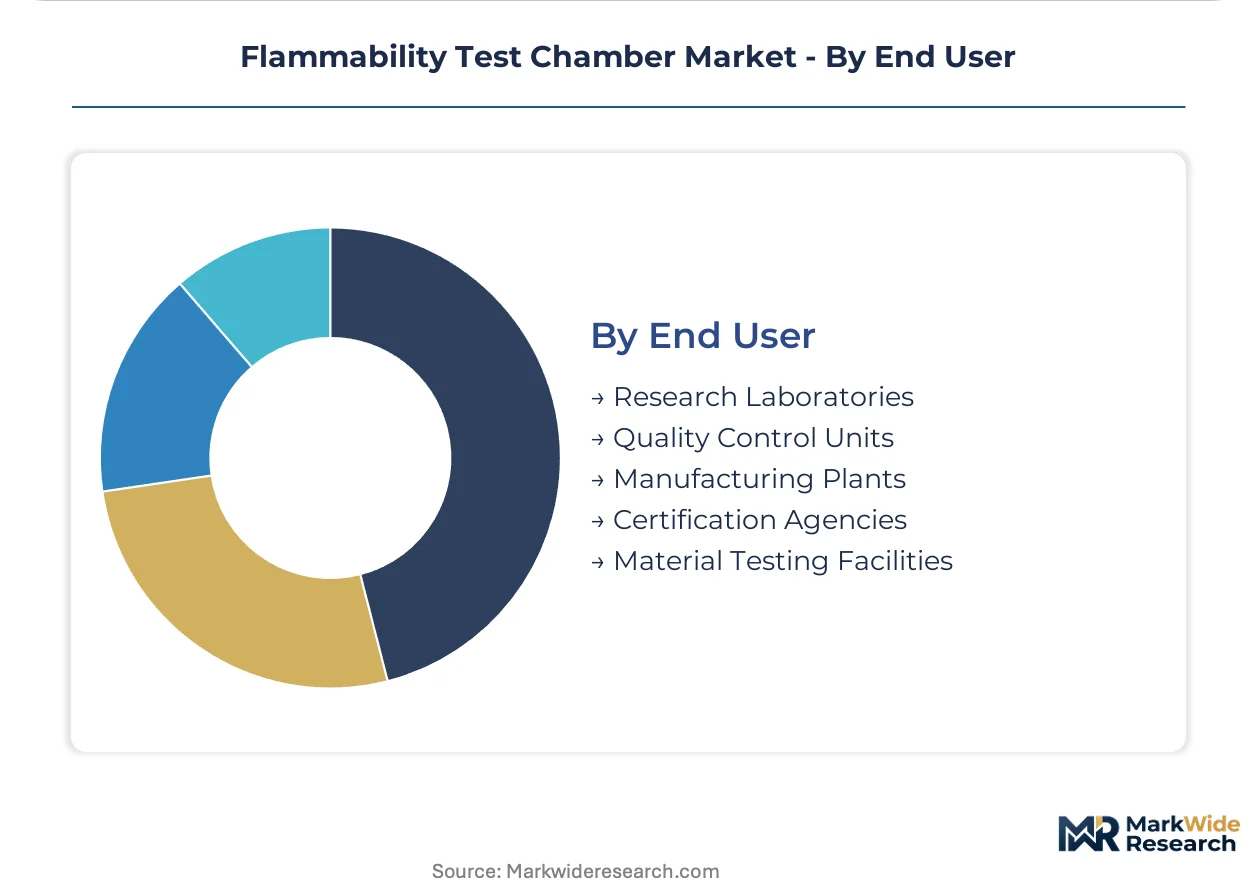
End User:
Procurement authority is consolidating toward third-party laboratory networks with multi-site standardization requirements.
- Certification Agencies:UL, Intertek, and SGS operate captive chamber fleets with pre-validated ASTM, ISO, and EN method libraries. These organizations specify standardized platforms to minimize inter-site protocol variance and accelerate client turnaround times.
- Manufacturing Plants:Automotive and electronics OEMs deploy inline conveyorized systems at mold-injection and lamination stations. Tier-1 suppliers in Stuttgart and Detroit embed flame testing directly into production quality loops, eliminating batch quarantine delays.
- Research Laboratories:University and government facilities pursue novel flammability phenomena beyond standardized protocols.
- Quality Control Units:Incoming material inspection departments at component suppliers perform spot-check validation.
- Material Testing Facilities:Independent commercial laboratories serve regional construction and textile sectors.
Certification agencies dominate specification authority; manufacturing plants drive the fastest capacity expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA mandates in the United States and EASA flame-resistance directives in Germany compress procurement cycles for aerospace suppliers. BIS fire-safety standards across Indian industrial corridors redirect capital toward automated testing infrastructure.
United States
Aerospace manufacturers in Seattle and Wichita expand vertical test chamber fleets to meet FAA 14 CFR Part 25.853 mandates for cabin materials. The 12-second vertical burn criteria for seat covers and insulation blankets sustain replacement demand ahead of regulatory deadlines. Boeing suppliers in the Pacific Northwest and Gulf Coast aerospace clusters drive concentrated procurement.
Germany
EASA CS-25 certification requirements enforce parallel flame-resistance standards across European aerospace supply chains. Airbus suppliers in Hamburg and Toulouse-aligned tier-1 networks in Bavaria upgrade testing infrastructure. Stuttgart automotive tier-1 suppliers deploy conveyorized chambers at mold-injection stations for inline quality validation.
China
GB standards for electrical equipment fire safety tighten across Guangdong and Jiangsu industrial zones. Electronics contract manufacturers in Dongguan and Shenzhen expand oxygen-index and glow-wire testing capacity. The Pearl River Delta concentration of PCB and connector housing production sustains chamber demand.
India
BIS fire-safety standards for switchgear and cable assemblies redirect capital toward automated testing infrastructure in Maharashtra and Gujarat. Industrial clusters in Pune and Ahmedabad expand IEC 60695 series compliance capacity. Electrical equipment manufacturers face compressed validation timelines under tightened distribution infrastructure mandates.
Japan
METI industrial safety directives and JIS standards govern protective equipment and textile flammability validation. Automotive suppliers in Aichi Prefecture and electronics manufacturers in Kanagawa maintain captive testing fleets. Precision oxygen-index determination for pharmaceutical packaging sustains microenvironment chamber demand.
Flammability Test Chamber Market Competitive Landscape
On the supply side, the industry is consolidating around multi-product analytical instrumentation platforms and captive certification networks. Thermo Fisher Scientific bundles flammability systems with broader materials characterization workflows. UL LLC sustains channel control through specification authority locked to certification demand. Strategic archetypes include diversified laboratory conglomerates, fire-safety heritage specialists, and third-party testing networks. Dominant competitive moves encompass portfolio bundling and multi-site standardization contracts.
Within the diversified instrumentation tier, Thermo Fisher Scientific Inc. represents the analytical platform archetype, leveraging cross-product integration. Hochiki Corporation exemplifies the fire-detection heritage extension model. UL LLC anchors the captive certification channel, where specification authority drives procurement lock-in. These three occupy positions across distinct competitive vectors rather than direct product rivalry.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Hochiki Corporation |
| AMETEK ATLAS |
| Aegis Scientific |
| Karg Industrietechnik |
| Wewon Environmental Chambers |
| Fire Testing Technology |
| UL LLC |
| Intertek Group plc |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp freight corridors govern landed cost differentials for precision sensor modules and radiant heat calibration equipment, compressing margins for European chamber assemblers while amplifying price spreads between ISO-certified premium units and uncertified economy alternatives in Asian industrial clusters.
Pricing Analysis
Certification level creates the primary spread across the product hierarchy. Three-tier pricing structure across premium, standard, and economy levels reflects UL/CE mark validation depth, with aerospace-grade vertical chambers commanding substantial premiums over textile-screening horizontal units. Cost compression in the economy tier intensifies because Indian and Chinese domestic manufacturers scale gas-flame commodity production. Certification agencies exhibit the lowest price sensitivity due to captive specification authority, while independent material testing facilities in emerging industrial corridors face acute budget constraints.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk planning for chamber OEMs. Component sourcing concentrates in Germany, Japan, and the United States for precision oxygen-index sensors, radiant heat flux panels, and IoT telemetry modules. Assembly draws from stainless steel fabrication clusters in China and India for chamber housings and conveyor frames. Single-source vulnerability persists for ASTM E662 smoke density calibration reference materials. Distribution runs through captive certification networks and third-party laboratory procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Conveyorized inline testing represents an early-cycle expansion story, with automotive and aerospace manufacturers embedding validation directly into production quality loops rather than offline sampling protocols.
For Market Incumbents: Build certification-library moats by pre-loading ASTM, ISO, and UL test method libraries into standardized chamber platforms. Consolidate multi-site standardization contracts with SGS and Intertek to lock in specification authority. Counter emerging entrant pressure from Chinese gas-flame commodity producers by bundling predictive analytics and IoT telemetry as value-added services.
For New Entrants and Emerging Players: Mid-market electrical equipment manufacturers in Maharashtra and Gujarat industrial corridors represent the most penetrable entry point, as BIS fire-safety mandates compress validation timelines without incumbent certification agency capture. Battery material validation for lithium-ion cell housings offers a second white-space avenue as EV production scales. Pursue direct OEM relationships rather than certification agency channel dependence.
For Investors and Strategic Acquirers: Fire-detection heritage specialists with sensor integration capabilities into chamber monitoring subsystems offer the most attractive acquisition profile for platform consolidation plays. Long-term viability rests on regulatory harmonization momentum across FAA, EASA, and emerging APAC certification regimes. Monitor REACH Annex XVII flame-retardant restriction enforcement as the inflection signal for chamber protocol reformulation demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Library Pre-Loading | UL and Intertek specify standardized platforms to minimize inter-site protocol variance. |
| Inline Conveyorized Deployment | Stuttgart and Detroit tier-1 suppliers embed flame testing at mold-injection stations. |
| IoT Telemetry Integration | Modern chamber units require custom middleware for legacy LIMS ingestion. |
| Battery Material Protocol Development | Lithium-ion separator validation demands novel oxygen-index and glow-wire matrices. |
| Multi-Site Laboratory Consolidation | Third-party networks standardize chamber fleets with centralized data management. |
Research Methodology
A spread of perspectives from chamber OEM technical directors, third-party laboratory procurement managers, aerospace supplier quality engineers, and certification agency specification leads converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FAA regulatory filings, EASA certification bulletins, ASTM and ISO standards documentation, and customs trade data for precision sensor imports. Bottom-up unit economics triangulated against top-down aerospace and automotive capital expenditure patterns.
Demand-supply balance dynamics anchored the analytical framework across the analysis window. Segmentation modeling incorporated product architecture, ignition source technology, application material class, and end-user procurement authority. CAGRs derived from regression against historical aerospace certification cycles and electrical equipment regulatory tightening trajectories. Forecast inputs included BIS enforcement timelines in Indian industrial corridors and REACH Annex XVII restriction implementation.
Practitioners should monitor FAA and EASA harmonization gaps, REACH flame-retardant substance restrictions, and battery material protocol standardization for early signals of specification divergence. Forecasts reflect assumptions about regulatory enforcement continuity and industrial cluster expansion momentum. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Benchtop Density Meter for Solids Market
Testing Equipment
Global Liquid Chromatography Systems Market
Testing Equipment
Chemical Analyzer Market
Testing Equipment
Glass Testing Instruments Market
Testing Equipment
Global Chromatography Columns Market
Testing Equipment
In-Line UV-Vis Spectroscopy Market
Testing Equipment
FTIR Fuel Analyzer Market
Testing Equipment
Global Dynamic Mechanical Analyzers Market
Testing Equipment
Wood Moisture Tester Market
Testing Equipment
Laboratory Accessories Market
Testing Equipment
HPLC Market
Testing Equipment
Steel Testing Equipment Market
Testing Equipment
Chemical Reaction Monitoring Equipment Market
Testing Equipment
PFAS Ultra-Trace Water Analysis Test Instruments Market
Testing Equipment
Particle Size Analysis Market
Testing Equipment
Low-Pressure Liquid Chromatography Market