
 Benchtop Density Meter for Solids Market | 2026-2036
Benchtop Density Meter for Solids Market Size, Share, and Industry Trends Forecast 2026-2036
Benchtop Density Meter for Solids Market Insights
Equipment leasing and managed service contracts is tilting competitive dynamics toward vendors with balance-sheet capacity to carry instrument fleets. Anton Paar leverages its Austrian manufacturing base to sustain premium positioning in oscillating U-tube systems. Mettler Toledo anchors North American demand through dense service networks and calibration protocols. Thermo Fisher Scientific competes by bundling density meters with broader analytical workflows.
A benchtop density meter for solids measures the mass per unit volume of solid samples using displacement or radiation-based methods, typically achieving precision to 0.0001 g/cm³ for quality control and research applications. Hydrostatic weighing dominates pharmaceutical testing where USP and EP compliance mandates documented density values for tablet porosity and active ingredient uniformity. Oscillating U-tube technology leads materials science applications due to speed and minimal sample preparation, while nuclear density methods retain share in mining operations where large particulate or ore samples resist fluid immersion. Digital calibration capabilities now differentiate mid-range systems as laboratories consolidate instrument platforms.
FDA 21 CFR Part 11 and EU MDR documentation requirements shape validation protocols for density meters deployed in pharmaceutical quality assurance labs. ISO 17025 accreditation standards force contract laboratories to demonstrate metrological traceability, directly driving replacement cycles for non-compliant legacy equipment. ISO, EMA, and FDA collectively determine which instrument architectures gain market access across regulated industries. Stakeholders must monitor evolving data-integrity enforcement patterns to anticipate procurement timing and specification shifts.
Market Dynamics
Equipment leasing and managed service contracts are consolidating procurement power among vendors capable of carrying instrument fleets on their balance sheets, compressing traditional capital expenditure cycles in pharmaceutical and materials science laboratories.
Growth Catalysts
- EU MDR documentation mandates:Medical device manufacturers must validate material density for biocompatibility assessments, forcing laboratory upgrades to compliant instrumentation.
- Oscillating U-tube speed advantages:Materials science R&D groups prioritize rapid throughput over absolute precision, favoring automated sample handling and reduced preparation time.
- Baden-Württemberg precision cluster:German instrument manufacturing concentration accelerates regional supply chain responsiveness and technical service density for European buyers.
Market Restraints
- Helium supply volatility:Oscillating U-tube systems depend on consistent gas supply for temperature control, exposing operators to price shocks from Qatar and US production disruptions.
- FDA 21 CFR Part 11 validation costs:Pharmaceutical laboratories face six-figure documentation and qualification expenses that extend replacement cycles for functional legacy equipment.
- Gamma radiation licensing:Nuclear density methods require specialized handling protocols and regulatory approvals that limit deployment flexibility outside mining operations.
Strategic Opportunities
- Contract research organization expansion:India and South Korea are building GLP-certified testing capacity to serve generic pharmaceutical exporters, creating instrument demand from new accreditation drives.
- Digital calibration platform convergence:Cloud-connected density meters integrating with laboratory information management systems enable remote diagnostics and predictive maintenance revenue streams.
- Battery materials qualification:Solid-state electrolyte and cathode active material developers require precise density data for porosity optimization, opening technical sales channels outside traditional pharmaceutical buyers.
Industry Challenges
- Metrological traceability staffing:ISO 17025 accreditation requires dedicated calibration technicians that smaller contract laboratories struggle to recruit and retain.
- Multi-instrument workflow integration:Density data must flow seamlessly into particle size distribution and surface area analyzers, demanding complex software validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benchtop Density Meter for Solids Market |
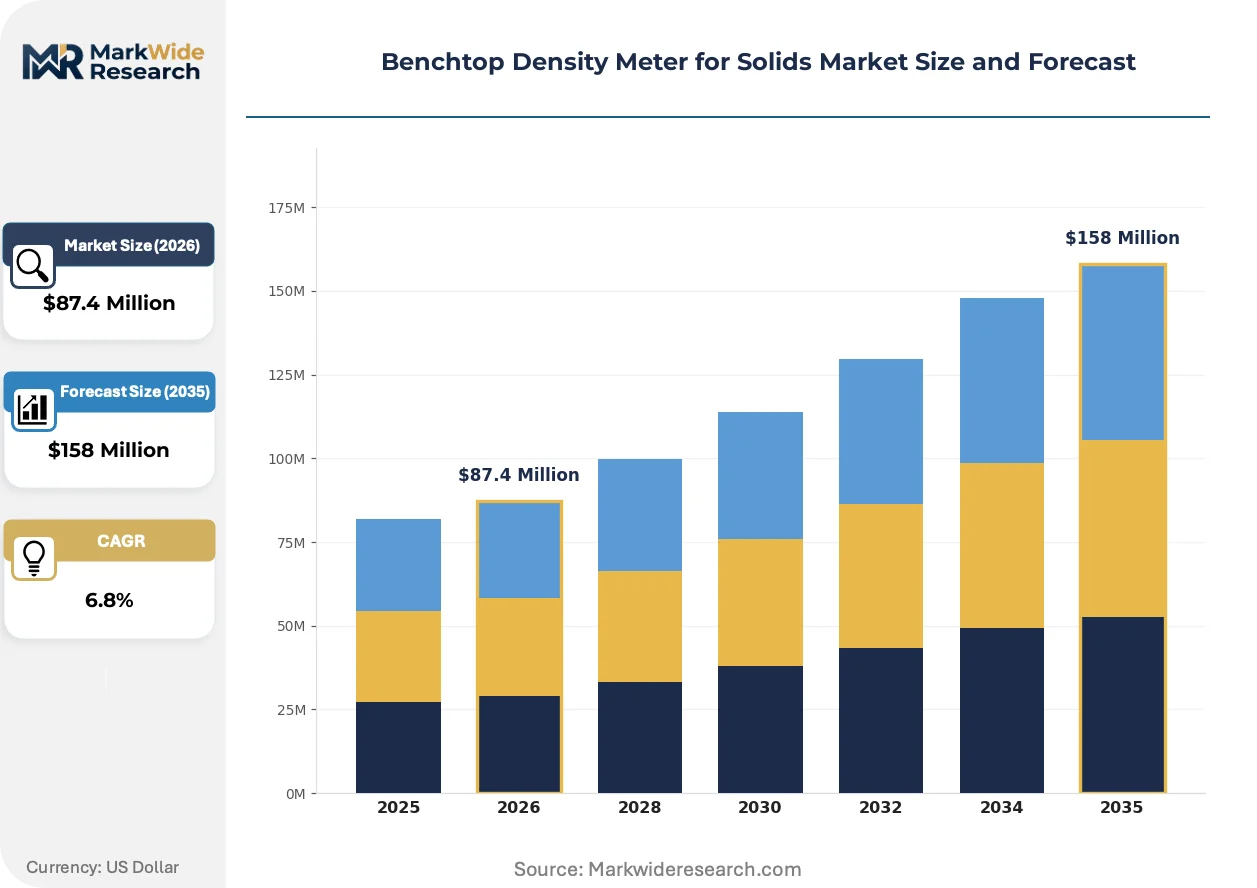
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
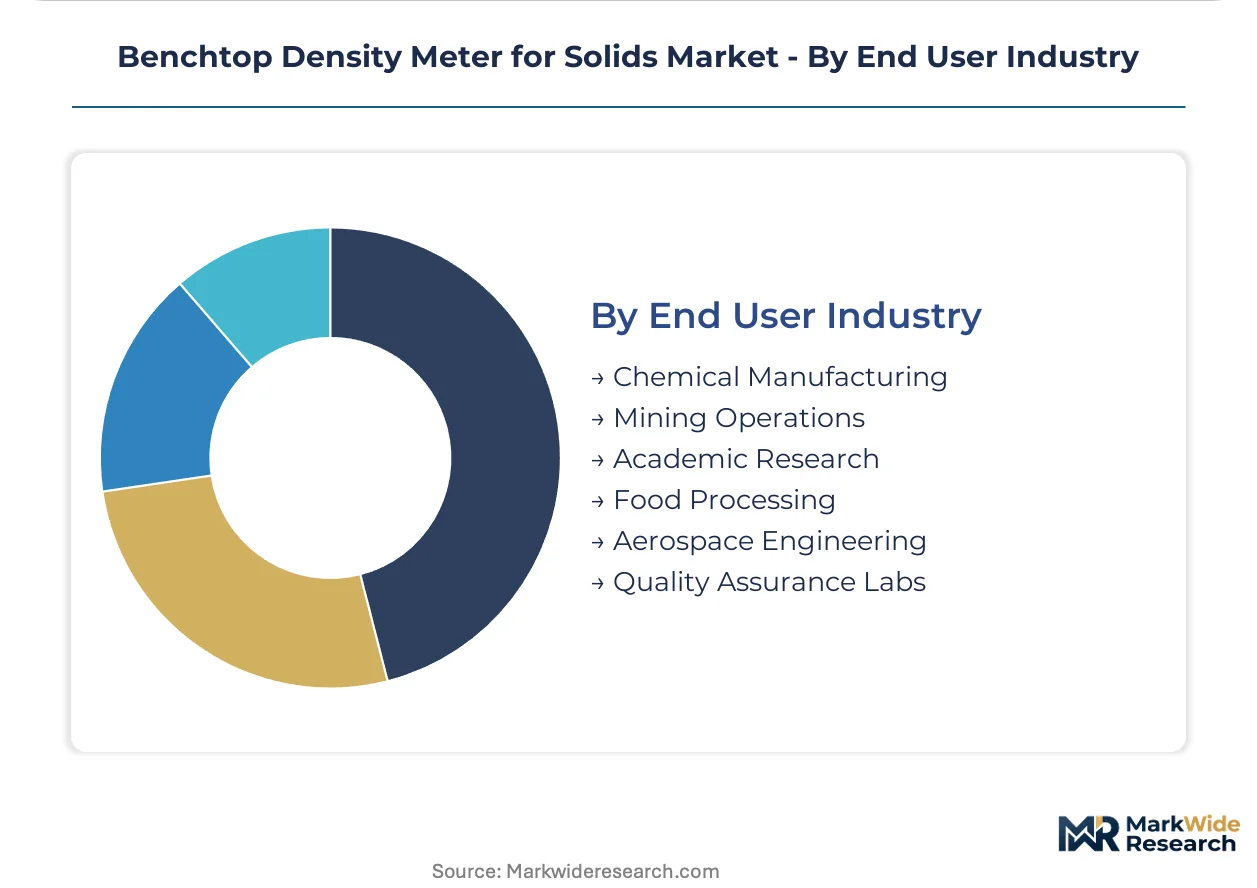
| Segmentation | Product Type: Ultrasonic Density Meter, Oscillating U-tube, Vibrating Element, Nuclear, Electromagnetic, Optical Technology: Hydrostatic Weighing, X-ray Absorption, Gamma-ray, Digital Calibration, Piezoelectric, Magnetic Resonance Application: Pharmaceutical Testing, Geological Analysis, Materials Science, Food Quality Control, Polymer Characterization, Metal Alloy Inspection End User Industry: Chemical Manufacturing, Mining Operations, Academic Research, Food Processing, Aerospace Engineering, Quality Assurance Labs |
| Companies Covered | Anton Paar, Mettler Toledo, Thermo Fisher Scientific, Emerson Electric, Endress+Hauser, ABB, Rudolph Research Analytical, Koehler Instrument Company, Bopp & Reuther Messtechnik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benchtop Density Meter for Solids Market Trends and Innovations
Digitalization of calibration workflows and convergence with broader analytical platforms are redefining how laboratories justify capital allocation for density measurement infrastructure.
Automated sample handling systems for oscillating U-tube density meters are hybridizing with robotic laboratory workflows, enabling unattended overnight operation in high-throughput pharmaceutical quality control. Large generic manufacturers in India and Eastern Europe are deploying these integrated platforms to compress batch release timelines. The technology is hybridizing capital equipment purchasing decisions, favoring vendors with software integration capabilities over pure hardware specialists.
EMA's strengthened data integrity guidance and FDA's continued 21 CFR Part 11 enforcement are mandating audit trails for all analytical measurements in GMP environments. Pharmaceutical contract laboratories must now demonstrate electronic record integrity from instrument raw data through final reporting. European quality assurance departments are responding by specifying density meters with embedded compliance software rather than retrofitting legacy units.
Service unbundling is fragmenting traditional instrument vendor relationships, with third-party calibration providers and independent service organizations capturing maintenance revenue previously retained by manufacturers. Mid-sized pharmaceutical laboratories in Germany and Switzerland are separating hardware procurement from multi-year service agreements to optimize total cost of ownership. This pattern is most visible in mature European markets where instrument density supports competitive aftermarket services.
Benchtop Density Meter for Solids Market Segmentation
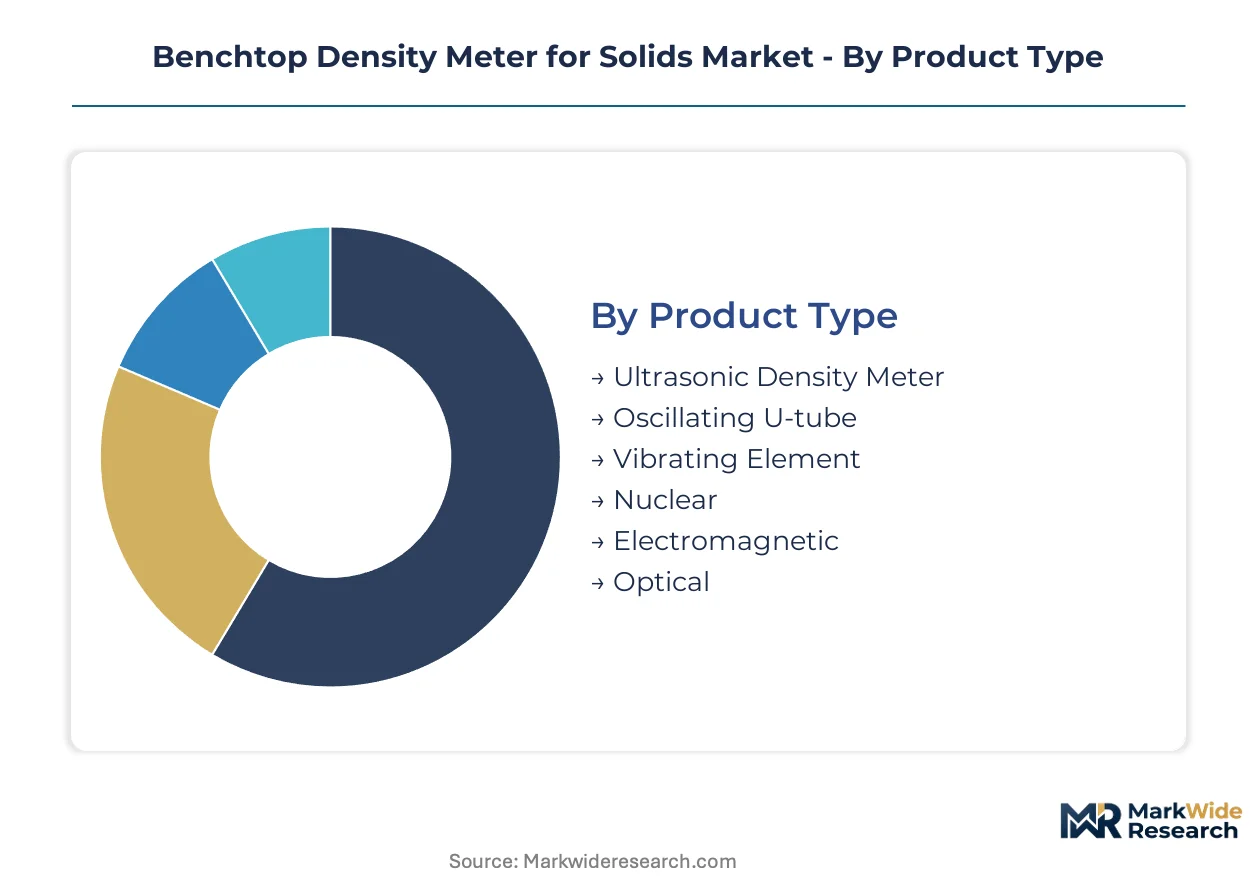
Segmentation in the benchtop density meter market reveals how service intensity, calibration complexity, and regulatory compliance requirements vary sharply across instrument architectures. Procurement patterns diverge significantly between high-throughput pharmaceutical environments and resource-sector deployments with limited technical staffing.
Product Type:
After-sales service intensity varies dramatically across product architectures, with oscillating U-tube systems demanding specialized helium-based temperature control maintenance while nuclear units require radiation safety certification renewals.
- Oscillating U-tube:Measures density through frequency changes in a gas-filled vibrating tube, achieving precision to 0.0001 g/cm³ with minimal sample preparation. Pharmaceutical quality control laboratories in Germany and Switzerland concentrate procurement here, driven by USP and EP compliance mandates for tablet porosity documentation. Service contracts typically represent 25-35% of lifetime cost.
- Nuclear:Employs gamma radiation attenuation through solid samples, eliminating fluid immersion requirements entirely. Mining operations in Australia and Canada favor this architecture for ore and large particulate analysis where hydrostatic methods fail. Regulatory licensing burdens limit geographic deployment flexibility outside established radiation-handling facilities.
- Ultrasonic Density Meter:Calculates density from acoustic impedance measurements in slurry or semi-solid preparations.
- Vibrating Element:Uses mechanical resonance frequency shifts for continuous process monitoring applications.
- Electromagnetic:Applies inductive principles for conductive material characterization in metal alloy workflows.
- Optical:Leverages refractive index correlation for transparent or translucent polymer samples.
By volume, oscillating U-tube leads. By growth pace, nuclear is ahead.
Technology:
Cost tier stratification separates capital-intensive radiation-based systems from accessible digital calibration platforms, with mid-range laboratories gravitating toward software-differentiated architectures.
- Digital Calibration:Embeds automated reference standard checking and cloud-connected drift monitoring, reducing technician labor by 60% versus manual protocols. Contract research organizations in India and South Korea prioritize this capability to meet ISO 17025 accreditation with limited metrology staffing. FDA 21 CFR Part 11 embedded compliance accelerates replacement cycles in pharmaceutical environments.
- Hydrostatic Weighing:Archimedes-based displacement measurement remains the compendial standard for USP and EP density determinations. European pharmaceutical manufacturers retain this technology for regulatory submission batches despite slower throughput, as authorities require documented traceability to fundamental physical principles.
- X-ray Absorption:Penetrates dense metal alloys and geological specimens without destructive sampling.
- Gamma-ray:Requires specialized handling protocols and national regulator licensing for source possession.
- Piezoelectric:Converts mechanical stress signals into density readings for ceramic and composite materials.
- Magnetic Resonance:Exploits nuclear spin relaxation properties for hydrogen-containing polymer characterization.
By installed base, hydrostatic weighing dominates. By expansion trajectory, digital calibration is climbing the fastest.
Application:
Application focus determines whether laboratories prioritize absolute precision, regulatory documentation depth, or sample throughput velocity in procurement specifications.
- Pharmaceutical Testing:Encompasses tablet porosity, active ingredient uniformity, and excipient density verification for batch release. US FDA and EMA validation requirements mandate electronic data integrity and audit trail capabilities, forcing specification of 21 CFR Part 11-compliant architectures. German quality assurance departments specify embedded compliance software rather than retrofitting legacy units.
- Materials Science:Spans battery electrolyte characterization, ceramic sintering analysis, and composite density mapping. Solid-state battery developers in Japan and South Korea require precise porosity data for cathode active materials, opening technical sales channels outside traditional pharmaceutical buyers. Oscillating U-tube speed advantages dominate R&D procurement decisions.
- Geological Analysis:Core sample and mineral density determination for resource estimation.
- Food Quality Control:Solid fat content and ingredient uniformity verification for processed products.
- Polymer Characterization:Crystallinity assessment and additive distribution analysis in plastic manufacturing.
- Metal Alloy Inspection:Porosity detection and inclusion mapping for aerospace and automotive castings.
Pharmaceutical testing commands premium pricing. Materials science is gaining share fastest.
End User Industry:
Customer type segmentation reveals divergent procurement authority structures, with centralized quality assurance labs favoring multi-instrument vendor relationships while academic researchers prioritize capital cost minimization.
- Quality Assurance Labs:Centralized testing facilities serving pharmaceutical, food, and chemical manufacturers with ISO 17025 accreditation requirements. These buyers separate hardware procurement from service agreements to optimize total cost of ownership, fragmenting traditional vendor relationships. Third-party calibration providers capture maintenance revenue previously retained by manufacturers in Germany and Switzerland.
- Mining Operations:Resource-sector deployments requiring ruggedized instruments for field laboratory or on-site processing facility use. Nuclear and electromagnetic architectures dominate due to large sample sizes and particulate characteristics resisting fluid immersion. Gamma radiation licensing requirements constrain vendor selection to established radiation safety equipment suppliers.
- Chemical Manufacturing:Process control and raw material verification for specialty and commodity chemical producers.
- Academic Research:University materials science and chemistry departments with limited capital budgets and student-operator labor pools.
- Food Processing:Ingredient characterization and quality control for packaged goods manufacturers.
- Aerospace Engineering:Titanium alloy and composite qualification for airframe and engine component certification.
Quality assurance labs drive replacement cycles. Mining operations show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical quality assurance laboratories concentrate instrument procurement in Germany, the United States, and Switzerland, while materials science R&D expansion accelerates demand across Japan and South Korea. Mining operations in Australia and Canada sustain specialized nuclear density applications. Contract research organization growth in India reshapes regional competitive dynamics.
Germany
Baden-Württemberg precision instrument manufacturing clusters anchor European supply chain responsiveness for oscillating U-tube systems. EU MDR documentation mandates force medical device manufacturers to validate material density for biocompatibility assessments. Stuttgart and Karlsruhe host dense technical service networks supporting pharmaceutical laboratories across Central Europe.
United States
FDA 21 CFR Part 11 validation requirements drive six-figure documentation expenses that extend replacement cycles for legacy equipment in pharmaceutical quality control labs. Generic pharmaceutical manufacturers deploy automated sample handling systems to compress batch release timelines. Boston and San Diego biotech corridors specify embedded compliance software rather than retrofitting older units.
Switzerland
Swissmedic oversight of pharmaceutical manufacturing quality creates stringent metrological traceability demands for contract laboratories. ISO 17025 accreditation standards force dedicated calibration technician staffing that smaller labs struggle to retain. Basel and Zurich quality assurance departments separate hardware procurement from multi-year service agreements to optimize total cost of ownership.
Japan
Solid-state battery developers in the Kanto and Kansai regions require precise porosity data for cathode active materials, opening technical sales channels outside traditional pharmaceutical buyers. METI industrial policy supports advanced materials characterization infrastructure. Osaka materials science R&D groups prioritize rapid throughput over absolute precision in procurement decisions.
India
CDSCO regulatory alignment with ICH standards drives GLP-certified testing capacity expansion to serve generic pharmaceutical exporters. Mumbai and Hyderabad contract research organizations prioritize digital calibration platforms to meet ISO 17025 accreditation with limited metrology staffing. Third-party calibration providers capture maintenance revenue previously retained by manufacturers.
Benchtop Density Meter for Solids Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around vendors with balance-sheet capacity to carry instrument fleets. Equipment leasing and managed service contracts compress traditional capital expenditure cycles in pharmaceutical and materials science laboratories. Three archetypes dominate: Austrian and Swiss precision instrument specialists, North American analytical platform bundlers, and German industrial automation conglomerates. Strategic moves center on software integration capabilities and geographic service network density.
Within the premium precision tier, Anton Paar and Mettler Toledo exemplify divergent geographic anchoring strategies—Austrian manufacturing sustaining oscillating U-tube positioning versus North American service density. Thermo Fisher Scientific occupies the platform-bundling position, competing through analytical workflow integration rather than standalone hardware specialization. These three represent how vendor archetypes map to distinct procurement authority structures in quality assurance laboratories.
| Leading Market Players |
|---|
| Anton Paar |
| Mettler Toledo |
| Thermo Fisher Scientific |
| Emerson Electric |
| Endress+Hauser |
| ABB |
| Rudolph Research Analytical |
| Koehler Instrument Company |
| Bopp & Reuther Messtechnik |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Antwerp freight corridors carry precision instrument components from Baden-Württemberg manufacturing clusters to pharmaceutical laboratories across Northwestern Europe, with container cost volatility feeding directly into oscillating U-tube system pricing and compressing margins for mid-range digital calibration platforms.
Pricing Analysis
Cost-plus contracts with helium price indexation dominate service agreements for oscillating U-tube systems, embedding fuel and cryogenic gas costs into multi-year maintenance bundles. Three-tier pricing structure across premium, standard, and economy levels separates Anton Paar's Austrian-manufactured precision systems from Mettler Toledo's North American service-anchored offerings and Asian entrants competing on capital cost. Pricing pressure stems from third-party calibration providers unbundling service revenue previously captured by manufacturers. Academic research laboratories exhibit highest price sensitivity; FDA-validated pharmaceutical quality assurance labs show lowest.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk planning for electromagnetic sensor components and piezoelectric elements. Manufacturing concentrates in Germany, Austria, and Switzerland for precision oscillating U-tube assemblies; China and South Korea supply digital calibration chipsets and cloud connectivity modules. Raw material dependencies include high-purity quartz tubing, helium for temperature control systems, and specialized radiation shielding alloys. Single-source vulnerability persists for gamma radiation sources used in nuclear density architectures. Distribution runs through authorized dealer networks serving pharmaceutical clusters, with direct OEM relationships dominating mining and materials science accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state battery materials qualification represents a high-growth disruption, with METI industrial policy in Japan and South Korean cathode active material investments creating technical sales channels outside traditional pharmaceutical density meter procurement.
For Market Incumbents: Harden service network density in Baden-Württemberg and Switzerland to defend against third-party calibration fragmentation. Deepen backward integration into helium recovery systems to offset Qatar supply volatility. Prioritize FDA 21 CFR Part 11 embedded software certification as a defensive moat against Asian digital calibration entrants. For New Entrants and Emerging Players: Establish a beachhead in Indian contract research organizations building GLP-certified capacity for generic pharmaceutical exporters. Target South Korean battery materials R&D groups requiring rapid-throughput porosity analysis. Lead with cloud-connected digital calibration platforms priced below premium oscillating U-tube systems. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision instrument specialists with captive service revenue streams and regulatory certification depth. Five-to-ten-year viability hinges on software integration capabilities rather than hardware manufacturing scale. Watch for EMA data integrity guidance enforcement patterns as the inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Calibration Platform Launch | Enables remote diagnostics for ISO 17025-accredited laboratories in India and South Korea. |
| Helium Supply Agreement | Secures temperature control gas for oscillating U-tube systems against Qatar production disruptions. |
| Backward Integration into Quartz Tubing | Captures precision component supply for U-tube manufacturing at Baden-Württemberg facilities. |
| FDA 21 CFR Part 11 Software Certification | Accelerates pharmaceutical laboratory replacement cycles through embedded compliance capabilities. |
| Battery Materials Technical Sales Partnership | Opens cathode active material qualification channels with Japanese solid-state electrolyte developers. |
Research Methodology
Initial hypotheses were tested against primary input from pharmaceutical quality control managers, contract laboratory calibration technicians, precision instrument service directors, and mining operations geologists, and refined through secondary validation against FDA 483 inspection observations, EMA GMP inspection reports, ISO 17025 accreditation databases, and customs trade data for analytical instrument imports. Bottom-up triangulation across installed base estimates and top-down cross-checks against vendor revenue disclosures anchored volume and value outputs.
Demand-supply-balance framing structured the analytical framework across the projection horizon, with segmentation dimensions spanning product architecture, calibration technology tier, application focus, and end-user industry procurement authority. CAGRs were derived from replacement cycle analysis, accreditation-driven upgrade patterns, and materials science R&D capital allocation trends. Model inputs incorporated helium price volatility scenarios and EU MDR documentation mandate implementation timelines.
Stress conditions across helium supply disruption severity, FDA enforcement intensity, and battery materials R&D funding trajectories were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory alignment and technology substitution rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Global Chromatography Columns Market
Testing Equipment
Global Adsorption Equipment Market
Testing Equipment
Global Liquid Chromatography Instruments Market
Testing Equipment
Viscometer Market
Testing Equipment
Piping Hydro Testing Market
Testing Equipment
Fibrin Degradation Product (Fndp) Assays Market
Testing Equipment
Environmental Testing Equipment Market
Testing Equipment
Glass Testing Instruments Market
Testing Equipment
Gas Calorimeter Market
Testing Equipment
Fugitive Emissions Detection and Quantification Test Systems Market
Testing Equipment
Hydrocarbon Tester Market
Testing Equipment
Chemisorption Analyzer Market
Testing Equipment
Chemical Warfare Agent Detectors Market
Testing Equipment
Lactose Assay Kit Market
Testing Equipment
Reagent Filling Systems Market
Testing Equipment
Test Point Hoses Market