
 Liquid Analytical Instrument Market | 2026-2036
Liquid Analytical Instrument Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Analytical Instrument Market Analytics
Pharmaceutical companies are reorganizing capital allocation toward in-line process analytical technology, displacing traditional quality control labs as the dominant buyer archetype. METTLER TOLEDO leverages its Swiss manufacturing base to dominate high-precision electrochemical sensor supply. Yokogawa Electric Corporation anchors Asia-Pacific demand through integrated liquid chromatography systems for chemical manufacturing. Emerson Electric Co. competes on digital twin integration, extending software layers across hardware deployments.
Liquid analytical instruments comprise electrochemical, optical, and chromatographic devices that measure chemical composition, pH, conductivity, and dissolved oxygen in fluid matrices, typically achieving detection limits in parts-per-billion for regulatory compliance. These systems serve pharmaceutical, environmental, and food safety applications where real-time composition data prevents batch failure or discharge violations. Electrochemical analyzers command the largest installed base due to lower capital requirements and minimal maintenance protocols. Mass spectrometry segments capture the fastest expansion as pharmaceutical companies adopt multi-attribute monitoring for biologic purity verification. Chromatography instruments retain the deepest margin pools in high-performance liquid chromatography configurations for complex separations.
EPA Clean Water Act enforcement and FDA process analytical technology guidance in the United States, alongside EMA good manufacturing practice updates in Europe, mandate validated measurement systems for discharge and production environments. REACH chemical registration requirements further compel European manufacturers to deploy continuous organic compound monitoring. ISO 17025 accreditation standards shape laboratory procurement criteria across export-oriented quality control labs. Stakeholders must weigh capital deployment timing between retrofitting existing electrochemical infrastructure and migrating toward integrated mass spectrometry platforms as regulatory stringency escalates.
Market Dynamics
Pharmaceutical manufacturers are consolidating quality control functions into production lines, eliminating separate laboratory infrastructure and forcing instrument vendors to embed validation protocols directly into sensor firmware.
Growth Catalysts
- EPA Clean Water Act enforcement:Discharge monitoring mandates in the United States compel municipal water utilities to deploy continuous dissolved oxygen and pH analyzers at treatment outfalls.
- Biologics manufacturing expansion:Multi-attribute monitoring requirements for monoclonal antibody purity drive mass spectrometer adoption across contract development and manufacturing organizations.
- Germany's chemical corridor concentration:BASF and Bayer facility upgrades in Ludwigshafen and Leverkusen sustain demand for integrated chromatography systems with minimal calibration drift.
Market Restraints
- Platinum electrode supply concentration:Russian and South African mining operations control over three-quarters of global platinum group metal output, exposing electrochemical sensor manufacturers to input price volatility and sanctions risk.
- Mass spectrometer technical complexity:Vacuum system maintenance and ion source contamination limit deployment to facilities with dedicated technical staff, constraining addressable market expansion.
- REACH chemical registration timelines:European manufacturers face extended compliance verification periods when introducing novel sensing chemistries, delaying product commercialization relative to North American competitors.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO's tightened good manufacturing practice inspections create demand for validated process analytical technology among domestic generic drug producers previously reliant on offline testing.
- Food safety blockchain integration:Real-time composition data from optical sensors is anchoring supply chain traceability platforms, opening instrumentation sales through enterprise software procurement channels.
- Electrochemical-optical sensor convergence:Hybrid platforms combining pH electrodes with UV-Vis absorbance detection are capturing bioprocess applications requiring both ionic and molecular speciation data.
Industry Challenges
- Metrology technician scarcity:Specialized calibration and validation expertise for chromatography systems concentrates among aging workforces in Germany and Switzerland, constraining service expansion.
- ISO 17025 accreditation timelines:Laboratory customers require documented measurement uncertainty budgets extending instrument qualification periods and compressing vendor revenue recognition.
- Legacy 4-20mA signal integration:Digital-native sensors with Ethernet-APL outputs face adoption friction in brownfield chemical plants operating decades-old distributed control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Analytical Instrument Market |
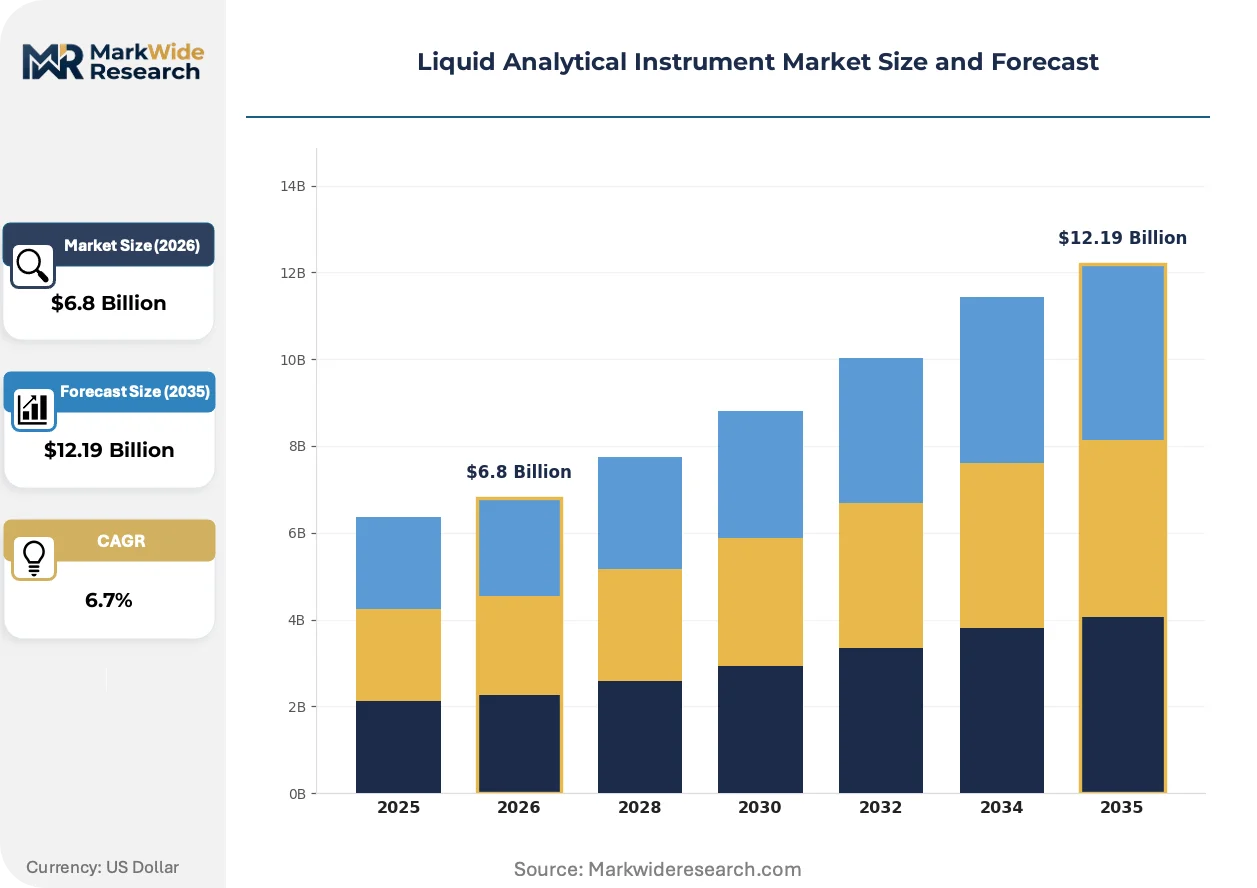
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chromatography Instruments, Spectroscopy Instruments, Electrochemical Analyzers, Liquid Handling Systems Technology: High-Performance Liquid Chromatography, Mass Spectrometry, Ultraviolet-Visible Spectroscopy, Infrared Spectroscopy Application: Pharmaceutical Analysis, Environmental Testing, Food & Beverage Testing, Chemical Manufacturing End User: Research Laboratories, Pharmaceutical Companies, Academic Institutions, Quality Control Labs |
| Companies Covered | Yokogawa Electric Corporation, METTLER TOLEDO, Emerson Electric Co., Teledyne Technologies Incorporated, Schneider Electric, Endress-Hauser Management AG, Honeywell International Inc., Electro-Chemical Devices, Inc., ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Analytical Instrument Market Evolving Landscape
Sensor miniaturization and edge computing are collapsing the distinction between laboratory-grade precision and field-deployable durability, rewriting procurement criteria across environmental monitoring and pharmaceutical quality assurance.
Raman spectroscopy is supplanting traditional high-performance liquid chromatography for real-time crystallization monitoring in active pharmaceutical ingredient manufacturing. Novartis and Merck facilities in Switzerland and Ireland have validated inline Raman probes for polymorph identification during batch production. This shift compresses analytical cycle times from hours to seconds while eliminating solvent consumption and waste disposal costs associated with chromatographic separations.
REACH chemical registration requirements in Europe are mandating continuous organic compound monitoring for downstream users of substances of very high concern. Chemical manufacturers in Germany's Ruhr region and Belgium's Port of Antwerp cluster must deploy total organic carbon analyzers with certified detection limits below 50 parts per billion. Instrument vendors are responding with pre-validated method packages that reduce customer implementation timelines from months to weeks.
Service unbundling is fragmenting traditional analyzer procurement into hardware, calibration, and data analytics components. Pharmaceutical buyers in the United States are separating sensor purchases from multiyear service contracts, engaging third-party metrology firms for ISO 17025-compliant calibration. This pattern concentrates in Massachusetts and North Carolina biotech clusters where specialized service providers have achieved accreditation density that rivals original equipment manufacturer capabilities.
Liquid Analytical Instrument Market Segmentation
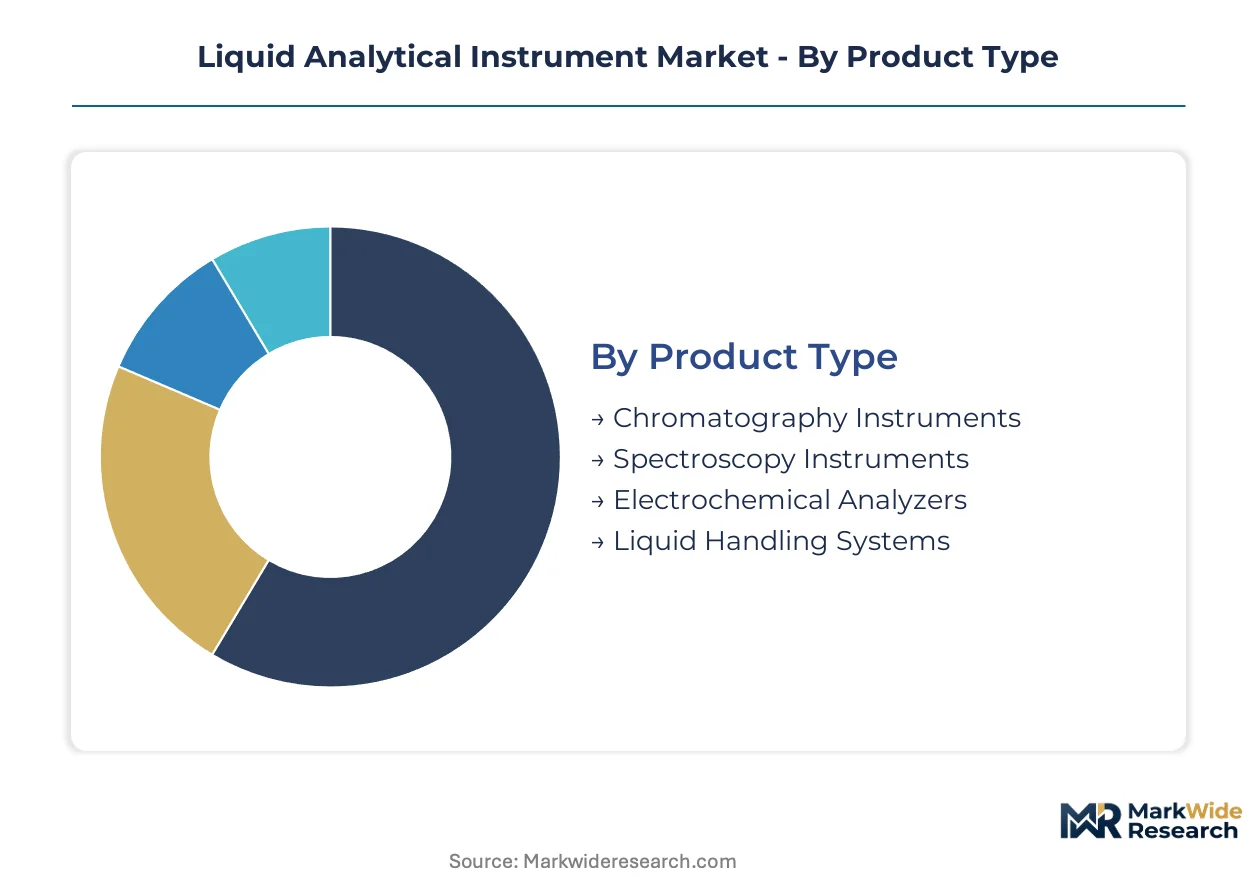
Liquid analytical instruments fragment across four distinct segmentation axes that reshape procurement patterns and vendor competitive positioning. Product type and technology dimensions capture capital equipment decisions, while application and end-user categories determine feature requirements and service intensity.
Product Type:
Margin pools concentrate in chromatography configurations where complex separations command premium pricing and recurring consumable revenue streams.
- Chromatography Instruments:High-performance liquid chromatography systems achieve baseline separation of complex mixtures through pressurized solvent delivery and specialized column chemistries. Pharmaceutical quality control labs in Massachusetts and North Carolina biotech clusters drive demand for ultra-high-pressure configurations with sub-two-micron particle columns. FDA process analytical technology guidance mandates validated methods that lock customers into specific instrument platforms.
- Electrochemical Analyzers:pH, conductivity, and dissolved oxygen sensors operate through potentiometric and amperometric measurement principles with minimal maintenance requirements. Municipal water utilities across the United States deploy continuous analyzers at treatment outfalls to meet EPA Clean Water Act discharge monitoring mandates. Lower capital thresholds expand the addressable customer base beyond specialized laboratory environments.
- Spectroscopy Instruments:UV-Vis, infrared, and Raman systems measure molecular absorbance and scattering properties for rapid compositional analysis.
- Liquid Handling Systems:Automated pipetting and sample preparation workstations standardize pre-analytical workflows in high-throughput screening environments.
The dominant share belongs to electrochemical analyzers, while chromatography instruments are closing the gap fastest through biopharmaceutical purity verification demand.
Technology:
Technology selection hinges on detection sensitivity requirements, with mass spectrometry configurations requiring dedicated infrastructure investments that reshape facility capital planning.
- Mass Spectrometry:Ionization source and mass analyzer combinations achieve parts-per-billion detection limits for molecular weight confirmation and structural elucidation. Contract development and manufacturing organizations in Switzerland and Ireland adopt multi-attribute monitoring platforms for monoclonal antibody purity verification. Vacuum system complexity limits deployment to facilities with specialized technical staff.
- High-Performance Liquid Chromatography:Pressurized solvent delivery systems with variable wavelength or mass spectrometric detection separate thermally labile compounds without derivatization. BASF and Bayer facilities in Germany's chemical corridor sustain demand for integrated systems with minimal calibration drift requirements. REACH chemical registration mandates compel continuous organic compound monitoring with certified detection protocols.
- Ultraviolet-Visible Spectroscopy:Benchtop and fiber-optic probe configurations measure electronic transitions for concentration determination and reaction monitoring.
- Infrared Spectroscopy:Fourier-transform and attenuated total reflectance modes identify functional groups through molecular vibration analysis.
High-performance liquid chromatography retains the deepest installed base, though mass spectrometry is expanding most quickly through biologics manufacturing proliferation.
Application:
Application-driven procurement concentrates compliance investment where regulatory enforcement carries immediate operational consequences.
- Pharmaceutical Analysis:Active pharmaceutical ingredient characterization and finished product release testing demand validated analytical methods with documented measurement uncertainty. EMA good manufacturing practice updates in Europe and FDA guidance in the United States mandate process analytical technology integration for real-time quality assurance. Batch failure costs exceeding millions of dollars justify premium instrument specifications.
- Environmental Testing:Surface water, groundwater, and wastewater monitoring requires continuous analyzers for dissolved oxygen, pH, and total organic carbon parameters. EPA enforcement actions against municipal utilities in the United States accelerate capital deployment for automated monitoring infrastructure. Discharge permit violations trigger penalties that instrument investments offset within single compliance events.
- Food & Beverage Testing:Contaminant screening and authenticity verification protect brand reputation through supply chain integrity programs.
- Chemical Manufacturing:In-process monitoring and final product certification ensure specification adherence for industrial chemical shipments.
Pharmaceutical analysis commands the largest revenue share, while environmental testing is gaining share fastest through tightening discharge mandates.
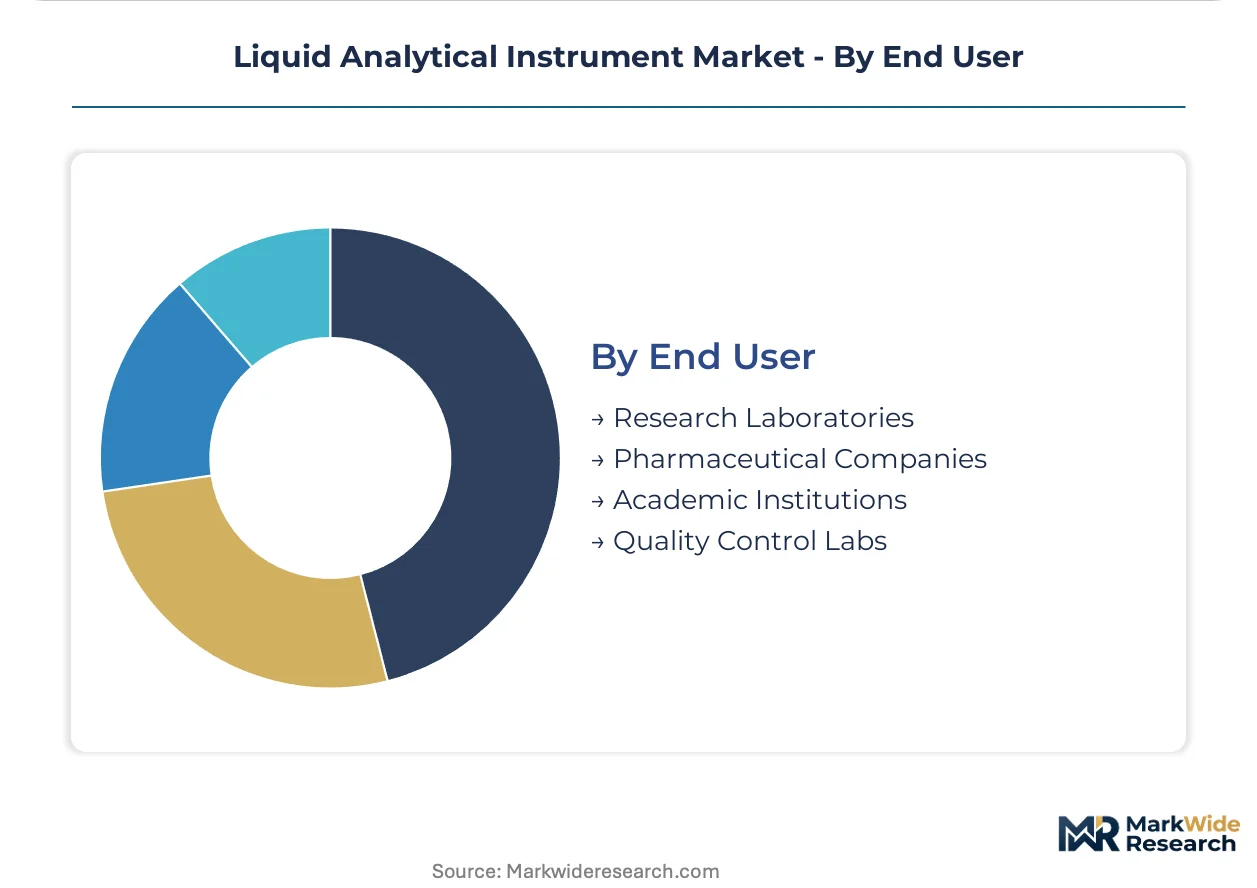
End User:
End-user categories separate capital availability from technical sophistication requirements, reshaping vendor sales motion and service bundling strategies.
- Pharmaceutical Companies:Integrated quality control and manufacturing organizations consolidate analytical functions into production lines to eliminate separate laboratory infrastructure. CDSCO tightened good manufacturing practice inspections in India create demand among domestic generic drug producers previously reliant on offline testing. Validation protocol embedding in sensor firmware becomes a competitive differentiator.
- Quality Control Labs:ISO 17025-accredited facilities serving multiple industrial clients require flexible instrument platforms with documented measurement traceability. Service unbundling trends in the United States separate hardware purchases from third-party metrology firm calibration contracts. Procurement criteria emphasize total cost of ownership over initial capital expenditure.
- Research Laboratories:Academic and government facilities prioritize methodological flexibility and publication-grade data integrity.
- Academic Institutions:Teaching and basic research applications balance capability demonstration against constrained capital budgets.
Pharmaceutical companies hold the dominant position, while quality control labs are climbing the fastest through third-party testing outsourcing trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German electrochemical sensor manufacturers export precision instrumentation to pharmaceutical clusters in Switzerland and Ireland, creating a trade corridor that channels European regulatory standards into global quality control infrastructure.
United States
EPA Clean Water Act enforcement drives municipal utility spending on continuous dissolved oxygen analyzers at treatment outfalls. FDA process analytical technology guidance mandates validated measurement systems for pharmaceutical manufacturing. Massachusetts and North Carolina biotech clusters absorb premium chromatography systems for monoclonal antibody production.
Germany
BASF and Bayer facility upgrades in Ludwigshafen and Leverkusen sustain demand for integrated chromatography with minimal calibration drift. REACH chemical registration requirements compel continuous organic compound monitoring across the Ruhr industrial basin. The chemical corridor concentration anchors European electrochemical analyzer supply chains.
Switzerland
Novartis and Merck facilities deploy inline Raman probes for polymorph identification during active pharmaceutical ingredient manufacturing. Swissmedic good manufacturing practice standards enforce validated analytical methods with documented measurement uncertainty. Basel and Zurich pharmaceutical clusters drive high-precision sensor procurement from domestic suppliers.
India
CDSCO tightened good manufacturing practice inspections create demand for validated process analytical technology among domestic generic drug producers. Pharmaceutical manufacturers in Maharashtra and Gujarat reorganize capital allocation toward in-line quality verification. Mumbai and Hyderabad manufacturing hubs displace traditional quality control labs with production-embedded sensors.
China
NMPA pharmaceutical quality standards accelerate electrochemical analyzer deployment across biologics manufacturing expansion. MEE environmental discharge mandates compel municipal water utilities toward automated monitoring infrastructure. Yangtze River Delta chemical parks integrate continuous analyzers for regulatory compliance verification.
Liquid Analytical Instrument Market Competitive Landscape
Listed leaders compete with private specialists across validation protocol integration and service bundling strategies. The vendor base concentrates around three tiers: diversified industrial conglomerates with digital twin capabilities, precision instrumentation specialists leveraging Swiss and German manufacturing heritage, and regional system integrators anchoring Asia-Pacific demand. Strategic archetypes include electrochemical sensor pure-plays, chromatography platform providers, and integrated automation houses. Competitive moves center on firmware-embedded validation protocols and third-party metrology service partnerships.
Within the precision instrumentation tier, METTLER TOLEDO and Endress-Hauser Management AG exemplify Swiss and German manufacturing heritage applied to high-precision electrochemical sensor supply. Yokogawa Electric Corporation anchors Asia-Pacific demand through integrated system architectures. Emerson Electric Co. occupies a position among diversified industrial conglomerates competing on digital integration layers across hardware deployments.
| Leading Market Players |
|---|
| Yokogawa Electric Corporation |
| METTLER TOLEDO |
| Emerson Electric Co. |
| Teledyne Technologies Incorporated |
| Schneider Electric |
| Endress-Hauser Management AG |
| Honeywell International Inc. |
| Electro-Chemical Devices, Inc. |
| ABB |
| Others |
Value Network & Pricing Analysis
ISO 17025 accreditation standards gate both supplier qualification and price differentiation simultaneously, compressing margins for uncertified vendors while allowing accredited metrology firms to command premium positioning in pharmaceutical procurement channels.
Pricing Analysis
Current-generation mass spectrometry platforms carry three-to-four-fold premiums over prior-generation electrochemical analyzers, while next-generation hybrid optical-electrochemical sensors are capturing mid-tier positioning. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated chromatography systems from industrial-grade pH sensors and unbranded replacement electrodes. Price differentiation hinges on certification level and after-sales service bundling, with ISO 17025-accredited calibration packages adding substantial recurring revenue. Cost compression in the economy tier is intensifying because municipal water utilities face budget constraints under EPA enforcement timelines. Contract development and manufacturing organizations exhibit least price sensitivity due to batch failure costs, while small generic drug producers in India show highest sensitivity to capital expenditure thresholds.
Supply Chain Analysis
Extended lead times for platinum group metal electrodes have stretched from standard procurement cycles to multi-quarter commitments, forcing sensor manufacturers to hold strategic inventory buffers. Manufacturing concentrates in Switzerland, Germany, and Japan for precision electrochemical components, while optical subassemblies source predominantly from South Korea and Taiwan. Raw material dependencies center on Russian and South African platinum output, specialized glass membranes from German suppliers, and rare-earth phosphors for optical detectors. Single-source vulnerability in platinum electrode supply exposes producers to sanctions risk and commodity price volatility. Distribution runs through authorized metrology service partners in pharmaceutical clusters and direct OEM relationships for municipal utility deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Process analytical technology mandates from FDA and EMA are accelerating instrument vendor consolidation, creating high-growth disruption as firmware-embedded validation protocols displace traditional laboratory infrastructure procurement patterns.
For Market Incumbents: Compound defensive positioning through backward integration into platinum electrode supply chains and captive calibration service networks in Massachusetts and North Carolina biotech clusters. Threat substitution from Raman spectroscopy probes in active pharmaceutical ingredient manufacturing demands accelerated R&D in hybrid sensor platforms. Certification investment in pre-validated method packages for REACH compliance represents the critical lever for European market retention. For New Entrants and Emerging Players: Lead with electrochemical-optical hybrid platforms targeting India's CDSCO-inspected generic drug facilities, where production-embedded quality verification is displacing offline laboratory infrastructure. Maharashtra and Gujarat pharmaceutical corridors offer the most penetrable geography due to capital reallocation pressures and limited incumbent service density. Go-to-market execution should anchor on third-party metrology partnerships rather than direct sales force buildout. For Investors and Strategic Acquirers: FDA process analytical technology guidance reshapes the acquisition landscape toward firms with firmware-embedded validation capabilities and ISO 17025-accredited service networks. Long-term viability centers on recurring revenue intensity from calibration contracts rather than hardware shipment volumes. Acquisition target archetype: precision electrochemical specialists with proven pharmaceutical customer retention and regional service accreditation density. Signal to watch: CDSCO inspection failure rates among Indian generic producers as demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware-Embedded Validation Protocols | Pharmaceutical buyers now mandate sensor-level compliance documentation, locking vendors into platform stickiness. |
| Backward Integration into Platinum Supply | Electrode manufacturers securing South African mining partnerships reduce input volatility exposure from sanctions risk. |
| Third-Party Metrology Service Partnerships | Quality control labs in US biotech clusters separate hardware purchases from accredited calibration contracts. |
| Pre-Validated REACH Method Packages | German chemical corridor buyers compress implementation timelines from months to weeks for organic compound monitoring. |
| Hybrid Optical-Electrochemical Platform Development | Bioprocess applications requiring ionic and molecular speciation data drive convergence R&D investment priority. |
Research Methodology
A standing panel of pharmaceutical quality control directors, municipal utility operations managers, contract manufacturing organization executives, and electrochemical sensor R&D leads provided ongoing calibration against market dynamics throughout the study period. Primary interview data combined with secondary validation from FDA guidance documents, EMA good manufacturing practice updates, EPA enforcement action records, and ISO 17025 accreditation databases. Bottom-up instrumentation shipment tracking triangulated against top-down pharmaceutical capital expenditure disclosures and water utility procurement records.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated product type, technology generation, application compliance intensity, and end-user capital availability dimensions. CAGRs derived from regression analysis of historical shipment patterns and regulatory mandate implementation timelines. Forecast inputs included CDSCO inspection schedule acceleration, REACH chemical registration phase-in requirements, and biologics manufacturing capacity expansion announcements.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement intensity or platinum supply disruption scenarios would require recalibration. Forecasts reflect documented assumptions regarding technology substitution rates and certification adoption curves. Specific risk factors including EMA guidance revisions, municipal utility budget cycles, and geopolitical sanctions exposure could materially revise trajectory. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Japan Material Testing Market
Testing Equipment
Hydrocarbon Tester Market
Testing Equipment
Laboratory Accessories Market
Testing Equipment
Hydrogen Gas Analyzers Market
Testing Equipment
Global Adsorption Equipment Market
Testing Equipment
Gold Tester Market
Testing Equipment
Water Analysis Instruments Market
Testing Equipment
Viscometer Market
Testing Equipment
Lactose Assay Kit Market
Testing Equipment
Pellistor Bead Chemical Sensor Market
Testing Equipment
Chemical Warfare Agent Detectors Market
Testing Equipment
Global Insulation Testers Market
Testing Equipment
Odor Emission Measurement and Dynamic Olfactometry Test Equipment Market
Testing Equipment
Melting Point Apparatus Market
Testing Equipment
Total Hydrocarbon Analyzers Market
Testing Equipment
Chlorine Meter Market