
 Global Liquor Bottles Market | 2026-2036
Global Liquor Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Liquor Bottles Market Outlook
Recycled flint glass is expanding its share in premium liquor packaging as brands seek to reduce Scope 3 emissions without sacrificing optical clarity. Diageo leverages its scale to secure long-term recycled glass supply agreements across multiple continents. Pernod Ricard sustains a dedicated lightweighting program that cuts transport costs per unit while maintaining structural integrity. Constellation Brands anchors its North American operations with regional glass furnace partnerships that shorten logistics loops.
Liquor bottles are rigid containers engineered to withstand internal pressure, thermal shock, and mechanical impact during filling, capping, distribution, and retail display; specifications typically include hydrolytic resistance class, wall thickness tolerance, and finish dimensional compatibility with automated capping lines. Glass dominates the material segment due to its inertness and premium perception, though plastic gains traction in travel retail and outdoor event channels where weight and breakage risk matter. Spirits occupies the largest product type segment, with 750ml capacity serving as the standard reference format for whiskey, vodka, and rum worldwide.
The U.S. FDA governs indirect food contact materials for liquor bottles through its food additive regulations, while the EU REACH framework restricts certain heavy metals and chemicals in glass colorants and decorative coatings. China's SAMR enforces GB standards for glass packaging safety that affect export-bound production. Stakeholders must monitor evolving extended producer responsibility schemes and carbon border adjustments that will reshape sourcing decisions and furnace location strategies.
Market Dynamics
The EU Green Deal's carbon border adjustment mechanism is forcing liquor bottle manufacturers to relocate furnace capacity closer to recycled glass feedstock sources, compressing legacy supply networks that relied on virgin silica sand imports.
Growth Catalysts
- Post-consumer recycled content mandates:Europe's packaging waste directive requires minimum recycled glass thresholds, pulling investment into cullet processing infrastructure across Germany and France.
- Craft distillery proliferation:Small-batch whiskey and gin producers in the United States commission custom embossed bottles, expanding the addressable base for specialized mold houses.
- Lightweighting technology diffusion:Thin-wall glass forming advances cut transport emissions per pallet, satisfying retailer sustainability scorecards without sacrificing shelf presence.
Market Restraints
- Natural gas price volatility:Furnace operations in Italy and Spain face input cost spikes that erode margin on standard-format bottles.
- Heavy base glass supply concentration:Premium whiskey's demand for thick-bottomed bottles concentrates qualified production among a handful of specialized furnaces in France.
- Plastic substitution in travel retail:PET and barrier-coated polymers capture onboard duty-free channels where weight restrictions and breakage liability dominate purchasing criteria.
Strategic Opportunities
- India's organized liquor retail expansion:State-level beverage corporation modernization creates demand for standardized 750ml formats with tamper-evident closures.
- Carbon border adjustment arbitrage:Manufacturers with verified low-carbon glass production can capture premium positioning in EU-bound exports.
- Direct-to-consumer channel growth:Subscription spirits clubs require smaller batch runs with rapid label changeover capabilities, favoring agile mold shops over mass producers.
Industry Challenges
- Skilled furnace operator scarcity:Glass melting expertise concentrates among aging workforces in the Czech Republic and Portugal, constraining capacity expansion timelines.
- Legacy equipment integration:Automated inspection systems for recycled flint glass must interface with decades-old forming lines, creating quality control gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Liquor Bottles Market |
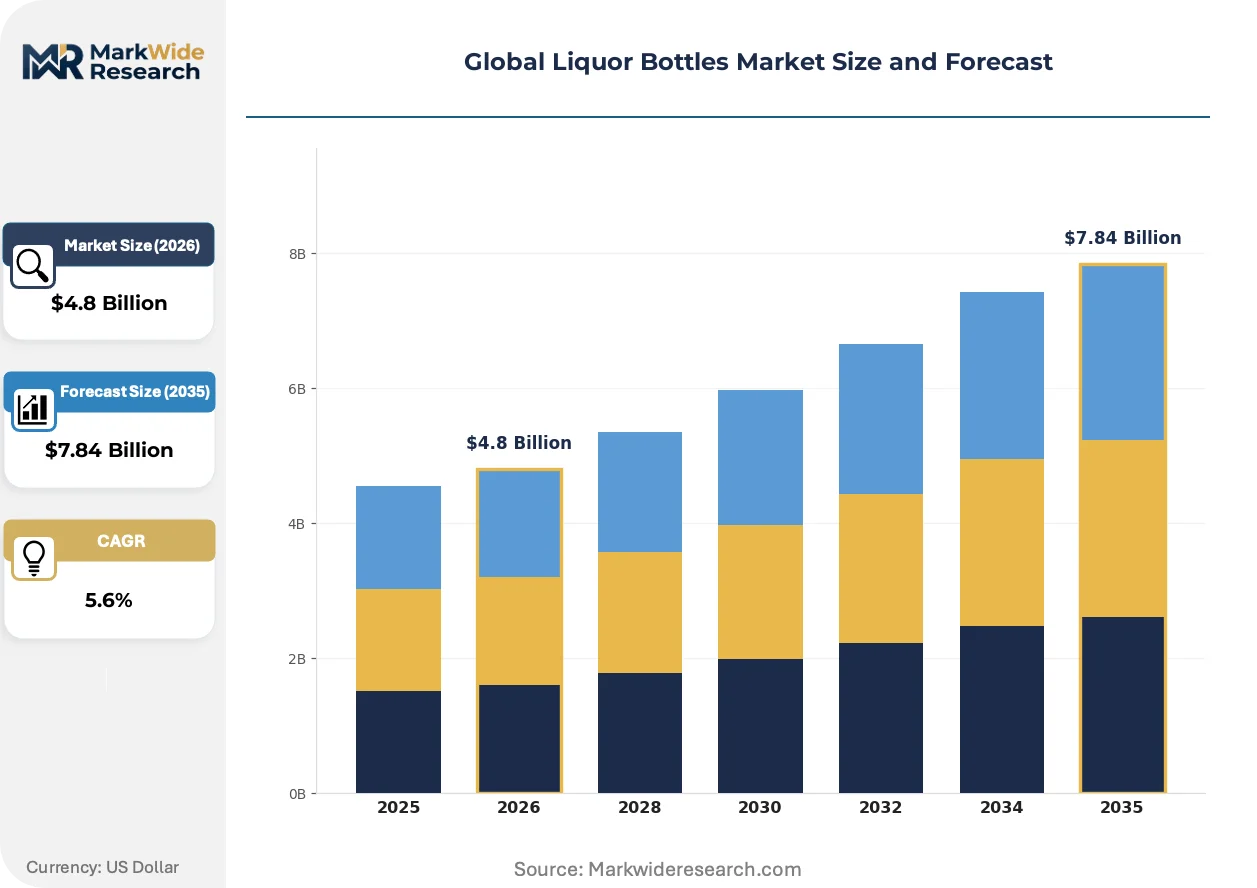
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Glass, Plastic, Metal, Ceramic Closure Type: Cork, Screw Cap, Flip Top, Snap Cap Product Type: Spirits, Liqueurs, Wine, Cider Capacity: 200ml, 500ml, 750ml, 1L |
| Companies Covered | Diageo, Pernod Ricard, Constellation Brands, Brown-Forman, Bacardi, Heineken, Campari Group, Molson Coors Beverage Company, Asahi Group Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Liquor Bottles Market Strategic Shifts
Digital printing and closed-loop recycling systems are compressing design-to-shelf timelines while redefining what constitutes premium packaging aesthetics across spirits categories.
Near-infrared sorting technology is unifying cullet quality standards across fragmented municipal waste streams. Premium vodka brands in Poland and Sweden now specify NIR-sorted flint glass for their core lines, compressing the price gap between virgin and recycled feedstock. This quality convergence is enabling furnace operators to push recycled content beyond previous optical clarity thresholds.
REACH Annex XVII restrictions on heavy metal colorants are forcing decorative coating reformulation across European supply chains. Cadmium and lead-based pigments in ceramic transfers face phase-out timelines, pushing distillers toward laser-etched or organic ink alternatives. Scotch whisky exporters to Germany and the Netherlands are accelerating compliance to avoid customs detention at Rotterdam.
Super-premium buyers now specify bottle weight and embossing depth as primary quality signals, displacing traditional label-centric branding. American bourbon collectors in Kentucky and Tennessee prioritize tactile heft over paper embellishment, compressing demand for conventional printed finishes. This specification shift favors mold-making specialists with deep engraving capabilities over standard glass converters.
Global Liquor Bottles Market Segmentation
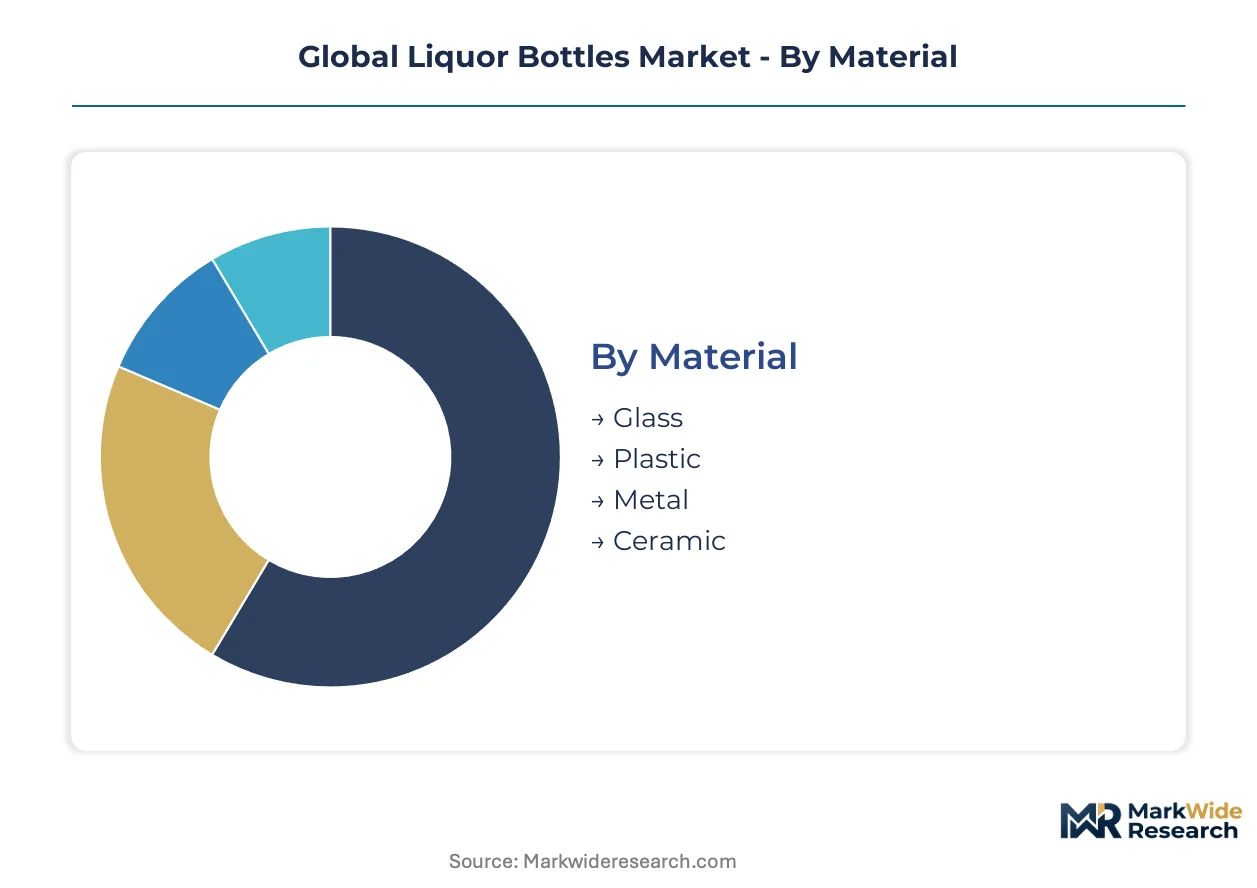
Liquor bottle procurement decisions split across material chemistry, closure mechanics, and volume economics. Distillers, wineries, and contract bottlers each weight these dimensions differently based on distribution channel, brand tier, and regulatory exposure.
Material:
Premium positioning and shelf-life requirements separate buyers in this category more than unit cost considerations.
- Glass:Soda-lime silica composition delivers inertness against alcohol oxidation and supports embossed surface treatments. Demand concentrates in American bourbon and Scotch whisky segments where tactile heft signals quality tier.
- Plastic:PET and barrier-coated polymers reduce breakage liability in travel retail and outdoor event channels. Airlines and cruise operators in the Caribbean specify sub-500g weights for onboard duty-free logistics.
- Metal:Aluminum and stainless steel formats serve niche ready-to-drink cocktails and premium miniatures where thermal conductivity and reuse cycles matter. Japanese highball brands trial limited runs for summer seasonal releases.
- Ceramic:Glazed stoneware and porcelain vessels anchor traditional spirits categories including Korean soju and Chinese baijiu heritage lines. Regional distillers in Sichuan and Gyeonggi-do provinces commission custom kiln runs for gift packaging.
Volume sits with glass; growth tilts toward plastic.
Closure Type:
Tamper evidence and oxygen transmission rates determine selection more than consumer convenience preferences.
- Cork:Natural and synthetic corks dominate wine and aged spirits where micro-oxygenation influences maturation profiles. Portuguese cork suppliers face pricing pressure from screw cap substitution in Australian and Chilean export wines.
- Screw Cap:Aluminum ROPP closures secure standard-format vodka and rum bottles across high-speed filling lines. German and Italian capping equipment manufacturers optimize for 28mm and 33mm finishes.
- Flip Top:Hinged polymer mechanisms serve ready-to-drink and mixer categories requiring repeated reseal. Brazilian cachaça producers adopt flip tops for beach retail channels.
- Snap Cap:Press-fit plastic closures minimize unit cost for value-tier spirits and airline miniatures. Chinese mold houses in Zhejiang province specialize in 20mm snap specifications for domestic baijiu.
Screw caps capture volume share; cork retains premium positioning.
Product Type:
Alcohol strength and consumption occasion shape bottle specification more than packaging aesthetics alone.
- Spirits:Whiskey, vodka, rum, and gin command the largest format diversity from 50ml miniatures to 1.75L handles. American craft distillers in Kentucky and Tennessee drive demand for heavy-base embossed designs.
- Liqueurs:Lower ABV formulations require less structural wall thickness but emphasize decorative differentiation. Italian amaro and French crème producers commission custom mold shapes for bar back visibility.
- Wine:750ml Bordeaux and Burgundy profiles remain standardized, though alternative formats including cans and bag-in-box erode glass share in entry-tier segments. Australian and Chilean exporters lead screw cap conversion.
- Cider:Crown-capped and swing-top formats dominate English and French traditional production, while American hard cider shifts toward 12oz longneck beer bottles for retail adjacency.
Spirits anchor volume; cider climbs fastest among alternatives.
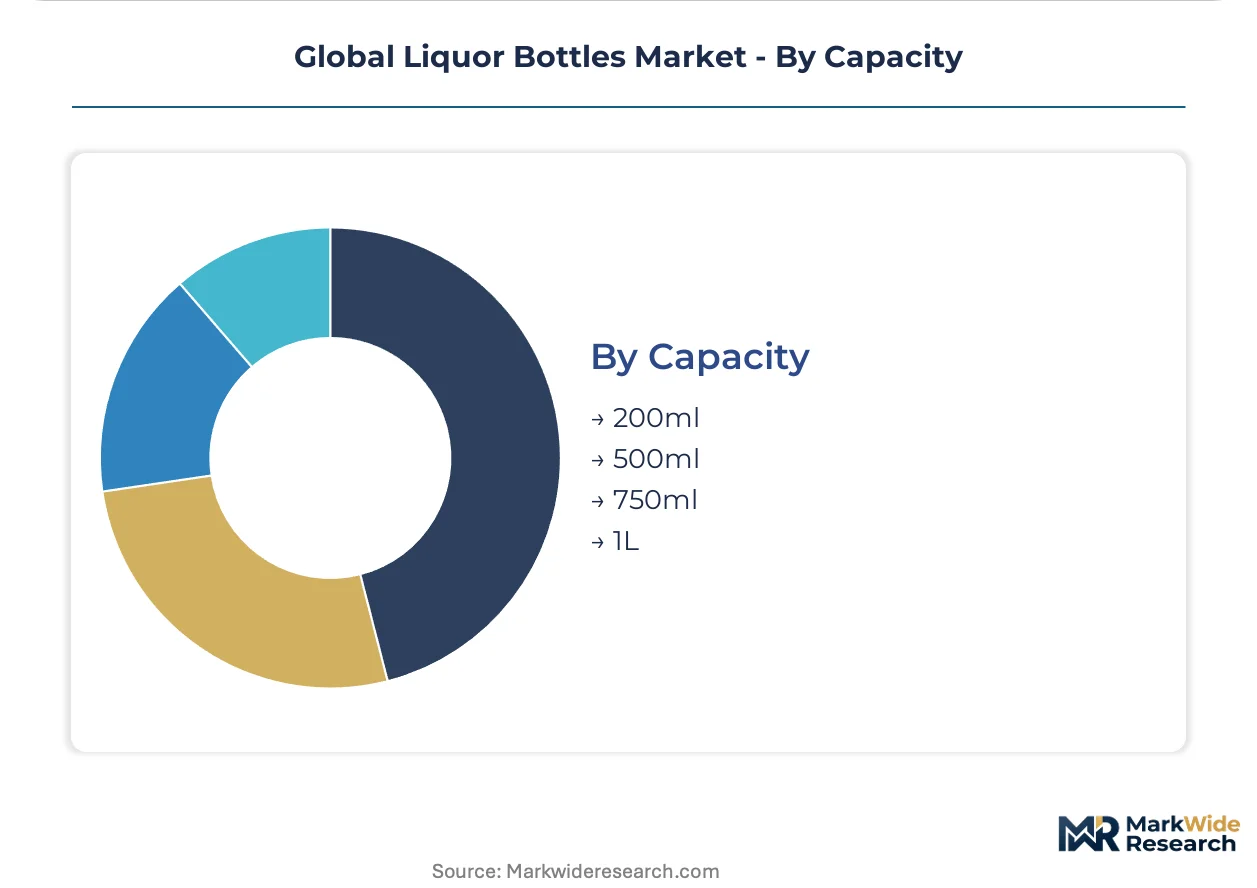
Capacity:
Distribution channel economics and taxation brackets fragment demand across volume tiers.
- 200ml:Miniature formats serve airline duty-free, hotel minibars, and sampler gift sets. Travel retail procurement in Dubai and Singapore concentrates specifications for single-serve spirits.
- 500ml:Mid-size bottles gain traction in Japanese and South Korean markets where household consumption patterns favor smaller purchase quantities. Suntory and HiteJinro specify 500ml as core format for domestic whiskey and soju.
- 750ml:The global reference standard for spirits taxation and retail shelving. American whiskey, French cognac, and Russian vodka producers align mold investments around this dimension.
- 1L:Value-tier and travel retail exclusive formats optimize per-liter logistics economics. Diageo and Pernod Ricard negotiate 1L specifications for airport retail channels in Heathrow and Charles de Gaulle.
750ml holds volume concentration; 500ml gains share in Asia-Pacific markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for liquor bottles concentrates in the United States, where craft distilleries and super-premium whiskey releases sustain specialized procurement. Secondary clusters operate in France, Germany, China, and India, each shaped by distinct regulatory and consumption patterns.
United States
Kentucky and Tennessee bourbon producers commission heavy-base embossed bottles as quality signals. The FDA governs indirect food contact materials through food additive regulations. Glass furnace partnerships in Ohio and Pennsylvania shorten logistics loops for Constellation Brands' North American operations.
France
Cognac houses and luxury spirits brands drive demand for thick-bottomed flint glass with deep engraving. The EU Green Deal's packaging waste directive mandates minimum recycled glass thresholds. Specialized furnaces in Normandy concentrate qualified production for premium whiskey export markets.
Germany
High-speed filling lines for standard-format vodka and rum optimize around 28mm and 33mm screw cap finishes. ECHA's REACH Annex XVII restricts heavy metal colorants in decorative coatings. Cullet processing infrastructure investment clusters along the Rhine corridor near recycled feedstock sources.
China
Baijiu heritage lines commission custom ceramic vessels from Sichuan province kilns while export-bound glass faces SAMR's GB packaging safety standards. The country's dual carbon goals accelerate furnace efficiency upgrades. Zhejiang mold houses specialize in 20mm snap cap specifications for domestic value-tier spirits.
India
State-level beverage corporation modernization creates demand for standardized 750ml formats with tamper-evident closures. BIS standards govern glass packaging safety for organized retail expansion. Maharashtra and Karnataka host emerging distillery clusters sourcing regional bottle supply.
Global Liquor Bottles Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with spirits companies controlling design specifications while glass converters execute production. The structure tilts toward consolidation among premium mold houses capable of deep embossing, while standard-format supply remains fragmented across regional furnaces. Three archetypes dominate: integrated spirits groups with captive glass agreements, specialized mold-making workshops with engraving capabilities, and scale-driven converters serving value-tier brands. Competitive moves center on long-term recycled glass supply contracts and lightweighting technology partnerships that cut transport emissions per pallet.
Among integrated spirits groups, Diageo leverages multi-continent scale to secure feedstock agreements, while Pernod Ricard exemplifies the lightweighting-focused archetype through dedicated structural integrity programs. Constellation Brands anchors the regional partnership model with North American furnace alliances. These three represent distinct strategic postures on sustainability integration and supply chain control.
| Leading Market Players |
|---|
| Diageo |
| Pernod Ricard |
| Constellation Brands |
| Brown-Forman |
| Bacardi |
| Heineken |
| Campari Group |
| Molson Coors Beverage Company |
| Asahi Group Holdings |
| Others |
Value Chain & Pricing Dynamics
Integrated spirits groups with multi-continent procurement footprints command pricing leverage through long-term recycled glass offtake agreements, compressing spot-market exposure for regional converters. Their volume concentration forces tiered pricing structures that stratify premium embossed formats from commodity flint glass.
Pricing Analysis
Volume-mass production runs on per-unit transactional pricing, while margin-rich specialty embossing commands project-based mold fees. Quality grade and customization level drive price differentiation, with heavy-base bourbon bottles carrying substantial premiums over standard vodka formats. Pricing pressure stems from natural gas cost volatility eroding furnace margins in Italy and Spain. Value-tier brands exhibit acute price sensitivity; super-premium distillers prioritize tactile heft over unit economics.
Supply Chain Analysis
Regional distribution centers in Ohio, Pennsylvania, and Normandy anchor hub-and-spoke patterns that shorten logistics loops for Constellation Brands and French cognac houses. Supply concentrates in France, Germany, and the United States, with specialized furnaces drawing from silica sand deposits and post-consumer cullet streams. Raw material dependencies rest on natural gas for melting energy, soda ash for flux chemistry, and recycled flint feedstock for optical clarity. Single-source vulnerability concentrates in heavy-base glass production among a handful of qualified furnaces. Distribution runs through spirits companies' captive procurement teams and contract bottler networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU carbon border adjustments and recycled content mandates are forcing consolidation among furnace operators lacking cullet processing infrastructure or verified low-carbon production.
For Market Incumbents: Hedge against feedstock disruption by securing long-term recycled glass supply agreements across multiple continents, mirroring Diageo's procurement posture. Deepen backward integration into cullet processing infrastructure near recycled feedstock sources, particularly along Germany's Rhine corridor. Defensive moves must address skilled furnace operator scarcity constraining capacity expansion in the Czech Republic and Portugal. For New Entrants and Emerging Players: The gap between premium embossed formats and economy-tier standard bottles offers white-space entry for agile mold shops with rapid label changeover capabilities. Target direct-to-consumer subscription spirits clubs requiring smaller batch runs, where incumbent scale becomes disadvantageous. India's state-level beverage corporation modernization presents the most penetrable geography for standardized 750ml format supply. For Investors and Strategic Acquirers: The window for entry favors specialized mold-making workshops with deep engraving capabilities, as super-premium specification shifts displace conventional printed finishes. Long-term viability hinges on furnace operators' verified low-carbon positioning for EU-bound export capture. Watch carbon border adjustment implementation timelines as the inflection signal for low-carbon production premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Glass Supply Agreement | Secures Scope 3 emission reductions for Diageo and Pernod Ricard across multiple continents. |
| Lightweighting Technology Partnership | Pernod Ricard's structural integrity program cuts transport emissions per pallet while maintaining shelf presence. |
| Regional Furnace Alliance | Constellation Brands' Ohio and Pennsylvania partnerships compress logistics loops for North American operations. |
| Cullet Processing Infrastructure Investment | EU packaging waste directive mandates pull capital into Germany and France recycling facilities. |
| Digital Printing Capability Acquisition | Compresses design-to-shelf timelines for direct-to-consumer channel growth in subscription spirits clubs. |
Study Parameters
Multi-period observation of furnace capacity utilization, cullet pricing spreads, and spirits company procurement patterns anchored the trend analysis, supplemented by interviews with glass furnace operators, mold-making specialists, spirits brand procurement directors, and contract bottler supply chain managers. Secondary validation drew from EU ETS carbon price data, FDA food additive regulations, ECHA REACH Annex XVII restrictions, and customs trade flows for glass packaging. Bottom-up volume modeling triangulated against top-down spirits consumption forecasts.
Input-output matrices mapped material chemistry, closure mechanics, and capacity tier against regional regulatory clusters and distribution channel economics across the projection horizon. Segmentation dimensions included material type, closure format, product category, and volume tier, with furnace location strategy modeled as an industry-specific dimension. CAGRs derived from regression analysis of historical production data against spirits release schedules and retail channel expansion patterns. Forecast inputs incorporated natural gas price trajectory assumptions and recycled content mandate compliance timelines.
Inputs from furnace operators and spirits procurement teams were available through the study window; gaps in real-time cullet quality standardization data introduce uncertainty bands around recycled content penetration forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Fruit Brandy Market
Alcoholic Beverages
Commercial Beer Tap System Market
Alcoholic Beverages
Instant Wine Chillers and Refreshers Market
Alcoholic Beverages
Premium Spirit Market
Alcoholic Beverages
Hip Flask Market
Alcoholic Beverages
Germany Tequila Market
Alcoholic Beverages
Cigar and Cigarillos Market
Alcoholic Beverages
Alcoholic Drinks Market
Alcoholic Beverages
Beer Pasteurization Equipment Market
Alcoholic Beverages
Irish Whiskey Market
Alcoholic Beverages
Citrus Alcohol Market
Alcoholic Beverages
Orange Wine Market
Alcoholic Beverages
Germany Wine Coolers Market
Alcoholic Beverages
Fruit Beer Market
Alcoholic Beverages
Gin Market
Alcoholic Beverages
Beer Bottle Market