
 Organic Juice Market | 2026-2036
Organic Juice Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Juice Market Outlook
USDA Organic certification is collapsing the supplier base as smaller processors fail to meet updated livestock and crop input documentation rules. Danone S.A. leverages its refrigerated distribution network to dominate European retail placements. Suja Life LLC anchors its position through exclusive Whole Foods Market shelf space agreements. Uncle Matt's Organic specializes in citrus-forward SKUs that compete on flavor intensity rather than price.
Organic juice comprises fruit and vegetable extracts derived from crops cultivated without synthetic pesticides, genetically modified organisms, or petroleum-based fertilizers, typically processed through cold-pressing or high-pressure processing to preserve enzyme activity and nutrient density below 45°C. Cold-pressed variants command the deepest margin pools due to perishable logistics and premium positioning, while high-pressure processed formats extend shelf life without thermal degradation for mainstream supermarket penetration. Health food stores and online retail channels are capturing the fastest-growing customer traffic as fitness enthusiasts and culinary professionals shift from conventional juice aisles.
The USDA National Organic Program, FDA juice HACCP regulations, and EU Organic Regulation 2018/848 collectively determine label claims, import eligibility, and processing facility audits across North American and European supply chains. Compliance costs are diverting capital toward in-house bottling infrastructure rather than co-packing arrangements. Stakeholders must monitor evolving EU pesticide residue thresholds and state-level organic fraud enforcement to protect brand equity and market access.
Market Dynamics
USDA National Organic Program documentation mandates are collapsing the supplier base as smaller processors fail to meet updated livestock and crop input traceability rules, redirecting procurement toward vertically integrated bottlers with captive agricultural supply.
Growth Catalysts
- Cold-Pressing Technology:Health-conscious consumers in premium grocery channels are accelerating purchases of enzyme-preserving variants processed below 45°C.
- FDA Juice HACCP:Mandatory hazard analysis protocols are professionalizing processing standards and building retailer confidence in shelf-stable formats.
- California Agricultural Concentration:Citrus and leafy green cultivation clusters in the Central Valley are shortening raw material transit windows for West Coast processors.
Market Restraints
- Perishable Logistics Costs:Cold-chain requirements for unpasteurized formats compress margins on distribution runs exceeding 48 hours.
- Organic Feedstock Volatility:Certified organic fruit acreage limitations in Florida and Mexico create input bottlenecks during seasonal transition windows.
- High-Pressure Processing Capital Intensity:In-house HPP equipment purchases exceed $2 million per line, excluding co-dependent processors from premium format competition.
Strategic Opportunities
- EU Organic Regulation 2018/848:Updated import eligibility criteria create first-mover positioning for USDA-certified exporters into German and French retail.
- Direct-to-Consumer Subscription:Weekly cold-pressed delivery models bypass slotting fee barriers at conventional supermarkets.
- Functional Ingredient Convergence:Probiotic and adaptogenic infusions are opening wellness-positioned SKUs adjacent to conventional juice aisles.
Industry Challenges
- Organic Certification Timeline:USDA National Organic Program transition periods require 36 months of documented chemical-free cultivation before label eligibility.
- High-Pressure Processing Technical Talent:Specialized equipment operation and maintenance skills remain concentrated among a narrow technician pool.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Juice Market |
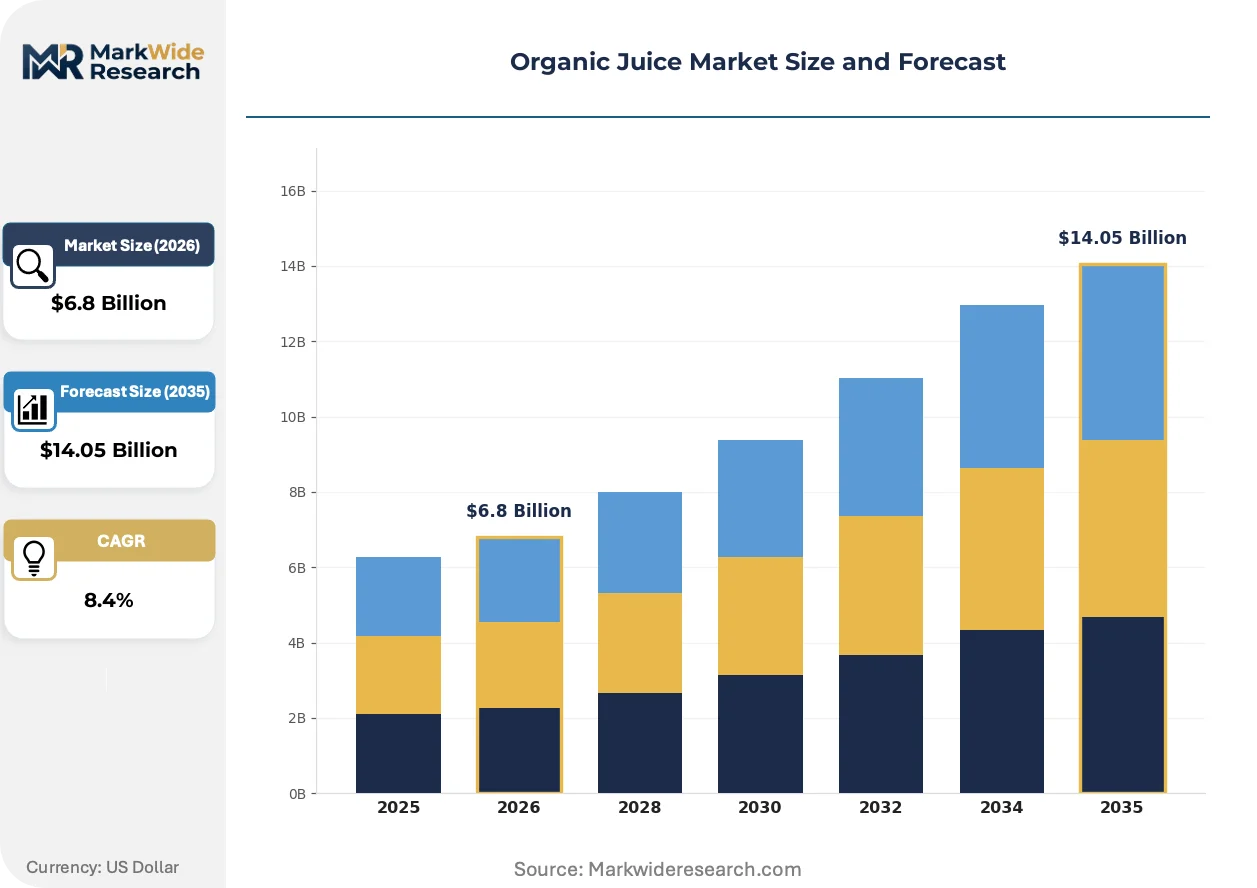
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold-Pressed, High-Pressure Processed, Puree, Concentrate Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Direct Sales Packaging Type: Bottles, Tetra Packs, Cans, Pouches Customer Type: Health-Conscious Consumers, Fitness Enthusiasts, Families, Culinary Professionals |
| Companies Covered | Suja Life LLC, Hain Celestial Group, Danone S.A., The Coca-Cola Company, PepsiCo, Inc., Parkers Organic Juices PTY LTD, Nestlé S.A., Uncle Matt's Organic, Knudsen Family, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Juice Market Strategic Shifts
Cold-pressed processing architectures are reshaping competitive positioning as enzyme preservation becomes a non-negotiable quality signal for premium buyers. Regulatory documentation burdens and perishable logistics constraints are simultaneously forcing capital allocation decisions across the value chain.
High-pressure processing is supplanting thermal pasteurization in mainstream supermarket penetration strategies. Retail buyers at conventional grocers are adopting HPP-stabilized formats to extend shelf life without the nutrient degradation associated with heat treatment. This shift is compressing the addressable market for refrigerated-only cold-pressed specialists while opening volume tiers previously inaccessible to organic juice.
EU Organic Regulation 2018/848 is tightening pesticide residue thresholds for import eligibility into European supply chains. German and French retailers are demanding batch-level documentation that exceeds prior certificate-based compliance. Processors with integrated organic certification from seed to bottle are capturing preferred vendor status while co-dependent importers face exclusion.
Subscription-based procurement is displacing conventional retail stocking for fitness enthusiasts and culinary professionals. Weekly delivery direct from bottlers eliminates slotting fees and expiration risk for high-velocity households in New York and California metropolitan corridors. This channel rotation is fragmenting volume concentration away from Whole Foods Market and Sprouts Farmers Market toward owned-commerce platforms.
Organic Juice Market Segmentation
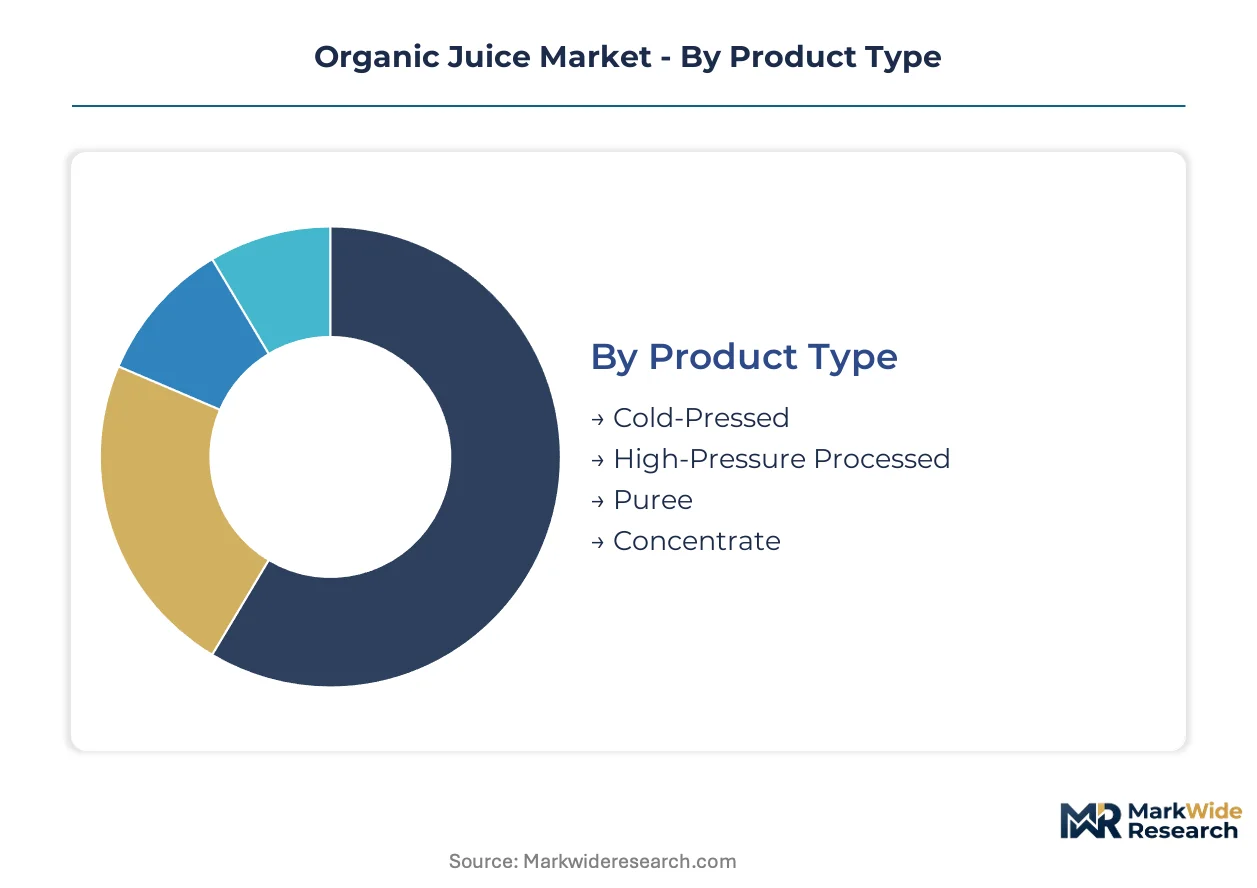
Organic juice segmentation reveals divergent margin structures across processing technologies and channel economics. Cold-pressed formats command premium shelf positioning while high-pressure processed variants unlock mainstream supermarket penetration through extended shelf stability.
Product Type:
Premium margin pools concentrate in enzyme-preserving formats that justify refrigerated logistics investments and shorter shelf-life positioning.
- Cold-Pressed:Extracted through hydraulic pressure below 45°C without thermal degradation, preserving polyphenol and enzyme activity. Demand concentrates in California and New York metropolitan corridors where health-conscious consumers pay substantial premiums for perceived nutritional integrity.
- High-Pressure Processed:Subjected to isostatic pressure at ambient temperature to eliminate pathogens while retaining fresh flavor profiles. Supermarket buyers in conventional retail channels are accelerating procurement of HPP-stabilized formats to reduce shrinkage from expired cold-pressed inventory.
- Puree:Retains fiber content through minimal filtration, serving smoothie preparation and infant nutrition applications.
- Concentrate:Water-reduced format for cost-sensitive foodservice and private-label manufacturing.
The dominant share belongs to Cold-Pressed, while High-Pressure Processed is closing the gap fastest.
Distribution Channel:
Channel selection determines working capital intensity through slotting fee exposure and inventory velocity requirements.
- Supermarkets:Conventional grocery chains demand extended shelf-life formats and promotional funding commitments. Retail consolidation in the United States is compressing supplier counts as category managers prioritize SKUs with proven household penetration metrics.
- Health Food Stores:Independent and regional chains emphasize local sourcing narratives and raw unpasteurized offerings. These outlets capture fitness enthusiasts seeking unprocessed alternatives absent from conventional juice aisles.
- Online Retail:Subscription models and direct-to-consumer platforms bypass traditional distributor markups.
- Direct Sales:Farmers market presence and juice bar co-location drive impulse trial among urban professionals.
Supermarkets retain volume leadership, though Online Retail is expanding most quickly through subscription-based household penetration.
Packaging Type:
Material selection balances oxygen barrier performance against sustainability positioning and transportation economics.
- Bottles:PET and glass formats dominate refrigerated cold-pressed presentation, with premium brands favoring amber glass for UV protection.
- Tetra Packs:Aseptic carton technology enables ambient distribution of HPP and concentrate formats, reducing cold-chain dependency for rural penetration.
- Cans:Aluminum formats gain traction in fitness-oriented positioning through portability and recycling credentials.
- Pouches:Flexible packaging serves single-serve children's segments and foodservice portion control.
Bottles command the installed base, while Tetra Packs are gaining share fastest through ambient distribution cost advantages.
Customer Type:
End-user differentiation separates occasion-based consumption from ingredient-forward purchasing behavior.
- Health-Conscious Consumers:Households prioritizing organic certification and clean label positioning drive cold-pressed premiumization. These buyers concentrate in coastal metropolitan markets with above-median disposable income and wellness infrastructure density.
- Fitness Enthusiasts:Athletes and gym members demand post-workout recovery formulations with specific electrolyte and protein adjuncts. This segment is accelerating adoption of functional infusions combining organic juice bases with adaptogenic and probiotic ingredients.
- Families:Multi-person households prioritize value-oriented formats and child-friendly flavor profiles.
- Culinary Professionals:Restaurant and catering buyers source puree and concentrate formats for sauce bases and cocktail programs.
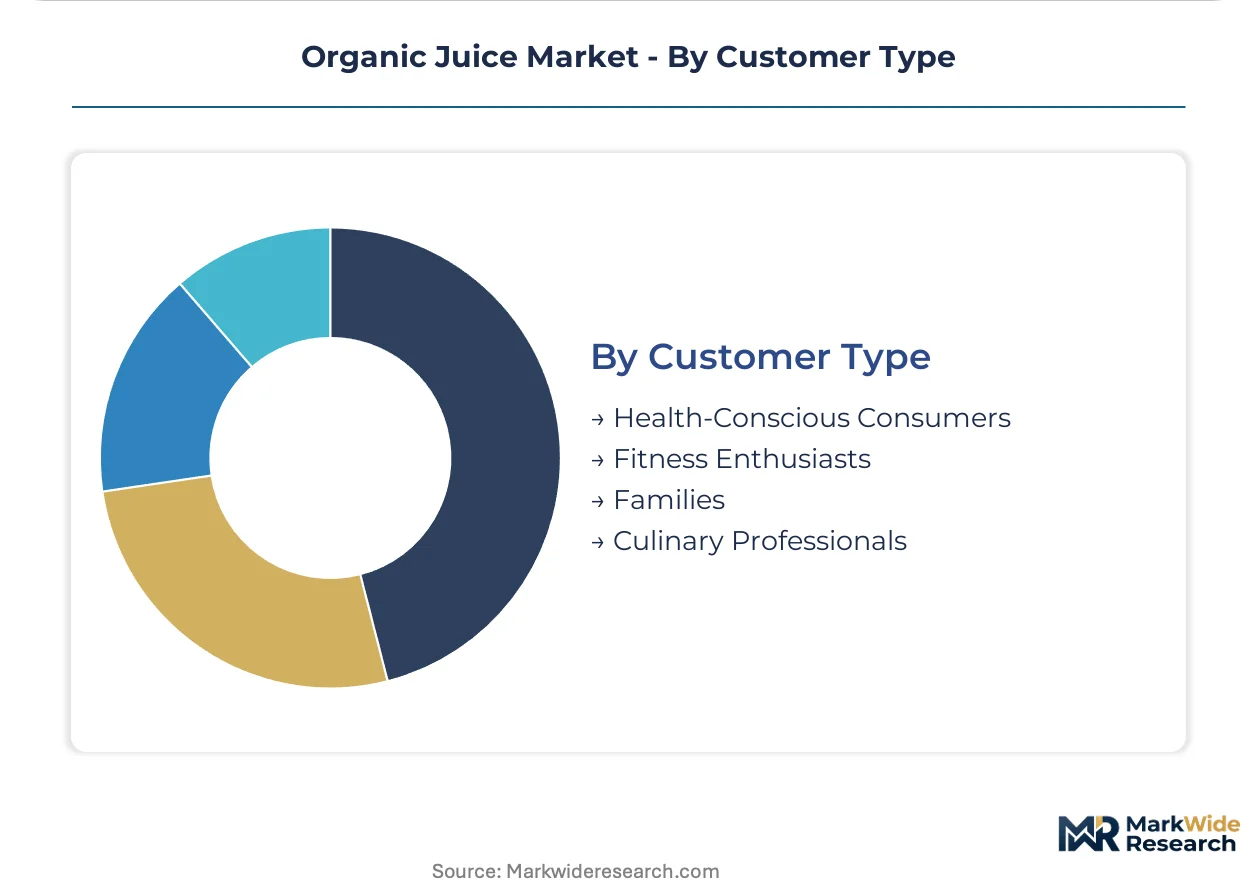
Health-Conscious Consumers anchor category value, while Fitness Enthusiasts are climbing the fastest through functional ingredient convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious consumers in coastal metropolitan corridors concentrate demand for enzyme-preserving formats, while regulatory documentation requirements diverge across certification regimes. Cold-pressed specialists and HPP-stabilized processors navigate distinct compliance landscapes from seed to shelf.
United States
California and New York metropolitan retail corridors anchor category volume through premium grocery channel penetration. The USDA National Organic Program mandates 36-month transition periods for chemical-free cultivation documentation. Central Valley citrus and leafy green clusters shorten raw material transit windows for West Coast processors.
Germany
Discerning buyers in Berlin and Hamburg metropolitan areas prioritize batch-level traceability exceeding certificate-based compliance. EU Organic Regulation 2018/848 tightens pesticide residue thresholds for import eligibility into German retail supply chains. Bavarian organic distributors capture preferred vendor status through integrated certification from seed to bottle.
France
Parisian health food stores and culinary professionals drive demand for raw unpasteurized offerings absent from conventional juice aisles. ANSM and DGCCRF enforcement of EU organic fraud regulations intensifies documentation scrutiny at port of entry. Provence-Alpes-Côte d'Azur agricultural cooperatives supply Mediterranean citrus inputs to regional bottlers.
United Kingdom
London and Southeast England fitness enthusiasts accelerate adoption of functional infusions combining organic juice bases with adaptogenic ingredients. The UK Department for Environment, Food and Rural Affairs enforces equivalence agreements with USDA organic standards for transatlantic trade. Midlands-based cold-pressed specialists leverage subscription delivery models to bypass supermarket slotting fees.
Australia
Sydney and Melbourne metropolitan households demonstrate above-median willingness to pay for perceived nutritional integrity in enzyme-preserving formats. Australian Certified Organic and NASAA accreditation requirements parallel USDA documentation stringency for export market access. Queensland citrus belt suppliers face seasonal input bottlenecks during transition windows to Victorian processing facilities.
Organic Juice Market Competitive Environment
Player mix skews toward diversified beverage conglomerates with refrigerated distribution infrastructure and cold-pressed specialists with captive organic supply. Market structure exhibits tiered consolidation with multinational CPG anchors commanding mainstream supermarket placements and regional bottlers occupying premium health channel niches. Strategic archetypes include vertically integrated agricultural operators, co-packing dependent regional brands, and direct-to-consumer subscription platforms. Dominant competitive moves encompass exclusive retail shelf space agreements and backward integration into certified organic acreage.
Among multinational beverage anchors, Danone S.A. and The Coca-Cola Company exemplify scale-driven refrigerated network leverage, while Suja Life LLC occupies a position within the premium cold-pressed specialist tier. Uncle Matt's Organic represents the citrus-forward flavor differentiation archetype, and Parkers Organic Juices PTY LTD anchors the Australia-Pacific regional concentration. Hain Celestial Group and Nestlé S.A. sit within the diversified natural products portfolio segment, with PepsiCo, Inc. exemplifying mainstream channel penetration strategies. Knudsen Family represents legacy organic heritage positioning in family-owned structure.
| Leading Market Players |
|---|
| Suja Life LLC |
| Hain Celestial Group |
| Danone S.A. |
| The Coca-Cola Company |
| PepsiCo, Inc. |
| Parkers Organic Juices PTY LTD |
| Nestlé S.A. |
| Uncle Matt's Organic |
| Knudsen Family |
| Others |
Value Chain & Pricing Dynamics
Cold-pressed substitution for thermally pasteurized formats is simultaneously relocating processing capacity toward California and New York metropolitan corridors and compressing margin structures for distributors unable to secure refrigerated logistics partnerships. This input-format shift redraws procurement economics as enzyme-preserving variants command premium positioning while high-pressure processed alternatives unlock mainstream supermarket penetration through extended shelf stability.
Pricing Analysis
Cost-plus contracts indexed to organic citrus futures dominate procurement between Florida and Central Valley growers and West Coast bottlers. Price differentiation hinges on USDA Organic certification tier and cold-chain delivery distance, with health-conscious coastal households showing lowest sensitivity. Pricing pressure stems from perishable logistics costs compressing margins on distribution runs exceeding 48 hours. Families and foodservice buyers represent the most price-sensitive segments, prioritizing concentrate and Tetra Pack formats.
Supply Chain Analysis
Florida Strait maritime transit underwrites seasonal citrus imports to East Coast processors, creating vulnerability during hurricane windows. Geographic supply concentrates in the United States, Mexico, and Spain for organic citrus inputs. Raw material dependencies rest on certified organic acreage, cold-chain refrigerated transport, and high-pressure processing equipment. Tariff exposure on Mexican organic citrus concentrates threatens margin stability. Distribution runs through refrigerated third-party logistics networks serving premium grocery channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as functional beverage infusions combining adaptogens with organic juice bases capture fitness enthusiast wallets. Plant-based protein and enhanced water formats threaten to displace conventional juice occasions.
For Market Incumbents: Compound defensive moats through backward integration into certified organic acreage in California and Florida, securing 36-month USDA transition documentation before competitor procurement. Expand captive high-pressure processing capacity to serve conventional supermarket buyers seeking shelf-stable formats. Counter functional beverage substitution threats by accelerating probiotic and adaptogenic SKU development.
For New Entrants and Emerging Players: Anchor in direct-to-consumer subscription models bypassing Whole Foods Market slotting fee barriers, targeting New York and California metropolitan fitness enthusiasts. Exploit white-space in online retail channel penetration where incumbent refrigerated network investments offer no advantage. Pursue weekly delivery cadence with batch-level traceability documentation exceeding certificate-based compliance.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated bottlers with captive agricultural supply and in-house USDA Organic certification infrastructure. Long-term viability favors processors controlling seed-to-bottle documentation rather than co-packing dependent regional brands. Monitor EU Organic Regulation 2018/848 import eligibility enforcement as inflection signal for transatlantic export opportunity capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Acreage | Captive supply secures 36-month USDA transition documentation and insulates against feedstock volatility. |
| Direct-to-Consumer Subscription Launch | Weekly delivery models bypass slotting fees and capture fitness enthusiast households in coastal metros. |
| High-Pressure Processing Capacity Addition | In-house HPP equipment unlocks conventional supermarket placements previously inaccessible to cold-pressed specialists. |
| Functional Ingredient Convergence | Probiotic and adaptogenic infusions open wellness-positioned SKUs adjacent to conventional juice aisles. |
| EU Organic Regulation 2018/848 Compliance Investment | Batch-level traceability documentation captures preferred vendor status with German and French retailers. |
Study Parameters
Desk research of USDA National Organic Program certification databases, FDA juice HACCP guidance documents, and EU Organic Regulation 2018/848 implementation notices preceded structured interviews with cold-pressed bottler operations directors, premium grocery category buyers, refrigerated logistics providers, and organic citrus growers. Secondary validation drew from customs trade records, agricultural acreage reports, and retail audit data. Bottom-up volume modeling triangulated against top-down category spend estimates.
Variance decomposition across processing technology, distribution channel, and customer type segments shaped the analytical framework over the projection horizon. Modeled dimensions included cold-pressed versus high-pressure processed formats, supermarket versus online retail channels, and health-conscious versus fitness enthusiast buyer archetypes. CAGRs derived from segment-level growth rate reconciliation with macroeconomic consumption indicators and organic certification penetration curves.
Material uncertainties — EU pesticide residue threshold revisions, organic fraud enforcement intensity, and cold-chain logistics cost inflation — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding certification timeline compliance and metropolitan demand concentration. Practitioners should keep alternative scenarios live as regulatory documentation requirements and substitute beverage format innovation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Organic Soda Market
Organic Food and Beverages
Organic Ice Cream Market
Organic Food and Beverages
Organic Dry Yeast Market
Organic Food and Beverages
Organic Food and Beverages Market
Organic Food and Beverages
Organic Honey Market
Organic Food and Beverages
Asia-Pacific Organic Food Market
Organic Food and Beverages
Organic Pasta Market
Organic Food and Beverages
India Organic Food Market
Organic Food and Beverages
Organic Maple Syrup Market
Organic Food and Beverages
Saudi Arabia Organic Food Market
Organic Food and Beverages
South Africa Organic Food Market
Organic Food and Beverages
Organic Soy Products Market
Organic Food and Beverages
Global Organic Chocolate Spreads Market
Organic Food and Beverages
South Korea Organic Food Market
Organic Food and Beverages
Organic Fruit Powder Market
Organic Food and Beverages
UK Organic Food Market