
 Hot Beverages Market | 2026-2036
Hot Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Hot Beverages Market Intelligence
Specialty store distribution is rewriting competitive access in premium hot beverages. Nestlé leverages its Nespresso boutique network to control high-margin capsule experiences in major metropolitan markets. Lavazza anchors Italian espresso heritage through flagship retail locations that double as brand education centers. Starbucks competes via Reserve Roastery concepts that merge roasting transparency with direct-to-consumer engagement.
Hot beverages encompass brewed, steeped, or dissolved drinks consumed above 60°C, typically derived from roasted seeds, dried leaves, cacao solids, or botanical extracts processed through fermentation, oxidation, or roasting protocols. Their commercial purpose spans functional stimulation, social ritual, and wellness positioning across institutional and retail channels. Coffee commands the largest revenue pool within product type segmentation, while matcha and herbal infusions represent the fastest-expanding margin categories as wellness positioning intensifies. Morning consumption occasion still generates the highest volume throughput, though afternoon break and post-meal occasions are capturing premium pricing through portion-controlled formats.
FDA food safety standards and USDA organic certification govern product composition and labeling claims in the United States, while the EU Green Deal and EFSA health claim regulations shape sustainable sourcing and permitted marketing language across European markets. These frameworks elevate compliance costs for smaller traders but create protected market access for certified operators. Stakeholders must monitor evolving carbon border adjustments and deforestation-free supply chain mandates that will determine sourcing viability for coffee and tea procurement networks.
Market Dynamics
The EU Green Deal's deforestation-free supply chain mandates are forcing wholesale restructuring of coffee and tea procurement networks, with compliance costs filtering down to certified operators while excluding uncertified traders from European market access.
Growth Catalysts
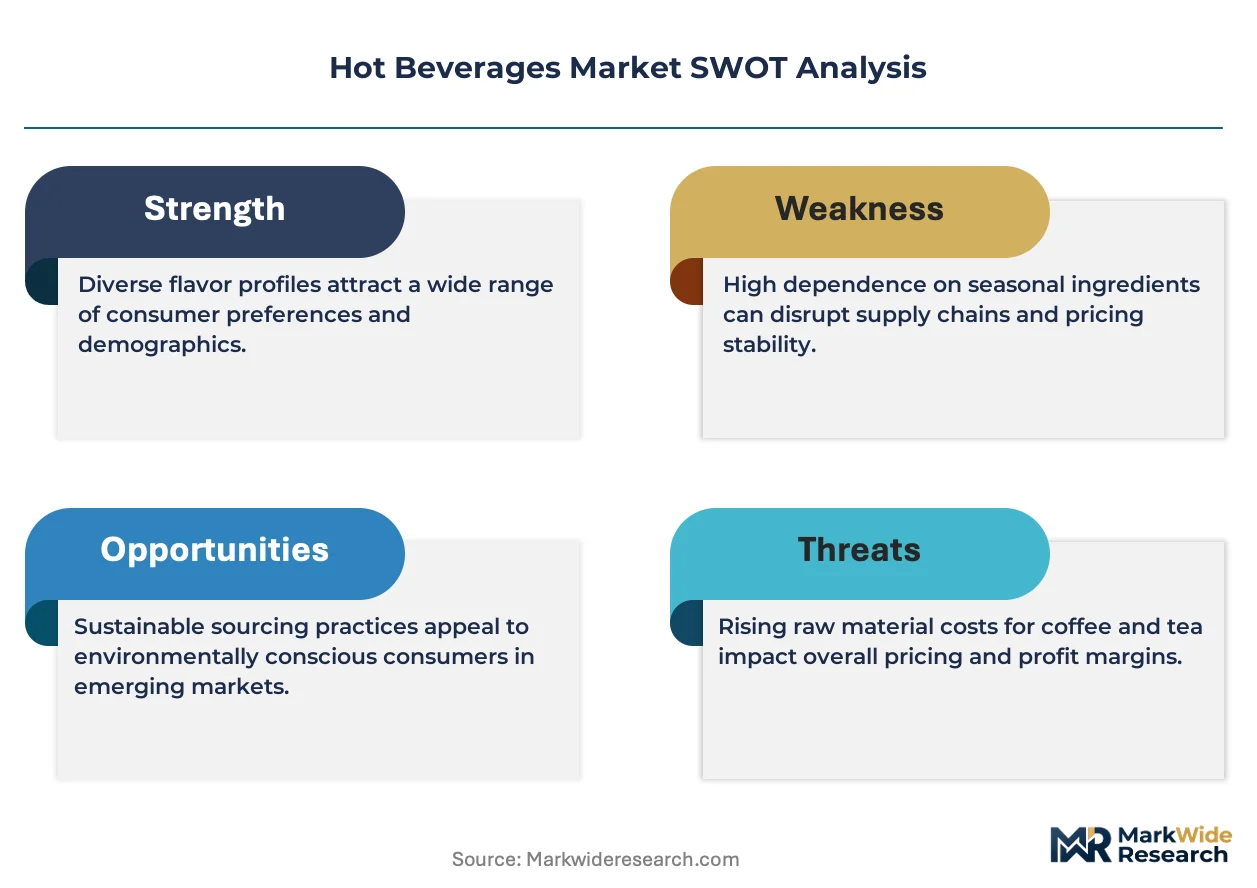
- EU Green Deal agricultural standards:Certification requirements for sustainable sourcing create protected market access for compliant operators across European distribution channels.
- Specialty cafe proliferation:Premium brewing experiences in urban centers deepen consumer engagement and expand margin capture through direct-to-consumer formats.
- Young professional demand clusters:Coffee consumption acceleration among professionals in Shanghai and Beijing intersects with traditional tea culture to expand total addressable occasions.
Market Restraints
- Arabica price volatility:Climate-induced harvest variability in Brazilian highland regions compresses roasting margins and destabilizes forward contracting.
- Input concentration risk:Vietnam and Brazil collectively dominate robusta and arabica output, creating systemic supply vulnerability to regional weather shocks.
- Energy-intensive roasting:Natural gas dependence in drum roasting operations exposes processors to utility cost spikes without short-term substitution pathways.
Strategic Opportunities
- Carbon border adjustment positioning:Early compliance with EU carbon border mechanisms creates first-mover advantage in premium European retail channels.
- Botanical extract convergence:Functional ingredient pairing of adaptogens with traditional coffee and tea bases opens wellness-positioned product lines.
- At-home brewing system penetration:Capsule and automated pour-over devices in underpenetrated Southeast Asian urban households expand recurring revenue pools.
Industry Challenges
- Q-grader talent scarcity:Certified cupping specialists capable of origin differentiation command premium wages that strain mid-size roaster economics.
- Organic certification timelines:Three-year conversion periods for conventional farmland lock supply growth behind demand expansion in certified segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot Beverages Market |
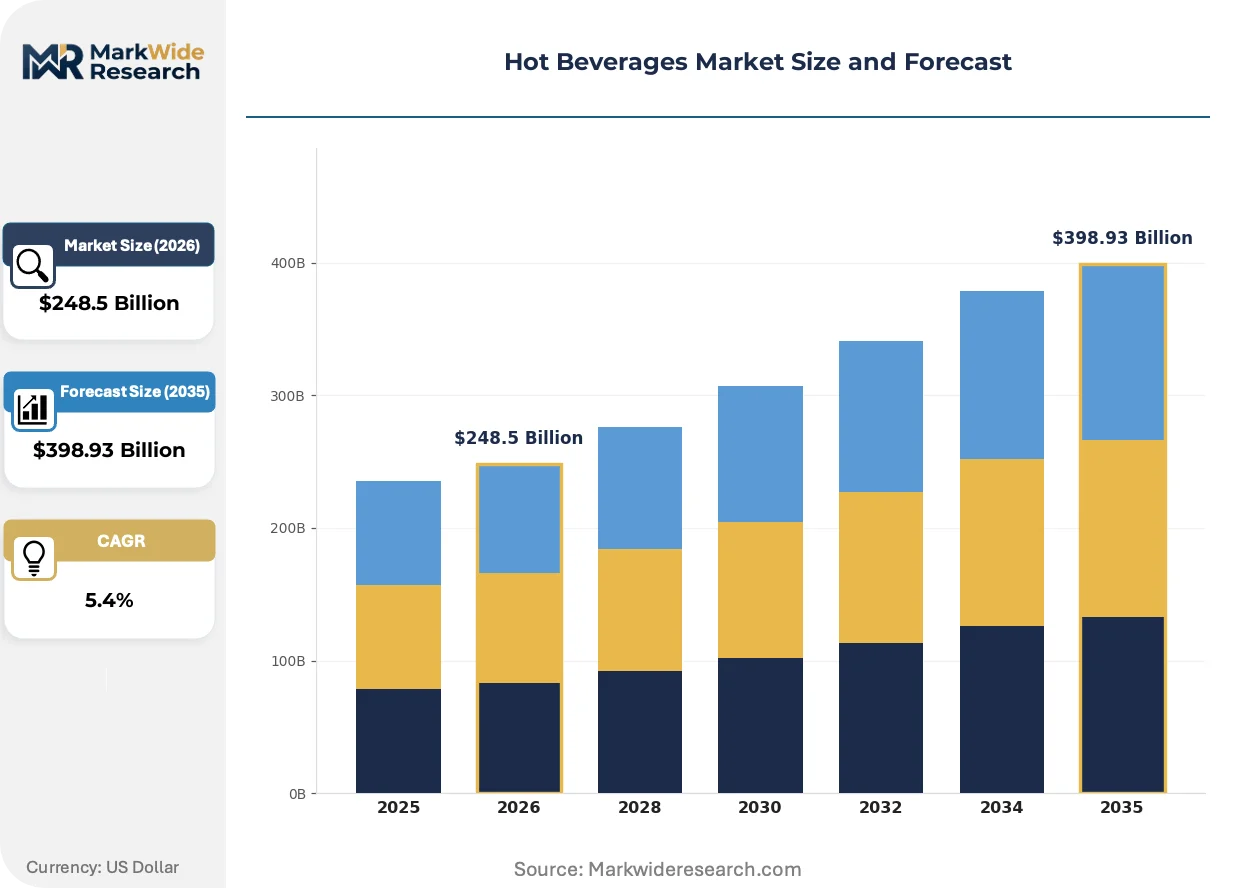
| Market Size in 2026 | $248.5 Billion |
| Market Size in 2035 | $398.93 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coffee, Tea, Hot Chocolate, Herbal Infusions, Chai, Matcha Consumption Occasion: Breakfast, Afternoon Break, Evening Relaxation, Social Gathering, Office Hours, Post-Meal Consumer Demographic: Millennials, Generation X, Baby Boomers, Seniors, Students, Young Professionals Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Stores, Cafes, Vending Machines |
| Companies Covered | Lavazza, Twinings, Nestlé, Carte Noire, Tetley, Starbucks, Lipton, Clipper, Keurig Dr Pepper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot Beverages Market Strategic Shifts & Innovations
Automation and regulatory transparency are compressing traditional value chain steps while wellness positioning redefines product formulation boundaries across hot beverage categories.
Cold brew concentration systems are rendering obsolete conventional hot-extraction methods for ready-to-drink applications. Mid-size roasting operations in North American metropolitan markets are adopting nitrogen-infused cold brewing at accelerating pace. This shift is compressing capital requirements for beverage-grade extraction while expanding shelf-stable product lines.
EFSA health claim regulations are restricting permissible marketing language for functional tea and coffee positioning across European markets. The framework elevates substantiation burdens for adaptogen and antioxidant claims while standardizing permissible caffeine content disclosures. Wellness-positioned brands are responding by reformulating around EFSA-approved botanical extracts with established safety dossiers.
Subscription-based replenishment models are displacing traditional grocery channel purchasing for premium at-home consumption. Direct-to-consumer platforms in urban Chinese markets are capturing recurring revenue through personalized roast profiles and predictive shipping algorithms. This behavioral shift concentrates customer data ownership with platform operators while fragmenting traditional wholesale relationships.
Hot Beverages Market Segmentation
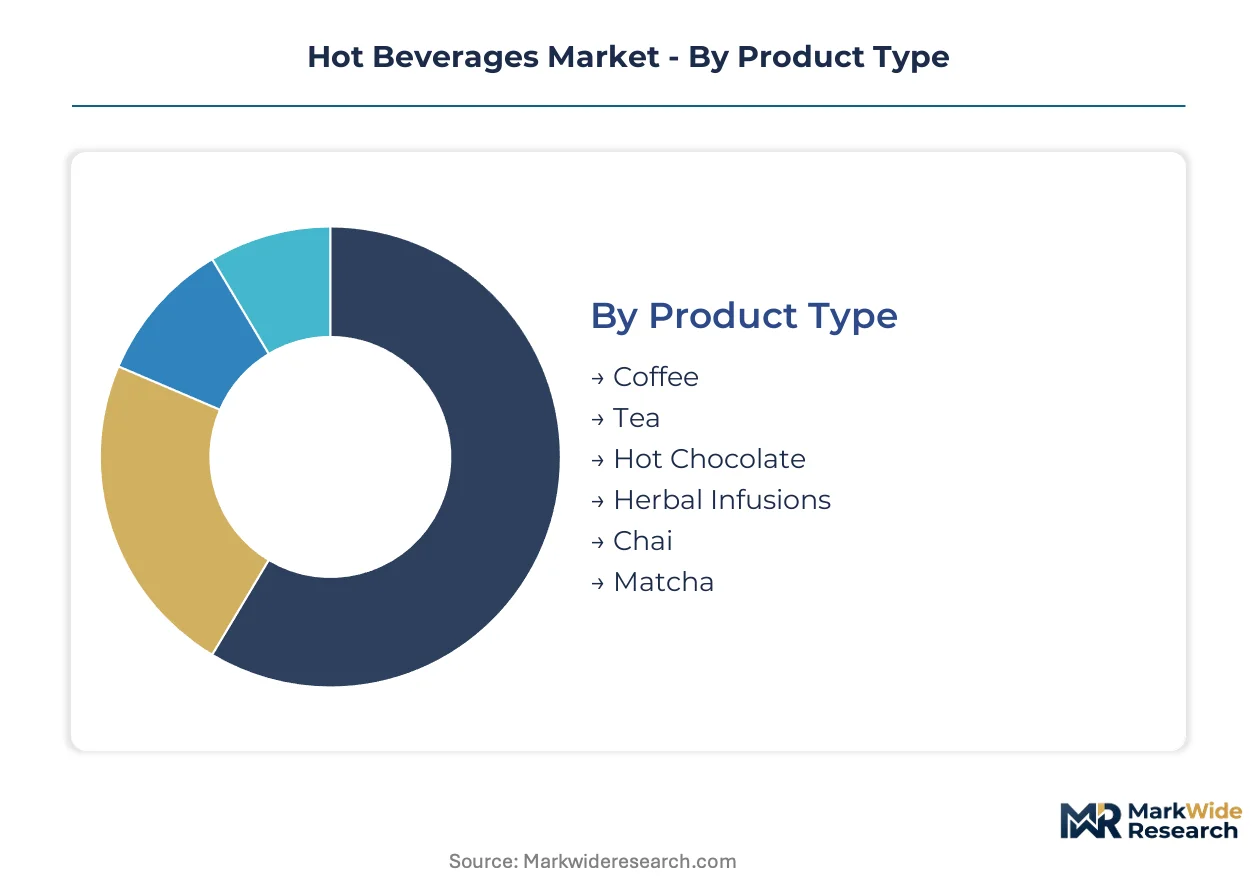
Hot beverage segmentation reveals how consumption rituals, generational preferences, and channel access reshape competitive positioning across distinct value pools. Manufacturers align formulation, packaging, and pricing architectures to capture occasion-specific demand while navigating divergent regulatory and retail environments.
Product Type:
Cost tier differentiation separates commodity-grade offerings from certified premium lines, with functional positioning commanding measurable price premiums across retail and foodservice channels.
- Coffee:Roasted arabica and robusta beans processed through drum or fluid bed roasting protocols generate the largest revenue concentration within the category. Demand clusters in Shanghai and Beijing among young professionals, where specialty cafe proliferation intersects with at-home capsule system adoption.
- Tea:Camellia sinensis leaves processed through oxidation, fermentation, or steaming protocols span black, green, oolong, and white varietals. Traditional consumption in China sustains volume leadership while EU Green Deal certification requirements reshape European sourcing specifications for certified supply chains.
- Hot Chocolate:Cacao solids combined with dairy or plant-based milk formulations target family and indulgence occasions.
- Herbal Infusions:Botanical extracts without Camellia sinensis content, including chamomile, peppermint, and rooibos, expand wellness-positioned portfolios.
- Chai:Spiced black tea blends with cardamom, cinnamon, and ginger anchor South Asian consumption traditions and Western specialty cafe menus.
- Matcha:Stone-ground shade-grown green tea powder delivers concentrated antioxidant positioning and ceremonial consumption rituals.
Coffee holds installed capacity. Matcha is rotating up the share rankings.
Consumption Occasion:
Application timing determines volume throughput versus margin capture, with morning occasions driving scale and post-meal segments enabling premium pricing through portion-controlled formats.
- Breakfast:The highest-volume consumption window generates recurring daily demand across household and foodservice channels. Volume concentrates in urban Chinese markets where coffee accelerates among professionals while traditional tea maintains household penetration.
- Afternoon Break:Workplace and cafe-based consumption creates premium pricing opportunities through single-serve and specialty formats. Specialty store distribution in metropolitan markets deepens engagement through direct-to-consumer brewing experiences.
- Evening Relaxation:Decaffeinated and botanical formulations target wind-down rituals with functional wellness positioning.
- Social Gathering:Cafe and hospitality settings drive experiential consumption with elevated margin structures.
- Office Hours:Institutional brewing systems and vending formats capture recurring workplace demand.
- Post-Meal:Digestive and premium positioned offerings command price premiums through reduced portion sizes.
Breakfast holds installed capacity. Afternoon Break is rotating up the share rankings.
Consumer Demographic:
Customer type stratification aligns product innovation with generational beverage rituals, from traditional tea culture among older cohorts to coffee experimentation among urban professionals.
- Millennials:Digital-native consumers aged 28-43 drive subscription replenishment and specialty cafe engagement. Demand clusters in Chinese tier-1 cities where personalized roast profiles and predictive shipping algorithms capture recurring revenue.
- Generation X:Mid-career professionals balance convenience-oriented at-home brewing with premium out-of-home occasions.
- Baby Boomers:Established consumption patterns favor traditional tea and conventional coffee formats with brand loyalty.
- Seniors:Decaffeinated and wellness-positioned botanicals align with health-conscious consumption restrictions.
- Students:Price-sensitive demand concentrates in instant and vending-machine accessible formats.
- Young Professionals:Urban cohorts in Shanghai and Beijing accelerate coffee adoption while maintaining tea consumption for client entertainment.
Millennials hold installed capacity. Young Professionals is rotating up the share rankings.
Distribution Channel:
Channel geography determines margin architecture and consumer data ownership, with direct formats capturing premium pricing while traditional retail maintains volume scale.
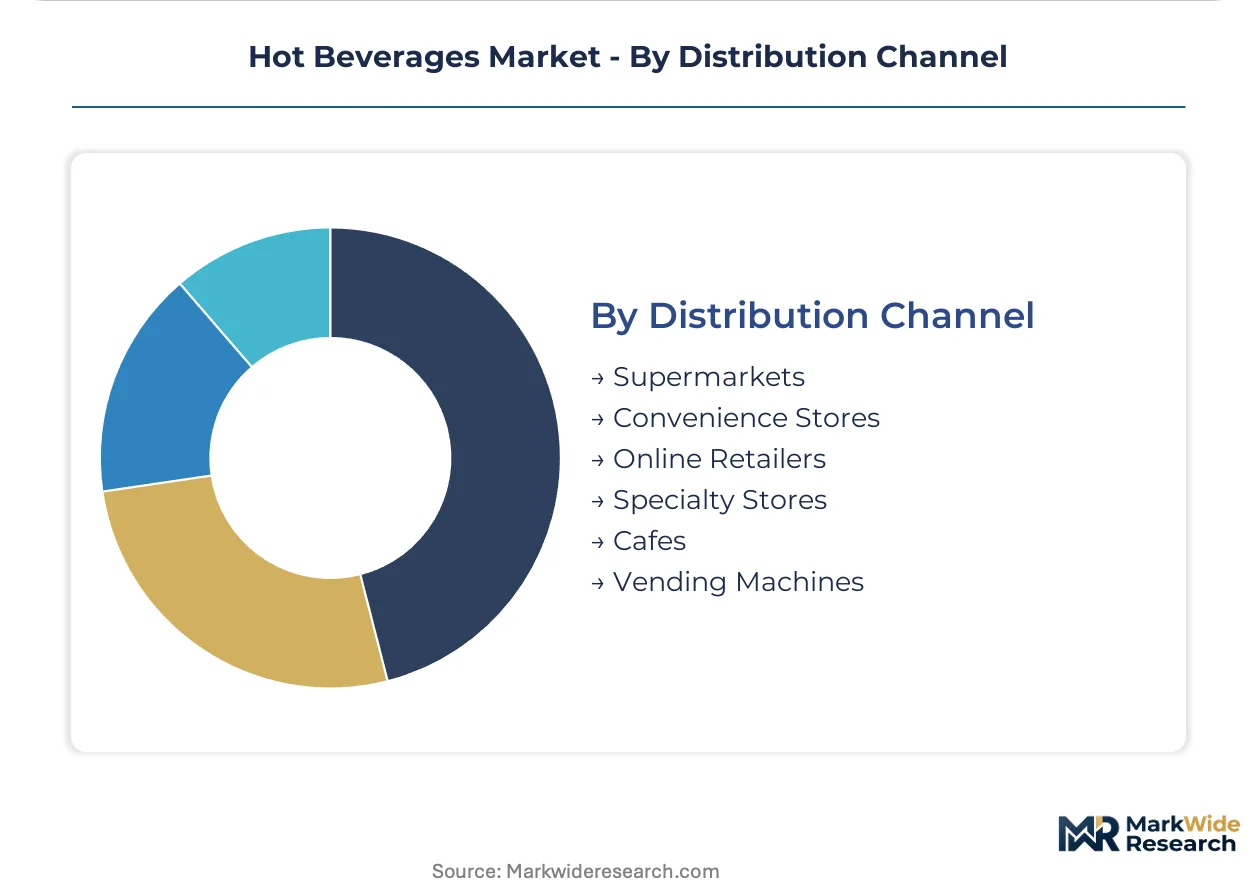
- Supermarkets:Mass-market retail generates volume throughput for commodity and mid-tier packaged offerings. Shelf space competition intensifies as private-label lines expand across European and North American markets.
- Specialty Stores:Boutique retail formats control high-margin capsule experiences and origin-differentiated whole bean sales. Nespresso and Lavazza anchor metropolitan networks that double as brand education centers.
- Convenience Stores:Immediate consumption and grab-and-go formats capture impulse demand in urban transit corridors.
- Online Retailers:Direct-to-consumer platforms fragment traditional wholesale relationships through personalized replenishment algorithms.
- Cafes:Out-of-home experiential consumption enables margin capture through brewing transparency and social ritual positioning.
- Vending Machines:Automated formats serve institutional and transit environments with limited service requirements.
Supermarkets hold installed capacity. Specialty Stores is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in European metropolitan markets where EU Green Deal certification creates protected access, while volume scale accumulates in Chinese urban centers where young professionals accelerate coffee adoption alongside traditional tea rituals.
China
Shanghai and Beijing drive coffee consumption acceleration among young professionals, with specialty cafe proliferation deepening engagement through direct-to-consumer brewing experiences. SAMR food safety standards and dual carbon goals reshape sustainable sourcing requirements for certified supply chains. The Yangtze River Delta anchors capsule system manufacturing and predictive replenishment platform development.
Germany
Specialty store distribution networks control high-margin capsule experiences in metropolitan markets, with flagship retail locations doubling as brand education centers. EU Green Deal deforestation-free mandates and EFSA health claim regulations elevate compliance costs while protecting certified operators. Bavaria and North Rhine-Westphalia concentrate drum roasting operations vulnerable to natural gas cost volatility.
United States
Morning breakfast occasions generate the highest volume throughput across household and foodservice channels, with subscription replenishment models displacing traditional grocery purchasing. FDA food safety standards and USDA organic certification govern product composition and labeling claims. The Pacific Northwest and Greater Boston metropolitan markets accelerate nitrogen-infused cold brewing adoption among mid-size roasting operations.
Japan
Traditional tea culture sustains ceremonial consumption rituals while matcha powder delivers concentrated antioxidant positioning for wellness segments. METI industrial standards and JIS quality frameworks standardize processing protocols for export-grade products. The Kanto region around Tokyo anchors premium at-home brewing system penetration and automated pour-over device distribution.
Brazil
Arabica production from highland regions faces climate-induced harvest variability that compresses roasting margins and destabilizes forward contracting. The national agricultural regulator enforces phytosanitary export standards aligned with EU and US market access requirements. Minas Gerais and São Paulo states concentrate processing infrastructure for origin-differentiated whole bean exports.
Hot Beverages Market Key Industry Players
Vertically integrated multinationals and specialty-focused regional players split the market between scale-driven commodity coverage and margin-capturing premium experiences. Consolidation pressure intensifies as compliance costs for EU Green Deal certification and FDA organic standards favor capital-heavy operators with dedicated regulatory affairs capabilities. Three archetypes dominate: heritage European houses with roasting expertise, North American platform operators with subscription infrastructure, and Asian market specialists with localized supply chain control. Competitive moves concentrate on strategic partnerships for sustainable sourcing certification and portfolio diversification into functional botanical extracts.
Within the heritage European tier, Lavazza and Twinings exemplify brand equity built through generational roasting expertise and controlled retail distribution. Nestlé occupies a position bridging mass-market scale and premium capsule experiences through metropolitan boutique networks. These three entities represent how origin storytelling and certification compliance create protected market access across divergent regulatory environments.
| Leading Market Players |
|---|
| Lavazza |
| Twinings |
| Nestlé |
| Carte Noire |
| Tetley |
| Starbucks |
| Lipton |
| Clipper |
| Keurig Dr Pepper |
| Others |
Cost & Logistics Intelligence
Vietnamese and Brazilian arabica and robusta concentration upstream funnels margin capture toward certified European roasters and metropolitan specialty retail networks downstream. EU Green Deal deforestation-free mandates filter procurement toward compliant operators, compressing uncertified traders into spot-market volatility while premium capsule formats extract value in Shanghai, Beijing, and Berlin.
Pricing Analysis
The customization-premium spread separates configured-to-order origin-differentiated whole bean offerings from standard commodity-grade packaged lines. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and brand heritage, with EU organic and Fairtrade tiers commanding measurable premiums over conventional alternatives. Cost compression in commodity arabica is intensifying because climate-induced harvest variability in Brazilian highland regions destabilizes forward contracting. Students and price-sensitive household segments exhibit highest price sensitivity, while young professionals in Chinese tier-1 cities show lowest sensitivity to premium single-serve formats.
Supply Chain Analysis
Contract-manufacturing concentration for capsule systems rests on Nestlé's proprietary foundry network and Keurig Dr Pepper's licensed production partnerships across North American and European facilities. Raw material flows draw from Vietnamese robusta plantations, Brazilian arabica highlands, and Kenyan specialty micro-lots, with botanical extracts for functional infusions sourcing from Indian and Sri Lankan organic conversions. Single-source vulnerability concentrates in Brazilian climate exposure for arabica volume. Distribution runs through supermarket chains for mass-market throughput, specialty boutiques for margin capture, and direct-to-consumer platforms for recurring subscription revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against ready-to-drink cold brew and functional wellness beverages that capture afternoon consumption occasions outside traditional hot preparation rituals.
For Market Incumbents: Pre-empt capsule commoditization by locking exclusive origin partnerships with certified Vietnamese and Brazilian cooperatives before EU Green Deal compliance deadlines exclude uncertified competitors. Reinforce metropolitan boutique networks in Shanghai and Berlin as brand education moats against private-label encroachment. Vertical integration into cold brew concentration systems captures ready-to-drink substitution demand.
For New Entrants and Emerging Players: Southeast Asian urban households outside Jakarta and Manila present the most penetrable white-space for automated pour-over and capsule system adoption among emerging middle-class consumers. Functional botanical extract pairings with traditional coffee bases offer wellness-positioned entry with lower certification barriers than commodity arabica procurement. Direct-to-consumer predictive replenishment algorithms bypass entrenched wholesale relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward heritage European houses with generational roasting expertise and established EU Green Deal certification compliance across the medium-term horizon. Acquisition targets should demonstrate captive supply relationships with certified origin cooperatives and controlled metropolitan retail footprints. The signal to watch is Q-grader talent scarcity compression that elevates mid-size roaster operating costs and accelerates consolidation toward capital-heavy operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Sustainability Certification Program | EU Green Deal compliance creates protected market access across German and French retail channels. |
| Direct-to-Consumer Platform Launch | Predictive replenishment algorithms capture recurring revenue from millennial subscribers in Chinese tier-1 cities. |
| Functional Product Line Extension | Adaptogen pairing with coffee bases opens wellness-positioned pricing in Japanese and North American markets. |
| Specialty Retail Footprint Expansion | Flagship locations in Shanghai and Berlin double as brand education centers against private-label competition. |
| Backward Integration into Origin Supply | Certified cooperative partnerships lock deforestation-free sourcing ahead of regulatory exclusion timelines. |
Research Approach
A standing panel of specialty roasting operations managers, EU regulatory affairs leads, supermarket category buyers, and direct-to-consumer platform operators provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from FDA food safety filings, EFSA health claim registers, SAMR standards documentation, and customs trade data for coffee and tea imports. Bottom-up volume modeling across consumption occasions and top-down macroeconomic triangulation anchored projections.
Scenario-bracketing framed analytical outputs across the projection horizon, with sensitivity testing for arabica price volatility and EU carbon border adjustment implementation timing. Segmentation dimensions modeled include product type, consumption occasion, consumer demographic, and distribution channel, with regional regulatory cluster as an additional cross-cutting variable. CAGRs derived from historical trajectory analysis and forward-looking adoption curve fitting, incorporating Q-grader labor scarcity and organic certification conversion timelines as industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Asian market specialists or platform-native subscription operators would shift outcomes beyond modeled ranges. Quarterly review of EU Green Deal enforcement timelines, Brazilian harvest yield reports, and Q-grader wage inflation indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Beverages Market
Beverages
Latin America Sports and Energy Drinks Market
Beverages
Crystal Boba Market
Beverages
Beverage Premix Market
Beverages
GCC Juice Market
Beverages
Low Calorie RTD Beverages Market
Beverages
Apple Juice Market
Beverages
Ready to Drink Shakes Market
Beverages
Asia-Pacific Bottled Water Market
Beverages
United States Beverage Contract Bottling and Filling Market
Beverages
NFC JUICE Market
Beverages
Bangladesh Energy Drinks Market
Beverages
Carbonated Beverages Market
Beverages
Asia Pacific Fruits and Vegetables Juice Market
Beverages
Caffeine-Based Drinks Market
Beverages
Rose Floral Water Market