
 Nasal Allergy Treatment Market | 2026-2036
Nasal Allergy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Nasal Allergy Treatment Market Foresight
Adult self-medicating consumers is bifurcating from physician-directed pediatric segments as over-the-counter intranasal corticosteroids gain pharmacy shelf space. GlaxoSmithKline PLC dominates the retail channel with established brand recognition and broad distribution networks. Sanofi SA differentiates through sustained investment in allergen immunotherapy platforms. Johnson & Johnson leverages its consumer health division to anchor pharmacy-led purchasing decisions across North American and European markets.
Nasal allergy treatment encompasses pharmacological and immunological interventions designed to alleviate inflammatory responses within the nasal mucosa, typically administered via intranasal sprays delivering corticosteroids, antihistamines, or decongestants in micronized particle sizes optimized for mucosal deposition. These therapies function primarily to reduce histamine-mediated symptoms and eosinophilic inflammation in patients with allergic rhinitis and related conditions. Corticosteroids and nasal sprays command the largest share of product type revenue due to superior efficacy in moderate-to-severe cases, while intranasal delivery mode exhibits the steepest growth trajectory as patients favor localized action with reduced systemic exposure. The home care end user segment is expanding fastest, reflecting broader shifts toward patient-managed chronic disease protocols.
The FDA maintains stringent bioequivalence requirements for nasal spray generics through pharmacokinetic and clinical endpoint studies, elevating development costs while protecting innovator formulations. EMA's MDR framework and REACH compliance standards govern device materials and propellant chemistry for European market access. EPA regulations on chlorofluorocarbon replacements in metered-dose inhalers extend to certain nasal spray propellant systems, forcing reformulation investments. Stakeholders must monitor evolving regulatory divergence between FDA and EMA bioequivalence pathways when prioritizing pipeline investments and geographic launch sequencing.
Market Dynamics
FDA bioequivalence requirements for nasal spray generics are elevating development costs and reshaping competitive entry pathways, while patient preference for localized intranasal delivery is compressing systemic antihistamine demand.
Growth Catalysts
- Pediatric allergy clinic expansion:Specialized pediatric facilities across the United States are expanding procurement of intranasal corticosteroid therapies, creating dedicated demand channels separate from general practice.
- Direct-to-consumer advertising:Sustained pharmaceutical advertising in the United States maintains higher per-capita treatment awareness and self-directed purchasing behavior than comparable developed markets.
- REACH compliance standardization:ECHA's unified chemical safety framework streamlines device material approvals across European markets, reducing redundant testing burdens for multi-country launches.
Market Restraints
- Propellant chemistry reformulation costs:EPA regulations on chlorofluorocarbon replacements force manufacturers to redesign metered-dose spray systems, raising capital requirements without commensurate pricing power.
- Bioequivalence study complexity:FDA pharmacokinetic and clinical endpoint requirements for nasal spray generics create structural barriers that protect innovator formulations and delay affordable alternatives.
- Seasonal demand concentration:Pollen burden seasonality in temperate climates concentrates revenue recognition into discrete quarterly windows, complicating manufacturing capacity planning and inventory management.
Strategic Opportunities
- Home care protocol expansion:Patient-managed chronic disease frameworks are opening pharmacy-led purchasing channels for over-the-counter intranasal corticosteroids outside traditional prescription pathways.
- Allergen immunotherapy platform convergence:Sustained investment in sublingual and subcutaneous immunotherapy creates cross-selling opportunities with symptomatic nasal spray portfolios.
- EMA-FDA regulatory arbitrage:Diverging bioequivalence pathway evolution between European and American regulators enables geographic launch sequencing that optimizes approval timelines and market exclusivity windows.
Industry Challenges
- Micronized particle engineering talent scarcity:Specialized formulation scientists capable of optimizing mucosal deposition profiles command premium compensation, constraining R&D expansion at mid-scale manufacturers.
- Legacy device platform integration:Established pump and valve supply chains must accommodate new propellant chemistries without disrupting validated manufacturing processes or patient handling familiarity.
- Multi-jurisdiction compliance synchronization:Simultaneous FDA, EMA, and national regulator submissions require dedicated regulatory affairs capacity that stretches emerging market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nasal Allergy Treatment Market |
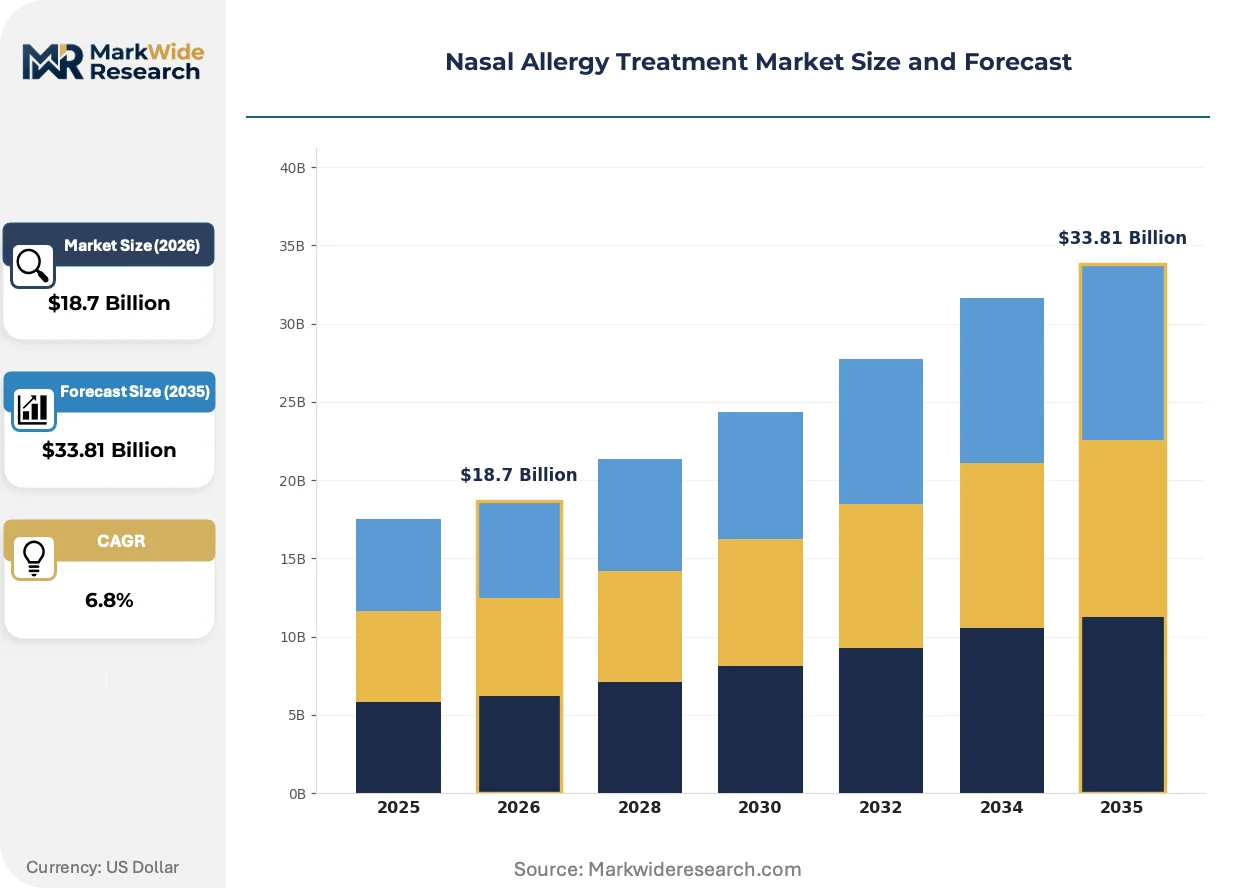
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihistamines, Decongestants, Corticosteroids, Nasal Sprays Delivery Mode: Oral, Intranasal, Injectable, Topical End User: Clinics, Home Care, Hospitals, Pharmacies Therapy Area: Allergic Rhinitis, Seasonal Allergies, Perennial Allergies, Others |
| Companies Covered | GlaxoSmithKline PLC, Johnson & Johnson, Sanofi SA, Merck KGaA, AstraZeneca, Novartis International AG, STALLergenes Greer, ALK-Abello, Allergy Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nasal Allergy Treatment Market Shifts & Advancements
Intranasal corticosteroid delivery systems are undergoing material and formulation evolution that prioritizes mucosal retention over systemic absorption, while regulatory divergence between major markets is fragmenting approval strategies.
Micronized particle engineering is supplanting conventional spray droplet sizing in next-generation nasal delivery platforms. Pediatric allergy clinics and specialized rhinology practices are adopting these advanced deposition systems ahead of general practitioners. This technology shift is enabling sustained local efficacy at reduced active pharmaceutical ingredient loads, compressing the cost structure of chronic therapy regimens.
EMA's Medical Device Regulation framework is tightening device material traceability requirements for European market access. Manufacturers must now document full supply chain provenance for pump components and propellant systems. Nasal spray device suppliers with established REACH compliance infrastructure are capturing preferential procurement positions from pharmaceutical partners prioritizing accelerated European launches.
Self-medicating adult consumers are fragmenting from physician-directed pediatric segments in channel preference and product selection criteria. Pharmacy shelf space allocation for over-the-counter intranasal corticosteroids is expanding at the expense of behind-the-counter positioning. This behavioral shift is most visible in the United States, where direct-to-consumer advertising sustains brand recognition that supports higher-margin retail purchasing independent of clinical consultation.
Nasal Allergy Treatment Market Segmentation
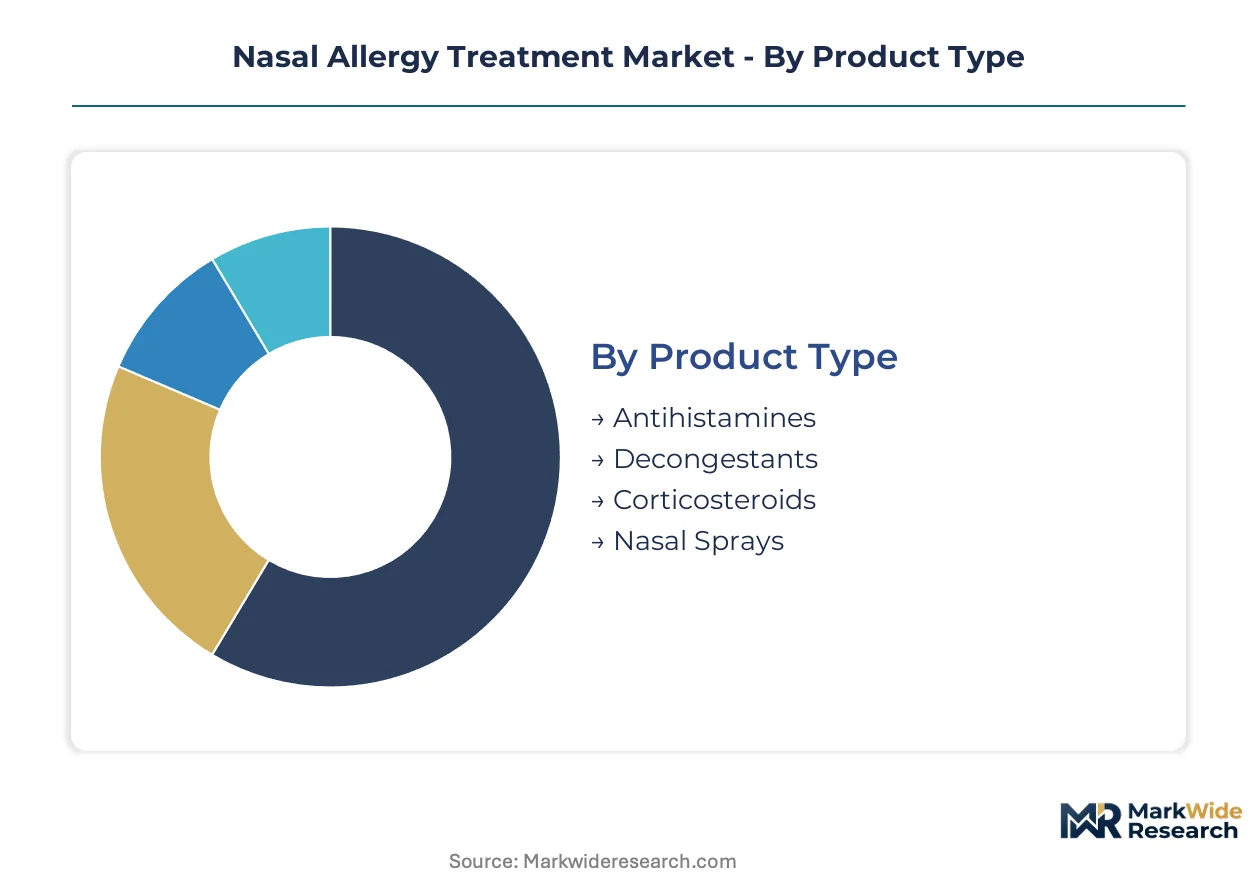
Segmentation in nasal allergy treatment reveals divergent competitive pressures across formulation types, with substitution threats reshaping portfolio priorities for manufacturers and procurement strategies for healthcare systems.
Product Type:
Intranasal corticosteroids face intensifying substitution pressure from over-the-counter antihistamines in mild symptom management, while prescription formulations defend their position in moderate-to-severe cases through superior efficacy data.
- Corticosteroids:Synthetic glucocorticoid formulations including fluticasone propionate and mometasone furoate deliver potent anti-inflammatory action through intranasal deposition. Pediatric allergy clinics in the United States concentrate procurement of these therapies for persistent allergic rhinitis, though FDA bioequivalence requirements protect innovator margins against generic erosion.
- Nasal Sprays:Pump-actuated aqueous and aerosol systems deliver micronized particles optimized for mucosal retention. Demand clusters in pharmacy retail channels where direct-to-consumer advertising drives brand recognition and self-directed purchasing decisions.
- Antihistamines:Oral and intranasal H1-receptor antagonists including cetirizine and azelastine compete on rapid symptom relief.
- Decongestants:Sympathomimetic agents provide short-term nasal patency through vasoconstriction.
Corticosteroids anchor the volume base while nasal sprays gain share at the steepest rate.
Delivery Mode:
Cost tier stratification separates premium intranasal devices from economy oral tablets, with reimbursement policies determining access thresholds across European and North American markets.
- Intranasal:Direct mucosal application via metered-dose pumps or squeeze bottles achieves localized drug deposition with minimal systemic absorption. Home care protocols in Germany and France favor these systems for chronic management, though EPA propellant regulations force ongoing reformulation investments.
- Oral:Systemic administration through tablets and capsules offers convenience but carries broader side-effect profiles. Pharmacy chains in the United States stock these formulations heavily in private-label configurations.
- Topical:External nasal application provides limited therapeutic value beyond adjunctive soothing.
- Injectable:Subcutaneous and intramuscular routes serve refractory cases and immunotherapy induction.
Oral formulations dominate prescription volumes while intranasal delivery climbs fastest on patient preference for localized action.
End User:
Customer type fragmentation separates institutional procurement with formulary constraints from retail purchasing driven by brand awareness and shelf visibility.
- Home Care:Patient-managed therapy selection through pharmacy and e-commerce channels now represents the primary growth vector. Self-medicating adults in the United States bypass clinical consultation for seasonal symptom control, sustaining higher per-capita treatment rates.
- Clinics:Specialized pediatric and allergy practices concentrate procurement of advanced corticosteroid formulations with documented deposition profiles.
- Pharmacies:Community and retail pharmacy networks function as the dominant distribution node for over-the-counter transitions.
- Hospitals:Acute care settings reserve nasal allergy treatment for perioperative optimization and refractory cases.
Home care anchors the volume base while clinics gain share at the steepest rate on pediatric specialization.
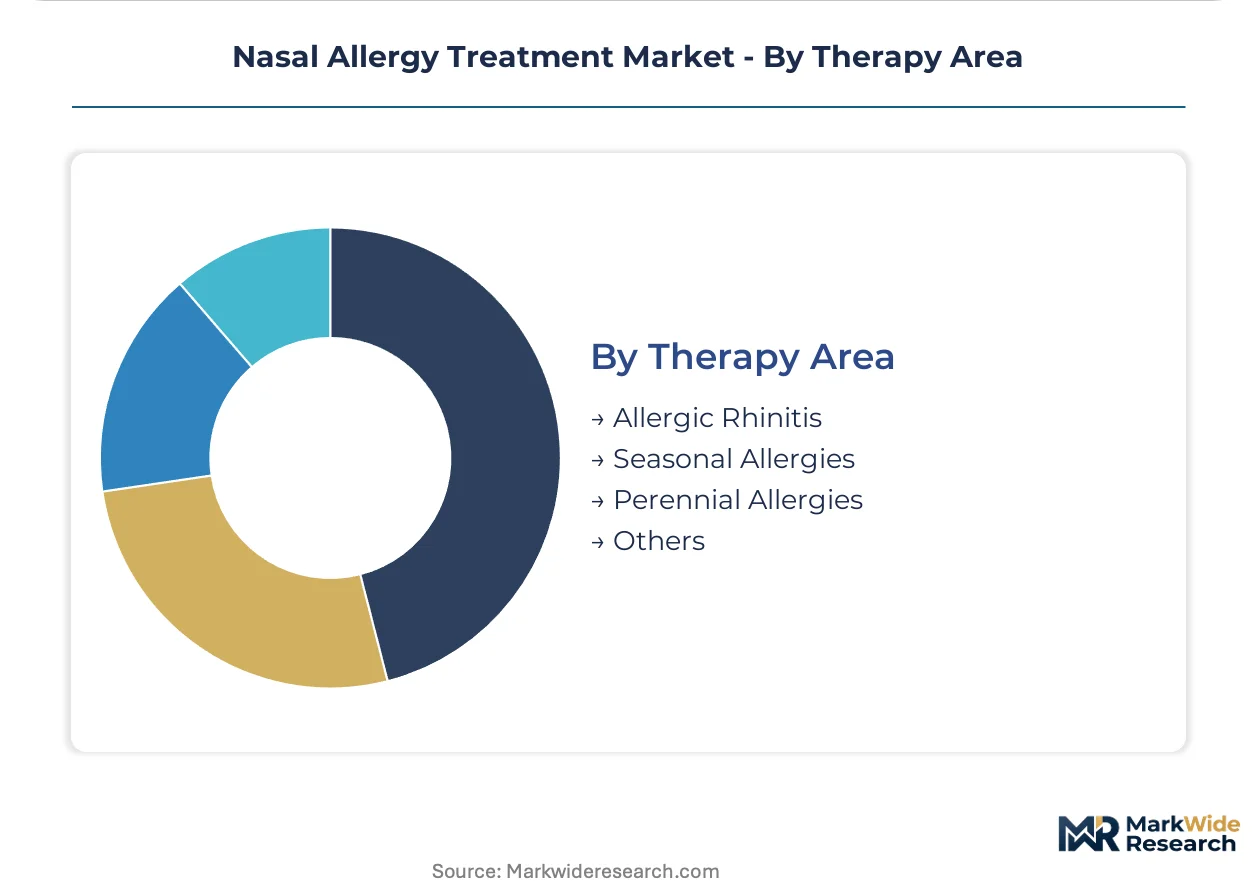
Therapy Area:
Maturity gradients separate well-established seasonal allergy protocols from emerging perennial allergy management approaches requiring sustained therapeutic innovation.
- Allergic Rhinitis:The core therapeutic indication encompasses both intermittent and persistent disease classifications with validated treatment algorithms. United States pollen burden patterns drive concentrated demand windows that complicate manufacturing planning.
- Seasonal Allergies:Pollen-specific sensitization creates predictable but intense treatment episodes. Direct-to-consumer advertising in North American markets sustains brand loyalty across symptom cycles.
- Perennial Allergies:Year-round triggers including dust mites and pet dander require continuous therapy regimens with adherence challenges.
- Others:Non-allergic rhinitis and occupational exposures represent niche expansion opportunities.
Seasonal allergies anchor the volume base while perennial allergies gain share at the steepest rate on chronic disease protocol expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation scientists capable of optimizing mucosal deposition profiles cluster in established pharmaceutical manufacturing hubs across three continents. Device engineering expertise concentrates in Germany, Switzerland, and the United States, where precision pump manufacturing infrastructure supports next-generation nasal spray development. Regulatory divergence between FDA and EMA pathways is forcing geographic launch sequencing strategies that prioritize one jurisdiction over another.
United States
Pollen burden seasonality in temperate climates drives concentrated demand windows that complicate manufacturing capacity planning. FDA bioequivalence requirements for nasal spray generics create structural barriers that protect innovator formulations and delay affordable alternatives. Pediatric allergy clinics in Texas and California are expanding procurement of intranasal corticosteroid therapies, creating dedicated demand channels separate from general practice.
Germany
Home care protocols in Germany favor intranasal delivery systems for chronic allergic rhinitis management. ECHA's REACH compliance framework streamlines device material approvals across European markets, reducing redundant testing burdens for multi-country launches. The Rhine-Ruhr metropolitan region hosts precision pump manufacturers supplying pharmaceutical partners with REACH-compliant device platforms.
United Kingdom
Pharmacy-led purchasing channels for over-the-counter intranasal corticosteroids are expanding outside traditional prescription pathways. The Medicines and Healthcare products Regulatory Agency maintains alignment with EMA standards while preserving national flexibility on pharmacy classification decisions. London-based allergy specialists are adopting advanced micronized particle deposition systems ahead of regional general practitioners.
Switzerland
Swissmedic's regulatory framework attracts pharmaceutical companies seeking centralized European approval pathways with accelerated timelines. Precision device engineering capabilities in the Basel-Zurich corridor support next-generation pump development for mucosal retention optimization. Multinational headquarters concentration in Geneva and Basel facilitates cross-border regulatory strategy coordination for EMA and FDA submissions.
India
CDSCO's evolving bioequivalence standards for nasal sprays are attracting contract manufacturing organizations serving export markets. Cost-competitive formulation development in Hyderabad and Mumbai supports generic pipeline expansion for regulated markets. Domestic pollen burden in northern states is driving clinic expansion for allergic rhinitis management with imported and locally manufactured therapies.
Nasal Allergy Treatment Market Competitive Landscape
Concentration sits with diversified pharmaceutical conglomerates possessing consumer health divisions and established pharmacy distribution networks. The competitive structure divides between prescription-focused innovators protected by FDA bioequivalence barriers and over-the-counter brands competing on retail shelf visibility. Three archetypes dominate: integrated pharmaceutical conglomerates with consumer health arms, specialized allergy immunotherapy platforms, and generic manufacturers navigating complex regulatory pathways. M&A activity targets allergen immunotherapy capabilities, while portfolio diversification moves emphasize home care protocol expansion.
Within the integrated pharmaceutical tier, GlaxoSmithKline PLC and Johnson & Johnson exemplify archetypes combining prescription innovation with consumer health scale. Sanofi SA occupies a position representing sustained investment in allergen immunotherapy platforms alongside symptomatic nasal spray portfolios. These three anchors demonstrate how regulatory expertise and distribution infrastructure create defensive positions against generic erosion.
| Leading Market Players |
|---|
| GlaxoSmithKline PLC |
| Johnson & Johnson |
| Sanofi SA |
| Merck KGaA |
| AstraZeneca |
| Novartis International AG |
| STALLergenes Greer |
| ALK-Abello |
| Allergy Therapeutics |
| Others |
Supply & Pricing Matrix
FDA bioequivalence requirements for nasal spray generics gate both supplier qualification and price differentiation simultaneously, forcing manufacturers to absorb elevated clinical study costs that compress mid-tier margins while insulating innovator formulations from immediate substitution.
Pricing Analysis
FDA bioequivalence requirements dictate the pricing tier structure across the nasal allergy treatment landscape. Three-tier pricing separates prescription intranasal corticosteroids from pharmacy-led over-the-counter brands and private-label economy alternatives. Price differentiation rests on certification tier and brand recognition in direct-to-consumer channels. Cost compression in generic development is intensifying because pharmacokinetic study complexity extends approval timelines without commensurate pricing power. Pharmacy chains exhibit highest price sensitivity, while pediatric allergy clinics demonstrate lowest sensitivity due to formulary constraints and efficacy prioritization.
Supply Chain Analysis
Germany and Switzerland anchor precision pump manufacturing for nasal spray devices, while India and China supply active pharmaceutical ingredients and contract formulation services. Device engineering draws from micronized particle specialists in the Rhine-Ruhr corridor and Basel-Zurich region, with propellant chemistry feedstock sourced from petrochemical complexes in the US Gulf Coast. Single-source vulnerability concentrates in validated pump valve suppliers serving multiple pharmaceutical partners. Distribution runs through wholesale pharmacy networks and direct-to-hospital procurement channels in regulated markets, with e-commerce platforms gaining share in over-the-counter segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nasal allergy treatment market sits in early-cycle expansion, with home care protocol adoption and patient-managed chronic disease frameworks driving penetration beyond traditional prescription pathways.
For Market Incumbents: Secure pediatric allergy clinic procurement relationships through dedicated formulary positioning and deposition profile documentation. Deepen backward integration into micronized particle engineering capabilities to offset talent scarcity premiums. FDA bioequivalence barriers protect innovator margins but require sustained regulatory affairs investment to defend against delayed generic entry. For New Entrants and Emerging Players: CDSCO's evolving bioequivalence fast-track for contract manufacturing organizations offers accelerated qualification for export-oriented production. Target northern Indian states where domestic pollen burden is driving clinic expansion with limited local manufacturing capacity. Pursue white-label supply agreements with European pharmaceutical partners seeking REACH-compliant device platforms. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across allergen immunotherapy platform convergence plays. Long-term viability favors diversified portfolios combining symptomatic nasal spray revenue with disease-modifying immunotherapy pipelines. Acquisition targets should demonstrate established regulatory affairs capacity spanning FDA and EMA pathways. Monitor EMA-FDA bioequivalence pathway divergence as the signal to watch for geographic launch sequencing arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Allergen Immunotherapy Platform Convergence | Sanofi SA's sustained investment creates cross-selling synergies with symptomatic nasal spray portfolios. |
| REACH-Compliant Device Supply Agreement | German precision pump manufacturers capture preferential procurement from pharmaceutical partners prioritizing European launches. |
| Pediatric Clinic Formulary Positioning | Texas and California allergy specialists concentrate procurement of advanced corticosteroid formulations with documented efficacy. |
| Direct-to-Consumer Channel Expansion | GlaxoSmithKline PLC leverages brand recognition from sustained pharmaceutical advertising in US markets. |
| Generic Bioequivalence Pathway Navigation | Contract manufacturing organizations in Hyderabad and Mumbai serve export markets through CDSCO qualification. |
Research Methodology
A standing panel of regulatory affairs specialists, pediatric allergy clinic procurement directors, pharmacy chain category managers, and formulation scientists provided ongoing calibration throughout the research process. Primary interviews with these stakeholders combined with secondary validation from FDA filings, EMA submission databases, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored market sizing across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across product type, delivery mode, end user, and therapy area segmentation dimensions. CAGRs were derived from patient prevalence trends, treatment rate evolution, and pricing trajectory modeling. Forecast inputs incorporated pollen burden seasonality patterns, regulatory approval pipeline status, and channel shift dynamics between prescription and over-the-counter transitions.
Underlying assumptions cover stable regulatory divergence between FDA and EMA pathways, with deviation risk concentrated in accelerated bioequivalence harmonization or propellant chemistry bans. Forecasts reflect these assumptions with explicit sensitivity to pediatric clinic expansion rates and direct-to-consumer advertising intensity. Recalibration cycles align with material shifts in FDA bioequivalence guidance, EPA propellant regulations, and EMA Medical Device Regulation enforcement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Nasopharyngeal Carcinoma Treatment Market
Medical Treatment
Gaucher Disease Treatment Market
Medical Treatment
Radioactive Iodine Ablation Therapy Market
Medical Treatment
Single-Dose Therapy Market
Medical Treatment
Malaria Treatment Market
Medical Treatment
Nontuberculous Mycobacterium Treatment Market
Medical Treatment
Thyroid Deficiency Treatment Market
Medical Treatment
Inguinal Hernia Market
Medical Treatment
Postoperative Nausea and Vomiting (PONV) Management Market
Medical Treatment
Paresthesia Treatment Market
Medical Treatment
Cholera Treatment Market
Medical Treatment
Behcet's Disease Treatment Market
Medical Treatment
Lyme Disease Treatment Market
Medical Treatment
Vulvovaginal Candidiasis Treatment Market
Medical Treatment
Encephalitis Treatment Market
Medical Treatment
Transarterial Chemoembolization (TACE) Market