
 Hypercoagulability Treatment Market | 2026-2036
Hypercoagulability Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hypercoagulability Treatment Market Foresight
Hospital formulary access is narrowing as integrated delivery networks consolidate purchasing decisions across regional health systems. Pfizer Inc. leverages its cardiovascular franchise to sustain institutional contracts for anticoagulant portfolios. Bristol-Myers Squibb anchors market presence through specialty pharmacy channels that manage complex thrombosis cases. Bayer AG competes on manufacturing scale, supplying active pharmaceutical ingredients to generic injectable producers.
Hypercoagulability treatment encompasses pharmacological interventions that modulate platelet aggregation, coagulation cascade activity, and fibrinolytic pathways to prevent or resolve pathological thrombus formation, with direct oral anticoagulants such as factor Xa inhibitors and direct thrombin inhibitors demonstrating predictable pharmacokinetics that eliminate routine INR monitoring requirements. Anticoagulants dominate prescription volume due to established reimbursement for atrial fibrillation stroke prevention, while thrombolytics command premium positioning in acute pulmonary embolism protocols where catheter-directed therapy is expanding. Injectable delivery modes retain criticality in perioperative bridging and intensive care settings where oral absorption is compromised.
FDA breakthrough therapy designation and EMA conditional marketing authorization frameworks compress development timelines for novel anticoagulant mechanisms, while WHO essential medicines listings shape procurement priorities in low-resource health systems. The analysis indicates stakeholders must monitor pharmacoeconomic evidence generation for oral factor XI inhibitors as these agents approach regulatory filing, since payer acceptance will determine whether this drug class displaces existing standards in orthopedic surgery prophylaxis and cancer-associated thrombosis.
Market Dynamics
Hospital formulary consolidation is compressing vendor access as integrated delivery networks centralize anticoagulant procurement across regional health systems, privileging manufacturers with cardiovascular franchise breadth and specialty pharmacy infrastructure.
Growth Catalysts
- Medicare reimbursement policy:CMS coverage determinations favor direct oral anticoagulant adoption over warfarin monitoring, accelerating outpatient thrombosis management transitions.
- FDA breakthrough therapy designation:Accelerated approval pathways compress development timelines for novel factor XI inhibitors approaching regulatory filing.
- Catheter-directed therapy expansion:Interventional radiology protocols for acute pulmonary embolism are driving thrombolytic utilization in tertiary care centers.
Market Restraints
- Active pharmaceutical ingredient concentration:Manufacturing scale advantages concentrate among German and Swiss suppliers, creating supply vulnerability for generic injectable producers.
- Reversal agent cost structure:Andexanet alfa and idarucizumab pricing limits hospital formulary placement of novel oral anticoagulants in budget-constrained systems.
- Warfarin substitution persistence:INR monitoring infrastructure and physician familiarity sustain generic competition in Medicare populations.
Strategic Opportunities
- Factor XI inhibitor class entry:Oral agents with reduced bleeding profiles target orthopedic surgery prophylaxis and cancer-associated thrombosis white space.
- WHO essential medicines listing:Procurement prioritization in low-resource health systems creates volume opportunity for established anticoagulant portfolios.
- Specialty pharmacy channel integration:Complex thrombosis case management through centralized dispensing models improves adherence monitoring and outcomes documentation.
Industry Challenges
- Pharmacoeconomic evidence generation:Payer acceptance of novel mechanisms depends on real-world data infrastructure and health technology assessment alignment.
- Perioperative bridging protocol complexity:Anticoagulation interruption management requires coordination across surgical, anesthesia, and hematology functions with variable institutional protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypercoagulability Treatment Market |
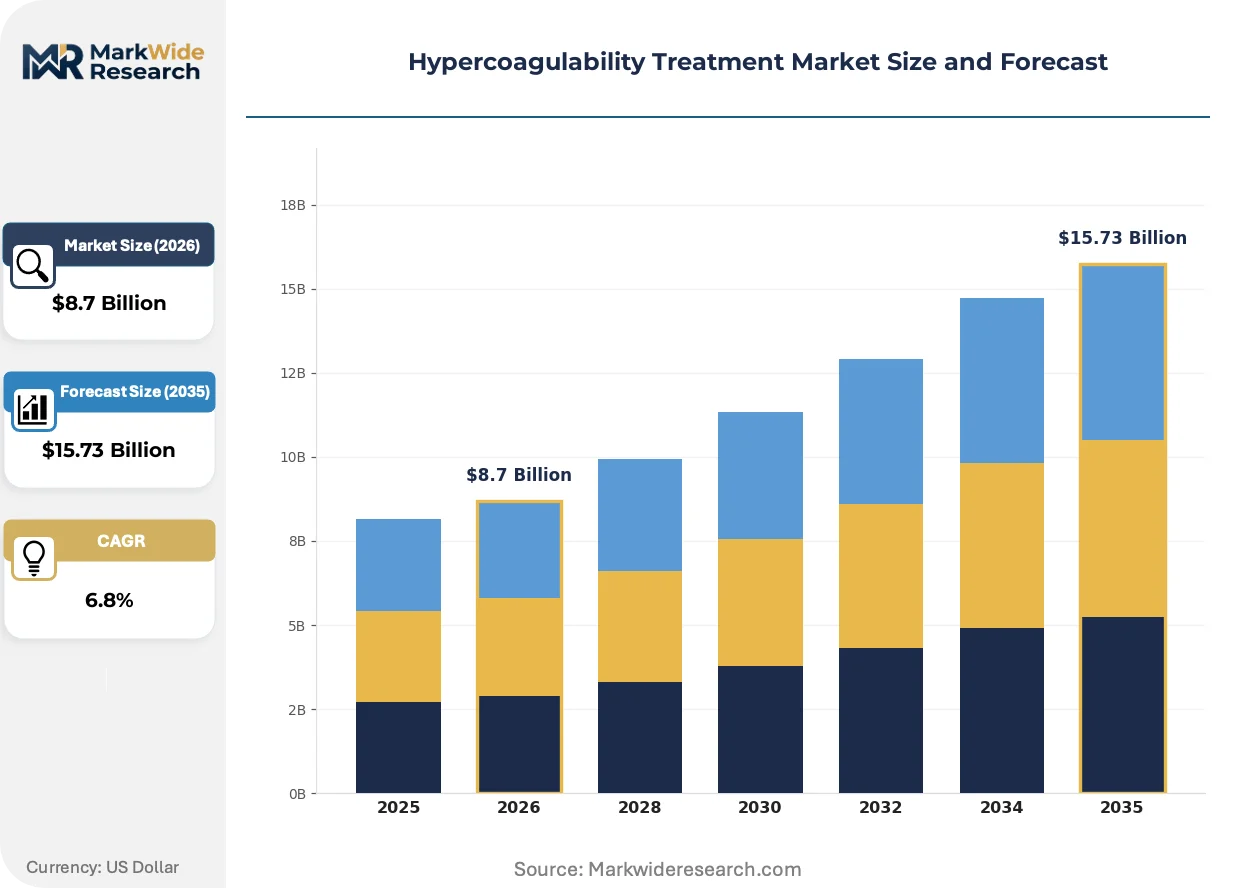
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anticoagulants, Antiplatelets, Thrombolytics, Direct Thrombin Inhibitors Application: Venous Thromboembolism, Pulmonary Embolism, Myocardial Infarction, Stroke End User: Hospitals, Clinics, Homecare, Research Laboratories Delivery Mode: Oral, Injectable, Intravenous, Transdermal |
| Companies Covered | Sanofi, Pfizer Inc., Novartis AG, Bristol-Myers Squibb, Johnson & Johnson, Teva Pharmaceutical Industries Ltd., F. Hoffmann-La Roche Ltd., Bayer AG, Boehringer Ingelheim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypercoagulability Treatment Market Shifts & Advancements
Anticoagulant development is pivoting toward mechanism-based differentiation as factor XI inhibition promises bleeding-sparing profiles, while delivery innovation targets adherence gaps in chronic therapy.
Oral factor XI inhibitors are collapsing the trade-off between thrombotic efficacy and hemorrhagic risk that has constrained anticoagulant expansion into surgical prophylaxis. Orthopedic surgery departments at academic medical centers are piloting these agents in total joint replacement protocols. The technology is collapsing historical limitations on anticoagulant duration and intensity in procedures with high bleeding sensitivity.
EMA conditional marketing authorization frameworks are enabling earlier patient access to novel anticoagulant mechanisms with post-approval evidence commitments. European health technology assessment bodies are integrating these pathways into reimbursement decision timelines. Oncology-thrombosis crossover indications are most affected, with sponsors adapting Phase III designs to meet conditional approval evidentiary standards.
Integrated delivery networks are unbundling anticoagulation monitoring from traditional anticoagulation clinic structures. Risk stratification algorithms and patient self-testing devices are displacing centralized INR management for stable warfarin patients. The United States exhibits the most visible shift, with Medicare Advantage plans incentivizing home-based monitoring to reduce emergency department visits for supratherapeutic events.
Hypercoagulability Treatment Market Segmentation
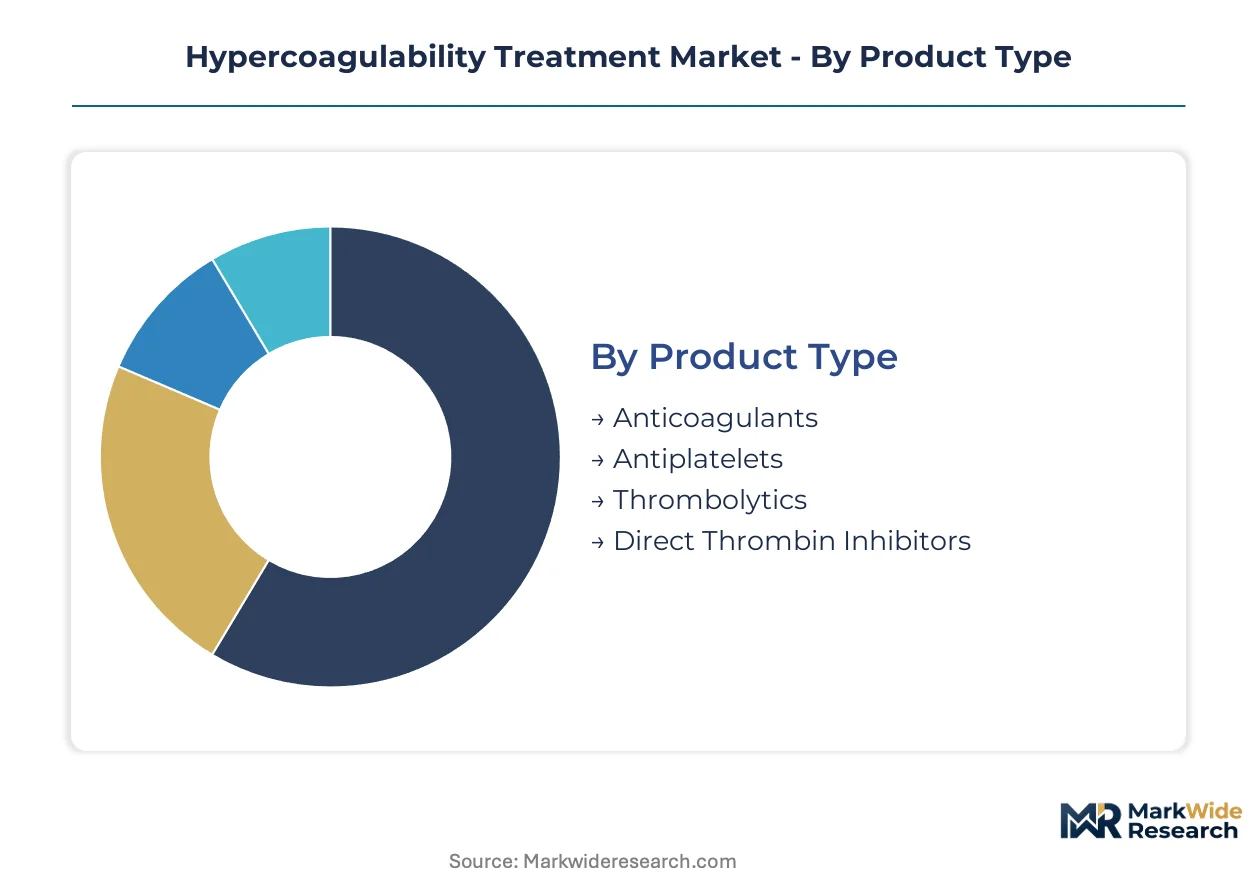
Hypercoagulability treatment markets fragment across pharmacological mechanism, clinical indication, care setting, and administration route. Each dimension carries distinct reimbursement logic and competitive intensity that shapes manufacturer positioning strategies.
Product Type:
Mature oral anticoagulants anchor prescription volumes while emerging mechanism classes reshape therapeutic paradigms in surgical prophylaxis.
- Anticoagulants:Factor Xa inhibitors and vitamin K antagonists constitute the pharmacological backbone for atrial fibrillation stroke prevention and venous thromboembolism management. Hospital formularies in the United States prioritize direct oral anticoagulant access following CMS coverage expansions that displaced warfarin monitoring infrastructure.
- Antiplatelets:P2Y12 inhibitors and cyclooxygenase inhibitors modulate platelet aggregation pathways in acute coronary syndrome protocols. Dual antiplatelet therapy duration decisions in European catheterization laboratories drive demand concentration for ticagrelor and prasugrel formulations.
- Thrombolytics:Tissue plasminogen activators and urokinase derivatives dissolve established fibrin clots in acute ischemic stroke and massive pulmonary embolism presentations.
- Direct Thrombin Inhibitors:Parenteral argatroban and oral dabigatran etexilate target thrombin-mediated coagulation in heparin-induced thrombocytopenia and chronic anticoagulation respectively.
Anticoagulants retain volume leadership; direct thrombin inhibitors hold the steepest expansion curve as novel oral formulations displace injectable standards.
Application:
Indication severity determines pricing tolerance and treatment setting, with acute life-threatening presentations commanding premium positioning against chronic prophylaxis indications.
- Venous Thromboembolism:Deep vein thrombosis and pulmonary embolism prevention and treatment represent the largest addressable patient population for anticoagulant therapy. Extended prophylaxis protocols in cancer patients at academic medical centers are expanding duration of therapy beyond traditional perioperative windows.
- Pulmonary Embolism:Acute clot burden stratification drives selection between anticoagulation alone and systemic or catheter-directed thrombolysis in tertiary care emergency departments.
- Myocardial Infarction:ST-elevation and non-ST-elevation acute coronary syndromes require immediate antiplatelet loading followed by maintenance therapy.
- Stroke:Acute ischemic cerebrovascular events demand rapid thrombolytic administration within narrow therapeutic windows.
Venous thromboembolism applications dominate prescription volume; pulmonary embolism interventions command the highest per-patient revenue intensity.
End User:
Care setting migration from institutional to ambulatory environments is compressing acute care utilization while expanding home-based therapy management.
- Hospitals:Inpatient anticoagulation stewardship programs coordinate perioperative bridging, intensive care coagulopathy reversal, and formulary restriction compliance. Integrated delivery network consolidation in the United States is narrowing vendor access to cardiovascular franchise manufacturers with specialty pharmacy infrastructure.
- Clinics:Outpatient anticoagulation clinics and hematology practices manage warfarin therapeutic monitoring and novel oral anticoagulant initiation.
- Homecare:Subcutaneous low-molecular-weight heparin and self-administered direct oral anticoagulants enable early hospital discharge protocols.
- Research Laboratories:Contract research organizations and academic centers conduct Phase I-III trials for factor XI inhibitors and reversal agents.
Hospitals retain volume leadership; homecare channels are gaining share fastest as Medicare Advantage plans incentivize outpatient thrombosis management.
Delivery Mode:
Administration route selection balances bioavailability reliability against patient adherence and healthcare resource utilization.
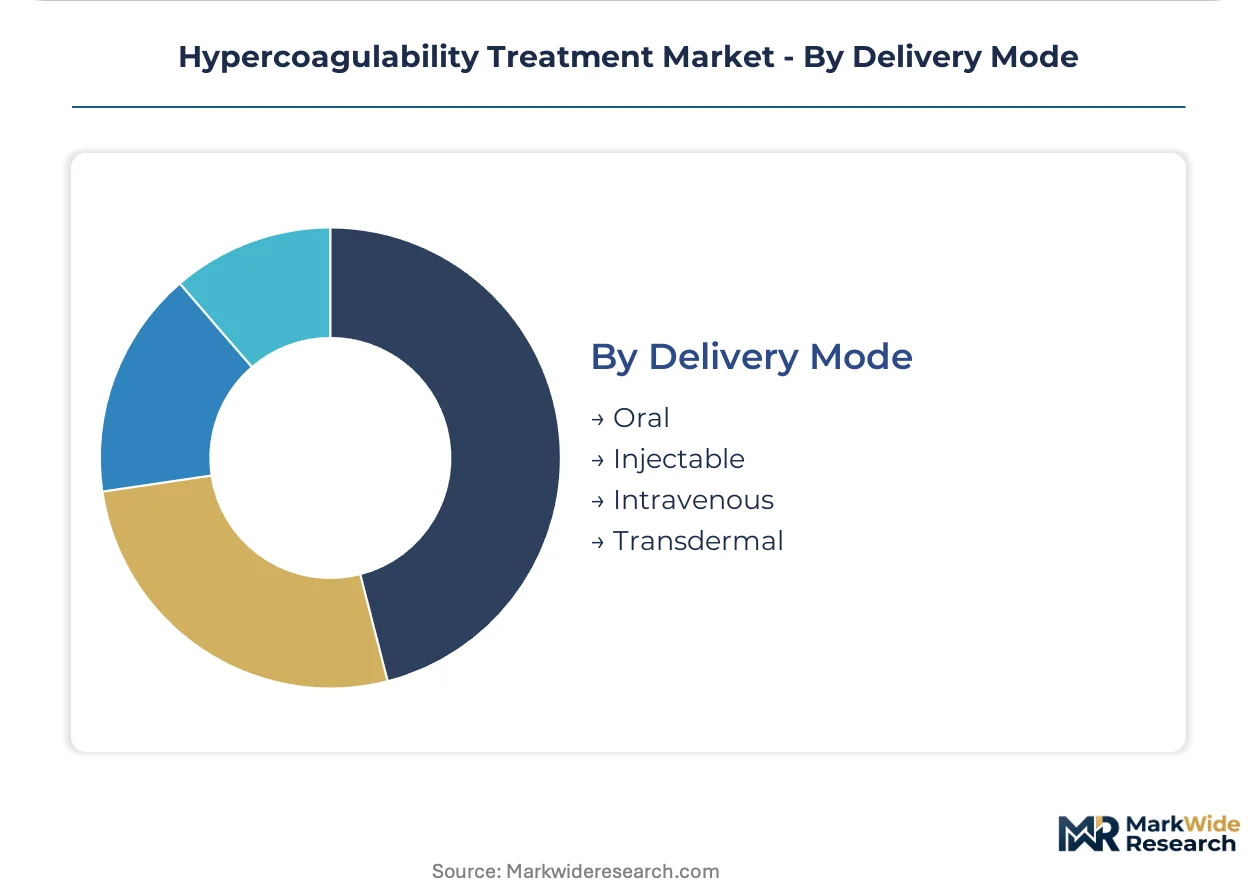
- Oral:Tablet and capsule formulations of direct oral anticoagulants eliminate injection burden and enable chronic outpatient therapy. Predictable pharmacokinetics without routine coagulation monitoring has displaced warfarin in Medicare populations.
- Injectable:Subcutaneous low-molecular-weight heparin and fondaparinux sodium serve perioperative prophylaxis and initial venous thromboembolism treatment.
- Intravenous:Unfractionated heparin infusion and thrombolytic bolus dosing provide immediate anticoagulation in acute coronary syndrome and massive pulmonary embolism.
- Transdermal:Patch-based delivery systems for anticoagulants remain investigational with limited commercial penetration.
Oral delivery dominates prescription volume; injectable modes maintain criticality in perioperative bridging where absorption reliability is paramount.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA reimbursement policies anchor United States demand concentration, while EMA conditional marketing authorization frameworks reshape European access timelines for novel anticoagulant mechanisms.
United States
Medicare Advantage plans accelerate outpatient thrombosis management transitions through home-based monitoring incentives. CMS coverage determinations favor direct oral anticoagulant adoption over warfarin infrastructure. Academic medical centers in Boston and the Research Triangle pilot factor XI inhibitors in orthopedic surgery protocols.
Germany
Integrated delivery network consolidation centralizes anticoagulant procurement across regional health systems. EMA conditional marketing authorization compresses evidentiary requirements for oncology-thrombosis crossover indications. The Rhine-Ruhr industrial corridor hosts active pharmaceutical ingredient manufacturing scale advantages for generic injectable supply.
Japan
PMDA regulatory harmonization with FDA breakthrough therapy pathways accelerates novel mechanism entry. METI industrial policy supports domestic thrombolytic production capacity expansion. The Kansai region's pharmaceutical cluster specializes in parenteral anticoagulant formulation for acute coronary syndrome protocols.
United Kingdom
NHS England integrated care systems consolidate anticoagulation stewardship across hospital and community settings. NICE health technology assessment integration with EMA conditional approval timelines shapes reimbursement decisions. The Golden Triangle research cluster generates real-world evidence infrastructure for novel oral anticoagulant pharmacoeconomic documentation.
India
CDSCO accelerated approval pathways for essential medicines expand access to established anticoagulant portfolios. WHO essential medicines listing shapes procurement prioritization in public health systems. The Hyderabad-Visakhapatnam pharmaceutical corridor supplies active pharmaceutical ingredients to generic injectable producers serving perioperative bridging demand.
Hypercoagulability Treatment Market Competitive Landscape
Cardiovascular franchise incumbents and specialty pharmacy-integrated manufacturers split the market through divergent channel strategies. Hospital formulary consolidation privileges manufacturers with institutional contract breadth and regional health system penetration. Three archetypes dominate: multinational pharmaceutical conglomerates with anticoagulant portfolios, active pharmaceutical ingredient suppliers with manufacturing scale advantages, and specialty pharmacy operators managing complex thrombosis cases. Competitive moves concentrate on strategic partnerships with integrated delivery networks and portfolio diversification into reversal agent co-development.
Within the multinational pharmaceutical tier, Pfizer Inc., Bristol-Myers Squibb, and Bayer AG occupy positions reflecting divergent strategic emphases. Pfizer exemplifies the cardiovascular franchise archetype sustaining institutional contracts across regional health systems. Bristol-Myers Squibb anchors specialty pharmacy channel integration for complex thrombosis case management. Bayer represents manufacturing scale advantages in active pharmaceutical ingredient supply to generic injectable producers.
| Leading Market Players |
|---|
| Sanofi |
| Pfizer Inc. |
| Novartis AG |
| Bristol-Myers Squibb |
| Johnson & Johnson |
| Teva Pharmaceutical Industries Ltd. |
| F. Hoffmann-La Roche Ltd. |
| Bayer AG |
| Boehringer Ingelheim |
| Others |
Supply & Pricing Matrix
The Hyderabad-Visakhapatnam pharmaceutical corridor concentrates active pharmaceutical ingredient capacity for generic injectable anticoagulants, translating upstream manufacturing scale into downstream pricing leverage for hospital formulary negotiations across perioperative bridging segments.
Pricing Analysis
Geographic price spreads between German-Swiss origin APIs and Indian-manufactured generics reach three-tier levels across premium, standard, and economy segments. Price differentiation rests on FDA certification tier and volume commitment scale, with academic medical centers commanding standard-tier rates while community hospitals face economy-tier constraints. Cost compression in the reversal agent category intensifies because andexanet alfa and idarucizumab pricing limits formulary access. Medicare Advantage plans exhibit highest price sensitivity; specialty pharmacy-integrated delivery networks demonstrate lowest sensitivity due to bundled outcomes contracts.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for heparin-derived inputs. Manufacturing concentration clusters in India, Germany, and Switzerland for active pharmaceutical ingredients, with formulation finishing distributed across the United States, Japan, and the United Kingdom. Raw material dependencies center on porcine intestinal mucosa for unfractionated heparin, synthetic chemistry precursors for direct oral anticoagulants, and recombinant protein platforms for reversal agents. Single-source vulnerability characterizes the andexanet alfa supply position. Distribution runs through integrated delivery network central procurement with specialty pharmacy last-mile delivery for outpatient oral anticoagulant fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized manufacturing capabilities for factor XI inhibitor production and pharmacoeconomic evidence generation infrastructure represent binding constraints that will determine competitive survival as novel mechanisms advance toward regulatory filing.
For Market Incumbents: Pre-empt generic erosion in the direct oral anticoagulant category by accelerating backward integration into active pharmaceutical ingredient production at the Hyderabad-Visakhapatnam corridor. Secure captive supply of heparin precursors to insulate against porcine source volatility. Deepen specialty pharmacy infrastructure to lock in integrated delivery network contracts before factor XI inhibitors reshape orthopedic surgery prophylaxis protocols. For New Entrants and Emerging Players: Build out pharmacoeconomic evidence generation capabilities targeting oncology-thrombosis crossover indications where real-world data infrastructure gaps create white-space opportunity. The cancer-associated thrombosis segment offers lowest competitive density and highest unmet need penetration. Pursue EMA conditional marketing authorization pathways to compress European access timelines ahead of health technology assessment integration. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with established cardiovascular franchise breadth and specialty pharmacy channel integration over pure-play API suppliers. Long-term viability hinges on portfolio diversification into reversal agent co-development and next-generation anticoagulant mechanisms. Watch FDA breakthrough therapy designation frequency for factor XI inhibitors as the signal indicating competitive inflection toward mechanism-based differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses development timelines for novel factor XI inhibitors approaching filing. |
| Manufacturing Scale-Up | Active pharmaceutical ingredient capacity expansion at the Rhine-Ruhr corridor secures generic injectable supply continuity. |
| Hospital System Partnership | Integrated delivery network formulary placement locks in institutional contracts across regional health system consolidation. |
| Reimbursement Strategy | Medicare coverage determination alignment accelerates direct oral anticoagulant displacement of warfarin monitoring infrastructure. |
| Pipeline Diversification | Reversal agent co-development hedges against pricing pressure limiting novel oral anticoagulant hospital formulary access. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases. Primary interviews engaged drug development executives, regulatory affairs leads, formulary directors at academic medical centers, and payer access specialists across the United States, Germany, and Japan. Secondary validation drew from CMS Medicare data, GPO contracts, and WHO essential medicines listings. Bottom-up prescription volume modeling and top-down market sizing triangulated demand estimates across the analysis window.
Forecast inputs span pharmacological mechanism, clinical indication severity, care setting migration patterns, and administration route adoption curves. Segmentation modeling incorporated treatment line positioning, dosage form differentiation, patient population risk stratification, and regional regulatory cluster dynamics. CAGRs were derived from growth rate convergence analysis across epidemiological trend projections and reimbursement policy trajectory scenarios. Pharmacoeconomic evidence generation timelines and FDA breakthrough therapy designation frequency served as industry-specific forecast modifiers.
Stress conditions across Medicare reimbursement policy shifts, active pharmaceutical ingredient supply disruptions, and factor XI inhibitor regulatory approval timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding integrated delivery network consolidation velocity and outpatient thrombosis management transition rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Avian Flu Treatment Market
Medical Treatment
Mesotherapy Market
Medical Treatment
Hereditary Amyloidosis Treatment Market
Medical Treatment
Rett Syndrome Treatment Market
Medical Treatment
Andersen Tawil Syndrome Treatment Market
Medical Treatment
Post-Operative Nausea and Vomiting (PONV) Market
Medical Treatment
Dengue Fever Treatment Market
Medical Treatment
Allergy Treatment Market
Medical Treatment
Familial Hypercholesterolemia Treatment Market
Medical Treatment
Ligament Repair and Reconstruction Market
Medical Treatment
Global Thyroid Disorder Treatment Market
Medical Treatment
Prion Disease Treatment Market
Medical Treatment
Europe Lysosomal Disease Treatment Market
Medical Treatment
Lice Treatment Market
Medical Treatment
Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Merkel Cell Carcinoma (MCC) Treatment Market