
 Migraine Treatment Market | 2026-2036
Migraine Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Migraine Treatment Market Foresight
North American biopharmaceutical manufacturing is restructuring its migraine pipeline capacity around monoclonal antibody production. AbbVie leverages its immunology infrastructure to anchor CGRP-targeted therapy supply chains. Eli Lilly and Company competes through differentiated dosing regimens that extend patient adherence windows. Pfizer controls access via established hospital formulary relationships that sustain volume through institutional procurement channels.
Migraine treatment encompasses pharmacological interventions designed to abort acute attacks, prevent episodic or chronic episodes, or provide rescue relief through mechanisms targeting serotonin receptors, calcitonin gene-related peptide pathways, or vascular modulation. Injectable formulations require cold-chain distribution with stability parameters typically maintained between two and eight degrees Celsius to preserve protein-based biologic integrity. Triptans occupy mature margin pools as oral generics dominate volume, while intranasal delivery systems capture premium positioning through faster onset kinetics. The preventive therapy area leads growth trajectory as CGRP inhibitors displace traditional anticonvulsant and antidepressant prophylaxis regimens.
FDA accelerated approval designations and EMA conditional marketing authorizations shape development timelines and reimbursement negotiations for novel mechanisms. The WHO inclusion of headache disorders in priority noncommunicable disease frameworks elevates national program funding for migraine-specific care pathways. Stakeholders must monitor evolving prior authorization criteria from pharmacy benefit managers and national health technology assessment bodies to anticipate access bottlenecks.
Market Dynamics
FDA's accelerated approval pathway for CGRP inhibitors has compressed development timelines and triggered a wholesale reconfiguration of preventive therapy supply chains around monoclonal antibody manufacturing infrastructure.
Growth Catalysts
- WHO Priority Disease Framework:The WHO inclusion of headache disorders in priority noncommunicable disease frameworks elevates national program funding for migraine-specific care pathways across member states.
- EMA Conditional Marketing Authorizations:EMA conditional pathways enable earlier patient access to novel mechanisms while confirmatory trials continue, expanding addressable populations for biologic preventive therapies.
- Specialty Pharmacy Networks:United States distribution infrastructure for cold-chain biologics now reaches patient homes directly, removing hospital-based infusion bottlenecks that previously constrained CGRP inhibitor adoption.
Market Restraints
- Cold-Chain Distribution Costs:Injectable CGRP inhibitors require uninterrupted two-to-eight-degree Celsius stability parameters, inflating logistics costs for rural and exurban patient populations.
- Prior Authorization Friction:Pharmacy benefit managers impose step-therapy requirements that force trial of oral generics before biologic approval, delaying preventive therapy initiation.
- Substitution by Triptan Generics:Oral sumatriptan and rizatriptan generics dominate acute treatment volume at price points that biologics cannot match for episodic migraine populations.
Strategic Opportunities
- Intranasal Delivery Innovation:Intranasal formulations targeting faster onset kinetics than oral triptans capture premium positioning in acute treatment while avoiding injection burden.
- India Domestic Manufacturing:Contract development and manufacturing organizations in India are building biologics capacity to serve emerging market demand at cost structures below North American production.
- Digital Therapeutics Integration:Prescription digital therapeutics for migraine behavioral management are securing FDA clearance as adjunctive interventions, creating reimbursement codes for non-pharmacological revenue streams.
Industry Challenges
- Biologics Manufacturing Talent Scarcity:Cell culture and aseptic fill-finish expertise concentrates among a limited pool of specialists, constraining capacity expansion timelines for CGRP antibody production.
- Legacy Formulary Contract Complexity:Hospital procurement committees maintain multi-year contracts with established triptan suppliers, creating contractual friction for biologic preventive therapy adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Migraine Treatment Market |
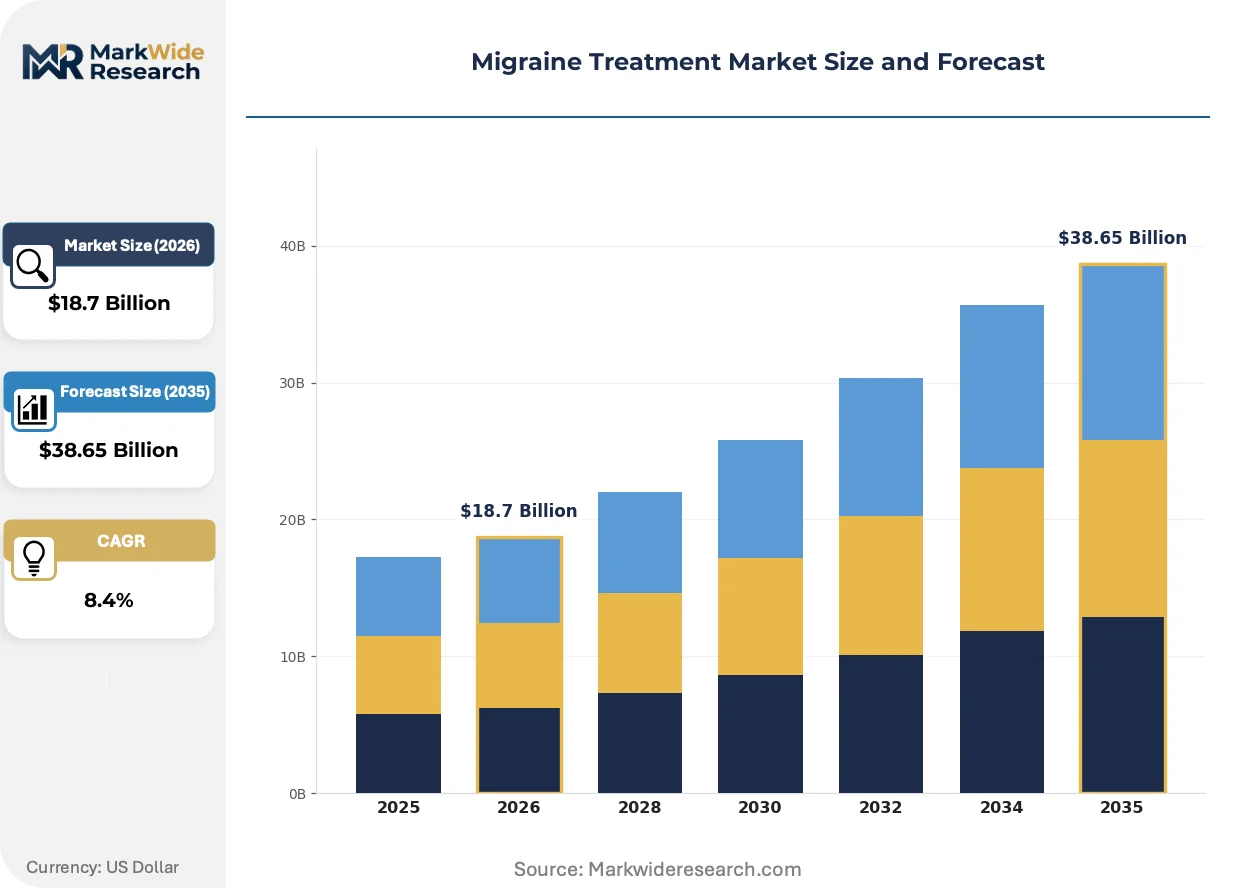
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Triptans, Ergots, Antidepressants, Anticonvulsants Route of Administration: Oral, Intranasal, Injectable, Transdermal Therapy Area: Acute, Preventive, Combination, Rescue End User: Hospitals, Clinics, Pharmacies, Homecare |
| Companies Covered | AbbVie, Amgen, Eli Lilly and Company, Pfizer, Teva Pharmaceutical Industries, Novartis, Lundbeck, GSK, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Migraine Treatment Market Shifts & Advancements
Delivery mechanism innovation and regulatory pathway evolution are converging to compress the gap between acute and preventive therapy positioning, while procurement models shift toward outcomes-based access frameworks.
Oral CGRP receptor antagonists are absorbing patient populations previously routed to injectable preventive biologics by eliminating cold-chain burden and enabling pharmacy-level dispensing. Primary care physicians in the United States are adopting these small-molecule alternatives at rates exceeding specialist clinic forecasts. The technology is absorbing margin pressure from injectable competitors while expanding total addressable market through primary care channel penetration.
REACH authorization requirements for pharmaceutical manufacturing excipients are forcing reformulation of stabilizing agents used in parenteral migraine therapies. European manufacturers are substituting legacy surfactants with bio-based alternatives to maintain market access. The regulatory shift most acutely affects intravenous formulations where excipient concentrations exceed threshold limits for new substance registration.
Specialty pharmacy direct-to-patient distribution is replacing hospital-based infusion centers as the dominant channel for CGRP inhibitor delivery. United States payers are mandating home administration training programs that displace clinic-based nursing support. This channel rotation is most visible in employer-sponsored insurance populations where site-of-care cost differentials drive benefit design.
Migraine Treatment Market Segmentation
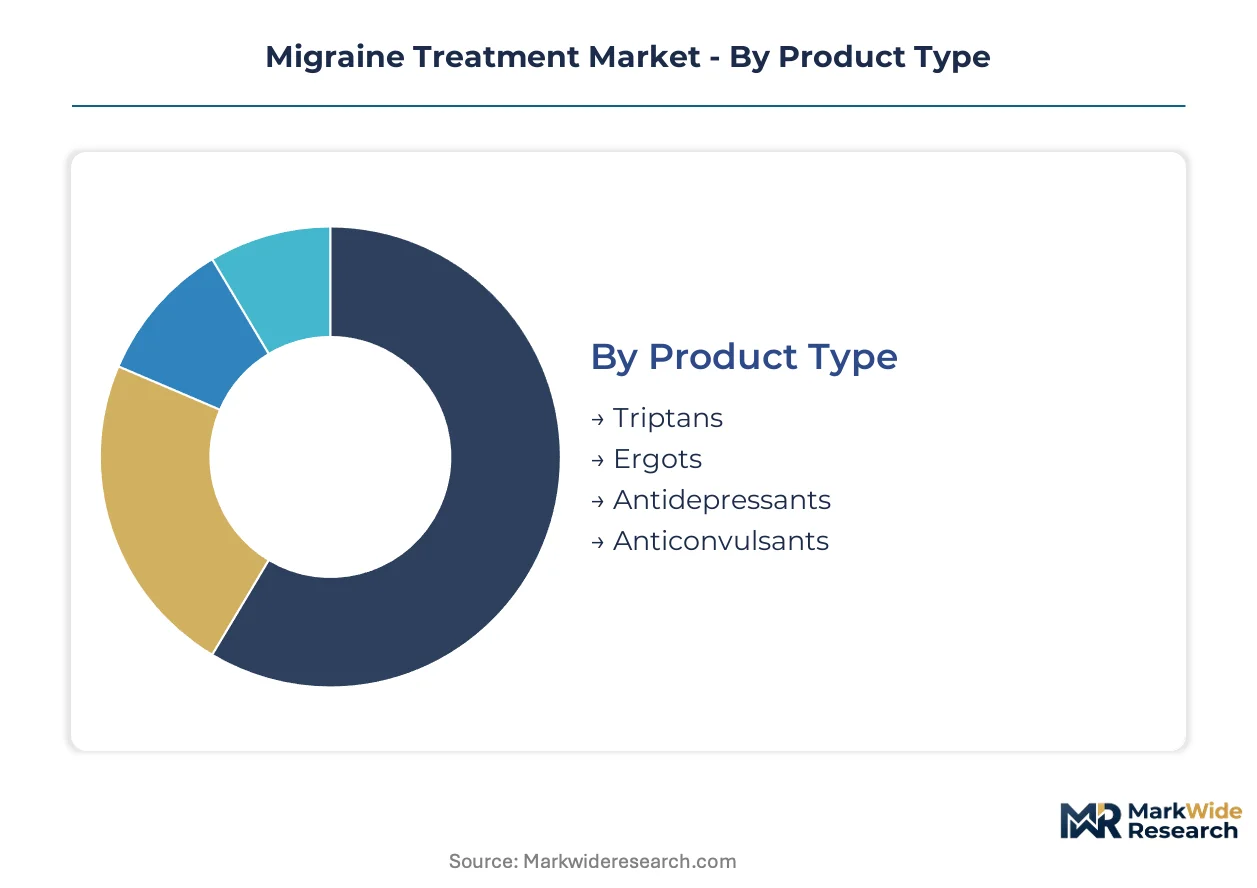
Treatment modality selection in migraine care hinges on attack frequency, severity patterns, and patient tolerance for administration complexity. Segmentation reveals how pharmaceutical innovation is redistributing volume across acute intervention and preventive maintenance channels.
Product Type:
Standardization dominates first-line prescribing while biologics introduce customization through mechanism-specific patient matching.
- Triptans:Serotonin 5-HT1B/1D receptor agonists available in oral, intranasal, and injectable formulations. Sumatriptan generics capture the largest acute treatment volume in the United States through pharmacy benefit manager preferred tiers. Price compression from multi-source competition limits margin expansion despite sustained prescription counts.
- Anticonvulsants:Topiramate and valproate derivatives serve as oral preventive options with established reimbursement pathways. Neurology clinics in Germany and France maintain substantial prescribing volumes for episodic migraine patients who fail first-line approaches. EMA labeling for migraine-specific indications supports continued formulary placement against newer mechanisms.
- Ergots:Ergotamine and dihydroergotamine preparations retain niche positioning for refractory acute attacks. Contraindication profiles restrict use to specialist-supervised settings.
- Antidepressants:Tricyclic amitriptyline and SNRI venlafaxine address comorbid depression-migraine populations. Primary care prescribing in the United Kingdom sustains modest volume through National Health Service formularies.
Leading the category by volume: Triptans. Growing fastest: Anticonvulsants.
Route of Administration:
Patient convenience preferences are compressing hospital-dependent channels toward self-administered alternatives.
- Oral:Tablets and capsules dominate both acute and preventive therapy dispensing. CGRP receptor antagonist tablets from Pfizer and AbbVie are absorbing patient share from injectable biologics in United States specialty pharmacy networks. Elimination of cold-chain logistics reduces total cost of care for payers.
- Injectable:Subcutaneous monoclonal antibodies require refrigeration-stable distribution between two and eight degrees Celsius. Home administration training programs mandated by United States employer-sponsored insurers are displacing clinic-based infusion centers. Nursing support costs drove this channel rotation.
- Intranasal:Sumatriptan and zolmitriptan sprays target faster onset kinetics for patients with gastric stasis during attacks. Premium pricing over oral equivalents captures patients prioritizing speed over cost.
- Transdermal:Patch-based delivery remains experimental for migraine applications. Limited commercial availability constrains adoption.
Oral administration captures the largest patient population. Injectable routes are expanding most quickly through biologic preventive adoption.
Therapy Area:
Volume concentration in acute treatment is shifting toward preventive as CGRP inhibitors reshape prescribing economics.
- Acute:Abortive interventions target individual attack termination through vascular constriction or CGRP pathway blockade. Triptan generics and newer gepants compete for episodic migraine populations in United States retail pharmacy channels. Prior authorization requirements for branded alternatives sustain generic volume.
- Preventive:Scheduled regimens reduce attack frequency and severity in chronic migraine populations. FDA accelerated approvals for quarterly and monthly injectable CGRP antibodies have compressed development timelines and expanded prescriber comfort with biologic prophylaxis. United States headache centers are doubling preventive therapy slots.
- Rescue:Backup options for breakthrough attacks when primary acute therapy fails. Opioid-sparing protocols in United States hospital emergency departments favor ketamine or antiemetic combinations.
- Combination:Fixed-dose products pairing analgesic with antiemetic or vasoconstrictor mechanisms. Limited pipeline activity suggests category stagnation.
Acute therapy leads by prescription volume. Preventive therapy shows the steepest expansion trajectory.
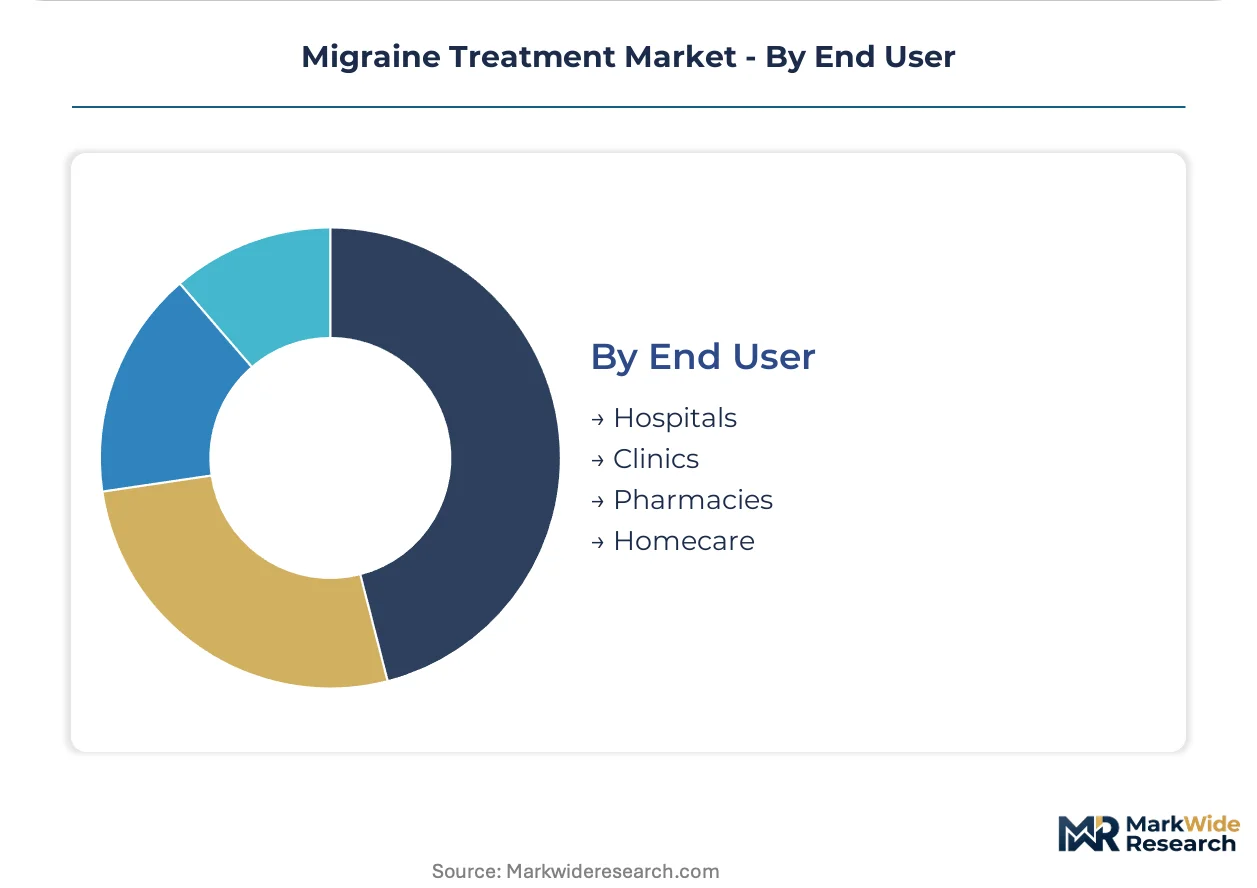
End User:
Site-of-care economics are redistributing patient touchpoints from institutional settings toward home-based management.
- Pharmacies:Retail and specialty pharmacy channels now handle the majority of migraine therapy dispensing in the United States. Cold-chain home delivery for biologics and oral small-molecule pickup for acute treatment split volume between channel types. Payer mandating of specialty pharmacy networks for CGRP inhibitors accelerated this concentration.
- Homecare:Self-administered injectable training and remote monitoring are capturing patients previously requiring clinic visits. United States commercial insurers are expanding home health benefits for chronic migraine populations to reduce emergency department utilization. Cost differentials drive benefit design.
- Hospitals:Emergency departments and dedicated headache centers manage refractory status migrainosus and complex comorbidities. North American academic medical centers are expanding dedicated headache center capacity with infusion suite investments.
- Clinics:Neurology and primary care offices handle diagnosis and initial therapy selection. United Kingdom NHS migraine pathway redesigns are shifting stable patients to community pharmacy follow-up.
Pharmacies lead by patient encounter volume. Homecare is gaining share fastest through biologic self-administration programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade peptide synthesis capacity clusters along the Interstate 95 corridor between Boston and Philadelphia, anchoring North American migraine therapy production networks. This concentration shapes regional supply patterns for CGRP-targeted biologics.
United States
Employer-sponsored insurers mandate home administration training for CGRP inhibitors, displacing hospital infusion centers. FDA accelerated approval pathways compress development timelines for preventive biologics. Massachusetts and New Jersey host the densest monoclonal antibody manufacturing clusters, with AbbVie and Eli Lilly anchoring production networks around existing immunology infrastructure.
Germany
Neurology clinics in Berlin and Munich maintain substantial prescribing volumes for topiramate and valproate prophylaxis. EMA conditional marketing authorizations enable earlier patient access to novel mechanisms while confirmatory trials continue. The Rhine-Main biotechnology corridor concentrates fill-finish capacity for parenteral migraine therapies serving European distribution networks.
Switzerland
Swissmedic regulatory frameworks support early access programs for breakthrough migraine mechanisms. Novartis and Lundbeck anchor Basel-region pharmaceutical R&D, with specialized CROs supporting clinical trial execution for CGRP pathway inhibitors. The country's precision manufacturing base supplies high-purity excipients for stabilizing parenteral formulations.
India
Contract development and manufacturing organizations in Hyderabad and Bengaluru are building biologics capacity to serve emerging market demand at cost structures below North American production. CDSCO streamlined approval pathways for biosimilars accelerate market entry for preventive therapy alternatives. Gujarat's pharmaceutical zones specialize in oral generic triptan production for export markets.
Japan
PMDA review timelines for migraine biologics align with EMA and FDA standards, enabling near-simultaneous market entry. Tokyo and Osaka headache centers adopt quarterly injectable CGRP antibodies for chronic migraine populations. The Kanto region's cold-chain logistics infrastructure supports direct-to-patient distribution for temperature-sensitive biologics.
Migraine Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue intranasal delivery and digital therapeutic adjacencies. The migraine treatment market consolidates around immunology-focused biopharmaceutical conglomerates with existing monoclonal antibody infrastructure. Three archetypes dominate: legacy neurology players with triptan portfolios, diversified biologics manufacturers leveraging CGRP mechanisms, and specialty pharmaceutical firms pursuing differentiated administration routes. Capacity expansion and strategic partnerships represent the dominant competitive vectors, with manufacturers securing fill-finish capacity and distribution network access.
Among North American biopharmaceutical conglomerates, AbbVie, Eli Lilly and Company, and Pfizer exemplify the diversified biologics archetype. AbbVie occupies a position representing immunology infrastructure repurposing for CGRP-targeted supply chains. Eli Lilly and Company exemplifies differentiation through dosing regimen innovation that extends patient adherence windows. Pfizer anchors the hospital formulary relationship tier, with institutional procurement channel control sustaining volume through established contracts. These three companies represent distinct strategic postures within the preventive therapy expansion trajectory.
| Leading Market Players |
|---|
| AbbVie |
| Amgen |
| Eli Lilly and Company |
| Pfizer |
| Teva Pharmaceutical Industries |
| Novartis |
| Lundbeck |
| GSK |
| AstraZeneca |
| Others |
Supply & Pricing Matrix
United States employer-sponsored insurers mandating home administration training for CGRP inhibitors have forced supply chain reconfiguration toward direct-to-patient cold-chain delivery, compressing margins on nursing support services while elevating logistics premiums for rural coverage.
Pricing Analysis
Service-bundling separates training-inclusive CGRP inhibitor programs from unbundled acute therapy procurement. Three-tier pricing structure across premium intranasal delivery, standard oral tablets, and economy generic triptans reflects administration complexity and onset speed. Cost compression in oral generics intensifies because multi-source competition erodes manufacturer margin, while biologic preventive therapies command sustained premiums through prior authorization gatekeeping. Pharmacy benefit manager preferred tiers render episodic migraine populations most price-sensitive, whereas chronic migraine patients with employer-sponsored coverage exhibit lowest sensitivity due to copay assistance programs.
Supply Chain Analysis
Monoclonal antibody production rests on mammalian cell culture capacity concentrated in Massachusetts, New Jersey, and the Rhine-Main biotechnology corridor. Aseptic fill-finish operations draw from single-source suppliers of pharmaceutical-grade surfactants and stabilizing excipients. REACH authorization requirements for manufacturing inputs introduce regulatory restriction risk for European parenteral formulation output. Distribution runs through specialty pharmacy networks that maintain two-to-eight-degree Celsius stability parameters from manufacturer to patient residence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The migraine treatment market sits in a technology-transition phase as oral CGRP receptor antagonists displace injectable biologics for preventive therapy, eliminating cold-chain burden while expanding primary care prescribing access.
For Market Incumbents: Cement formulary control through multi-year hospital procurement contracts that embed step-therapy requirements protecting against oral small-molecule substitution. Secure captive supply of pharmaceutical-grade excipients to buffer REACH-driven reformulation costs. Prioritize backward integration into monoclonal antibody fill-finish capacity to constrain emerging entrant manufacturing access. For New Entrants and Emerging Players: Telehealth platforms offer the lowest-friction route to patient acquisition for digital therapeutic adjuncts seeking FDA clearance as prescription behavioral interventions. White-space concentrates in India domestic manufacturing for emerging market biosimilar supply and in intranasal acute therapy formats bypassing gastric stasis limitations. Pursue direct-to-patient subscription models that bundle device delivery with remote monitoring. For Investors and Strategic Acquirers: The window for entry favors contract development and manufacturing organizations with proven biologics capacity in Hyderabad or Bengaluru. Long-term viability hinges on regulatory pathway expertise bridging EMA conditional marketing authorization and FDA accelerated approval frameworks. Watch for CDSCO streamlined biosimilar approval velocity as inflection signal for emerging market manufacturing competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Cell culture capacity expansion in Massachusetts anchors CGRP antibody supply security. |
| Regulatory Approval Pathway | FDA accelerated designation compresses development timelines for preventive biologics. |
| Licensing Agreement | Specialty pharmacy network access agreements determine patient reach for cold-chain products. |
| Pipeline Diversification | Intranasal delivery formats capture premium acute therapy positioning beyond oral generics. |
| Clinical Trial Advancement | Confirmatory trial completion secures full EMA marketing authorization for conditional entrants. |
Research Methodology
Document review covered FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases, complemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation validated segmentation outputs across treatment modality, administration route, and regional regulatory clusters.
Market size and growth trajectory outputs reflect analytical framework integration of epidemiological prevalence data, prescribing pattern shifts, and reimbursement pathway evolution across the projection horizon. CAGRs were derived from modeled adoption curves for CGRP-targeted mechanisms versus legacy prophylaxis regimens, with dosage form penetration and specialty pharmacy channel share as key forecast inputs.
Inputs from FDA and EMA regulatory databases were available through the study window; gaps in real-time formulary placement data and payer prior authorization denial rates introduce uncertainty bands around access velocity assumptions. Forecasts reflect documented assumptions regarding biosimilar entry timing and oral small-molecule substitution rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Merkel Cell Carcinoma (MCC) Treatment Market
Medical Treatment
Psittacosis Treatment Market
Medical Treatment
Europe Chronic Disease Management Market
Medical Treatment
Lice Treatment Market
Medical Treatment
CINV Treatment Market
Medical Treatment
Thyroid Gland Disorders Treatment Market
Medical Treatment
Necrotizing Skin Infections Treatment Market
Medical Treatment
Avian Flu Treatment Market
Medical Treatment
Purpura Treatment Market
Medical Treatment
Alagille Syndrome Treatment Market
Medical Treatment
Histoplasmosis Treatment Market
Medical Treatment
Phototherapy Treatment Market
Medical Treatment
Malaria Treatment Market
Medical Treatment
Ligament Repair and Reconstruction Market
Medical Treatment
Thyroid Deficiency Treatment Market
Medical Treatment
Molluscum Contagiosum (MC) Treatment Market