
 Systemic Sclerosis Treatment Market | 2026-2036
Systemic Sclerosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Systemic Sclerosis Treatment Market Analytics
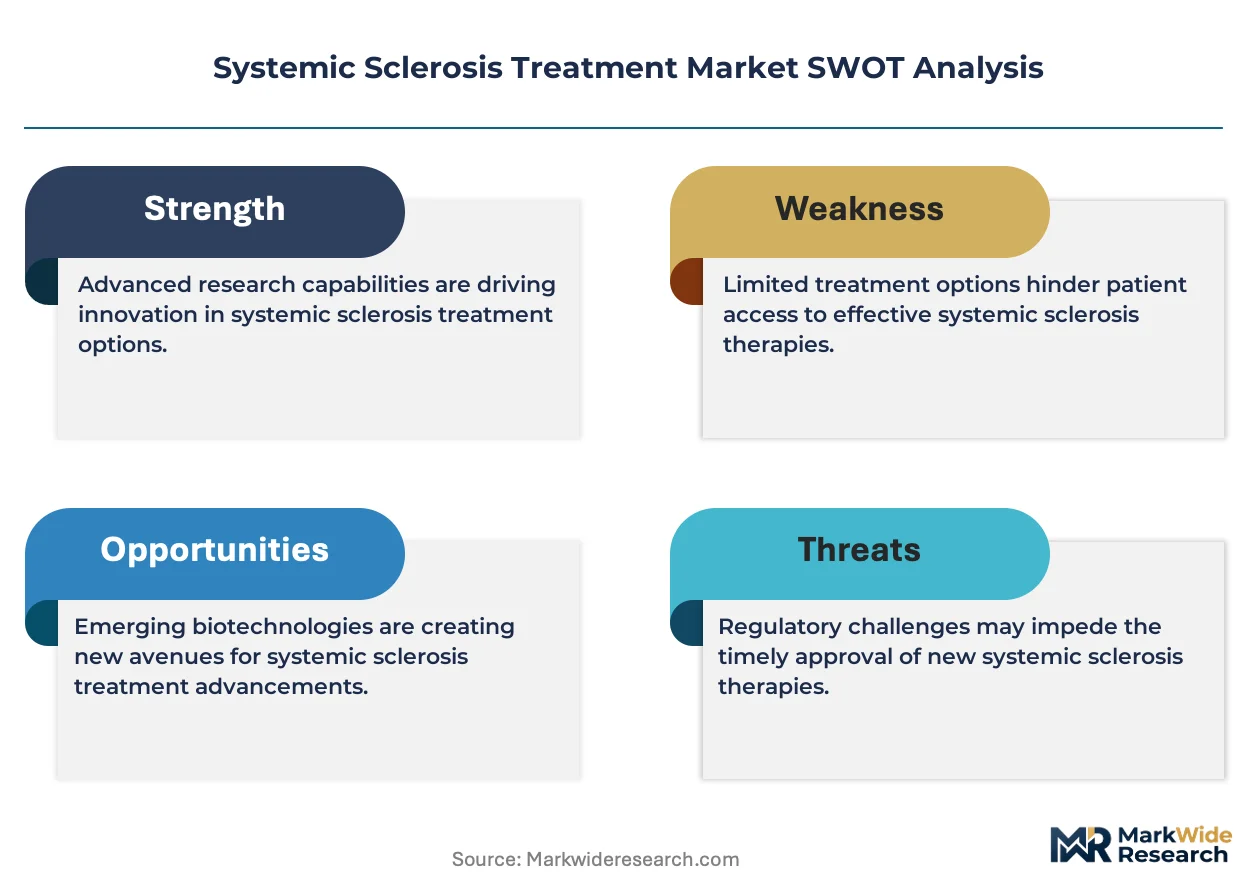
FDA orphan drug exclusivity is shifting the cost-of-entry calculus for systemic sclerosis developers, raising the stakes for clinical trial design and post-market surveillance. AbbVie Inc. leverages its immunology infrastructure to sustain biologic development pipelines across autoimmune indications. Boehringer Ingelheim International GmbH anchors its position through specialized antifibrotic research directed at interstitial lung disease. F. Hoffmann-La Roche Ltd competes via differentiated diagnostics-therapeutics integration in fibrotic disease management.
Systemic sclerosis treatment encompasses pharmacological interventions targeting immune dysregulation, vascular pathology, and fibrotic progression in diffuse and limited cutaneous subtypes; these therapies modulate T-cell activation, B-cell function, and transforming growth factor-beta signaling to preserve organ function and reduce mortality. The primary commercial purpose centers on halting disease progression in a rare autoimmune disorder with heterogeneous organ involvement and limited curative options. Biologics command premium positioning due to targeted mechanism of action in refractory skin and lung disease, while immunosuppressants retain volume leadership in early-line therapy across adult women, the dominant patient demographic. Oral administration routes maintain convenience advantages for chronic maintenance, though intravenous delivery dominates hospital-based initiation of biologic and antifibrotic regimens.
The FDA maintains stringent requirements for rare disease trial endpoints, while the EMA enforces post-authorization efficacy studies under the EU pharmaceutical legislation overhaul, and Japan's PMDA operates accelerated review pathways for serious autoimmune conditions with unmet need. These frameworks collectively elevate evidence standards, extend development timelines, and concentrate commercialization expertise among established rare disease players. Stakeholders must monitor evolving payer evidence requirements for combination therapy positioning and real-world data acceptance across major reimbursement markets.
Market Dynamics
Orphan drug exclusivity windows are compressing development timelines for systemic sclerosis candidates, forcing sponsors to front-load biomarker validation and adaptive trial designs before regulatory submission.
Growth Catalysts
- FDA accelerated approval pathways:The FDA's breakthrough therapy designation for interstitial lung disease subsets enables earlier market entry based on surrogate endpoints, reducing Phase III duration.
- Biomarker-driven patient stratification:Autoantibody profiling and gene expression signatures are refining trial enrollment, improving signal detection in heterogeneous patient populations.
- Germany's orphan drug reimbursement:Germany's G-BA maintains favorable benefit assessment procedures for rare disease therapies, anchoring European commercialization strategy.
Market Restraints
- Plasma-derived biologics input costs:Immunoglobulin and monoclonal antibody manufacturing depends on plasma collection networks concentrated in the United States, exposing margins to supply volatility.
- EMA post-authorization efficacy requirements:The EU pharmaceutical legislation overhaul mandates confirmatory trials after conditional approval, extending evidence generation obligations.
- Diagnostic latency:Average four-year delay from symptom onset to systemic sclerosis diagnosis compresses addressable patient windows and complicates trial recruitment.
Strategic Opportunities
- Japan's PMDA Sakigake designation:Japan's priority review system for serious autoimmune conditions with unmet need offers twelve-month approval timelines and enhanced pricing.
- Digital biomarker integration:Wearable lung function monitoring and smartphone-based skin scoring are converging with telemedicine platforms to enable decentralized trial execution.
- Combination therapy positioning:Immunosuppressant-antifibrotic sequencing protocols create white space for fixed-dose development in diffuse cutaneous subsets.
Industry Challenges
- Rare disease trialist scarcity:Principal investigators with systemic sclerosis expertise concentrate at academic medical centers in Boston, London, and Tokyo, creating site activation bottlenecks.
- Real-world evidence standardization:EMA and FDA maintain divergent requirements for registry-based effectiveness studies, forcing dual-track post-market surveillance infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Systemic Sclerosis Treatment Market |
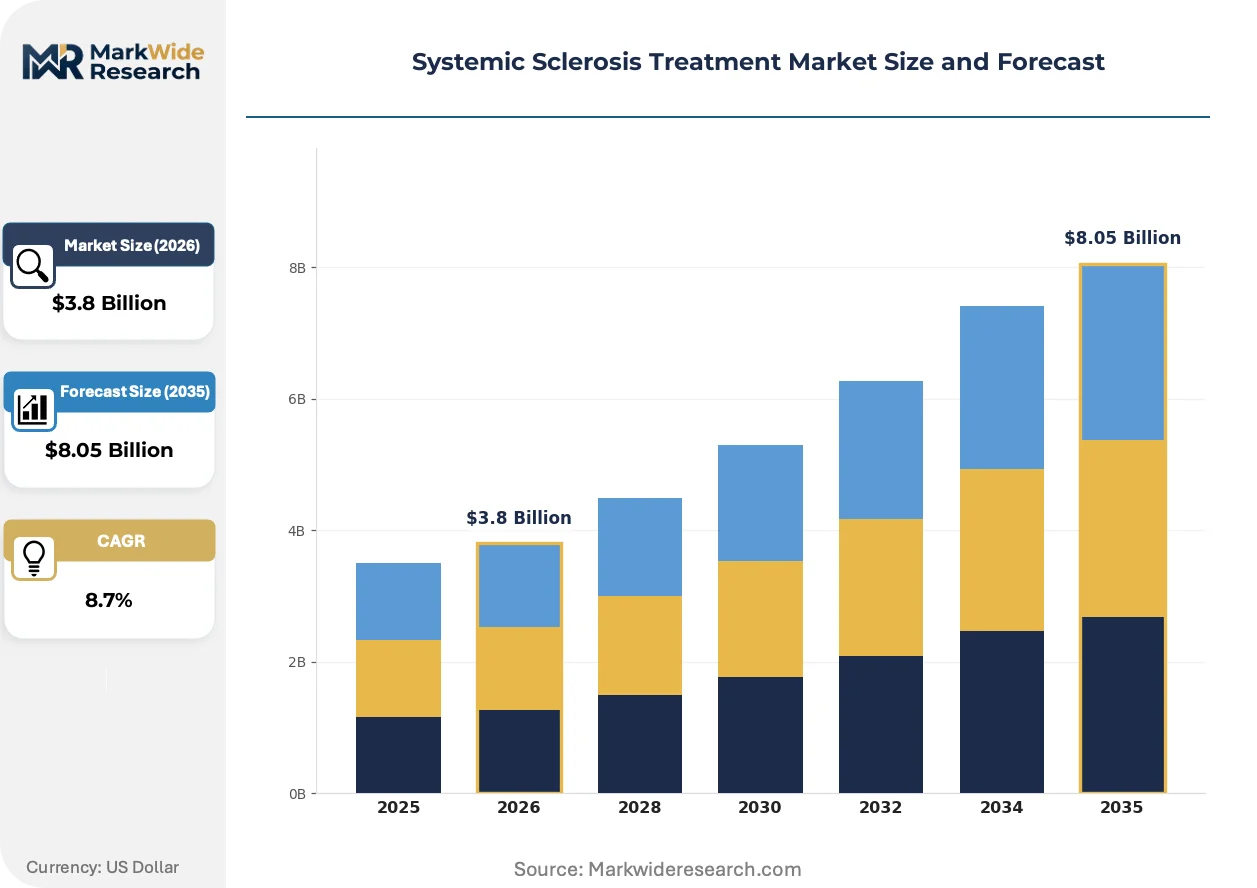
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Immunosuppressants, Antifibrotic Agents, Steroids, Biologics Administration Route: Oral, Subcutaneous, Intravenous, Transdermal Application Area: Skin Involvement, Pulmonary Fibrosis, Gastrointestinal Manifestations, Cardiac Involvement Patient Type: Adult Women, Adult Men, Pediatric Patients, Elderly Patients |
| Companies Covered | AbbVie Inc., Novartis AG, F. Hoffmann-La Roche Ltd, Sanofi, AstraZeneca, Bristol-Myers Squibb Company, GSK plc, Amgen Inc., Boehringer Ingelheim International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Systemic Sclerosis Treatment Market Evolving Landscape
Targeted B-cell and T-cell modulation platforms are displacing broad immunosuppression as the therapeutic backbone, while antifibrotic mechanisms gain parallel traction in interstitial lung disease subsets.
Tyrosine kinase inhibitors are consolidating position in second-line refractory skin disease by offering oral administration advantages over intravenous biologics. Rheumatology clinics in the United States and Germany are adopting these agents for patients failing anti-CD20 therapy. This shift is consolidating market share around small-molecule portfolios with established immunology infrastructure.
REACH registration requirements and the EU Green Deal pharmaceutical strategy are tightening environmental release standards for active pharmaceutical ingredient manufacturing. Contract development organizations face capital demands for wastewater treatment upgrades and solvent recovery systems. Biologics manufacturers with European supply chains are responding by relocating fill-finish operations to facilities with verified green chemistry certifications.
Hospital formulary committees are compressing evaluation cycles for systemic sclerosis therapies from eighteen months to nine months, driven by pharmacy benefit manager consolidation and therapeutic class review standardization. This acceleration favors manufacturers with pre-negotiated distribution agreements and transparent net pricing models. The pattern is most visible in United States integrated delivery networks where specialty pharmacy carve-outs dominate channel access.
Systemic Sclerosis Treatment Market Segmentation
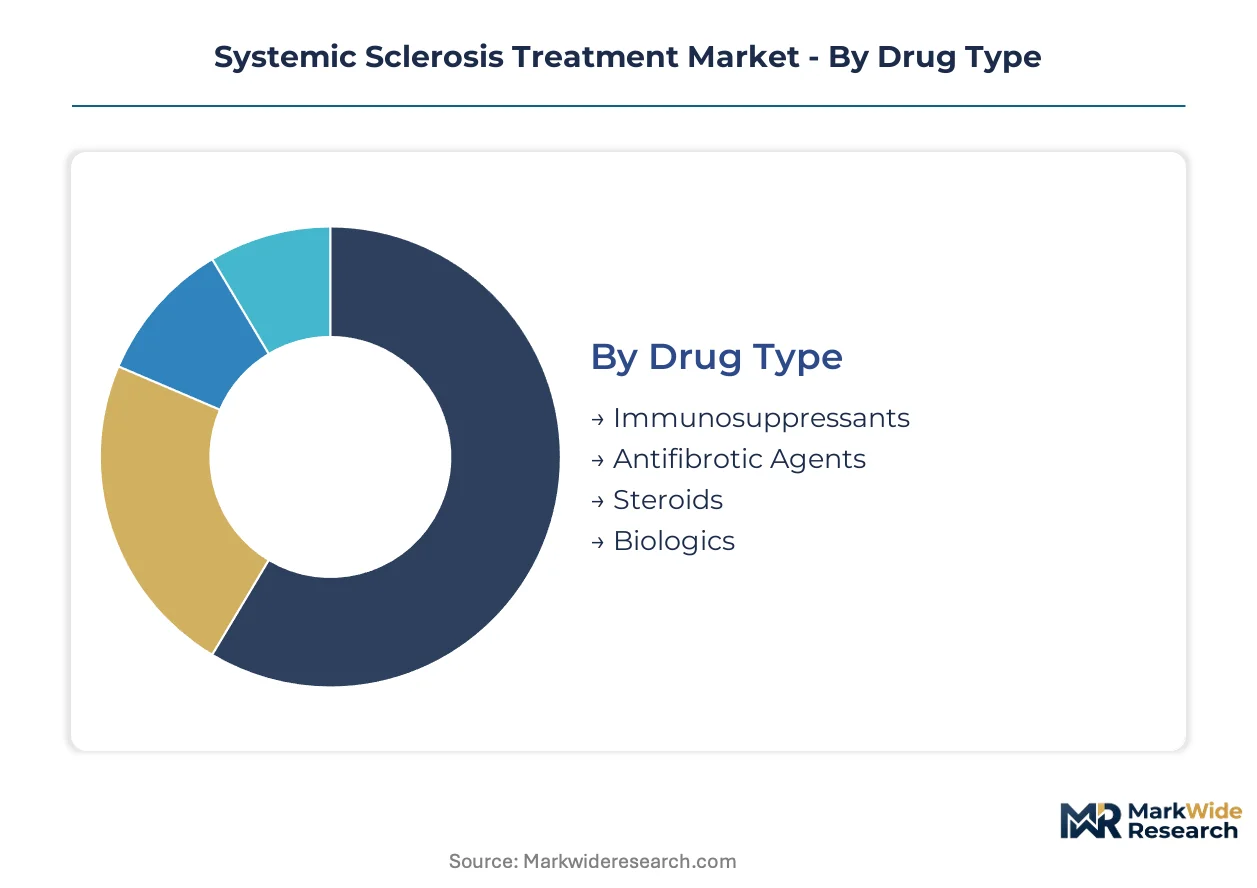
Systemic sclerosis treatment segmentation reflects the disease's heterogeneous organ involvement and the distinct mechanistic approaches required for immune modulation versus fibrotic arrest. Pharmaceutical positioning strategies diverge sharply across these axes, with reimbursement pathways and clinical trial endpoints varying by both drug class and target organ system.
Drug Type:
Mechanism of action defines commercial trajectory, with targeted biologics commanding development investment while immunosuppressants retain volume leadership through established access pathways.
- Biologics:Monoclonal antibodies and fusion proteins targeting B-cell depletion, IL-6 inhibition, and T-cell costimulation blockade deliver precision intervention for refractory diffuse cutaneous and interstitial lung disease subsets. Demand concentrates in United States academic medical centers where FDA breakthrough therapy designations accelerate formulary placement and specialty pharmacy networks manage infused delivery.
- Immunosuppressants:Small-molecule agents including mycophenolate mofetil, cyclophosphamide, and methotrexate constitute first-line standard of care through oral administration convenience and decades of clinical familiarity. Germany's G-BA maintains favorable orphan drug reimbursement for these agents in early diffuse disease, anchoring European volume.
- Antifibrotic Agents:Tyrosine kinase inhibitors and anti-fibrotic compounds targeting TGF-beta signaling and tyrosine kinase pathways address progressive interstitial lung disease with oral dosing advantages over intravenous alternatives.
- Steroids:Corticosteroid protocols manage acute inflammatory flares and overlap syndromes despite limited disease-modifying efficacy in pure systemic sclerosis pathology.
Immunosuppressants lead on scale; biologics lead on momentum.
Administration Route:
Delivery modality shapes patient adherence patterns, site of care economics, and competitive differentiation between hospital-based infusion centers and home-based self-administration models.
- Intravenous:Hospital and infusion center delivery dominates biologic initiation, with United States integrated delivery networks consolidating purchasing through specialty pharmacy carve-outs. EMA post-authorization requirements for infused agents mandate robust pharmacovigilance infrastructure.
- Oral:Small-molecule immunosuppressants and emerging tyrosine kinase inhibitors sustain chronic maintenance therapy through patient self-administration, with Japan's PMDA Sakigake designation prioritizing oral agents for serious autoimmune conditions.
- Subcutaneous:Self-injected biologics bridge convenience and mechanism specificity, gaining traction in German rheumatology clinics where home nursing support reduces hospital burden.
- Transdermal:Topical formulations address limited cutaneous manifestations and digital ulcer management, though systemic efficacy constraints restrict addressable populations.
Oral administration dominates patient-years; intravenous captures revenue intensity per treated case.
Application Area:
Organ-specific targeting determines regulatory strategy, with interstitial lung disease subsets attracting accelerated review pathways and skin-focused programs facing surrogate endpoint validation challenges.
- Pulmonary Fibrosis:Interstitial lung disease represents the leading mortality driver, with FDA breakthrough therapy designations and EMA PRIME eligibility concentrating development resources. Antifibrotic mechanisms gain priority in United States and Japanese reimbursement frameworks where forced vital capacity decline serves as accepted surrogate endpoint.
- Skin Involvement:Modified Rodnan skin score remains the regulatory standard for diffuse cutaneous disease, though heterogeneity in disease trajectory complicates trial design and payer value demonstration.
- Gastrointestinal Manifestations:Motility disorders and malabsorption syndromes drive significant morbidity with limited targeted therapeutic options, creating unmet need for prokinetic and anti-fibrotic approaches.
- Cardiac Involvement:Myocardial fibrosis and pulmonary hypertension subsets command premium pricing where demonstrated mortality benefit supports value-based contracting in German and United States markets.
Pulmonary fibrosis leads on investment intensity; skin involvement leads on addressable prevalence.
Patient Type:
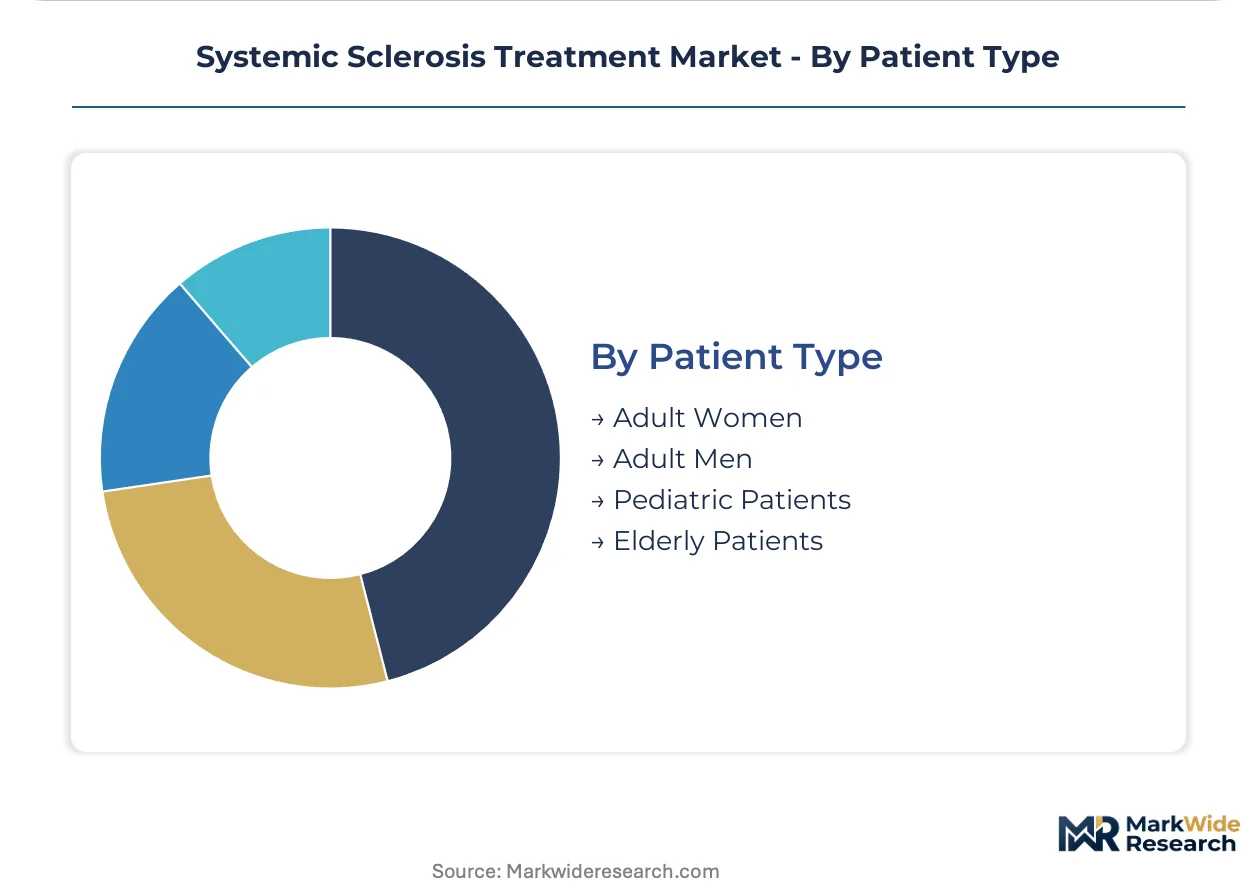
Demographic concentration shapes trial enrollment protocols and commercial targeting, with adult women representing the overwhelming disease burden and pediatric subsets triggering distinct regulatory incentives.
- Adult Women:Comprising approximately 80% of incident cases, this demographic anchors Phase III enrollment and drives United States direct-to-consumer awareness campaigns. Autoantibody profiling refines risk stratification for interstitial lung disease progression in this population.
- Elderly Patients:Comorbidity burden and polypharmacy constraints favor oral small-molecule profiles with established drug-drug interaction data over complex biologic regimens.
- Adult Men:Higher prevalence of diffuse disease and interstitial lung disease in male subsets drives targeted screening protocols and aggressive early immunosuppression approaches.
- Pediatric Patients:Juvenile systemic sclerosis triggers FDA rare pediatric disease priority review vouchers and EMA paediatric investigation plan requirements, though trial recruitment challenges persist.
Adult women lead on absolute patient volume; elderly patients lead on polypharmacy complexity and formulary negotiation leverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Systemic sclerosis therapeutics originated in mid-20th century European academic medical centers before maturing into a commercial specialty anchored by United States biopharma infrastructure and Japanese regulatory innovation.
United States
FDA breakthrough therapy designations for interstitial lung disease subsets concentrate clinical trial activity at Boston and New York academic medical centers. The agency's orphan drug exclusivity framework sustains premium pricing for biologics targeting refractory diffuse cutaneous disease. United States integrated delivery networks consolidate purchasing through specialty pharmacy carve-outs, compressing formulary evaluation cycles.
Germany
Germany's G-BA maintains favorable benefit assessment procedures for rare disease therapies, anchoring European commercialization strategy for immunosuppressants and antifibrotic agents. The Federal Joint Committee's orphan drug reimbursement pathways reduce payer friction for early-line systemic sclerosis treatments. Rheumatology clinics in North Rhine-Westphalia and Bavaria expand biologic adoption through established hospital outpatient networks.
Japan
PMDA's Sakigake designation system offers twelve-month approval timelines for serious autoimmune conditions with unmet need, accelerating market entry for oral small-molecule candidates. Tokyo and Osaka academic centers concentrate principal investigators with systemic sclerosis expertise, enabling rapid site activation for multinational trials. Japan's pricing framework for designated orphan drugs supports sustained investment in refractory disease subsets.
United Kingdom
NICE technology appraisals for rare disease therapies concentrate evaluation expertise in London and Manchester, though post-Brexit divergence from EMA standards complicates parallel regulatory submissions. The NHS England specialized commissioning framework for autoimmune conditions creates centralized access pathways for high-cost biologics. UK biobank infrastructure supports biomarker validation for patient stratification in diffuse cutaneous trials.
Switzerland
Swissmedic operates accelerated review pathways for medicines addressing serious unmet medical needs, complementing EMA procedures for systemic sclerosis candidates. Basel and Zurich anchor European pharmaceutical R&D infrastructure, with contract research organizations specializing in rare disease trial execution. Swiss pricing negotiations for orphan drugs reference German and French benchmarks, creating regional coherence in value assessment.
Systemic Sclerosis Treatment Market Competitive Landscape
The competitive structure tilts toward diversified immunology platforms with established rare disease commercial infrastructure. Development pipelines concentrate among large-cap biopharmaceuticals with legacy autoimmune portfolios, while mid-cap specialists pursue targeted mechanisms in interstitial lung disease subsets. Two strategic archetypes dominate: integrated immunology platforms leveraging cross-indication regulatory experience, and fibrosis-focused developers with specialized biomarker capabilities. Competitive moves center on portfolio diversification into combination therapy positioning and geographic expansion through pre-negotiated distribution agreements in United States integrated delivery networks.
Within the integrated immunology tier, AbbVie Inc. and F. Hoffmann-La Roche Ltd occupy positions defined by cross-portfolio infrastructure and diagnostics-therapeutics linkages. Boehringer Ingelheim International GmbH represents the specialized antifibrotic archetype, with organizational structure reflecting concentrated research investment in interstitial lung disease mechanisms. These three entities exemplify the capability requirements for sustained participation: regulatory affairs specialization across FDA, EMA, and PMDA jurisdictions; established rare disease patient access programs; and biomarker-integrated clinical trial execution.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Novartis AG |
| F. Hoffmann-La Roche Ltd |
| Sanofi |
| AstraZeneca |
| Bristol-Myers Squibb Company |
| GSK plc |
| Amgen Inc. |
| Boehringer Ingelheim International GmbH |
| Others |
Value Network & Pricing Analysis
Captive plasma collection networks in the United States anchor biologic manufacturing economics, concentrating supply leverage among immunoglobulin producers while forcing price premiums for plasma-dependent monoclonal antibodies. This integration pattern sustains margin structures for infused therapies even as oral small-molecules erode pricing power in maintenance segments.
Pricing Analysis
Bundled infusion services dominate biologic delivery, with hospital outpatient departments capturing facility fees alongside drug costs while unbundled oral prescriptions flow through retail pharmacy networks. Three-tier pricing structure across premium biologics, standard immunosuppressants, and economy corticosteroid protocols reflects mechanism specificity and organ-targeting precision. Pricing pressure stems from United States integrated delivery network consolidation, compressing net prices for infused agents. Academic medical centers exhibit lowest price sensitivity due to research funding offsets; community rheumatology practices face highest sensitivity due to capitated reimbursement.
Supply Chain Analysis
Freight costs for temperature-controlled biologics from United States plasma fractionators to European fill-finish facilities impose working capital burdens that amplify batch-release delays. Manufacturing concentrates in the United States, Germany, and Switzerland, with active pharmaceutical ingredient synthesis drawing from Indian and Chinese contract manufacturers. Supply chain risk centers on single-source plasma collection vulnerability exposed to donor availability fluctuations. Distribution runs through specialty pharmacy carve-outs in United States integrated delivery networks and hospital outpatient pharmacies in German rheumatology centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Systemic sclerosis therapeutics represent a late-cycle quality story as payer pathways mature and development pipelines shift toward precision mechanisms targeting interstitial lung disease subsets with demonstrated mortality benefit.
For Market Incumbents: To counter biosimilar erosion in immunosuppressant categories, AbbVie Inc. and F. Hoffmann-La Roche Ltd should deepen diagnostics-therapeutics integration through companion biomarker platforms while securing exclusive distribution agreements with United States specialty pharmacy networks. Regulatory affairs specialization across FDA, EMA, and PMDA jurisdictions remains essential for accelerated pathway access. For New Entrants and Emerging Players: Enter via gastrointestinal manifestation subsets where prokinetic and anti-fibrotic mechanisms face minimal established competition, targeting Japan's PMDA Sakigake designation for oral small-molecule candidates. Germany's G-BA orphan drug reimbursement pathway offers lowest payer friction for early-line positioning in diffuse cutaneous disease. For Investors and Strategic Acquirers: Roll-up economics work for fibrosis-focused specialists because biomarker-integrated trial capabilities concentrate among mid-cap developers with EMA PRIME eligibility and FDA breakthrough therapy designations. Five-to-ten year viability hinges on combination therapy positioning in interstitial lung disease. Watch FDA advisory committee posture on surrogate endpoint acceptance as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker-Integrated Trial Design | Autoantibody profiling refines patient stratification for FDA breakthrough pathway eligibility. |
| Specialty Pharmacy Distribution Agreements | Pre-negotiated United States carve-outs compress formulary evaluation cycles to nine months. |
| EMA PRIME Designation Pursuit | Accelerated assessment timelines reduce development risk for interstitial lung disease candidates. |
| Plasma Supply Security Investments | Vertical control over United States collection networks insulates margins from donor volatility. |
| Digital Biomarker Platform Development | Wearable lung function monitoring enables decentralized trial execution and real-world evidence generation. |
Research Methodology
Multiple input streams — regulatory filing analysis, clinical trial database extraction, and payer policy documentation — were reconciled against primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and German G-BA benefit assessment reports. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Data-stream reconciliation across the projection horizon applied treatment-line stratification, administration-route segmentation, and regional regulatory clustering to derive volume and value trajectories. CAGRs were computed from modeled annual progression rates applied to base-year estimates. Forecast inputs incorporated orphan drug exclusivity windows, biomarker adoption curves, and payer pathway maturation indices specific to rare autoimmune therapeutics.
Inputs from FDA advisory committee transcripts and EMA rapporteur assessment reports were available through the study window; gaps in real-world evidence standardization across jurisdictions introduce uncertainty bands around combination therapy adoption timelines. Forecasts reflect documented assumptions regarding regulatory pathway success rates and payer value demonstration thresholds. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Molluscum Contagiosum (MC) Treatment Market
Medical Treatment
Sepsis Treatment Market
Medical Treatment
Tennis Elbow Treatment Market
Medical Treatment
Urea Cycle Disorders Treatment Market
Medical Treatment
Transarterial Chemoembolization (TACE) Market
Medical Treatment
Factor XIII Deficiency Treatment Market
Medical Treatment
Ringworm Treatment Market
Medical Treatment
Aspergillosis Treatment Market
Medical Treatment
Asthma Treatment Market
Medical Treatment
Acupuncture Treatment Market
Medical Treatment
Global Nano Therapy Market
Medical Treatment
Global Von Willebrand Disease Treatment Market
Medical Treatment
Hyperkalemia Treatment Market
Medical Treatment
Lyme Disease Treatment Market
Medical Treatment
Leprosy Treatment Market
Medical Treatment
Mast Cell Tumors Treatment Market