
 Radioimmunotherapy Treatment Market | 2026-2036
Radioimmunotherapy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Radioimmunotherapy Treatment Market Analytics
Asset-light contract manufacturing and radiopharmaceutical leasing arrangements is tilting competitive dynamics toward firms that avoid heavy isotope production investments. Novartis leverages its established radioligand therapy infrastructure to anchor supply security across multiple markets. Telix Pharmaceuticals sustains R&D intensity through specialized partnerships rather than captive manufacturing. Bayer Healthcare Pharmaceuticals dominates commercial scale in approved radioimmunotherapy indications through controlled distribution networks.
Radioimmunotherapy treatment deploys monoclonal antibodies conjugated with therapeutic radioisotopes to deliver cytotoxic radiation directly to malignant cells, typically utilizing beta-emitters like yttrium-90 or lutetium-177 with half-lives calibrated to tumor residence time. This precision mechanism spares surrounding healthy tissue while inducing DNA double-strand breaks in targeted cancer populations. Radiolabeled antibodies command the dominant margin pool as established reimbursement codes and proven clinical outcomes attract concentrated investment. Targeted alpha therapies represent the fastest-advancing segment, with actinium-225 and lead-212 conjugates demonstrating superior linear energy transfer against resistant micrometastases.
The FDA oversees radiopharmaceutical chemistry, manufacturing, and controls through its Office of Radiological Health, while the Nuclear Regulatory Commission governs isotope handling, dosage administration, and waste disposal protocols that dictate site certification requirements. EMA's centralized marketing authorization procedure and REACH compliance for isotope supply chains create dual regulatory thresholds for transatlantic market participants. Stakeholders must monitor evolving CMS reimbursement determinations for novel radioisotopes and prepare for potential site-of-care policy shifts that could redirect treatment volume between hospital outpatient departments and freestanding clinics.
Market Dynamics
The radioimmunotherapy treatment market pivots on isotope supply security, where reactor-dependent production of lutetium-177 and actinium-225 creates chokepoints that dictate which developers can scale commercial operations. This supply architecture concentrates competitive advantage among firms with secured radioisotope contracts.
Growth Catalysts
- CMS reimbursement expansion:Medicare's coverage determinations for novel radioisotopes in lymphoma and prostate cancer indications accelerate hospital outpatient department adoption across United States oncology networks.
- Targeted alpha therapy:Actinium-225 conjugates demonstrate superior linear energy transfer against resistant micrometastases, pulling R&D investment toward next-generation radioligand platforms.
- Academic medical centers:Major university hospitals integrate radiolabeled antibodies into standard lymphoma protocols, creating institutional demand anchors for approved therapies.
Market Restraints
- Reactor supply concentration:High-assay low-enriched uranium conversion timelines and aging research reactor infrastructure in Canada and Netherlands constrain actinium-225 availability.
- Radiopharmaceutical half-life logistics:Lutetium-177's 6.6-day decay window imposes just-in-time manufacturing and distribution requirements that limit treatment site radius.
- NRC site certification:Nuclear Regulatory Commission licensing for isotope handling, dosage administration, and waste disposal creates multi-year barriers to new treatment center entry.
Strategic Opportunities
- Freestanding clinic channel:Site-of-care policy evolution redirects treatment volume from hospital outpatient departments toward specialized radiopharmaceutical infusion centers with lower overhead structures.
- India manufacturing:Contract manufacturing organizations in Indian pharmaceutical corridors leverage BIS standards alignment and CDSCO regulatory pathways to serve Asia-Pacific demand.
- Dual-isotope platforms:Convergence of diagnostic gallium-68 and therapeutic lutetium-177 theranostics creates integrated treatment planning workflows that command premium positioning.
Industry Challenges
- Radioisotope handling expertise:Nuclear pharmacy specialists and radiation safety officers remain scarce, constraining treatment center expansion timelines.
- Cold chain infrastructure:Capital requirements for compliant storage, transport, and waste management systems exceed typical oncology clinic investment thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radioimmunotherapy Treatment Market |
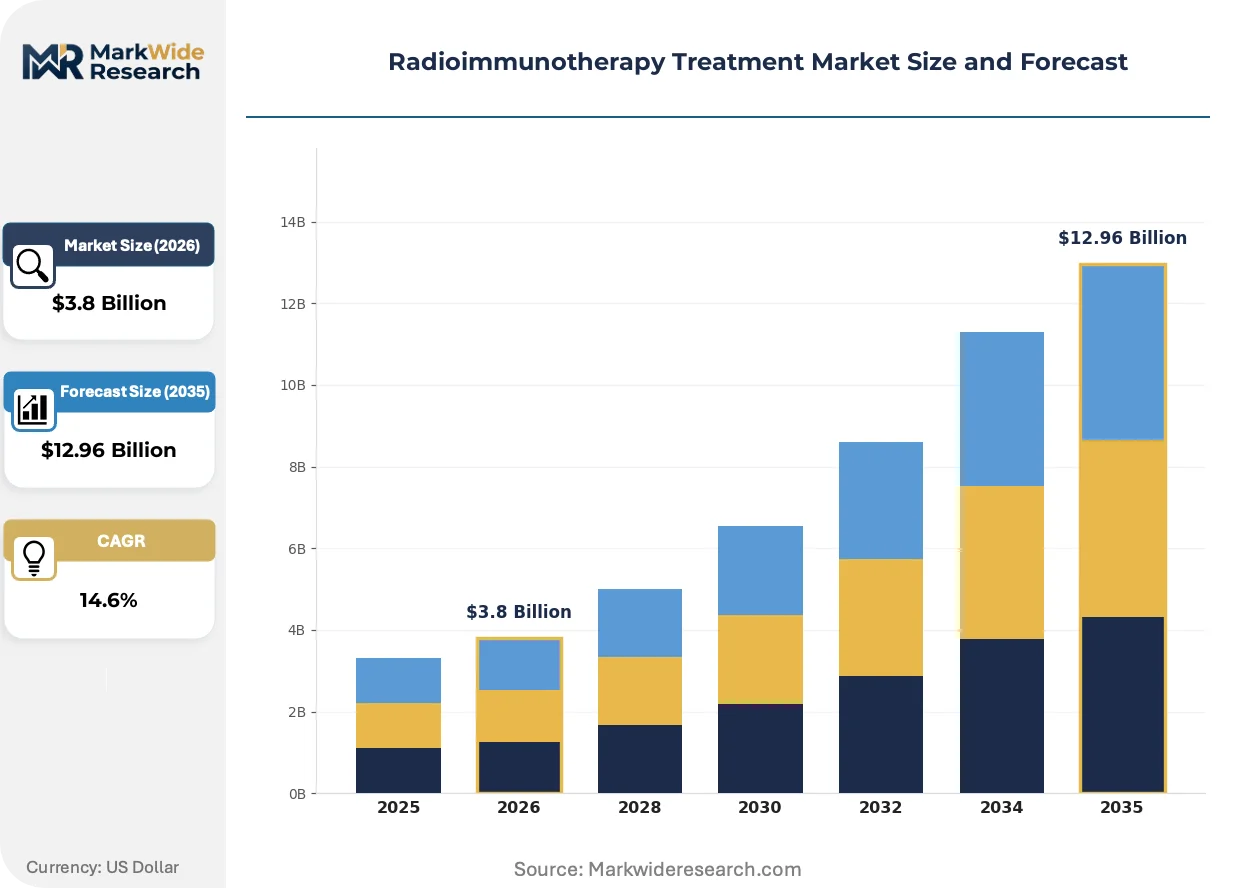
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Radiolabeled Antibodies, Combination Therapies, Targeted Alpha Therapies Therapy Area: Oncology, Hematology, Autoimmune Disorders, Infectious Diseases Delivery Mode: Intravenous, Subcutaneous, Oral, Topical End User: Hospitals, Clinics, Research Laboratories, Home Care |
| Companies Covered | Bayer Healthcare Pharmaceuticals, Telix Pharmaceuticals, Actinium Pharmaceuticals, Clarity Pharmaceuticals, Nordic Nanovector, Immunomedics, BioSynthema, Novartis, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radioimmunotherapy Treatment Market Evolving Landscape
Radioimmunotherapy development is compressing traditional pharmaceutical timelines through theranostic pairing and decentralized manufacturing models. Three convergent forces are restructuring how radiolabeled therapies reach patients.
Alpha-emitting radionuclides are collapsing the efficacy gap between first-line and salvage therapy settings. Actinium-225 and lead-212 conjugates deliver irreparable DNA double-strand breaks to resistant cancer cell populations. Oncology departments at major academic medical centers in the United States and Germany are fast-tracking these agents into early-line protocols, compressing historical progression timelines for metastatic disease management.
EMA's centralized marketing authorization procedure is harmonizing radiopharmaceutical quality standards across European Union member states. REACH compliance requirements for isotope supply chains create dual regulatory thresholds that favor developers with established European distribution infrastructure. Transatlantic market participants are responding by consolidating chemistry, manufacturing, and controls documentation to satisfy both FDA and EMA reviewer expectations simultaneously.
Hospital procurement committees are consolidating vendor relationships around full-service radiopharmaceutical partners. Single-source contracts covering isotope supply, dose preparation, logistics, and waste management are displacing fragmented multi-vendor arrangements. This concentration is most visible in United States metropolitan markets where integrated delivery networks negotiate system-wide agreements.
Radioimmunotherapy Treatment Market Segmentation
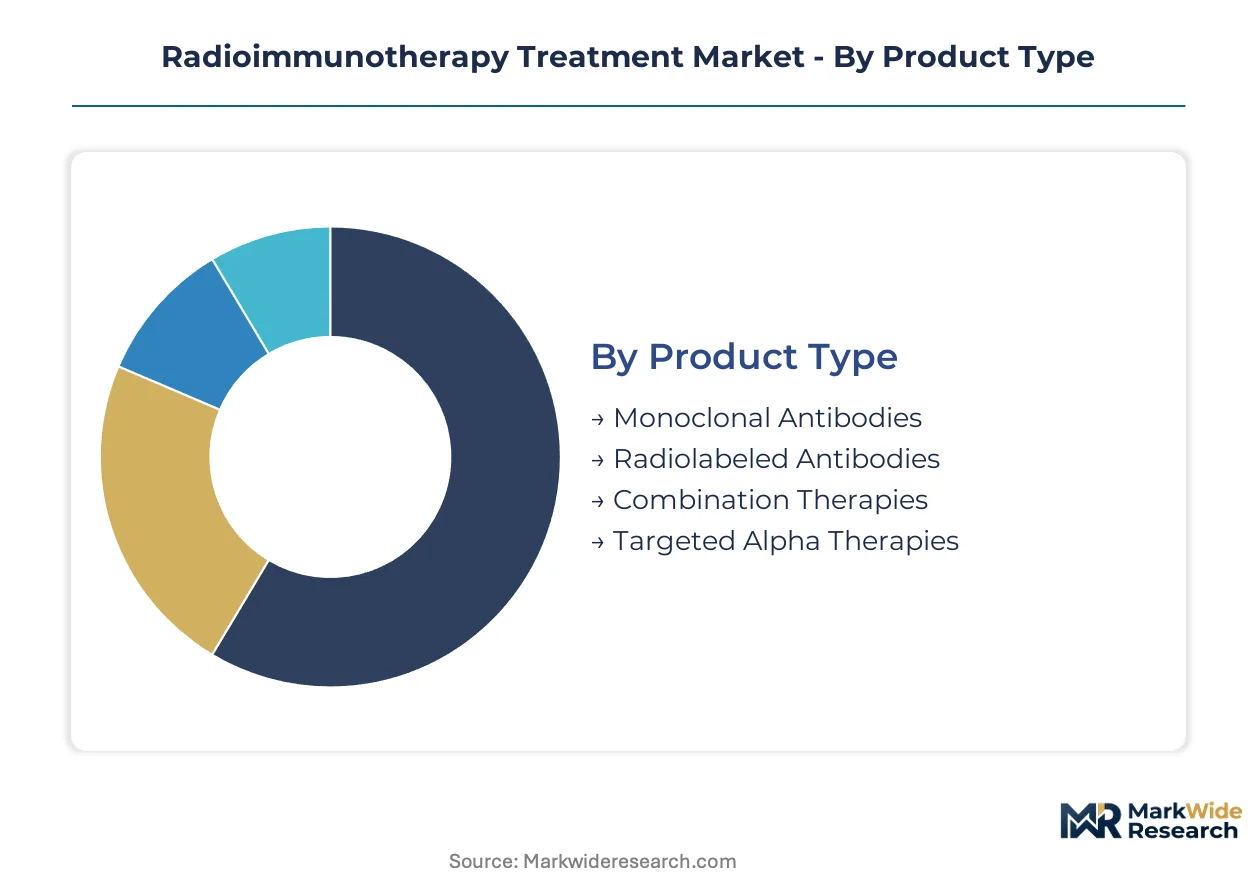
Radioimmunotherapy treatment market segmentation reveals distinct commercial tiers where radiolabeled antibodies command premium positioning while targeted alpha therapies reshape competitive boundaries. Product architecture and therapy area specialization determine reimbursement codes, manufacturing complexity, and site certification requirements.
Product Type:
Cost tier differentiation separates established radiolabeled platforms from emerging alpha-emitting constructs with divergent isotope supply economics.
- Radiolabeled Antibodies:Monoclonal antibodies conjugated with beta-emitting isotopes like lutetium-177 or yttrium-90 deliver cytotoxic radiation calibrated to tumor residence time. United States hospital outpatient departments anchor demand through established Medicare reimbursement codes for lymphoma indications.
- Targeted Alpha Therapies:Actinium-225 and lead-212 conjugates exploit superior linear energy transfer to induce irreparable DNA double-strand breaks in resistant micrometastases. Academic medical centers in Germany and the United States are fast-tracking these agents into early-line protocols.
- Monoclonal Antibodies:Unlabeled antibody platforms serve as backbone constructs for future radioconjugation development.
- Combination Therapies:Sequential or concurrent radiolabeled and systemic agents address heterogenous tumor populations.
Radiolabeled Antibodies holds installed capacity. Targeted Alpha Therapies is rotating up the share rankings.
Therapy Area:
Application focus determines clinical trial design, regulatory pathway selection, and partnership strategies with academic investigators.
- Oncology:Solid tumors and hematologic malignancies represent the primary addressable population for commercial radioligand programs. Prostate cancer and neuroendocrine tumor indications concentrate United States reimbursement investment.
- Hematology:Lymphoma subtypes including non-Hodgkin and Hodgkin disease constitute the historical foundation of approved radioimmunotherapy agents. Major academic medical centers integrate these protocols into standard-of-care sequences.
- Autoimmune Disorders:Radiolabeled antibody applications in immune cell depletion remain investigational with limited clinical translation.
- Infectious Diseases:Targeted radiopharmaceutical approaches to resistant bacterial or viral reservoirs are preclinical.
Oncology holds installed capacity. Hematology is rotating up the share rankings.
Delivery Mode:
Volume concentration follows intravenous administration due to isotope half-life logistics and radiation safety protocols that constrain alternative routes.
- Intravenous:Systemic circulation enables antibody distribution to disseminated disease sites with controlled infusion rates. Hospital outpatient departments and specialized nuclear medicine suites manage the required radiation monitoring.
- Subcutaneous:Depot formation alters pharmacokinetic profiles for selected antibody constructs with modified clearance properties.
- Oral:Gastrointestinal radiopharmaceutical delivery faces bioavailability barriers and radiation exposure concerns.
- Topical:Surface applications for cutaneous lymphoma or localized lesions occupy niche positioning with limited scaling potential.
Intravenous holds installed capacity. Subcutaneous is rotating up the share rankings.
End User:
Customer type stratification reflects capital requirements for isotope handling infrastructure and regulatory certification depth.
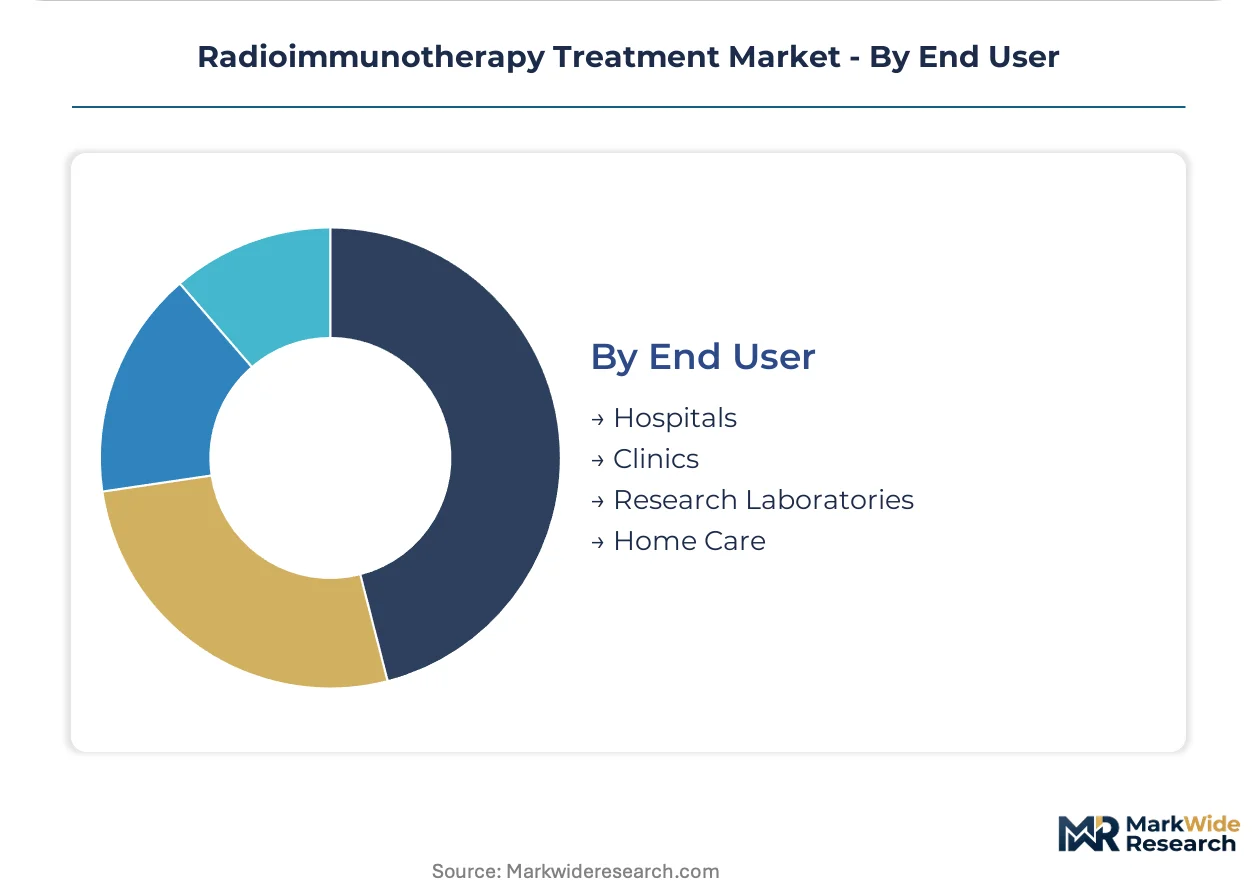
- Hospitals:Integrated delivery networks and academic medical centers possess Nuclear Regulatory Commission licensing for isotope receipt, storage, administration, and waste management. Medicare reimbursement policies favor hospital outpatient department billing.
- Clinics:Freestanding infusion centers with specialized radiopharmaceutical capabilities are expanding as site-of-care policies evolve toward lower-overhead settings.
- Research Laboratories:Preclinical and early-phase clinical sites drive pipeline expansion through investigator-initiated trials.
- Home Care:Radiation safety constraints and isotope decay logistics currently preclude home-based administration.
Hospitals holds installed capacity. Clinics is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement policies in the United States and EMA centralized procedures in Germany are accelerating clinical translation timelines. Hospital outpatient departments and academic medical centers in these markets anchor initial demand for radiolabeled antibody protocols.
United States
CMS coverage determinations for novel radioisotopes in lymphoma and prostate cancer indications drive hospital outpatient department adoption across oncology networks. The FDA's Office of Radiological Health oversees chemistry, manufacturing, and controls for radiopharmaceutical approval. The Greater Boston and San Francisco Bay Area clusters concentrate early-phase clinical trial activity for next-generation radioligand platforms.
Germany
Academic medical centers in Heidelberg and Munich integrate actinium-225 conjugates into early-line protocols for resistant micrometastases. EMA centralized marketing authorization harmonizes quality standards across EU member states. The Rhine-Main and Upper Bavaria regions host specialized nuclear medicine suites managing radiation safety protocols for therapeutic isotope administration.
Switzerland
Swissmedic's regulatory pathway for radiopharmaceuticals attracts developers seeking parallel FDA-EMA submission strategies. Basel and Zurich anchor contract manufacturing and radiopharmaceutical logistics infrastructure. The country's dual-track regulatory alignment supports transatlantic clinical trial coordination for lutetium-177 based therapies.
India
CDSCO regulatory pathways and BIS standards alignment enable contract manufacturing organizations in pharmaceutical corridors to serve Asia-Pacific demand. Mumbai and Hyderabad clusters specialize in antibody production and radioconjugation chemistry for export markets. Domestic hospital networks in Delhi-NCR and Karnataka are building nuclear medicine capacity for regional patient access.
Japan
PMDA's structured consultation framework for radiopharmaceuticals accelerates local clinical development timelines. The Kanto region around Tokyo concentrates hospital-based nuclear medicine infrastructure for isotope handling and waste management. Osaka and Nagoya academic centers participate in global trials for targeted alpha therapy agents against solid tumors.
Radioimmunotherapy Treatment Market Competitive Landscape
On the supply side, the industry is consolidating around firms with secured radioisotope contracts and established distribution infrastructure. Reactor-dependent production of lutetium-177 and actinium-225 creates supply chokepoints that favor players with backward integration into isotope sourcing or long-term supply agreements. Three strategic archetypes dominate: integrated pharmaceutical conglomerates with captive radioligand platforms, specialized radiopharmaceutical developers leveraging partnership manufacturing, and contract manufacturers serving multiple pipeline assets. Competitive moves center on securing reactor capacity allocations and expanding site-of-care networks through specialized clinic partnerships.
Within the integrated pharmaceutical tier, Novartis and Bayer Healthcare Pharmaceuticals exemplify scale-driven positioning through controlled distribution networks and established reimbursement relationships. Telix Pharmaceuticals represents the specialized developer archetype, sustaining R&D intensity through external manufacturing partnerships rather than captive production infrastructure. These three anchors illustrate how supply security and commercial infrastructure, rather than molecule innovation alone, determine competitive position in radioimmunotherapy.
| Leading Market Players |
|---|
| Bayer Healthcare Pharmaceuticals |
| Telix Pharmaceuticals |
| Actinium Pharmaceuticals |
| Clarity Pharmaceuticals |
| Nordic Nanovector |
| Immunomedics |
| BioSynthema |
| Novartis |
| GlaxoSmithKline |
| Others |
Value Network & Pricing Analysis
The Greater Boston biopharmaceutical corridor concentrates radiopharmaceutical manufacturing infrastructure where reactor-dependent isotope supply constraints translate directly into pricing power for developers with secured lutetium-177 and actinium-225 contracts. Academic medical centers and hospital outpatient departments absorb premium positioning for approved radioimmunotherapy agents as reimbursement codes consolidate around established radiolabeled antibody protocols.
Pricing Analysis
Certification level (FDA-grade radiopharmaceutical manufacturing) creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels reflects NRC site certification depth, cold chain infrastructure investment, and waste management capability bundling. Cost compression in the economy tier intensifies because contract manufacturing organizations in Indian pharmaceutical corridors leverage BIS standards alignment to undercut established Western producers. Hospital outpatient departments demonstrate lowest price sensitivity due to Medicare reimbursement protection, while freestanding clinics face margin pressure from capital requirements for compliant storage systems.
Supply Chain Analysis
Contract manufacturing organizations in India, Switzerland, and the United States hold radiopharmaceutical production capacity for antibody conjugation and isotope handling. The supply chain draws from high-assay low-enriched uranium conversion facilities in Canada and the Netherlands, specialized reactor infrastructure for actinium-225 generation, and gallium-68 generator distribution networks. Single-source vulnerability concentrates in aging research reactor infrastructure where conversion timelines constrain actinium-225 availability. Distribution runs through controlled radiopharmaceutical logistics partners managing just-in-time dose preparation within lutetium-177's 6.6-day decay window.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through NRC site certification and FDA radiopharmaceutical approval pathways creates substantial barriers to competitive replication. Switching costs for hospital outpatient departments anchor demand around established isotope supply relationships.
For Market Incumbents: Insulate market position by securing long-term reactor capacity allocations for actinium-225 and lutetium-177 through direct supply agreements or backward integration into isotope production. Expand site-of-care networks through specialized clinic partnerships before freestanding infusion centers achieve critical mass. Counter emerging contract manufacturing threats from Indian pharmaceutical corridors by emphasizing FDA-grade certification depth and established reimbursement relationships with Medicare. For New Entrants and Emerging Players: Pursue white-space opportunity in targeted alpha therapy platforms where academic medical centers in Germany and the United States are fast-tracking actinium-225 conjugates into early-line protocols. Concentrate initial commercial efforts on lymphoma indications where established reimbursement codes reduce payer access friction. Deploy asset-light partnership models with specialized radiopharmaceutical contract manufacturers to avoid capital-intensive reactor infrastructure investments. For Investors and Strategic Acquirers: Long-term, this sits as a supply-security play because reactor-dependent isotope production creates chokepoints that favor developers with secured radioisotope contracts and established distribution infrastructure. Target acquisition candidates with FDA-approved radioligand platforms and captive manufacturing relationships or long-term supply agreements. Monitor CMS reimbursement determinations for novel radioisotopes as the primary inflection signal for treatment volume expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Reactor Capacity Securement | Long-term isotope supply agreements with Canadian and Dutch facilities lock in actinium-225 availability for scaling commercial operations. |
| Freestanding Clinic Partnership | Site-of-care policy evolution redirects treatment volume from hospital outpatient departments toward specialized radiopharmaceutical infusion centers. |
| FDA Radiopharmaceutical Submission | Streamlined approval pathway through the Office of Radiological Health accelerates clinical translation timelines for developers. |
| Dual-Isotope Theranostic Platform | Convergence of diagnostic gallium-68 and therapeutic lutetium-177 creates integrated treatment planning workflows commanding premium positioning. |
| India Manufacturing Scale-Up | CDSCO regulatory pathways enable contract manufacturing organizations in Mumbai and Hyderabad corridors to serve Asia-Pacific demand expansion. |
Research Methodology
The analysis maps radiolabeled antibodies, targeted alpha therapies, monoclonal antibody platforms, and combination therapy constructs, each validated through nuclear medicine specialists, regulatory affairs leads at radiopharmaceutical developers, hospital procurement managers, and payer access specialists. Primary interview intelligence triangulates against FDA filings, EMA centralized marketing authorization submissions, ClinicalTrials.gov records, and CMS reimbursement determination databases. Bottom-up patient volume modeling and top-down market sizing approaches reconcile across the analysis window.
Assumptions held fixed include current NRC site certification requirements, existing Medicare reimbursement policies for approved radioisotopes, and reactor infrastructure capacity in Canada and the Netherlands. Variables tested include site-of-care policy evolution timing, actinium-225 supply expansion trajectories, and academic medical center protocol integration rates. Segmentation dimensions encompass product type, therapy area, delivery mode, and end-user category with geographic regulatory cluster overlays. CAGRs derive from patient population epidemiology, treatment penetration curves, and pricing trajectory modeling across hospital outpatient and freestanding clinic channels.
Sensitivities concentrate around reactor conversion timeline delays, CMS coverage determination reversals for novel radioisotopes, and NRC regulatory relaxation for freestanding clinic certification. Forecasts reflect documented assumptions regarding isotope supply security and reimbursement policy stability. Quarterly review of FDA radiopharmaceutical approval decisions, CMS national coverage determinations, and reactor infrastructure investment announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Amyloidosis Treatment Market
Medical Treatment
Thyroid Deficiency Treatment Market
Medical Treatment
Middle Ear Infection Treatment Market
Medical Treatment
Systemic Inflammatory Response Syndrome Treatment Market
Medical Treatment
Frozen Skin Graft Market
Medical Treatment
Global Autoimmune Treatment Market
Medical Treatment
North America Nerve Repair and Regeneration Market
Medical Treatment
Hyperphosphatemia Treatment Market
Medical Treatment
Japan Radiotherapy Market
Medical Treatment
Trauma and Extremities Market
Medical Treatment
Ventral Hernia Treatment Market
Medical Treatment
Cephalic Disorders Treatment Market
Medical Treatment
Cervical Cancer Treatment Market
Medical Treatment
Surgical Procedures Volume Market
Medical Treatment
Motion Sickness Treatment Market
Medical Treatment
Dementia and Alzheimers Disease Treatment Market