
 Peri-Implantitis Treatment Market | 2026-2036
Peri-Implantitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Peri-Implantitis Treatment Market Analytics
ISO 13485 certification cycles for dental device manufacturers is collapsing from three-year to annual surveillance audits in major markets. Straumann Group leverages its Swiss manufacturing base to sustain premium positioning across implant maintenance portfolios. Dentsply Sirona anchors North American distribution through integrated digital dentistry workflows. Geistlich Pharma AG specializes in xenogeneic collagen matrices that dominate European regenerative periodontal protocols.
Peri-implantitis treatment encompasses therapeutic interventions targeting inflammatory destruction of soft and hard tissues surrounding osseointegrated dental implants, employing antimicrobial decontamination, guided bone regeneration with particulate or block grafts, and adjunctive laser photodynamic therapy at wavelengths between 810-980 nanometers. The primary purpose is to arrest disease progression, re-establish peri-implant tissue seal integrity, and preserve functional implant load-bearing capacity. Antimicrobial agents occupy the largest revenue share due to repetitive purchase cycles in maintenance protocols, while laser therapy represents the fastest-expanding segment as chairside delivery reduces specialist referral bottlenecks. Surgical intervention commands premium pricing through bone graft adjuncts, whereas topical application segments compete on formulary inclusion across dental group purchasing organizations.
The FDA regulates bone graft substitutes as Class II or III devices requiring 510(k) clearance or PMA approval based on structural similarity to predicate products, while the EU MDR demands clinical evaluation reports with post-market surveillance for all implantable periodontal biomaterials. EMA guidance on human-derived tissue products further constrains allograft sourcing and traceability across European supply chains. Stakeholders must monitor evolving reimbursement coding for adjunctive surgical procedures as payors scrutinize evidence hierarchies separating maintenance from therapeutic intervention.
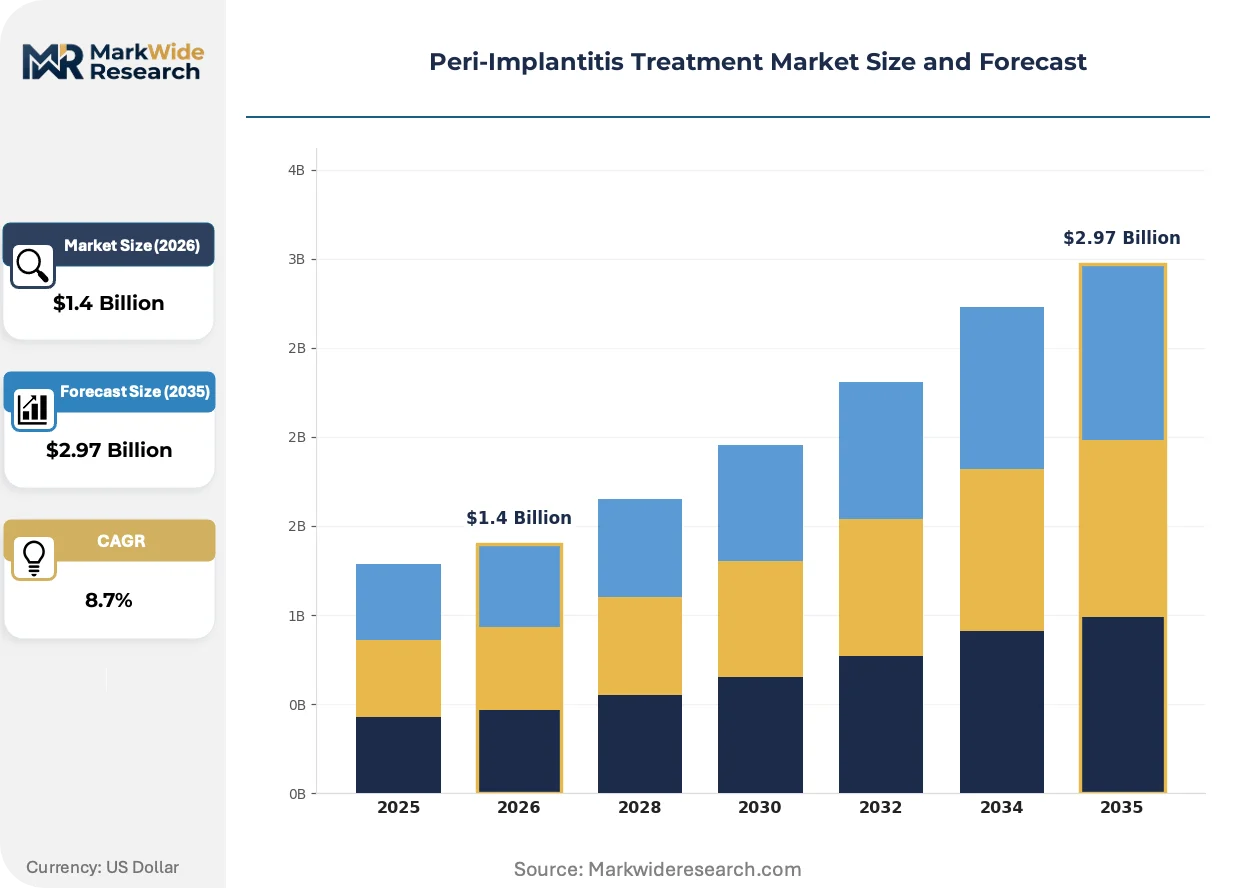
Market Dynamics
EU MDR annual surveillance audit compression is forcing bone graft manufacturers to restructure quality management systems, collapsing three-year certification cycles and diverting R&D capital toward compliance documentation rather than product pipeline expansion.
Growth Catalysts
- EU MDR Implementation:The Medical Device Regulation's tightened clinical evaluation requirements for implantable biomaterials is accelerating consolidation among substantiated suppliers, clearing shelf space for compliant portfolios.
- Laser Photodynamic Therapy:Chairside delivery at 810-980 nanometer wavelengths is eliminating specialist referral bottlenecks, expanding addressable procedure volume beyond periodontal specialist density constraints.
- German Dental Implantology Clinics:Regenerative protocol adoption in Baden-Württemberg and Bavaria clusters is establishing clinical reference sites that drive protocol diffusion across German-speaking Europe.
Market Restraints
- Xenogeneic Collagen Sourcing:EMA traceability requirements for bovine and porcine-derived matrices constrain Geistlich Pharma AG's supply base and extend batch release timelines.
- Allograft Procurement:Human tissue product sourcing faces EMA donor screening mandates that limit European supply chain flexibility and inflate cold chain logistics costs.
- Antimicrobial Resistance:Repetitive chlorhexidine application in maintenance protocols risks therapeutic efficacy erosion, pressuring formulary committees toward alternative decontamination chemistries.
Strategic Opportunities
- Swiss Manufacturing Premium:ISO 13485 certification from Swissmedic-accredited bodies commands pricing power in private-pay dental markets across the Gulf States and Southeast Asia.
- Digital Dentistry Integration:Intraoral scanning and CAD/CAM workflows are converging with regenerative planning software, creating bundled service revenue streams for integrated device-distribution platforms.
- Maintenance Protocol Expansion:Group purchasing organization formulary inclusion for topical antimicrobial kits opens recurring revenue models distinct from one-time surgical intervention economics.
Industry Challenges
- Periodontal Specialist Density:Geographic maldistribution of board-certified practitioners in the United States creates access bottlenecks that compress procedure throughput in rural and exurban markets.
- 510(k) Predicate Strategy:FDA structural similarity requirements for bone graft substitutes force developers toward incremental innovation pathways that limit mechanistic differentiation claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peri-Implantitis Treatment Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antimicrobial Agents, Bone Grafts, Soft Tissue Grafts, Laser Therapy Delivery Mode: Topical Application, Injectable Form, Systemic Administration, Surgical Intervention End User: Dentists, Oral Surgeons, Periodontists, Research Institutions Treatment Approach: Conservative Management, Surgical Management, Combination Therapy, Personalized Therapy |
| Companies Covered | Dentsply Sirona, Straumann Group, Zimmer Biomet, Geistlich Pharma AG, Nobel Biocare, Pfizer Inc., Henry Schein Inc., BioHorizons, Osstem Implant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peri-Implantitis Treatment Market Evolving Landscape
Photodynamic therapy hardware is migrating from specialist suites to general practice operatories, compressing the traditional referral hierarchy that has structured peri-implantitis care delivery for two decades.
Er:YAG and diode laser systems is bifurcating the decontamination market between high-capital specialist platforms and portable chairside units. General dentistry practices in Florida and Texas are adopting 980nm diode systems at triple the rate of periodontal specialty clinics. This hardware democratization is compressing specialist procedure premiums while expanding total addressable treatment episodes.
EMA's tightened post-market surveillance mandates for implantable periodontal biomaterials are extending clinical evaluation report revision cycles from biennial to annual frequencies. Swiss and German manufacturers are absorbing compliance personnel costs equivalent to 15-20% of quality assurance budgets. The xenogeneic collagen matrix segment faces the steepest documentation burden, accelerating supplier consolidation toward vertically integrated tissue processors.
After-sales service unbundling is disrupting traditional device-distribution relationships in the North American dental group practice segment. Procurement committees at Dental Service Organizations are separating hardware acquisition from maintenance protocol supply agreements, forcing antimicrobial and graft material suppliers toward direct contractual relationships. This pattern is most visible in the Southwestern United States, where multi-site practice consolidation has concentrated buying power among three major DSO platforms.
Peri-Implantitis Treatment Market Segmentation
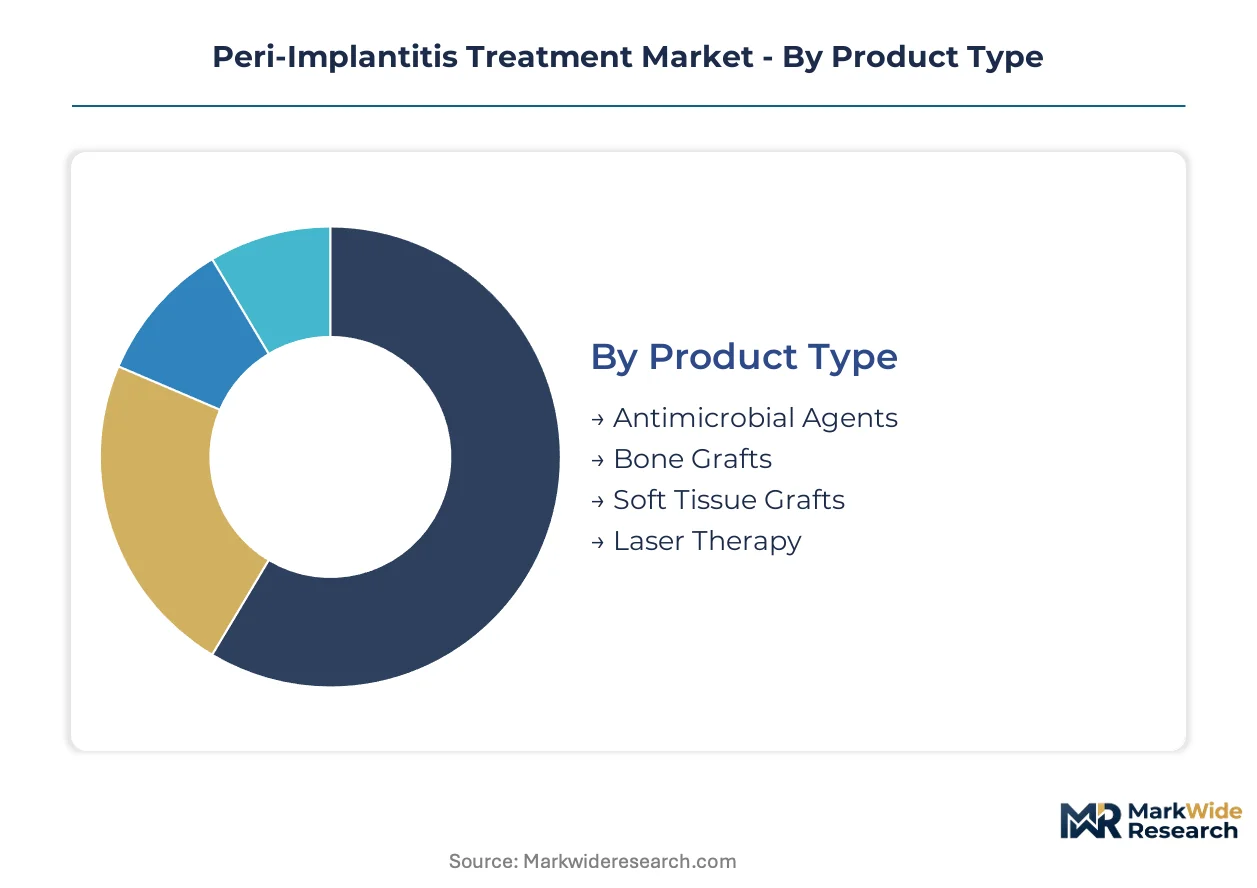
Treatment modality selection in peri-implantitis care hinges on disease staging, implant surface characteristics, and clinician specialty training. Channel economics diverge sharply between high-frequency maintenance consumables and capital-intensive surgical platforms. Understanding segment flow through dental group purchasing organizations versus direct specialist procurement shapes portfolio positioning.
Product Type:
Antimicrobial agents and bone grafts dominate dental supply house inventories, while laser systems and soft tissue matrices route through specialty distributors with clinical training attachments.
- Antimicrobial Agents:Chlorhexidine gluconate solutions and minocycline microspheres constitute repetitive purchase cycles embedded in maintenance protocols. Demand concentrates in United States dental service organizations seeking formulary standardization across multi-site practices, though chlorhexidine resistance patterns pressure chemistry diversification.
- Bone Grafts:Particulate mineralized allografts and xenogeneic collagen matrices command premium positioning through regenerative protocol adoption. German implantology clinics in Baden-Württemberg and Bavaria anchor European volume, with Swiss manufacturing certification sustaining pricing power in Gulf State private-pay markets.
- Soft Tissue Grafts:Autogenous connective tissue and acellular dermal matrices address peri-implant mucosal recession.
- Laser Therapy:Diode and Er:YAG systems at 810-980 nanometer wavelengths enable chairside decontamination without specialist referral.
By volume, Antimicrobial Agents leads. By growth pace, Laser Therapy is expanding most quickly.
Delivery Mode:
Cost tier stratification separates commodity topical kits from premium surgical bundles, with reimbursement coding determining channel viability across national health systems.
- Topical Application:Antiseptic rinses and localized drug delivery vehicles target early-stage peri-mucositis. United States group purchasing organizations drive centralized procurement, compressing margin structures toward high-volume, low-unit-economics models.
- Surgical Intervention:Open flap debridement with guided bone regeneration commands procedure-based reimbursement at specialist fee schedules. German statutory health insurance recognition of regenerative adjuncts sustains access, while Swiss private-pay markets absorb full cost recovery.
- Injectable Form:Antibiotic-loaded hydrogels and growth factor suspensions enable minimally invasive delivery.
- Systemic Administration:Adjunctive antibiotics address aggressive peri-implantitis phenotypes with microbial consortium involvement.
Topical Application captures the highest procedure count. Surgical Intervention generates the steepest revenue per episode.
End User:
Customer type fragmentation maps to credentialing requirements, with board certification status determining access to surgical reimbursement codes and advanced biomaterial portfolios.
- Periodontists:Board-certified specialists perform complex regenerative procedures with bone graft adjuncts. United States geographic maldistribution creates access bottlenecks in rural markets, concentrating volume in urban academic medical centers and metropolitan group practices.
- Dentists:General practitioners adopt chairside laser systems for decontamination and maintenance protocols. Florida and Texas lead hardware adoption rates, with triple the penetration of periodontal specialty clinics.
- Oral Surgeons:Implant placement originators handle late-stage failures requiring explantation and site redevelopment.
- Research Institutions:Academic centers generate protocol evidence and training curricula for diffusion across clinical practice.
Periodontists anchor surgical graft consumption. Dentists drive laser system volume expansion.
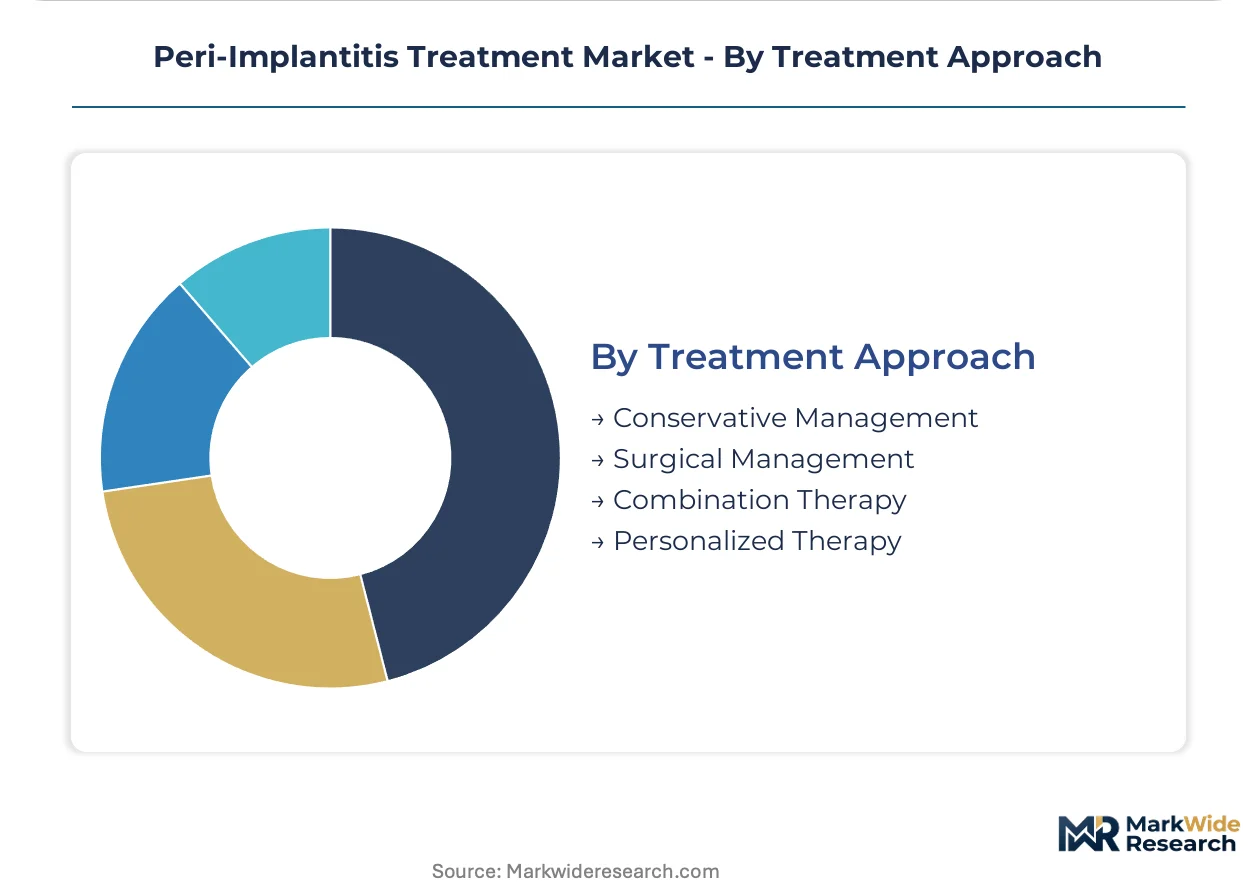
Treatment Approach:
Maturity gradients separate established conservative protocols from emerging personalized strategies, with evidence hierarchies determining payer coverage decisions.
- Conservative Management:Mechanical debridement and antimicrobial protocols arrest early disease without surgical morbidity. Maintenance program enrollment in United States dental service organizations sustains recurring revenue streams distinct from one-time intervention economics.
- Combination Therapy:Sequential antimicrobial and regenerative protocols address moderate disease with mixed hard and soft tissue deficits. German reference clinics establish protocol templates that diffuse through German-speaking Europe via continuing education channels.
- Surgical Management:Resective or regenerative surgery targets advanced peri-implantitis with implant mobility risk.
- Personalized Therapy:Microbial profiling and biomarker-guided intervention selection remains investigational.
Conservative Management retains the largest patient volume. Combination Therapy is gaining share fastest through protocol standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dental service organizations in the United States concentrate procurement volume for antimicrobial maintenance protocols, while Swiss and German implantology clinics anchor European regenerative procedure adoption.
United States
Periodontal specialist density in metropolitan corridors drives surgical intervention volume, with Florida and Texas leading laser system adoption among general dentists. FDA 510(k) clearance pathways for bone graft substitutes structure predicate-based innovation timelines. The Southwestern United States hosts concentrated dental service organization buying power that unbundles hardware from consumable procurement.
Germany
Baden-Württemberg and Bavaria implantology clusters establish regenerative protocol templates that diffuse through German-speaking Europe. EU MDR annual surveillance audit compression forces quality management system restructuring among domestic manufacturers. Statutory health insurance recognition of regenerative adjuncts sustains procedure access beyond private-pay markets.
Switzerland
Swissmedic-accredited ISO 13485 certification commands pricing power in Gulf State and Southeast Asian private-pay dental markets. Straumann Group leverages domestic manufacturing for premium positioning across implant maintenance portfolios. Basel and Zurich anchor xenogeneic collagen matrix production facing EMA traceability documentation burdens.
China
Domestic implant placement volume expansion creates downstream peri-implantitis treatment demand in tier-one hospital stomatology departments. NMPA Class III device registration requirements for bone graft substitutes extend commercialization timelines versus predicate-reliant pathways. Shanghai and Beijing academic medical centers generate clinical training curricula for regional protocol diffusion.
United Arab Emirates
Private-pay dental tourism in Dubai and Abu Dhabi absorbs premium-priced Swiss-manufactured regenerative portfolios. MOHAP medical device registration mandates substantiation documentation for imported implantable biomaterials. Gulf State procurement committees prioritize Swiss certification pedigree in specialist clinic equipment tenders.
Peri-Implantitis Treatment Market Competitive Landscape
Player mix skews toward diversified dental device conglomerates with integrated distribution platforms, creating tiered competition between premium Swiss-manufactured portfolios and scale-driven North American supply networks. Swiss and German specialists in xenogeneic biomaterials occupy differentiated positions against diversified implant manufacturers. Competitive moves concentrate on digital dentistry workflow integration and direct contractual relationships with dental service organizations.
Within the premium Swiss-manufactured tier, Straumann Group and Geistlich Pharma AG exemplify certification-dependent positioning that commands Gulf State and Southeast Asian private-pay pricing power. Dentsply Sirona anchors North American scale advantages through integrated digital dentistry workflows and dental service organization procurement penetration. These three entities represent distinct archetypes: Swiss biomaterial specialization, diversified device-platform integration, and North American distribution consolidation.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Straumann Group |
| Zimmer Biomet |
| Geistlich Pharma AG |
| Nobel Biocare |
| Pfizer Inc. |
| Henry Schein Inc. |
| BioHorizons |
| Osstem Implant |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation agreements between German implantology clinics and Swiss collagen matrix manufacturers lock in supply access while stabilizing unit economics across EMA-mandated batch release cycles. These contractual structures insulate premium regenerative portfolios from spot-market volatility while compressing margin flexibility for non-contracted buyers.
Pricing Analysis
Cost-plus contracts with Swissmedic certification indexation anchor premium tier positioning for xenogeneic matrices in Gulf State private-pay markets. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified Swiss manufacturing from CE-marked European production and non-certified alternatives. Pricing pressure stems from dental service organization formulary standardization in the United States, which compresses antimicrobial kit margins toward high-volume, low-unit-economics models. General dentistry practices exhibit highest price sensitivity due to capital constraints on laser hardware acquisition, while academic medical centers absorb premium surgical bundle pricing.
Supply Chain Analysis
Strategic stockpiling of bovine-derived collagen precursors dominates Swiss and German manufacturer inventory strategy, buffering EMA traceability documentation delays. Supply concentrates in Switzerland, Germany, and the United States for xenogeneic matrices, allograft processing, and antimicrobial formulation respectively. Raw material dependencies span bovine pericardium sourcing, human tissue donor networks, and chlorhexidine active pharmaceutical ingredients. Single-source vulnerability runs through Swissmedic-accredited certification bodies for premium market access. Distribution runs through specialty dental distributors with clinical training attachments for laser systems, while commodity antimicrobials flow via group purchasing organization centralized procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peri-implantitis treatment demand follows implant placement cycles with a seven-to-ten-year lag, positioning the market for procedural volume recovery as prior-year implant volumes mature into maintenance and intervention episodes.
For Market Incumbents: Fortify quality management system capacity to absorb EU MDR annual surveillance audit compression without diverting R&D capital toward compliance documentation. Deepen backward integration into xenogeneic tissue processing to secure supply base against EMA traceability mandate bottlenecks. Prioritize direct contractual relationships with dental service organizations to defend antimicrobial kit formulary positioning against unbundling trends. For New Entrants and Emerging Players: FDA 510(k) predicate pathway fast-track via structural similarity claims offers lowest regulatory barrier for bone graft substitute market entry. Target general dentistry laser system adoption in Florida and Texas, where chairside decontamination hardware penetration triples specialist clinic rates. Pursue software companion development for intraoral scanning integration as differentiated go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated tissue processors with captive xenogeneic collagen supply and Swissmedic certification pedigree. Long-term viability hinges on consolidation of fragmented antimicrobial formulation capacity under platforms with dental service organization procurement penetration. Watch laser system adoption rates among general dentists as inflection indicator for addressable market expansion beyond periodontal specialist density constraints.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evaluation report preparation secures implantable biomaterial market access across German-speaking Europe. |
| Hospital System Partnership | Academic medical center alliances in Baden-Württemberg establish protocol templates for regenerative procedure diffusion. |
| Software Companion Development | CAD/CAM workflow integration creates bundled service revenue streams for digital dentistry platforms. |
| Reimbursement Strategy | Statutory health insurance recognition of regenerative adjuncts sustains procedure access in German markets. |
| Backward Integration | In-house production of xenogeneic collagen matrices buffers EMA traceability documentation timeline volatility. |
Research Methodology
Cross-validation between primary interviews with periodontal specialists, dental service organization procurement directors, and biomedical engineers anchors the qualitative findings against secondary validation from FDA 510(k) filings, EU MDR clinical evaluation reports, and hospital procurement databases. Bottom-up procedure volume estimates triangulate with top-down market sizing from dental supply house inventory flows and group purchasing organization contract disclosures.
Sensitivity analysis around periodontal specialist density assumptions, laser system adoption curves, and EU MDR compliance cost absorption informs projection robustness across the modeling period. Segmentation dimensions span treatment modality, delivery mode, clinician specialty, and disease staging severity. CAGR derivation incorporates implant placement vintage analysis, maintenance protocol adherence rates, and regenerative procedure conversion ratios.
Decision-makers should treat outputs as directional under stable EU MDR enforcement intensity and continued dental service organization consolidation; material deviation would warrant model refresh. Revision becomes warranted when laser system penetration among general dentists crosses thresholds that structurally alter referral hierarchy economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Dengue Fever Treatment Market
Medical Treatment
Corneal Transplant Market
Medical Treatment
Postoperative Nausea and Vomiting (PONV) Management Market
Medical Treatment
Persistent Epithelial Defect Management Market
Medical Treatment
Prion Disease Treatment Market
Medical Treatment
Giardiasis Treatment Market
Medical Treatment
Beta Thalassemia Treatment Market
Medical Treatment
Factor XIII Deficiency Treatment Market
Medical Treatment
Lysosomal Disease Treatment Market
Medical Treatment
Anaphylaxis Treatment Market
Medical Treatment
Ventral Hernia Treatment Market
Medical Treatment
Vulvovaginal Candidiasis Treatment Market
Medical Treatment
Global Leishmaniasis Treatment Market
Medical Treatment
Trauma and Extremities Market
Medical Treatment
Transarterial Chemoembolization (TACE) Market
Medical Treatment
Non-Invasive Surgery Market