
 China Whey Protein Market | 2026-2036
China Whey Protein Market Size, Share, and Industry Trends Forecast 2026-2036
China Whey Protein Market Outlook
Inner Mongolia's dairy processing corridor is reconfiguring China's whey protein supply landscape through expanded fractionation capacity and cold-chain integration. Mengniu Dairy leverages its regional milk collection network to secure fresh whey streams for captive protein extraction. Glanbia plc anchors its China position through specialized sports nutrition ingredient supply to domestic brand manufacturers. Fonterra Co-operative Group Limited competes via direct farm partnerships that guarantee traceable whey concentrate volumes for the food and beverage sector.
Whey protein comprises a heterogeneous mixture of beta-lactoglobulin, alpha-lactactalbumin, bovine serum albumin, and immunoglobulins recovered during cheese or casein manufacture, typically yielding protein concentrations from 34% to 90% depending on filtration intensity and ion exchange processing. Its primary commercial purpose centers on delivering high biological value amino acid profiles for muscle protein synthesis, clinical recovery protocols, and functional food fortification. Concentrate grades still occupy the largest volume share due to cost-sensitive food and beverage applications, while isolate and hydrolysate segments command premium positioning among fitness enthusiasts and healthcare professionals seeking rapid absorption and reduced lactose content. Sports nutrition applications lead absolute demand expansion as gym penetration deepens in Chinese urban centers.
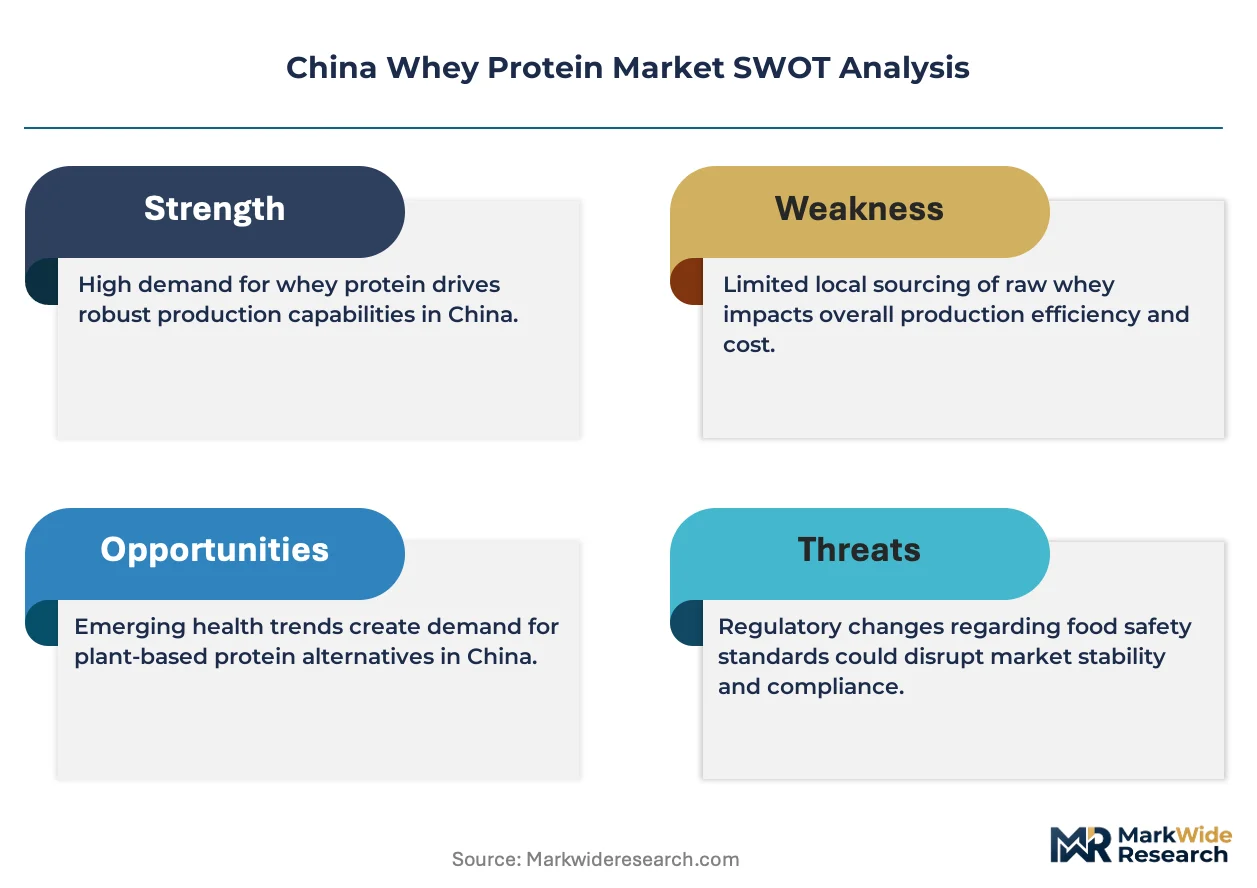
SAMR's national food safety registration requirements and GB standards for dairy-derived protein products shape import clearance timelines and domestic manufacturing compliance costs for whey processors. The National Health Commission's evolving nutrition labeling rules and protein content verification protocols are forcing reformulation investments across supplement and clinical nutrition portfolios. Stakeholders must monitor how China's dual carbon goals and provincial energy intensity targets reshape whey fractionation facility siting decisions and operational cost structures in the northern dairy belt.
Market Dynamics
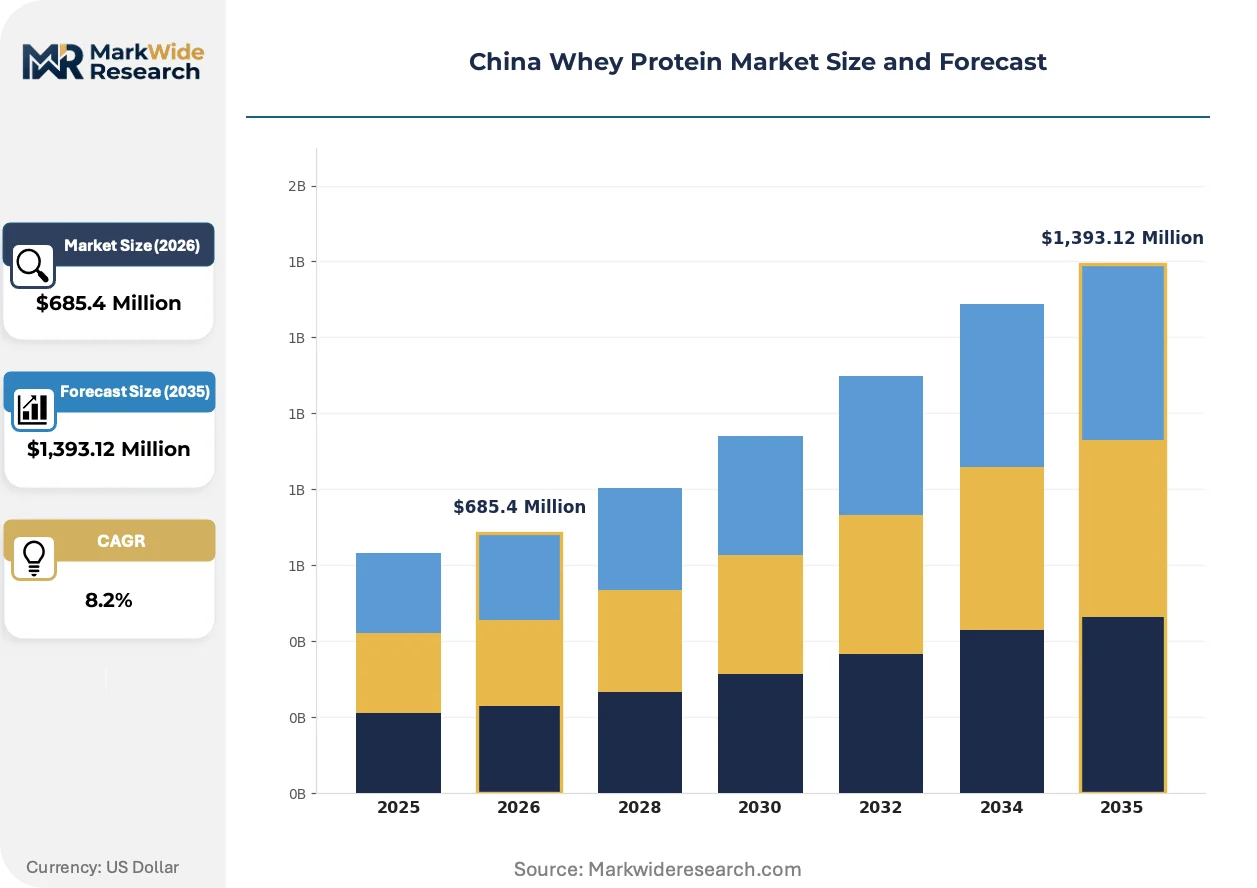
China's whey protein market is being fundamentally restructured by SAMR's tightened GB standards for dairy-derived protein products, which are forcing domestic and imported processors to upgrade fractionation infrastructure and reformulate portfolios to meet stricter purity and labeling verification protocols.
Growth Catalysts
- Fitness culture maturation:Gym penetration in Shanghai and Beijing has created a concentrated base of affluent consumers demanding isolate and hydrolysate formats for rapid recovery protocols. Sports nutrition brands are expanding SKU counts to capture this segment.
- Clinical nutrition protocols:Hospital systems in tier-one cities are integrating whey protein into post-surgical recovery and geriatric care regimens, driving institutional procurement of medical-grade concentrates.
- Inner Mongolia dairy corridor expansion:Cold-chain integration and expanded fractionation capacity in the northern dairy belt are reducing lead times for fresh whey streams and improving domestic supply security.
Market Restraints
- Import dependency for premium grades:China lacks sufficient ion exchange and microfiltration capacity to produce pharmaceutical-grade isolates domestically, creating exposure to international supply disruptions.
- Lactose intolerance prevalence:Approximately 85% of Han Chinese adults exhibit lactose malabsorption, limiting concentrate adoption and forcing costly reformulation toward hydrolysate and isolate grades.
- GB standard compliance costs:SAMR's protein content verification protocols and National Health Commission labeling rules require capital-intensive laboratory infrastructure that squeezes mid-tier domestic processors.
Strategic Opportunities
- Plant-whey hybrid formulations:Convergence of pea protein extraction technology with whey fractionation is enabling reduced-lactose blended products targeting China's lactose-sensitive majority.
- Tier-two city penetration:Chengdu, Hangzhou, and Wuhan exhibit rising gym membership rates but underdeveloped premium protein distribution, creating first-mover whitespace for isolate formats.
- Dual carbon policy alignment:Provincial energy intensity targets in Inner Mongolia favor processors investing in renewable-powered fractionation facilities, unlocking preferential grid access and carbon credit monetization.
Industry Challenges
- Skilled technician scarcity:Cross-flow membrane operation and chromatographic separation require specialized dairy engineering expertise that remains concentrated in multinational technical centers.
- Cold-chain integrity gaps:Temperature excursions during whey liquid transport from cheese manufacturing sites to fractionation plants degrade protein quality and create batch rejection risk.
- Dual-labeling complexity:Products targeting both sports nutrition and clinical nutrition segments must navigate divergent SAMR registration pathways, extending time-to-market by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Whey Protein Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,393.12 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Isolate, Hydrolysate, Blends Customer Type: Retail Consumers, Fitness Enthusiasts, Athletes, Healthcare Professionals Application: Nutritional Supplements, Food and Beverage, Sports Nutrition, Clinical Nutrition Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Stores |
| Companies Covered | Royal FrieslandCampina N.V., Mengniu Dairy, Glanbia plc, Shenzhen Lifeworth Biotechnology, Hilmar Cheese Company, Inc., Fonterra Co-operative Group Limited, Lactalis Group, Shaanxi Hongda Phytochemistry, Arla Foods Ingredients Group P/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Whey Protein Market Strategic Shifts
Digital traceability systems and precision fermentation are converging with evolving Chinese regulatory frameworks to reshape how whey protein is sourced, processed, and certified for domestic consumption.
Membrane filtration technology is digitizing quality control workflows across China's whey fractionation plants. Advanced sensor arrays and machine learning algorithms now monitor protein concentration and lactose removal in real-time. Domestic processors in Inner Mongolia are adopting these systems to reduce batch-to-batch variation. This digitizing of process control is compressing the quality gap between Chinese and imported isolate grades.
China's National Health Commission has issued updated protein powder GB standards that mandate stricter heavy metal limits and amino acid profile disclosure. Domestic manufacturers must now submit third-party verification for every production lot. Imported brands face extended customs clearance timelines as SAMR implements enhanced laboratory testing. Sports nutrition SKUs with complex flavor systems are experiencing the longest reformulation delays.
Direct-to-consumer subscription models are displacing traditional gym-based retail for premium whey products. Young professionals in Beijing and Shenzhen prefer mobile-app ordering with personalized dosing recommendations over physical store purchases. E-commerce platforms are responding with cold-chain last-mile delivery partnerships. This channel shift is most pronounced among 25-35 year old consumers purchasing hydrolysate formats for post-workout recovery.
China Whey Protein Market Segmentation
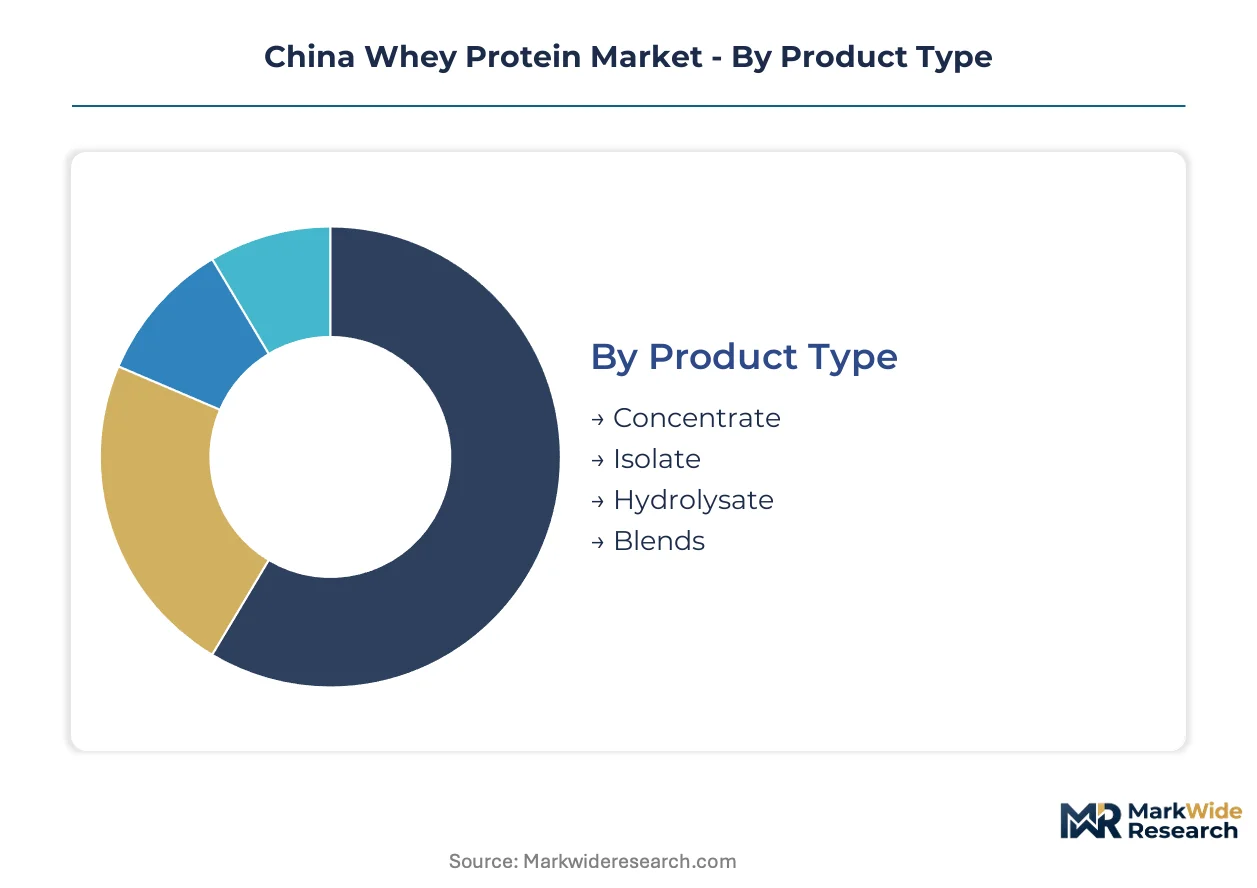
Whey protein segmentation in China reflects divergent technical specifications, regulatory pathways, and consumption occasions across product grades and buyer profiles. Understanding these divides reveals where margin concentrates versus where volume scales.
Product Type:
Inventory velocity varies sharply across filtration grades, with hydrolysate turning fastest in Shanghai gym channels while concentrate moves steadily through food manufacturing procurement.
- Concentrate:Protein content ranges from 34% to 80% depending on ultrafiltration intensity, retaining higher lactose and lipid fractions. Food and beverage manufacturers in Guangdong and Shandong source this grade for baked goods and dairy beverages where cost efficiency outweighs purity requirements.
- Isolate:Cross-flow microfiltration and ion exchange processing push protein concentration above 90% with minimal lactose. Beijing and Shenzhen fitness enthusiasts drive demand for this grade in post-workout applications where rapid absorption commands premium positioning.
- Hydrolysate:Enzymatic pre-digestion creates peptide fractions for accelerated gastric emptying.
- Blends:Combinations of concentrate, isolate, and casein target sustained-release protocols in clinical nutrition.
Concentrate anchors the volume base while hydrolysate gains share at the steepest rate.
Customer Type:
Procurement authority and price sensitivity split sharply between self-directed retail buyers and institutionally constrained healthcare professionals.
- Retail Consumers:Mass-market purchasers responding to e-commerce promotions and influencer recommendations. This segment exhibits high brand switching and seasonal purchasing spikes around fitness resolutions.
- Fitness Enthusiasts:Gym members with structured supplementation protocols and format preferences for isolate and hydrolysate. Tier-one city consumers in this cohort show strongest loyalty to traceable domestic sourcing.
- Athletes:Competitive and professional performers requiring batch-tested products with anti-doping certification.
- Healthcare Professionals:Hospital nutritionists and clinical dietitians prescribing medical-grade concentrates for sarcopenia and post-surgical recovery.
Healthcare professionals anchor procurement value while fitness enthusiasts expand most quickly.
Application:
Regulatory registration requirements create divergent time-to-market economics across end-use categories.
- Nutritional Supplements:SAMR's blue-hat registration pathway demands 12-18 month approval timelines for health claims. Domestic brands reformulate constantly to meet evolving GB standards for heavy metal limits and amino acid disclosure.
- Sports Nutrition:Gym-centric consumption concentrates in tier-one cities with highest per-capita protein spending. This application leads SKU innovation for flavor systems and single-serve portability.
- Food and Beverage:Bakery and dairy processors incorporate whey for emulsification and protein fortification.
- Clinical Nutrition:Hospital system procurement follows strict tender protocols for enteral feeding and recovery formulations.
Food and beverage anchors volume throughput while sports nutrition climbs the fastest.
Distribution Channel:
Cold-chain capabilities and customer acquisition costs determine channel profitability across urban tiers.
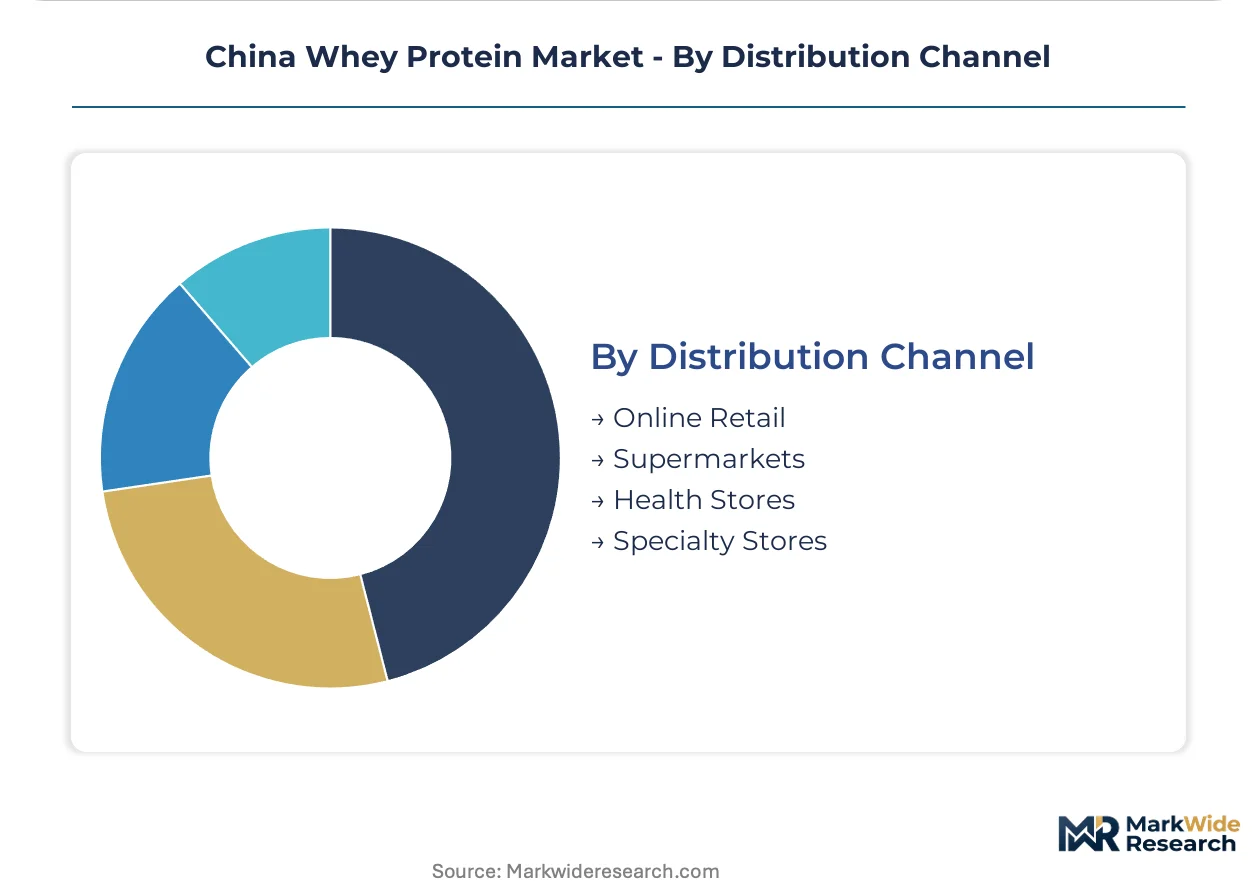
- Online Retail:Tmall and JD.com dominate premium isolate sales with subscription models and same-day delivery in Beijing, Shanghai, and Shenzhen. Direct-to-consumer brands bypass traditional margin stacking through livestream commerce.
- Supermarkets:Concentrate and blended formats reach mass-market buyers through Walmart and domestic chains like Yonghui. Shelf placement competition intensifies as sports nutrition brands expand into mainstream retail.
- Health Stores:Pharmacy-adjacent outlets serve older consumers seeking clinical-grade products with pharmacist consultation.
- Specialty Stores:Gym-proximate retail and bodybuilding-focused outlets provide format education and sampling.
Supermarkets anchor physical volume while online retail expands most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GB standards issued by SAMR anchor regulatory compliance across China's whey protein value chain, with provincial implementation varying by regional dairy infrastructure and urban consumption density.
Beijing-Tianjin-Hebei
Hospital procurement networks and sports nutrition retail concentrate demand for isolate and hydrolysate formats. The National Health Commission's clinical nutrition protocols drive institutional purchasing from medical-grade concentrate suppliers. Beijing's cold-chain logistics hubs enable rapid distribution of temperature-sensitive whey fractions to northern tier-one cities.
Yangtze River Delta
Shanghai's gym penetration and affluent fitness culture generate premium pricing for traceable isolate products. SAMR's import clearance requirements extend timelines for European and Oceanian whey shipments through Yangshan Port. Suzhou and Hangzhou host expanding fractionation facilities serving regional sports nutrition manufacturers.
Pearl River Delta
Shenzhen's direct-to-consumer subscription models and livestream commerce channels displace traditional retail for hydrolysate products. The province's dual carbon implementation rules favor renewable-powered dairy processing investments. Guangzhou's food and beverage manufacturers absorb concentrate volumes for baked goods and dairy beverage fortification.
Inner Mongolia
Mengniu Dairy's captive whey streams and expanded fractionation capacity reduce import dependency for concentrate grades. Provincial energy intensity targets under China's dual carbon policy reshape facility siting decisions for membrane filtration plants. Hohhot's dairy processing corridor integrates cold-chain infrastructure linking cheese manufacturing to protein extraction.
Sichuan-Chongqing
Chengdu's rising gym membership rates create whitespace for premium isolate distribution in an underdeveloped sports nutrition market. The western region's lactose intolerance prevalence exceeds national averages, favoring hydrolysate adoption. Chongqing's food manufacturing base sources concentrate for processed dairy and bakery applications.
China Whey Protein Market Competitive Environment
Multinational ingredient suppliers and domestic dairy processors split the market along filtration-grade specialization and captive supply control. Concentrate volumes flow through cost-optimized domestic channels while isolate and hydrolysate grades remain import-dependent. Three archetypes dominate: integrated dairy conglomerates with captive whey streams, specialized sports nutrition ingredient suppliers, and regional fractionation specialists serving food manufacturing. Competitive positioning hardens through backward integration into cheese manufacturing and forward partnerships with e-commerce distribution platforms.
Among integrated dairy conglomerates, Mengniu Dairy exemplifies captive supply control through regional milk collection networks. Glanbia plc occupies a position as a specialized sports nutrition ingredient supplier to domestic brand manufacturers. Fonterra Co-operative Group Limited anchors the import-dependent tier through direct farm partnerships guaranteeing traceable whey concentrate volumes.
| Leading Market Players |
|---|
| Royal FrieslandCampina N.V. |
| Mengniu Dairy |
| Glanbia plc |
| Shenzhen Lifeworth Biotechnology |
| Hilmar Cheese Company, Inc. |
| Fonterra Co-operative Group Limited |
| Lactalis Group |
| Shaanxi Hongda Phytochemistry |
| Arla Foods Ingredients Group P/S |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in ion exchange and microfiltration infrastructure across Inner Mongolia and Hebei provinces drives divergent supplier behavior between domestic concentrate producers and import-dependent isolate processors, compressing margins for mid-tier domestic players while insulating premium-grade importers from price competition.
Pricing Analysis
Shanghai-to-Hohhot price spreads for pharmaceutical-grade isolates exceed those for standard concentrates by multiples reflecting freight costs and cold-chain integrity premiums. Three-tier pricing structure across premium hydrolysate, standard isolate, and economy concentrate levels stratifies by lactose content and filtration intensity. Pricing pressure stems from SAMR's batch-testing requirements extending customs clearance timelines and elevating working capital costs for imported brands. Mass-market retail consumers exhibit highest price sensitivity, while clinical nutrition procurement officers prioritize traceability over unit cost.
Supply Chain Analysis
Fresh whey liquid feedstock draws from cheese manufacturing clusters in Inner Mongolia, New Zealand, and the European Union, with geographic concentration creating divergent freshness profiles and protein yield variations. Raw material dependencies center on rennet and acid casein production volumes, membrane filtration equipment, and enzymatic hydrolysis catalysts. Single-source vulnerability pervades the premium isolate tier where Chinese domestic ion exchange capacity remains insufficient for pharmaceutical-grade output. Distribution runs through cold-chain logistics partnerships linking northern dairy processing corridors to tier-one city e-commerce fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's whey protein market is approaching a platform-economics inflection where direct-to-consumer subscription interfaces and precision dosing algorithms are displacing traditional gym-retail relationships, with interoperability between fitness-tracking apps and personalized nutrition platforms redefining customer acquisition economics.
For Market Incumbents: Entrench position through backward integration into captive cheese manufacturing in Inner Mongolia, securing fresh whey streams that reduce feedstock cost volatility. Invest in SAMR pre-registration laboratory infrastructure to compress batch-testing timelines and defend against emerging domestic fractionation specialists. Channel control through exclusive e-commerce platform partnerships offers defensive moat against subscription-native entrants.
For New Entrants and Emerging Players: Pursue whitespace in Chengdu and Wuhan gym channels where premium isolate distribution remains underdeveloped relative to membership growth rates. Target plant-whey hybrid formulations addressing lactose intolerance prevalence exceeding national averages in western provinces. Livestream commerce integration with fitness influencer networks offers lowest customer acquisition cost entry vector.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription brands with cold-chain last-mile capabilities, suggesting long-term viability favors asset-light platform operators over capital-intensive fractionation facilities. Acquisition target archetype: regional fractionation specialists with SAMR laboratory certification and unexploited e-commerce channel relationships. Monitor dual carbon policy implementation velocity in Inner Mongolia as inflection signal for domestic production cost competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cheese Manufacturing | Mengniu Dairy's captive whey streams demonstrate feedstock security against import price volatility. |
| SAMR Pre-Registration Laboratory Investment | Domestic processors with in-house batch-testing capability compress clearance timelines versus import-dependent competitors. |
| Direct-to-Consumer Subscription Launch | Beijing and Shenzhen fitness apps with personalized dosing algorithms displace traditional gym-retail margin stacking. |
| Plant-Whey Hybrid Formulation Development | Pea protein convergence with whey fractionation targets lactose-sensitive Han Chinese majority. |
| Renewable-Powered Fractionation Facility Siting | Inner Mongolia dual carbon policy alignment unlocks preferential grid access and carbon credit monetization. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across China's whey protein value chain, including sports nutrition brand managers, clinical dietitians at tier-one hospital systems, membrane filtration plant engineers in Inner Mongolia, and e-commerce category buyers at Tmall and JD.com. Secondary validation drew from SAMR regulatory filings, National Health Commission GB standard updates, customs import data, and dairy industry association production statistics. Bottom-up SKU-level demand modeling triangulated against top-down macro consumption projections.
Calibration against historical volume trajectories and elasticity assumptions shaped the analytical framework across the analysis window. Segmentation dimensions modeled include filtration grade, customer archetype, application category, and distribution channel, with provincial urban tier penetration rates as an additional industry-specific dimension. CAGRs were derived from slope-consistent growth rate applications across the projection horizon, incorporating gym membership expansion curves and clinical nutrition protocol adoption rates as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending indices or dairy raw material pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation timelines and cold-chain infrastructure buildout rates. Cross-checking against National Bureau of Statistics urban household consumption surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Fish Protein Isolate Market
Nutritional Supplements
Vitamins Gummies Market
Nutritional Supplements
Chia-Based Protein Market
Nutritional Supplements
Phytoestrogen Supplements Market
Nutritional Supplements
Omega-3 Fatty Acids Market
Nutritional Supplements
Omega 3 Market
Nutritional Supplements
Asia-Pacific Collagen Peptide Products Market
Nutritional Supplements
North America Dietary Supplements Market
Nutritional Supplements
South America Whey Protein Market
Nutritional Supplements
Gummy Vitamins Market
Nutritional Supplements
Coq10 Gummies Market
Nutritional Supplements
Vegan Protein Powder Market
Nutritional Supplements
Asia-Pacific Omega-3 Products Market
Nutritional Supplements
Concentrate Protein Market
Nutritional Supplements
Global Elderly Nutrition Market
Nutritional Supplements
Green Tea Supplements Market