
 Dry Whole Milk Powder Market | 2026-2036
Dry Whole Milk Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Whole Milk Powder Market Analysis
Multi-layer pouch packaging is repositioning buyer choice away from traditional tins in emerging-market retail channels. Fonterra Co-operative Group Limited leverages its New Zealand sourcing base to dominate bulk ingredient supply to Asian dairy manufacturers. Nestlé S.A. differentiates through fortified powder formulations aimed at nutritional supplement segments. Lactalis Group sustains competitive pressure with integrated dairy processing across European and North American facilities.
Dry whole milk powder is dehydrated milk produced by spray-drying or roller-drying liquid whole milk to approximately 95% solids, retaining milk fat at 26-28% by weight for reconstitution into fluid milk or industrial dairy applications. Its primary commercial purpose is to provide shelf-stable, transport-efficient dairy solids for food manufacturing and consumer markets where cold-chain infrastructure remains limited. Instant milk powder commands the largest volume share due to superior solubility in reconstitution applications, while fortified milk powder captures expanding margin pools from health-positioned nutritional products. Organic milk powder occupies a premium niche with constrained supply, as dairy manufacturers and nutritional supplements end users drive specification divergence across procurement contracts.
FDA standards for dairy product identity and labeling shape US market access requirements, while EFSA nutrition and health claims regulation influences fortified powder positioning in European markets. Codex Alimentarius standards coordinate international trade parameters for moisture content and microbiological limits, reducing bilateral friction for exporters like Fonterra and FrieslandCampina. China's SAMR dairy registration rules impose additional compliance layers for foreign suppliers seeking infant formula ingredient status. Stakeholders must monitor how diverging national fortification mandates reshape product portfolio priorities and regional manufacturing footprints.
Market Dynamics
The EU Green Deal is compressing margins across European spray-drying operations while Southeast Asian infant formula manufacturers accelerate procurement of fortified milk powder as a base ingredient, creating divergent cost pressures across regional supply chains.
Growth Catalysts
- Fortification Mandates:National nutrition programs in Vietnam and Indonesia are requiring vitamin-enriched dairy inputs for school feeding schemes, expanding specification demand for fortified milk powder.
- Energy Transition Incentives:The EU Green Deal's carbon border adjustments are accelerating capital deployment into heat-recovery spray-drying systems among Dutch and German processors.
- Cold-Chain Gaps:Reconstitution capacity investments by Indonesian dairy brands are displacing fluid milk imports in favor of shelf-stable powder with 18-month stability windows.
Market Restraints
- Feed Cost Volatility:New Zealand and Australian dairy farmers face pasture-dependent production swings that transmit directly into milk solids pricing volatility for powder manufacturers.
- Supplier Concentration:Bulk ingredient procurement for Asian dairy processors concentrates among Oceania-based cooperatives, creating single-source vulnerability during El Niño drought cycles.
- Substitution Pressure:Plant-based fat-protein blends from oat and coconut sources are capturing niche positioning in nutritional supplement formulations targeting lactose-intolerant demographics.
Strategic Opportunities
- Domestic Reconstitution:Vietnamese dairy brands are building in-house blending facilities to reduce dependency on pre-mixed imported formulations, opening equipment and technical service contracts.
- Organic Certification:EU organic dairy regulations are creating premium tier separation for pasture-certified milk powder with traceable supply chains and restricted antibiotic use.
- E-commerce Direct:Instant milk powder SKUs are migrating from traditional wholesale channels into platform-direct consumer fulfillment, bypassing import distributor markups in tier-two Chinese cities.
Industry Challenges
- Spray-Drying Engineering Talent:Southeast Asian dairy processors face acute shortages of process engineers capable of optimizing heat-transfer efficiency in multi-stage drying towers.
- SAMR Registration Timelines:China's infant formula ingredient approval process extends 18-24 months for foreign suppliers, freezing market entry investments during regulatory review.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Whole Milk Powder Market |
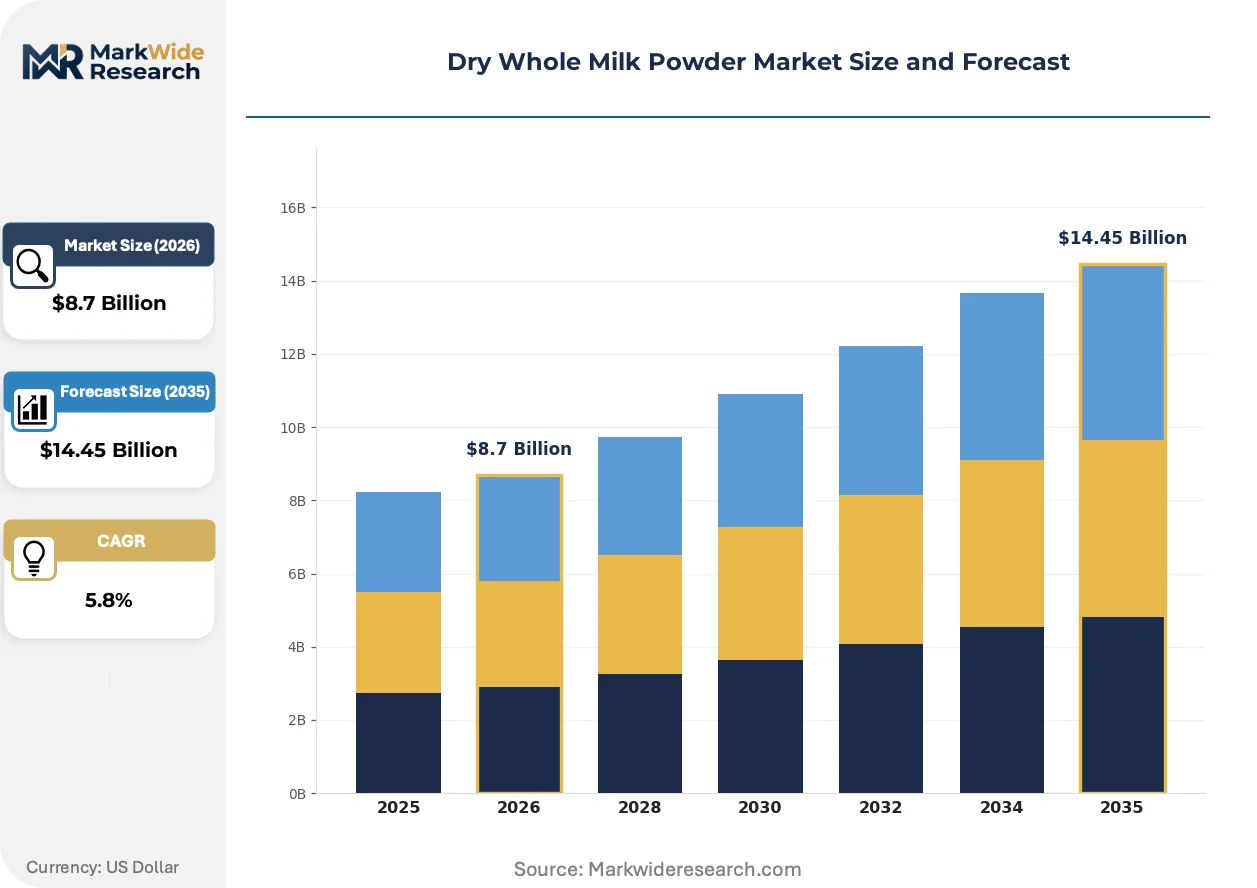
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Milk Powder, Non-Instant Milk Powder, Fortified Milk Powder, Organic Milk Powder End User: Dairy Manufacturers, Food & Beverage Industry, Bakery Products, Nutritional Supplements Distribution Channel: Retail Stores, Online Stores, Wholesalers, Direct Sales Packaging Type: Bags, Cartons, Tins, Pouches |
| Companies Covered | Fonterra Co-operative Group Limited, Nestlé S.A., Lactalis Group, Arla Foods amba, Royal FrieslandCampina N.V., Saputo Inc., Danone S.A., Dairy Farmers of America, Inc., Amul, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Whole Milk Powder Market Emerging Trajectories
Processing efficiency mandates and packaging format evolution are compressing traditional supply chain configurations while opening new specification tiers for differentiated powder products.
Membrane filtration pre-concentration is electrifying energy intensity profiles in spray-drying operations by reducing water removal requirements before thermal processing. European dairy cooperatives are retrofitting existing plants with reverse osmosis and nanofiltration stages, cutting natural gas consumption per ton of powder produced. This technology convergence is enabling smaller-batch production runs that respond faster to fortification specification changes.
EFSA nutrition and health claims regulation is tightening evidentiary requirements for immune-support and cognitive-development positioning on fortified milk powder packaging. Reformulation investments are concentrating on probiotic and HMO additive combinations with published clinical trial backing. Infant formula ingredient suppliers targeting European markets are restructuring regulatory affairs teams to manage parallel dossier submissions across member state competent authorities.
Multi-layer pouch formats are displacing metal tins in emerging-market retail channels, cutting unit shipping weight and enabling shelf-ready display without secondary cardboard. Indonesian and Vietnamese supermarket chains are specifying high-barrier laminate structures with resealable zippers for their private-label instant milk powder lines. This packaging pivot is compressing traditional canning equipment utilization rates while expanding flexible film converter order books.
Dry Whole Milk Powder Market Segmentation
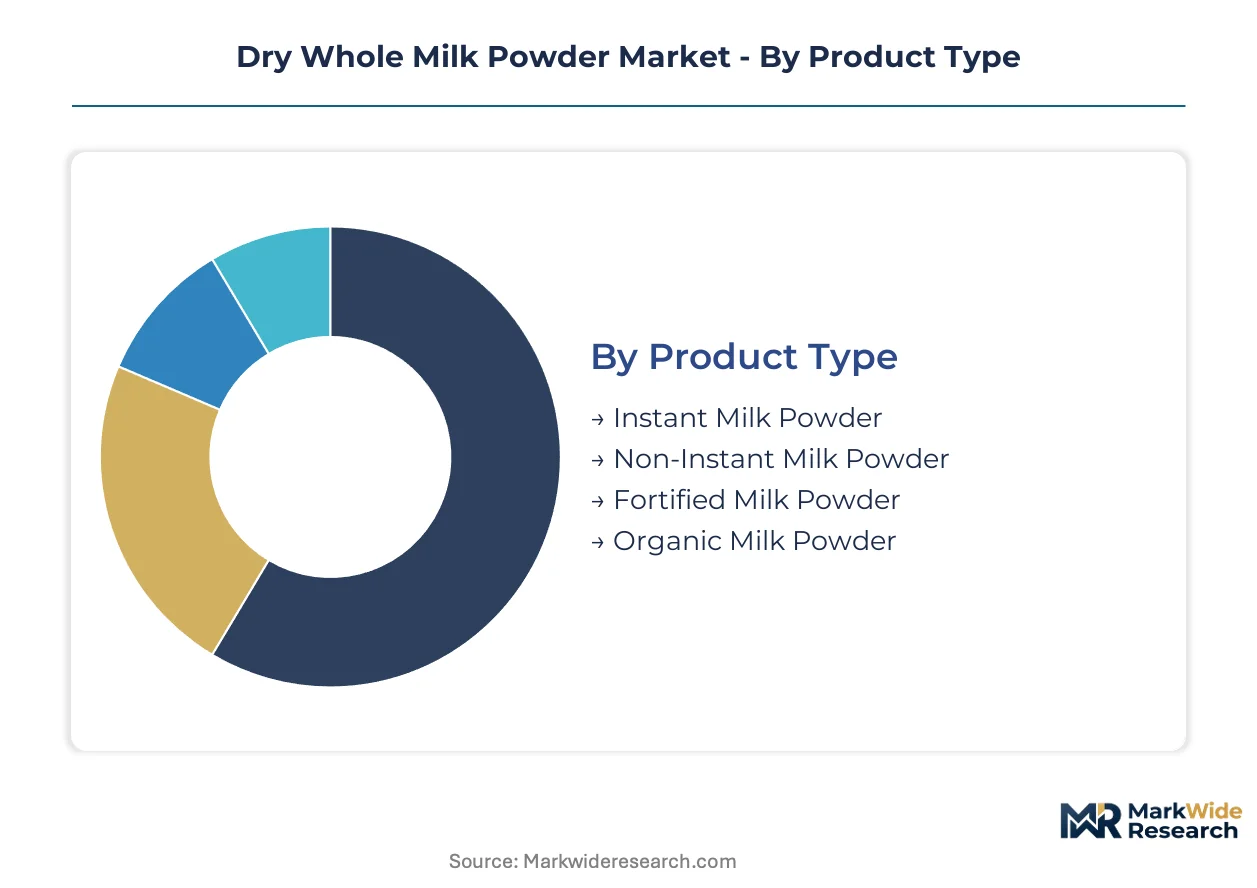
Segmentation in dry whole milk powder reveals how capital deployment, regulatory compliance, and shelf-life requirements fragment procurement patterns across industrial buyers and consumer channels. Specification divergence between instant and fortified formulations creates distinct margin pools that reshape manufacturing priorities.
Product Type:
Capital intensity varies sharply across drying technologies, with spray-drying towers requiring the heaviest upfront investment while organic certification demands sustained compliance expenditure rather than equipment.
- Instant Milk Powder:Agglomerated particles with enhanced wettability dissolve rapidly in ambient-temperature water without mechanical agitation. Dairy manufacturers in Vietnam and Indonesia prioritize instant specifications for reconstitution lines serving school feeding programs. Most installed capacity flows through Instant Milk Powder. Expansion is steepest in Fortified Milk Powder.
- Fortified Milk Powder:Vitamin A, D, and mineral-enriched formulations meeting national nutrition program mandates. SAMR registration requirements in China extend approval timelines for foreign suppliers seeking infant formula ingredient status, concentrating demand among pre-approved Oceania cooperatives.
- Non-Instant Milk Powder:Standard spray-dried particles requiring mechanical mixing for reconstitution. Cost-sensitive bakery and confectionery applications in Indonesia absorb volume.
- Organic Milk Powder:Pasture-certified production with restricted antibiotic use and traceable supply chains. EU organic regulations create premium tier separation with constrained supply.
Equipment utilization rates favor high-volume instant lines, while organic batches run at lower throughput with extended cleaning protocols.
End User:
Application requirements dictate specification stringency, with nutritional supplements demanding the tightest microbiological controls and infant formula triggering the longest regulatory pathways.
- Nutritional Supplements:Clinical-grade fortification with probiotic and HMO additive combinations. EFSA health claims regulation tightens evidentiary requirements for immune-support positioning in European markets.
- Dairy Manufacturers:Bulk ingredient procurement for reconstitution into fluid milk and fermented products. Indonesian brands building domestic blending facilities reduce dependency on pre-mixed imported formulations.
- Food & Beverage Industry:Standardized milk solids for processed cheese, ice cream, and beverage bases. Cold-chain gaps favor shelf-stable powder with 18-month stability windows.
- Bakery Products:Cost-optimized non-instant powder for bread, pastry, and biscuit manufacturing. Volume concentrates in Southeast Asian commercial bakeries.
Regulatory complexity clusters around nutritional supplements, while dairy manufacturers drive procurement scale.
Distribution Channel:
Channel economics separate bulk industrial flows from consumer-facing fulfillment, with platform-direct models compressing traditional import distributor margins.
- Wholesalers:Bulk tonnage movements to dairy processors and food manufacturers. Fonterra dominates Oceania-to-Asia bulk ingredient supply through long-term procurement contracts.
- Online Stores:Platform-direct consumer fulfillment bypassing tier-two Chinese city distributors. Instant milk powder SKUs migrate from wholesale into e-commerce with resealable pouch specifications.
- Retail Stores:Supermarket and convenience store distribution for household reconstitution. Indonesian chains specify high-barrier laminate private-label lines.
- Direct Sales:Technical service bundling with equipment for domestic reconstitution facilities. Vietnamese dairy brands contract process engineering alongside powder supply.
Wholesalers handle volume concentration, while online channels capture margin expansion in premium positioning.
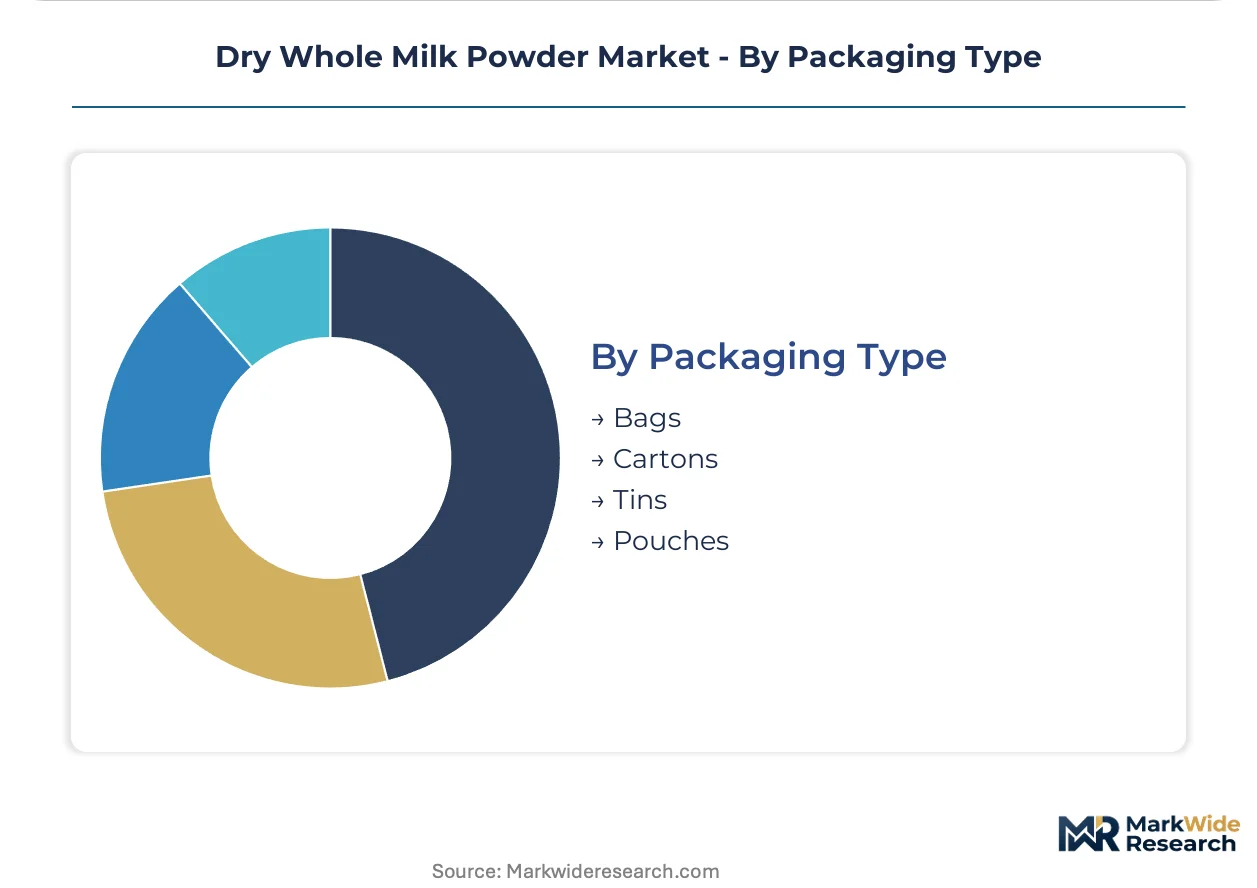
Packaging Type:
Material science investments differentiate barrier performance, with multi-layer laminates requiring specialized converter capacity against established metal canning infrastructure.
- Pouches:Multi-layer high-barrier laminates with resealable zippers displacing metal tins. Vietnamese and Indonesian supermarket chains specify shelf-ready display formats cutting unit shipping weight.
- Tins:Traditional metal canning for 18-month shelf stability in humid climates. Equipment utilization rates compress as flexible formats gain share.
- Bags:Industrial bulk packaging for dairy manufacturer procurement. Standard polyethylene liners with nitrogen flushing for oxidation protection.
- Cartons:Secondary retail packaging for multi-unit household formats. Limited penetration outside premium organic positioning.
Pouch adoption accelerates fastest in emerging-market retail, while tins retain institutional procurement preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The dry whole milk powder industry traces its modern commercial origins to New Zealand's cooperative dairy system, which pioneered large-scale spray-drying for export markets in the mid-twentieth century. This heritage established Oceania as the foundational supply basin for Asian reconstitution industries. Today procurement patterns concentrate in five national markets where fortification mandates, processing infrastructure, and retail channel evolution create distinct operational environments.
New Zealand
Pasture-based dairy farming cooperatives supply bulk instant milk powder to Southeast Asian reconstitution facilities. The country's environmental regulator enforces freshwater management standards that constrain herd expansion and milk solids volume growth. Waikato region processing plants dominate export tonnage movements through Tauranga port logistics.
China
Domestic dairy brands are building captive spray-drying capacity to reduce dependency on Oceania imports for infant formula base ingredients. SAMR registration requirements extend 18-24 month approval timelines for foreign fortified powder suppliers. Heilongjiang province dairy clusters are expanding technical service bundling with equipment procurement for domestic blending facilities.
Vietnam
National nutrition programs mandate vitamin-enriched dairy inputs for school feeding schemes, expanding specification demand for fortified milk powder. The Ministry of Health fortification standards reshape procurement contracts for dairy manufacturers building in-house reconstitution lines. Ho Chi Minh City supermarket chains specify multi-layer pouch formats with resealable zippers for private-label instant powder lines.
Indonesia
Local dairy brands are displacing fluid milk imports through investments in shelf-stable powder with 18-month stability windows. Cold-chain infrastructure gaps favor dry whole milk powder reconstitution over fresh dairy distribution. Java-based processors face acute shortages of spray-drying process engineers capable of optimizing heat-transfer efficiency in multi-stage drying towers.
Germany
The EU Green Deal's carbon border adjustments accelerate capital deployment into heat-recovery spray-drying systems among Dutch and German processors. EFSA nutrition and health claims regulation tightens evidentiary requirements for immune-support positioning on fortified powder packaging. Bavarian dairy cooperatives are retrofitting plants with reverse osmosis pre-concentration stages to cut natural gas consumption per ton produced.
Dry Whole Milk Powder Market Vendor Landscape
Premium-margin players sit above commodity-margin players across fortification certification and organic pasture traceability tiers. The vendor base clusters around three strategic positions: Oceania-based cooperatives dominating bulk ingredient supply to Asian processors, European and North American integrated dairy groups with multi-regional processing footprints, and specialized nutritional supplement formulators targeting clinical-grade additive combinations. Competitive moves concentrate on membrane filtration technology licensing for energy efficiency gains and multi-layer pouch packaging format conversion for emerging-market retail channels.
Within the cooperative archetype tier, Fonterra Co-operative Group Limited and Royal FrieslandCampina N.V. represent the dominant sourcing positions for Asian dairy manufacturers requiring long-term procurement contracts. Among integrated multinational processors, Nestlé S.A. and Lactalis Group occupy positions spanning European fortification expertise and North American distribution scale. These named entities exemplify how geographic origin and corporate structure shape competitive positioning without dictating specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Fonterra Co-operative Group Limited |
| Nestlé S.A. |
| Lactalis Group |
| Arla Foods amba |
| Royal FrieslandCampina N.V. |
| Saputo Inc. |
| Danone S.A. |
| Dairy Farmers of America, Inc. |
| Amul |
| Others |
Supply Flow & Price Mechanics
Global Dairy Trade auction price indices cascade through Oceania-to-Asia supply chains into three distinct procurement tiers. Fonterra's fortnightly price discovery mechanisms anchor contract negotiations for bulk instant powder shipments to Vietnamese and Indonesian dairy manufacturers. Buyers in these markets face escalating feed cost volatility from New Zealand pasture conditions that transmit directly into milk solids pricing.
Pricing Analysis
Contract-based long-term offtake agreements dominate bulk ingredient procurement between Oceania cooperatives and Asian dairy processors. Price differentiation rests on fortification certification grade and volume scale, with SAMR-registered fortified powder commanding premium positioning over standard instant specifications. Cost compression in standard-grade powder is intensifying because EU Green Deal carbon border adjustments are elevating processing energy costs for European suppliers. Dairy manufacturers in Vietnam exhibit highest price sensitivity due to thin reconstitution margins, while nutritional supplement formulators in China show least sensitivity given clinical-grade specification requirements.
Supply Chain Analysis
Returns and reprocessing flows for off-specification powder create secondary material circuits between Southeast Asian reconstitution facilities and animal feed compounders. Geographic supply concentration centers on New Zealand, Australia, and the Netherlands as primary sourcing basins. Raw material dependencies draw from pasture-based milk solids, natural gas for spray-drying thermal energy, and multi-layer laminate films for emerging-market retail packaging. Single-source vulnerability during El Niño drought cycles poses structural risk for Asian processors locked into Oceania cooperative contracts. Distribution runs through Tauranga and Rotterdam port logistics into long-term procurement contracts with Vietnamese and Indonesian dairy brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Specification demand for probiotic and HMO-fortified infant formula ingredients is shifting procurement priorities toward clinical-grade certification tiers.
For Market Incumbents: To counter plant-based fat-protein substitution pressure from oat and coconut blend suppliers, Fonterra and FrieslandCampina should deepen backward integration into pasture-certified milk supply with restricted antibiotic protocols. Channel control through technical service bundling for Vietnamese domestic reconstitution facilities represents a second defensive lever against emerging-market processor consolidation. For New Entrants and Emerging Players: The EU Green Deal's carbon border adjustment mechanism in Germany and the Netherlands opens a window for membrane filtration technology licensors to capture equipment retrofit contracts among Bavarian dairy cooperatives. White-space targets include organic certification tiers with traceable supply chains and e-commerce direct fulfillment for instant powder SKUs in tier-two Chinese cities. A go-to-market angle through platform-direct consumer fulfillment bypasses entrenched import distributor networks. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized nutritional supplement formulators possessing EFSA dossier submission capabilities and published clinical trial backing for immune-support positioning. Long-term viability over a multi-year horizon favors acquisition targets with SAMR pre-approval status and established technical service relationships with Southeast Asian dairy brands. The signal to watch is acceleration in Chinese domestic spray-drying capacity buildout in Heilongjiang province as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Retrofit | Bavarian cooperatives cut natural gas consumption per ton through reverse osmosis pre-concentration stages. |
| SAMR Registration Investment | Foreign suppliers secure 18-24 month approval timelines for infant formula ingredient status in China. |
| Multi-Layer Pouch Conversion | Indonesian supermarket chains specify high-barrier laminate formats with resealable zippers for private-label lines. |
| Domestic Reconstitution Buildout | Vietnamese dairy brands reduce import dependency through in-house blending facilities and technical service contracts. |
| Organic Pasture Certification | EU organic regulations create premium tier separation with constrained supply and traceable antibiotic-free protocols. |
Methodological Framework
Coverage spans New Zealand, China, Vietnam, Indonesia, and Germany, with primary inputs from each market's dairy processing clusters. The approach combines primary interviews with spray-drying process engineers, procurement leads at Asian dairy manufacturers, regulatory affairs specialists navigating SAMR and EFSA frameworks, and flexible film converter technical directors with secondary validation. Secondary sources include Fonterra Global Dairy Trade auction data, EU Green Deal implementation tracking, Codex Alimentarius standards documentation, and Chinese customs import records. Bottom-up volume modeling triangulates against top-down macroeconomic consumption indicators.
Granularity-level modeling disaggregates volume and value outputs across product type, end user, distribution channel, and packaging format dimensions throughout the forecast period. CAGRs derive from segment-level growth trajectory analysis calibrated to national fortification mandate implementation timelines and cold-chain infrastructure development patterns. Industry-specific forecast inputs incorporate El Niño cycle probability distributions for pasture-based milk solids supply and membrane filtration technology adoption curves among European processors.
Revisions become necessary when diverging national fortification mandates reshape product portfolio priorities or when carbon border adjustment mechanisms alter inter-regional cost competitiveness. Forecasts reflect assumptions regarding SAMR registration timeline stability and EU organic dairy regulation enforcement consistency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Probiotic Yogurt Market
Dairy Products
Donkey Milk Market
Dairy Products
Europe Cow Milk Minerals Market
Dairy Products
Milk Protein Concentrate Market
Dairy Products
Buttermilk Powder Market
Dairy Products
Low Cholesterol Cheese Market
Dairy Products
Milk Mineral Market
Dairy Products
Africa Dairy Protein Market
Dairy Products
Cheese Shreds Market
Dairy Products
Fluid Milk Market
Dairy Products
Parmesan Cheese Market
Dairy Products
Europe Dairy Market
Dairy Products
Canada Milk Protein Market
Dairy Products
Fat-Filled Milk Powder Market
Dairy Products
Sweetened Condensed Milk Market
Dairy Products
Milk Fat Fractions Market