
 China Pea Protein Market | 2026-2036
China Pea Protein Market Size, Share, and Industry Trends Forecast 2026-2036
China Pea Protein Market Outlook
China's dual carbon goals from MEE is broadening the addressable market for low-carbon protein ingredients as food manufacturers face binding emissions disclosure requirements. Roquette Frères SA leverages its European extraction expertise to serve multinational brands operating in China. Shandong Yuwang Industrial Co Ltd anchors domestic supply through integrated pea processing in Shandong province. Shandong Jianyuan Bioengineering Co Ltd specializes in isolates for nutritional supplements, competing on purity specifications against imported alternatives.
Pea protein denotes the isolated or concentrated protein fraction extracted from yellow or green peas through dry or wet milling, typically yielding protein contents from fifty to ninety percent depending on processing intensity. Its primary commercial purpose centers on replacing animal-derived proteins in formulated foods where emulsification, gelation, or foaming properties must replicate dairy or egg functionality. Isolates command premium positioning in nutritional supplements and sports nutrition due to superior amino acid completeness and minimal off-flavor carryover. Textured pea protein gains traction in meat alternatives as extrusion technology improves fibrous mouthfeel replication. Dairy alternatives applications absorb significant volume as oat and almond bases blend pea protein to achieve complete protein claims.
SAMR enforces GB standards for plant protein labeling and safety thresholds, while MEE audits carbon intensity in processing facilities under provincial emissions trading schemes. BIS-aligned import checks on pea protein isolates create compliance friction for non-domestic suppliers seeking shelf placement. Stakeholders must monitor how China's evolving green finance taxonomy reclassifies protein extraction investments and whether provincial energy quotas constrain expansion timelines for new processing capacity.
Market Dynamics
China's dual carbon goals from MEE are restructuring protein extraction economics, forcing coastal processors to retrofit facilities with carbon capture and renewable energy systems while inland competitors face stranded asset risk from provincial emissions trading schemes.
Growth Catalysts
- Plant-based dairy alternatives:Shanghai and Beijing food manufacturers blend pea protein into oat and almond bases to achieve complete protein claims, absorbing significant isolate volume.
- Dual carbon disclosure mandates:Binding emissions reporting requirements from MEE broaden the addressable market for low-carbon protein ingredients as manufacturers seek certified inputs.
- Extrusion technology advances:Textured pea protein gains traction in meat alternatives as improved fibrous mouthfeel replication attracts reformulating foodservice operators.
Market Restraints
- Yellow pea import dependency:Domestic protein processors rely on Canadian and Australian yellow pea supply, exposing margins to currency volatility and ocean freight rate spikes.
- GB standard compliance friction:SAMR labeling and safety threshold enforcement creates technical barriers for imported isolates seeking shelf placement against domestic alternatives.
- Soy protein substitution pressure:Established soy protein isolate infrastructure in Shandong and Heilongjiang provinces competes aggressively on price in nutritional supplement applications.
Strategic Opportunities
- Central and western province penetration:Underdeveloped food processing clusters in Sichuan and Hubei present first-mover advantages for localized pea protein distribution networks.
- Green finance taxonomy reclassification:China's evolving sustainable investment framework may reclassify protein extraction as eligible for preferential lending, accelerating capacity expansion timelines.
- Sports nutrition channel expansion:Direct-to-consumer e-commerce platforms and specialty fitness retailers remain fragmented, offering margin capture potential for isolate suppliers with purity certifications.
Industry Challenges
- Food-grade extraction engineering shortage:Provincial universities produce limited specialists in plant protein wet milling and membrane filtration, constraining facility commissioning schedules.
- Provincial energy quota allocation:New processing capacity in eastern coastal clusters faces uncertain electricity supply guarantees under tightening industrial consumption caps.
- Carbon intensity audit preparation:MEE facility inspections require documented supply chain emissions data that most domestic processors lack systematic tracking systems to generate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Pea Protein Market |
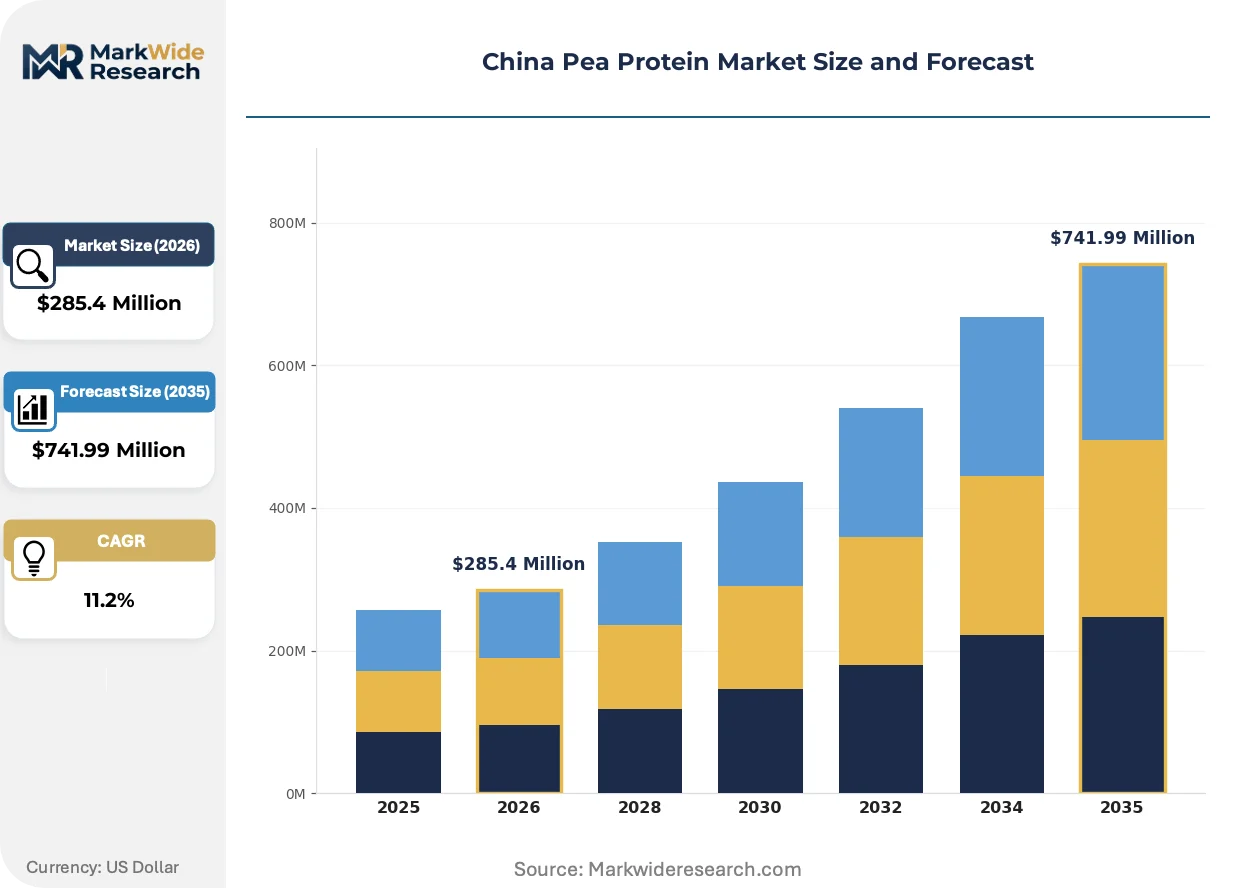
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $741.99 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolates, Concentrates, Textured, Flour End User: Food & Beverages, Nutritional Supplements, Animal Feed, Bakery Application: Meat Alternatives, Dairy Alternatives, Protein Fortification, Snacks Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Food Stores |
| Companies Covered | Roquette Frères SA, Shandong Yuwang Industrial Co Ltd, Shandong Jianyuan Bioengineering Co Ltd, Wuxi Jinnong Biotechnology Co Ltd, Shandong Qufeng Food Technology Co Ltd, Yantai Shuangta Food Co. Ltd, ETChem, Foodchem International Corporation, Archer Daniels Midland Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Pea Protein Market Strategic Shifts
Processing technology convergence and regulatory disclosure mandates are compressing competitive timelines across China's pea protein value chain, rewarding operators with integrated carbon accounting and advanced extraction capabilities.
Membrane filtration systems paired with enzymatic debittering protocols are unifying protein purity and sensory performance in a single processing train. Nutritional supplement manufacturers in Guangdong province adopt these integrated lines at accelerating pace. The technology is unifying what previously required separate isolation and flavor-masking stages, compressing capital requirements for 90%+ protein isolate production.
MEE's provincial emissions trading schemes now audit carbon intensity in protein extraction facilities, binding facility operators to documented energy sourcing and waste heat recovery protocols. Industrial clusters in Shandong province face the steepest compliance curves given legacy coal-dependent thermal systems. Dairy alternative formulators increasingly source exclusively from processors with verified low-carbon certifications, shifting procurement criteria.
Direct ingredient sourcing from extraction facilities is displacing layered distributor networks for large-volume food manufacturers. Multinational brands operating in China now contract directly with Shandong-based processors for isolate supply, bypassing traditional import trading houses. This pattern concentrates most visibly in Beijing and Shanghai headquarters of reformulating food companies seeking supply chain transparency for ESG reporting.
China Pea Protein Market Segmentation
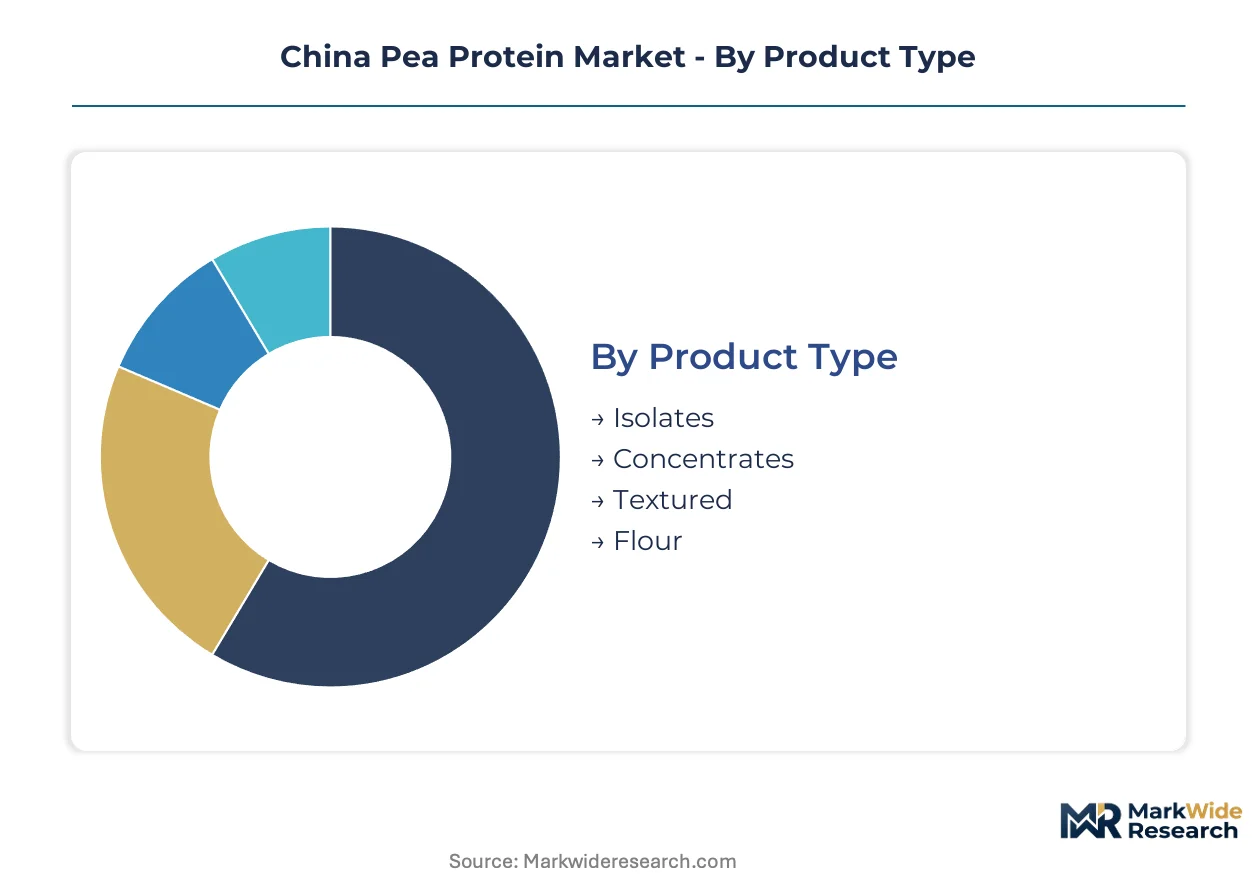
Pea protein segmentation in China reflects divergent capital requirements across extraction intensity levels and end-use specifications. Manufacturers configure processing lines around isolate purity targets or textured functionality, with each tier demanding distinct membrane filtration and extrusion investments.
Product Type:
Isolates demand the steepest upfront capital for multi-stage membrane filtration and enzymatic debittering systems, while textured variants require precision extrusion infrastructure.
- Isolates:Protein fractions exceeding 85% purity achieved through wet milling, centrifugation, and diafiltration sequences. Nutritional supplement manufacturers in Guangdong province source these for amino acid completeness claims, though MEE carbon audits raise operating costs for coastal processors.
- Concentrates:Intermediate protein levels from 50-70% via dry fractionation without full isolation. Dairy alternative blenders in Shanghai combine concentrates with oat bases to manage formulation costs while maintaining protein content thresholds.
- Textured:High-moisture extrusion creates fibrous structures replicating meat mouthfeel. Foodservice operators in Beijing reformulate menu items using these inputs as extrusion technology advances.
- Flour:Whole pea milling retains starch and fiber alongside protein. Animal feed compounders in Shandong province absorb volume for cost-efficient protein supplementation.
Isolates absorb the bulk of installed capacity; textured is expanding most quickly.
End User:
Customer type determines margin structure, with nutritional supplements commanding purity premiums and foodservice demanding volume scalability.
- Food & Beverages:Dairy alternative formulators in Beijing and Shanghai blend pea protein into oat and almond bases for complete protein positioning. SAMR GB labeling compliance shapes procurement criteria.
- Nutritional Supplements:Sports nutrition brands specify isolate purity above 90% with documented amino acid profiles. Direct-to-consumer e-commerce channels capture margin through specialty fitness retailers.
- Animal Feed:Compound feed manufacturers in Shandong province utilize pea protein flour for cost-efficient protein supplementation in aquaculture and livestock rations.
- Bakery:Protein fortification in baked goods remains nascent, with technical challenges around moisture retention and crumb structure limiting adoption.
Food & Beverages commands the largest volume share; Nutritional Supplements delivers the steepest margin expansion.
Application:
Functional requirements vary sharply across meat replication, dairy extension, and direct fortification use cases.
- Meat Alternatives:Textured pea protein extruded into fibrous matrices replicates muscle tissue structure. Improved high-moisture extrusion technology attracts reformulating foodservice operators in tier-one cities.
- Dairy Alternatives:Isolate and concentrate blends achieve emulsification and gelation properties mimicking dairy proteins. Binding emissions disclosure requirements from MEE steer procurement toward low-carbon certified processors.
- Protein Fortification:Concentrates integrate into beverages and bars without complete solubility requirements. Cost-sensitive positioning competes against established soy protein infrastructure.
- Snacks:Extruded puffed applications utilize pea protein for texture modification and protein content elevation in savory formulations.
Dairy Alternatives anchors current demand; Meat Alternatives is climbing the fastest as extrusion capabilities mature.
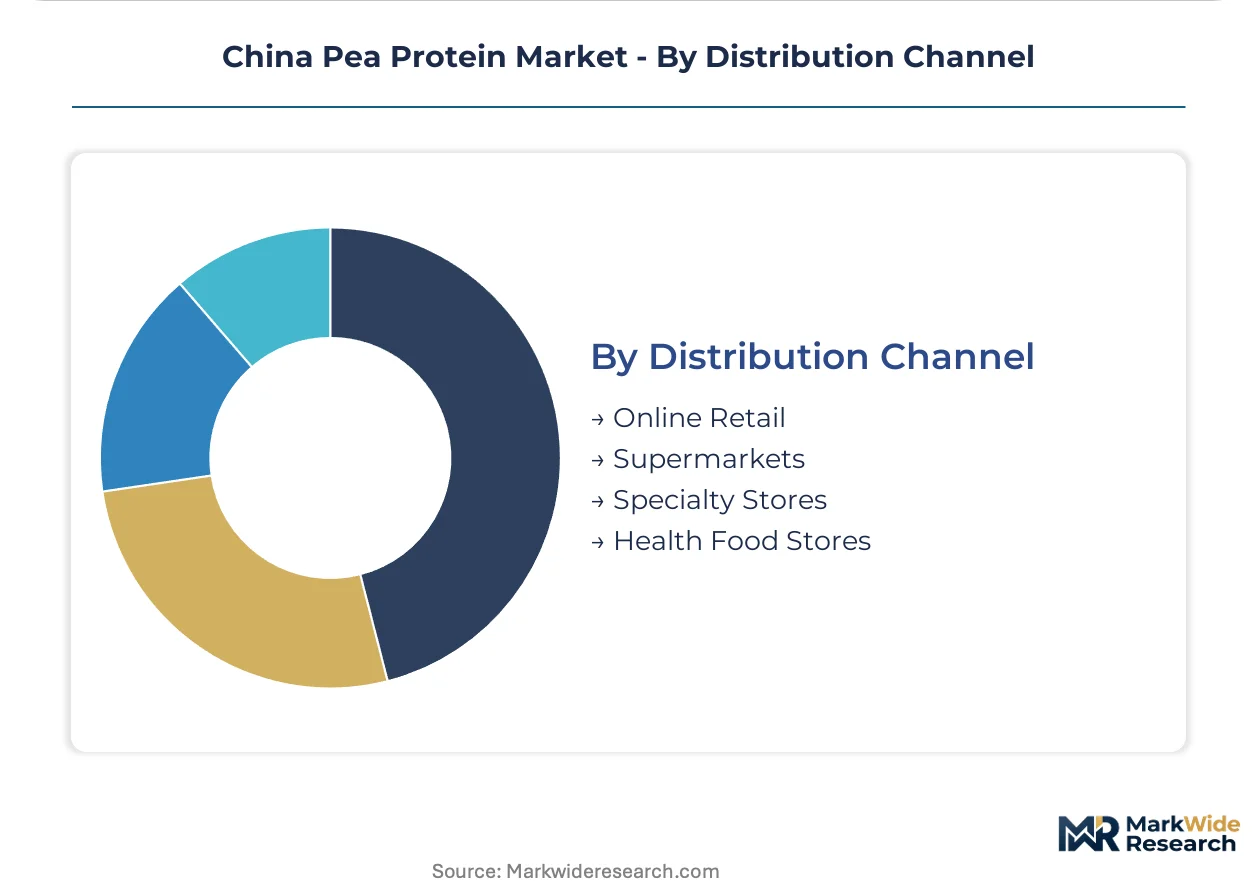
Distribution Channel:
Channel selection reflects customer scale and transparency requirements, with large manufacturers bypassing intermediaries.
- Online Retail:Direct-to-consumer platforms enable isolate suppliers with purity certifications to reach fragmented specialty fitness markets. E-commerce penetration concentrates in tier-one and tier-two urban centers.
- Supermarkets:Mass retail placement requires GB standard compliance and established brand recognition, favoring domestic processors with SAMR registration history.
- Specialty Stores:Health food retailers curate premium isolates for sports nutrition enthusiasts, capturing margin through certification-driven differentiation.
- Health Food Stores:Traditional pharmacy-adjacent channels serve aging demographics seeking protein fortification, though volume remains limited.
Online Retail is gaining share fastest; Supermarkets retains the deepest volume foundation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic pea protein production concentrates in Shandong province while consumption gravitates toward eastern coastal manufacturing clusters. This geographic mismatch creates logistical premiums that reshape procurement patterns across tier-one cities.
Shandong Province
Integrated pea processing facilities in Shandong province supply the bulk of domestic isolate output. MEE provincial emissions trading schemes audit carbon intensity at extraction sites, forcing retrofits of legacy coal-dependent thermal systems. Yuwang Industrial and Jianyuan Bioengineering anchor production in this cluster, serving multinational brands with direct sourcing contracts.
Yangtze River Delta
Shanghai and Jiangsu food manufacturers blend pea protein into oat and almond bases for complete protein positioning. SAMR GB labeling compliance shapes procurement criteria for dairy alternative formulators. The region's food processing infrastructure absorbs significant isolate volume despite lacking local extraction capacity.
Beijing-Tianjin-Hebei
Reformulating foodservice operators in Beijing drive textured pea protein adoption as extrusion technology improves. MEE dual carbon disclosure mandates steer procurement toward low-carbon certified processors. Direct ingredient sourcing from Shandong-based facilities bypasses traditional distributor networks for headquarters-based multinationals.
Pearl River Delta
Guangdong nutritional supplement manufacturers adopt membrane filtration systems paired with enzymatic debittering protocols at accelerating pace. SAMR enforces safety thresholds for plant protein labeling, creating technical barriers for imported isolates. The region's sports nutrition e-commerce channels capture margin through specialty fitness retailers.
Sichuan-Chongqing
Underdeveloped food processing clusters in Sichuan and Hubei present first-mover advantages for localized distribution networks. Provincial energy quota allocation constrains new processing capacity in eastern coastal clusters, redirecting expansion interest inland. Localized pea sourcing infrastructure remains nascent, requiring supply chain buildout investment.
China Pea Protein Market Competitive Environment
The competitive structure tilts toward domestic integrated processors with captive supply chains. Market concentration remains moderate, with multinational ingredient suppliers competing against provincial industrial conglomerates for share in premium isolate segments. Three archetypes dominate: European extraction technology licensors, Shandong-based integrated processors with backward control over raw material sourcing, and specialty isolate purifiers serving nutritional supplement channels. Capacity expansion and direct sourcing relationships constitute the dominant competitive moves, as food manufacturers bypass layered distributor networks for supply chain transparency.
Among European technology licensors, Roquette Frères SA represents the extraction expertise archetype serving multinational brands operating in China. Shandong Yuwang Industrial Co Ltd and Shandong Jianyuan Bioengineering Co Ltd occupy positions within the domestic integrated processor tier, anchoring provincial supply networks. These three exemplify the geographic and capability segmentation that structures procurement decisions across dairy alternative and nutritional supplement end uses.
| Leading Market Players |
|---|
| Roquette Frères SA |
| Shandong Yuwang Industrial Co Ltd |
| Shandong Jianyuan Bioengineering Co Ltd |
| Wuxi Jinnong Biotechnology Co Ltd |
| Shandong Qufeng Food Technology Co Ltd |
| Yantai Shuangta Food Co. Ltd |
| ETChem |
| Foodchem International Corporation |
| Archer Daniels Midland Company |
| Others |
Value Chain & Pricing Dynamics
Backward integration into Canadian and Australian yellow pea sourcing anchors both supply security and pricing power for Shandong-based processors, while coastal formulators absorb ocean freight volatility through contract structures. This captive supply model concentrates margin control among integrated domestic players as MEE carbon audits add compliance premiums to extraction economics.
Pricing Analysis
Margin tightening in isolate tiers reflects MEE carbon audit premiums and enzymatic debittering capital costs. Three-tier pricing structure across premium, standard, and economy levels separates 90%+ purity isolates for sports nutrition from 50-70% concentrates for dairy blending and flour-grade feed inputs. Cost-down pressure on concentrates accelerates because soy protein substitution in Shandong competes aggressively on price. Nutritional supplement manufacturers show least price sensitivity; animal feed compounders absorb economy-grade volume with maximum sensitivity to input fluctuations.
Supply Chain Analysis
Ocean freight rate spikes from Vancouver and Melbourne ports transmit directly to Shandong processing margins, forcing inventory carrying cost trade-offs. Raw material flows draw from Canadian prairie provinces and Australian southern growing regions, with protein content variability creating batch standardization challenges. Single-source vulnerability concentrates in yellow pea import channels given minimal domestic cultivation. Distribution runs through direct contracts from extraction facilities to Beijing and Shanghai formulators, displacing layered import trading houses for ESG transparency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's pea protein sector is consolidating around carbon-compliant integrated processors as MEE emissions trading schemes force sub-scale competitors into stranded asset positions.
For Market Incumbents: Lock in direct sourcing relationships with multinational dairy alternative brands headquartered in Beijing and Shanghai before provincial energy quotas constrain eastern coastal expansion timelines. Prioritize membrane filtration capacity additions with documented carbon intensity certifications to defend against Roquette's European technology licensing. Backward integration into pea protein flour production for Shandong aquaculture feed compounders absorbs volume during isolate demand troughs. For New Entrants and Emerging Players: Capture underdeveloped food processing clusters in Sichuan and Chongqing through localized distribution partnerships before incumbent logistics networks extend inland. Target sports nutrition e-commerce channels in Guangdong with 90%+ purity isolates and documented amino acid profiles, where fragmentation among specialty fitness retailers permits margin capture. Lead with SAMR GB pre-registration to bypass compliance friction that slows imported competitor shelf placement. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of Shandong-based processors with verified low-carbon certifications and existing direct contracts to multinational reformulators. Long-term viability favors operators with captive pea sourcing infrastructure and membrane filtration engineering capabilities that provincial universities cannot rapidly replicate. Watch MEE provincial emissions trading scheme expansion announcements as the inflection signal for compliance cost restructuring across competitor cost bases.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit | MEE audits force coal-dependent Shandong processors to install waste heat recovery or face quota penalties. |
| Direct Sourcing Contract | Multinational brands in Beijing bypass import trading houses for supply chain transparency in ESG reporting. |
| Membrane Filtration Expansion | Guangdong nutritional supplement manufacturers adopt integrated enzymatic debittering lines for 90%+ isolate purity. |
| Inland Distribution Buildout | Sichuan and Hubei food processing clusters lack localized pea protein infrastructure, creating first-mover advantages. |
| SAMR GB Pre-Registration | Compliance with plant protein labeling standards accelerates shelf placement against non-domestic isolate competitors. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced against primary interviews with extraction facility engineers, dairy alternative formulators in Shanghai, sports nutrition brand procurement leads, and SAMR compliance officers. Bottom-up volume triangulation from Shandong processor capacity utilization merged with top-down demand sizing from foodservice operator reformulation surveys. MEE provincial emissions disclosures and GB standard enforcement records provided regulatory constraint parameters.
Production volume streams reconciled against import customs data for Canadian and Australian yellow pea shipments, with protein content assays validating extraction yield assumptions across the projection horizon. Segmentation modeling incorporated product type tiers, end-user margin structures, application functional requirements, and distribution channel transparency demands. CAGRs derived from capacity expansion timelines, provincial energy quota allocations, and direct sourcing contract velocity.
The model holds under sustained MEE enforcement of dual carbon disclosure mandates; deviation in provincial emissions trading scheme coverage expansion or yellow pea import tariff adjustments would shift competitive positioning toward domestic cultivation investments. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
United States Meat Substitutes Market
Plant Based Food
France Plant Protein Market
Plant Based Food
Global Vegan Fast Foods Market
Plant Based Food
Europe Textured Vegetable Protein Market
Plant Based Food
Vegan Margarine Market
Plant Based Food
Hemp-Based Food Market
Plant Based Food
Plant-Based Tzatziki and Labneh Ferment Bases Market
Plant Based Food
United Kingdom Soy Protein Market
Plant Based Food
Vegan Tortillas Market
Plant Based Food
Plant-Based Meatballs Market
Plant Based Food
Plant Based Supplement Market
Plant Based Food
Asia-Pacific Rice Protein Market
Plant Based Food
United Kingdom Tofu Market
Plant Based Food
Vegan Meat Alternatives Market
Plant Based Food
Vegan Oatmeal Market
Plant Based Food
USA Plant-Based Creamers Market