
 Reduced Fat Cheeses Market | 2026-2036
Reduced Fat Cheeses Market Size, Share, and Industry Trends Forecast 2026-2036
Reduced Fat Cheeses Market Analytics
Food service buyers are unwinding their traditional full-fat cheese commitments as retail health-conscious consumers gain share in reduced fat cheese procurement. Kraft Heinz Company leverages its retail distribution scale to sustain shelf presence across mainstream grocers. Arla Foods anchors its European supply base with specialized dairy processing capabilities for lower-fat variants. Lactalis Group competes through integrated milk sourcing that controls cost structures across multiple geographies.
Reduced fat cheeses are dairy products manufactured with lowered butterfat content, typically achieved through skimming, enzymatic modification, or fat-mimetic ingredient integration, delivering comparable melt and texture profiles for commercial food production and home consumption. Cheddar variants dominate volume flows in North American retail, while mozzarella captures expanding demand in food service pizza applications where operators seek calorie-compliant menu options. The snacking application segment leads margin generation through premium-positioned portion packs, whereas online distribution channels represent the fastest-growing access point for athlete and family customer types seeking direct-to-home replenishment.
FDA standards govern fat-content labeling claims and nutritional disclosure requirements for reduced fat cheeses sold in the United States, while EFSA evaluates novel enzyme technologies and fat replacer additives under EU food safety protocols. These frameworks shape reformulation investment priorities and determine which ingredient innovations achieve commercial scale across regulated markets. Stakeholders must monitor evolving clean-label thresholds and regional enforcement intensity to align R&D pipelines with compliant product positioning.
Market Dynamics
Clean-label mandates from FDA and EFSA are forcing cheese manufacturers to abandon synthetic fat replacers in favor of enzymatic skimming and natural protein-stabilized emulsions, reshaping R&D priorities across the dairy value chain.
Growth Catalysts
- Calorie-Compliant Menu Mandates:Food service operators in United States school districts and healthcare cafeterias now specify reduced-fat mozzarella for pizza applications, creating institutional procurement pull-through.
- EFSA Novel Enzyme Approvals:Streamlined safety evaluations for lipase-modified dairy proteins accelerate European reformulation timelines and reduce regulatory uncertainty for exporters.
- Athlete Nutrition Segmentation:Sports dietitians in Germany and Japan recommend portion-controlled reduced-fat cheddar as post-workout protein sources, expanding premium snacking demand.
Market Restraints
- Butterfat Input Volatility:Cream separation yields fluctuate with seasonal milk composition, compressing margins for skimming-dependent production.
- Natural Fat Replacer Cost Premium:Microcrystalline cellulose and inulin command 40-60% price premiums over hydrogenated alternatives, limiting mass-market penetration.
- Texture Performance Ceiling:Current enzymatic modification cannot replicate full-fat melt stretch in high-temperature pizza applications, constraining food service adoption.
Strategic Opportunities
- Direct-to-Consumer Subscription Channels:Online replenishment platforms targeting family households in United States suburban markets bypass traditional grocery slotting fees.
- Fermentation-Derived Protein Convergence:Precision fermentation of dairy-identical proteins combined with traditional cheesemaking opens clean-label positioning without skimming yield loss.
- Japan's Functionality Claims Framework:FOSHU (Foods for Specified Health Uses) approval pathways enable premium pricing for cholesterol-reduction positioned products.
Industry Challenges
- Clean-Label Reformulation Talent Scarcity:Dairy protein chemists with enzymatic modification expertise command premium compensation in competitive labor markets.
- Dual Certification Timelines:Simultaneous FDA GRAS self-determination and EFSA novel food dossier preparation extends time-to-market by 18-24 months.
- Legacy Equipment Retrofit Requirements:Existing cheese vats require stainless steel upgrades to prevent protein-stabilized emulsion fouling during reduced-fat production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reduced Fat Cheeses Market |
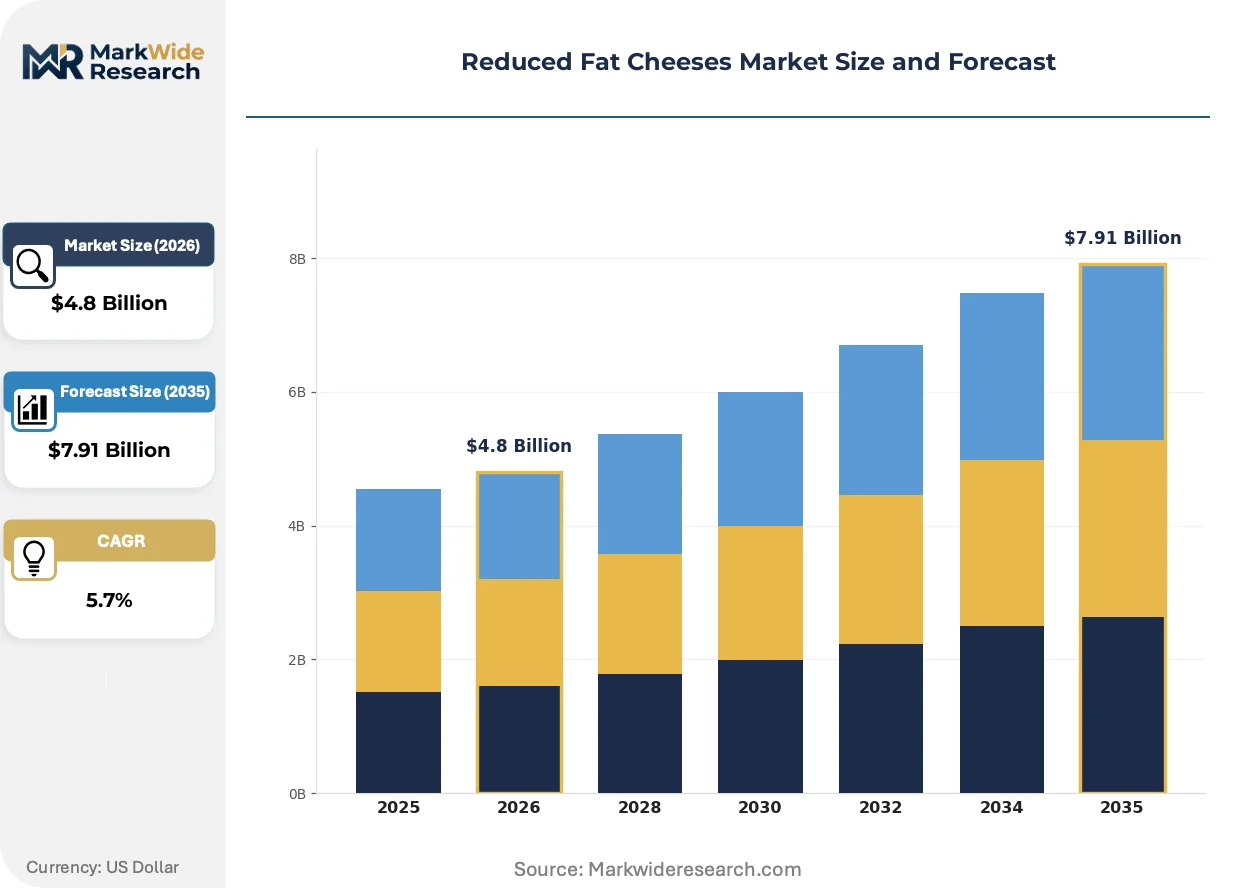
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cheddar, Mozzarella, Cream Cheese, Paneer Application: Snacking, Cooking, Baking, Spreading Distribution Channel: Supermarkets, Food Service, Online, Specialty Stores Customer Type: Health-Conscious Consumers, Athletes, Families, Culinary Experts |
| Companies Covered | Kraft Heinz Company, Arla Foods, Lactalis Group, Dairy Farmers of America, Nestlé S.A., Danone S.A., Sargento Foods Inc., Land O'Lakes Inc., Saputo Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reduced Fat Cheeses Market Evolving Landscape
Enzymatic fat modification and precision fermentation are converging to solve the texture-melt paradox that has historically limited reduced-fat cheese acceptance in food service channels.
Microbial lipase systems is decomposing the traditional trade-off between fat reduction and functional performance in cheddar production. Pizza chain procurement teams in the United States Midwest are piloting these modified proteins for institutional contracts. The technology is compressing the performance gap between reduced-fat and full-fat mozzarella in high-temperature applications.
EFSA's 2023 updated guidance on enzyme-mediated dairy processing has clarified safety dossier requirements for cross-border EU trade. French and Dutch processors now accelerate novel formulation submissions under the streamlined framework. Italian PDO consortia resist adopting these methods, preserving traditional production specifications as competitive differentiation.
Subscription-based replenishment for athlete and family segments is displacing conventional grocery restocking cycles in United States coastal metros. Direct-to-home platforms capture recurring revenue through personalized portion sizing and flavor rotation. Germany's fitness studio retail partnerships replicate this model, embedding cheese products within wellness ecosystem touchpoints.
Reduced Fat Cheeses Market Segmentation
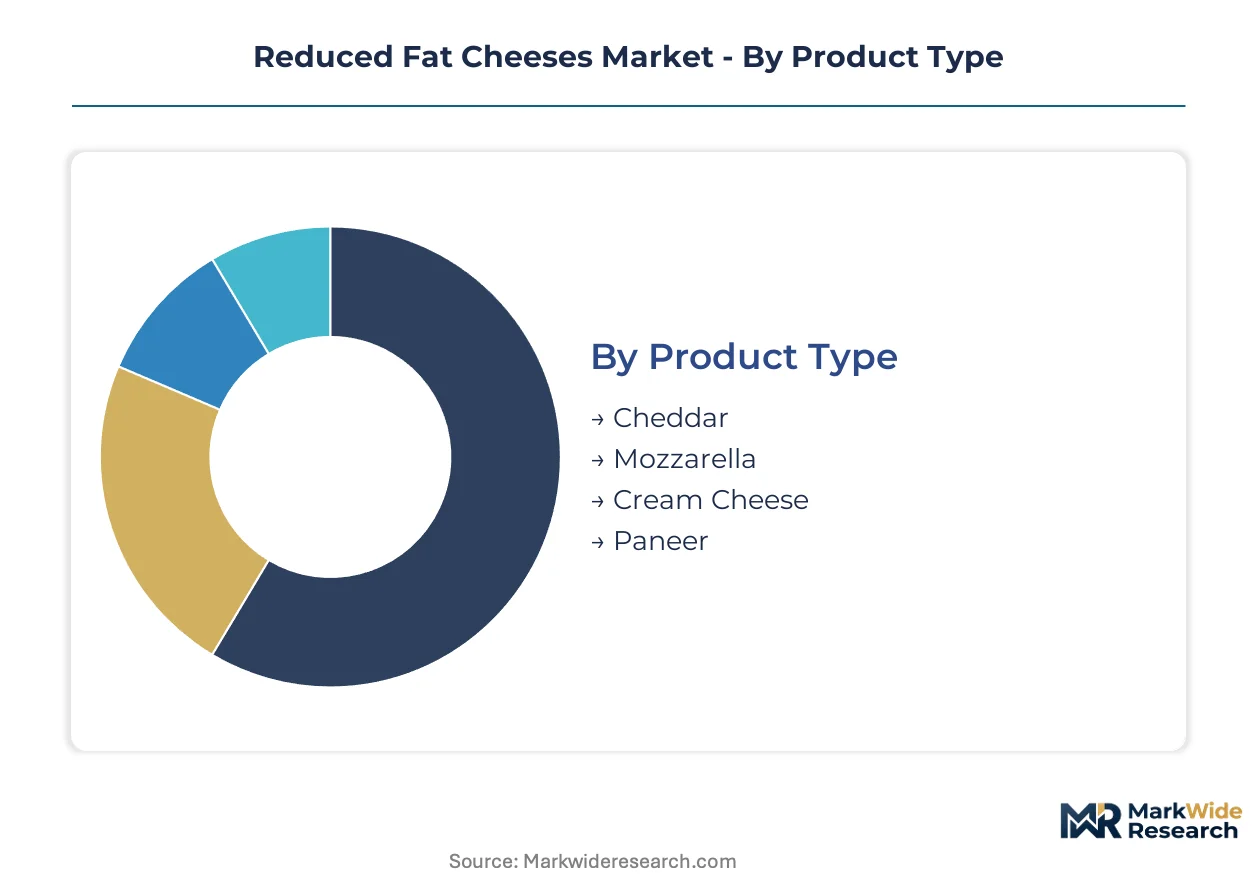
Reduced fat cheese segmentation reveals how regulatory frameworks and consumer health priorities fragment demand across distinct product specifications and channel access points. Manufacturers align formulation investments with the compliance requirements and functional expectations of each segment cluster.
Product Type:
FDA fat-content labeling thresholds and EFSA novel enzyme approvals create divergent formulation pathways across cheese varieties, determining which products achieve commercial scale in regulated markets.
- Cheddar:Enzymatic modification and protein-stabilized emulsions deliver reduced-fat variants with melt profiles suitable for institutional food service in United States school districts. Demand concentrates in North American retail where health-conscious households prioritize familiar flavor profiles in calorie-controlled formats.
- Mozzarella:Skimming-dependent production with natural fat replacers targets pizza chain procurement specifications for healthcare and education cafeteria contracts. Texture performance limitations in high-temperature applications constrain adoption despite expanding institutional menu mandates.
- Cream Cheese:Clean-label reformulation with inulin and microcrystalline cellulose serves spreading applications in Germany and Japan where FOSHU-adjacent positioning commands premium shelf placement.
- Paneer:Traditional skimming methods dominate South Asian export markets with lower regulatory burden on enzymatic modification.
Cheddar handles the majority of throughput; Mozzarella is the fastest mover on share.
Application:
Margin concentration varies sharply by use case, with portion-controlled formats capturing premium pricing against commodity cooking applications.
- Snacking:Single-serve portion packs with athlete-targeted protein positioning generate the highest margin per kilogram through direct-to-consumer subscription channels in United States coastal metros. Sports dietitian recommendations in Germany and Japan expand addressable demand beyond traditional grocery cycles.
- Cooking:Shredded and sliced formats for home meal preparation compete on price-per-ounce in supermarket dairy aisles with limited differentiation beyond fat-content claims.
- Baking:Melt-stability specifications for institutional pastry production favor full-fat alternatives, leaving reduced-fat variants with niche positioning in home baker segments.
- Spreading:Bagel and cracker pairing occasions in North American breakfast routines sustain steady volume through cream cheese variants with texture-mimetic formulations.
Snacking commands the steepest margin premium; Cooking moves the largest absolute tonnage through retail channels.
Distribution Channel:
Channel selection determines compliance burden intensity and customer acquisition economics for reduced-fat cheese manufacturers.
- Supermarkets:Slotting fee structures and clean-label shelf placement requirements in United States mainstream grocers favor established processors with reformulation scale. Kraft Heinz leverages existing retail relationships to defend position against emerging natural brands.
- Food Service:Institutional procurement specifications for calorie-compliant menus in United States school districts and healthcare facilities create volume anchors for mozzarella variants with documented nutritional profiles.
- Online:Subscription replenishment platforms bypass traditional grocery intermediaries, capturing recurring revenue through personalized portion sizing for athlete and family segments in suburban United States markets.
- Specialty Stores:Premium positioning in natural food retailers emphasizes enzymatic modification transparency and European sourcing credentials for discerning health-conscious consumers.
Supermarkets handle the majority of throughput; Online is expanding most quickly as direct-to-home platforms displace conventional restocking cycles.
Customer Type:
Segment-specific nutritional literacy shapes willingness to accept texture trade-offs and price premiums for reduced-fat alternatives.
- Health-Conscious Consumers:Clean-label scrutiny drives preference for enzymatic skimming over synthetic fat replacers, with EFSA novel food approvals serving as purchase validation in European markets.
- Athletes:Post-workout protein timing requirements in Germany and Japan create demand for portion-controlled cheddar with documented amino acid profiles and direct-to-locker-room distribution partnerships.
- Families:Calorie-reduction goals for household meal planning prioritize familiarity and value pricing over premium formulation credentials in United States suburban supermarkets.
- Culinary Experts:Texture performance skepticism limits adoption among professional chefs, though pizza chain procurement teams pilot enzymatic modified proteins for institutional contracts.
Health-Conscious Consumers anchor volume demand; Athletes are gaining share fastest through wellness ecosystem embedding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skimming-dependent production clusters concentrate in dairy-intensive regions where cream separation infrastructure and enzymatic modification capabilities overlap. United States, Germany, and Japan anchor throughput through distinct regulatory pathways and consumer health priorities.
United States
FDA fat-content labeling thresholds and school district calorie-compliant menu mandates drive mozzarella procurement for institutional pizza contracts. The Midwest dairy belt surrounding Wisconsin hosts enzymatic modification facilities serving national food service distribution networks. Chicago-based processors pilot microbial lipase systems for high-temperature melt applications.
Germany
EFSA novel enzyme approvals accelerate cheddar reformulation timelines while sports dietitian recommendations expand athlete-targeted snacking demand. Bavaria's specialized dairy processing corridor supplies lower-fat variants across European retail channels. Munich fitness studio retail partnerships embed portion-controlled products within wellness ecosystem touchpoints.
Japan
FOSHU functionality claims framework enables premium pricing for cholesterol-reduction positioned cream cheese variants. Tokyo's direct-to-home subscription platforms capture recurring revenue from health-conscious suburban households. Kansai region processors navigate clean-label thresholds for export-compliant formulations.
France
PDO consortia resist enzymatic modification methods, preserving traditional production specifications as competitive differentiation against reformulated imports. ANSM and EFSA dual oversight shapes novel ingredient dossier preparation timelines. Normandy's heritage dairy clusters maintain full-fat positioning while Lille-area processors experiment with protein-stabilized emulsions.
Canada
Health Canada nutritional disclosure requirements align with FDA frameworks for cross-border product standardization. Quebec's integrated dairy cooperatives control milk sourcing cost structures for skimming-dependent cheddar production. Ontario retail channels prioritize clean-label shelf placement for family household procurement.
Reduced Fat Cheeses Market Competitive Landscape
Concentration sits with diversified dairy conglomerates possessing integrated milk sourcing and retail distribution scale. Kraft Heinz Company leverages existing supermarket relationships to defend shelf position against emerging natural brands. Arla Foods anchors European supply through specialized processing capabilities. Lactalis Group competes via captive milk supply controlling cost structures. Dominant competitive moves include enzymatic modification R&D partnerships and direct-to-consumer channel bypass strategies.
Among North American-based processors, Kraft Heinz Company and Land O'Lakes Inc. exemplify scale-driven archetypes with entrenched retail slotting arrangements. Sargento Foods Inc. occupies a position within the specialty snacking tier. European-based Lactalis Group and Arla Foods represent integrated supply chain models. Saputo Inc. anchors Canadian-American cross-border production capabilities. These archetypes illustrate how milk sourcing control and reformulation scale determine competitive positioning under tightening clean-label mandates.
| Leading Market Players |
|---|
| Kraft Heinz Company |
| Arla Foods |
| Lactalis Group |
| Dairy Farmers of America |
| Nestlé S.A. |
| Danone S.A. |
| Sargento Foods Inc. |
| Land O'Lakes Inc. |
| Saputo Inc. |
| Others |
Value Network & Pricing Analysis
FDA fat-content labeling thresholds and EFSA novel enzyme approval pathways gate both supplier qualification and price differentiation simultaneously, forcing manufacturers to invest in compliant reformulation infrastructure before accessing premium shelf placement or institutional procurement contracts.
Pricing Analysis
FDA and EFSA compliance tiers dictate the pricing tier structure across the reduced fat cheese market. Three-tier pricing stratifies across premium enzymatic-modification products, standard skimming-based variants, and economy private-label offerings. Price differentiation rests on clean-label certification status and texture performance grade. Cost compression in the standard tier is intensifying because natural fat replacer inputs command substantial premiums over synthetic alternatives. Family households in United States suburban supermarkets exhibit highest price sensitivity, while athlete-targeted subscription channels accept substantial premiums for documented amino acid profiles.
Supply Chain Analysis
The United States, Germany, and Japan anchor reduced fat cheese production through distinct regulatory-specialized processing clusters. Raw material dependencies center on fluid milk supply, enzymatic modification inputs, and natural fat replacer stocks including microcrystalline cellulose and inulin. Supply chain risk concentrates in single-source vulnerability for lipase enzyme suppliers serving cross-border EU trade. Distribution runs through integrated dairy conglomerates controlling captive milk sourcing, with direct-to-consumer platforms emerging as alternative channel infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in wellness ecosystem embedding, as athlete nutrition segmentation and family subscription demand create niche entry points outside incumbent-controlled supermarket slotting structures.
For Market Incumbents: Compound defensive positioning through backward integration into enzymatic modification R&D partnerships and stainless steel equipment retrofit programs. Threat from precision fermentation entrants demands accelerated clean-label certification investment. Channel control through direct-to-consumer subscription platforms offers margin protection against private-label erosion. For New Entrants and Emerging Players: Lead with FOSHU-adjacent positioning in Japan's functionality claims framework and athlete locker-room distribution partnerships in Germany. Most penetrable white space sits in online replenishment platforms for suburban United States family households. Go-to-market angle should emphasize personalized portion sizing with flavor rotation capabilities. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision fermentation convergence plays, favoring early-stage positioning before scale economics crystallize. Long-term viability over the coming decade hinges on clean-label reformulation talent acquisition and dual-certification timeline compression. Acquisition target archetype: specialized dairy processors with EFSA-approved enzymatic capabilities and existing direct-to-consumer infrastructure. Signal to watch: streamlined novel enzyme approval timelines accelerating cross-border EU market access.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Modification R&D Partnership | Microbial lipase systems from Danish and Dutch biotechnology suppliers compress texture-melt performance gaps for food service contracts. |
| Direct-to-Consumer Subscription Launch | United States coastal metro platforms bypass Kraft Heinz slotting fee structures while capturing recurring athlete and family revenue. |
| FOSHU Functionality Claims Investment | Japan's cholesterol-reduction positioning enables premium pricing for cream cheese variants in Tokyo direct-to-home channels. |
| Backward Integration into Milk Sourcing | Quebec and Bavaria dairy cooperatives control skimming-dependent cost structures against butterfat input volatility. |
| Dual Certification Timeline Compression | Simultaneous FDA GRAS and EFSA novel food preparation reduces 18-24 month market entry delays for cross-border exporters. |
Research Methodology
Initial hypotheses were tested against primary input from dairy protein chemists, food service procurement directors, sports dietitians, and clean-label retail buyers and refined through secondary validation. Bottom-up demand modeling drew from FDA labeling databases, EFSA novel food submission records, and Nielsen retail audit data covering United States supermarket dairy aisles. Top-down supply assessment incorporated customs trade flows and SEC filings from integrated dairy conglomerates. Triangulation across these sources anchored volume and value estimates.
Variance decomposition across the projection horizon isolates drivers by product type, application use case, distribution channel, and customer nutrition literacy segment. CAGRs were derived from segment-level growth rate reconciliation against macro dairy consumption trends. Industry-specific forecast inputs included seasonal milk composition data affecting cream separation yields and EFSA enzyme approval velocity indices.
Forecasts assume regulatory continuity in FDA labeling thresholds and EFSA novel food frameworks; material policy shifts would require re-modeling. Specific risks include accelerated clean-label mandate tightening, precision fermentation regulatory reclassification, and butterfat input cost spikes. Recalibration cycles align with material shifts in enzyme approval timelines and subscription channel penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
North America Fluid Milk Market
Dairy Products
Butter Powder Market
Dairy Products
Mexico Whey Protein Market
Dairy Products
Dairy Foods Market
Dairy Products
US Yogurt and Probiotic Drink Market
Dairy Products
Hydrolyzed Casein Market
Dairy Products
Russia Whey Protein Market
Dairy Products
Cream and Soft Cheese Market
Dairy Products
Low Fat Yogurt Market
Dairy Products
Processed Cheese Market
Dairy Products
Fat-Rich Dairy Products Market
Dairy Products
Canada Milk Protein Market
Dairy Products
Emmental Cheese Market
Dairy Products
Camel Dairy Market
Dairy Products
United States Casein and Caseinate Market
Dairy Products
North America Anhydrous Milk Fat Market