
 Saudi Arabia Dairy Products Market | 2026-2036
Saudi Arabia Dairy Products Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Dairy Products Market Analytics
Expatriate dairy technologist availability is reorganizing production capacity expansion timelines across the Kingdom. Almarai Company leverages its integrated farming and processing infrastructure to dominate fresh milk distribution. Al Safi Danone anchors the yogurt segment through specialized fermentation expertise and brand recognition. NADEC competes on cost-efficient supply chains tied to its agricultural land holdings.
Saudi Arabia dairy products encompass fluid milk, fermented goods, and fat-based derivatives requiring controlled-temperature processing, standardized fat content, and hygienic packaging to preserve nutritional integrity and extend shelf life. Milk and yogurt command the largest volume share given per capita consumption habits and daily dietary integration. Cheese is expanding fastest among product types as Western-style dining and pizza chains multiply across urban centers. The food service end-user segment concentrates margin pools through bulk procurement contracts and specialized product specifications.
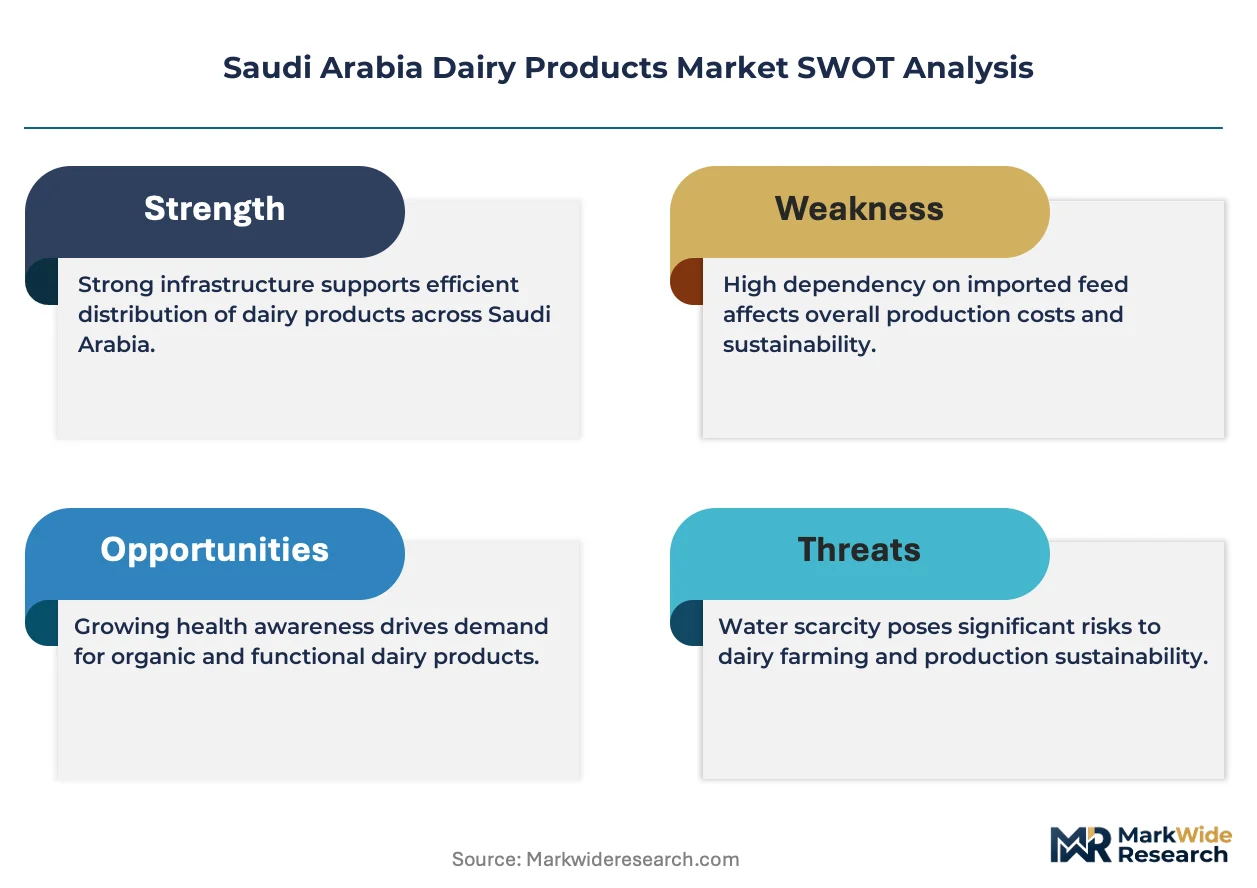
SFDA enforces food safety protocols and nutritional labeling standards that processors must satisfy for market authorization. SASO mandates packaging material specifications and shelf-life declarations that directly influence product formulation decisions. Halal certification requirements administered by domestic religious authorities shape ingredient sourcing and cross-border trade eligibility. Stakeholders must monitor water tariff reforms and feed import policies that threaten input cost stability for domestic producers.
Market Dynamics
SFDA's updated labeling mandates and water tariff reforms are compressing processor margins while accelerating consolidation among domestic dairy operators unable to absorb compliance and input cost shocks.
Growth Catalysts
- Urban purchasing power concentration:Riyadh and Jeddah metropolitan corridors absorb disproportionate volume as domestic migration patterns concentrate affluent households in these cities.
- Food service channel expansion:Hotel and restaurant chains across the Kingdom are expanding procurement of premium dairy lines through specialized bulk contracts.
- Halal certification standardization:Domestic religious authorities are streamlining cross-border trade eligibility requirements, reducing friction for export-oriented processors.
Market Restraints
- Feed import dependency:Alfalfa and soybean meal price volatility tied to international commodity markets destabilizes raw milk production economics for domestic farms.
- Water tariff escalation:Ministry of Environment, Water and Agriculture reforms are raising irrigation costs for fodder cultivation, squeezing integrated operators.
- Expatriate technologist scarcity:Visa restrictions and competitive regional recruitment are delaying fermentation specialist placement at yogurt and cheese facilities.
Strategic Opportunities
- Eastern Province underpenetration:Dammam and Khobar retail and food service channels remain underserved relative to Riyadh-Jeddah corridor concentration.
- Extended shelf-life UHT innovation:Aseptic packaging convergence with ambient distribution infrastructure opens rural and remote settlement access.
- SASO packaging material mandates:New biodegradable and recyclability standards create first-mover advantage for compliant domestic suppliers.
Industry Challenges
- Fermentation specialist recruitment:Industrial microbiology and culture management expertise shortages are extending product development timelines for probiotic and specialized cheese lines.
- Cold chain capex intensity:Controlled-temperature logistics infrastructure requirements for fresh milk distribution demand substantial capital deployment with extended payback periods.
- SFDA compliance timeline compression:Accelerated nutritional labeling and safety audit schedules are forcing reformulation and packaging redesign cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Dairy Products Market |
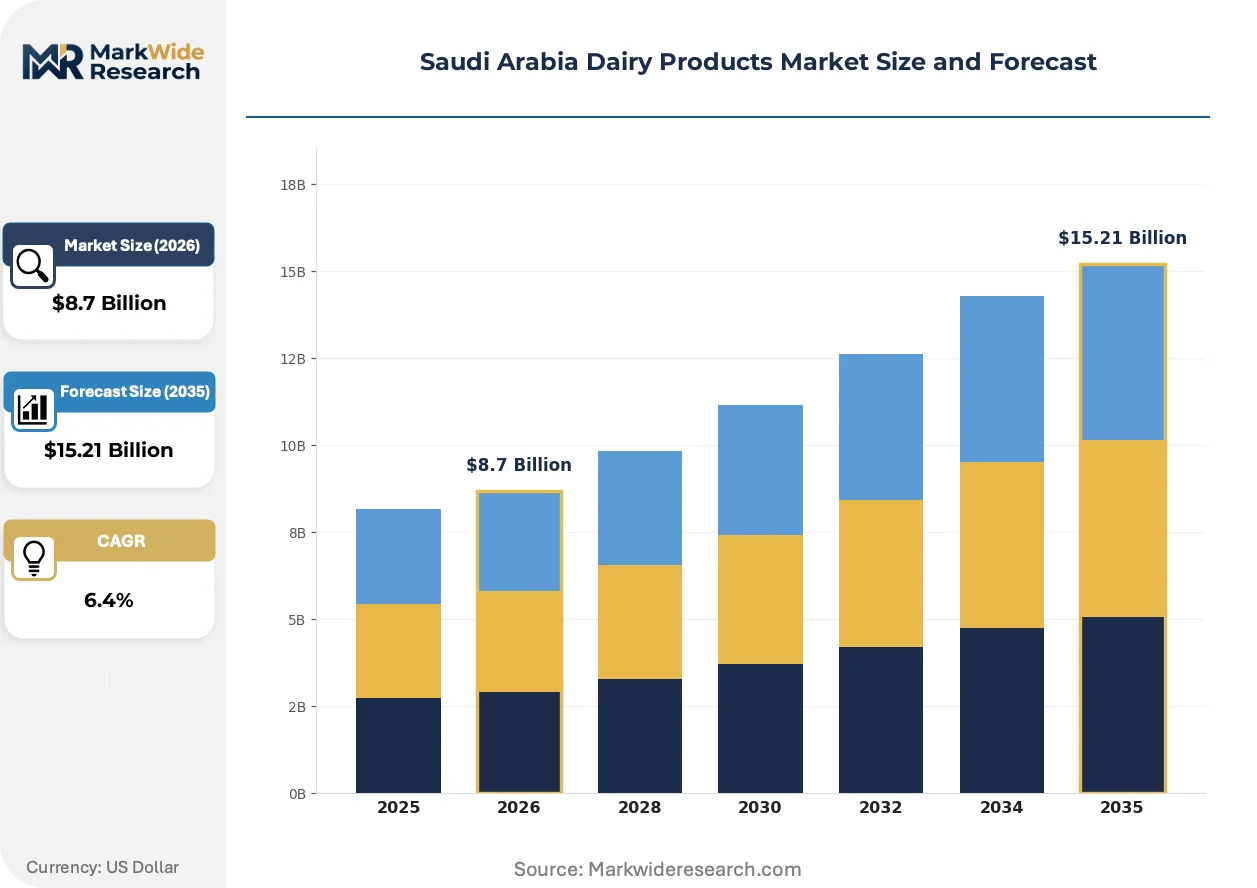
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Yogurt, Butter Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Service End User: Households, Restaurants, Cafés, Catering Services Packaging Type: Cartons, Bottles, Tubs, Sachets |
| Companies Covered | Al Safi Danone, Nestle, Almarai Company, Al Rashed Food Company, AlRawabi Dairy Company, Saudia Dairy and Foodstuff Company (SADAFCO), Arla Foods, Nesma Holding, National Agricultural Development Company (NADEC), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Dairy Products Market Evolving Landscape
Processing technology and distribution infrastructure are diverging toward premium fresh segments versus shelf-stable mass-market lines, with regulatory pressure and consumption geography determining investment allocation.
Aseptic UHT processing paired with multilayer carton packaging is bifurcating the fluid milk category into ambient-distributed economy tiers and cold-chain-dependent premium fresh segments. Rural retail and institutional buyers are adopting ambient lines for inventory flexibility. This technology split is compressing margin pools in the mid-market while concentrating profitability at extremes.
SFDA's nutritional labeling and safety standard updates are forcing reformulation investments across yogurt and cheese portfolios. Processors are removing artificial additives and standardizing fat content declarations to satisfy audit protocols. Fresh milk and fermented goods segments face the steepest compliance cost absorption.
Food service procurement consolidation is displacing traditional wholesale distribution in urban centers. Hotel chains and restaurant groups are negotiating direct supply agreements with processors for specialized fat specifications and private-label dairy derivatives. Riyadh and Jeddah hospitality clusters exhibit the most advanced procurement centralization.
Saudi Arabia Dairy Products Market Segmentation
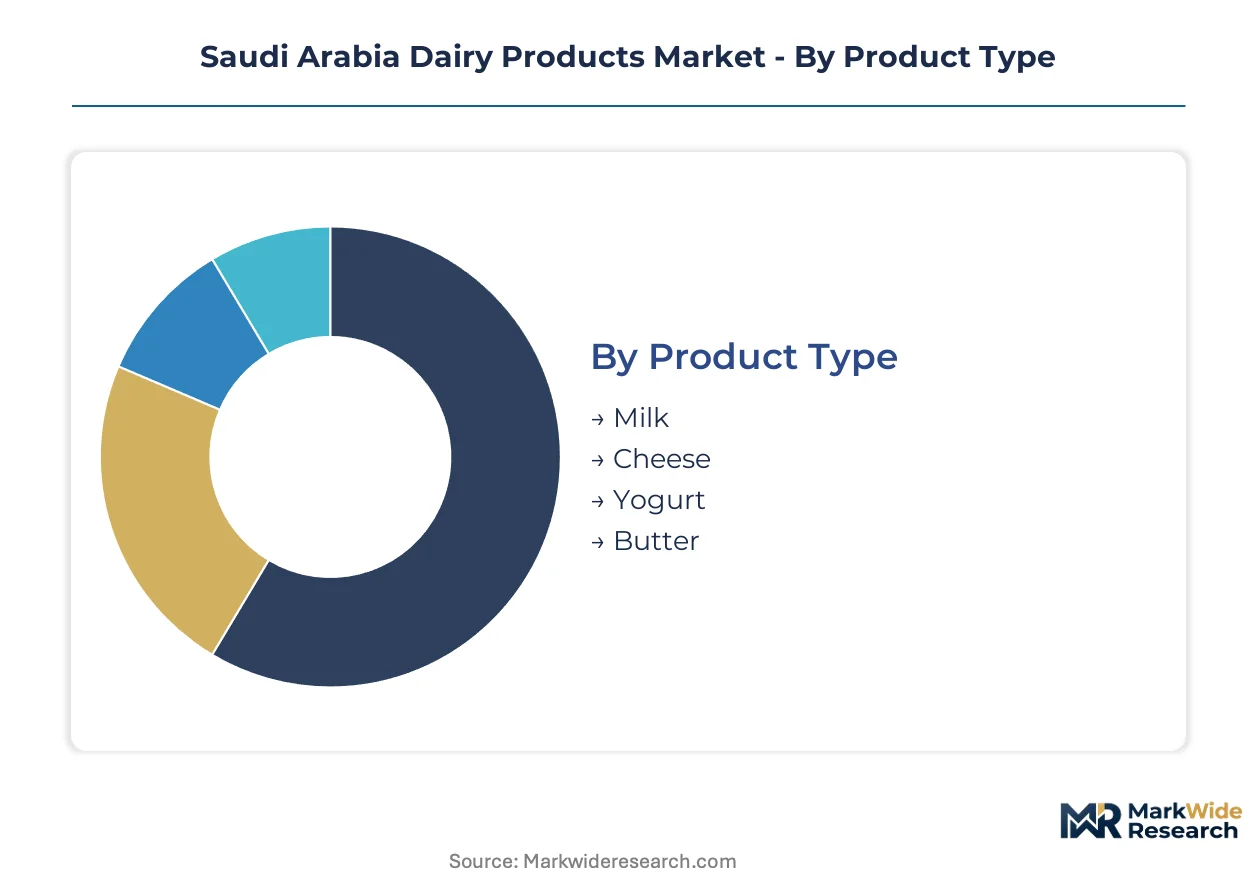
Segmentation reveals how Saudi Arabia's dairy market stratifies across temperature-dependent supply chains and consumption occasions. Each dimension exposes distinct margin structures and regulatory exposure profiles that processors must navigate.
Product Type:
Domestic production dominates fluid milk and yogurt, while cheese draws heavier import dependency and specialized fermentation expertise concentrated in Riyadh-Jeddah processing clusters.
- Milk:Fluid milk requires controlled-temperature processing from farm gate through retail shelf. Riyadh and Jeddah metropolitan corridors absorb disproportionate fresh milk volumes as urban migration concentrates affluent households with daily consumption habits. Cold chain capex intensity and SFDA safety audit schedules compress margins for mid-tier processors.
- Cheese:Western-style dining proliferation across urban centers drives demand for mozzarella, cheddar, and processed cheese variants. Pizza chains and hotel restaurants in Riyadh hospitality clusters negotiate direct supply agreements for specialized fat specifications, displacing traditional wholesale distribution.
- Yogurt:Fermented goods with standardized fat content declarations face steep SFDA reformulation costs; domestic religious authorities administer Halal certification requirements shaping ingredient sourcing.
- Butter:Fat-based derivatives serve institutional baking and food manufacturing; ambient stability permits broader rural distribution beyond cold-chain constraints.
Milk holds the largest share; momentum sits with cheese as food service procurement centralization accelerates.
Distribution Channel:
Channel economics diverge sharply between temperature-controlled fresh networks and ambient-stable mass-market infrastructure, with regulatory pressure determining investment allocation.
- Supermarkets:Controlled-temperature retail infrastructure in Riyadh and Jeddah anchors fresh milk and yogurt volume, with SASO packaging mandates forcing biodegradable material transitions.
- Convenience Stores:Neighborhood outlets prioritize ambient UHT lines for inventory flexibility; Eastern Province Dammam-Khobar corridor remains underserved relative to western metropolitan concentration.
- Online Retail:E-commerce platforms demand extended shelf-life packaging compatible with last-mile delivery timelines; cold chain reliability gaps constrain fresh segment penetration.
- Food Service:Hotel chains and restaurant groups negotiate bulk procurement contracts with specialized product specifications, concentrating margin pools in Riyadh and Jeddah hospitality clusters.
Supermarkets command the greatest volume throughput; food service channels are expanding most quickly as procurement centralization displaces wholesale intermediaries.
End User:
User categories split between daily household consumption patterns and institutional procurement cycles with divergent price sensitivity and specification complexity.
- Households:Daily dietary integration of milk and yogurt drives per capita consumption; urban purchasing power concentration in Riyadh and Jeddah shapes premium product uptake.
- Restaurants:Western-style dining multiplication generates specialized cheese and cream demand; direct processor relationships bypass traditional distribution.
- Cafés:Coffee culture expansion creates steady fresh milk demand with precise fat content requirements for foam stability.
- Catering Services:Institutional buyers adopt ambient UHT lines for inventory flexibility across remote settlement access points.
Households absorb the greatest volume; restaurants are gaining share fastest as dining-out frequency rises in metropolitan corridors.
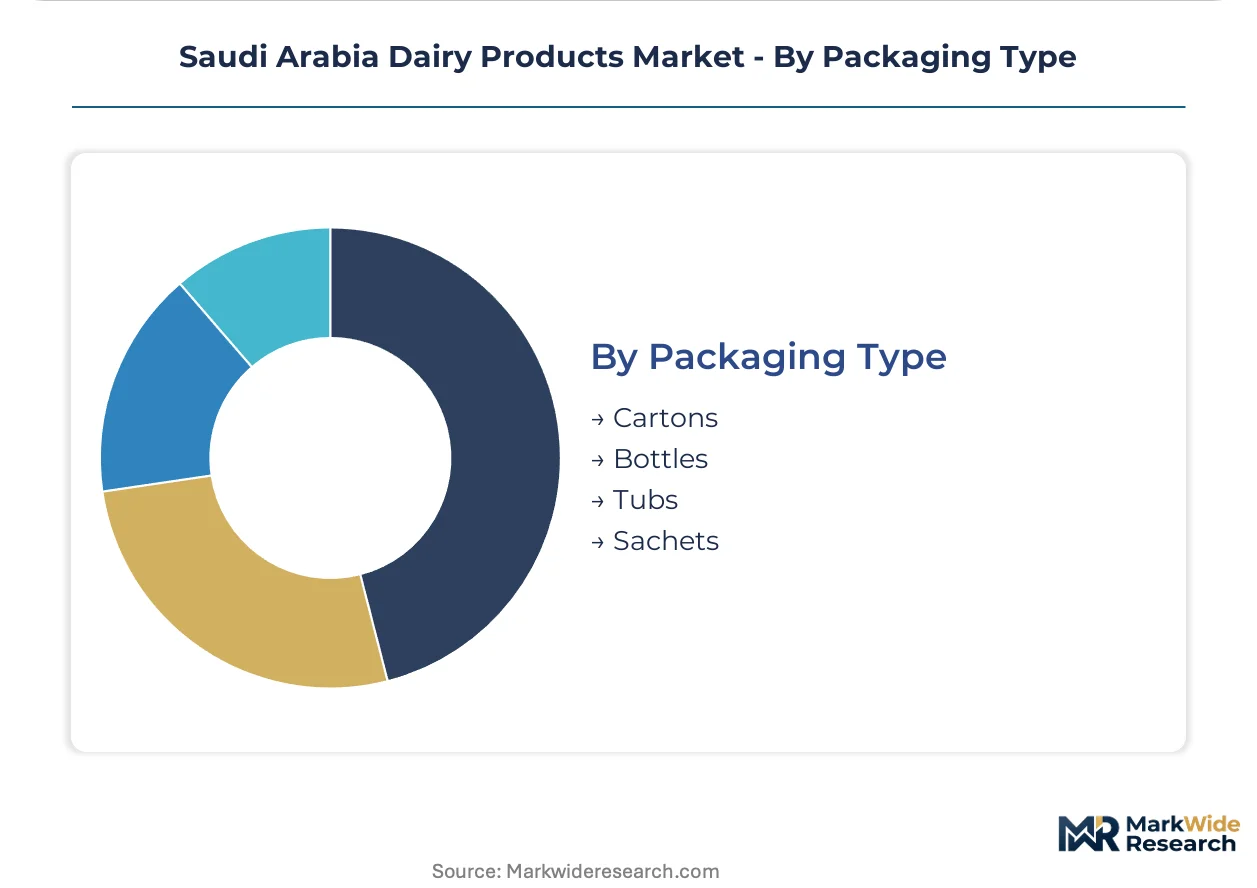
Packaging Type:
Material specifications directly influence product formulation decisions and shelf-life declarations under SASO mandates, with sustainability transitions creating compliance differentiation.
- Cartons:Multilayer aseptic cartons enable ambient distribution infrastructure for rural access; SASO recyclability standards create first-mover advantage for compliant domestic suppliers.
- Bottles:Polyethylene terephthalate and HDPE formats dominate fresh milk retail; water tariff reforms raise irrigation costs for fodder cultivation, squeezing integrated operators' packaging material choices.
- Tubs:Polypropylene containers serve yogurt and cheese spreads; SFDA nutritional labeling mandates force redesign cycles.
- Sachets:Flexible pouches target price-sensitive mass-market segments with reduced material costs; limited barrier properties constrain shelf-life extension.
Cartons lead in ambient-stable applications; bottles retain dominance in fresh segments despite sustainability pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh and Jeddah metropolitan corridors absorb disproportionate fresh milk and yogurt volumes through cold-chain retail infrastructure, while the Eastern Province and rural settlements rely more heavily on ambient UHT lines for distribution flexibility.
Riyadh
Affluent household concentration drives premium fresh milk and specialized cheese demand through supermarket and food service channels. SFDA nutritional labeling mandates force reformulation investments across yogurt portfolios in this corridor. Hotel chains and restaurant groups in Riyadh hospitality clusters negotiate direct supply agreements, displacing traditional wholesale intermediaries.
Jeddah
Western-style dining multiplication generates mozzarella and processed cheese demand from pizza chains and hospitality operators. SASO packaging material specifications mandate biodegradable transitions for retail-facing products. Jeddah's retail infrastructure anchors controlled-temperature fresh milk distribution with extended cold-chain capex deployment.
Eastern Province
Dammam and Khobar retail and food service channels remain underserved relative to western metropolitan concentration, creating distribution gaps for fresh segments. Water tariff reforms under Ministry of Environment, Water and Agriculture raise irrigation costs for fodder cultivation, squeezing integrated operators. Ambient UHT lines dominate institutional procurement across remote settlement access points.
Western Region
Makkah and Madinah pilgrimage traffic creates seasonal demand spikes for ambient-stable dairy derivatives with extended shelf-life requirements. Halal certification standardization by domestic religious authorities streamlines cross-border trade eligibility for export-oriented processors. Convenience store networks in secondary cities prioritize inventory-flexible UHT cartons over cold-chain-dependent fresh formats.
Saudi Arabia Dairy Products Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with backward integration into agricultural land holdings and captive dairy farming distinguishing the upper tier from packaging-dependent assemblers. The structure concentrates fresh milk and yogurt volume among operators with controlled-temperature infrastructure, while cheese and ambient lines attract specialized fermentation and aseptic processing entrants. Strategic archetypes include integrated farm-to-shelf operators, fermentation-focused specialists, and regional wholesale distributors. Competitive moves center on direct food service procurement relationships and compliance-first packaging transitions under SASO mandates.
Within the integrated tier, Almarai Company and NADEC exemplify farm-holding-backed scale positions, while Al Safi Danone occupies a specialized fermentation expertise niche. These three anchors represent distinct competitive vectors: captive agricultural supply, cost-efficient land-based supply chains, and branded yogurt culture management respectively.
| Leading Market Players |
|---|
| Al Safi Danone |
| Nestle |
| Almarai Company |
| Al Rashed Food Company |
| AlRawabi Dairy Company |
| Saudia Dairy and Foodstuff Company (SADAFCO) |
| Arla Foods |
| Nesma Holding |
| National Agricultural Development Company (NADEC) |
| Others |
Value Network & Pricing Analysis
Feed substitution from domestic fodder cultivation to imported alfalfa and soybean meal simultaneously redraws procurement geography toward Black Sea and South American supply basins and compresses raw milk production economics across Saudi integrated operators. This input-cost migration feeds directly into processor margin structures, with water tariff reforms under the Ministry of Environment, Water and Agriculture amplifying cost pressure on backward-integrated farm holdings.
Pricing Analysis
Long-term offtake contracts between hotel chains and major processors anchor pricing for premium fresh milk and specialized cheese specifications, while spot-market transactions govern ambient UHT bulk sales to institutional buyers. Three-tier pricing structure across premium, standard, and economy levels differentiates cold-chain-dependent fresh segments from shelf-stable mass-market lines, with Halal certification tier and volume scale as primary price drivers. Pricing pressure stems from SFDA compliance cost absorption and feed import volatility, with economy-tier ambient products exhibiting highest price sensitivity and food service premium contracts showing least elasticity.
Supply Chain Analysis
Port congestion at Jeddah Islamic Port and container availability constraints on Asia-Middle East trade lanes elevate inbound logistics costs for packaging materials and specialized fermentation equipment. Supply concentration rests on domestic integrated operators with captive agricultural land, plus Danish and French dairy technology suppliers for culture management systems. Raw material dependencies span imported alfalfa from Argentina, soybean meal from Brazil, and multilayer carton substrates from European converters. Single-source vulnerability in fermentation specialist recruitment extends product development timelines. Distribution runs through controlled-temperature logistics for fresh segments and ambient wholesale networks for rural institutional access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's dairy market constitutes a high-growth disruption as SFDA regulatory compression and water tariff reforms force simultaneous compliance investment and supply chain restructuring across domestic processors.
For Market Incumbents: Shield margin pools by deepening backward integration into fodder cultivation despite water tariff headwinds, and accelerate SASO-compliant biodegradable packaging transitions ahead of mandate deadlines. Almarai-style integrated farm infrastructure offers defensive moat against feed import volatility, while fermentation specialist retention programs counter visa-restriction-driven talent scarcity threatening yogurt and cheese innovation pipelines.
For New Entrants and Emerging Players: Food service procurement centralization gaps in Eastern Province Dammam-Khobar corridors offer white-space entry point for specialized cheese and cream suppliers willing to bypass traditional wholesale distribution. Direct supply relationships with underserviced hotel chains and restaurant groups, coupled with aseptic UHT innovation for rural institutional penetration, provide viable go-to-market path without confronting Riyadh-Jeddah incumbent strongholds.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier processors with compliant packaging infrastructure and established food service relationships rather than greenfield farm investments facing water cost escalation. Long-term viability across the analysis window hinges on regulatory compliance capability and cold-chain asset ownership. Monitor SFDA audit timeline compression and water tariff reform implementation velocity as inflection indicators for sector consolidation pace.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fodder Cultivation | Captive alfalfa supply insulates processors from Black Sea commodity volatility and currency fluctuation. |
| SASO-Compliant Packaging Transition | Biodegradable material first-mover advantage secures retail shelf access ahead of mandate enforcement. |
| Fermentation Specialist Recruitment Programs | Industrial microbiology talent pipelines accelerate probiotic and specialized cheese development timelines. |
| Direct Food Service Supply Agreements | Bypassing wholesale intermediaries captures margin pools concentrated in Riyadh-Jeddah hospitality clusters. |
| Aseptic UHT Infrastructure Expansion | Ambient distribution capability opens Eastern Province and rural settlement penetration without cold-chain capex. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with dairy processing executives, SFDA regulatory affairs specialists, hotel procurement managers, and cold-chain logistics operators; and secondary validation through SFDA labeling guidelines, SASO packaging standards, Ministry of Environment water tariff disclosures, and customs import records for feed commodities. Bottom-up volume triangulation across product type, distribution channel, and regional consumption patterns converged with top-down value estimates derived from processor capacity disclosures and food service contract structures.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning temperature-dependent supply chains, Halal certification tiers, and urban-rural consumption geography. CAGRs were derived from trend extrapolation of per capita consumption patterns, urbanization-driven purchasing power concentration, and food service channel expansion rates. Industry-specific forecast inputs incorporated water tariff reform implementation schedules and SFDA compliance timeline compression effects on processor economics.
Underlying assumptions cover continued urbanization concentration in Riyadh-Jeddah corridors, stable feed import availability from South American and Black Sea origins, and phased SFDA enforcement without abrupt regulatory disruption, with deviation risk concentrated in water tariff escalation velocity and fermentation specialist visa policy shifts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Global Yogurt Powder Market
Dairy Products
Evaporated Filled Milk Market
Dairy Products
Lactose-Free Cheese Market
Dairy Products
Colombia Dairy Market
Dairy Products
Fermented Dairy Products Market
Dairy Products
Asia-Pacific Milk Protein Market
Dairy Products
Dairy Carton Market
Dairy Products
US and Europe Nuts and Seeds Cheese Market
Dairy Products
Germany Dairy Market
Dairy Products
Skimmed Milk Powder Market
Dairy Products
Goat Milk Products Market
Dairy Products
Goat Milk Powder Market
Dairy Products
Dairy Based Dressings Market
Dairy Products
North America Anhydrous Milk Fat Market
Dairy Products
Europe Dairy Market
Dairy Products
Japan Dairy Market