
 China Plant Protein Market | 2026-2036
China Plant Protein Market Size, Share, and Industry Trends Forecast 2026-2036
China Plant Protein Market Outlook
Precision fermentation and enzymatic extraction is fragmenting traditional protein processing into modular, cell-free platforms that bypass conventional crop-to-isolate supply chains. Yantai Shuangta Food Co Ltd anchors domestic pea protein capacity with backward integration into raw material sourcing across Shandong province. Archer Daniels Midland Company leverages its global oilseed processing network to sustain isolate purity grades for Chinese beverage manufacturers. Roquette Frères competes through specialized extrusion technology that controls texturization parameters for meat alternative applications.
China plant protein encompasses concentrated or isolated protein fractions extracted from legumes, cereals, or oilseeds through mechanical separation, aqueous extraction, or enzymatic hydrolysis, typically achieving protein content ranging from fifty percent in concentrates to over ninety percent in isolates. These ingredients function primarily as functional binders, emulsifiers, and nutritional fortifiers in formulated foods designed to replace or extend animal-derived proteins. Protein isolate commands premium positioning due to superior solubility and minimal flavor carryover in neutral-pH beverages. Textured protein occupies the fastest-expanding application niche as domestic meat alternative brands scale extrusion capacity. Soy retains volume leadership across all source categories while pea protein captures disproportionate growth in nutritional supplements targeting lactose-intolerant consumers.
SAMR enforces GB standards for plant-based food labeling and protein content claims, compelling manufacturers to verify amino acid profiles through third-party certification. The dual carbon goals framework from MEE channels industrial policy toward lower-energy extraction technologies, reshaping capital allocation for new processing facilities. BIS-equivalent provincial quality bureaus in Shandong and Jiangsu conduct randomized inspections of isolate heavy metal thresholds. Stakeholders must monitor whether enzymatic processing patents or carbon intensity benchmarks become the decisive gate for facility licensing in major producing provinces.
Market Dynamics
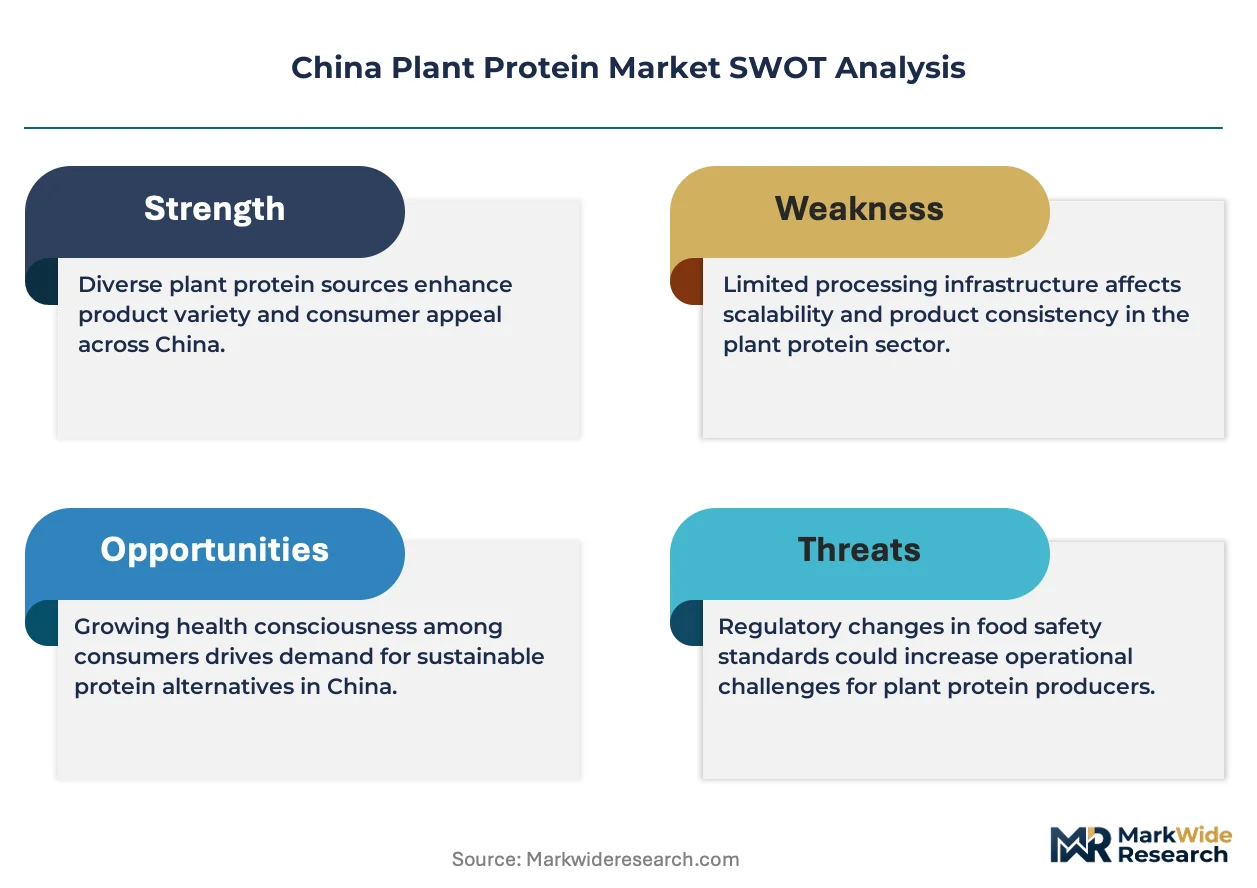
Precision fermentation platforms are fragmenting conventional protein extraction economics by bypassing crop cultivation entirely, forcing traditional processors to defend isolate purity premiums against cell-free alternatives that slash capital intensity and energy input requirements.
Growth Catalysts
- Dual carbon goals framework:MEE channels industrial policy toward lower-energy enzymatic extraction technologies, accelerating facility upgrades in Shandong and Jiangsu provinces.
- Sports nutrition vertical:Domestic brands now formulate with pea and soy isolates at commercial scale, pulling demand from whey protein alternatives for lactose-intolerant athletes.
- Shanghai-Guangdong corridor:Food tech clusters attract formulation startups concentrating R&D investment and pilot-scale extrusion capacity in coastal provinces.
Market Restraints
- Input cost volatility:Yellow pea import dependency exposes processors to Black Sea supply disruptions and currency fluctuation against contracted protein content specifications.
- Supply concentration risk:Domestic isolate capacity clusters in Shandong province, creating single-point vulnerability for beverage manufacturers requiring consistent solubility grades.
- Technical limitation:Enzymatic hydrolysis struggles to achieve neutral flavor profiles in oat and rice proteins, constraining application expansion beyond niche nutritional bars.
Strategic Opportunities
- Underpenetrated western provinces:Sichuan and Shaanxi present whitespace for regional extrusion facilities serving meat alternative brands with localized texturization parameters.
- Regulatory tailwind:SAMR's tightened GB standards for plant-based labeling create first-mover advantage for manufacturers with third-party amino acid certification already in place.
- Technology convergence:Precision fermentation paired with AI-driven strain optimization promises cell-free protein production without agricultural land use or seasonal input constraints.
Industry Challenges
- Enzymatic process engineering talent:Shortage of specialists capable of scaling cell-free platforms from pilot to industrial throughput limits facility licensing timelines.
- GB standard compliance timeline:Third-party verification of heavy metal thresholds and amino acid profiles extends product launch cycles by six to twelve months.
- Extrusion equipment integration:Legacy spray-dry infrastructure requires substantial modification to accommodate high-moisture texturization for meat alternative applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Plant Protein Market |
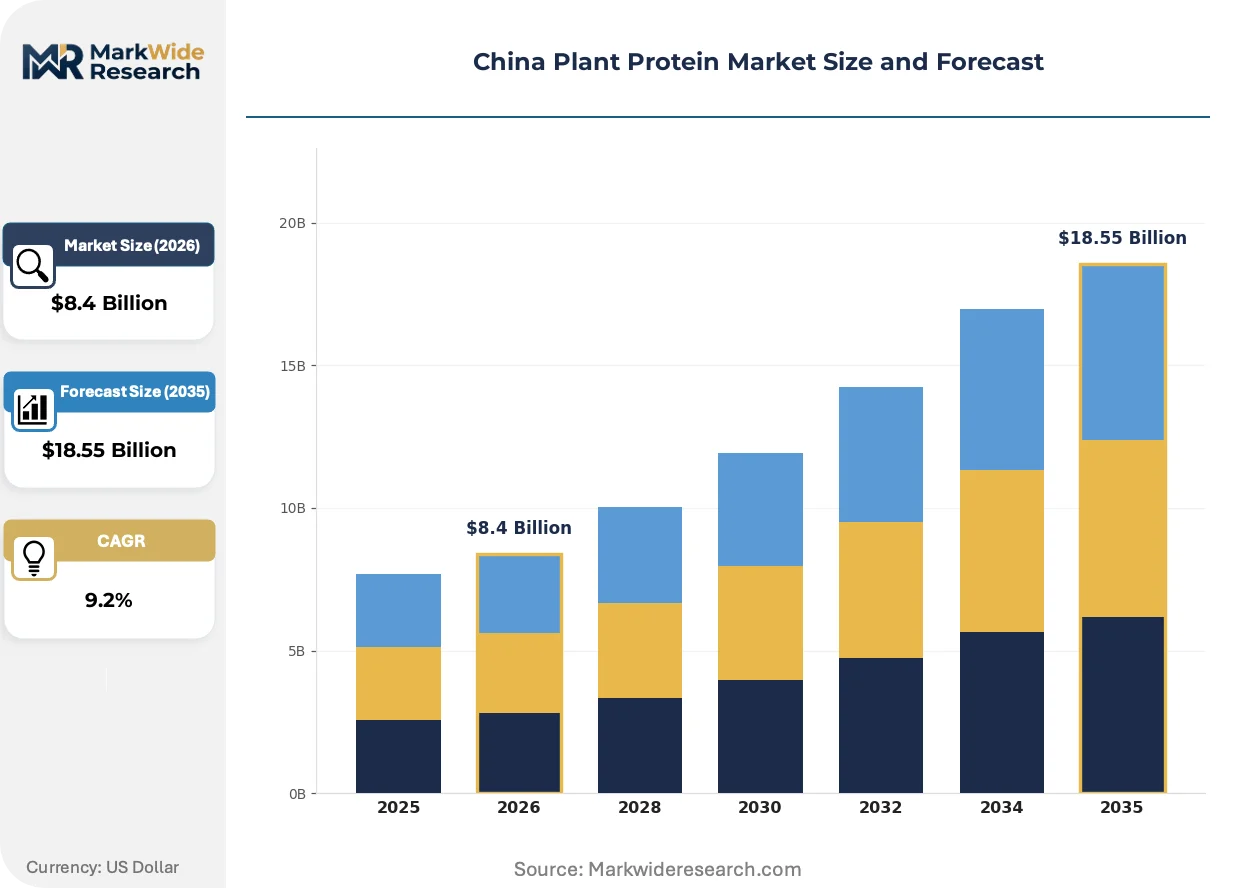
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $18.55 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textured Protein, Protein Isolate, Protein Concentrate, Flour Application: Food & Beverage, Nutritional Supplements, Animal Feed, Meat Alternatives Source: Soy, Pea, Rice, Hemp End User: Food Manufacturers, Dietary Supplements, Fitness Enthusiasts, Vegans |
| Companies Covered | Yantai Shuangta Food Co Ltd, Foodchem International Corporation, Shandong Jianyuan Bioengineering Co Ltd, Archer Daniels Midland Company, Wilmar International Ltd, Shandong Yuwang Industrial Co Ltd, Wuxi Jinnong Biotechnology Co Ltd, Roquette Frères, Shandong Qufeng Food Technology Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Plant Protein Market Strategic Shifts
Active restructuring of extraction economics is compressing traditional crop-to-isolate supply chains while regulatory disclosure mandates and procurement model evolution reshape competitive positioning across formulation tiers.
Enzymatic extraction technology is hybridizing mechanical separation with cell-free biocatalysis to produce isolate fractions without conventional aqueous processing. Beverage manufacturers in Guangdong province are piloting these platforms at pilot scale. The technology is hybridizing capital allocation decisions by enabling modular facility deployment that bypasses backward integration into agricultural sourcing.
GB standards for plant-based food labeling now mandate verified amino acid profiles and heavy metal thresholds through third-party certification. SAMR enforcement compels reformulation of legacy products carrying protein content claims. Textured protein applications face the steepest compliance burden as meat alternative brands scramble to retrofit supply chains before inspection cycles intensify.
Ingredient sourcing patterns now favor direct contracting with provincial quality bureaus rather than spot market procurement. Nutritional supplement brands in Shanghai are consolidating supplier panels to three certified isolators per protein source. This concentration is most visible in pea protein procurement, where beverage manufacturers demand batch-level carbon intensity documentation aligned with MEE dual carbon benchmarking.
China Plant Protein Market Segmentation
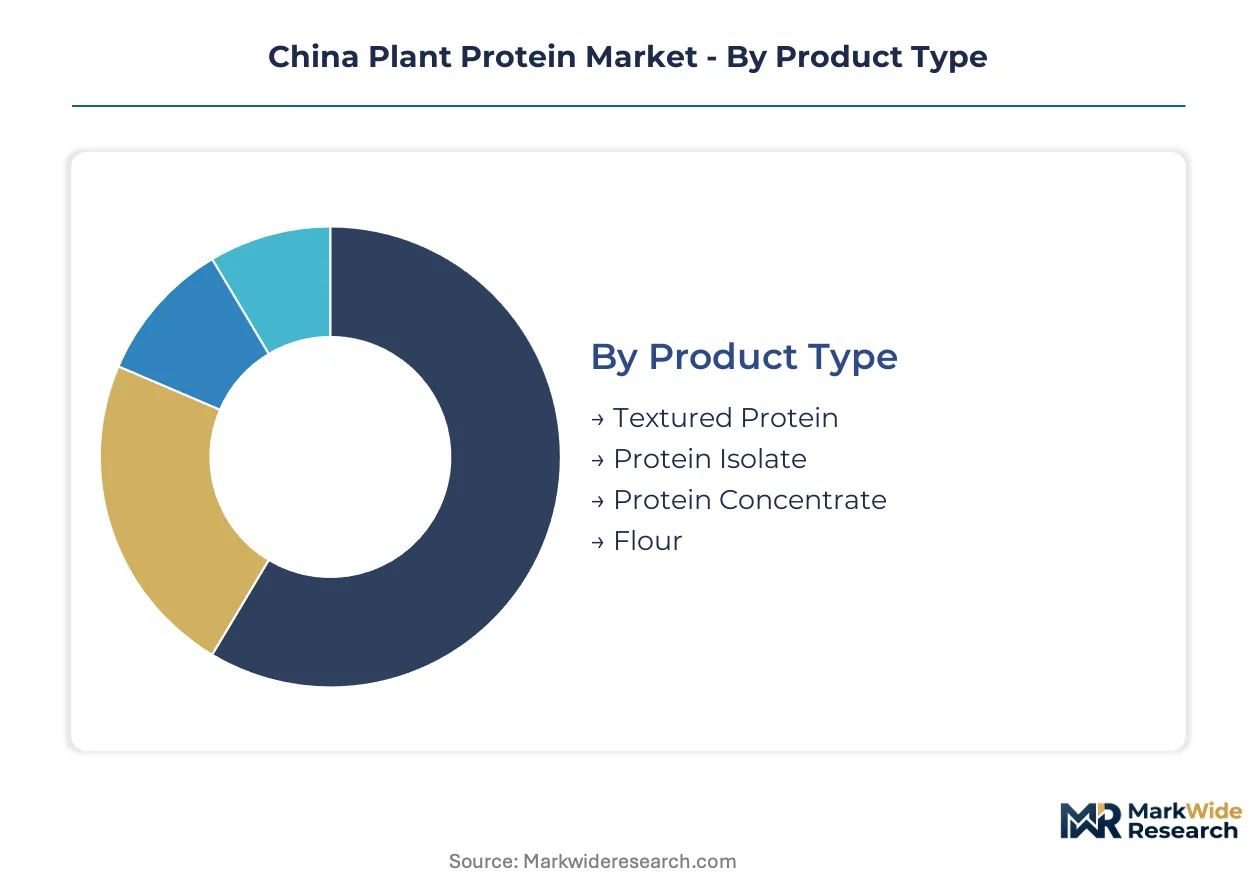
Plant protein segmentation in China reflects divergent technical requirements across extraction grades and end-use specifications. SAMR's GB labeling mandates force manufacturers to align product portfolios with verified amino acid profiles and heavy metal thresholds.
Product Type:
After-sales technical support intensity escalates with protein purity tiers as beverage manufacturers demand batch-to-batch solubility consistency and extrusion parameter calibration.
- Protein Isolate:Exceeds ninety percent protein content through aqueous or enzymatic extraction with minimal flavor carryover. Shanghai beverage manufacturers specify this grade for neutral-pH applications requiring transparent solubility.
- Textured Protein:High-moisture extrusion creates fibrous matrices mimicking meat muscle structure. Meat alternative brands in Guangdong province scale dedicated extrusion lines to control bite resistance and water-holding capacity.
- Protein Concentrate:Fifty to eighty percent protein content retains more fiber and lipid fractions than isolates. Animal feed compounders in Shandong province absorb volume shipments for cost-efficient nutritional fortification.
- Flour:Ground whole legume or cereal powders with protein content below fifty percent. Regional bakeries in Sichuan province incorporate these fractions for partial wheat replacement in traditional formulations.
Protein isolate holds the largest share; momentum sits with textured protein.
Application:
Cost tier stratification separates premium-positioned nutritional formulations from commodity feed applications with divergent certification burdens and margin structures.
- Meat Alternatives:Extruded and formed products replacing animal muscle tissue in analog applications. Domestic brands in the Shanghai-Guangdong corridor pilot next-generation fibrous structures targeting foodservice distribution.
- Nutritional Supplements:Powder and ready-to-drink formats targeting protein intake augmentation. Fitness enthusiasts in tier-one cities drive pea isolate demand for lactose-free post-workout recovery.
- Food & Beverage:Bakery, dairy alternative, and beverage formulations using protein for functional binding or nutritional enhancement. Processors navigate GB standard reformulation timelines for legacy product lines.
- Animal Feed:Cost-optimized protein supplementation for livestock and aquaculture operations. Shandong province's integrated oilseed processors channel soy concentrate into regional feed mill supply chains.
Food and beverage commands volume leadership; nutritional supplements are climbing the fastest.
Source:
Supply concentration geography dictates procurement risk profiles as import dependency for yellow pea contrasts with domestic soy crushing infrastructure.
- Soy:Dominates volume through established crushing and isolate extraction networks across Shandong and Jiangsu provinces. MEE dual carbon goals pressure processors to upgrade energy-intensive aqueous extraction facilities.
- Pea:Captures disproportionate growth in nutritional supplements as lactose-intolerant consumers reject dairy-derived alternatives. Black Sea supply disruptions expose processors to currency and protein content specification volatility.
- Rice:Hypoallergenic profile suits infant nutrition and sensitive digestive applications despite enzymatic hydrolysis challenges with neutral flavor achievement.
- Hemp:Niche positioning in premium nutritional bars leverages complete amino acid profiles and omega fatty acid co-benefits with limited scale extraction infrastructure.
Soy retains foundational volume; pea gains share fastest among alternative sources.
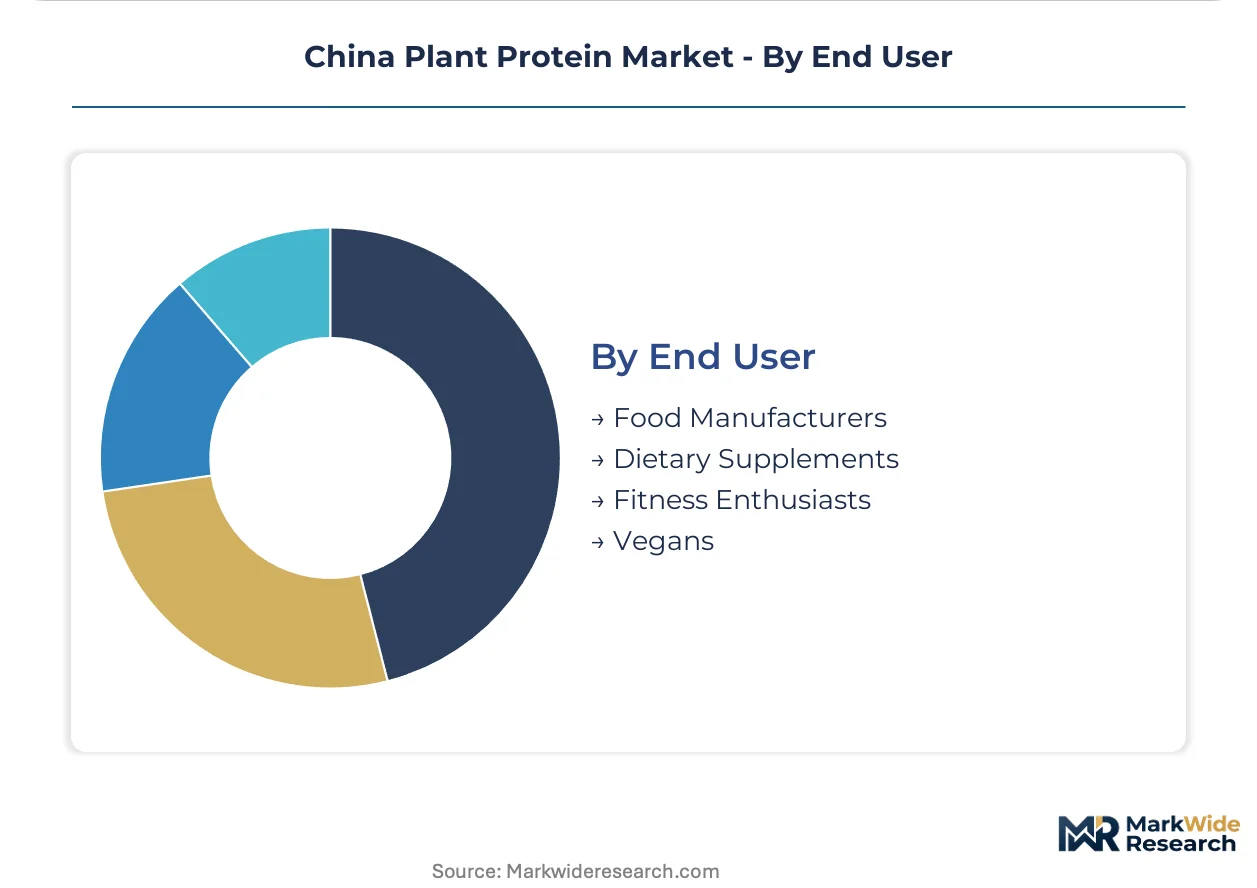
End User:
Customer type determines specification stringency as food manufacturers enforce batch certification against fitness enthusiast tolerance for variable solubility.
- Food Manufacturers:Industrial-scale formulators requiring consistent functional performance across extrusion, emulsification, and gelation applications. GB standard compliance mandates third-party amino acid verification extending procurement cycles.
- Dietary Supplements:Brands packaging isolates and concentrates for direct consumer consumption with label claims scrutiny from SAMR enforcement actions.
- Fitness Enthusiasts:Individual consumers prioritizing protein content per serving and digestibility scores over price sensitivity in tier-one urban markets.
- Vegans:Ethically motivated purchasers demanding supply chain documentation excluding animal-derived processing aids or cross-contamination risks.
Food manufacturers represent the largest demand pool; dietary supplements show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fitness enthusiasts and food manufacturers cluster in coastal provinces with advanced extrusion infrastructure. Provincial quality bureaus enforce divergent certification timelines. Industrial policy from Beijing channels capacity expansion toward lower-carbon extraction technologies.
Shandong Province
Animal feed compounders and beverage manufacturers anchor demand for soy concentrate and isolate grades. Provincial quality bureaus conduct randomized inspections of heavy metal thresholds per GB standards. Yantai-based processors maintain backward integration into raw material sourcing across the peninsula.
Jiangsu Province
Food tech startups and extrusion equipment fabricators concentrate near Nanjing and Suzhou industrial corridors. MEE dual carbon goals pressure processors to upgrade energy-intensive aqueous extraction facilities. Wuxi-based biotechnology clusters pilot enzymatic hydrolysis platforms for neutral-flavor protein fractions.
Guangdong Province
Meat alternative brands and beverage manufacturers drive textured protein demand for foodservice distribution. SAMR enforcement of tightened GB labeling mandates extends product launch cycles by six to twelve months. Shenzhen-Guangzhou corridor attracts formulation startups scaling pilot extrusion capacity.
Shanghai Municipality
Nutritional supplement brands and fitness-oriented consumers pull pea isolate demand for lactose-free recovery formulations. Third-party amino acid certification requirements concentrate supplier panels to three certified isolators per protein source. Pudong-based food tech clusters attract venture capital for precision fermentation pilots.
Sichuan Province
Regional bakeries and emerging meat alternative brands present whitespace for localized extrusion facilities. BIS-equivalent provincial quality bureaus align with national GB standards while permitting longer compliance timelines. Chengdu-based food manufacturers experiment with whole legume flour fractions for traditional formulation adaptation.
China Plant Protein Market Competitive Environment
Channel-controlling players compete with product-specialist players across extraction grade tiers. Domestic oilseed processors and global ingredient traders anchor volume positions in soy isolate. Three archetypes dominate: backward-integrated agricultural processors, technology-licensing specialists, and global trading houses with regional formulation support. Competitive moves concentrate on capacity expansion in Shandong and strategic partnerships for enzymatic extraction licensing.
Among Shandong-based processors, Yantai Shuangta Food Co Ltd and Shandong Jianyuan Bioengineering Co Ltd exemplify the backward-integrated archetype with captive raw material sourcing. Roquette Frères occupies a position representing technology-specialist competition through extrusion parameter control. These three anchors illustrate how domestic provincial concentration meets global technical expertise in procurement decisions.
| Leading Market Players |
|---|
| Yantai Shuangta Food Co Ltd |
| Foodchem International Corporation |
| Shandong Jianyuan Bioengineering Co Ltd |
| Archer Daniels Midland Company |
| Wilmar International Ltd |
| Shandong Yuwang Industrial Co Ltd |
| Wuxi Jinnong Biotechnology Co Ltd |
| Roquette Frères |
| Shandong Qufeng Food Technology Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Shandong province's crushing capacity concentration grants domestic soy processors substantial leverage over isolate pricing for beverage manufacturers in downstream provinces. The peninsula's backward-integrated processors extract premiums through captive supply chains that insulate them from Black Sea pea price volatility affecting competitors.
Pricing Analysis
Cost-plus contracts with Chicago Board of Trade indexation dominate yellow pea procurement for isolate production. Three-tier pricing structure across premium, standard, and economy levels separates certified amino acid profiles from uncertified concentrates and feed-grade fractions. Pricing pressure stems from enzymatic extraction technology licensing costs pressuring mid-tier processors. Animal feed compounders exhibit highest price sensitivity while nutritional supplement brands absorb premiums for solubility consistency.
Supply Chain Analysis
Export-control regimes on precision fermentation bioreactor technology limit cell-free platform deployment in Chinese facilities. Supply concentrates in Canada, Ukraine, and France for yellow pea raw material while domestic soy crushing anchors Shandong and Jiangsu provinces. Single-source vulnerability concentrates in Black Sea logistics corridors for pea protein imports. Distribution runs through provincial quality bureau-certified isolators rather than spot market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized enzymatic process engineers represent the scarcest capability layer, with facility licensing timelines extending twelve to eighteen months for processors lacking in-house strain optimization expertise.
For Market Incumbents: Entrench through backward integration into Shandong province raw material sourcing and third-party amino acid certification investment ahead of SAMR inspection intensification. Precision fermentation platforms threaten traditional isolate premiums; defend through extrusion technology licensing partnerships controlling texturization parameters for meat alternative brands. For New Entrants and Emerging Players: Build out regional extrusion capacity in Sichuan and Shaanxi provinces where meat alternative brands lack localized fibrous structure supply. The whitespace sits in whole legume flour fractions for traditional bakery adaptation. Go-to-market through direct contracting with Chengdu-based food manufacturers seeking GB-compliant ingredient panels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors enzymatic extraction specialists with pilot-to-industrial scale-up capability over commodity crush-and-extract operators. Long-term viability hinges on carbon intensity benchmarking alignment with MEE dual carbon goals. Watch for precision fermentation strain optimization patents achieving commercial throughput as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Extraction Licensing | Modular cell-free platforms bypass agricultural land use constraints for beverage-grade isolates. |
| Third-Party Certification Investment | SAMR GB standard compliance creates six-month first-mover advantage in product launch cycles. |
| Regional Extrusion Facility Buildout | Sichuan and Shaanxi whitespace capture serves meat alternative brands with localized texturization. |
| Backward Integration into Raw Material | Shandong province captive supply insulates processors from Black Sea import volatility. |
| Carbon Intensity Documentation Systems | MEE dual carbon benchmarking alignment secures facility licensing in major producing provinces. |
Study Parameters
A spread of perspectives from extraction plant engineers, SAMR regulatory affairs specialists, beverage formulation directors, and sports nutrition brand procurement managers converged on the working assumptions. Primary fieldwork combined with secondary validation through customs records, GB standard documentation, and MEE policy circulars anchored supply-side estimates. Bottom-up facility capacity surveys triangulated against top-down protein consumption models derived from food industry association data.
Demand-supply-balance framing across the analysis window modeled protein isolate, textured protein, concentrate, and flour segments by application tier and source crop. The analytical framework incorporated extraction technology type, certification grade, and regional production hub as segmentation dimensions. CAGRs emerged from iterative reconciliation of capacity expansion announcements, import dependency ratios, and end-use substitution elasticities. Strain optimization patent filings and enzymatic processing equipment order backlogs informed technology adoption pacing.
The forecast holds incumbent behavior within observed patterns; aggressive moves by precision fermentation specialists achieving industrial throughput would shift outcomes. Material shifts in MEE carbon intensity benchmarks or SAMR enforcement timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant Based Protein Market
Plant Based Food
Europe Tofu Market
Plant Based Food
Plant-Based Diet Market
Plant Based Food
South America Meat Substitute Market
Plant Based Food
Canada Plant Protein Market
Plant Based Food
Plant Based Eggs Market
Plant Based Food
Italy Plant Protein Market
Plant Based Food
South America Soy Beverages Market
Plant Based Food
Plant-Based Natural Flavor Market
Plant Based Food
India Plant Based Meat Alternatives Market
Plant Based Food
Plant-Based Frozen Dessert Market
Plant Based Food
Vegan Protein Blend Market
Plant Based Food
Australia Plant Protein Market
Plant Based Food
Plant Based Ice Cream Market
Plant Based Food
Europe Textured Vegetable Protein Market
Plant Based Food
Brazil Soy Beverages Market