
 Malted Milk Powder Market | 2026-2036
Malted Milk Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Malted Milk Powder Market Foresight
India is rewriting capacity dynamics in malted milk powder as domestic dairy cooperatives and ingredient processors expand spray-drying facilities to serve regional beverage and nutritional markets. Nestlé S.A. leverages its existing dairy infrastructure across South Asia to sustain bulk supply contracts with institutional buyers. Associated British Foods plc anchors European demand through its baking and beverage ingredient divisions, while Muntons plc competes on heritage malt sourcing and specialized roasting profiles for premium confectionery applications.
Malted milk powder is a spray-dried composite of malted barley, wheat flour, and milk solids, typically containing 7.5–8.5% malt extract by weight, produced through controlled germination, kilning, and vacuum evaporation before drying. The powder functions primarily as a flavor carrier, nutritional fortifier, and browning agent across commercial food production. Instant malt powder dominates household and food service channels due to solubility advantages in hot and cold beverages, while organic malt powder captures expanding margin pools as EFSA-certified clean-label requirements tighten across European bakery supply chains. Non-dairy malt powder is gaining traction among manufacturers reformulating for lactose-intolerant demographics, though it remains a niche relative to dairy-based formulations in nutritional supplements.
EFSA standards govern additive thresholds and labeling claims for malted ingredients sold into EU food and beverage channels, while India's FSSAI enforces fortification norms and dairy-adjacent product classifications that shape import and domestic production requirements. The EU Green Deal's deforestation-free supply chain mandates are pressing malted milk powder processors to document barley and wheat sourcing from certified agricultural zones. Stakeholders must monitor evolving FSSAI fortification guidelines and EU supply chain traceability enforcement to align procurement and product development decisions with compliance timelines.
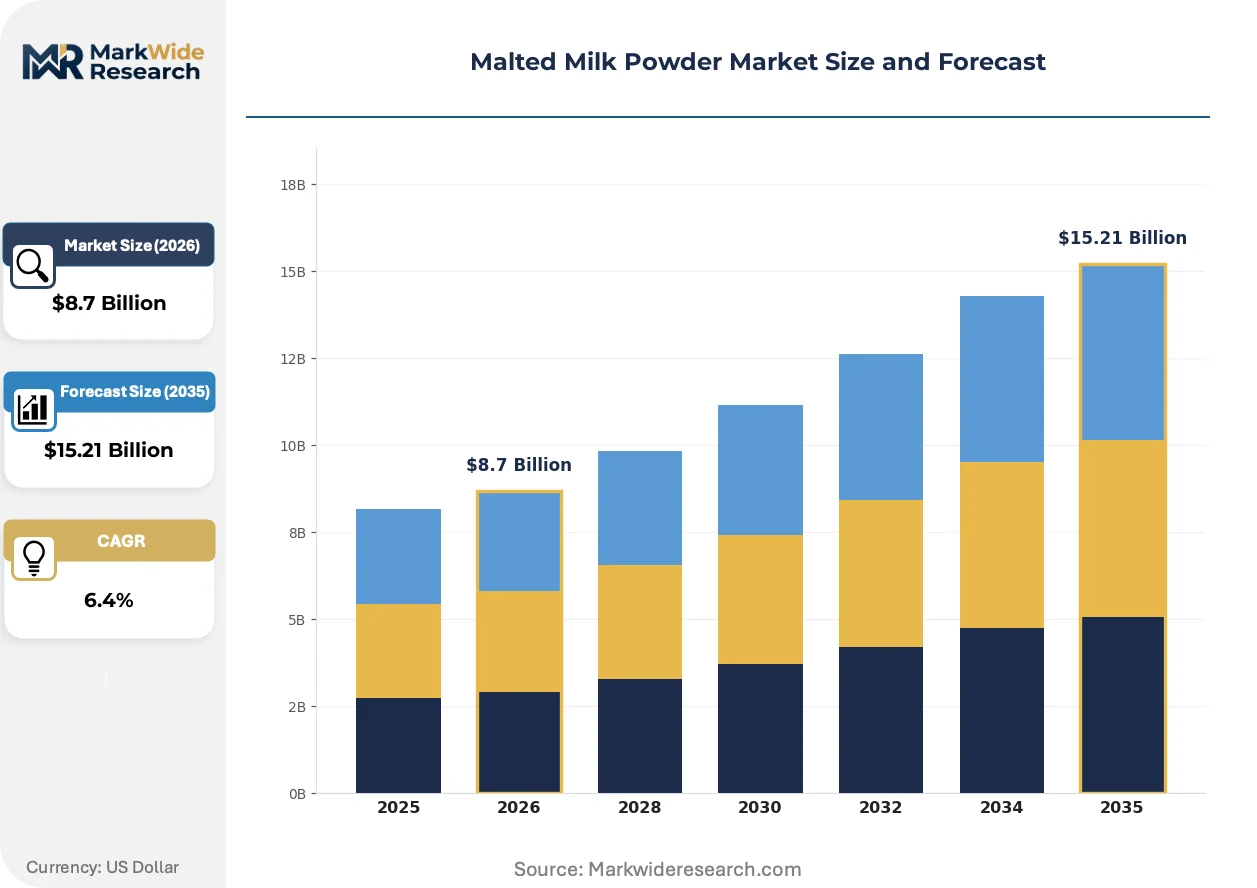
Market Dynamics
EFSA-certified clean-label mandates and EU Green Deal deforestation-free supply chain requirements are compressing procurement timelines for malted milk powder processors, forcing upstream documentation of barley and wheat sourcing from certified agricultural zones across Europe and Asia.
Growth Catalysts
- Clean-label bakery demand:Southeast Asian bakery manufacturers are expanding procurement of instant and flavored malt powders for reformulated applications, pulling volume through food service channels.
- Nutritional fortification mandates:India's FSSAI enforces dairy-adjacent product classifications that shape domestic production requirements, scaling spray-drying capacity for health food brands.
- EU supply chain traceability:The EU Green Deal's deforestation-free mandates press processors to document grain sourcing, accelerating certified organic malt powder adoption across European confectionery supply chains.
Market Restraints
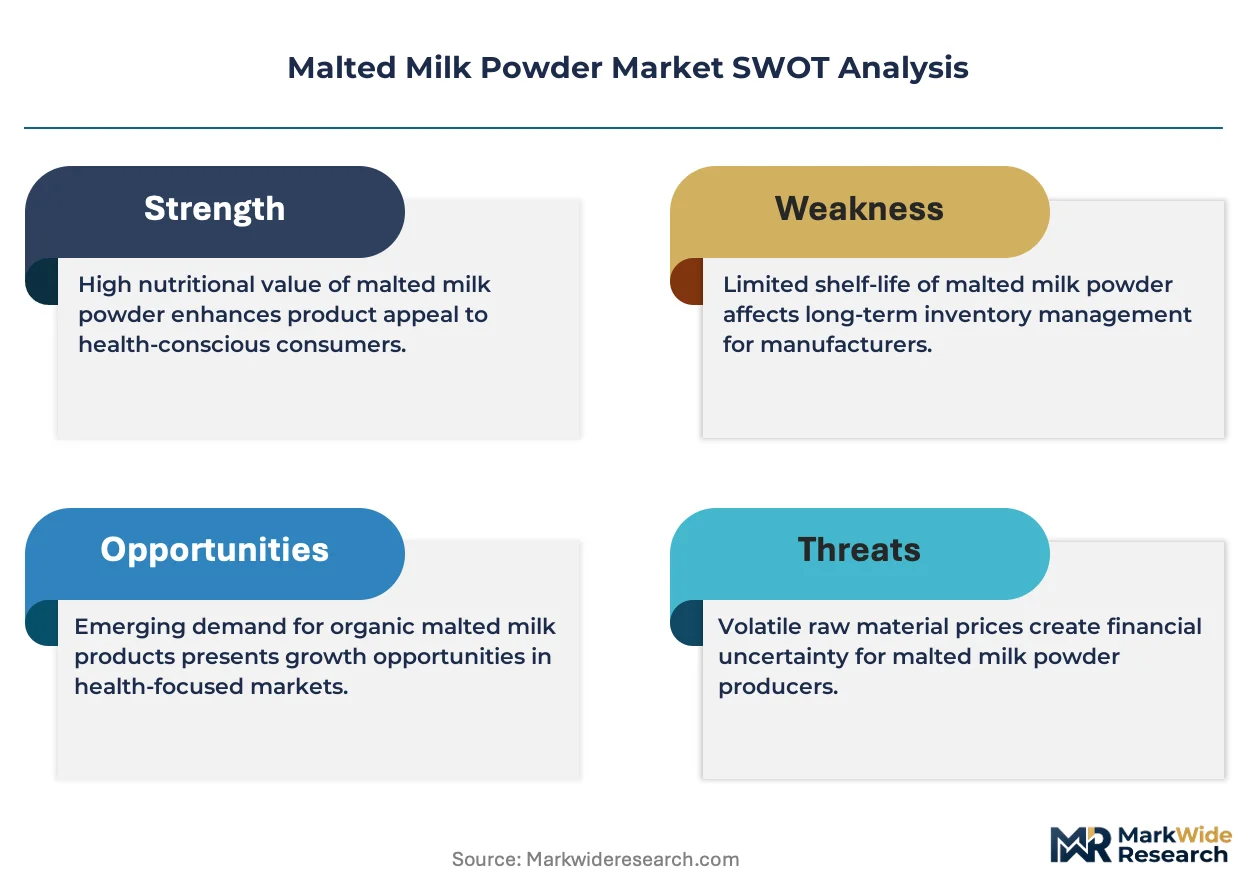
- Barley input cost volatility:Climate-driven yield fluctuations in major barley-producing regions create margin pressure for malt extract suppliers dependent on agricultural commodity markets.
- Supply concentration in dairy infrastructure:Spray-drying capacity clusters with established dairy cooperatives in India and South Asia, limiting new entrant access to contract manufacturing networks.
- Lactose-based formulation dominance:Non-dairy malt powder remains technically constrained by solubility and flavor-masking limitations, restricting penetration into lactose-intolerant demographic segments.
Strategic Opportunities
- Underpenetrated non-dairy formulations:Plant-based milk protein technologies enable malt powder variants targeting lactose-intolerant consumers in North American and European specialty channels.
- EFSA organic certification tailwind:Tightening additive thresholds under EFSA standards create margin expansion for certified organic malt powder in premium European bakery applications.
- Cold-beverage solubility innovation:Instant malt powder formulations with enhanced cold-water dispersibility unlock ready-to-drink beverage manufacturing partnerships.
Industry Challenges
- Spray-drying capex intensity:Vacuum evaporation and atomization equipment requires significant capital deployment, constraining capacity expansion timelines for regional dairy processors.
- FSSAI fortification compliance timelines:Evolving nutritional supplement classifications in India demand reformulation cycles that compress product development windows for export-oriented manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malted Milk Powder Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Malt Powder, Flavored Malt Powder, Organic Malt Powder, Non-Dairy Malt Powder Application: Beverages, Bakery Products, Nutritional Supplements, Confectionery End User: Households, Food Service, Manufacturers, Health Institutions Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | SSP Private Limited, Family Cereal Sdn. Bhd., Nestlé S.A., Associated British Foods plc, Unilever PLC, Briess Malt & Ingredients, Muntons plc, GSK plc, Imperial Malts Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malted Milk Powder Market Shifts & Advancements
Technology migration, regulatory tightening, and procurement model compression are reshaping how malted milk powder moves from grain to finished formulation across food manufacturing value chains.
Spray-drying technology is migrating from conventional single-stage atomization toward multi-stage vacuum evaporation systems with integrated malt extract concentration controls. European and Indian dairy processors are retrofitting existing facilities to capture energy efficiency gains and tighter particle size distribution. This equipment transition is compressing the technical gap between commodity malt powder and specialized roasting profiles for premium confectionery applications.
The EU Green Deal's deforestation-free supply chain mandates now require documented traceability for barley and wheat entering European food channels. Processors must submit geolocation data and certification records at import checkpoints, adding administrative overhead but creating competitive separation for suppliers with established farm-level partnerships. Organic malt powder categories face the steepest compliance burden, with EFSA-certified clean-label products commanding expanded margin pools as conventional alternatives face sourcing documentation gaps.
Buyer concentration among institutional bakery and beverage manufacturers is compressing procurement cycles from annual to quarterly contracting. Large-scale food service distributors in Southeast Asia and India now demand just-in-time delivery schedules with volume flexibility clauses, displacing traditional bulk spot purchasing. This pattern is most visible in India's nutritional supplement sector, where domestic health food brands scale malted milk formulations through direct processor relationships rather than layered distribution networks.
Malted Milk Powder Market Segmentation
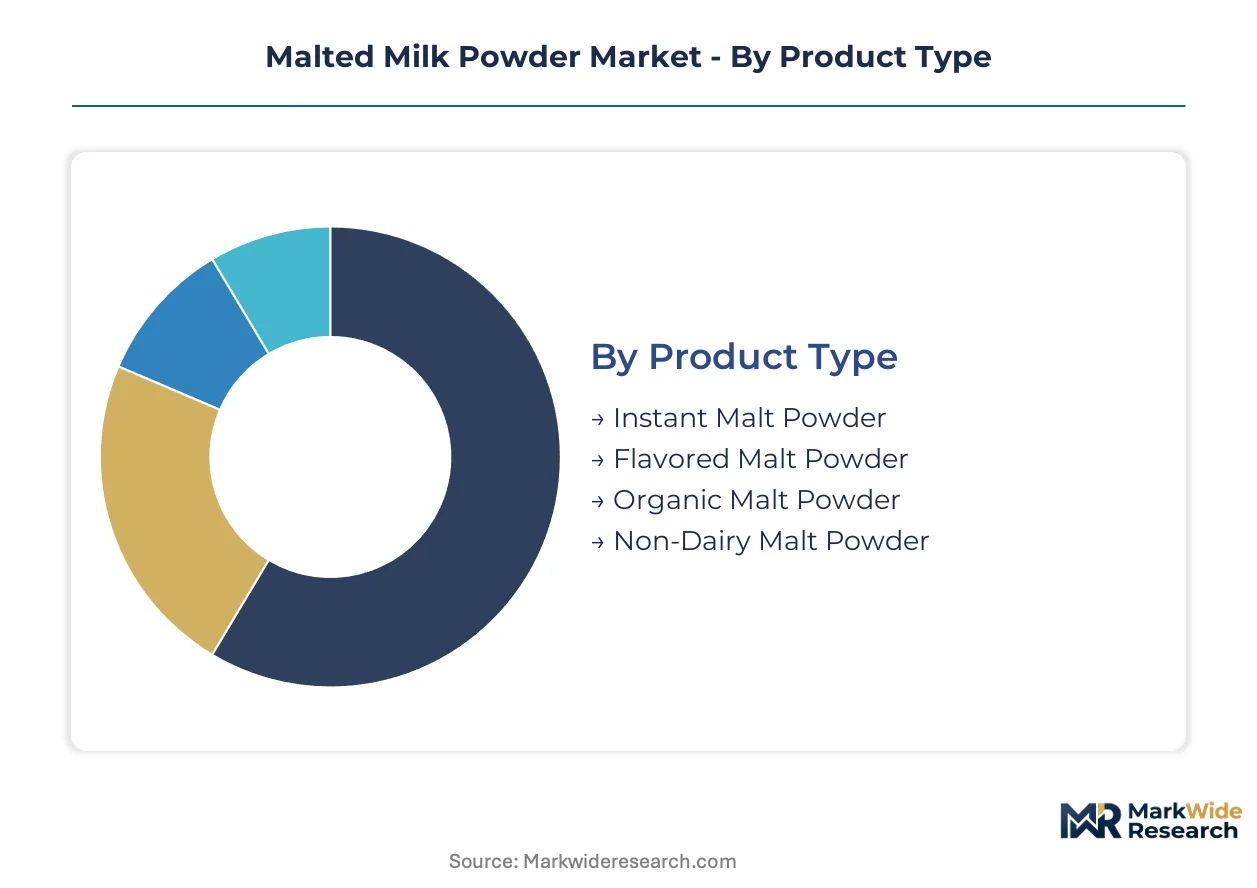
Malted milk powder segments diverge sharply by solubility performance, certification requirements, and end-use technical specifications. Procurement patterns across these dimensions determine margin capture and supply chain positioning for ingredient processors.
Product Type:
Cost tier differentiation separates commodity formulations from certified organic and specialized non-dairy variants, with spray-drying complexity and input certification driving price stratification.
- Instant Malt Powder:Engineered for rapid cold-water dispersibility through agglomerated particle structures and lecithin coating. Southeast Asian food service distributors pull volume through quarterly contracting with just-in-time delivery clauses. This formulation dominates household and beverage manufacturing channels where solubility performance commands premium placement.
- Organic Malt Powder:Produced from EFSA-certified barley and wheat sourcing with full geolocation documentation under EU Green Deal mandates. European bakery supply chains absorb expanding volumes as clean-label additive thresholds tighten, creating margin expansion for certified processors with established farm-level partnerships.
- Flavored Malt Powder:Incorporates cocoa, vanilla, or regional flavor systems during the vacuum evaporation stage. Confectionery applications in India and Southeast Asia drive procurement.
- Non-Dairy Malt Powder:Plant-based protein carriers replace milk solids for lactose-intolerant demographics. Technical constraints around solubility and flavor masking restrict penetration despite growing North American and European specialty channel interest.
Instant malt powder commands the established base. The steepest expansion runs through organic malt powder.
Application:
End-use technical requirements range from beverage solubility benchmarks to bakery browning kinetics and nutritional fortification compliance.
- Beverages:Hot and cold drink formulations demand specific particle size distribution and dispersibility indices. India's domestic dairy processors scale spray-drying capacity to serve regional health food brands expanding malted milk nutritional supplement lines.
- Bakery Products:Functions as flavor carrier, browning agent, and moisture retention aid in commercial production. EFSA-certified clean-label procurement is compressing sourcing timelines across European supply chains.
- Nutritional Supplements:FSSAI fortification norms govern dairy-adjacent product classifications in India. Direct processor relationships are displacing layered distribution networks.
- Confectionery:Specialized roasting profiles and heritage malt sourcing differentiate premium applications. Muntons plc competes on this technical capability.
Beverage applications command the established base. The steepest expansion runs through nutritional supplements.
End User:
Customer type determines order scale, formulation customization depth, and regulatory compliance burden.
- Manufacturers:Institutional bakery, beverage, and confectionery producers drive bulk procurement with quarterly contracting and volume flexibility demands. Nestlé S.A. leverages South Asian dairy infrastructure to sustain supply contracts with this segment.
- Food Service:Southeast Asian distributors require just-in-time delivery schedules, displacing traditional spot purchasing patterns.
- Households:Retail-packaged instant malt powder for home beverage preparation. Supermarket and online retail channels dominate.
- Health Institutions:Clinical nutrition and therapeutic feeding programs with fortified formulation requirements. FSSAI compliance shapes procurement in India.
Manufacturers command the established base. The steepest expansion runs through food service.
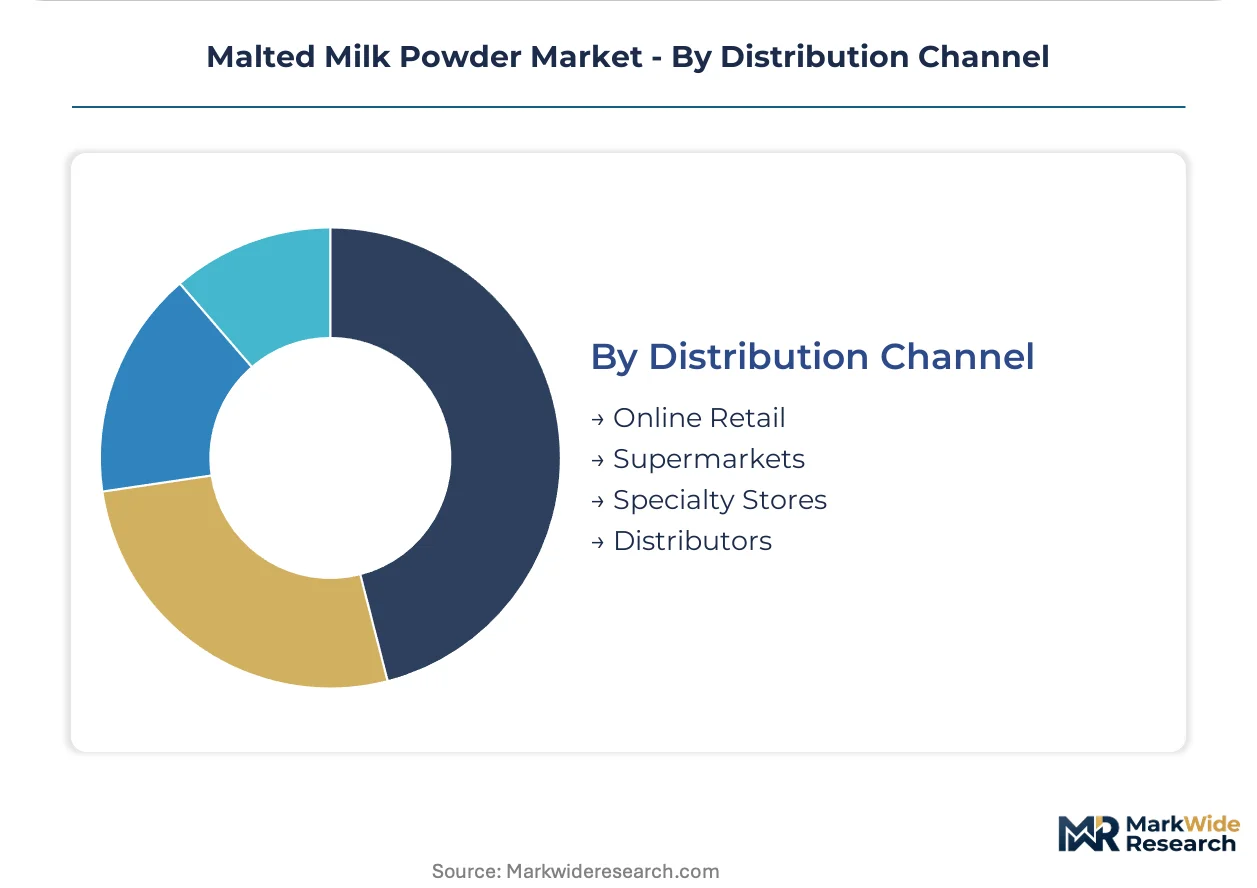
Distribution Channel:
Channel selection determines margin retention, customer data access, and speed to market for new formulations.
- Distributors:Layered networks traditional to bulk ingredient procurement are being compressed as Indian health food brands and Southeast Asian manufacturers build direct processor relationships.
- Online Retail:E-commerce platforms enable specialty and organic variant discovery for household consumers. Cold-beverage solubility innovation unlocks ready-to-drink partnerships through this channel.
- Supermarkets:Mass-market instant malt powder placement with limited SKU depth. Price competition intensifies.
- Specialty Stores:Premium organic and flavored variants targeting clean-label conscious consumers in European urban centers.
Distributors command the established base. The steepest expansion runs through online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spray-drying capacity clusters with established dairy cooperatives across South Asia and Europe, creating procurement bottlenecks for new entrants. India anchors volume expansion through domestic health food brands scaling malted milk formulations. European processors face compressed sourcing timelines under EFSA-certified clean-label mandates.
India
Domestic dairy cooperatives and ingredient processors expand spray-drying facilities to serve regional beverage and nutritional markets. FSSAI fortification norms govern dairy-adjacent product classifications, shaping import and domestic production requirements. Maharashtra and Gujarat host concentrated malt powder manufacturing infrastructure serving health food brands.
Germany
EFSA-certified clean-label requirements tighten across bakery supply chains, accelerating certified organic malt powder adoption. The EU Green Deal's deforestation-free supply chain mandates press processors to document barley and wheat sourcing from certified agricultural zones. Bavaria anchors heritage malt sourcing for premium confectionery applications.
United Kingdom
Baking and beverage ingredient divisions drive procurement of instant and flavored malt powders for reformulated applications. EFSA standards govern additive thresholds and labeling claims for malted ingredients sold into EU food channels. London and the Southeast concentrate distribution networks for European confectionery supply chains.
Malaysia
Southeast Asian bakery manufacturers expand procurement of instant and flavored malt powders for clean-label applications. Food service distributors demand just-in-time delivery schedules with volume flexibility clauses, displacing traditional bulk spot purchasing. Kuala Lumpur anchors regional procurement networks for institutional buyers.
Switzerland
Existing dairy infrastructure sustains bulk supply contracts with institutional buyers across South Asia and Europe. Swissmedic and EFSA dual compliance requirements shape premium formulation standards. Zurich and Basel concentrate multinational headquarters coordinating regional spray-drying capacity.
Malted Milk Powder Market Competitive Landscape
Multinational dairy conglomerates and specialized malt processors split the market between scale-driven commodity supply and heritage-certified premium positioning. Tiered competition separates instant formulation specialists from organic certification leaders. Nestlé S.A. and Associated British Foods plc exemplify integrated food conglomerates leveraging existing dairy infrastructure. Muntons plc and Briess Malt & Ingredients represent heritage malt sourcing specialists. Dominant competitive moves include backward integration into spray-drying capacity and strategic partnerships for EFSA-certified organic supply chains.
Within the heritage malt specialist tier, Muntons plc exemplifies technical differentiation through specialized roasting profiles for premium confectionery applications. Associated British Foods plc anchors European demand through its baking and beverage ingredient divisions. Nestlé S.A. occupies a position leveraging South Asian dairy infrastructure for institutional bulk contracts. These three entities represent distinct archetypes: heritage technical specialization, diversified ingredient platforms, and integrated dairy conglomerates with regional manufacturing footprints.
| Leading Market Players |
|---|
| SSP Private Limited |
| Family Cereal Sdn. Bhd. |
| Nestlé S.A. |
| Associated British Foods plc |
| Unilever PLC |
| Briess Malt & Ingredients |
| Muntons plc |
| GSK plc |
| Imperial Malts Ltd. |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp freight corridors carry barley and wheat derivatives into European spray-drying facilities, with bunker fuel cost volatility compressing margins for commodity malt powder while EFSA-certified organic variants capture pricing power through documented geolocation traceability.
Pricing Analysis
EFSA-certified clean-label mandates dictate the pricing tier structure across European bakery supply chains, separating organic malt powder with full farm-level documentation from conventional alternatives facing sourcing gaps. Price differentiation rests on certification grade and volume scale, with institutional manufacturers commanding quarterly contract discounts unavailable to food service distributors. Cost compression in commodity instant malt powder is intensifying because spray-drying capacity clusters with established dairy cooperatives in India and South Asia. Food service distributors in Southeast Asia exhibit the highest price sensitivity due to just-in-time delivery demands, while health food brands in India show lowest sensitivity when securing FSSAI-compliant fortification formulations.
Supply Chain Analysis
Extended payment terms from Indian dairy cooperatives and supply-chain finance facilities anchored by Nestlé S.A. infrastructure shape working capital dynamics for regional spray-drying networks. Geographic supply concentration centers on India, Germany, and the United Kingdom, with Maharashtra and Gujarat hosting concentrated manufacturing infrastructure. Raw material dependencies draw from malting-grade barley, wheat flour, and milk solids sourced through documented farm partnerships. Single-source vulnerability runs through spray-drying equipment suppliers for vacuum evaporation and atomization systems. Distribution runs through direct processor relationships that are displacing traditional layered networks across Indian nutritional supplement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from plant-based protein fortifiers and specialized malt extracts targeting clean-label confectionery, requiring defensive positioning around certification barriers and captive supply infrastructure.
For Market Incumbents: Harden EFSA-certified organic supply chains through backward integration into certified barley sourcing from Bavarian and Punjab agricultural zones. Lock in spray-drying capacity expansion ahead of FSSAI fortification compliance deadlines to preempt competitor access to Indian dairy cooperative networks. Nestlé S.A.'s South Asian infrastructure demonstrates how regional manufacturing footprints constrain new entrant procurement access. For New Entrants and Emerging Players: North American lactose-intolerant demographics present the most penetrable white-space target, where non-dairy malt powder formulations remain technically constrained by solubility limitations. Target cold-beverage solubility innovation partnerships with ready-to-drink manufacturers seeking agglomerated particle structures. Build direct e-commerce channel presence to bypass distributor concentration in Southeast Asian food service networks. For Investors and Strategic Acquirers: Heritage malt specialists with established roasting profiles and farm-level partnerships represent the priority acquisition archetype, given EFSA traceability mandates and EU Green Deal deforestation-free requirements. Monitor FSSAI fortification guideline evolution as the inflection indicator for Indian domestic production scaling versus import dependency shifts. Long-term viability across the analysis window hinges on certified organic capacity positioning and spray-drying technology migration toward multi-stage vacuum evaporation systems.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Organic Certification Investment | Full geolocation documentation unlocks premium European bakery supply chain access under EU Green Deal mandates. |
| Spray-Drying Capacity Expansion | Maharashtra and Gujarat facility additions capture Indian health food brand demand scaling nutritional supplement lines. |
| Cold-Beverage Solubility R&D | Agglomerated particle structures with lecithin coating enable ready-to-drink manufacturing partnerships in North America. |
| Backward Integration into Barley Sourcing | Certified farm partnerships in Bavaria and Punjab secure deforestation-free supply chain documentation for EU compliance. |
| Direct Processor Relationship Development | Bypassing layered distributors captures margin retention and customer data access across Indian nutritional supplement channels. |
Research Methodology
Cross-validation between primary interviews with spray-drying facility managers, FSSAI compliance officers at Indian dairy cooperatives, European bakery procurement leads, and malt extract technical directors anchors the qualitative findings against secondary validation from EFSA additive threshold documentation, EU Green Deal supply chain traceability filings, FSSAI fortification guideline releases, and Indian customs trade data. Bottom-up capacity assessments across Maharashtra and Gujarat manufacturing clusters triangulate against top-down demand modeling from health food brand formulation scaling.
Calibration against historical spray-drying capacity deployment patterns and EFSA certification adoption curves shapes the analytical framework across the analysis window. Segmentation dimensions span product type, application, end user, and distribution channel, with additional modeling of certification tier and solubility performance specifications. CAGRs derive from fitted growth curves against observed procurement pattern shifts, incorporating barley input cost volatility indices and dairy infrastructure investment flows as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by Asian dairy conglomerates or accelerated plant-based protein substitution would shift outcomes. Macroeconomic deviation in agricultural commodity markets, regulatory tightening in EU traceability enforcement, or breakthrough cold-solubility technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
GCC Dairy Market
Dairy Products
Non-GMO Yogurt Market
Dairy Products
Smoked Cheese Market
Dairy Products
Global Dairy Cream Market
Dairy Products
Recombined Milk Market
Dairy Products
Global Yogurt Market
Dairy Products
Global Cultured Dairy Products Market
Dairy Products
Global Grass Fed Dairy Product Market
Dairy Products
Asia-Pacific Dairy Market
Dairy Products
North America Casein Market
Dairy Products
Europe Cheese Market
Dairy Products
Butter Fat Fraction Market
Dairy Products
Textured Butter Market
Dairy Products
Dry Whole Milk Powder Market
Dairy Products
Lactose Free Probiotic Yogurt Market
Dairy Products
China Dairy Market