
 China Factory Automation and Industrial Controls Market | 2026-2036
China Factory Automation and Industrial Controls Market Size, Share, and Industry Trends Forecast 2026-2036
China Factory Automation and Industrial Controls Market Outlook
Multi-sourcing of critical control components is hardening as a defensive posture among Chinese equipment builders. Inovance Technology leverages its captive servo and drive manufacturing to anchor pricing power in domestic EV battery lines. ABB Ltd. competes through its Shanghai robotics campus, sustaining technology transfer advantages in arc welding and material handling cells. Hollysys Automation Technologies Ltd. specializes in safety-critical DCS architectures for petrochemical complexes along the Bohai Rim.
Factory automation and industrial controls encompass electromechanical systems, programmable logic controllers, distributed control architectures, and human-machine interfaces that regulate machine motion, process variables, and production sequencing with millisecond response tolerances. Their primary purpose is to replace manual intervention with repeatable, sensor-driven execution across continuous and discrete manufacturing environments. PLC and DCS product categories dominate capital allocation in process-heavy sectors like refining and chemicals, where redundancy and deterministic control justify premium positioning. Industrial IoT and sensor technology segments attract the fastest upgrade cycles as edge analytics and predictive maintenance protocols displace scheduled downtime models in electronics and automotive plants.
MIIT's GB standards for industrial cybersecurity and SAMR's certification requirements for safety-integrated systems are tightening compliance burdens on imported control platforms while accelerating domestic substitution timelines. NMPA-equivalent pressure equipment directives and MEE emissions monitoring mandates force integrators to embed certified sensor networks and audit-trail logging into every greenfield installation. Stakeholders must weigh the trade-off between foreign technology reliability and local supplier qualification speed when bidding on state-backed smart factory tenders.
Market Dynamics
MIIT's smart manufacturing directives and dual carbon goals are forcing a wholesale replacement of imported PLC architectures with indigenous control platforms across China's industrial base.
Growth Catalysts
- EV battery gigafactory buildouts:Lithium-ion cell manufacturers in the Yangtze River Delta are commissioning robotic assembly lines at unprecedented scale, pulling precision servo systems and motion controllers into continuous procurement cycles.
- MIIT GB/T 33008 certification:The industrial cybersecurity standard mandates encrypted control networks for critical infrastructure, accelerating replacement of legacy fieldbus architectures in petrochemical and power generation facilities.
- SAMR safety-integrated system mandates:Functional safety requirements for machinery are compelling automotive OEMs to specify certified safety PLCs and redundant drive systems in new welding and paint shop installations.
Market Restraints
- Semiconductor supply concentration:IGBT and MCU shortages originating from Taiwan and South Korean foundries continue to extend lead times for servo drives and variable frequency drives beyond 26 weeks.
- Indigenous PLC reliability gaps:Domestic programmable logic controllers still exhibit mean-time-between-failures shortfalls versus Siemens and Rockwell equivalents in high-temperature forging applications.
- MEE emissions audit burdens:Environmental monitoring mandates require embedded sensor networks and continuous data logging, adding 12-18% to control system integration costs for Bohai Rim chemical processors.
Strategic Opportunities
- Central China manufacturing migration:Henan and Hubei provinces are attracting electronics and automotive component factories fleeing coastal labor costs, creating greenfield automation demand outside saturated eastern markets.
- Edge-to-cloud control convergence:Integration of time-sensitive networking with 5G private networks enables machine builders to offer predictive maintenance subscriptions as recurring revenue streams.
- NMPA pharmaceutical equipment mandates:Drug manufacturing digitization rules are driving demand for batch control systems and electronic batch records in biologics production facilities.
Industry Challenges
- Control systems engineering talent scarcity:Shortages of programmers fluent in IEC 61131-3 languages and safety PLC configuration are delaying commissioning timelines for complex material handling installations.
- Legacy equipment interoperability:Brownfield sites running decades-old proprietary fieldbus protocols face costly gateway implementations when upgrading to Ethernet-based control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Factory Automation and Industrial Controls Market |
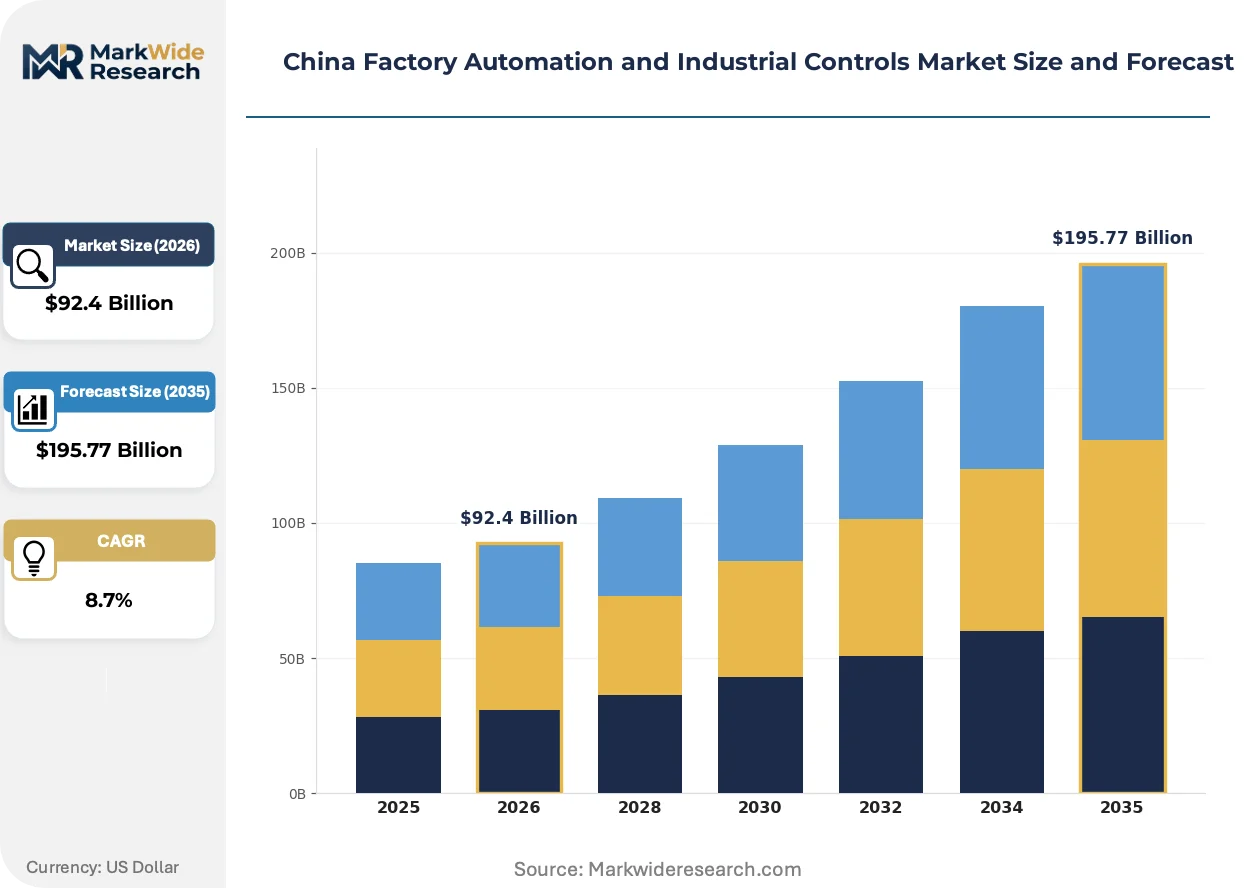
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $195.77 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLC, DCS, SCADA, HMI Technology: Industrial IoT, Robotics, Machine Learning, Sensors End User: Automotive, Electronics, Food & Beverage, Pharmaceutical Application: Manufacturing, Process Control, Quality Assurance, Asset Management |
| Companies Covered | Schneider Electric SE, Honeywell International Inc., ABB Ltd., Rockwell Automation, Inc., Emerson Electric Company, Inovance Technology Co., Ltd., Shanghai STEP Electric Corporation, Hollysys Automation Technologies Ltd., Siasun Robot & Automation Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Factory Automation and Industrial Controls Market Strategic Shifts
Digital twin technology and AI-driven process optimization are compressing commissioning cycles and enabling virtual validation of control logic before physical deployment.
Time-sensitive networking over standard Ethernet is rewriting real-time control architectures by enabling deterministic communication between PLCs, drives, and vision systems on unified cabling infrastructure. Automotive OEMs in Guangdong and Jiangsu are piloting TSN-enabled production lines to eliminate separate fieldbus networks. This convergence is rewriting supplier competitive dynamics by favoring vendors with integrated switch and controller portfolios over specialized fieldbus incumbents.
MIIT's GB/T 39264 standard for industrial data classification is mandating tiered security architectures and encrypted communications in smart factory deployments. Equipment builders must now embed hardware security modules and certificate management into every controller shipped to state-backed tender projects. Process industries along the Yangtze River are responding by specifying domestic control platforms pre-certified to the standard, accelerating substitution timelines for foreign DCS suppliers.
Equipment-as-a-service contracting is displacing traditional capex procurement in electronics manufacturing. Contract manufacturers in Shenzhen and Suzhou now demand outcome-based pricing tied to overall equipment effectiveness guarantees rather than per-unit hardware costs. This shift is most visible in SMT line automation, where Japanese and European robot suppliers are restructuring commercial teams to deliver uptime commitments rather than discrete machine sales.
China Factory Automation and Industrial Controls Market Segmentation
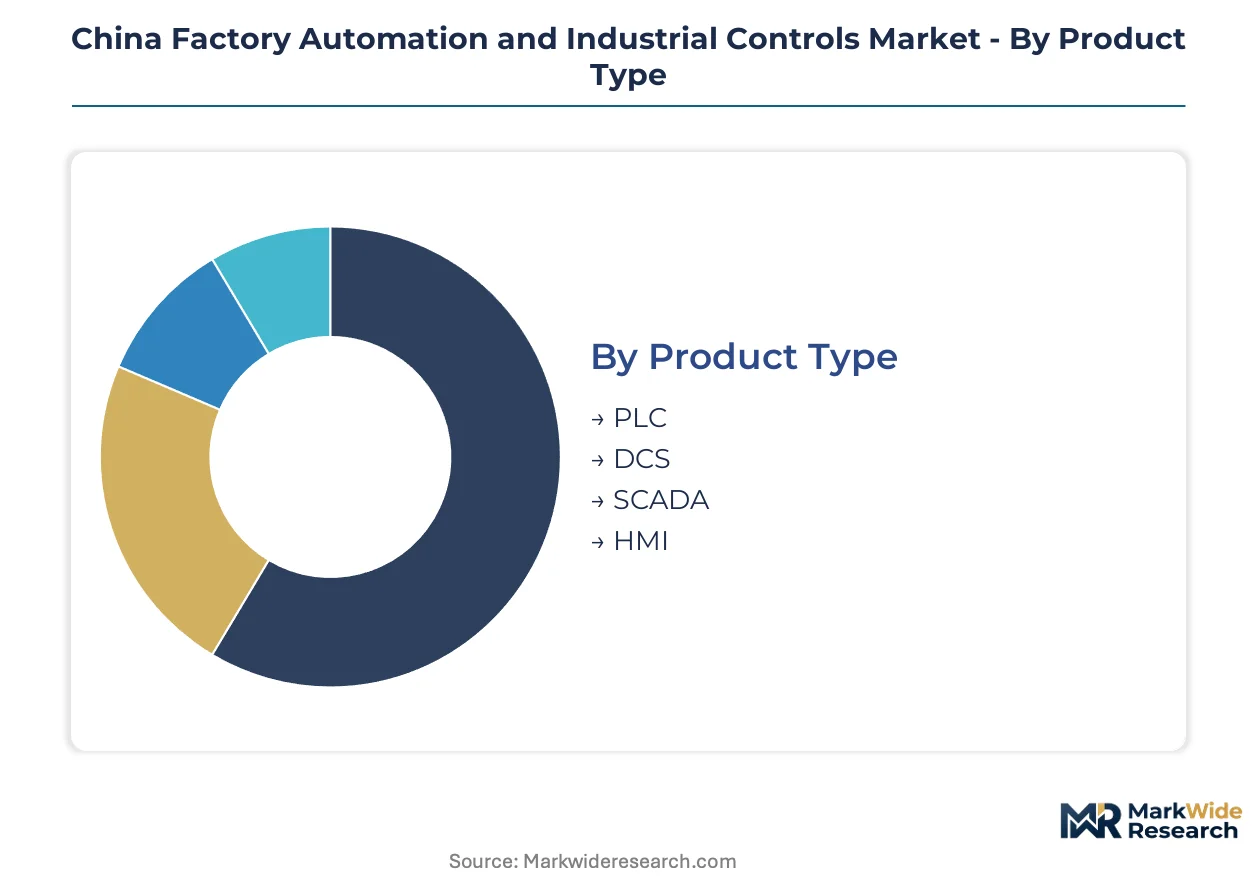
Control system procurement in China follows distinct technology adoption curves across product architectures and end-use verticals. Upgrade cycles vary sharply between process-heavy sectors demanding redundancy and discrete manufacturing chasing cycle-time compression.
Product Type:
Replacement timelines diverge most dramatically in this dimension, with cybersecurity mandates and semiconductor obsolescence forcing divergent refresh strategies.
- PLC:Modular programmable controllers execute discrete logic with deterministic scan cycles under 10 milliseconds. Automotive welding lines in Guangdong specify safety-integrated PLCs to meet SAMR machinery directives, pulling certified units into continuous replacement schedules.
- DCS:Distributed control architectures manage continuous processes through redundant controller pairs and fault-tolerant I/O networks. Petrochemical complexes along the Bohai Rim deploy DCS platforms for reactor temperature cascade control, with MIIT GB/T 33008 encryption standards accelerating migration from legacy foreign systems.
- SCADA:Supervisory systems aggregate field data across geographically dispersed assets through historian databases and alarm management layers.
- HMI:Operator interfaces consolidate machine status visualization through industrial panel PCs and mobile-enabled thin clients.
Volume placements concentrate in PLC architectures serving discrete manufacturing; the faster expansion belongs to DCS platforms driven by process industry cybersecurity retrofits.
Technology:
Cost tiers separate established automation hardware from software-defined layers commanding premium integration fees.
- Industrial IoT:Edge-to-cloud connectivity stacks embed MQTT brokers, OPC UA servers, and containerized analytics runtimes directly on control hardware. Electronics manufacturers in Suzhou deploy IIoT-enabled predictive maintenance subscriptions, shifting procurement from capex hardware to recurring software fees.
- Robotics:Multi-axis articulated arms and collaborative cobots execute pick-place, welding, and assembly sequences through synchronized servo networks. EV battery gigafactories in the Yangtze River Delta commission robotic cell lines at unprecedented density, pulling precision motion systems into procurement backlogs.
- Machine Learning:Neural network inference engines optimize process setpoints and detect anomaly patterns through edge-deployed GPU accelerators.
- Sensors:Smart transmitters and vision systems feed high-fidelity data streams into closed-loop control algorithms.
Hardware-centric robotics captures the largest installed base; machine learning layers are climbing the fastest as virtual commissioning and digital twin adoption accelerate.
End User:
Application maturity varies by sector certification burdens and production volume sensitivity.
- Automotive:OEMs and tier suppliers operate synchronized assembly lines with millisecond-level cycle-time tolerances and functional safety requirements. Paint shops and body-in-white welding cells in Jiangsu specify redundant safety PLCs and certified servo systems under SAMR machinery mandates.
- Electronics:Contract manufacturers demand SMT line automation with overall equipment effectiveness guarantees rather than per-unit machine pricing. Shenzhen and Suzhou facilities are piloting equipment-as-a-service contracts tied to uptime commitments.
- Food & Beverage:Hygienic design requirements and batch traceability regulations shape control system specifications.
- Pharmaceutical:NMPA digitization mandates drive demand for electronic batch records and validated control systems in biologics production.
Automotive represents the deepest installed base; pharmaceutical applications are gaining share fastest on regulatory digitization timelines.
Application:
Customer type separates capital-intensive greenfield deployments from retrofit-heavy brownfield upgrades.
- Manufacturing:Discrete production lines execute assembly, machining, and material handling through synchronized multi-axis motion control. Central China migration into Henan and Hubei provinces is creating greenfield automation demand outside saturated coastal markets.
- Process Control:Continuous operations in refining and chemicals maintain tight regulatory loops for temperature, pressure, and flow variables. MEE emissions monitoring mandates force embedded sensor networks and audit-trail logging into every Bohai Rim installation.
- Quality Assurance:Automated inspection systems deploy machine vision and dimensional measurement for defect detection.
- Asset Management:Condition monitoring platforms track equipment health through vibration analysis and thermal imaging.
Manufacturing applications hold the broadest deployment footprint; process control is expanding most quickly on environmental compliance investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth processing capacity in Jiangxi anchors the upstream material base for servo motor manufacturing. Control system demand clusters along three distinct industrial corridors where MIIT smart manufacturing directives intersect with provincial industrial policies.
Yangtze River Delta
EV battery gigafactories and electronics contract manufacturers pull precision motion controllers into continuous procurement cycles. Jiangsu and Zhejiang provincial governments coordinate MIIT-funded smart factory pilots targeting semiconductor packaging lines. Suzhou and Ningbo host dense concentrations of SMT automation integrators migrating toward equipment-as-a-service contracting models.
Pearl River Delta
Automotive OEMs in Guangdong specify redundant safety PLCs for welding and paint shop installations under SAMR machinery directives. Shenzhen electronics manufacturers pilot edge-to-cloud control convergence through 5G private networks. Dongguan machine builders embed GB/T 39264 hardware security modules to qualify for state-backed tender projects.
Beijing-Tianjin-Hebei
Petrochemical complexes along the Bohai Rim deploy encrypted DCS architectures to meet MIIT GB/T 33008 cybersecurity mandates. MEE emissions monitoring requirements force embedded sensor networks into every greenfield installation. Tianjin port automation and Shijiazhuang pharmaceutical equipment manufacturers drive demand for validated batch control systems.
Sichuan-Chongqing
Central China manufacturing migration attracts electronics and automotive component factories fleeing coastal labor costs. Chongqing municipal authorities offer tax incentives for industrial robot deployment in motorcycle and automotive parts production. Chengdu aerospace suppliers commission precision machining cells with deterministic motion control requirements.
Shandong Peninsula
Heavy machinery and forging equipment manufacturers test indigenous PLC platforms in high-temperature applications. Qingdao and Yantai port automation projects specify time-sensitive networking over standard Ethernet for crane control systems. Provincial industrial policies prioritize domestic substitution in rubber and tire manufacturing automation.
China Factory Automation and Industrial Controls Market Competitive Environment
Capacity expansion dominates the current landscape as domestic suppliers scale servo and drive manufacturing to capture EV battery line procurement. The market exhibits a tiered structure with multinational incumbents defending premium positioning in safety-critical applications while local players capture volume in standard automation. Three archetypes define competitive positioning: integrated motion control specialists, safety-system certifiers, and robotics-centric solution providers. Geographic expansion into Central China provinces and strategic partnerships with battery manufacturers represent the dominant competitive moves.
Within the integrated motion control tier, Inovance Technology Co., Ltd. and Shanghai STEP Electric Corporation exemplify the captive manufacturing archetype that anchors pricing power in domestic supply chains. Among safety-system specialists, Hollysys Automation Technologies Ltd. occupies a position representing the certified architecture provider for process industry retrofits. These three companies collectively illustrate how competitive positioning stratifies between hardware integration depth and regulatory certification breadth.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Honeywell International Inc. |
| ABB Ltd. |
| Rockwell Automation, Inc. |
| Emerson Electric Company |
| Inovance Technology Co., Ltd. |
| Shanghai STEP Electric Corporation |
| Hollysys Automation Technologies Ltd. |
| Siasun Robot & Automation Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
MIIT's dual carbon goals and emissions compliance mandates gate qualified supply and premium-tier pricing access. Equipment builders embedding certified sensor networks and audit-trail logging command pricing premiums in state-backed smart factory tenders, while uncertified suppliers face exclusion from Bohai Rim chemical and Yangtze River Delta EV battery procurement.
Pricing Analysis
Warranty and service bundling separates premium-tier positioning from transactional hardware sales. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service depth. Price differentiation stems from SAMR safety-integrated system certification and MIIT GB/T 33008 cybersecurity compliance. Cost compression in standard automation tiers is intensifying because indigenous PLC suppliers anchor pricing power through captive servo manufacturing. Electronics contract manufacturers in Shenzhen exhibit highest price sensitivity through equipment-as-a-service demands, while petrochemical operators along the Bohai Rim show lowest sensitivity given redundancy requirements.
Supply Chain Analysis
Workforce availability constraints in Jiangsu and Zhejiang provinces concentrate precision motion control manufacturing in the Yangtze River Delta. Geographic supply concentration centers on China, Taiwan, and South Korea for IGBT and MCU components. Raw material dependencies include rare earth magnets from Jiangxi, silicon wafers from Taiwanese foundries, and copper windings from domestic smelters. Single-source vulnerability in semiconductor supply extends lead times for servo drives. Distribution runs through direct OEM partnerships for large battery manufacturers and systems integrator channels for mid-tier automotive suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive servo and drive manufacturing determines pricing power. Players pursuing upstream control over IGBT sourcing and downstream integration into EV battery line commissioning capture margin expansion.
For Market Incumbents: Cement technology transfer advantages in arc welding and material handling cells through Shanghai-based robotics campuses. Deepen certification breadth for SAMR safety-integrated systems to defend against indigenous PLC substitution in automotive paint shops. Capacity addition in Central China provinces anchors positioning in Henan and Hubei manufacturing migration.
For New Entrants and Emerging Players: Begin with pharmaceutical equipment digitization in Chengdu and Tianjin biologics facilities where NMPA mandates create qualified supplier gaps. Target SMT line automation in Suzhou with predictive maintenance subscriptions as the most penetrable segment. Pursue equipment-as-a-service contracting to bypass incumbent hardware lock-in.
For Investors and Strategic Acquirers: MIIT GB/T 39264 pre-certification announcements are the leading indicator that domestic control platform substitution timelines are accelerating. Long-term viability favors vertically integrated motion control specialists with captive rare earth magnet sourcing and in-house PLC development. Watch for SAMR machinery directive enforcement spikes as the signal for safety-system certification premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into IGBT Sourcing | Captive semiconductor supply insulates servo drive margins from Taiwanese foundry allocation constraints. |
| GB/T 39264 Pre-Certification Investment | Hardware security module embedding qualifies controllers for state-backed Yangtze River Delta tenders. |
| Central China Geographic Expansion | Henan and Hubei facility placement captures electronics manufacturing migration from coastal labor costs. |
| Equipment-as-a-Service Model Launch | Uptime-based contracting in Suzhou SMT lines shifts procurement from capex hardware to recurring software fees. |
| Safety-Integrated System Partnership | Collaboration with automotive OEMs secures SAMR-compliant welding cell specifications in Jiangsu. |
Study Parameters
MIIT policy filings, SAMR certification databases, and provincial smart factory tender records formed the secondary backbone. Primary interviews with plant engineers at EV battery gigafactories, procurement leads at automotive OEMs, systems integrators in Suzhou and Shenzhen, and aftermarket service heads at domestic PLC suppliers validated demand assumptions. SEC filings from listed automation vendors and customs data on servo drive imports provided trade flow calibration. Bottom-up and top-down triangulation cross-checked segment estimates.
Bottom-up modeling aggregated individual product category trajectories while top-down analysis tested aggregate market coherence against industrial output indicators. Segmentation dimensions included product architecture, technology layer, end-use vertical, and regional production cluster. CAGRs were derived from installed base turnover rates and upgrade cycle compression. Forecast inputs incorporated MIIT smart manufacturing directive implementation timelines and SAMR machinery safety enforcement intensity.
Underlying measurement precision varies by segment; PLC and DCS product categories carry tighter precision than emerging machine learning layers. Forecasts reflect assumptions on semiconductor supply normalization and indigenous control platform reliability convergence. Material deviation in MIIT cybersecurity standard enforcement or IGBT supply allocation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Global Healthcare Automation Market
Industrial Automation
Global Distribution Feeder Automation System Market
Industrial Automation
Conveyor Sorting Systems Market
Industrial Automation
Warehouse Automation Solutions Market
Industrial Automation
Rotary Vector (RV) Reducer Market
Industrial Automation
United States Human Machine Interface Market
Industrial Automation
Industrial Automation Motion Control System Software Market
Industrial Automation
Predictive Maintenance Market
Industrial Automation
Industrial Automation Products Market
Industrial Automation
North America Process Automation Market
Industrial Automation
North America Smart Manufacturing Market
Industrial Automation
Utility Automation Market
Industrial Automation
Assembly Automation Systems Market
Industrial Automation
Middle East and Africa Industrial Automation Market
Industrial Automation
Middle East and Africa Machine Control System Market
Industrial Automation
Latin America Factory Automation and Industrial Controls Market