
 United States Human Machine Interface Market | 2026-2036
United States Human Machine Interface Market Size, Share, and Industry Trends Forecast 2026-2036
United States Human Machine Interface Market Intelligence
Multi-source component procurement is consolidating across the United States Human Machine Interface Market as tier-one suppliers reduce vendor fragmentation. Rockwell Automation leverages its factory automation installed base to sustain embedded HMI module dominance in process industries. Honeywell International anchors aviation and building automation segments through proprietary display and control software architectures. Emerson Electric competes in energy and utility applications with ruggedized terminal portfolios designed for hazardous environments.
A human machine interface constitutes the hardware and software layer enabling operator interaction with machines, encompassing touch panels with resistive or capacitive sensing matrices, industrial PCs running real-time operating systems, and protocol gateways translating fieldbus signals into graphical representations. Its primary commercial purpose centers on reducing cognitive load, accelerating fault response, and enabling remote supervisory control across manufacturing, transportation, and medical equipment platforms. Touch screen interfaces occupy the largest revenue pool among product types, while augmented reality technology represents the fastest-expanding capability layer as maintenance and training applications mature. Embedded technology remains the structural backbone for industrial end users, though cloud-based architectures are displacing legacy local installations in smart home and healthcare monitoring applications where edge-to-cloud latency tolerances permit.
FCC certification requirements govern wireless-enabled HMI devices, while NHTSA regulations directly shape automotive control interface design to minimize driver distraction. FDA oversight applies to healthcare monitoring interfaces, mandating validation protocols for software-defined displays used in diagnostic and therapeutic equipment. OSHA electrical safety standards influence panel construction and enclosure ratings for factory-floor deployments. Stakeholders must monitor how impending updates to federal cybersecurity frameworks for operational technology reshape software-defined and cloud-based interface architectures.
Market Dynamics
Automotive electrification is compressing HMI development cycles as electric vehicle platforms demand unified cockpit-display architectures that merge instrument clusters with infotainment systems under single compute substrates.
Growth Catalysts
- NHTSA Distraction Guidelines:Federal mandates on driver attention are forcing OEMs to redesign touch interfaces with haptic feedback and voice-first controls, expanding contract volumes for compliant module suppliers.
- Gesture Recognition Maturation:Time-of-flight sensors and computer vision stacks are migrating from premium to mid-tier vehicle trims, creating replacement demand across Detroit's supplier base.
- Michigan-California Corridor Concentration:Proximity between automotive engineering centers in Detroit and display manufacturing clusters in San Jose accelerates prototype-to-production pipelines for next-generation interfaces.
Market Restraints
- Semiconductor Input Volatility:Tight supply of automotive-grade microcontrollers and display driver ICs from Asian foundries creates production scheduling uncertainty for domestic HMI assemblers.
- FCC Certification Friction:Wireless-enabled interface modules face extended testing timelines for 5G and Wi-Fi 6E compliance, delaying product launches in connected vehicle segments.
- Capacitive Touch Substitution:Ultrasonic and radar-based touchless sensing technologies threaten to displace conventional capacitive matrices in hygiene-critical medical and food-processing applications.
Strategic Opportunities
- Texas Energy Corridor:Oilfield services operators in Houston and Midland are retrofitting drilling platforms with ruggedized HMIs, opening industrial demand outside traditional automotive supply chains.
- FDA Digital Health Pathway:Streamlined premarket review for software-as-medical-device interfaces is accelerating hospital adoption of patient monitoring displays with integrated diagnostic workflows.
- AR Maintenance Convergence:Overlay of spatial computing headsets with industrial HMIs is creating new service revenue streams for equipment manufacturers training technicians on complex machinery.
Industry Challenges
- Embedded Software Talent Scarcity:Shortage of engineers proficient in real-time operating systems and functional safety standards (ISO 26262) is inflating compensation costs across Michigan and California development centers.
- Legacy System Integration Burden:Brownfield manufacturing facilities in the Rust Belt require protocol gateways and middleware layers to bridge decades-old PLCs with modern graphical interfaces, complicating deployment scopes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Human Machine Interface Market |
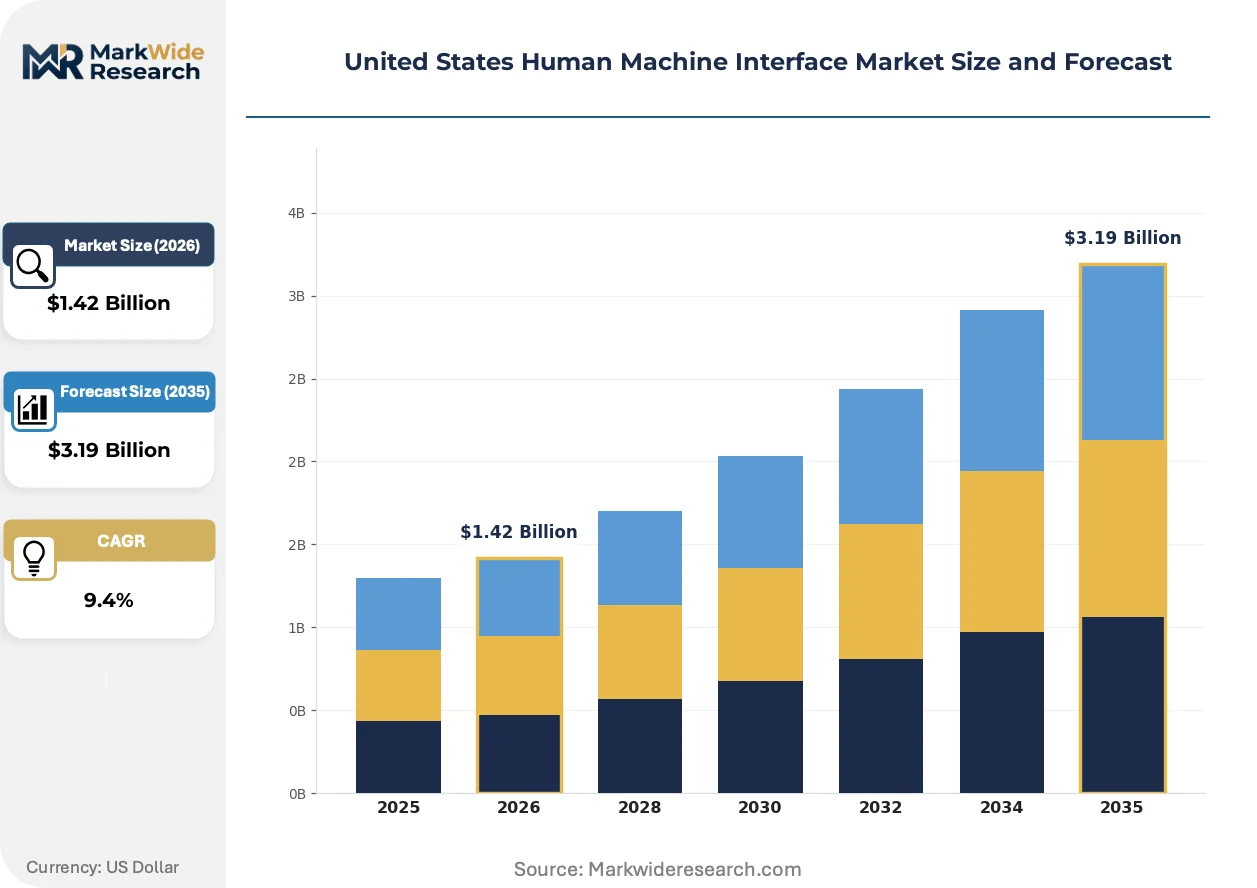
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.19 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Touch Screen, Gesture Recognition, Voice Recognition, Button-Based Technology: Embedded, Software-Defined, Cloud-Based, Augmented Reality End User: Aerospace, Automotive, Healthcare, Industrial Application: Gaming, Healthcare Monitoring, Smart Home, Automotive Control |
| Companies Covered | Rockwell Automation, Honeywell International, Emerson Electric, General Electric, Advantech, American Industrial Systems, Beijer Electronics, Red Lion Controls, Maple Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Human Machine Interface Market Strategic Shifts & Innovations
HMI architectures are bifurcating between edge-heavy industrial deployments and cloud-dependent consumer applications, with each trajectory demanding distinct engineering competencies and supplier relationships.
Edge AI inference engines are integrating directly into automotive display modules to enable real-time driver monitoring and predictive maintenance alerts without round-trip latency to remote servers. Tier-one suppliers in Detroit are adopting these system-on-chip configurations for 2027 model year electric vehicle programs. This silicon consolidation is integrating previously discrete camera, radar, and compute subsystems into single-domain controllers, reducing wiring harness complexity and assembly cost.
OSHA electrical safety standard updates for industrial control panels are mandating arc-fault detection circuitry and enhanced enclosure ingress protection, forcing panel builders to redesign legacy form factors. Manufacturers serving food and beverage processing must now validate stainless steel HMI housings for high-pressure washdown compatibility. The pharmaceutical packaging segment is responding fastest, with Chicago-area integrators certifying new IP69K-rated terminal portfolios ahead of enforcement deadlines.
Hospital procurement departments are consolidating vendor relationships for bedside monitoring interfaces, favoring suppliers offering unified fleets across telemetry, ventilator, and infusion pump platforms. This specification bundling is displacing point-solution vendors who lack cross-modal software architectures. The shift is most visible in California's integrated delivery networks, where Kaiser Permanente and Sutter Health are standardizing on single-platform HMI ecosystems to reduce nurse training burden and spare parts inventory.
United States Human Machine Interface Market Segmentation
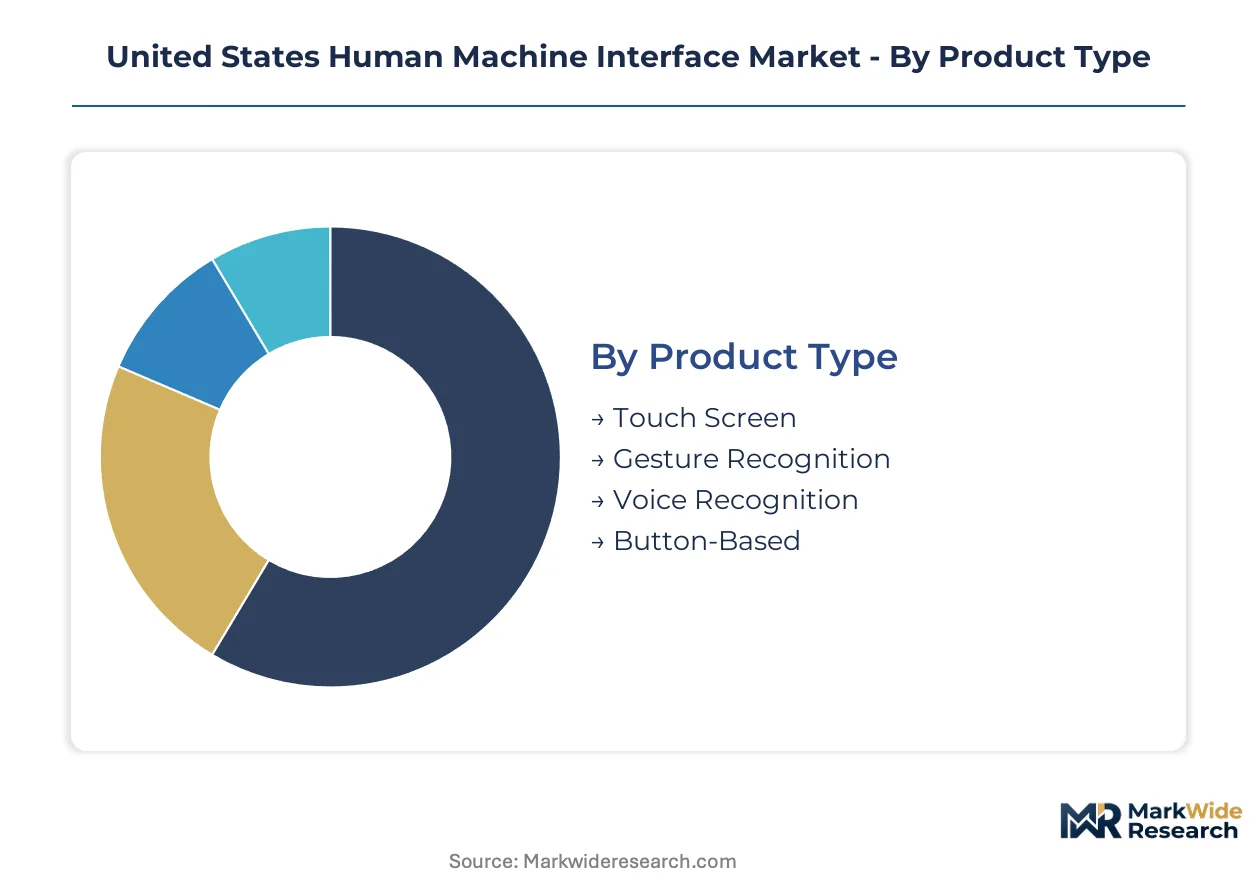
HMI purchasing decisions in the United States hinge on interface modality, compute architecture, and regulatory exposure across end-use environments. Each segmentation dimension reveals distinct procurement patterns shaped by safety mandates, integration complexity, and operator training requirements.
Product Type:
Procurement budgets prioritize interface reliability under vibration, contamination, and electromagnetic interference conditions.
- Touch Screen:Capacitive and resistive sensing matrices dominate factory floors and vehicle cabins where operators require immediate visual feedback. Michigan automotive assembly plants specify projected capacitive panels with glove-compatible sensitivity for electric vehicle production lines.
- Gesture Recognition:Time-of-flight sensors and infrared arrays enable contactless control in sterile medical environments and food processing facilities. California semiconductor cleanrooms are retrofitting equipment with mid-air gesture layers to eliminate surface contamination vectors.
- Voice Recognition:Natural language processing engines process operator commands in high-noise industrial settings and hands-busy automotive scenarios.
- Button-Based:Physical switches and membrane keypads persist in hazardous locations where tactile confirmation outweighs interface flexibility.
Touch Screen leads on scale; Gesture Recognition leads on momentum.
Technology:
Deployment architecture selection depends on latency tolerance, cybersecurity posture, and legacy infrastructure age.
- Embedded:Real-time operating systems running on dedicated industrial PCs guarantee deterministic response for safety-critical machinery. Texas oilfield operators specify embedded terminals with intrinsic safety ratings for drilling platform control rooms.
- Software-Defined:Decoupled hardware-software stacks enable rapid feature updates without physical module replacement. Hospital networks in California are migrating to software-defined bedside monitors to streamline FDA validation cycles.
- Cloud-Based:Browser-accessible dashboards aggregate distributed equipment data for remote supervisory control.
- Augmented Reality:Spatial computing overlays project maintenance guidance and training simulations onto physical equipment.
Embedded technology commands installed base; Augmented Reality is climbing the fastest.
End User:
Regulatory jurisdiction and certification burden shape vendor qualification timelines across sectors.
- Automotive:NHTSA distraction guidelines and ISO 26262 functional safety standards govern cockpit interface design. Detroit OEMs are consolidating supplier pools for unified instrument cluster-infotainment substrates.
- Industrial:OSHA electrical safety mandates and hazardous location classifications determine enclosure specifications. Rust Belt manufacturers demand IP69K-rated panels for high-pressure washdown compatibility.
- Healthcare:FDA software-as-medical-device pathways and HIPAA data security requirements constrain display architecture choices.
- Aerospace:FAA certification protocols and DO-178C software standards extend development cycles for flight deck interfaces.
Automotive leads on scale; Healthcare leads on momentum.
Application:
Use case-specific interaction patterns dictate sensor configuration, display brightness, and environmental sealing requirements.
- Automotive Control:Unified cockpit systems merge instrument clusters with infotainment under single compute domains. Electric vehicle platforms in California and Michigan are driving demand for curved OLED and mini-LED display substrates.
- Healthcare Monitoring:Bedside telemetry, ventilator, and infusion pump interfaces require alarm fatigue mitigation and nurse workflow integration. Kaiser Permanente and Sutter Health networks are standardizing on single-platform ecosystems to reduce training burden.
- Smart Home:Cloud-dependent architectures prioritize consumer-grade aesthetics and voice-first interaction over industrial durability.
- Gaming:High-refresh-rate panels and haptic feedback systems target entertainment-oriented user experiences.
Automotive Control leads on scale; Healthcare Monitoring leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration patterns within the United States reflect cost-of-compliance arbitrage, with manufacturers relocating assembly operations to states offering streamlined OSHA enforcement and favorable tax treatment for capital-intensive display fabrication. Michigan and California retain design authority while Texas and the Southeast absorb volume manufacturing.
Michigan
Automotive cockpit consolidation drives HMI engineering concentration in Detroit's metropolitan corridor. NHTSA distraction guidelines compel Tier-1 suppliers to maintain compliance engineering teams near OEM headquarters. Auburn Hills and Ann Arbor host the nation's densest cluster of instrument cluster-infotainment integration facilities.
California
Silicon Valley display technology and San Diego semiconductor design anchor the premium HMI substrate supply chain. FCC certification timelines for wireless-enabled modules favor proximity to testing laboratories in Santa Clara County. Los Angeles basin integrators specialize in entertainment and aerospace interface applications.
Texas
Houston oilfield services operators and Midland shale producers generate demand for hazardous-location-rated terminals. FERC pipeline safety regulations mandate operator interface upgrades across compressor stations and storage facilities. Dallas-Fort Worth logistics hubs distribute ruggedized panels to Permian Basin drilling contractors.
Illinois
Chicago-area pharmaceutical packaging and food processing equipment builders specify IP69K-rated washdown-compatible interfaces. FDA validation requirements for software-defined displays concentrate vendor qualification activity in the Midwest's medical device corridor. Rockford industrial automation integrators bridge legacy PLC architectures with modern graphical terminals.
Southeast
Georgia and Tennessee automotive assembly plants attract HMI module suppliers seeking proximity to electric vehicle production ramps. Right-to-work status and lower facility costs pull final assembly operations from higher-wage coastal states. Charleston port infrastructure supports import of Asian-sourced display driver components.
United States Human Machine Interface Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue software-defined and augmented reality overlay capabilities outside traditional hardware-dominated segments. Market structure tilts toward consolidation among industrial automation incumbents with captive distribution channels, while specialized display fabricators compete on customization velocity. Three archetypes dominate: diversified conglomerates leveraging cross-sector technology transfer, pure-play HMI specialists defending niche verticals, and Asian electronics contractors absorbing commodity panel assembly. Competitive dynamics center on backward integration into semiconductor sourcing and strategic partnerships with electric vehicle platform architects.
Among diversified industrial technology conglomerates, Rockwell Automation, Honeywell International, and Emerson Electric exemplify scale-driven positioning across factory automation, building controls, and energy infrastructure respectively. These entities anchor the premium tier through embedded software ecosystems and certified safety architectures. Their geographic footprints mirror end-use concentration, with Midwest engineering centers serving automotive and industrial demand while Southwest operations target oilfield and utility applications. Each represents a distinct competitive thesis: Rockwell through programmable automation controller integration, Honeywell through aviation-derived reliability standards, and Emerson through process industry hazardous location expertise.
| Leading Market Players |
|---|
| Rockwell Automation |
| Honeywell International |
| Emerson Electric |
| General Electric |
| Advantech |
| American Industrial Systems |
| Beijer Electronics |
| Red Lion Controls |
| Maple Systems |
| Others |
Cost & Logistics Intelligence
Embedded software engineers concentrated in Michigan and California command compensation premiums that compress margins in mid-tier HMI modules while widening spreads between premium safety-certified and economy-grade offerings. Labor-cost differentials between Detroit automotive corridors and Southeast assembly states translate directly into tiered pricing architectures that OEM procurement teams exploit during supplier qualification.
Pricing Analysis
Distributor margins of 15-25 percent separate factory-direct OEM contracts from aftermarket channel pricing, with project-based licensing for software-defined medical interfaces commanding premium multiples over transactional hardware sales. Price differentiation hinges on ISO 26262 functional safety certification tier and customization depth for legacy PLC integration, with Rust Belt manufacturers exhibiting acute price sensitivity compared to California healthcare networks prioritizing FDA validation speed. Cost compression in standard-grade automotive touch modules is intensifying because Asian display driver IC supply constraints force domestic assemblers to absorb input volatility or surrender share.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth and Chicago employ hub-and-spoke patterns to serve Permian Basin oilfield operators and Midwest pharmaceutical packagers with divergent lead-time tolerances. Manufacturing concentration rests on Taiwan and South Korea for automotive-grade microcontrollers and display substrates, with China supplying resistive touch sensing matrices and Mexico providing nearshore enclosure fabrication. Single-source vulnerability in automotive-grade MCU supply from TSMC-affiliated foundries exposes domestic HMI assemblers to allocation risk during semiconductor upcycles. Distribution runs through authorized industrial automation distributors with captive technician networks rather than open-market electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Human Machine Interface Market constitutes a late-cycle quality story as automotive and healthcare procurement shifts toward unified cockpit and bedside monitoring platforms that demand premium specification compliance. Specification bundling across electric vehicle lines and integrated delivery networks rewards suppliers with cross-modal software architectures and punishes point-solution vendors.
For Market Incumbents: Hedge against ultrasonic and radar-based touchless substitution in hygiene-critical segments by acquiring mid-air gesture specialists with FDA pathway experience. Deepen backward integration into automotive-grade MCU supply through strategic partnerships with foundry operators or captive inventory positions. Prioritize certification investment in ISO 26262 and FDA software-as-medical-device validation to defend margin position against emerging software-defined entrants. For New Entrants and Emerging Players: Enter via Texas energy corridor demand for hazardous-location-rated terminals, where incumbent industrial automation suppliers lack oilfield-specific application engineering depth. Target pharmaceutical packaging integrators in Illinois seeking IP69K-rated washdown-compatible interfaces with shorter qualification cycles than diversified conglomerates offer. Pursue direct sales to independent drilling contractors rather than distributor-dependent channel strategies that incumbent scale advantages block. For Investors and Strategic Acquirers: Automotive Tier 1 suppliers seeking cockpit consolidation capabilities are the most active acquirer in this space, with particular appetite for embedded AI inference engine specialists. Five-to-ten year viability favors targets with cross-vertical software architectures spanning automotive, healthcare, and industrial end uses rather than single-sector hardware fabricators. Monitor NHTSA distraction guideline enforcement intensity as inflection indicator for compliant module supplier valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Unifies instrument cluster-infotainment substrates for Detroit OEM electric vehicle programs. |
| Backward Integration | Captures automotive-grade microcontroller supply through foundry partnerships or inventory positions. |
| Software-Defined Vehicle Investment | Enables over-the-air feature updates for hospital bedside monitors without hardware replacement. |
| FDA Digital Health Pathway | Accelerates premarket review for software-as-medical-device interfaces in California health networks. |
| Geographic Manufacturing Footprint | Relocates final assembly to Southeast right-to-work states from Michigan and California. |
Research Approach
Coverage spans Michigan automotive corridors, California display technology clusters, Texas energy infrastructure, and Southeast assembly states, with primary inputs from each. The approach combines structured interviews with Tier 1 supplier procurement directors, OEM platform engineers, hospital biomedical engineers, and oilfield services operations managers with secondary validation against SEC 10-K filings, NHTSA regulatory dockets, FDA 510(k) submission databases, and IHS Markit vehicle production data. Bottom-up demand modeling and top-down supply-side triangulation reconcile volume estimates across the projection horizon.
Rate-of-change decomposition separates volume growth from value expansion across interface modality, compute architecture, and regulatory exposure dimensions. The analytical framework models touch screen, gesture recognition, voice recognition, and button-based modalities against embedded, software-defined, cloud-based, and augmented reality technology tiers, with automotive, industrial, healthcare, and aerospace end-use segments. CAGRs derive from segment-level adoption curves weighted by content-per-vehicle trajectories in electric platforms and FDA validation cycle compression in healthcare. Forecast inputs include NHTSA distraction guideline compliance timelines and OSHA electrical safety standard update enforcement schedules.
The model holds under stable semiconductor allocation and continued NHTSA enforcement intensity; deviation in foundry capacity constraints or federal cybersecurity framework implementation would shift supplier competitive positioning. Forecasts reflect documented assumptions regarding electric vehicle production ramp rates and hospital procurement consolidation trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Latin America Process Automation Market
Industrial Automation
Connected Worker Market
Industrial Automation
Smart Warehouse System Market
Industrial Automation
Middle East and Africa Medical Automation Market
Industrial Automation
Programmable Automation Controller (PAC) Market
Industrial Automation
Global Electric Gripper Market
Industrial Automation
Agricultural Automation Market
Industrial Automation
Europe Water Automation and Instrumentation Market
Industrial Automation
Europe ICS Market
Industrial Automation
Geosteering Technology Market
Industrial Automation
Monitor Arm Market
Industrial Automation
North America Human Machine Interface Market
Industrial Automation
Smart Manufacturing Market
Industrial Automation
Industrial Fieldbus Solution Market
Industrial Automation
Robotic Paint Booth Market
Industrial Automation
Global Smart Warehousing Market