
 Rotary Vector (RV) Reducer Market | 2026-2036
Rotary Vector (RV) Reducer Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary Vector (RV) Reducer Market Insights
Robotics companies are reorganizing procurement priorities toward precision reducers capable of sub-arc-minute positioning repeatability. Nabtesco dominates cycloidal drive manufacturing for heavy-payload industrial arms, leveraging captive machining capacity in Japan's Aichi Prefecture. Harmonic Drive Systems competes through specialized strain-wave configurations optimized for collaborative robot joints. Zhongda Leader anchors domestic supply chains in China with backward integration into steel alloy forging for RV reducer housings.
A Rotary Vector (RV) Reducer transmits torque through cycloidal disc engagement with pin gears, achieving reduction ratios from 30:1 to 300:1 with positional accuracy below one arc-minute in precision configurations. Manufacturers machine the cycloidal profile from bearing steel or alloyed cast iron, then grind contact surfaces to sub-micron tolerances for zero-backlash operation in semiconductor wafer handling and surgical robotics. Precision reducers command the deepest margin pools where harmonic drive and cycloidal drive technologies overlap in seven-axis cobot wrist joints. Multi-axis reducers are accelerating fastest as integrators consolidate multiple degrees of freedom into compact actuator modules for mobile manipulator platforms.
Japan's METI enforces JIS B 8398 precision standards that constrain imported reducer qualification timelines for domestic robot OEMs. China's SAMR administers GB/T 12643 robot performance standards that now incorporate reducer backlash and torsional rigidity testing protocols. The EU Machinery Directive via CE marking mandates functional safety validation for reducers deployed in collaborative human-robot workspaces. Stakeholders must monitor how dual carbon goals in Beijing and Brussels reshape energy intensity requirements for precision gear grinding operations.
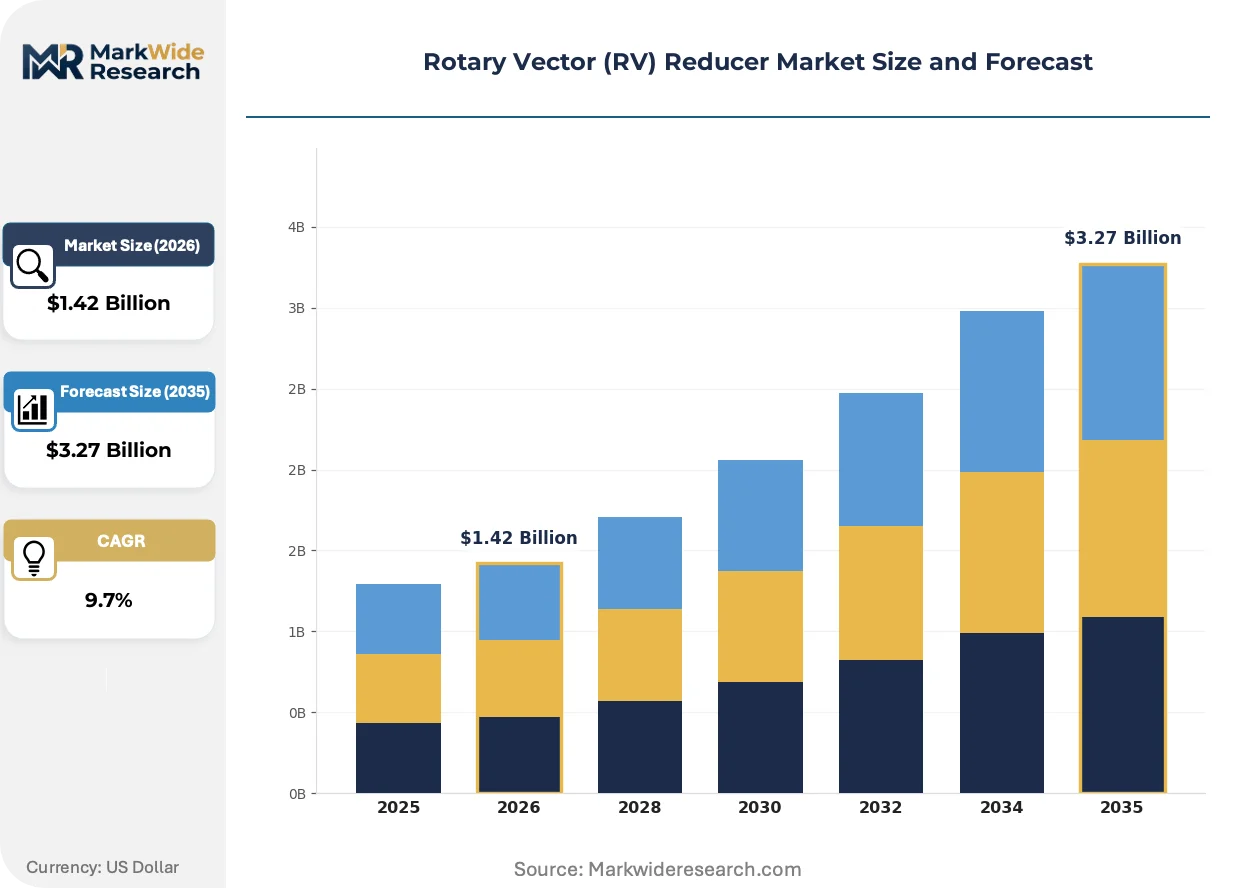
Market Dynamics
Precision motion control requirements in collaborative robotics are compressing qualification timelines for cycloidal and harmonic drive suppliers, forcing capital allocation toward sub-micron grinding capacity and captive bearing steel forging.
Growth Catalysts
- GB/T 12643 Backlash Protocols:China's SAMR-mandated torsional rigidity testing for industrial robots is disqualifying legacy reducer designs and opening procurement slots for certified precision manufacturers.
- Wafer Handling Automation:Semiconductor fabrication equipment builders in Japan's Nagoya corridor are specifying zero-backlash RV reducers for sub-arc-minute repeatability in vacuum chamber manipulators.
- Cycloidal Disc Material Advances:Alloyed bearing steel formulations with enhanced fatigue resistance are extending maintenance intervals for surgical robotics joints, reducing total cost of ownership for hospital capital equipment buyers.
Market Restraints
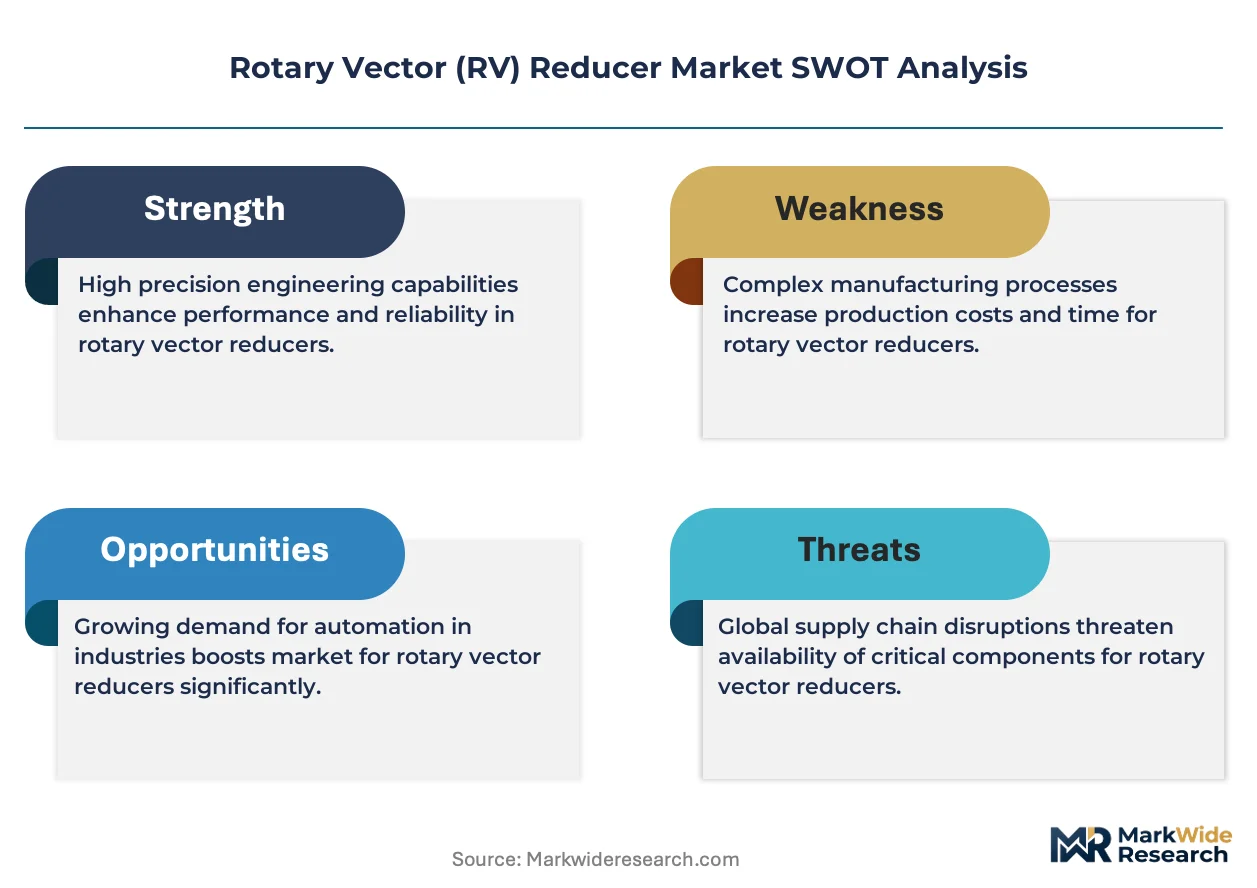
- Bearing Steel Price Volatility:Specialty alloy input costs fluctuate with nickel and chromium spot markets, compressing margin pools for mid-tier reducer assemblers lacking captive forging capacity.
- Aichi Prefecture Supply Concentration:Captive machining clusters around Nabtesco's Nagoya facilities create geographic single-point vulnerability for automotive robot OEMs dependent on just-in-time reducer delivery.
- Harmonic Drive Substitution:Strain-wave configurations achieve comparable reduction ratios in sub-50kg payload cobots, threatening RV reducer share in lightweight collaborative arm segments.
Strategic Opportunities
- India Industrial Automation:PLI scheme incentives for electronics manufacturing are attracting robot integrators seeking localized reducer supply chains outside established East Asian hubs.
- Mobile Manipulator Convergence:Autonomous mobile robot platforms with integrated seven-axis arms require compact multi-degree-of-freedom actuator modules, opening design wins for consolidated reducer-in-motor assemblies.
- EU Machinery Directive CE Pathways:Functional safety validation requirements for collaborative workspaces favor suppliers with pre-certified torque-limiting reducer architectures, accelerating qualification for European cobot builders.
Industry Challenges
- Precision Grinding Talent Scarcity:Sub-micron tolerance machining for cycloidal profiles requires specialized metrology skills concentrated in Japan and Germany, constraining capacity expansion in emerging manufacturing regions.
- JIS B 8398 Qualification Timelines:METI-enforced precision standards for domestic robot OEMs extend reducer validation cycles, delaying revenue recognition for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary Vector (RV) Reducer Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.27 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Axis Reducers, Multi-Axis Reducers, Precision Reducers, Heavy-Duty Reducers End User: Automotive OEMs, Aerospace Manufacturers, Robotics Companies, Industrial Equipment Suppliers Technology: Harmonic Drive, Cycloidal Drive, Planetary Drive, Worm Gear Drive Material: Aluminum, Steel, Plastic, Composite |
| Companies Covered | Nabtesco, Harmonic Drive Systems, Sumitomo Drive, SPINEA, Zhongda Leader, Shuanghuan Driveline, Qinchuan Machine Tool & Tool Group, Hengfengtai, Nantong Zhenkang, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary Vector (RV) Reducer Market Trends and Innovations
Electromechanical actuator architectures are converging toward integrated torque-density optimization, compressing the traditional separation between motor windings and reduction stages in precision robotics joints.
Integrated cycloidal-motor modules are fragmenting the conventional two-supplier model where discrete motor and reducer vendors interfaced through standardized flanges. Collaborative robot OEMs in Germany and Japan are consolidating procurement toward single-source compact actuators. This integration is fragmenting aftermarket service revenues and forcing legacy reducer specialists to develop in-house motor winding capabilities or exit the cobot wrist joint segment entirely.
China's dual carbon goals are tightening energy intensity benchmarks for precision gear grinding operations under MEE enforcement protocols. Grinding shops in Jiangsu and Zhejiang provinces face power rationing during peak demand periods, compressing effective machining capacity. Domestic reducer suppliers are responding by relocating forging operations to western provinces with surplus renewable generation, lengthening supply chains but securing operational continuity.
Robot integrators are consolidating vendor relationships toward qualified precision reducer suppliers with pre-archived safety documentation. Large automotive manufacturers in Detroit and Stuttgart are reducing their approved vendor lists from twelve to three certified cycloidal drive sources, prioritizing suppliers with ISO 10218-1 pre-certification. This concentration is most visible in North American electric vehicle battery assembly lines, where downtime penalties exceed the premium paid for qualified reducer supply security.
Rotary Vector (RV) Reducer Market Segmentation
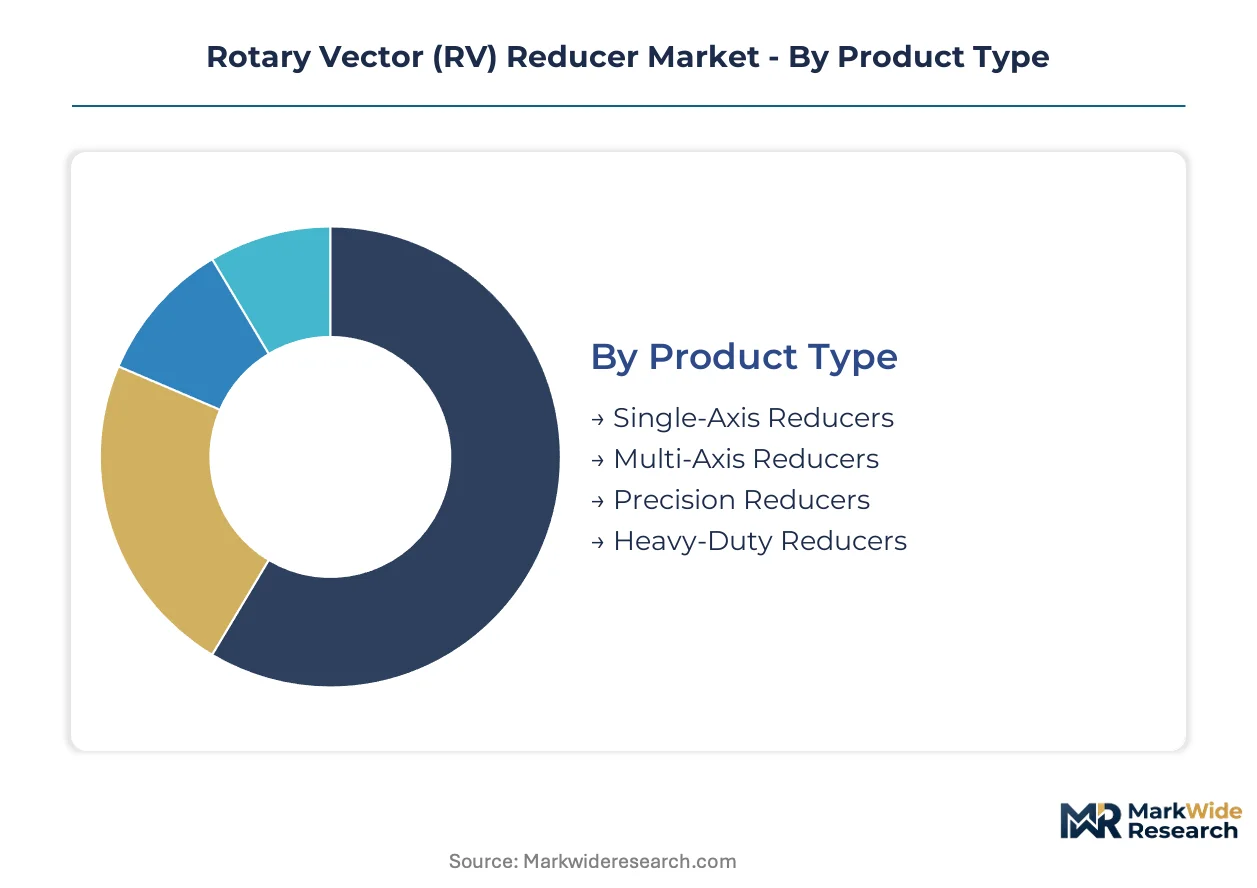
RV reducer segmentation reveals how cycloidal and harmonic drive technologies compete for positioning precision in collaborative robotics. Product architecture, end-use specialization, and material selection determine qualification timelines and margin capture across automotive, semiconductor, and surgical equipment supply chains.
Product Type:
Multi-axis reducers face the most acute substitution pressure as integrated actuator modules displace discrete reducer-motor pairings in cobot wrist joints.
- Multi-Axis Reducers:Consolidated actuator modules integrate two or three reduction stages into compact housings for seven-axis collaborative arms. Demand concentrates in Germany's cobot OEMs as integrators consolidate vendor relationships toward single-source supply.
- Precision Reducers:Zero-backlash configurations machined from bearing steel achieve sub-arc-minute repeatability for semiconductor wafer handling. Japan's Nagoya fabrication equipment builders specify these for vacuum chamber manipulators where positioning errors destroy wafer yields.
- Single-Axis Reducers:Discrete reduction stages for traditional industrial robot joints.
- Heavy-Duty Reducers:High-torque cycloidal drives for automotive welding and paint lines.
Multi-axis reducers retain volume leadership; precision reducers hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive precision specifications from price-sensitive volume procurement.
- Robotics Companies:Collaborative robot OEMs in Japan and Germany drive demand for compact, torque-dense actuators with ISO 10218-1 pre-certification. These buyers consolidate approved vendor lists from twelve sources to three qualified cycloidal drive suppliers to secure uptime guarantees.
- Automotive OEMs:Electric vehicle battery assembly lines in Detroit and Stuttgart specify heavy-duty RV reducers for welding and material handling. Downtime penalties exceed premiums paid for qualified supply security, favoring pre-certified vendors with archived safety documentation.
- Aerospace Manufacturers:Precision motion for satellite deployment and aircraft assembly.
- Industrial Equipment Suppliers:General automation and material handling systems.
Automotive OEMs retain volume leadership; robotics companies hold the steepest expansion curve.
Technology:
Application-specific performance requirements determine where cycloidal profiles outperform strain-wave alternatives.
- Cycloidal Drive:Torque transmission through eccentric cycloidal disc engagement with pin gears achieves 30:1 to 300:1 reduction ratios. Nabtesco anchors production in Japan's Aichi Prefecture for heavy-payload industrial arms where torsional rigidity exceeds harmonic drive capabilities.
- Harmonic Drive:Strain-wave configurations with flexible spline deformation achieve comparable reduction ratios in sub-50kg payload cobots. These threaten RV reducer share in lightweight collaborative arm segments where compactness outweighs absolute torque capacity.
- Planetary Drive:Concentric gear arrangements for moderate precision requirements.
- Worm Gear Drive:Right-angle torque transmission for space-constrained installations.
Cycloidal drive retains volume leadership; harmonic drive holds the steepest expansion curve.
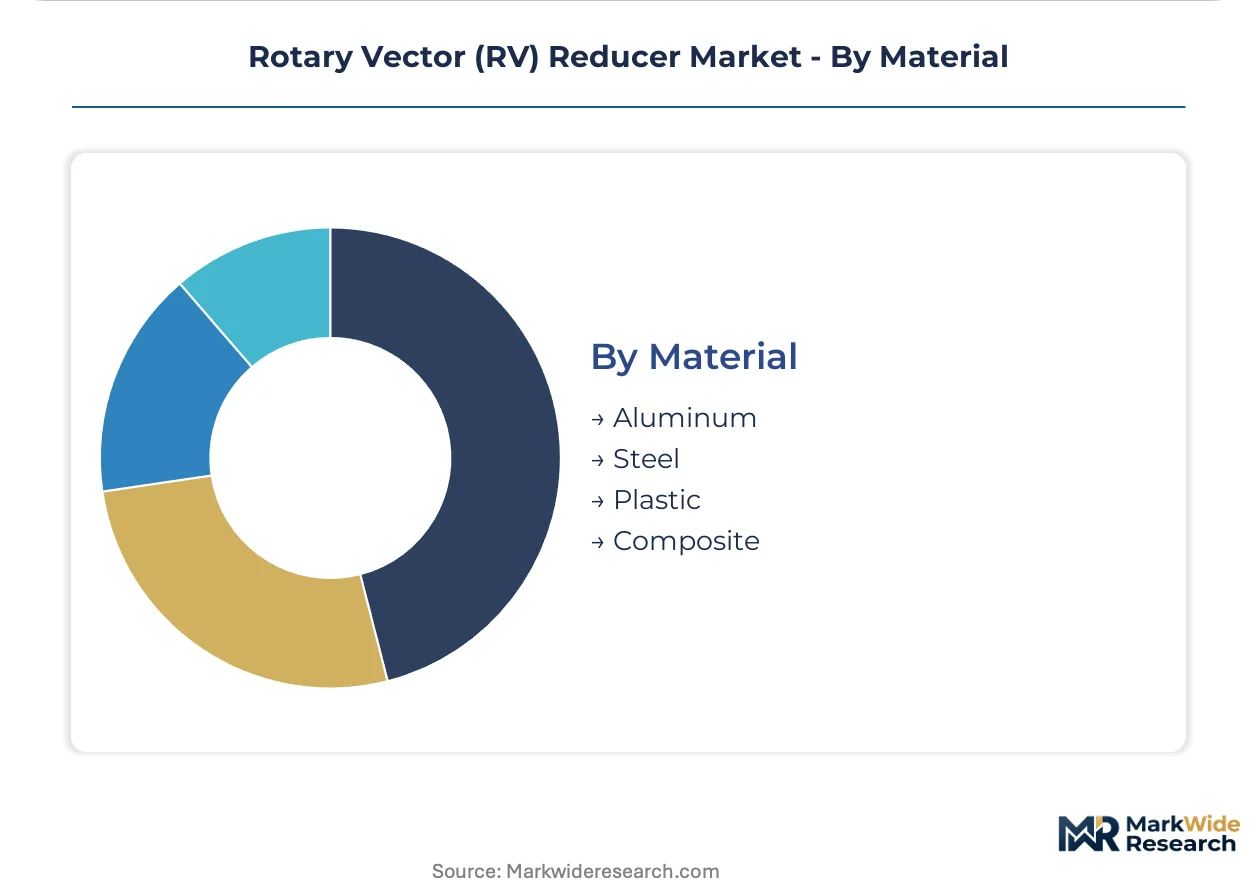
Material:
Supply concentration in East Asian forging capacity shapes procurement security for critical alloy inputs.
- Steel:Bearing steel and alloyed cast iron formulations dominate precision reducer machining. Zhongda Leader maintains backward integration into steel alloy forging for RV reducer housings, insulating against nickel and chromium spot market volatility.
- Aluminum:Lightweight housings for collaborative robot joints where payload minimization drives design.
- Composite:Emerging formulations for surgical robotics where magnetic transparency matters.
- Plastic:Cost-driven applications with minimal load requirements.
Steel retains volume leadership; aluminum holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Nagoya anchors Japan's precision machinery export corridor, handling cycloidal reducer shipments to automotive and semiconductor equipment builders across East Asia. This maritime infrastructure underwrites the geography's dominance in high-torque motion control components.
Japan
Automotive robot OEMs in Toyota City and semiconductor equipment builders in Nagoya drive demand for zero-backlash RV reducers. METI enforces JIS B 8398 precision standards that constrain imported reducer qualification timelines. Nabtesco's captive machining clusters in Aichi Prefecture supply just-in-time cycloidal drives to welding and paint line integrators.
China
Collaborative robot deployments in Shenzhen and EV battery assembly lines in Changzhou accelerate procurement of certified precision reducers. SAMR administers GB/T 12643 standards incorporating torsional rigidity testing protocols. Zhongda Leader maintains backward integration into steel alloy forging for RV reducer housings in Jiangsu Province.
Germany
Cobot OEMs in Munich and Stuttgart consolidate vendor relationships toward single-source compact actuators with ISO 10218-1 pre-certification. The EU Machinery Directive mandates functional safety validation for collaborative workspace deployments. Grinding specialists in Baden-Württemberg machine cycloidal profiles to sub-micron tolerances for surgical robotics joints.
United States
Electric vehicle battery assembly lines in Detroit specify heavy-duty RV reducers where downtime penalties exceed premiums for qualified supply security. OSHA workplace safety protocols intersect with collaborative robot deployment standards. Precision reducer distributors in Michigan maintain archived safety documentation for automotive OEM approved vendor lists.
South Korea
Display panel manufacturers in Gyeonggi Province and shipbuilding automation in Busan demand high-torque cycloidal drives for heavy-payload manipulators. MFDS medical device regulations shape specifications for surgical robotics joints. Seoul-based robot integrators qualify reducer suppliers through extended validation cycles for cleanroom wafer handling equipment.
Rotary Vector (RV) Reducer Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity tiers, with publicly traded Japanese and Chinese entities facing off against European and Korean private manufacturers. The vendor base stratifies into three tiers: integrated actuator developers, discrete reducer specialists, and captive forging-to-assembly operators. Strategic moves center on in-house motor winding capability acquisition and geographic relocation of grinding capacity to renewable-rich regions.
Within the integrated actuator tier, Nabtesco and Harmonic Drive Systems exemplify contrasting technology anchoring strategies, while Zhongda Leader occupies a position among vertically integrated Chinese specialists with upstream steel alloy control. These three represent the dominant archetypes: Japanese cycloidal dominance, harmonic strain-wave specialization, and Chinese backward-integrated forging capacity.
| Leading Market Players |
|---|
| Nabtesco |
| Harmonic Drive Systems |
| Sumitomo Drive |
| SPINEA |
| Zhongda Leader |
| Shuanghuan Driveline |
| Qinchuan Machine Tool & Tool Group |
| Hengfengtai |
| Nantong Zhenkang |
| Others |
Pricing and Supply Chain Analysis
Captive forging capacity in Japan's Aichi Prefecture and Jiangsu Province creates scale economies that compress unit costs for bearing steel alloy inputs while simultaneously elevating price floors for precision-ground cycloidal profiles. Automotive robot OEMs in Detroit and Stuttgart absorb premiums for qualified supply security that mid-tier assemblers cannot match, bifurcating the market between certified precision manufacturers and price-competitive volume suppliers.
Pricing Analysis
Three-tier pricing structure across precision-certified, standard-industrial, and economy-volume levels governs procurement contracts for RV reducers. Price differentiation rests on JIS B 8398 certification status and captive steel alloy forging capacity, with automotive OEMs least sensitive and logistics robot integrators most sensitive to unit cost. Pricing pressure stems from harmonic drive substitution in sub-50kg cobot segments, forcing cycloidal specialists to bundle preventive maintenance contracts to defend margin pools.
Supply Chain Analysis
Inbound logistics costs through the Port of Nagoya and Shanghai Yangshan terminals fluctuate with container availability on East Asia-North America trade lanes, compressing delivery windows for just-in-time automotive contracts. Geographic supply concentrates in Japan, China, and Germany, drawing from bearing steel alloy, precision grinding spindles, and specialized metrology equipment inputs. Single-source vulnerability around Nabtesco's Aichi machining clusters threatens automotive OEM uptime guarantees. Distribution runs through authorized distributor networks with archived safety documentation for CE and ISO 10218-1 pre-certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The RV reducer market rewards service-attach strategies where predictive maintenance contracts and spare-part subscription programs expand recurring revenue faster than hardware shipments. Aftermarket torque-monitoring diagnostics and remote vibration analysis packages penetrate semiconductor fabrication and surgical robotics accounts with the highest lifetime value profiles.
For Market Incumbents: Fortify captive bearing steel forging capacity in western China provinces with surplus renewable generation to insulate against MEE power-rationing enforcement. Nabtesco and Harmonic Drive Systems should accelerate in-house motor winding capability acquisition before integrated actuator modules fragment discrete reducer procurement entirely. METI qualification timeline extensions favor incumbents with pre-archived JIS B 8398 documentation. For New Entrants and Emerging Players: Aftermarket service-layer gaps in India's PLI-scheme electronics manufacturing corridor offer white-space entry where established East Asian suppliers lack localized grinding capacity. Target mobile manipulator platforms requiring compact multi-degree-of-freedom actuator modules, as integrators consolidate vendor relationships toward single-source supply. Pursue ISO 10218-1 pre-certification partnerships with German cobot OEMs to bypass extended validation cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated specialists with upstream steel alloy control and downstream actuator integration capabilities. Long-term viability hinges on renewable-energy-advantaged forging locations and grinding talent pipelines in Baden-Württemberg or Nagoya. Acquisition targets should demonstrate captive capacity in bearing steel formulations with enhanced fatigue resistance. Watch GB/T 12643 torsional rigidity testing protocol expansion as the signal for procurement slot redistribution toward certified precision manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bearing Steel Forging | Insulates margin pools from nickel and chromium spot market volatility in Jiangsu Province. |
| In-House Motor Winding Capability Acquisition | Preserves cobot wrist joint share as integrated actuator modules displace discrete reducers. |
| ISO 10218-1 Pre-Certification Investment | Accelerates qualification timelines for European automotive OEM approved vendor lists. |
| Relocation to Renewable-Rich Western China Provinces | Secures grinding capacity continuity under MEE energy intensity enforcement protocols. |
| Predictive Maintenance Service Launch | Captures recurring revenue from semiconductor wafer handling equipment uptime guarantees. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with precision reducer procurement managers at automotive OEMs, collaborative robot platform engineers, and semiconductor fabrication equipment builders; and secondary validation against METI JIS B 8398 filings, SAMR GB/T 12643 testing records, SEC 10-K equipment supplier disclosures, and customs trade data for bearing steel alloy shipments. Bottom-up unit demand modeling from end-use equipment production forecasts triangulated against top-down market sizing from reducer manufacturer revenue disclosures.
Across the projection horizon, the analytical framework modeled segmentation dimensions including product architecture (multi-axis, precision, single-axis, heavy-duty), end-use vertical (robotics, automotive, aerospace, industrial equipment), and technology type (cycloidal drive, harmonic drive, planetary, worm gear). CAGRs derived from equipment production growth rates, replacement cycle analysis, and content-per-unit assumptions for seven-axis cobot joints. Industry-specific forecast inputs incorporated PLI scheme incentive timelines in India and EV battery assembly line expansion in Detroit and Stuttgart.
Forecasts assume regulatory continuity in Japan's METI JIS B 8398 enforcement, China's SAMR GB/T 12643 expansion, and EU Machinery Directive CE marking pathways; material policy shifts tightening precision standards or carbon intensity benchmarks would require re-modeling. Specific risks include bearing steel price volatility, Aichi Prefecture supply concentration disruption, and harmonic drive technology substitution acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Smart Industries Market
Industrial Automation
Global System Integrator for Industrial Automation Market
Industrial Automation
Industrial Multiprotocol Gateways Market
Industrial Automation
HMI Market
Industrial Automation
Smart Warehouse System Market
Industrial Automation
Industrial Automation Motion Control System Software Market
Industrial Automation
Digital Transformation in Manufacturing Market
Industrial Automation
Industrial Human-Machine Interface Market
Industrial Automation
Utility Automation Market
Industrial Automation
Europe Industrial Automation Software Market
Industrial Automation
Smart Sorting Line Market
Industrial Automation
Global Healthcare Automation Market
Industrial Automation
Europe Warehouse Automation Systems Market
Industrial Automation
United States SCADA Market
Industrial Automation
France Factory Automation and Industrial Controls Market
Industrial Automation
South Korea Factory Automation and Industrial Controls Market