
 Utility Automation Market | 2026-2036
Utility Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Utility Automation Market Analytics
Municipal utilities is redrawing procurement priorities across the automation stack. ABB leverages its substation automation heritage to anchor European grid modernization programs. Siemens competes through integrated IoT-to-cloud platforms that span generation and distribution layers. Honeywell sustains North American market presence with field-hardened control systems for gas distribution networks.
Utility Automation encompasses the hardware, software, and communication infrastructure that monitors, controls, and optimizes electricity, water, and gas distribution networks through real-time data acquisition and remote actuation. SCADA Systems form the operational backbone, processing telemetry from thousands of field devices with sub-second latency requirements for fault isolation. Distribution Management Systems command the highest margin pools as utilities prioritize outage management and volt-var optimization over basic monitoring. Advanced Metering Infrastructure grows fastest where regulators mandate time-of-use pricing and demand-response programs. Substation Automation remains mature in developed grids but expands rapidly in markets replacing electromechanical relay infrastructure.
The EPA, FERC, and NERC CIP standards collectively shape product roadmaps by mandating encrypted communications, access logging, and incident reporting for critical infrastructure operators. EMA and EU AI Act frameworks in Europe impose algorithmic transparency requirements on automated grid decision systems. Stakeholders must weigh cybersecurity certification costs against the operational savings of autonomous fault recovery when selecting platform architectures.
Market Dynamics
SCADA-to-cloud migration is compressing procurement cycles as utilities replace electromechanical relay infrastructure with digital substation platforms. FERC Order 2222 and NERC CIP-013 reshape vendor qualification requirements, forcing automation suppliers to embed encrypted telemetry and access logging into base product architectures.
Growth Catalysts
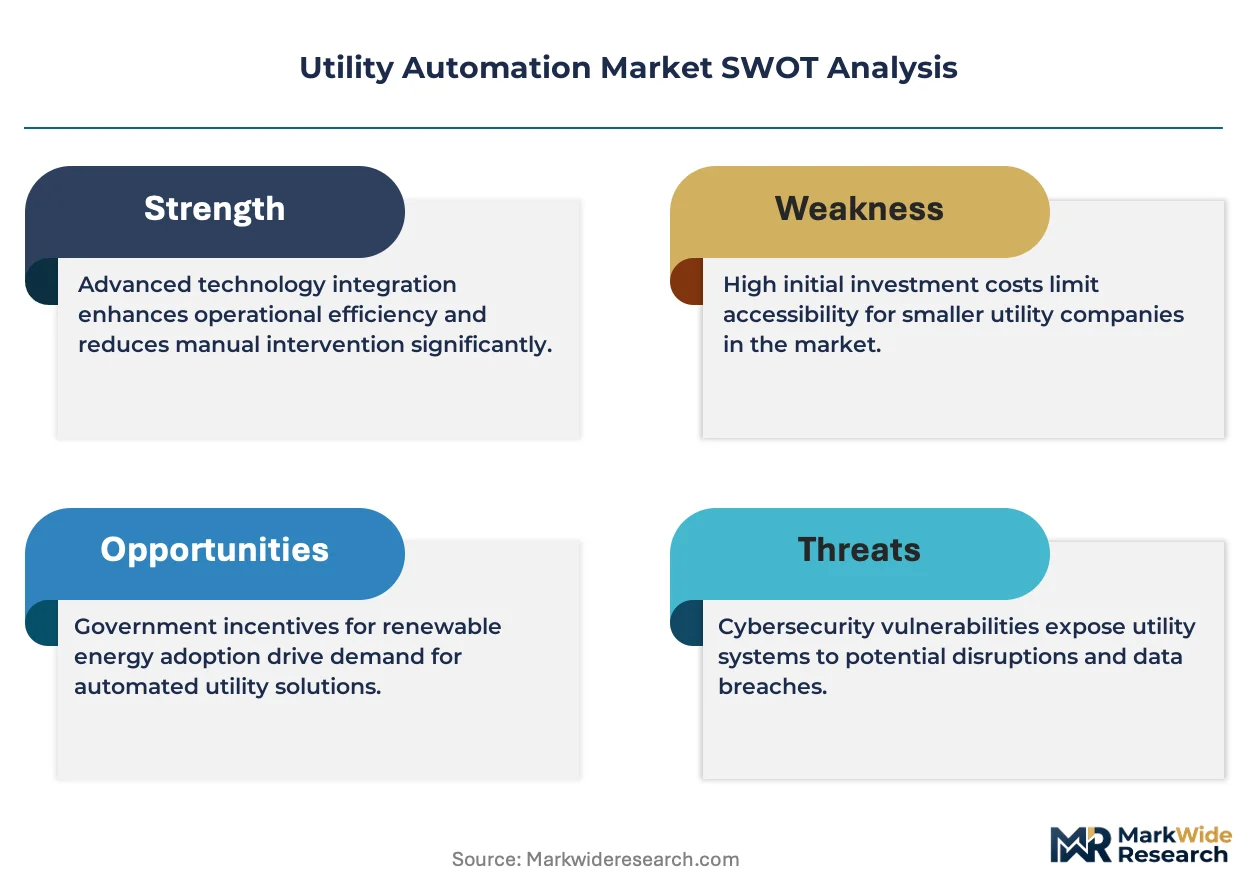
- NERC CIP Cybersecurity Mandates:Critical infrastructure operators must deploy encrypted communications and incident reporting systems, creating replacement demand across North American transmission networks.
- Germany's Grid Modernization Timelines:Industrial corridor utilities compress deployment schedules for distribution management systems to integrate renewable generation at scale.
- Time-of-Use Pricing Mandates:Regulators in multiple jurisdictions require advanced metering infrastructure to enable demand-response programs and dynamic tariff structures.
Market Restraints
- Semiconductor Supply Concentration:Field device manufacturers face input bottlenecks from concentrated Asian foundry capacity, extending lead times for RTU and PLC shipments.
- Copper and Rare Earth Volatility:Substation automation hardware depends on magnet materials and conductive metals subject to export restriction risks and price swings.
- Legacy Protocol Interoperability:DNP3 and Modbus installations create technical debt that slows cloud-native platform adoption in mature grids.
Strategic Opportunities
- India Smart City Programs:Municipal water utilities in rapidly urbanizing districts lack SCADA coverage, creating first-mover openings for integrated automation vendors.
- EU AI Act Algorithmic Transparency:Automated grid decision systems face new explainability requirements, favoring suppliers with embedded audit trail capabilities.
- Edge-to-Cloud Convergence:Utilities seek unified platforms merging substation edge computing with centralized analytics, displacing siloed legacy architectures.
Industry Challenges
- Cybersecurity Certification Timelines:NERC CIP compliance validation extends sales cycles by 8-14 months for new market entrants.
- OT-IT Integration Complexity:Engineering teams lack personnel fluent in both industrial control protocols and enterprise cloud security frameworks.
- Electromechanical Replacement Coordination:Scheduled outages for relay upgrades must align with seasonal demand peaks, constraining deployment windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Utility Automation Market |
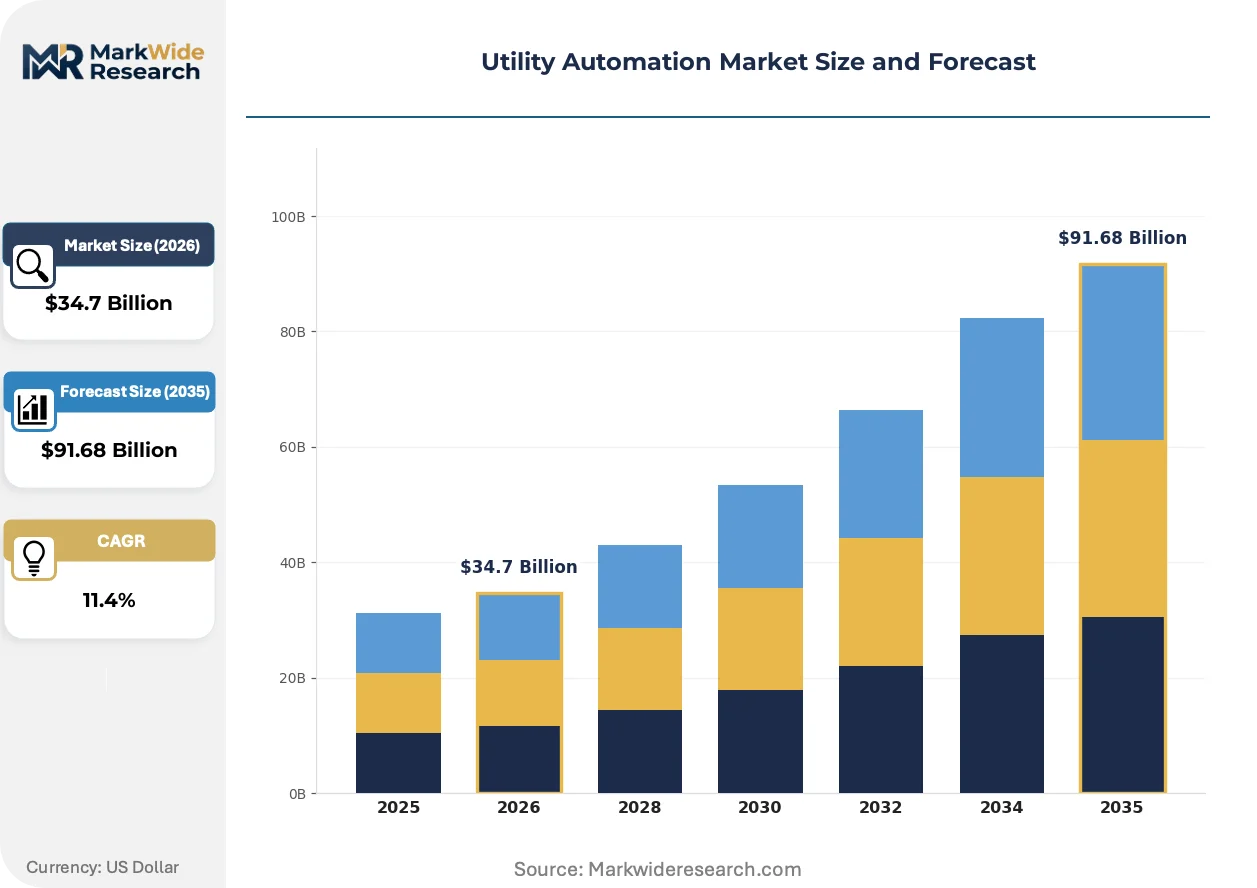
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $91.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SCADA Systems, Distribution Management Systems, Advanced Metering Infrastructure, Substation Automation Technology: IoT Solutions, Cloud Computing, Artificial Intelligence, Big Data Analytics End User: Electric Utilities, Water Utilities, Gas Utilities, Renewable Energy Providers Service Type: Consulting Services, System Integration, Maintenance Services, Managed Services |
| Companies Covered | Honeywell, Johnson Controls, ABB, Mitsubishi Electric, Yokogawa Electric, Schneider Electric, Rockwell Automation, OMRON Automation, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Utility Automation Market Evolving Landscape
Digital twin technology is displacing physical prototyping in substation design, while AI-driven predictive maintenance compresses fault response times. Regulatory pressure on algorithmic transparency and encrypted telemetry is reshaping product roadmaps across the automation stack.
Digital twin platforms for electrical substations are bifurcating the design-to-commissioning workflow. Transmission utilities in Germany and Texas deploy virtual replicas to simulate fault scenarios before hardware installation. This capability is bifurcating vendor competitive positions, separating suppliers with integrated simulation engines from those offering standalone SCADA without modeling layers.
EPA cybersecurity mandates for water sector critical infrastructure now require encrypted communications and access logging for all remote monitoring systems. Municipal utilities must retrofit existing SCADA deployments or face enforcement actions. Water treatment operators in the US Midwest are prioritizing vendors with pre-certified NERC CIP-013 compliant architectures to accelerate procurement timelines.
Outcome-based service contracts are displacing traditional hardware-plus-maintenance agreements in European distribution automation. Grid operators in France and the Netherlands now pay for guaranteed uptime and volt-var optimization performance rather than capital equipment. This shift concentrates vendor selection criteria on demonstrated operational track records rather than technical specifications alone.
Utility Automation Market Segmentation
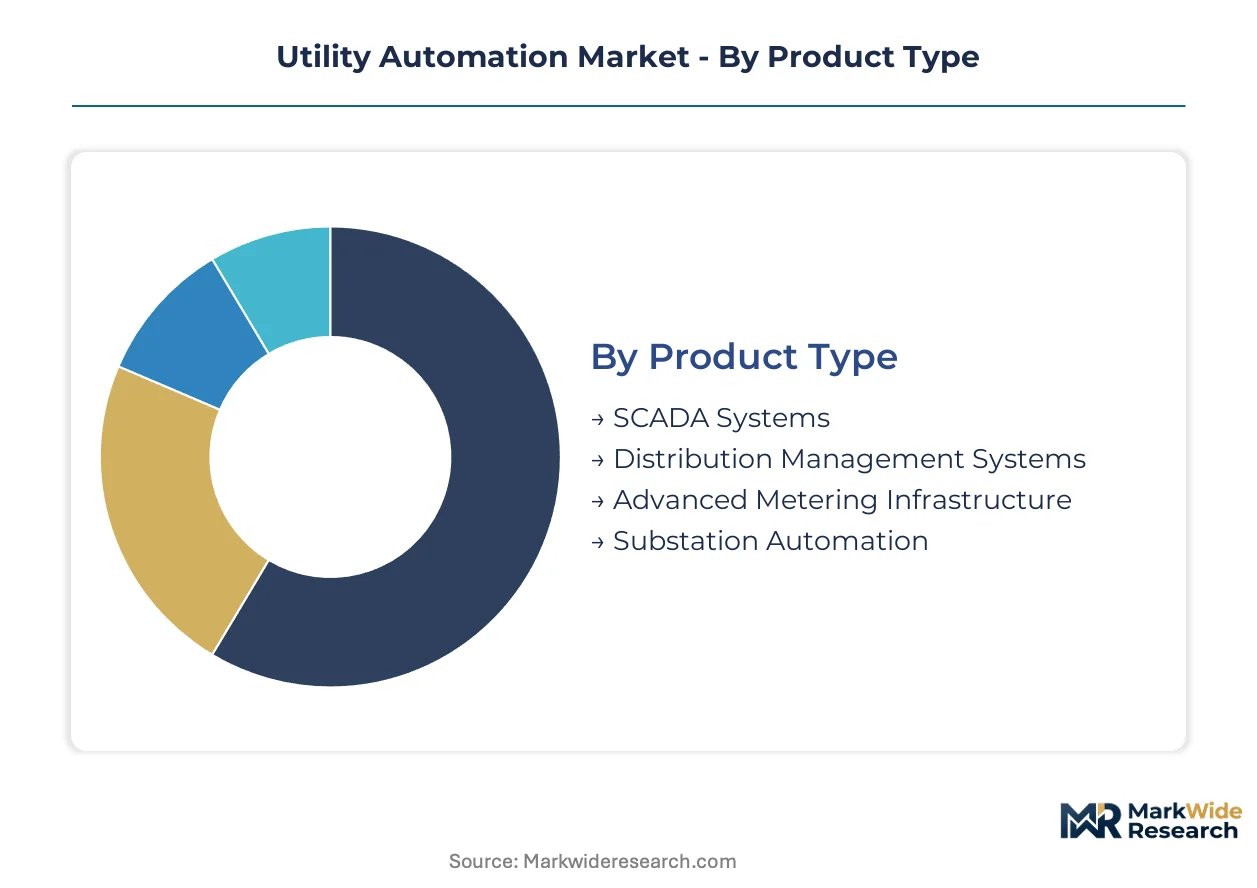
Segmentation in utility automation reveals distinct procurement patterns across infrastructure types and operational maturity. Technology choices diverge sharply between utilities modernizing legacy electromechanical systems and those building greenfield digital platforms from inception.
Product Type:
Domestic procurement dominates SCADA and substation automation, while distribution management systems see concentrated export demand from European grid operators.
- SCADA Systems:Real-time telemetry platforms processing field device data with sub-second latency for fault isolation. Water utilities across the US Midwest prioritize EPA-compliant encrypted architectures to avoid enforcement exposure.
- Distribution Management Systems:Outage management and volt-var optimization software commanding premium margins. German industrial corridor utilities compress deployment timelines to integrate renewable generation at scale.
- Advanced Metering Infrastructure:Time-of-use pricing enablement hardware mandated by regulators in multiple jurisdictions.
- Substation Automation:Digital relay and protection systems replacing electromechanical infrastructure in developing markets.
SCADA Systems holds the largest share; momentum sits with Distribution Management Systems.
Technology:
Cost tiers separate pilot-scale deployments from production-grade implementations, with cloud and AI solutions carrying 3-4x integration overhead against established protocols.
- IoT Solutions:Sensor networks and edge devices enabling distributed monitoring across transmission and distribution networks. Gas utilities in North America deploy field-hardened control systems for leak detection and pressure management.
- Cloud Computing:Centralized analytics platforms aggregating substation edge data with enterprise systems. Municipal utilities face 8-14 month sales cycle extensions for NERC CIP compliance validation.
- Artificial Intelligence:Predictive maintenance and autonomous fault recovery algorithms subject to EU AI Act transparency requirements.
- Big Data Analytics:Pattern recognition systems processing historical telemetry for load forecasting and asset optimization.
IoT Solutions commands current deployment volumes; Artificial Intelligence is climbing the fastest as algorithmic transparency mandates reshape vendor selection.
End User:
Customer type determines procurement authority structure, with municipal water utilities accelerating capital programs against regulated return frameworks governing electric and gas operators.
- Electric Utilities:Transmission and distribution operators managing generation intermittency and grid stability. FERC Order 2222 aggregation mandates drive distributed energy resource integration investments.
- Water Utilities:Municipal treatment and distribution operators facing EPA cybersecurity mandates for critical infrastructure protection.
- Gas Utilities:Pipeline and distribution network operators prioritizing leak detection and pressure optimization.
- Renewable Energy Providers:Solar and wind farm operators requiring grid code compliance and forecasting integration.
Electric Utilities retains dominant procurement volumes; Renewable Energy Providers is gaining share fastest on capacity addition timelines.
Service Type:
Supply concentration favors established system integrators with certified cybersecurity architectures over boutique consulting firms.
- Consulting Services:Grid modernization strategy and regulatory compliance advisory. European operators seek algorithmic transparency expertise under EU AI Act frameworks.
- System Integration:OT-IT convergence implementation requiring personnel fluent in industrial protocols and cloud security.
- Maintenance Services:Scheduled and reactive support for electromechanical relay infrastructure approaching replacement windows.
- Managed Services:Outcome-based uptime and performance guarantees displacing traditional hardware-plus-maintenance agreements in France and the Netherlands.
System Integration represents the largest addressable pool; Managed Services shows steepest expansion trajectory on performance contracting adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The NordLink interconnector underwrites Germany's role as the continent's grid modernization laboratory, channeling Norwegian hydroelectric capacity into industrial load centers while compressing automation deployment timelines.
United States
FERC Order 2222 aggregation mandates and NERC CIP-013 cybersecurity standards drive procurement of encrypted telemetry architectures across transmission networks. The EPA's critical infrastructure mandates for water utilities accelerate SCADA replacement cycles in the Midwest industrial corridor. Chicago-based municipal operators prioritize pre-certified compliance frameworks to sidestep enforcement exposure.
Germany
Industrial corridor utilities compress distribution management system deployment schedules to integrate renewable generation at scale. The EU AI Act imposes algorithmic transparency requirements on automated grid decision systems, reshaping vendor qualification criteria. The Ruhr Valley automation cluster concentrates substation digitalization investments as electromechanical relay infrastructure reaches replacement windows.
China
Dual carbon policy targets and ultra-high voltage transmission expansion create demand for digital substation platforms across provincial grid operators. MIIT cybersecurity standards for critical infrastructure mandate encrypted communications and access logging for remote monitoring systems. The Yangtze River Delta manufacturing belt anchors domestic production of field-hardened control systems for gas distribution networks.
India
Rapid urbanization and Smart Cities Mission funding expose gaps in municipal water utility SCADA coverage across rapidly expanding districts. CEA grid code compliance requirements for renewable integration drive distribution automation investments in solar-rich states. The Gujarat industrial corridor concentrates first-mover procurement of integrated automation vendors serving greenfield digital platform deployments.
Japan
Grid stability imperatives from nuclear generation reduction accelerate substation automation investments across regional transmission operators. METI critical infrastructure protection standards mandate incident reporting and encrypted telemetry for control systems. The Kanto-Tokyo metropolitan cluster concentrates demand-response program enablement through advanced metering infrastructure deployments.
Utility Automation Market Competitive Landscape
Concentration sits with diversified industrial conglomerates possessing certified cybersecurity architectures and legacy protocol expertise. The vendor base stratifies across three tiers: integrated platform providers spanning generation through distribution, specialized substation automation houses, and regional system integrators with regulatory compliance capabilities. Dominant competitive moves include strategic partnerships bridging OT-IT convergence gaps and portfolio diversification into outcome-based managed services.
Among diversified European industrial groups, ABB, Siemens, and Schneider Electric occupy positions reflecting distinct automation heritage paths. ABB anchors the substation automation vector through legacy protection relay expertise. Siemens exemplifies the integrated IoT-to-cloud platform archetype spanning generation and distribution layers. Schneider Electric represents the energy management optimization tier with field device-to-software integration capabilities.
| Leading Market Players |
|---|
| Honeywell |
| Johnson Controls |
| ABB |
| Mitsubishi Electric |
| Yokogawa Electric |
| Schneider Electric |
| Rockwell Automation |
| OMRON Automation |
| Siemens |
| Others |
Value Network & Pricing Analysis
NERC CIP-013 certification gates simultaneously constrain supplier qualification and stratify price tiers across the automation stack. Utilities in the US Midwest pay premiums for pre-certified architectures that compress procurement timelines, while uncertified vendors absorb validation costs or exit transmission network tenders entirely.
Pricing Analysis
Volume-discount tiering structures separate municipal water utilities purchasing SCADA at scale from smaller gas distribution operators acquiring field-hardened control systems in project-based increments. Pricing stratifies across premium, standard, and economy tiers based on cybersecurity certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying because semiconductor input bottlenecks force vendors to absorb margin erosion. Municipal water utilities exhibit highest price sensitivity due to capital budget constraints, while German industrial corridor utilities prioritize performance guarantees over unit economics.
Supply Chain Analysis
Extended lead times for RTU and PLC shipments expose inventory vulnerability across North American automation deployers. Manufacturing concentrates in Germany, Japan, and China, with magnet materials and conductive metals drawing from concentrated Asian foundry capacity. Single-source vulnerability sits with rare earth processing dependencies. Distribution runs through certified system integrators with NERC CIP compliance capabilities rather than direct vendor-to-utility channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified personnel fluent in both industrial control protocols and enterprise cloud security frameworks remain scarcer than capital across this market. The capability gap between OT heritage and IT convergence demands shapes competitive outcomes more than raw R&D spending.
For Market Incumbents: Secure backward integration into semiconductor sourcing to insulate margin positions against foundry concentration risks. Anchor European grid modernization programs through pre-certified EU AI Act compliant architectures that emerging entrants cannot replicate within validation timelines. Prioritize Germany's industrial corridor for capacity expansion given compressed deployment schedules.
For New Entrants and Emerging Players: Lead with algorithmic transparency audit trail capabilities that incumbent legacy stacks lack, targeting EU markets where the AI Act reshapes vendor qualification. Municipal water utilities in India's rapidly urbanizing districts present the most penetrable white space given SCADA coverage gaps. Pursue outcome-based managed services contracts to bypass capital equipment procurement barriers.
For Investors and Strategic Acquirers: NERC CIP-013 enforcement acceleration reshapes the acquisition landscape toward vendors with embedded compliance architectures rather than retrofit-capable portfolios. Five-to-ten year viability favors system integrators possessing both OT protocol expertise and cloud security certification. Watch EPA enforcement actions against non-compliant water utilities as the inflection signal for replacement demand timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Sourcing | Mitigates foundry concentration risks that extend RTU lead times for North American deployers. |
| EU AI Act Compliance Certification | Accelerates vendor qualification for German industrial corridor distribution management tenders. |
| Outcome-Based Managed Services Launch | Displaces hardware-plus-maintenance agreements in France and Netherlands grid operator procurement. |
| Digital Twin Platform Integration | Bifurcates competitive position between suppliers with simulation engines and standalone SCADA vendors. |
| India Smart City Partnership | Captures first-mover position in municipal water SCADA gaps across rapidly urbanizing districts. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FERC filings, EPA enforcement databases, EIA grid investment data, and EU regulatory transparency portals. Utility planning officers, substation automation engineers, cybersecurity compliance leads at transmission operators, and procurement directors at municipal water utilities provided operational perspective. Bottom-up project pipeline assessment triangulates against top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled span product type, technology tier, end-user vertical, and service delivery mode throughout the forecast period. CAGRs derive from regression analysis against historical deployment velocity and regulatory mandate timelines. Forecast inputs incorporate renewable integration targets and cybersecurity compliance acceleration curves without assuming linear adoption patterns.
Underlying assumptions cover stable regulatory enforcement intensity and continued semiconductor supply normalization, with deviation risk concentrated in tariff exposure on magnet materials and export restriction escalations. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Geosteering Technology Market
Industrial Automation
Asia Pacific Manufacturing Execution Systems (MES) Market
Industrial Automation
Global Warehouse Automation Market
Industrial Automation
Switzerland Industrial Automation Market
Industrial Automation
Global Blasting Automation Services Market
Industrial Automation
Smart Sorting Line Market
Industrial Automation
Cross-Belt Sorters Market
Industrial Automation
South Korea Factory Automation and Industrial Controls Market
Industrial Automation
Robotic Paint Booth Market
Industrial Automation
North America Automated Rotary Indexing Table Market
Industrial Automation
North America Smart Manufacturing Market
Industrial Automation
Industrial Automation Software Market
Industrial Automation
North America Industrial Vending Machine Market
Industrial Automation
United Kingdom Factory Automation and Industrial Control Systems Market
Industrial Automation
Warehouse Automation Systems Market
Industrial Automation
Factory Automation in Japan Market