
 Industrial Automation Motion Control System Software Market | 2026-2036
Industrial Automation Motion Control System Software Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Automation Motion Control System Software Market Insights
Germany's industrial automation corridor is fragmenting as regional software ecosystems compete for dominance in precision manufacturing. Siemens AG leverages its embedded PLC and motion controller integration to sustain engineering loyalty across European automotive plants. ABB Ltd anchors its position through robotics-centric software stacks that dominate high-speed packaging lines. Rockwell Automation differentiates via FactoryTalk platforms that control material handling workflows in North American manufacturing facilities.
Industrial automation motion control system software comprises programmable algorithms and real-time operating environments that coordinate motor drives, servo systems, and actuators through deterministic communication cycles measured in sub-millisecond response times. Its primary purpose is to synchronize multi-axis machinery with repeatable positioning accuracy for continuous production environments. CNC software retains the largest installed base among product types due to decades of machine tool penetration, though motion controllers are capturing the fastest expansion as cobot deployments multiply. EtherCAT technology leads new protocol adoption because its distributed clock architecture eliminates jitter in robotics applications where nanosecond synchronization prevents collision errors.
FDA validation requirements for pharmaceutical manufacturing software and EU Machinery Directive safety integrity standards are compelling vendors to embed certified functional safety modules directly into motion control platforms. OSHA lockout-tagout interoperability rules in the United States and Japan's METI-led Smart Manufacturing initiatives are further segmenting compliance architectures by geography. Stakeholders must evaluate whether to maintain region-specific certification portfolios or pursue unified safety stacks that satisfy multiple regulator test suites simultaneously.
Market Dynamics
Deterministic communication cycles measured in sub-millisecond response times are compressing engineering margins as automotive OEMs demand nanosecond synchronization for electric vehicle powertrain assembly. This precision threshold is forcing software vendors to embed certified functional safety modules directly into motion control platforms.
Growth Catalysts
- EU Machinery Directive:CE marking requirements are compelling manufacturers toward certified, interoperable control platforms that embed safety integrity standards directly into motion architectures.
- Electric vehicle powertrain assembly:Automotive OEMs are expanding adoption of precision motion control software for multi-axis synchronization in battery module and motor assembly lines.
- EtherCAT protocol:Its distributed clock architecture eliminates jitter in robotics applications where nanosecond synchronization prevents collision errors in cobot deployments.
Market Restraints
- Silicon carbide supply concentration:Motion controller hardware depends on concentrated sourcing of wide-bandgap semiconductors from limited foundry capacity.
- FDA validation timelines:Pharmaceutical manufacturing software requires 18-36 month certification cycles that delay platform releases and freeze engineering roadmaps.
- Legacy PLC protocol lock-in:Decades of proprietary fieldbus installations create switching costs that retard migration to open real-time Ethernet standards.
Strategic Opportunities
- India's PLI scheme for manufacturing:Production-linked incentives for advanced manufacturing are attracting motion control vendors to establish localized software development centers.
- Edge-AI convergence:Machine learning inference engines are hybridizing with deterministic control loops to enable predictive vibration suppression in high-speed packaging lines.
- Japan METI Smart Manufacturing:National initiatives are mandating OPC-UA interoperability standards that create openings for certified middleware vendors.
Industry Challenges
- Real-time systems engineering scarcity:The talent pool for deterministic kernel programming and FPGA-based motion algorithms remains critically thin across all major industrial clusters.
- Multi-standard certification burden:Vendors must maintain parallel safety stacks for OSHA lockout-tagout interoperability, EU Machinery Directive SIL ratings, and Japan's JIS functional safety grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Automation Motion Control System Software Market |
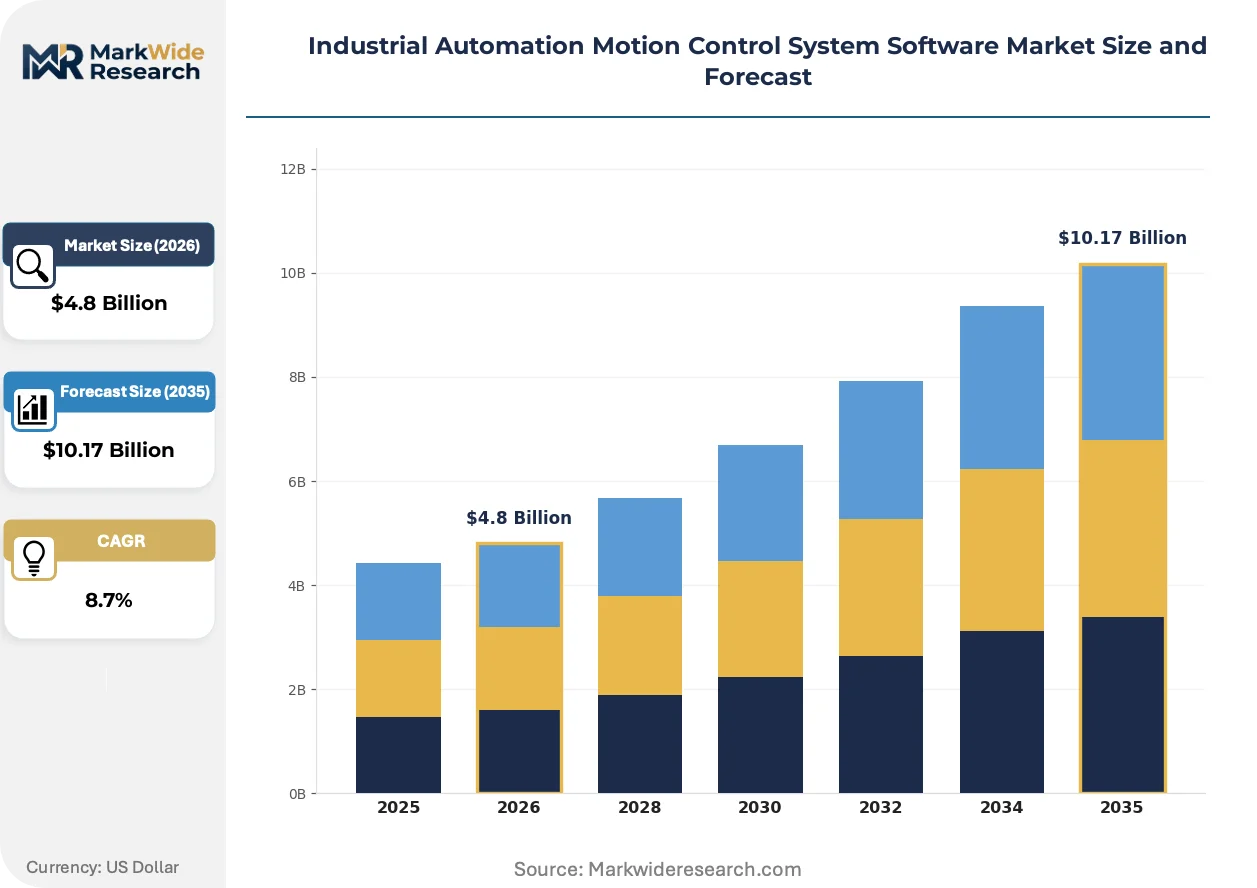
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLC, CNC, SCADA, Motion Controllers Technology: EtherCAT, CANopen, Modbus, Profibus Application: Robotics, Packaging, Assembly, Material Handling End User: Manufacturing, Automotive OEMs, Aerospace, Food & Beverage |
| Companies Covered | Siemens AG, ABB Ltd, Schneider Electric SE, Emerson Electric Co, Rockwell Automation, FANUC Corporation, Yaskawa Electric Corporation, Mitsubishi Electric Corporation, OMRON Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Automation Motion Control System Software Market Trends and Innovations
Motion control software architectures are fragmenting along real-time performance tiers as deterministic requirements diverge between precision manufacturing and adaptive robotics. This bifurcation is compressing vendor R&D priorities and reshaping partnership strategies across the industrial automation stack.
Time-sensitive networking (TSN) extensions to standard Ethernet is hybridizing industrial communication by merging IT infrastructure economics with OT determinism. Automotive battery manufacturers in Germany and South Korea are adopting TSN-enabled motion controllers to unify factory networks while preserving microsecond synchronization for electrode winding processes. This convergence is collapsing the traditional separation between enterprise resource planning layers and shop-floor control systems.
The EU AI Act's risk classification framework is mandating conformity assessments for autonomous motion systems deployed in safety-critical manufacturing environments. Machinery builders exporting to European automotive plants must now document algorithmic transparency and fail-safe behavioral boundaries for AI-enhanced path planning. High-speed packaging line OEMs are responding by segregating certified safety kernels from optional AI optimization modules to isolate regulatory scope.
After-sales service unbundling is accelerating as end-users demand modular software subscriptions separate from hardware maintenance contracts. German automotive tier-1 suppliers are negotiating per-axis licensing for motion algorithms rather than perpetual platform purchases, compressing vendor revenue recognition timelines. This shift is most visible in Stuttgart's industrial automation cluster, where powertrain assembly specialists are piloting usage-based billing for servo tuning and vibration analysis tools.
Industrial Automation Motion Control System Software Market Segmentation
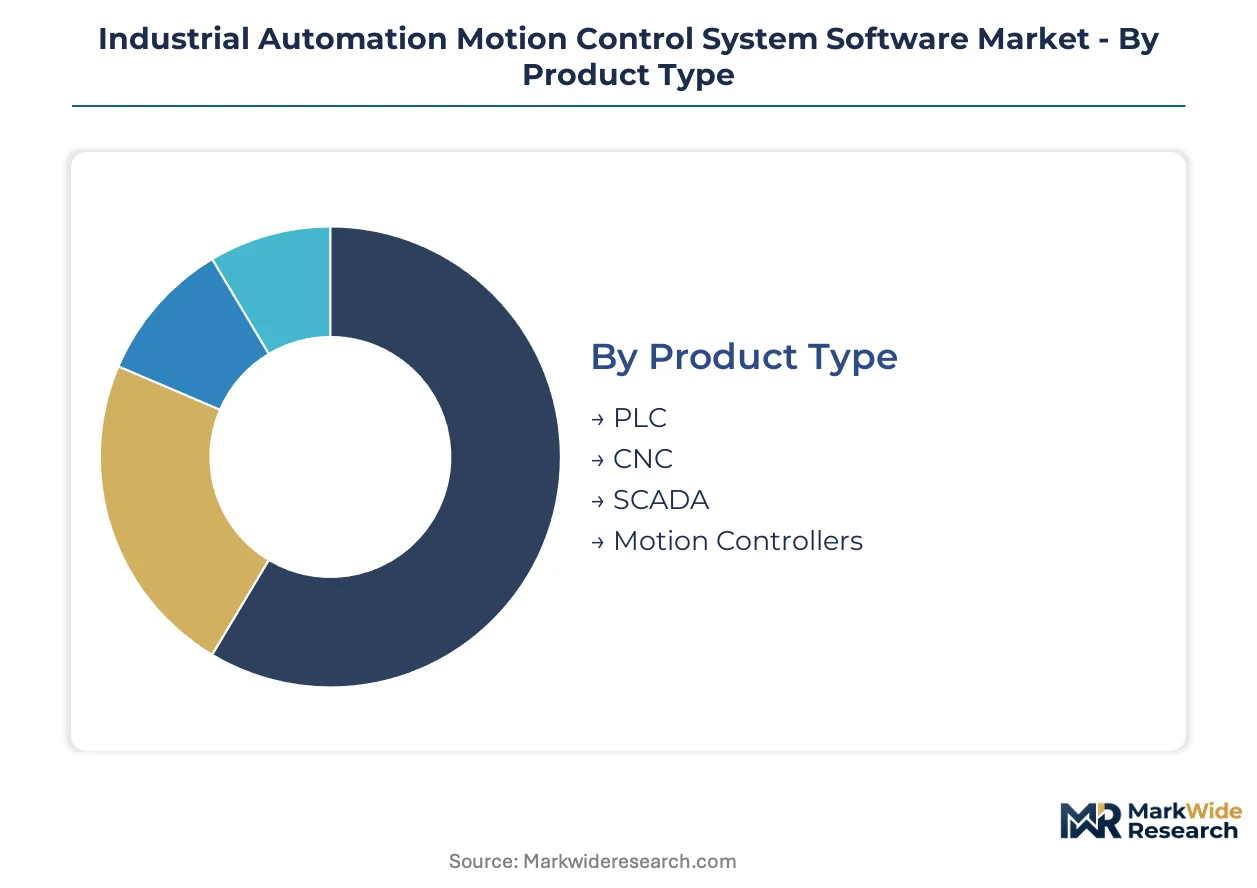
Segmentation in industrial automation motion control software reveals how deterministic performance requirements fragment across machinery types, communication protocols, and end-use precision thresholds. Each dimension carries distinct certification burdens and engineering talent demands that reshape vendor priorities.
Product Type:
Engineering teams select control platforms based on axis complexity, synchronization tolerance, and legacy infrastructure integration requirements.
- CNC:G-code execution engines govern multi-axis machine tools with interpolated path planning and spindle synchronization. Demand concentrates in Germany's automotive die-mold sector where micrometer-grade surface finishes require deterministic trajectory lookahead algorithms.
- Motion Controllers:Dedicated servo coordination platforms execute sub-millisecond position loops for robotics and packaging lines. Cobot deployments in Stuttgart's powertrain assembly plants are driving adoption where nanosecond distributed clock synchronization prevents collision errors.
- PLC:General-purpose logic controllers with motion modules serve material handling and conveyor systems where moderate precision tolerates millisecond-level jitter.
- SCADA:Supervisory layers aggregate motion status data across plant networks, prioritizing visualization and alarm management over real-time determinism.
The dominant share belongs to CNC, while motion controllers are closing the gap fastest.
Technology:
Protocol selection locks in hardware ecosystems and determines synchronization granularity for multi-axis coordination.
- EtherCAT:Distributed clock architecture achieves sub-microsecond jitter across 100+ node networks without dedicated motion cards. South Korean battery manufacturers and German automotive plants are standardizing on this protocol for electrode winding and powertrain assembly where drift corrupts process quality.
- Profibus:Legacy fieldbus retains installed base in European process industries with certified safety profiles for SIL-rated machinery.
- CANopen:Low-cost multi-drop bus serves compact servo drives in packaging machinery and mobile robotics where node counts stay below 50.
- Modbus:Simple master-slave protocol persists in material handling retrofits and cost-constrained conveyor systems with loose synchronization requirements.
EtherCAT commands the fastest expansion trajectory as TSN convergence collapses IT-OT network separation.
Application:
Precision thresholds and cycle time pressures create divergent software architecture requirements across machinery categories.
- Robotics:Six-axis path planning with collision avoidance and force-torque feedback integration dominates automotive welding and cobot assembly. FDA validation requirements for surgical robot OEMs extend software certification timelines.
- Packaging:High-speed flying shear and rotary knife applications demand electronic cam profiling with microsecond registration correction for print-to-cut alignment.
- Assembly:Press-fit and threaded fastening operations require force-limited motion with torque-angle signature validation for quality traceability.
- Material Handling:Crane and AGV coordination prioritizes throughput optimization over positional repeatability, accepting looser synchronization tolerances.
Robotics captures the deepest engineering investment, though packaging applications are scaling fastest with servo-driven format changeover demands.
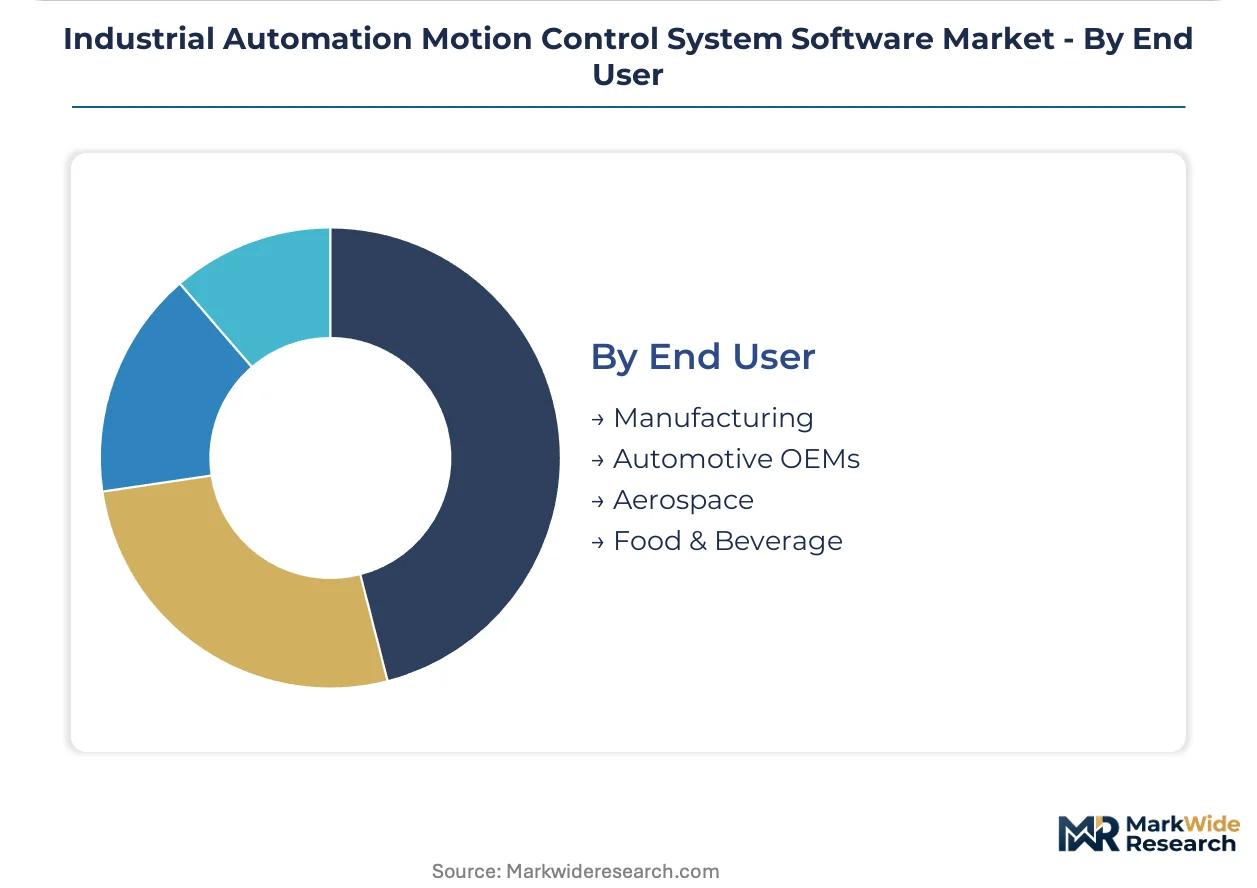
End User:
Regulatory environments and production economics segment software procurement across verticals with divergent safety integrity requirements.
- Automotive OEMs:Powertrain and battery assembly lines mandate OPC-UA interoperability and EU Machinery Directive CE marking for multi-vendor line integration. Stuttgart and Munich clusters concentrate procurement authority.
- Aerospace:AS9100 quality systems and FAA traceability requirements impose documentation burdens on motion software used in composite layup and machining centers.
- Food & Beverage:USDA sanitary design standards and washdown-rated hardware compatibility constrain controller selection for filling and packaging lines.
- Manufacturing:General machinery builders balance cost and performance across metal fabrication, plastics, and textile applications with fragmented compliance requirements.
Automotive OEMs anchor platform development roadmaps, while aerospace qualification cycles create the steepest vendor margin compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Machinery Directive anchors European procurement standards, yet demand generation now spans three continents as automotive electrification and battery manufacturing reshape geographic priorities.
Germany
Automotive OEMs in Stuttgart and Munich drive precision motion control procurement for electric vehicle powertrain assembly. CE marking requirements under the EU Machinery Directive compel vendors to embed certified functional safety modules into control platforms. Baden-Württemberg's industrial automation cluster concentrates engineering talent and vendor development centers.
United States
OSHA lockout-tagout interoperability rules segment compliance architectures for material handling and packaging line deployments. The FDA's 18-36 month validation timelines for pharmaceutical manufacturing software delay platform releases and freeze vendor roadmaps. Michigan and Ohio automotive corridors anchor North American demand for multi-axis synchronization systems.
China
Battery manufacturers in the Yangtze River Delta and Pearl River Delta adopt EtherCAT-enabled motion controllers for electrode winding processes. MIIT industrial internet initiatives mandate OPC-UA interoperability standards that reshape middleware procurement. Shenzhen and Shanghai concentrate domestic motion control software development.
Japan
METI-led Smart Manufacturing initiatives mandate OPC-UA interoperability standards that create openings for certified middleware vendors. FANUC and Yaskawa anchor domestic robotics-centric software stacks for high-speed automation. The Chubu region around Nagoya retains concentrated machine tool and automotive component manufacturing demand.
South Korea
Battery manufacturers standardize on EtherCAT protocol distributed clock architectures for nanosecond synchronization in electrode winding. MFDS pharmaceutical regulations extend software certification requirements for medical device manufacturing. The Busan-Ulsan industrial corridor concentrates shipbuilding and heavy machinery motion control applications.
Industrial Automation Motion Control System Software Market Competitive Landscape
Capability concentration sits with European engineering conglomerates; scale advantage sits with diversified automation multinationals. Siemens AG and ABB Ltd anchor the premium tier through embedded PLC integration and robotics-centric stacks respectively. Rockwell Automation occupies the North American manufacturing workflow segment. Two strategic archetypes dominate: integrated platform vendors bundling hardware-software stacks, and specialized motion controller firms targeting cobot deployments. Competitive moves concentrate on strategic partnerships for TSN convergence and portfolio diversification into edge-AI modules.
Among European-based engineering conglomerates, Siemens AG and ABB Ltd exemplify the integrated platform archetype through their embedded control and robotics software positions. Rockwell Automation represents the North American manufacturing workflow specialization. These three anchors illustrate how geographic regulatory alignment—EU Machinery Directive compliance, OSHA interoperability, FDA validation—shapes competitive positioning without requiring identical capability investments.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd |
| Schneider Electric SE |
| Emerson Electric Co |
| Rockwell Automation |
| FANUC Corporation |
| Yaskawa Electric Corporation |
| Mitsubishi Electric Corporation |
| OMRON Corporation |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in South Korean battery manufacturing is compressing motion controller hardware margins while concentrating pricing power among EtherCAT protocol licensors. This utilization asymmetry forces software vendors to unbundle after-sales service contracts from hardware sales to preserve revenue recognition timelines.
Pricing Analysis
German automotive OEMs pay 40-60% premiums for CE-marked safety-integrated platforms versus standard motion controllers sold into Asian battery manufacturing. Three-tier pricing structure across safety-certified, performance-optimized, and basic configuration levels dominates procurement negotiations. Pricing pressure stems from India's PLI scheme attracting localized software development centers with cost-competitive engineering talent. Tier-2 packaging machinery builders exhibit highest price sensitivity, while pharmaceutical OEMs absorbing FDA validation costs show lowest.
Supply Chain Analysis
Tariff exposure between China and the United States dominates silicon carbide semiconductor sourcing strategies for motion controller hardware. Wide-bandgap semiconductor fabrication concentrates in Taiwan, Germany, and the United States, with rare earth magnet supply for servo motors anchored in China and Myanmar. Single-source vulnerability in FPGA supply for deterministic kernel programming threatens lead time stability. Distribution runs through authorized system integrators serving Stuttgart, Munich, and Detroit automotive clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Motion control software vendors face a service-attach inflection as German automotive tier-1 suppliers pilot per-axis licensing for servo tuning tools, expanding recurring revenue faster than perpetual platform sales.
For Market Incumbents: Pre-empt edge-AI module commoditization by embedding predictive vibration suppression algorithms directly into safety-certified kernels before regulatory scope expands. Backward integration into TSN-enabled switch hardware secures deterministic communication stack control against emerging industrial Ethernet specialists. For New Entrants and Emerging Players: Pursue white-space openings in India's PLI scheme manufacturing clusters where localized software development centers lack embedded functional safety expertise. Target pharmaceutical OEMs facing FDA validation timeline compression with pre-certified middleware stacks. Lead with OPC-UA interoperability compliance as the go-to-market wedge against legacy fieldbus installations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cobot motion controller sub-segments as software-defined architectures displace dedicated hardware cards. Five-to-ten year viability favors vendors with certified safety stacks spanning EU Machinery Directive, OSHA lockout-tagout, and Japan JIS grades. Acquisition target archetype: specialized motion controller firms with EtherCAT distributed clock expertise and existing automotive OEM qualifications. Signal to watch: TSN convergence adoption rates in South Korean battery manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | TSN-enabled motion controllers unify factory networks for German automotive battery manufacturers. |
| Backward Integration | In-house FPGA production for deterministic kernels reduces silicon carbide supply vulnerability. |
| Strategic Partnership | OPC-UA middleware certification opens Japan METI Smart Manufacturing procurement channels. |
| Product Launch | Edge-AI vibration suppression modules capture predictive maintenance budgets in packaging lines. |
| Geographic Expansion | Localized software centers in India exploit PLI scheme production-linked incentives. |
Research Methodology
A spread of perspectives from motion control software engineering directors, automotive OEM procurement leads, system integrators, and industrial Ethernet protocol specialists converged on the working assumptions. Primary interviews combined with secondary validation from SEC 10-K filings, EU Machinery Directive certification databases, and MIIT industrial internet policy documents. Bottom-up vendor revenue triangulation against top-down end-user spend analysis anchored segmentation sizing.
Demand-supply-balance framing modeled motion controller deployment against battery manufacturing capacity expansion and automotive powertrain electrification timelines across the projection horizon. Segmentation dimensions included product type, communication protocol, application precision tier, and end-user regulatory cluster. CAGRs derived from curve-fitting historical adoption patterns against technology substitution rates, with EtherCAT penetration and TSN convergence as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration by diversified automation multinationals would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Asia-Pacific Industrial Automation Market
Industrial Automation
Europe Process Automation Market
Industrial Automation
North America Machine Control System Market
Industrial Automation
Intelligent Conveyor System Market
Industrial Automation
Global Intelligent Process Automation Market
Industrial Automation
Warehouse Automation Equipment Market
Industrial Automation
Electric Linear Actuator Market
Industrial Automation
Factory Automation in Japan Market
Industrial Automation
Europe Smart Manufacturing Market
Industrial Automation
Liquid Handling Technology Market
Industrial Automation
Latin America Automated Storage and Retrieval System Market
Industrial Automation
Programmable Automation Controller (PAC) Market
Industrial Automation
Europe Warehouse Automation Systems Market
Industrial Automation
North America Process Automation Market
Industrial Automation
Supervisory Control and Data Acquisition (SCADA) Market
Industrial Automation
Asia Pacific Factory Automation and Industrial Controls Market