
 Brazil Factory Automation and Industrial Controls Market | 2026-2036
Brazil Factory Automation and Industrial Controls Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Factory Automation and Industrial Controls Market Outlook
Direct distribution through system integrators is fragmenting as Brazilian manufacturers seek localized service and faster commissioning cycles. Siemens AG sustains formidable channel presence through its Campinas engineering hub and certified partner network. WEG leverages its domestic manufacturing footprint to anchor mid-market drive sales across Minas Gerais and São Paulo industrial zones. ABB Ltd. competes on robotics integration strength, particularly in automotive welding and material handling lines.
Factory automation and industrial controls encompass electromechanical systems, software platforms, and communication protocols that govern manufacturing processes through real-time sensing, logic execution, and actuation with millisecond response tolerances. These systems execute continuous process regulation, discrete motion sequencing, and production data acquisition to yield throughput consistency, defect reduction, and energy optimization. Programmable Logic Controllers remain the structural revenue backbone due to their universality across process and discrete applications, though Industrial IoT platforms capture accelerating capital allocation as manufacturers retrofit brownfield assets for cloud-connected predictive maintenance. Robotics applications in automotive body-in-white and food packaging lines represent the fastest-expanding margin pool, driven by labor cost pressures and precision requirements.
ANVISA mandates GAMP 5 validation protocols for pharmaceutical batch control systems, forcing vendors to certify software lifecycle documentation and audit trail integrity. The Brazilian central bank's open banking framework and PIX instant payment infrastructure indirectly shape industrial IT security standards as manufacturers harden network perimeters against financial-cyber convergence threats. INMETRO certification requirements for electrical safety and electromagnetic compatibility filter market access, elevating compliance costs for imported drive and sensor portfolios. Stakeholders must weigh the trade-off between imported technology leadership and local content thresholds under Brazil's industrial policy mechanisms.
Market Dynamics
ANVISA's GAMP 5 validation mandate for pharmaceutical batch control systems is forcing rapid upgrades across São Paulo's manufacturing corridor, compressing vendor certification timelines and reshaping competitive positioning among automation suppliers.
Growth Catalysts
- Automotive OEM Expansion:São Paulo and Minas Gerais manufacturers are deploying PLCs and robotics at scale to modernize body-in-white and material handling lines.
- ANVISA Pharmaceutical Standards:Updated validation protocols mandate audit-trail integrity and software lifecycle documentation, accelerating control system replacement cycles.
- Industrial IoT Retrofit Urgency:Brownfield assets across southeastern Brazil's manufacturing belt require cloud-connected predictive maintenance platforms to reduce unplanned downtime.
Market Restraints
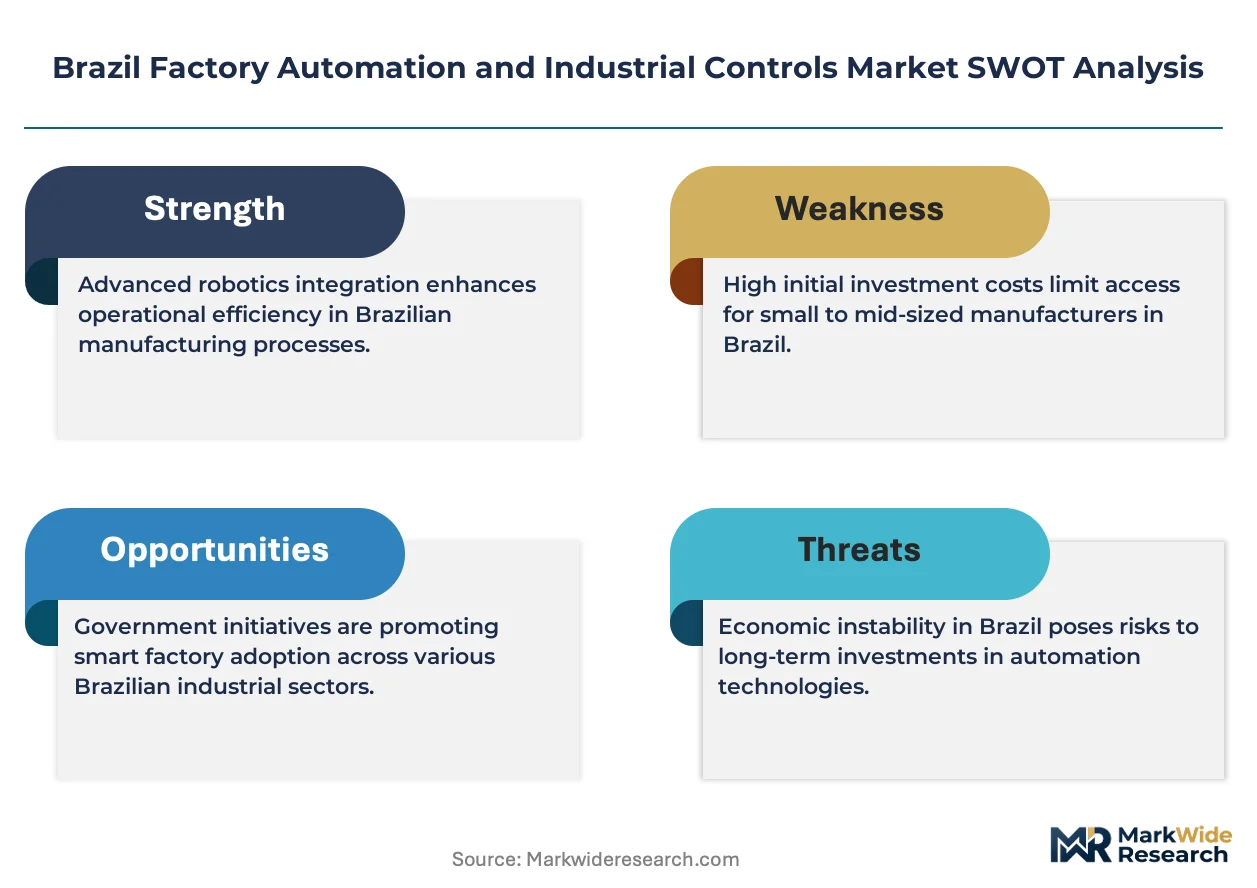
- Import Cost Structure:INMETRO certification requirements for electromagnetic compatibility and electrical safety elevate landed costs for European and Asian drive portfolios.
- Technical Talent Scarcity:Validation-grade control engineering expertise concentrates in Campinas and São Paulo, constraining deployment velocity in secondary industrial zones.
- Local Content Thresholds:Brazil's industrial policy mechanisms impose domestic sourcing requirements that complicate technology transfer from foreign automation vendors.
Strategic Opportunities
- Food Packaging Robotics:Precision requirements and labor cost pressures in meat processing and beverage bottling create white space for collaborative robot deployments.
- PIX Security Convergence:The central bank's instant payment infrastructure indirectly elevates industrial IT security standards, opening cybersecurity service attach rates.
- System Integrator Disintermediation:Direct manufacturer-vendor relationships are fragmenting traditional distribution, rewarding localized service and faster commissioning capabilities.
Industry Challenges
- Legacy PLC Integration Complexity:Brownfield facilities in Minas Gerais face protocol mismatch between decades-old discrete controllers and modern Industrial IoT gateways.
- Validation Documentation Burden:Pharmaceutical manufacturers struggle to assemble GAMP 5-compliant software lifecycle records for mixed-vendor control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Factory Automation and Industrial Controls Market |
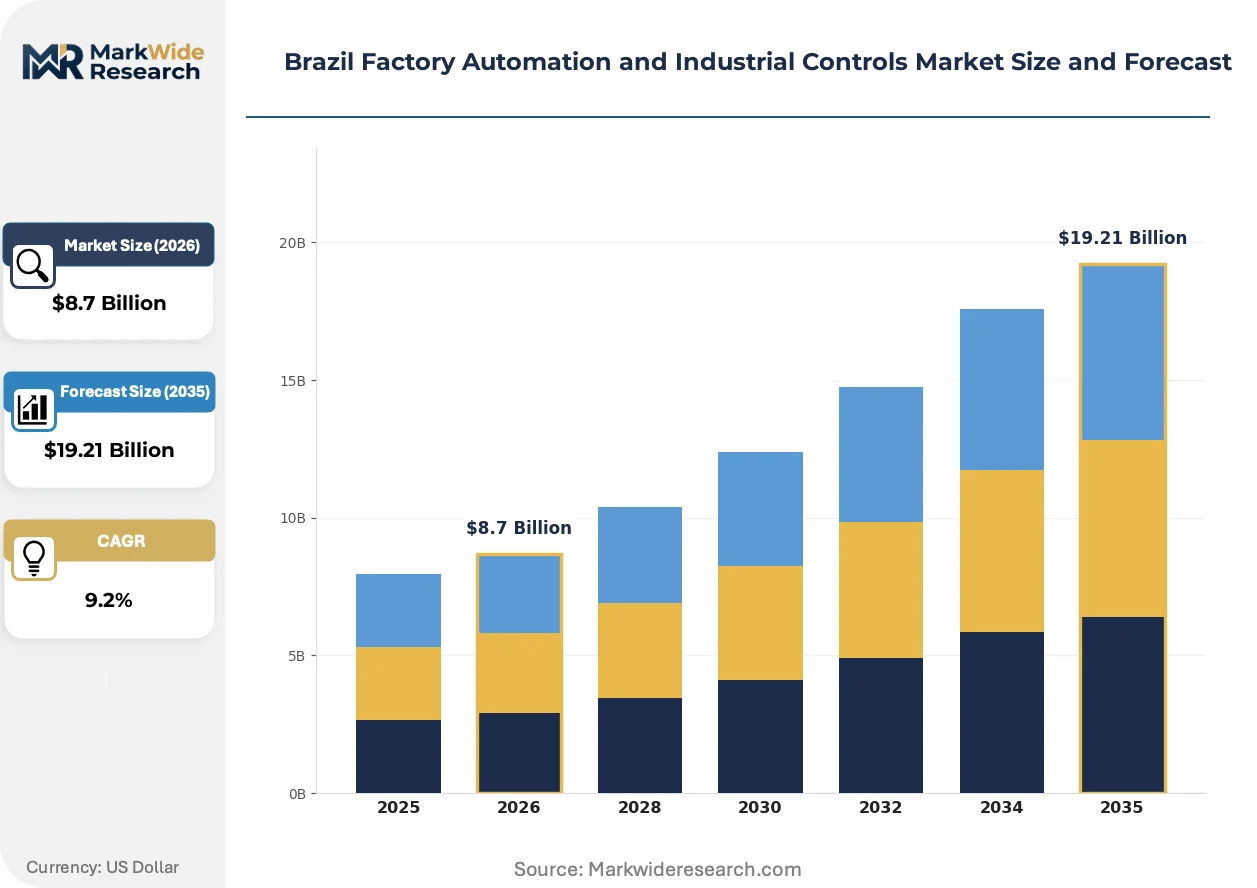
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.21 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Programmable Logic Controllers, Sensors, Drives, Human-Machine Interfaces End User: Manufacturing, Food & Beverage, Automotive, Pharmaceuticals Technology: Industrial IoT, SCADA, Robotics, Machine Learning Application: Process Automation, Quality Control, Supply Chain Management, Asset Tracking |
| Companies Covered | ABB Ltd., Siemens AG, Rockwell Automation Inc., Emerson Electric Co, General Electric Company, Honeywell International Inc., WEG, NOVA Smar, Schneider Electric SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Factory Automation and Industrial Controls Market Strategic Shifts
Edge computing architectures are collapsing latency tolerances for real-time process control, while regulatory pressure on batch integrity and financial-cyber convergence reshape vendor capability requirements across Brazil's industrial base.
Time-sensitive networking over standard Ethernet is collapsing the traditional separation between information technology and operational technology layers in factory automation. Automotive OEMs in São Paulo are adopting TSN-enabled PLCs to synchronize robotics cells with microsecond precision. This convergence is collapsing the historical need for parallel control networks, reducing infrastructure complexity and commissioning cycles.
ANVISA's enforcement of GAMP 5 validation protocols for pharmaceutical manufacturing is mandating software lifecycle documentation and audit trail integrity across batch control systems. Vendors must now certify code versioning, change control, and electronic signature compliance prior to commercial deployment. São Paulo's pharmaceutical cluster is responding by consolidating supplier relationships around validation-capable automation partners.
After-sales service unbundling is fragmenting traditional system integrator relationships as Brazilian manufacturers seek direct vendor engagement for faster commissioning. Mid-market discrete manufacturers in Minas Gerais are bypassing distributor channels to secure localized engineering support and spare parts availability. This behavioral shift is most visible in automotive supplier parks where downtime costs exceed premium pricing tolerance for bundled service contracts.
Brazil Factory Automation and Industrial Controls Market Segmentation
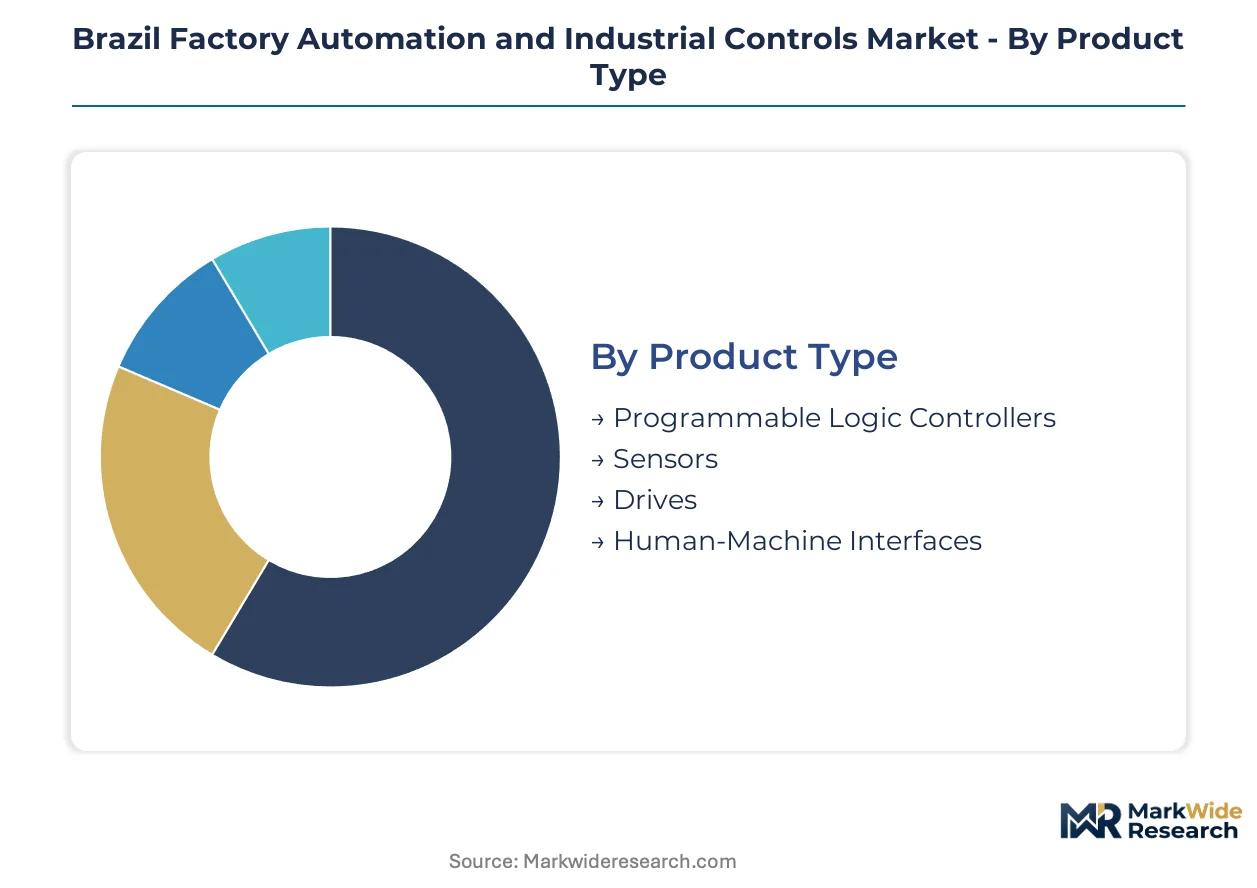
Segmentation in Brazil's factory automation market reveals how service intensity, regulatory pressure, and brownfield retrofit economics concentrate vendor opportunity across distinct technology and application layers. Understanding these divisions exposes where commissioning speed and validation-grade documentation create pricing power.
Product Type:
After-sales service intensity varies sharply across product categories, with field-replaceable components and firmware-dependent systems commanding divergent support contract attach rates.
- Programmable Logic Controllers:Ruggedized industrial computers executing ladder logic and structured text with millisecond scan cycles form the control backbone across discrete and process applications. Demand concentrates in São Paulo's automotive supplier parks where ANVISA-mandated batch record integration forces validation-grade PLC upgrades. Service contracts here capture 40-60% of lifetime revenue through firmware maintenance and spare module provisioning.
- Sensors:Photoelectric, proximity, and pressure transducers convert physical variables into 4-20mA or digital process signals for closed-loop regulation. Minas Gerais mining and metals operations drive heavy demand for harsh-environment IP67-rated units with predictive calibration alerts.
- Drives:Variable frequency and servo motor controllers modulate torque and velocity for energy-efficient motion profiles.
- Human-Machine Interfaces:Touch panels and industrial PCs visualize process data and enable operator intervention.
Programmable Logic Controllers hold the largest share; momentum sits with Sensors as predictive maintenance retrofits accelerate.
End User:
Cost tier stratification separates validation-intensive regulated industries from price-sensitive discrete manufacturing, reshaping vendor sales motion and certification investment.
- Manufacturing:General discrete production spanning metal fabrication, plastics, and assembly operations deploys standard PLCs and basic HMI configurations. São Paulo's industrial corridor dominates volume, though margin compression from Chinese drive imports constrains pricing power in this tier.
- Food & Beverage:Meat processing, dairy, and beverage bottling lines require washdown-rated stainless steel enclosures and hygienic design certifications. Precision portioning and packaging robotics in Minas Gerais protein processing plants are climbing the fastest as labor costs rise and export compliance tightens.
- Automotive:OEM and tier supplier body-in-white, paint, and final assembly operations.
- Pharmaceuticals:ANVISA-regulated batch manufacturing with GAMP 5 validation requirements.
Manufacturing holds the largest share; momentum sits with Food & Beverage as cooperative robot deployments expand.
Technology:
Application maturity determines whether technologies command standalone budgets or attach as incremental modules to existing control architectures.
- Industrial IoT:Edge gateways, cloud connectivity, and predictive analytics platforms retrofit brownfield assets with digital thread capabilities. Southeastern Brazil's manufacturing belt shows concentrated demand for vibration monitoring and energy optimization dashboards that reduce unplanned downtime in aging Minas Gerais facilities.
- Robotics:Articulated arms, SCARA units, and collaborative robots execute precision motion with force-feedback safety. Automotive welding cells in São Paulo OEM plants are expanding most quickly as body-in-white automation ratios rise toward European benchmarks.
- SCADA:Supervisory control and data acquisition systems for centralized process visualization.
- Machine Learning:Quality inspection and predictive maintenance algorithms deployed at the edge.
SCADA holds the largest share; momentum sits with Industrial IoT as cloud-connected retrofit urgency intensifies.
Application:
Customer type segmentation separates capital-project buyers from operational-technology managers with divergent procurement authority and vendor relationship preferences.
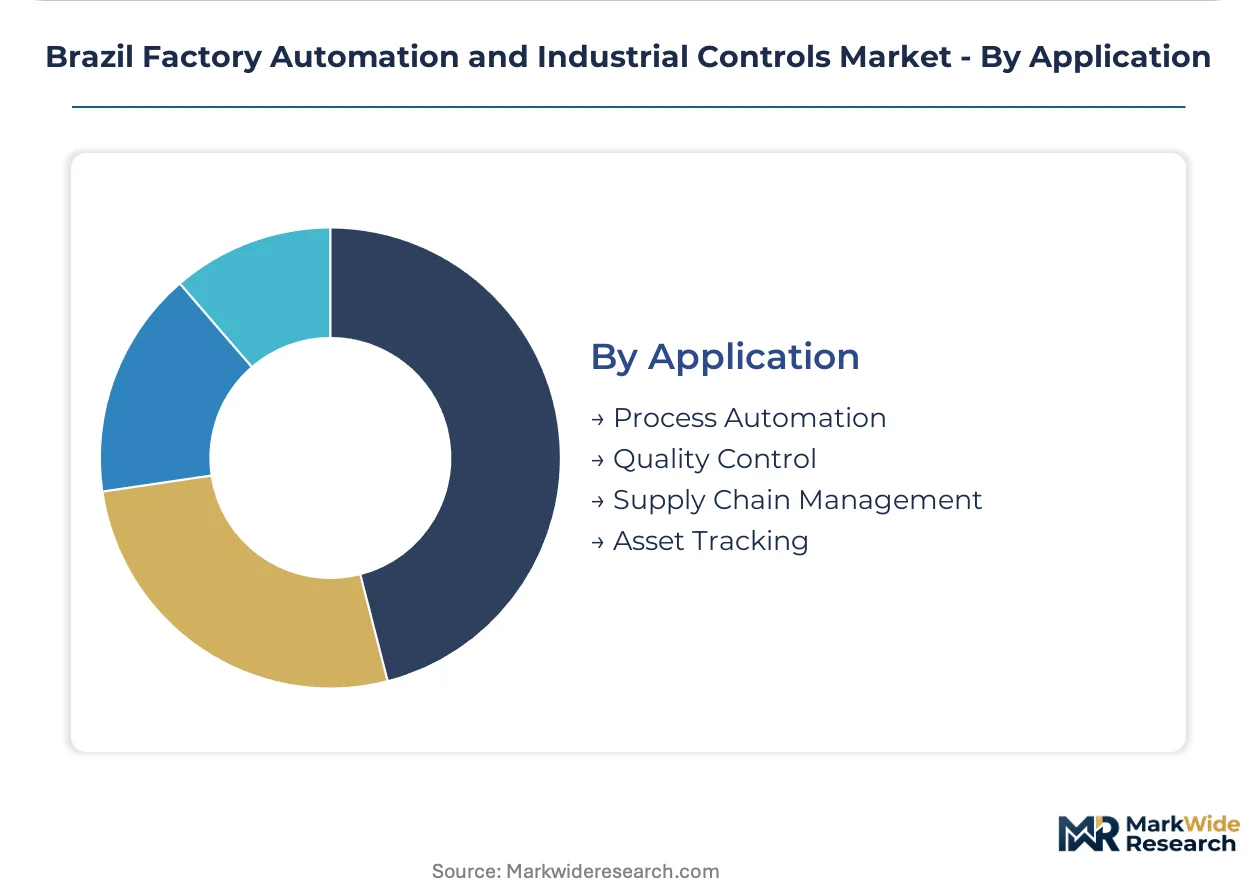
- Process Automation:Continuous and batch control of temperature, pressure, flow, and level variables across chemical, pharmaceutical, and food processing operations. ANVISA's GAMP 5 enforcement in São Paulo's pharmaceutical cluster forces documented software lifecycle integrity and electronic signature compliance.
- Quality Control:In-line vision inspection, statistical process control, and automated testing systems.
- Supply Chain Management:Warehouse automation, AGV coordination, and inventory tracking integration.
- Asset Tracking:RFID and barcode-based location monitoring for tool and work-in-progress visibility.
Process Automation holds the largest share; momentum sits with Quality Control as vision system costs decline and precision requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's industrial policy mechanisms and tax incentives for domestic manufacturing are redirecting automation procurement toward localized engineering support and faster commissioning cycles across southeastern states.
São Paulo
Automotive OEMs and tier suppliers are deploying PLCs and robotics at scale to modernize body-in-white and paint shop operations. ANVISA's GAMP 5 validation protocols for pharmaceutical batch control systems are forcing documented software lifecycle upgrades across the state's manufacturing corridor. The Campinas engineering hub anchors certified partner networks serving both automotive supplier parks and regulated pharmaceutical facilities.
Minas Gerais
Mining and metals operations drive heavy demand for harsh-environment sensors and variable frequency drives with predictive calibration alerts. INMETRO certification requirements for electromagnetic compatibility filter market access for imported drive portfolios. Belo Horizonte's industrial zones concentrate validation-grade control engineering expertise that constrains deployment velocity in surrounding secondary markets.
Rio de Janeiro
Offshore oil and gas platform automation sustains demand for explosion-proof control systems and subsea instrumentation. The national petroleum regulator mandates functional safety certifications that elevate compliance costs for foreign valve and actuator suppliers. The Macaé petrochemical cluster requires continuous process control upgrades to maintain operational integrity across aging refining assets.
Rio Grande do Sul
Food packaging and meat processing lines are climbing fastest as labor costs rise and export compliance tightens for protein processors. Hygienic design certifications for washdown-rated stainless steel enclosures separate qualified vendors from commodity suppliers. Porto Alegre's industrial corridor concentrates cooperative robot deployments in precision portioning applications for dairy and beverage bottling operations.
Paraná
Agricultural machinery manufacturers are integrating precision motion controllers and GPS-guided automation for harvest equipment production. The state's automotive supplier parks bypass traditional distributor channels to secure localized spare parts availability and faster commissioning cycles. Curitiba's manufacturing belt shows concentrated demand for edge computing architectures that collapse latency tolerances for real-time process control.
Brazil Factory Automation and Industrial Controls Market Competitive Environment
On the supply side, the industry is consolidating around validation-capable automation partners capable of certifying software lifecycle documentation and audit trail integrity. Three strategic archetypes dominate: multinational industrial conglomerates with established Brazilian engineering hubs, domestic manufacturers leveraging local content thresholds, and specialized robotics integrators focused on automotive welding and material handling lines. Competitive moves center on direct manufacturer engagement to fragment traditional system integrator relationships and geographic expansion through certified partner networks in secondary industrial zones.
Among multinational industrial conglomerates, ABB Ltd., Siemens AG, and Rockwell Automation Inc. exemplify the validation-grade tier where pharmaceutical and automotive manufacturers consolidate supplier relationships. These companies occupy positions that reward localized service capabilities and faster commissioning cycles over bundled distributor contracts. Domestic manufacturers such as WEG represent the mid-market drive segment where local manufacturing footprints anchor pricing power across Minas Gerais and São Paulo industrial zones.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens AG |
| Rockwell Automation Inc. |
| Emerson Electric Co |
| General Electric Company |
| Honeywell International Inc. |
| WEG |
| NOVA Smar |
| Schneider Electric SE |
| Others |
Value Chain & Pricing Dynamics
The Santos-Guarulhos freight corridor's elevated logistics costs compress margins for imported drive portfolios while amplifying price spreads between INMETRO-certified premium tiers and uncertified economy alternatives. Brazilian manufacturers respond by consolidating procurement around domestic assembly partners who absorb certification overhead into bundled service contracts.
Pricing Analysis
Certification level (INMETRO/CE-grade for electromagnetic compatibility) creates the primary spread between premium and economy positioning in Brazil's automation market. Project-based pricing dominates for pharmaceutical validation-grade upgrades, while per-unit transactional models govern mid-market drive sales. Cost compression in standard PLC tiers intensifies as Chinese imports erode pricing power, though automotive OEMs show lowest price sensitivity due to downtime cost tolerance. Food packaging lines exhibit highest price sensitivity, prioritizing spare parts availability over upfront capital outlay.
Supply Chain Analysis
Export-control restrictions on advanced robotics controllers and precision servo motors constrain flows from Germany, Japan, and South Korea into Brazilian automotive plants. Domestic assembly draws from German-engineered PLCs, Taiwanese sensor components, and Chinese variable frequency drives. Single-source vulnerability concentrates in validation-grade software platforms where ANVISA-mandated audit trail capabilities limit vendor substitution. Distribution runs through certified system integrator networks anchored by the Campinas engineering hub.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's factory automation market sits in early-cycle expansion as ANVISA's GAMP 5 enforcement forces replacement demand across São Paulo's pharmaceutical corridor. Industrial IoT retrofit urgency in aging Minas Gerais facilities accelerates penetration beyond traditional automotive strongholds.
For Market Incumbents: Harden validation-grade service capabilities against emerging domestic competitors exploiting local content thresholds. Deepen backward integration into firmware maintenance and spare module provisioning to capture 40-60% lifetime revenue attach rates. Consolidate channel control through direct manufacturer engagement as Brazilian OEMs bypass traditional distributors for faster commissioning.
For New Entrants and Emerging Players: Mid-market food packaging lines in Rio Grande do Sul represent the most penetrable entry point as labor costs rise and export compliance tightens for protein processors. Secondary industrial zones surrounding Belo Horizonte offer white space where validation-grade engineering expertise concentrates but deployment velocity lags. Pursue cooperative robot deployments with localized spare parts warehousing as the primary go-to-market angle.
For Investors and Strategic Acquirers: ANVISA's GAMP 5 enforcement reshapes the acquisition landscape toward validation-capable automation partners with certified software lifecycle documentation. The five-to-ten year viability window favors targets with established Brazilian engineering hubs over import-dependent distributors. Watch for PIX security convergence elevating industrial cybersecurity service attach rates as the inflection signal for premium valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Validation-Capable Partner Certification | ANVISA's GAMP 5 protocols force pharmaceutical manufacturers to consolidate supplier relationships around audit-trail-compliant vendors. |
| Direct Manufacturer Engagement | Bypassing traditional system integrators captures localized service premiums as Brazilian OEMs prioritize commissioning speed. |
| Edge Computing Architecture Deployment | TSN-enabled PLCs in São Paulo automotive plants collapse latency tolerances for microsecond-precision robotics synchronization. |
| Cooperative Robot Localization | Food packaging lines in Minas Gerais protein processing plants demand precision portioning with force-feedback safety certification. |
| PIX Security Service Attach | Brazil's instant payment infrastructure elevates industrial IT hardening requirements, opening cybersecurity recurring revenue streams. |
Study Parameters
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this study. Primary interviews combined with secondary validation from INMETRO certification databases, ANVISA regulatory filings, customs trade records, and industrial production statistics. Bottom-up segmentation triangulation across product type, end user, technology, and application layers converged with top-down macroeconomic calibration.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling discrete and process automation demand separately. Segmentation dimensions included control system architecture, regulatory compliance tier, brownfield versus greenfield deployment, and regional industrial cluster concentration. CAGRs derived from unit shipment trajectories and average selling price evolution, with specific inputs for pharmaceutical validation upgrade cycles and automotive body-in-white automation ratios.
Practitioners should monitor ANVISA enforcement intensity, PIX security standard evolution, and local content threshold adjustments for early signals of forecast revision. Material shifts in INMETRO certification timelines or central bank payment infrastructure security mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Europe Sortation Systems Market
Industrial Automation
Agricultural Automation Market
Industrial Automation
Smart and Connected Elevators and Elevators Control Systems Market
Industrial Automation
Smart Sorting Machine Market
Industrial Automation
Global Feeder Automation Market
Industrial Automation
Global Electric Gripper Market
Industrial Automation
Modular Automation and Services Market
Industrial Automation
Operational Predictive Maintenance Market
Industrial Automation
Asia Pacific Manufacturing Execution Systems (MES) Market
Industrial Automation
Latin America Process Automation Market
Industrial Automation
Global System Integrator for Industrial Automation Market
Industrial Automation
North America Smart Factory Market
Industrial Automation
Smart Industries Market
Industrial Automation
Internet of Things Enabled Industrial Wearables Market
Industrial Automation
Mini-Load Systems Market
Industrial Automation
Robotic Paint Booth Market