
 China Diesel Generator Market | 2026-2036
China Diesel Generator Market Size, Share, and Industry Trends Forecast 2026-2036
China Diesel Generator Market Analysis
Multi-source procurement among state-owned infrastructure developers is broadening supplier access for mid-range generator sets. Weichai leverages captive engine manufacturing to control cost structures across stationary installations. Cummins anchors its position through localized assembly partnerships that bypass import tariff exposure. Yuchai competes aggressively in the portable segment where construction contractors prioritize acquisition cost over lifecycle efficiency.
A diesel generator converts mechanical energy from internal combustion into electrical output through an alternator, typically operating at 1500 RPM for 50 Hz grids or 1800 RPM for 60 Hz configurations, with prime power ratings spanning 10 kVA to 3000 kVA. These systems serve as emergency backup for hospitals, continuous prime power for remote mining camps, and peak shaving assets for industrial parks facing grid congestion. Stationary installations dominate value capture due to permanent civil works and integrated fuel storage, while portable units grow fastest in rail and highway construction where site mobility dictates equipment turnover. The emergency power application commands premium pricing through automatic transfer switch integration and sub-10-second start requirements.
China's Ministry of Ecology and Environment enforces Stage IV emission standards that compel selective catalytic reduction and diesel particulate filter adoption, raising bill-of-material costs for domestic manufacturers. GB standards on noise limits and fuel efficiency push product differentiation toward electronically governed engines with optimized combustion mapping. MIIT certification requirements for grid-forming capability in distributed energy resources are reshaping specification sheets for prime power units. Stakeholders must monitor how provincial dual carbon implementation timelines alter diesel generator permitting in manufacturing zones.
Market Dynamics
China's tightening GB emission standards are compressing the cost advantage of domestic engine manufacturers while accelerating technology transfer from international joint ventures. Provincial dual carbon timelines in Jiangsu and Guangdong are forcing industrial buyers to reassess diesel backup power economics against hybrid alternatives.
Growth Catalysts
- Data center buildout:Hyperscale facilities in Beijing and Shanghai require N+1 redundancy configurations that mandate diesel backup capacity regardless of grid reliability improvements.
- MIIT grid-forming mandates:Distributed energy resource certification requirements are expanding addressable demand for prime-rated generator sets in industrial parks.
- Seasonal coastal manufacturing:Jiangsu and Zhejiang factories face summer peak load shedding that drives emergency procurement of 500-2000 kVA units.
Market Restraints
- Stage IV compliance costs:Selective catalytic reduction and diesel particulate filter adoption adds material cost to domestic bill-of-materials without corresponding pricing power.
- High-speed rail electrification:Construction contractors along completed trunk lines are decommissioning portable generator fleets faster than replacement demand materializes on new routes.
- Natural gas infrastructure density:Pipeline coverage expansion in the Yangtze River Delta enables fuel switching for prime power applications that previously relied on diesel.
Strategic Opportunities
- Western province industrialization:Sichuan and Chongqing manufacturing zones lack grid redundancy equivalent to coastal provinces, creating first-mover positioning for certified suppliers.
- Dual-fuel retrofit kits:Conversion systems allowing diesel-methanol blending address emission thresholds while preserving existing generator assets.
- Rental fleet digitization:Telematics-enabled portable units command premium lease rates from construction contractors managing dispersed highway projects.
Industry Challenges
- Emissions calibration expertise:Stage IV compliance requires combustion engineers familiar with electronic governor mapping, a skill set concentrated at joint-venture engine plants.
- Fuel quality variability:Sulfur content inconsistency across provincial supply chains degrades aftertreatment system performance and voids warranty coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Diesel Generator Market |
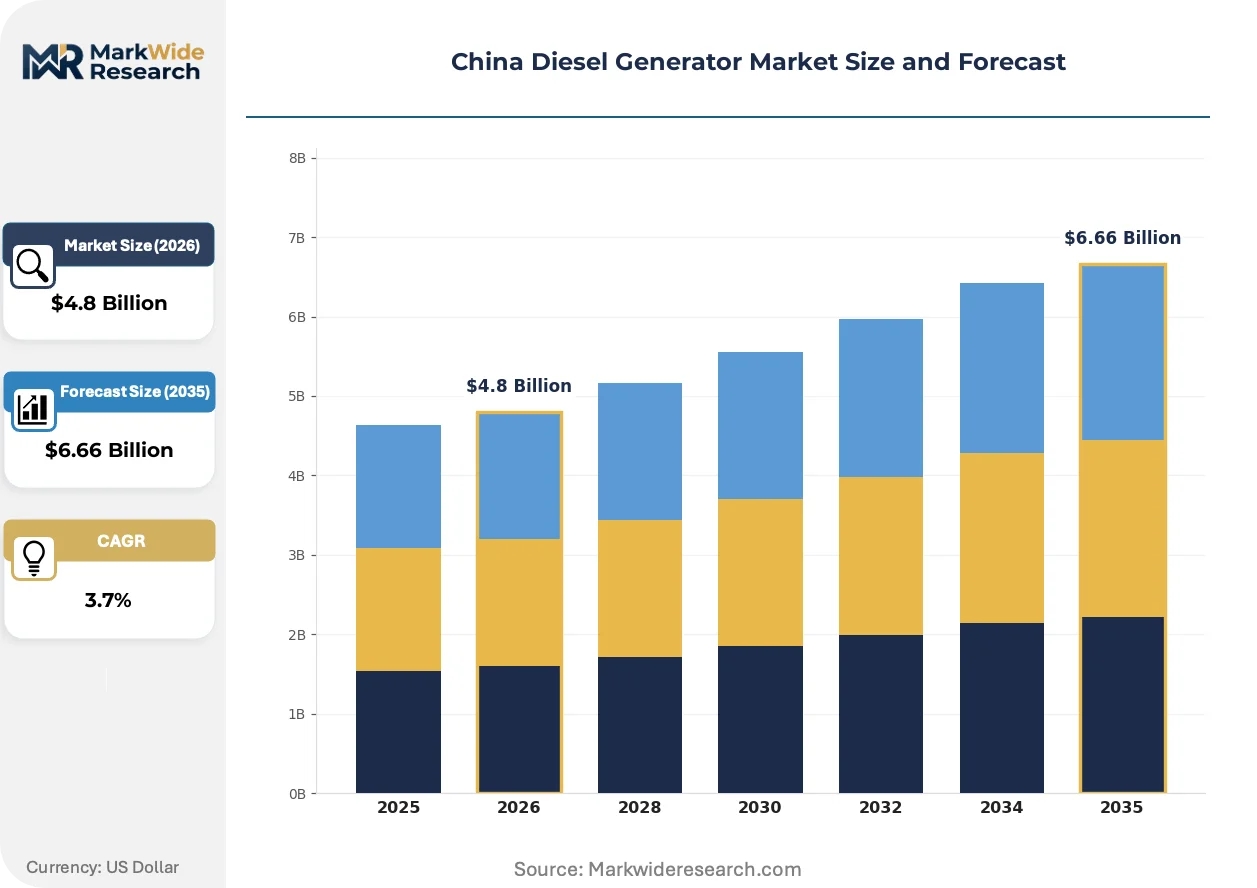
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Dual Fuel, Standby End User: Construction, Telecommunications, Healthcare, Mining Fuel Type: Diesel, Biodiesel, Kerosene, Others Application: Emergency Power, Prime Power, Peak Shaving, Remote Location |
| Companies Covered | Weichai, Yuchai, Cummins, Perkins, Caterpillar, Mitsubishi Heavy Industries Engine & Turbocharger, Yanmar Holdings, Changzhou ETK Power Machinery, SDEC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Diesel Generator Market Emerging Trajectories
Electronic engine management is displacing mechanical governor systems across the Chinese diesel generator supply base. This transition is compressing development cycles for domestic manufacturers while raising the technical barrier for new entrants.
Integrated selective catalytic reduction is consolidating exhaust aftertreatment into single-canister architectures that reduce installation footprint. Data center operators in Shanghai are specifying these compact configurations for rooftop and basement mechanical rooms where space constraints previously limited generator sizing. The technology is consolidating supplier tiers by eliminating standalone DPF vendors from the value chain.
China's Ministry of Ecology and Environment is accelerating Stage IV enforcement timelines in the Beijing-Tianjin-Hebei corridor ahead of national schedules. Engine manufacturers must recalibrate certification roadmaps to satisfy provincial pre-emption. Prime power installations in northern industrial parks face the steepest compliance cost escalation.
Buying committees at state-owned infrastructure developers are unbundling generator procurement from EPC contracts to access direct manufacturer pricing. Contractors previously capturing margin on packaged power systems are responding by repositioning as installation and commissioning specialists. This pattern is most visible in Guangdong highway and port construction projects where tender documentation now separates mechanical from electrical scope.
China Diesel Generator Market Segmentation
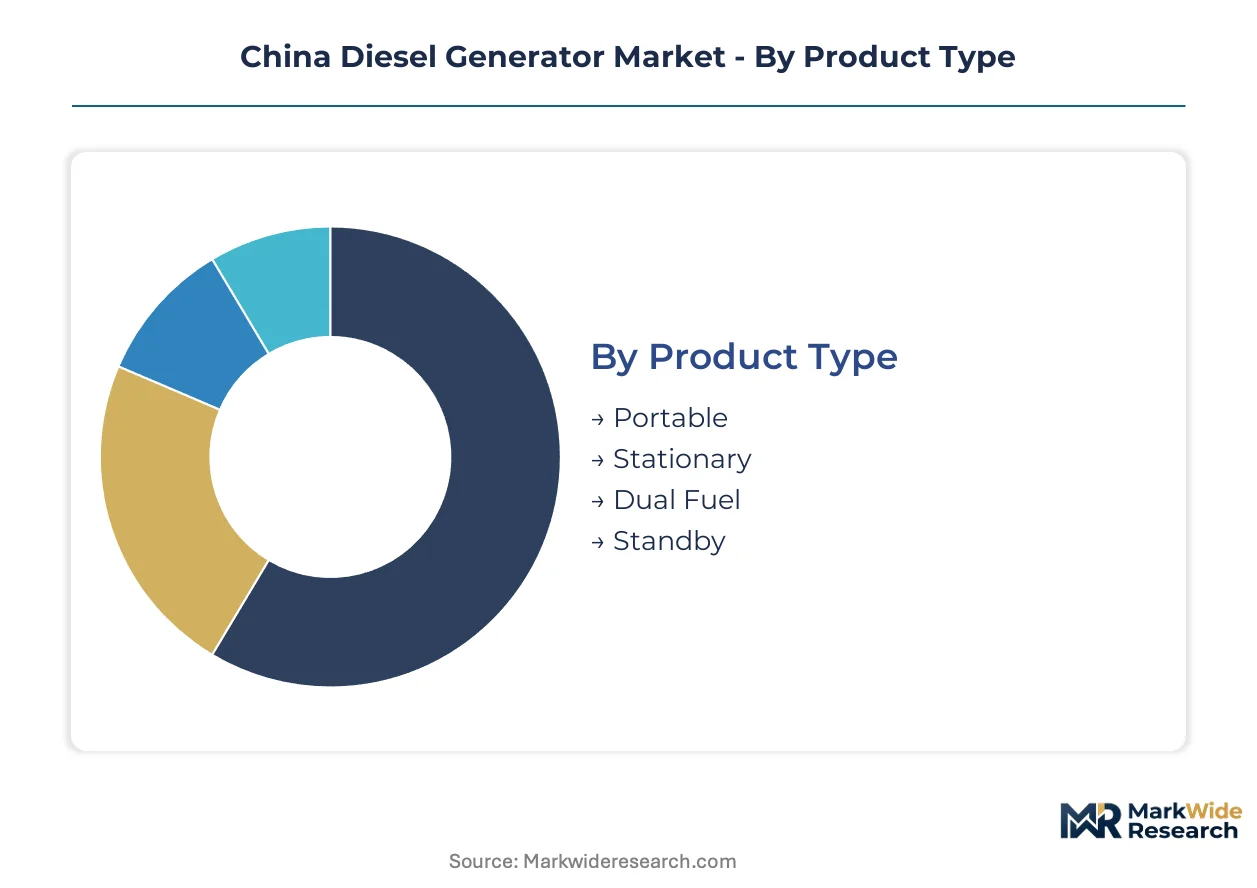
China's diesel generator market segments along four distinct axes that reflect divergent technical requirements and procurement patterns. Product type determines installation permanence and fuel flexibility, while end-user concentration shapes regional demand geography and specification intensity.
Product Type:
Standalone installations dominate capital deployment, whereas embedded or mobile configurations serve transient power needs across dispersed sites.
- Stationary:Permanent civil works anchor these units with integrated fuel storage and sound-attenuated enclosures. Jiangsu and Zhejiang manufacturing parks specify 500-2000 kVA stationary sets for summer peak shaving where grid congestion triggers seasonal load shedding.
- Portable:Trailer-mounted or skid-based designs enable rapid deployment across highway and rail construction corridors. Sichuan and Chongqing infrastructure contractors prioritize acquisition cost over lifecycle efficiency when sourcing these units for western province industrialization projects.
- Dual Fuel:Diesel-methanol blending capability addresses tightening GB emission thresholds while preserving existing generator assets. Conversion kits are gaining traction among operators seeking to retrofit stationary fleets without full replacement.
- Standby:Automatic transfer switch integration and sub-10-second start requirements command premium pricing. Beijing and Shanghai data center operators mandate N+1 redundancy configurations regardless of grid reliability improvements.
Volume placements concentrate in Stationary; the faster expansion belongs to Dual Fuel.
End User:
Customer procurement maturity varies sharply, with state-owned developers unbundling generator purchases from EPC contracts while private contractors remain price-sensitive.
- Telecommunications:Hyperscale data center buildouts in Beijing and Shanghai drive specification intensity for backup power systems. MIIT grid-forming mandates are expanding addressable demand for prime-rated sets in distributed energy resource configurations.
- Construction:Highway and rail contractors manage dispersed projects where site mobility dictates equipment turnover. Telematics-enabled portable units command premium lease rates from operators tracking fleet utilization across multiple work sites.
- Healthcare:Hospitals require emergency power with automatic transfer switch integration for life-critical loads. GB noise limits and fuel efficiency standards push product differentiation toward electronically governed engines with optimized combustion mapping.
- Mining:Remote camps rely on continuous prime power where grid extension remains uneconomical. Stage IV emission compliance raises bill-of-material costs for domestic manufacturers supplying these installations.
Procurement value concentrates in Telecommunications; Construction exhibits the steepest expansion trajectory.
Fuel Type:
Supply chain configuration and aftertreatment compatibility determine fuel selection, with sulfur content variability across provincial supply chains degrading system performance.
- Diesel:Dominant fuel for prime power and emergency applications with established distribution infrastructure. Stage IV selective catalytic reduction and diesel particulate filter adoption adds material cost without corresponding pricing power for domestic manufacturers.
- Biodiesel:Blending mandates in coastal provinces are creating specification requirements for compatible engine calibrations. MEE enforcement timelines in the Beijing-Tianjin-Hebei corridor are accelerating ahead of national schedules.
- Kerosene:Cold-weather operability drives adoption in northern industrial parks where fuel gelling concerns limit conventional diesel use. Availability constraints restrict deployment scale.
- Others:Synthetic and renewable diesel alternatives are emerging in dual carbon implementation zones. Jiangsu and Guangdong provincial timelines are forcing industrial buyers to reassess conventional fuel economics.
Volume concentrates in Diesel; Biodiesel is climbing the fastest.
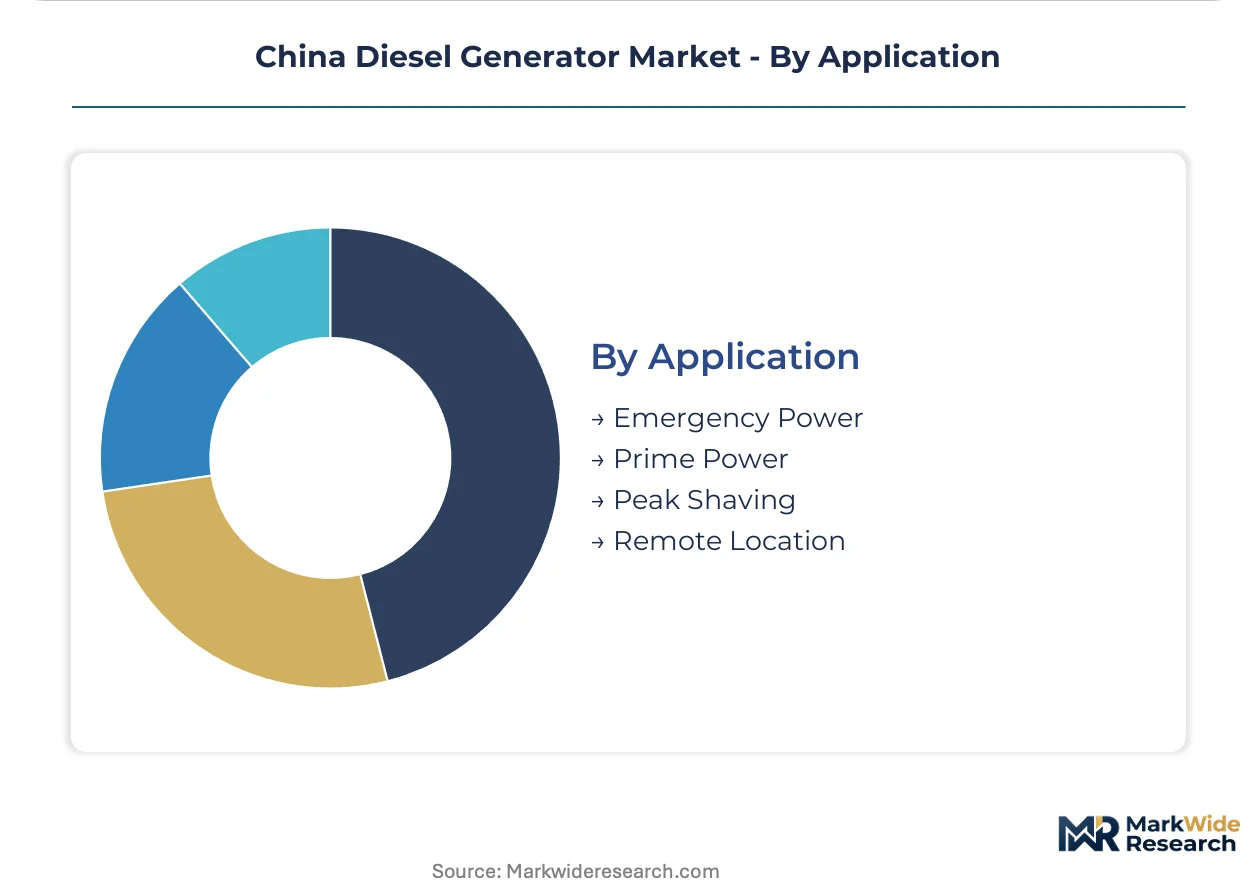
Application:
Functional role determines duty cycle intensity and regulatory exposure, with continuous prime power facing steeper compliance cost escalation than intermittent emergency use.
- Emergency Power:Automatic start requirements and transfer switch integration define specification standards. Data center operators in Shanghai specify compact selective catalytic reduction configurations for space-constrained mechanical rooms.
- Prime Power:Continuous operation demands robust engine durability and optimized fuel mapping. Northern industrial parks face the steepest Stage IV compliance cost escalation for these high-utilization installations.
- Peak Shaving:Seasonal grid congestion in coastal manufacturing provinces drives 500-2000 kVA procurement. Jiangsu and Zhejiang factories face summer load shedding that triggers emergency procurement cycles.
- Remote Location:Grid extension economics determine deployment feasibility for mining camps and highway construction sites. Western province industrialization in Sichuan and Chongqing is creating first-mover positioning for certified suppliers.
Revenue concentrates in Emergency Power; Peak Shaving is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for diesel generators clusters along three coastal manufacturing belts where grid congestion and data center buildouts concentrate procurement volume. Provincial dual carbon timelines and MIIT certification requirements are reshaping specification standards across these zones.
Beijing-Tianjin-Hebei Corridor
Hyperscale data center operators in Beijing mandate N+1 redundancy configurations that sustain diesel backup procurement despite grid reliability investments. MEE accelerated Stage IV enforcement timelines ahead of national schedules. Tianjin port industrial parks face the steepest compliance cost escalation for prime power installations.
Yangtze River Delta
Jiangsu and Zhejiang manufacturing parks specify 500-2000 kVA stationary sets for summer peak shaving where seasonal load shedding triggers emergency procurement. GB noise limits and fuel efficiency standards push differentiation toward electronically governed engines. Shanghai data center operators specify compact SCR configurations for space-constrained mechanical rooms.
Pearl River Delta
Guangdong highway and port construction projects unbundle generator procurement from EPC contracts to access direct manufacturer pricing. Provincial dual carbon timelines force industrial buyers to reassess diesel backup economics against hybrid alternatives. Shenzhen and Guangzhou contractors manage dispersed projects where telematics-enabled portable units command premium lease rates.
Sichuan-Chongqing
Western province industrialization lacks grid redundancy equivalent to coastal provinces, creating first-mover positioning for certified suppliers. Construction contractors prioritize acquisition cost over lifecycle efficiency when sourcing portable units for rail and highway corridors. Chongqing manufacturing zones drive demand for mid-range generator sets as state-owned developers broaden supplier access.
Shandong Peninsula
Industrial parks across Qingdao and Jinan face tightening GB emission standards that compress domestic manufacturer cost advantages. Fuel quality variability across provincial supply chains degrades aftertreatment system performance. Mining camps in remote Shandong counties rely on continuous prime power where grid extension remains uneconomical.
China Diesel Generator Market Vendor Landscape
Strategic partnerships dominate the current landscape as international joint ventures localize assembly to bypass import tariff exposure. The market exhibits tiered concentration with captive engine manufacturers controlling cost structures, localized assemblers anchoring premium positioning, and portable specialists competing on acquisition price. Three archetypes define competitive positioning: engine-integrated conglomerates, joint-venture assemblers, and construction-focused portable suppliers. Technology licensing agreements and backward integration into engine manufacturing represent the dominant competitive moves reshaping supplier economics.
Among engine-integrated conglomerates, Weichai leverages captive manufacturing to control stationary installation cost structures. Yuchai occupies a position within the portable segment where construction contractors prioritize upfront acquisition economics. Cummins exemplifies the joint-venture assembler archetype through localized partnerships that mitigate tariff exposure while preserving technical certification. These three anchors illustrate how competitive positioning fragments across product permanence and procurement maturity segments.
| Leading Market Players |
|---|
| Weichai |
| Yuchai |
| Cummins |
| Perkins |
| Caterpillar |
| Mitsubishi Heavy Industries Engine & Turbocharger |
| Yanmar Holdings |
| Changzhou ETK Power Machinery |
| SDEC |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between Stage IV-compliant and legacy generator sets splits pricing power along emission compliance lines, with MIIT-certified units commanding supply chain priority from engine manufacturers while uncertified inventory liquidates through secondary channels. This bifurcation concentrates procurement leverage among joint-venture assemblers with established GB standard certification pathways.
Pricing Analysis
Volume-vs-margin split separates prime power installations where captive engine manufacturing preserves profitability from portable units where Yuchai and construction-focused suppliers compete on acquisition cost. Price differentiation hinges on Stage IV certification status and integrated SCR-DPF architecture, with automatic transfer switch bundling adding further tier separation. Pricing pressure stems from domestic manufacturers absorbing Stage IV compliance costs without corresponding pricing power, compressing margins on mid-range stationary sets. State-owned infrastructure developers exhibit lowest price sensitivity through unbundled direct procurement, while Sichuan and Chongqing construction contractors prioritize upfront capital outlay over lifecycle efficiency.
Supply Chain Analysis
Single-source vulnerability sits with selective catalytic reduction catalyst suppliers concentrated in Germany and Japan, where combustion calibration IP limits domestic substitution options. Engine block casting draws from foundry capacity in China and India, while electronic governor systems rest on semiconductor inputs from Taiwan and South Korea. Tariff exposure on aftertreatment components creates structural risk for localized assemblers dependent on imported catalyst substrates. Distribution runs through state-owned infrastructure developer procurement committees and EPC contractor equipment packages, with direct manufacturer access expanding in Guangdong highway and port projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China diesel generator market functions as a vertical-integration race where captive engine manufacturing and aftertreatment system control determine cost structures, with backward integration into electronic governor production representing the decisive upstream lever.
For Market Incumbents: Acquire electronic governor and combustion calibration engineering capabilities to defend margin position against joint-venture technology transfer. Consolidate aftertreatment supply through catalyst substrate partnerships that reduce import dependency. Stage IV enforcement acceleration in the Beijing-Tianjin-Hebei corridor threatens uncertified inventory positions; prioritize MIIT grid-forming certification investment to anchor premium positioning. For New Entrants and Emerging Players: GB dual carbon timelines in Jiangsu and Guangdong open a window for dual-fuel retrofit kit deployment targeting existing stationary fleet operators seeking emission compliance without full replacement. Target western province industrialization in Sichuan and Chongqing where grid redundancy gaps exceed coastal standards and certified supplier presence remains thin. Pursue telematics-enabled portable unit leasing to construction contractors managing dispersed highway projects as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with joint-venture assemblers possessing Stage IV certification and localized manufacturing given MIIT grid-forming mandate expansion across industrial parks. Long-term viability frames around emission compliance technology ownership rather than assembly margin capture. Monitor provincial dual carbon implementation timeline acceleration as the inflection signal for diesel generator permitting restriction severity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Engine Manufacturing | Weichai's captive production model demonstrates cost control advantages in stationary installations. |
| Stage IV Certification Investment | MIIT and MEE enforcement timelines in Beijing-Tianjin-Hebei reward early compliance with procurement priority. |
| Dual-Fuel Retrofit Kit Development | Diesel-methanol blending addresses GB emission thresholds while preserving existing generator asset values. |
| Telematics Platform Integration | Construction contractors in Sichuan and Chongqing pay premium lease rates for fleet utilization visibility. |
| Joint Venture Localization | Cummins partnerships bypass import tariff exposure while maintaining technical certification standards. |
Methodological Framework
Multi-period observation of MIIT certification filings, provincial dual carbon timeline announcements, and data center power procurement contracts anchored the trend analysis, supplemented by interviews with plant engineers at Jiangsu and Zhejiang manufacturing parks, procurement directors at state-owned infrastructure developers, EPC contractor equipment specialists, and aftermarket service heads. Secondary validation drew from GB standards documentation, MEE enforcement notices, customs import records for aftertreatment components, and MIIT grid-forming certification databases. Bottom-up generator unit deployment tracking and top-down industrial power demand modeling provided triangulation.
Segment-weighting across product type, end user, fuel type, and application dimensions structured the analytical framework, with product permanence and duty cycle intensity serving as cross-cutting modifiers throughout the projection horizon. CAGRs were derived from deployment trajectory analysis against regulatory compliance cost curves. Prime power utilization rates in mining camps and seasonal peak shaving frequency in coastal manufacturing provinces supplied industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for dual-fuel blending or battery-hybrid substitution would alter the outlook for diesel generator demand intensity. Forecasts reflect assumptions regarding Stage IV enforcement uniformity across provincial jurisdictions and data center redundancy configuration standards. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Military Generator Market
Generators
Europe Gas Turbine Market
Generators
Generator (Up to 20 Kva) Market
Generators
Gas Generator Market
Generators
South America and Africa Diesel Generator Market
Generators
Asia-Pacific Gas Generator Market
Generators
Middle East Portable Generator Market
Generators
Heat Recovery System Generator Market
Generators
Hand Crank Power Generator Market
Generators
North America Generator Sets Market
Generators
India Diesel Generator Market
Generators
Middle East and Africa Gas Generator Market
Generators
Commercial Standby Generator Sets Market
Generators
India Portable Generator Market
Generators
North West Europe Diesel Generator Market
Generators
Europe Generator Sets Market