
 Europe Generator Sets Market | 2026-2036
Europe Generator Sets Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Generator Sets Market Analysis
Remote monitoring and predictive maintenance subscriptions are restructuring how generator sets are sold across Europe. Cummins Inc. leverages its digital service platform to lock in long-term contracts with industrial clients. Wärtsilä Corporation anchors the high-megawatt segment through integrated power plant solutions that bundle hardware with lifecycle support. Aggreko plc competes via flexible rental fleets that respond to grid instability events in the United Kingdom and Nordic markets.
Generator sets are self-contained engine-alternator assemblies that convert mechanical energy into electrical power, typically rated from sub-10 kW residential units to multi-megawatt industrial installations capable of black-start grid recovery. Diesel generators still dominate installed base volumes across European healthcare and construction applications, though gas generators are gaining share where pipeline infrastructure permits continuous operation. The data center end-user segment commands premium pricing for above-1 MW configurations with sub-15-second startup requirements. Portable generators serve a mature replacement cycle in residential and small commercial settings with thinner margins and fewer service attach rates.
The EU Green Deal and Stage V emission standards enforced by national regulators in Germany and France are phasing out older diesel engines in non-road applications, redirecting procurement budgets toward natural gas and biogas fuel types. ECHA's REACH framework restricts certain lubricant additives and surface treatments, compelling manufacturers to reformulate component specifications. The EU AI Act introduces compliance obligations for autonomous load-management software embedded in smart generator controllers. Stakeholders must track how carbon border adjustments and evolving renewable curtailment patterns reshape the economic case for on-site backup versus grid-scale battery storage.
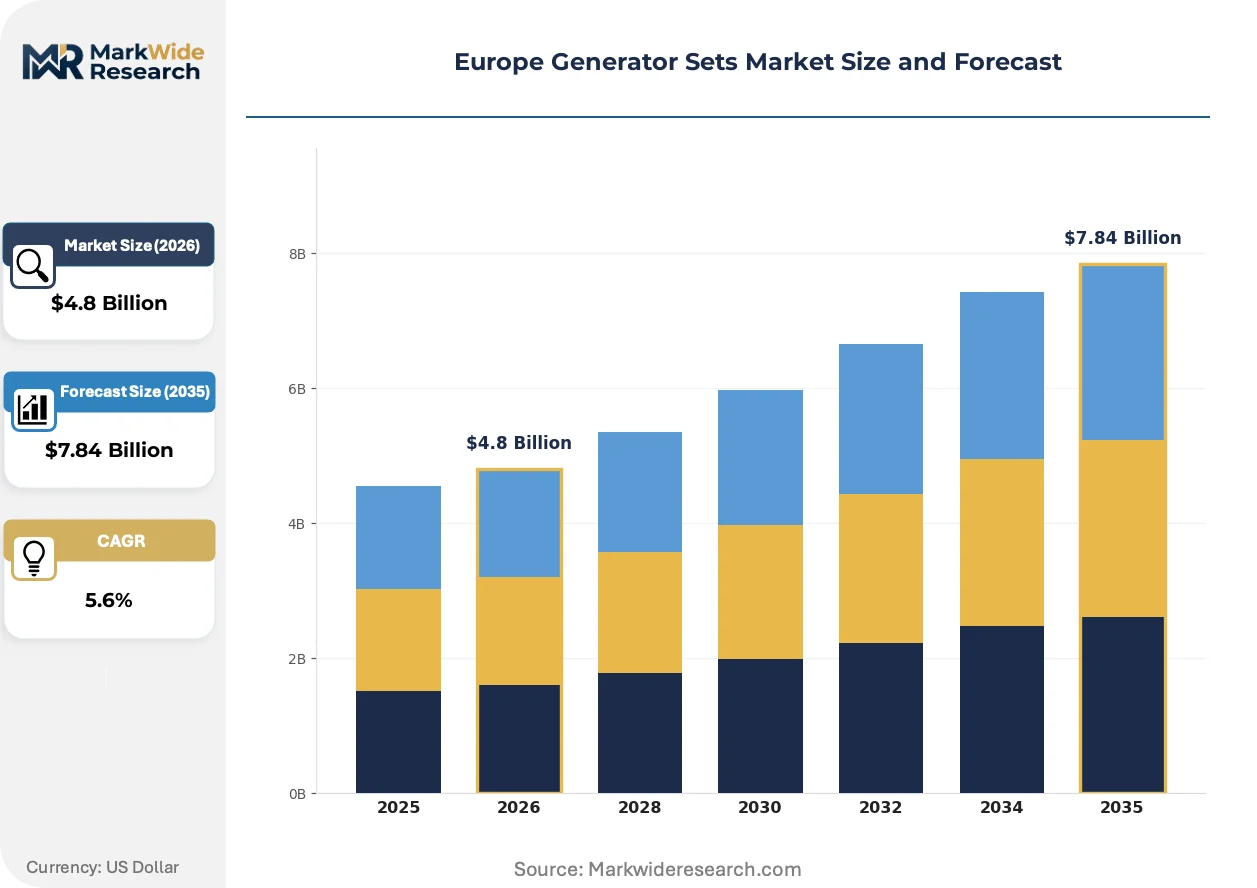
Market Dynamics
The EU Green Deal and Stage V emission standards are compressing diesel generator lifecycles and redirecting capital toward gas, biogas, and hybrid configurations. Fleet operators face simultaneous pressure from ECHA REACH chemical restrictions and tightening carbon border adjustments.
Growth Catalysts
- Data center expansion:Hyperscale facilities in Germany and France require above-1 MW backup systems with sub-15-second startup. These contracts carry premium service attach rates and long-term maintenance subscriptions.
- EU Green Deal benchmarks:Stricter emission thresholds for stationary engines are accelerating replacement cycles in industrial clusters. Operators must upgrade or retire aging diesel assets ahead of compliance deadlines.
- Grid instability events:Frequency excursions and renewable curtailment patterns in the United Kingdom and Nordic markets are extending rental fleet utilization periods. Temporary power providers capture demand spikes during transmission constraints.
Market Restraints
- Input cost volatility:Rare earth magnet prices and copper winding costs fluctuate with energy transition demand. Generator manufacturers face margin compression when long-term contracts lock in pricing.
- Supply concentration risk:High-megawatt alternator production concentrates among a limited set of European and Asian suppliers. Lead times for critical components extend during periods of infrastructure investment.
- Substitution threat:Lithium-ion battery storage and grid-scale BESS projects compete for backup power budgets. Data center operators evaluate total cost of ownership across 10-year horizons.
Strategic Opportunities
- Biogas corridor development:Agricultural regions in France and Italy possess underutilized anaerobic digestion capacity. Generator OEMs can bundle fuel supply agreements with equipment sales.
- EU AI Act compliance services:Autonomous load-management software embedded in smart controllers faces new algorithmic transparency requirements. Vendors offering pre-certified control systems capture specification advantages.
- Hybrid architecture penetration:Battery-generator combinations reduce fuel consumption and noise profiles. Construction sites in urban Germany and the Netherlands specify these configurations for environmental permits.
Industry Challenges
- Emissions certification timelines:Stage V type-approval processes for new engine platforms require 18-24 month validation cycles. Product roadmaps must anticipate regulatory evolution.
- Legacy controller integration:Existing installed bases run proprietary communication protocols. Smart monitoring retrofits face interoperability friction with third-party energy management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Generator Sets Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel Generators, Gas Generators, Portable Generators, Industrial Generators End User: Healthcare Facilities, Data Centers, Construction Sites, Residential Power Rating: Up to 10 kW, 10 kW to 100 kW, 100 kW to 1 MW, Above 1 MW Fuel Type: Diesel, Natural Gas, Propane, Biogas |
| Companies Covered | Wärtsilä Corporation, Aggreko plc, Cummins Inc., Atlas Copco AB, Generac Holdings Inc., Caterpillar Inc., Kohler, DEUTZ AG, Rolls-Royce Power Systems, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Generator Sets Market Emerging Trajectories
Digital service platforms and predictive analytics are restructuring generator set commercial models across European industrial markets. Hardware margins compress while recurring software revenue expands.
Containerized battery-generator hybrid systems are decentralizing backup power architecture in data center and healthcare applications. Facility managers in Germany and France deploy these units to reduce diesel runtime and satisfy local air quality ordinances. The technology is decentralizing capital allocation away from centralized plant rooms toward distributed, modular installations.
F-Gas Regulation phase-down schedules are accelerating adoption of low-global-warming-potential refrigerants in generator cooling circuits. Engine manufacturers reformulate thermal management designs to maintain output ratings under constrained coolant specifications. Industrial genset portfolios in Northern Europe face the steepest redesign obligations due to earlier enforcement timelines.
Power-as-a-service contracting is displacing traditional equipment ownership in construction and event rental segments. German and UK fleet operators now specify uptime guarantees rather than asset purchase, shifting balance sheet exposure to OEMs and rental providers. This transformation concentrates most visibly in urban infrastructure projects where temporary power needs fluctuate seasonally.
Europe Generator Sets Market Segmentation
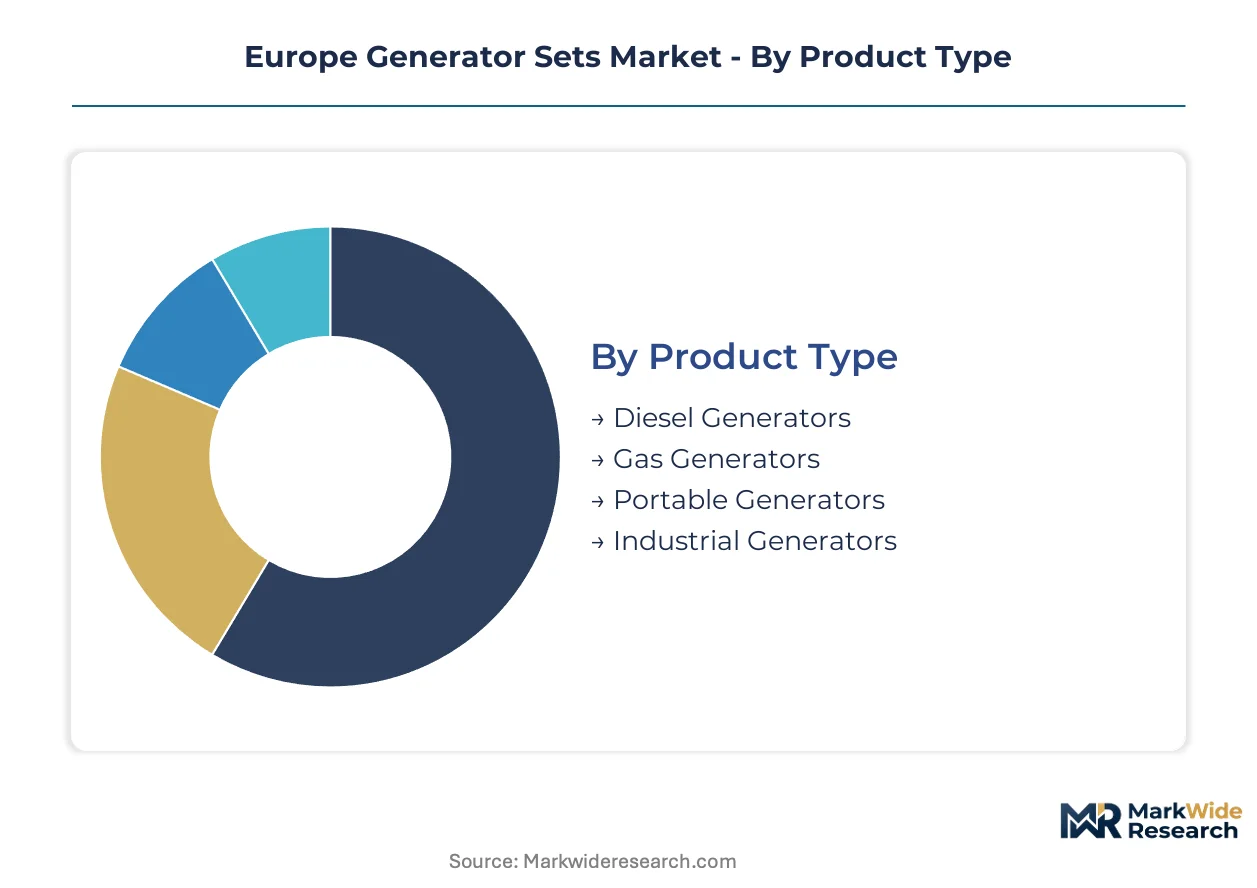
Generator set procurement patterns diverge sharply across technical specifications, end-use criticality, and fuel compliance requirements. Understanding these segmentation boundaries clarifies where pricing power concentrates and where commoditization pressures dominate.
Product Type:
Technical architecture and duty cycle specifications define competitive positioning across hardware categories.
- Diesel Generators:Compression-ignition engines deliver high torque density and rapid load acceptance for black-start applications. German healthcare networks and French industrial clusters specify these units for emergency power where sub-15-second startup is mandatory under EU Green Deal timelines.
- Gas Generators:Spark-ignited engines running natural gas or biogas offer lower NOx emissions and reduced carbon intensity. Netherlands and Danish district heating operators deploy these for continuous CHP operation where pipeline infrastructure permits steady fuel supply.
- Portable Generators:Sub-10 kW mobile units serve construction sites and residential backup with pull-start or electric ignition. UK rental fleets rotate these through seasonal demand peaks.
- Industrial Generators:Fixed-installation systems above 100 kW with integrated control enclosures serve manufacturing campuses. Polish and Czech automotive suppliers specify these for production line protection.
Diesel generators lead on scale; gas generators lead on momentum.
End User:
Criticality tiers and uptime requirements reshape procurement specifications and service attach rates.
- Data Centers:Hyperscale facilities in Frankfurt and Paris require N+1 redundancy with sub-15-second automatic transfer. These contracts bundle predictive maintenance subscriptions and remote monitoring at premium pricing.
- Healthcare Facilities:Hospitals in Berlin and Munich face life-safety code requirements for uninterrupted power. German KBA emission certifications constrain engine selection for new installations.
- Construction Sites:Temporary power needs fluctuate with infrastructure project cycles. French and Spanish contractors favor rental models over capital deployment.
- Residential:Single-family backup units in rural UK and Nordic regions serve mature replacement demand with minimal service revenue.
Data centers concentrate margin capture; healthcare anchors regulatory compliance spending.
Power Rating:
Scale thresholds determine alternator sourcing complexity and control system sophistication.
- Up to 10 kW:Single-phase residential units with air-cooled engines dominate consumer retail channels. Italian and Spanish homeowners purchase these for rural property protection.
- 10 kW to 100 kW:Three-phase commercial units serve small business and light industrial loads. German Mittelstand manufacturers specify these for partial facility backup.
- 100 kW to 1 MW:Medium-voltage configurations with paralleling capability support manufacturing campuses. French chemical processors deploy these for process safety.
- Above 1 MW:High-voltage synchronous machines with digital voltage regulation serve grid-scale and data center applications. Lead times for these alternators extend due to concentrated European supplier bases.
Above-1 MW systems concentrate supply risk; sub-100 kW segments face battery substitution pressure.
Fuel Type:
Emission compliance trajectories and infrastructure availability reshape fuel economics across member states.
- Diesel:Liquid fuel with highest energy density enables rapid deployment without pipeline dependency. Stage V standards are compressing residual demand to emergency-only applications.
- Natural Gas:Pipeline-delivered methane offers lower particulate emissions and carbon border adjustment advantages. Netherlands and UK grid operators favor these for distributed generation.
- Propane:Liquefied petroleum gas serves remote sites lacking natural gas infrastructure. Alpine construction projects in Austria and Switzerland specify these for cold-weather reliability.
- Biogas:Anaerobic digestion-derived methane qualifies for renewable energy incentives under EU Green Deal frameworks. Italian and French agricultural regions deploy these for waste-to-power conversion.
Natural gas leads on installed base; biogas climbs the fastest on policy support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the largest installed base of industrial generator sets in Europe, while France accelerates faster on data center-driven procurement. The regulatory divergence between KBA emission enforcement in Germany and EDF grid stability contracts in France creates distinct national demand profiles.
Germany
Industrial clusters in North Rhine-Westphalia and Bavaria drive replacement demand for Stage V-compliant units. The KBA enforces stringent type-approval timelines that compress product development cycles. Frankfurt's data center corridor requires above-1 MW configurations with sub-15-second startup for hyperscale facilities.
France
Hyperscale cloud operators in Paris and Marseille are expanding backup power contracts ahead of EU Green Deal deadlines. The ANSM coordinates with environmental regulators on stationary engine emission benchmarks. Auvergne-Rhône-Alpes hosts chemical processors deploying gas generators for continuous CHP operation.
United Kingdom
Grid instability events and renewable curtailment patterns extend rental fleet utilization periods. OFGEM transmission constraints create demand spikes for temporary power providers. London's financial district and Manchester's media clusters specify hybrid battery-generator configurations for noise-sensitive urban permits.
Netherlands
District heating operators in Rotterdam and Amsterdam favor natural gas generators for baseload CHP applications. The national climate agreement accelerates biogas corridor development in agricultural provinces. Eindhoven's high-tech manufacturing campuses require resilient on-site generation for semiconductor production lines.
Italy
Agricultural regions in Emilia-Romagna and Lombardy deploy biogas generators for waste-to-power conversion under EU Green Deal incentives. The GSE manages renewable energy certificates for anaerobic digestion projects. Milan's pharmaceutical and food processing clusters specify gas-fired backup for emission-sensitive urban environments.
Europe Generator Sets Market Vendor Landscape
Top-tier vendors anchor the high-megawatt integrated power plant segment, while mid-tier specialists compete on flexible rental and digital service platforms. The market exhibits tiered concentration with distinct capability requirements across stationary, portable, and hybrid architectures. Strategic archetypes include lifecycle service integrators, temporary power rental operators, and emission-compliant engine specialists. Competitive moves center on predictive maintenance subscription expansion and biogas fuel supply bundling.
Within the integrated solutions tier, Wärtsilä Corporation and Rolls-Royce Power Systems represent archetypes of high-megawatt project developers bundling hardware with long-term service agreements. Among flexible rental operators, Aggreko plc exemplifies the temporary power model responding to grid instability events. Cummins Inc. anchors the digital service platform approach, leveraging remote monitoring to secure industrial maintenance contracts. These three occupy positions that span the technology and commercial model spectrum.
| Leading Market Players |
|---|
| Wärtsilä Corporation |
| Aggreko plc |
| Cummins Inc. |
| Atlas Copco AB |
| Generac Holdings Inc. |
| Caterpillar Inc. |
| Kohler |
| DEUTZ AG |
| Rolls-Royce Power Systems |
| Others |
Supply Flow & Price Mechanics
Containerized battery-generator hybrid architectures are compressing manufacturing cost curves while redistributing supply leverage toward alternator specialists and power electronics integrators. This dual transformation tightens margins on conventional diesel hardware even as it opens premium pricing tiers for emission-compliant configurations bundled with predictive maintenance subscriptions.
Pricing Analysis
Capacity additions in Poland and the Czech Republic are reshaping price floors for sub-100 kW generator sets, pressuring legacy Western European manufacturers. Three-tier pricing structure across premium, standard, and economy levels segments the market: premium tiers attach remote monitoring and EU AI Act-compliant controllers, standard tiers compete on emission certification speed, and economy tiers serve replacement cycles in residential channels. Price differentiation rests on Stage V certification status and after-sales service bundling. Cost compression in the portable segment is intensifying because battery substitution erodes replacement demand. Construction rental operators exhibit highest price sensitivity; data center procurement teams prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Freight cost volatility from Asian component ports to European assembly hubs is amplifying inventory carrying costs for high-megawatt alternators. Manufacturing concentration in Germany, Italy, and China feeds European generator set production. Rare earth magnets for permanent magnet alternators, copper windings, and silicon steel laminations constitute critical input dependencies. Single-source vulnerability concentrates in high-voltage synchronous alternator production, where European suppliers command extended lead times. Distribution runs through OEM-direct channels for industrial projects, rental fleet operators for temporary power, and specialized distributors for aftermarket parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through predictive maintenance subscription attach rates and biogas fuel supply bundling, offsetting hardware commoditization in diesel segments.
For Market Incumbents: Extend digital service platform penetration to lock in lifecycle revenue ahead of battery substitution threats. Backward integration into alternator production reduces exposure to concentrated European supplier bases. Anchor high-megawatt positions through integrated power plant solutions that bundle hardware with long-term maintenance contracts, defending against rental fleet operators capturing grid instability demand spikes. For New Entrants and Emerging Players: Rental fleet partnerships offer the fastest channel to scale without capital-intensive manufacturing footprints. Biogas corridor development in French and Italian agricultural regions represents the most penetrable white-space, where fuel supply agreements can differentiate commodity hardware. Target construction site hybrid configurations for urban German and Dutch environmental permit compliance, leveraging power-as-a-service contracting to displace traditional equipment ownership. For Investors and Strategic Acquirers: Roll-up economics work for regional service integrators because predictive maintenance platforms create customer switching costs that compound across installed bases. Mid-cap specialists with captive biogas fuel agreements and EU AI Act pre-certified control systems represent prime acquisition targets. Watch Stage V enforcement timelines as the inflection signal: accelerated replacement cycles in German industrial clusters will concentrate market share among emission-compliant portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Biogas Fuel Supply Bundling | Captures EU Green Deal incentives while locking in long-term fuel-offtake contracts with agricultural processors. |
| Predictive Maintenance Platform Expansion | Converts transactional hardware sales into recurring revenue streams with industrial data center clients. |
| EU AI Act Pre-Certification | Secures specification advantages for autonomous load-management software in smart generator controllers. |
| Hybrid Battery-Generator Architecture | Reduces diesel runtime to satisfy German and Dutch urban air quality permitting requirements. |
| Power-as-a-Service Contracting | Shifts balance sheet exposure from construction operators to OEMs while capturing seasonal demand fluctuations. |
Methodological Framework
Coverage spans Germany, France, the United Kingdom, the Netherlands, and Italy, with primary inputs from each market. The research combines structured interviews with data center infrastructure directors, industrial plant engineers, rental fleet operations managers, and biogas project developers with secondary validation from ECHA REACH regulatory filings, EU Green Deal implementation schedules, KBA type-approval databases, and national grid operator transmission constraint reports. Bottom-up segment sizing and top-down macroeconomic triangulation cross-validate volume and value estimates.
Rate-of-change decomposition separates volume growth from mix-shift effects across the projection horizon. The analytical framework models generator set demand by fuel type, power rating tier, end-use criticality, and regional regulatory cluster. CAGRs derive from segment-level growth trajectory analysis incorporating data center capex pipelines, Stage V replacement cycle timing, and renewable curtailment frequency patterns. Industry-specific inputs include hyperscale facility backup power specifications, anaerobic digestion capacity expansion in agricultural corridors, and rental fleet utilization rates during grid instability events.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium-ion battery cost curves and carbon border adjustment implementation scope. Forecasts reflect assumptions about emission regulation enforcement timelines, biogas infrastructure buildout rates, and grid stability investment patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Dual-Fuel Generator Market
Generators
Africa Diesel Generator Market
Generators
Digital Inverter Generator Market
Generators
Africa Portable Generator Market
Generators
Mobile Generators Market
Generators
Generator (Up to 20 Kva) Market
Generators
North America Diesel Generator Market
Generators
China Gas Generator Market
Generators
North America Gasoline Gensets Market
Generators
Silent Generator Market
Generators
Asia Pacific Electric Generators Market
Generators
Generator Sales Market
Generators
Boiler, Turbine, and Generator (BTG) Market
Generators
South America Generator Sets Market
Generators
Gas Generator Market
Generators
Hand Crank Power Generator Market