
 Military Generator Market | 2026-2036
Military Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Military Generator Market Analysis
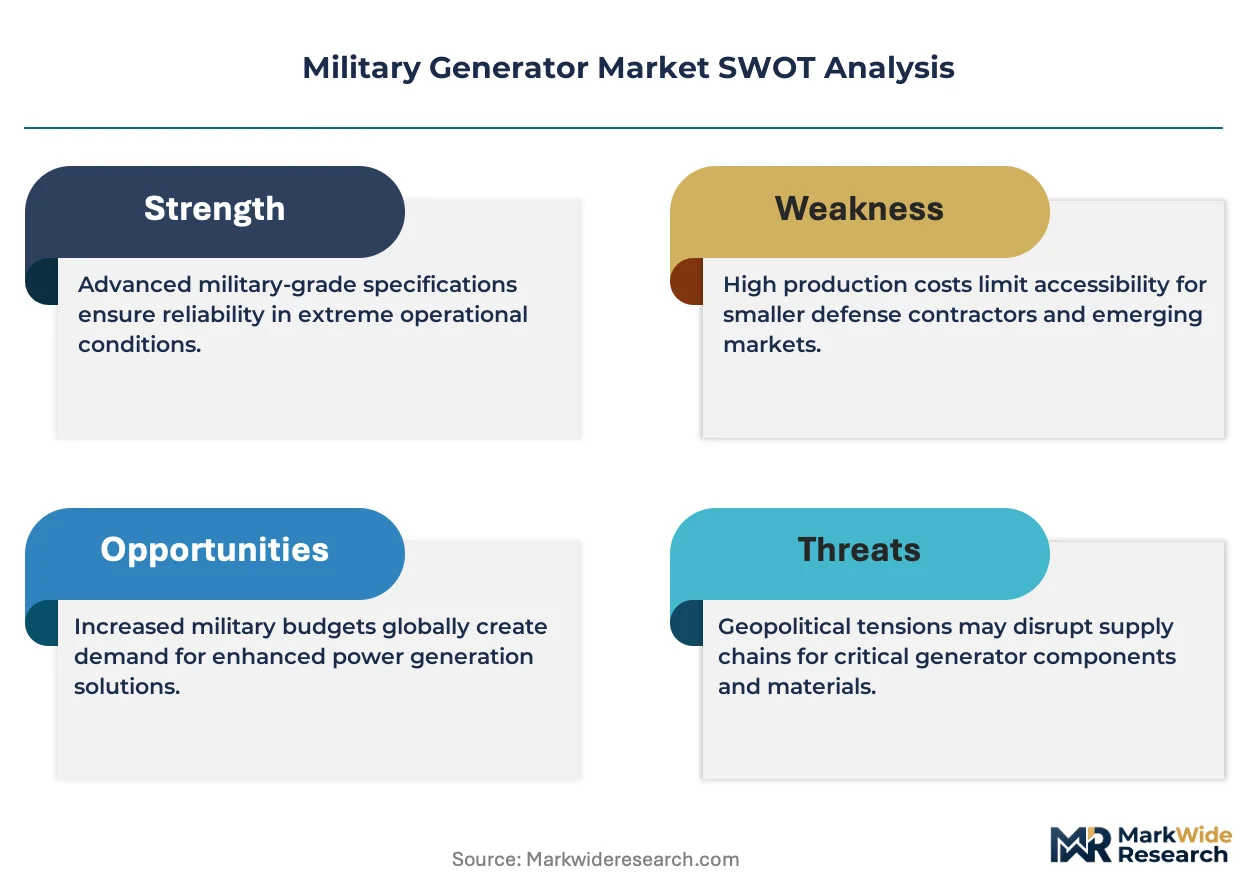
EPA Tier 4 final emission standards for non-road diesel engines is pivoting the competitive landscape toward aftertreatment-intensive designs. Caterpillar Inc. leverages its integrated engine-generator architecture to sustain compliance without third-party exhaust systems. Cummins Inc. anchors its position through military-specific control software that optimizes load response under battlefield conditions. Kohler Co. competes on compact footprint designs that fit constrained vehicle bays and shelter configurations.
A military generator is a self-contained prime or standby power unit engineered to deliver specified kilowatt output under extreme environmental conditions, typically incorporating skid-mounted frames, electromagnetic interference shielding, and multi-fuel combustion systems for tactical deployment. Diesel technology occupies the dominant revenue position due to energy density and established logistics chains, while hybrid configurations are gaining traction in silent-watch applications where acoustic and thermal signature reduction matters. The 101-500 kW power output band captures the largest share of procurement value, as this range satisfies brigade-level camp power and mobile command post requirements without the mobility penalties of above-500 kW systems.
FERC grid interconnection standards and EPA emission mandates in the United States, alongside NATO STANAG agreements on fuel interoperability, collectively dictate product architecture and testing protocols for vendors seeking defense contracts. The EU Green Deal's emerging defense energy efficiency targets are beginning to influence tender specifications for European military procurement agencies. Stakeholders must monitor how multi-fuel and hybrid technology maturation alters the traditional diesel-centric supplier base before committing to long-term platform investments.
Market Dynamics
EPA Tier 4 final emission standards for non-road diesel engines are compressing the supplier base toward aftertreatment-intensive architectures, while NATO STANAG fuel interoperability mandates simultaneously reshape combustion system design priorities for expeditionary power systems.
Growth Catalysts
- Expeditionary Force Modernization:Forward operating base electrification across NATO member states is accelerating procurement of mobile prime power units with reduced thermal and acoustic signatures.
- JP-8 Fuel Compatibility Mandates:The U.S. Department of Defense's single-fuel policy is standardizing multi-fuel combustion architectures across tactical generator platforms.
- EU Green Deal Defense Annex:Emerging energy efficiency targets for military procurement are creating specification pull for hybrid and load-optimized generator configurations in European tenders.
Market Restraints
- Aftertreatment Cost Burden:Diesel particulate filters and selective catalytic reduction systems add substantial capital cost and maintenance complexity to sub-500 kW tactical units.
- Specialized Component Concentration:High-reliability alternators and military-grade control modules depend on a concentrated supplier base in Germany and the United States.
- Battery Substitution Pressure:Silent-watch lithium-ion battery packs are displacing low-load diesel runtime in reconnaissance and special operations vehicle applications.
Strategic Opportunities
- Australia-Pacific Theater Expansion:AUKUS security framework investments are opening sustained procurement pipelines for deployable power infrastructure across northern Australian basing networks.
- Hybrid-Architectures for Signature Management:Converging diesel-electric systems with intelligent load-following software create white space in brigade-level mobile command post applications.
- Performance-Based Logistics Contracts:Availability-guarantee contracting models are displacing traditional unit-purchase arrangements in U.S. Army and Marine Corps generator fleet management.
Industry Challenges
- Embedded Software Certification:MIL-STD-882E safety-critical software validation for generator control systems extends development timelines by 18-24 months.
- Legacy Fleet Interoperability:Interface standardization gaps between new digital control platforms and existing analog-load distribution equipment complicate phased modernization programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Generator Market |
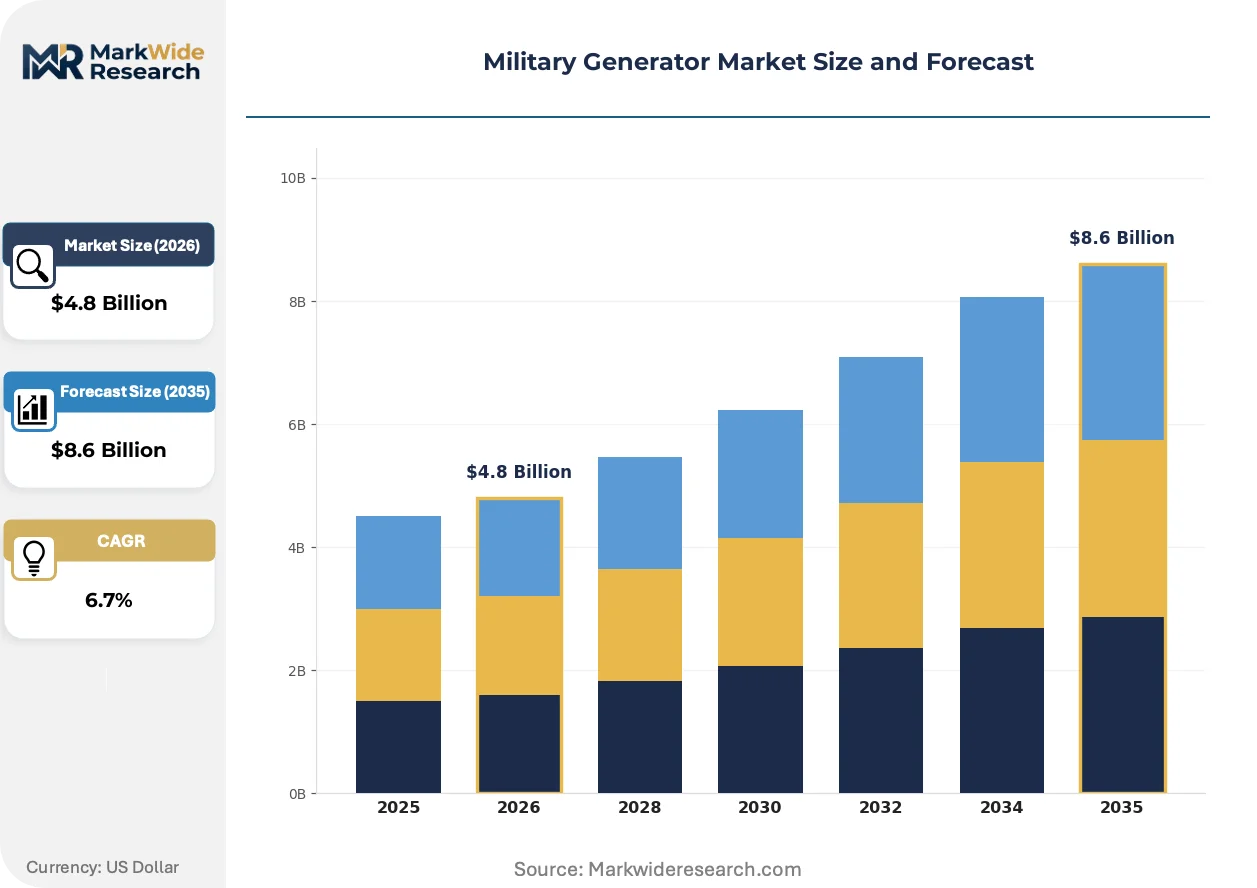
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Portable Generators, Inverter Generators, Standby Generators, Diesel Generators Technology: Gas Turbine, Diesel, Solar, Hybrid Power Output: 10-50 kW, 51-100 kW, 101-500 kW, Above 500 kW Application: Camp Power, Tactical Operations, Emergency Backup, Training Exercises |
| Companies Covered | Caterpillar Inc., Cummins Inc., Honeywell International Inc., Kohler Co., MTU Onsite Energy, Generac Power Systems Inc., Fischer Panda, HDT Global, Leonardo DRS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Generator Market Emerging Trajectories
Power electronics and thermal management advances are converging to enable new generator architectures that were technically infeasible under legacy mechanical-governing constraints. These developments compress signature profiles while expanding operational envelopes.
Silicon carbide power semiconductors are unifying inverter and generator control functions into single-package variable-speed architectures. Special operations vehicle integrators are adopting these systems fastest, drawn by 40% volume reduction in constrained engine bays. The technology is unifying prime power and battery charging subsystems, eliminating redundant rotating machinery from tactical platforms.
The EU Green Deal's emerging defense energy efficiency targets are tightening tender specifications for European military procurement agencies. Minimum fuel efficiency thresholds and maximum idle-consumption limits now appear in German and French generator solicitations. Vendors must revalidate product lines against these criteria to maintain position in NATO continental tenders.
Contracting officers are bundling generator procurement with ten-year sustainment and fuel-consumption guarantees. The U.S. Army's Project Manager Mobile Electric Power is leading this shift, displacing traditional unit-purchase awards with availability-based performance contracts. This pattern concentrates most visibly in brigade-level camp power programs where operational tempo unpredictability favors risk transfer to suppliers.
Military Generator Market Segmentation
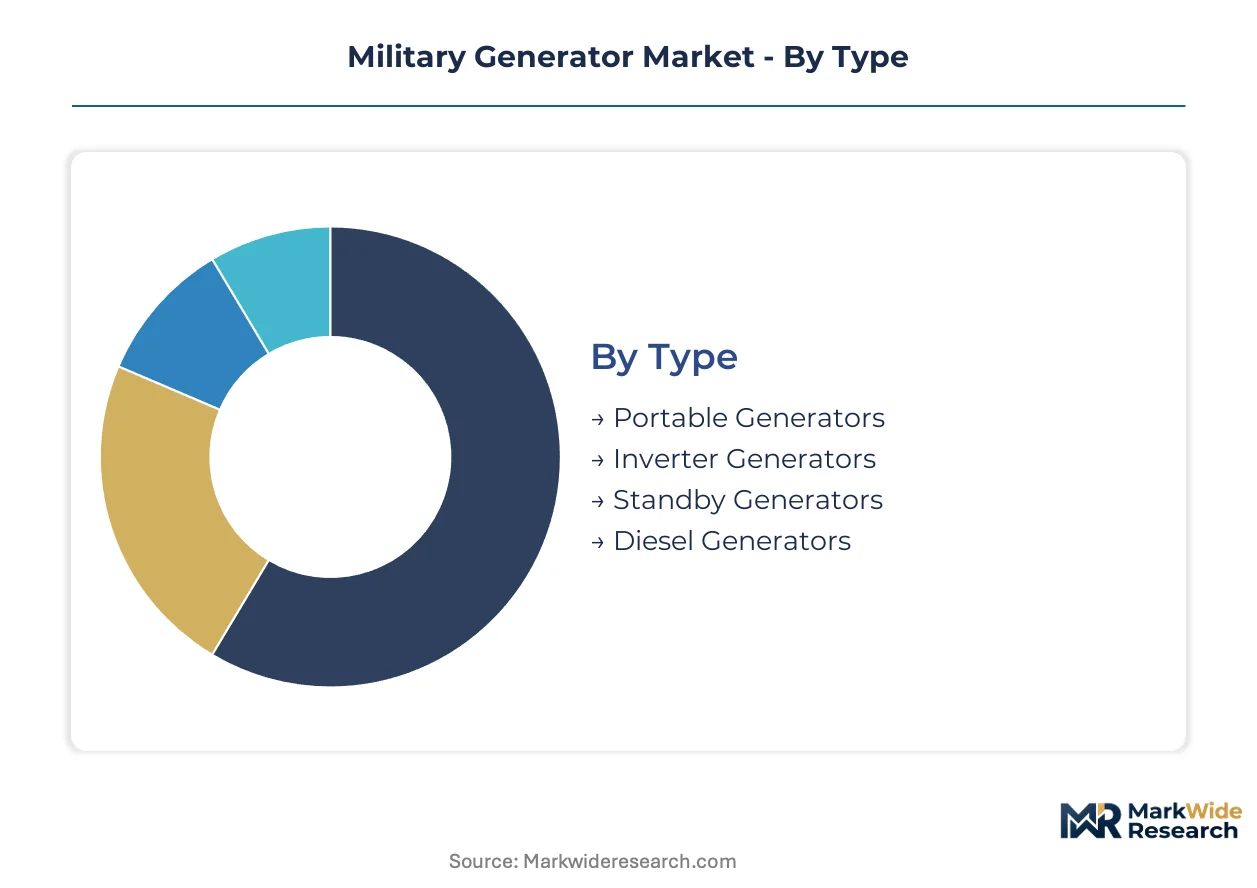
Military procurement officers segment generator acquisitions by operational tempo, signature requirements, and fuel logistics compatibility. Each dimension carries distinct certification burdens and lifecycle cost profiles that shape vendor qualification pathways.
Type:
Procurement budgets prioritize mobility against runtime duration when selecting generator configurations.
- Diesel Generators:These systems dominate brigade-level installations with JP-8 multi-fuel combustion architectures. The U.S. Army's Project Manager Mobile Electric Power sources these units for forward operating bases where energy density and established fuel logistics outweigh thermal signature concerns.
- Portable Generators:Compact skid-mounted units under 10 kW serve dismounted patrol bases and special operations teams. Australian Defence Force investments under the AUKUS framework are expanding procurement pipelines for these deployable systems across northern basing networks.
- Inverter Generators:Variable-speed electronic governing enables precise voltage regulation for sensitive command-and-control equipment. NATO STANAG electromagnetic interference shielding requirements add certification complexity.
- Standby Generators:Fixed installations at permanent military installations provide automatic failover for critical infrastructure. These units emphasize reliability over mobility.
Diesel generators lead on scale; portable generators lead on momentum.
Technology:
Emission compliance trajectories and signature reduction mandates are rebalancing technology procurement priorities across defense ministries.
- Diesel:EPA Tier 4 final aftertreatment architectures dominate current fleet procurement despite capital cost premiums. Caterpillar and Cummins anchor this segment with integrated engine-generator designs.
- Hybrid:Converged diesel-electric systems with intelligent load-following software are gaining specification traction. The EU Green Deal's defense energy efficiency targets are embedding minimum fuel efficiency thresholds in German and French tenders.
- Solar:Deployable photovoltaic arrays supplement generator runtime in extended silent-watch applications. These systems reduce thermal and acoustic signatures during reconnaissance operations.
- Gas Turbine:High-power-density turbines serve above-500 kW applications where weight constraints override fuel efficiency considerations. These units require specialized maintenance infrastructure.
Diesel technology leads on scale; hybrid configurations lead on momentum.
Power Output:
Mission duration and load diversity determine procurement band selection across expeditionary force structures.
- 101-500 kW:This band satisfies brigade-level camp power and mobile command post requirements without mobility penalties. The range captures the largest procurement value concentration as NATO members modernize tactical energy infrastructure.
- 10-50 kW:Compact units fit vehicle bays and shelter configurations for company-level detachments. Kohler Co. competes aggressively here on footprint-optimized designs.
- 51-100 kW:Battalion support units bridge tactical mobility and sustained runtime needs. These systems balance load capacity with transportability.
- Above 500 kW:Fixed-base and theater-level installations require these heavy systems. Mobility penalties restrict deployment to established logistics nodes.
The 101-500 kW band leads on scale; the 10-50 kW band leads on momentum.
Application:
Operational tempo and threat environment shape specification requirements across use cases.
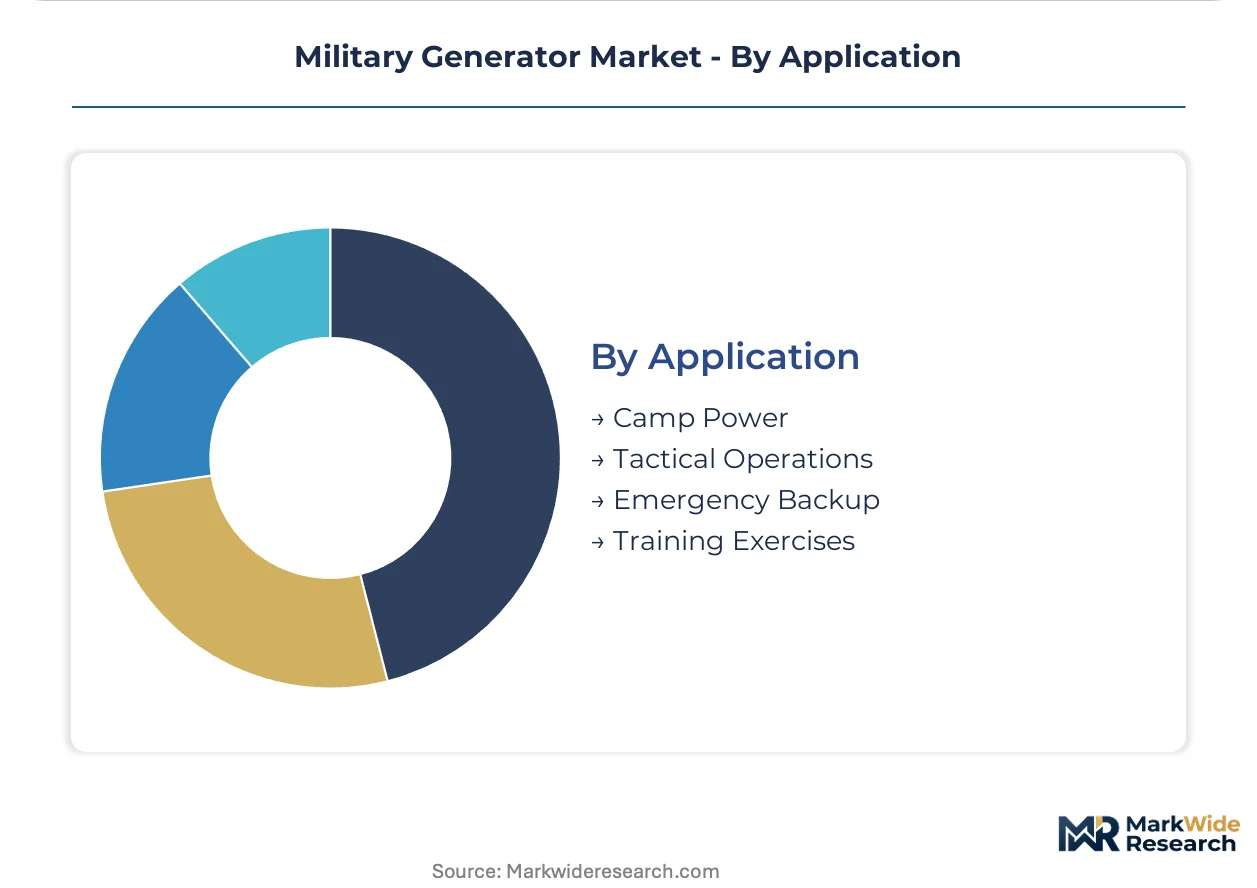
- Camp Power:Sustained prime power for semi-permanent forward operating bases drives procurement volume. Performance-based logistics contracts with ten-year availability guarantees are displacing traditional unit purchases in this application.
- Tactical Operations:Mobile command posts and maneuver units demand rapid deployment and signature management. Silicon carbide power semiconductors are enabling 40% volume reduction in constrained engine bays.
- Emergency Backup:Fixed military installations require automatic failover systems for critical infrastructure protection. Reliability metrics dominate procurement evaluation.
- Training Exercises:High-utilization scenarios prioritize fuel efficiency and maintenance accessibility over combat-specific features. These units often serve as fleet rotation assets.
Camp power leads on scale; tactical operations leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense engineering talent clusters in the United States, Germany, and Australia anchor procurement decision-making for expeditionary power systems. These concentrations shape technical specifications and testing protocols across NATO-aligned forces.
United States
Forward operating base electrification and AUKUS infrastructure investments drive procurement volume. EPA Tier 4 final emission standards compress supplier qualification toward aftertreatment-intensive designs. Huntsville, Alabama hosts concentrated defense contractor engineering operations supporting Project Manager Mobile Electric Power programs.
Germany
EU Green Deal defense energy efficiency targets reshape tender specifications for brigade-level camp power. NATO STANAG fuel interoperability mandates standardize multi-fuel combustion architectures. Munich and Stuttgart industrial corridors concentrate alternator and control module manufacturing for European defense supply chains.
Australia
Northern basing network expansion under AUKUS creates sustained demand for deployable power infrastructure. The country's national defense regulator embeds environmental operating envelope requirements in acquisition contracts. Brisbane and Darwin host growing maintenance and integration facilities for expeditionary generator fleets.
United Kingdom
Mobile command post modernization programs prioritize signature-reduced power systems for special operations support. Ministry of Defence procurement guidelines emphasize NATO interoperability standards. The Midlands defense manufacturing cluster sustains alternator winding and electromagnetic shielding capabilities.
Japan
Pacifist constitutional constraints channel investment into defensive power infrastructure rather than expeditionary platforms. METI industrial standards govern military-adjacent generator specifications for dual-use applications. Nagoya and Yokohama engineering centers develop compact footprint designs for constrained vehicle bays.
Military Generator Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across three discernible tiers. Integrated engine-generator architectures dominate the premium segment, while compact footprint specialists capture vehicle-integration contracts. The supplier base concentrates around EPA compliance capability and NATO STANAG certification holdings. Consolidation pressure intensifies as performance-based logistics contracts displace unit-purchase arrangements. Strategic moves cluster on backward integration into alternator manufacturing and geographic expansion into AUKUS-aligned procurement pipelines.
Within the integrated-systems tier, Caterpillar Inc. and Cummins Inc. exemplify engine-generator architecture consolidation. Caterpillar's Illinois-based operations represent conglomerate diversification into defense power systems. Cummins occupies a position emphasizing military-specific control software development. Kohler Co. anchors the compact-footprint specialist archetype, with Wisconsin-based manufacturing supporting shelter and vehicle bay constraints. These three sit within distinct competitive vectors: scale-driven platform breadth, software-defined load optimization, and dimensional engineering for constrained deployments.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Cummins Inc. |
| Honeywell International Inc. |
| Kohler Co. |
| MTU Onsite Energy |
| Generac Power Systems Inc. |
| Fischer Panda |
| HDT Global |
| Leonardo DRS |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists with multi-generational alternator manufacturing heritage anchor supply-side discipline across the United States and Germany, translating captive component production into pricing power that resists commoditization pressure from Asian system integrators.
Pricing Analysis
The bundled-vs-unbundled service split defines procurement economics across defense ministries. Three-tier pricing structure across premium, standard, and economy levels separates EPA Tier 4 final certified units with integrated aftertreatment from legacy export-tier configurations lacking emission controls. Price differentiation rests on certification grade and volume scale, with brigade-level camp power contracts commanding premiums for ten-year availability guarantees. Pricing pressure stems from lithium-ion battery substitution in silent-watch applications, compressing margins in sub-50 kW diesel segments. Training exercise procurement officers exhibit highest price sensitivity, while special operations vehicle integrators prioritize signature performance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements embedded in U.S. Army and NATO STANAG qualification protocols mandate multi-supplier qualification for high-reliability alternators and military-grade control modules. Geographic supply concentrates in the United States, Germany, and Japan, with Munich and Stuttgart industrial corridors feeding European defense supply chains. Raw material dependencies center on silicon carbide semiconductors, rare-earth magnetic materials, and JP-8 compatible fuel system components. Single-source vulnerability persists in MIL-STD-882E safety-critical software validation, where qualified engineering talent pools concentrate in Huntsville, Alabama and select German technical universities. Distribution runs through defense contractor prime integrators and direct military procurement channels with minimal aftermarket intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EPA Tier 4 final compliance costs in the United States and emerging EU Green Deal defense energy efficiency targets in Europe, with regulatory differential creating specification divergence that favors dual-certified product architectures.
For Market Incumbents: Deploy backward integration into alternator manufacturing to secure supply continuity against German and U.S. component concentration. Lock in ten-year performance-based logistics contracts with the U.S. Army Project Manager Mobile Electric Power before hybrid architectures mature. Battery substitution pressure in reconnaissance vehicle applications threatens sub-50 kW diesel volumes; counter with silicon carbide-enabled variable-speed systems that unify prime power and charging functions. For New Entrants and Emerging Players: The 40-60% price-point gap between premium EPA Tier 4 final systems and economy-tier export configurations creates white space in AUKUS-aligned Australian northern basing networks. Target portable generator procurement under 10 kW where Australian Defence Force expansion outpaces established vendor capacity. Enter through NATO STANAG fuel interoperability certification as a qualification wedge, then migrate to brigade-level camp power tenders. For Investors and Strategic Acquirers: Defense conglomerates with expeditionary power portfolios are the most active acquirer in this space, seeking alternator winding and electromagnetic shielding capabilities to fill architecture gaps. Long-term viability hinges on hybrid technology maturation displacing pure-diesel dominance over the mid-term horizon. Acquire compact-footprint specialists with shelter-integration expertise and existing MIL-STD-882E software certification to compress 18-24 month validation timelines. Monitor EU Green Deal defense annex implementation velocity as inflection indicator for European tender specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alternator Manufacturing | Captive supply of high-reliability rotating machinery insulates against German component concentration and NATO STANAG qualification bottlenecks. |
| Silicon Carbide Power Semiconductor Adoption | Variable-speed architectures enabled by SiC devices compress generator volume by 40% for special operations vehicle bays. |
| Performance-Based Logistics Contracting | Ten-year availability guarantees with the U.S. Army displace unit-purchase arrangements and concentrate vendor relationships. |
| EU Green Deal Defense Certification | German and French tender specifications now embed minimum fuel efficiency thresholds that require product line revalidation. |
| AUKUS Geographic Expansion | Northern Australian basing network investments under the security framework open sustained procurement pipelines for deployable power infrastructure. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with defense procurement officers, generator system engineers, alternator manufacturing specialists, and military logistics contractors with secondary validation against U.S. Department of Defense budget justification documents, NATO STANAG technical standards, EPA non-road diesel engine certification databases, and EU defense procurement tender archives. Bottom-up shipment tracking across power output bands and top-down defense budget allocation analysis provided cross-verification.
Comparable-period anchoring tied projection models to historical procurement cycles observed across expeditionary force modernization programs. The forecast framework spans type, technology, power output, and application dimensions alongside regional defense spending cluster analysis. CAGRs were derived from segmented demand build-up reflecting brigade-level camp power requirements, silent-watch signature reduction mandates, and JP-8 fuel logistics compatibility constraints. Hybrid architecture adoption curves and battery substitution thresholds informed scenario weighting.
The model assumes a particular technology adoption path; alternative pathways for silicon carbide power semiconductor integration or lithium-ion silent-watch displacement would alter the outlook. Forecasts reflect assumptions regarding NATO STANAG standardization velocity, EPA Tier 4 final enforcement consistency, and AUKUS infrastructure commitment durability. Deviation in EU Green Deal defense annex implementation timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Saudi Arabia Diesel Generator Market
Generators
Commercial Standby Generator Sets Market
Generators
Heat Recovery Steam Generator Sales Market
Generators
North America Generator Sets Market
Generators
Home Standby Gensets Market
Generators
Dual-Fuel Generator Market
Generators
Tri Fuel Generators Market
Generators
Wind Turbine Alternator Market
Generators
Telecom Generator Market
Generators
Europe Diesel Generator Market
Generators
Middle-East and Africa Generator Sets Market
Generators
Asia-Pacific Generator Sets Market
Generators
Tanzania Diesel Generator Market
Generators
Europe Turbo Generator Market
Generators
Emergency Power Generators Sales Market
Generators
Middle-East and Africa Diesel Generator Market