
 Commercial Standby Generator Sets Market | 2026-2036
Commercial Standby Generator Sets Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Standby Generator Sets Market Analysis
Data center operators are rotating toward higher-capacity standby generator sets as hyperscale cloud deployments multiply power redundancy requirements. Caterpillar dominates the above-200 kW segment through its integrated engine-alternator manufacturing scale. Cummins leverages its nationwide service network to anchor aftermarket revenue streams across healthcare and retail installations. Generac competes aggressively in the 51-100 kW range where distributed retail and small manufacturing demand clusters.
Commercial standby generator sets are self-contained power systems comprising an engine, alternator, cooling assembly, and automatic transfer switch designed to activate within 10 seconds of utility failure, with diesel configurations historically delivering the highest kilowatt density per unit footprint. Diesel generators still occupy the largest installed base across heavy industrial applications where fuel energy density and load-bearing capacity remain paramount. Gas generators are gaining fastest in data center and healthcare settings where emissions compliance and carbon reduction targets reshape procurement criteria. The above-200 kW power rating bracket captures the deepest margin pools due to engineering complexity and specialized installation requirements.
The US EPA enforces Tier 4 Final standards that limit nitrogen oxide and particulate emissions from non-road diesel engines, compelling manufacturers to integrate selective catalytic reduction or exhaust gas recirculation systems that raise unit costs and alter competitive economics. The EU F-Gas Regulation and CE marking requirements under the Machinery Directive shape product access across European member states, while India's CEA grid reliability mandates and BIS certification protocols accelerate formal standby power adoption in commercial construction. Stakeholders must monitor evolving emissions thresholds and fuel infrastructure availability as dual-fuel architectures reshape capital allocation across the product portfolio.
Market Dynamics
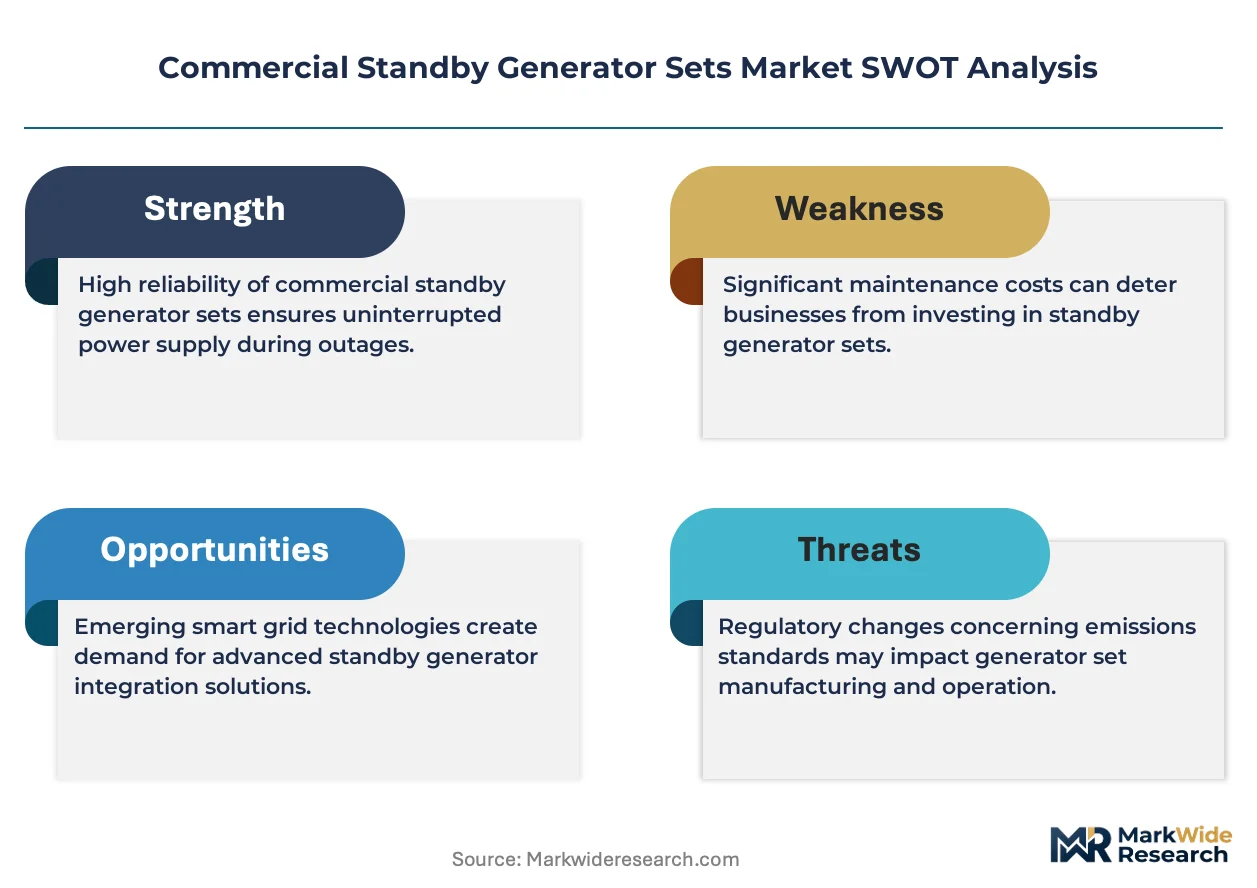
EPA Tier 4 Final compliance costs are compressing diesel generator margins while accelerating gas and bi-fuel architectures across data center and healthcare procurement. This regulatory pressure is restructuring manufacturer R&D allocation and reshaping competitive positioning in the above-200 kW segment.
Growth Catalysts
- Hyperscale Data Center Buildouts:Cloud computing operators are mandating N+1 or N+2 redundancy standards that double standby generator counts per facility. This procurement surge concentrates in Northern Virginia, Frankfurt, and Singapore metro clusters.
- CEA Grid Reliability Mandates:India's Central Electricity Authority now requires formal standby power systems in commercial buildings above specified load thresholds, accelerating formal adoption in Mumbai, Bangalore, and Hyderabad construction.
- Bi-Fuel Engine Architectures:Dual-fuel diesel-natural gas systems are penetrating hospital and university campuses where emissions compliance and fuel flexibility outweigh pure diesel density advantages.
Market Restraints
- Emissions Aftertreatment Cost Burden:Selective catalytic reduction and diesel particulate filter integration adds 15-25% to diesel unit production costs, eroding margin pools in the 50-150 kW range.
- Critical Component Supply Concentration:Alternator copper windings and engine control modules source predominantly from Chinese and German tier-two suppliers, exposing lead time volatility.
- Stationary Battery Substitution:Lithium-ion battery energy storage systems are capturing four-hour backup applications in commercial and light industrial settings where runtime requirements permit.
Strategic Opportunities
- Modular Containerized Systems:Skid-mounted and containerized generator packages are penetrating remote mining and oil & gas extraction sites in Western Australia, Chile, and Kazakhstan where permanent installation is uneconomical.
- EU Green Deal Hydrogen Readiness:The European Commission's hydrogen backbone infrastructure funding is prompting generator OEMs to engineer combustion chambers compatible with 20-30% hydrogen blending.
- Telecom Tower Electrification:India's tower infrastructure companies are replacing diesel-only systems with gas and bi-fuel alternatives to meet Department of Telecommunications carbon intensity targets.
Industry Challenges
- Field Service Technician Scarcity:EPA Tier 4 Final diagnostics and aftertreatment maintenance require specialized training that exceeds the current certified technician pipeline in North American distributor networks.
- Automatic Transfer Switch Integration Complexity:Synchronization with modern building management systems and microgrid controllers demands software engineering capabilities outside traditional generator OEM core competencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Standby Generator Sets Market |
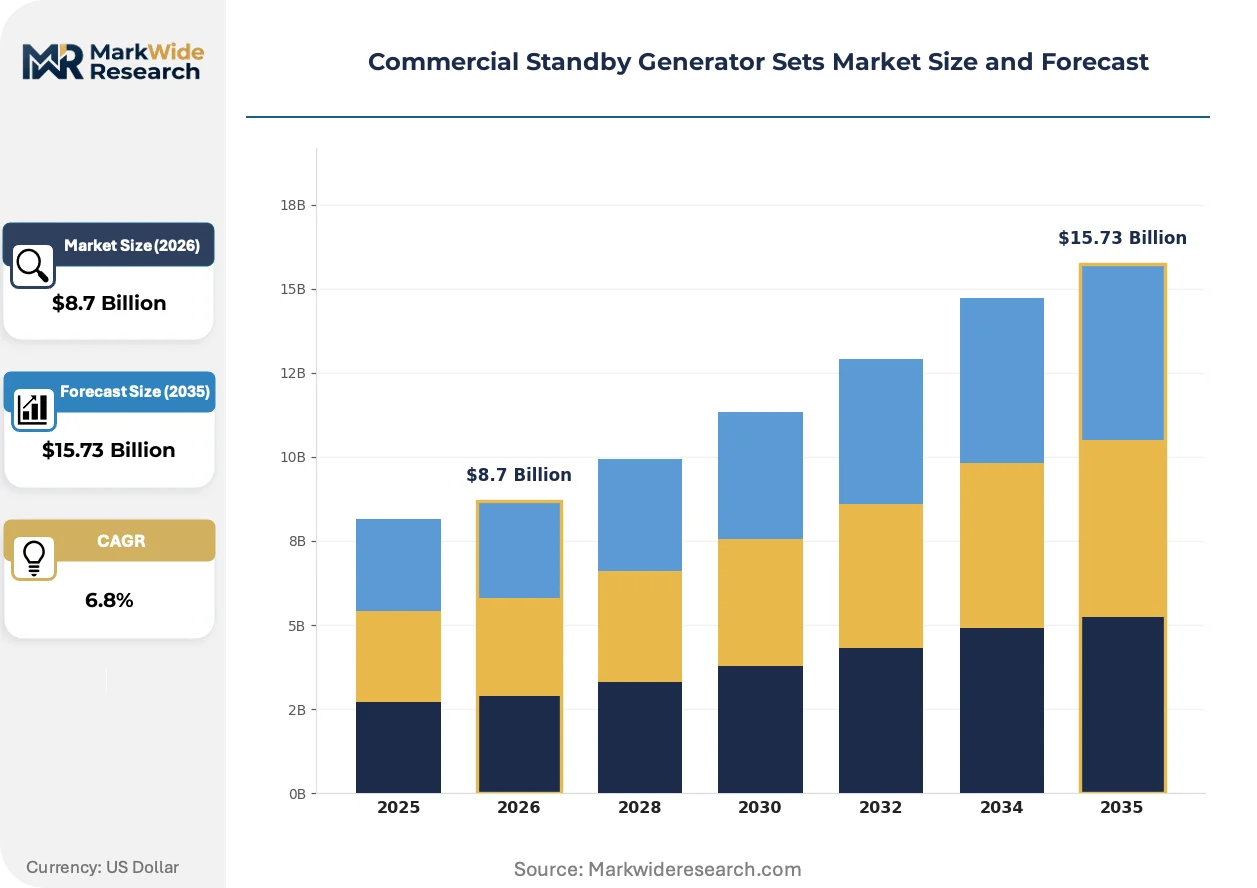
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel Generators, Gas Generators, Bi-Fuel Generators, Propane Generators Power Rating: 10-50 kW, 51-100 kW, 101-200 kW, Above 200 kW Installation: Indoor, Outdoor, Mobile, Permanent End User: Healthcare Facilities, Data Centers, Retail Outlets, Manufacturing Plants |
| Companies Covered | Caterpillar, Winco, Generac, MTU, Champion Power Equipment, Cummins, Briggs & Stratton, Honda, Kohler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Standby Generator Sets Market Emerging Trajectories
Digital load management and predictive maintenance architectures are transforming standby generator sets from passive insurance assets into active grid-interactive resources. This shift is compressing traditional service revenue models while opening software-centric value pools.
Power electronics-based variable speed drives are miniaturizing generator control systems while enabling precise frequency regulation. Data center operators are deploying these drives in hyperscale facilities across Ashburn and Phoenix to improve transient response during utility switching events. The technology is compressing mechanical governor component counts and shifting margin toward semiconductor suppliers.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in generator cooling circuits, compelling manufacturers to adopt CO2 or propane-based alternatives. This transition is extending engineering validation timelines by 12-18 months for European market entry. The above-500 kW segment is absorbing these compliance costs most readily through project-specific pricing.
Buyers are unbundling long-term maintenance contracts from initial equipment procurement, treating service as a separately negotiated performance-based agreement. Healthcare systems in Texas and California are leading this disintermediation, sourcing parts and labor through third-party service integrators. This pattern is compressing OEM captive service attach rates and forcing pricing transparency on spare parts catalogs.
Commercial Standby Generator Sets Market Segmentation
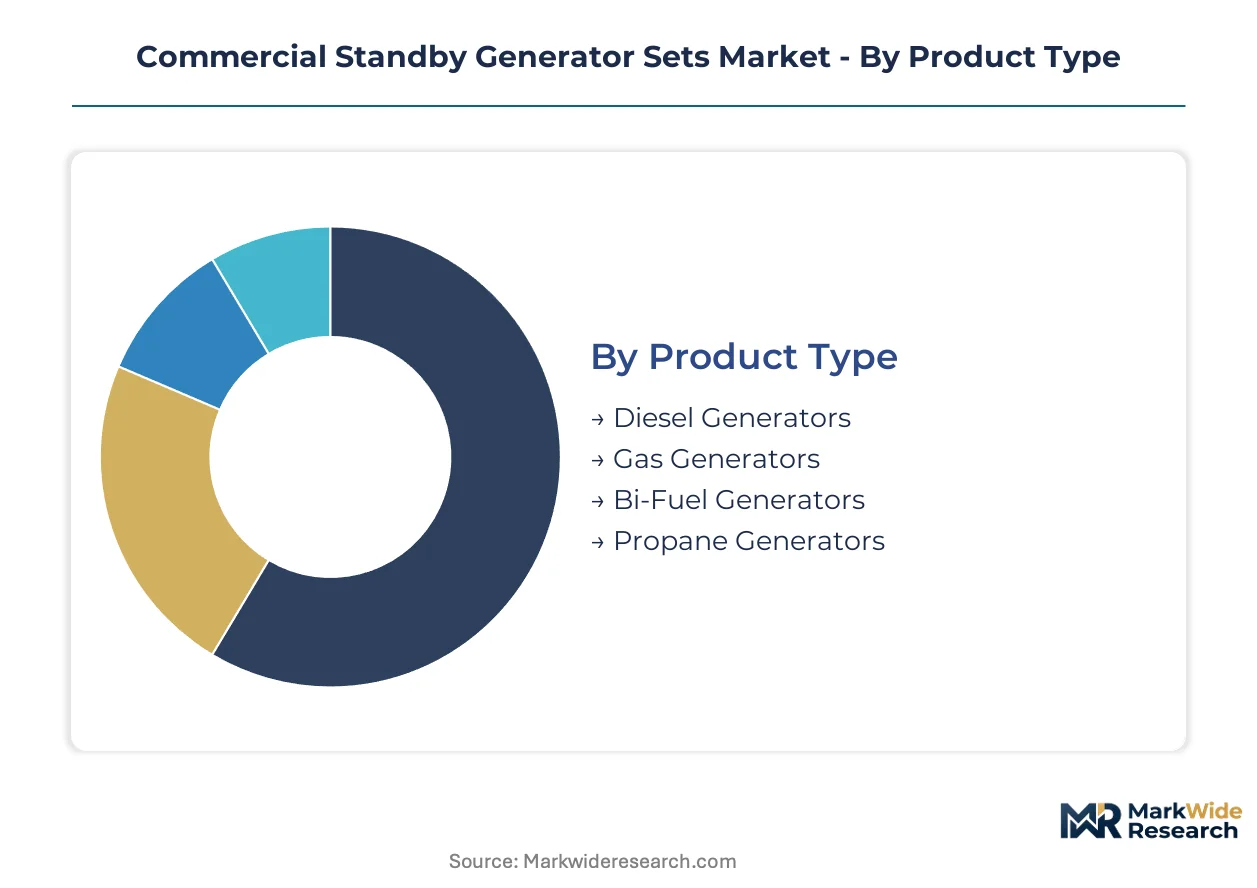
Segmentation in commercial standby generator sets reveals how regulatory pressure and application-specific runtime requirements fragment demand across fuel types, power classes, and installation modes. Buyers optimize for emissions compliance, footprint constraints, and redundancy architectures that vary sharply between hospital campuses and hyperscale data halls.
Product Type:
Diesel configurations face the most acute substitution pressure from battery storage and gas alternatives as EPA Tier 4 Final aftertreatment costs erode their historical cost advantage.
- Diesel Generators:Compression-ignition engines deliver the highest kilowatt density per unit footprint with sub-10-second startup capability. Demand concentrates in heavy manufacturing and mining operations across Texas, Western Australia, and Kazakhstan where load-bearing capacity outweighs emissions constraints. Tier 4 Final selective catalytic reduction systems add substantial production cost, compressing margins in the 50-150 kW range.
- Gas Generators:Spark-ignited natural gas engines eliminate diesel particulate filter maintenance while meeting stricter air quality standards. Procurement is accelerating in Northern Virginia and Frankfurt data center clusters where operators prioritize carbon intensity reduction and pipeline fuel security over liquid fuel density.
- Bi-Fuel Generators:Dual-fuel diesel-natural gas architectures provide runtime flexibility during pipeline disruption.
- Propane Generators:LPG configurations serve remote retail and telecom tower applications lacking natural gas infrastructure.
Diesel generators anchor the volume base while gas generators gain share at the steepest rate.
Power Rating:
Cost tier stratification separates commodity procurement in lower kilowatt brackets from engineered-to-order systems above 200 kW where specialized installation and synchronization command pricing power.
- Above 200 kW:Industrial-grade alternators and heavy-duty engine blocks require custom skid design, vibration isolation, and paralleling switchgear integration. Demand clusters in Mumbai, Bangalore, and Hyderabad hospital construction where India's CEA mandates formal standby power above specified load thresholds. Engineering complexity and site-specific engineering sustain the deepest margin pools.
- 101-200 kW:Mid-range systems balance packaged modularity with sufficient capacity for small manufacturing and commercial retail.
- 51-100 kW:Distributed retail and light industrial applications drive volume in this bracket.
- 10-50 kW:Compact residential-scale units adapted for small commercial backup face the strongest lithium-ion battery substitution threat in four-hour runtime applications.
The above-200 kW bracket commands the highest project values while 51-100 kW systems move the greatest unit volumes.
Installation:
Application context dictates whether permanent concrete pad construction or rapid deployment mobility delivers superior lifecycle economics.
- Permanent:Fixed concrete pad installations with integrated fuel tanks and weather enclosures dominate hospital and data center specifications. Procurement in Singapore and Frankfurt prioritizes seismic-rated enclosures and fire suppression integration for critical facility certification.
- Outdoor:Weatherproof enclosures with integrated cooling and noise attenuation serve retail and light industrial sites lacking dedicated mechanical rooms.
- Mobile:Trailer-mounted and skid-mounted packages penetrate Chilean and Kazakh mining operations where extraction site relocation outpaces permanent infrastructure payback periods.
- Indoor:Engine room installations with remote radiator configurations address urban footprint constraints and noise ordinances.
Permanent installations generate the longest service revenue streams while mobile configurations expand most quickly in resource extraction geographies.
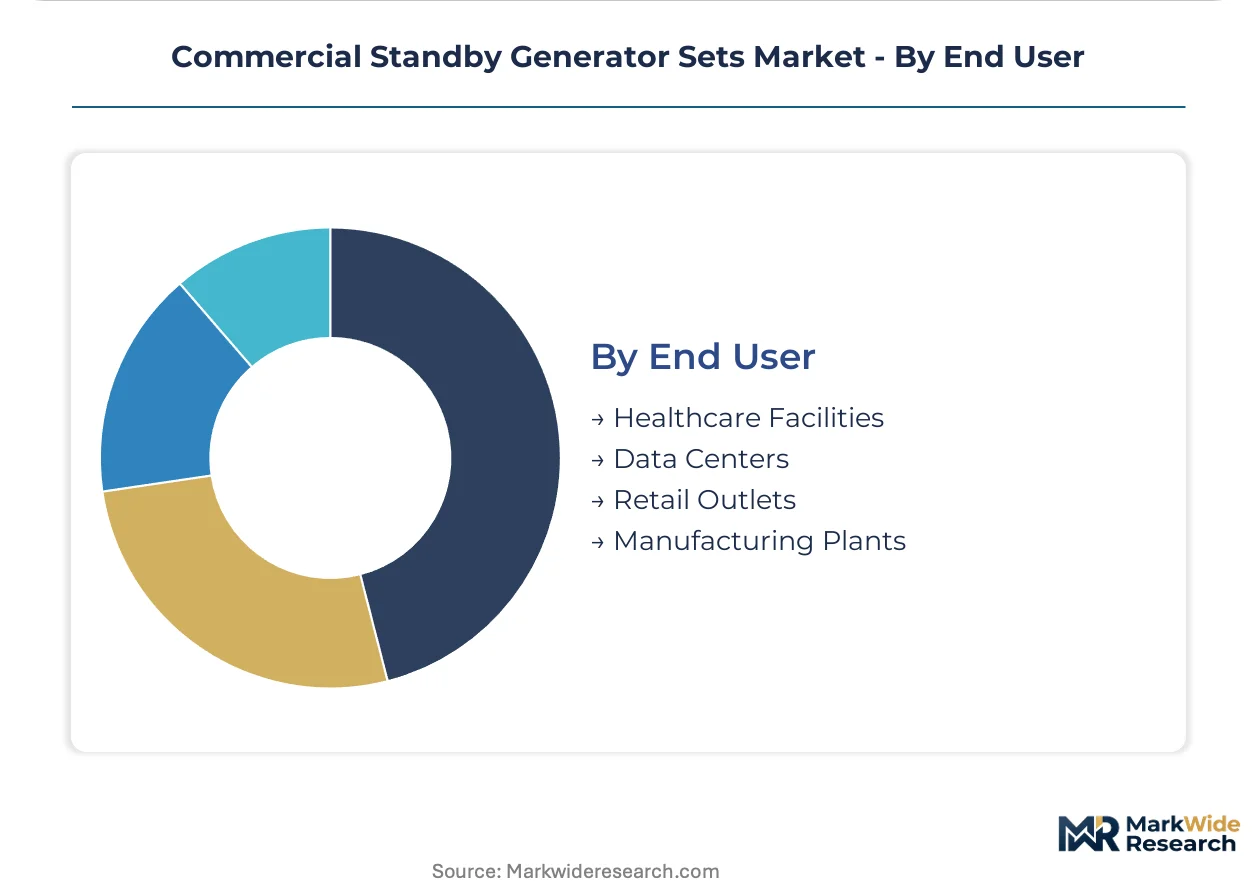
End User:
Customer type determines whether procurement prioritizes life-safety code compliance, uptime SLA guarantees, or inventory protection economics.
- Data Centers:Hyperscale cloud operators mandate N+1 or N+2 redundancy architectures that double generator counts per facility. Ashburn and Phoenix deployments specify sub-500 millisecond transient response and paralleling capability for seamless utility switching.
- Healthcare Facilities:Joint Commission accreditation and CMS emergency preparedness rules require automatic startup within 10 seconds for life safety circuits. Texas and California health systems are unbundling maintenance contracts from equipment procurement, sourcing third-party service integrators.
- Manufacturing Plants:Continuous process industries prioritize fuel energy density and load acceptance capability over emissions profiles.
- Retail Outlets:Distributed store networks favor standardized 51-100 kW packages with remote monitoring for fleet management.
Data centers drive the steepest capacity expansion while healthcare facilities sustain the most predictable replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States interstate natural gas pipeline network underwrites North American standby generator deployment by ensuring fuel security for gas-fired backup systems. Grid reliability concerns and hyperscale data center construction drive procurement concentration across specific metropolitan clusters.
United States
Hyperscale data center buildouts in Northern Virginia and Phoenix mandate N+1 redundancy configurations that double generator counts per facility. EPA Tier 4 Final standards enforce nitrogen oxide and particulate emissions limits through selective catalytic reduction requirements. Ashburn and Phoenix metro clusters specify sub-500 millisecond transient response capabilities for seamless utility switching.
Germany
Industrial manufacturing resilience and healthcare facility accreditation sustain demand for above-200 kW engineered systems. EU F-Gas Regulation phases down hydrofluorocarbon refrigerants in generator cooling circuits, extending validation timelines. Frankfurt data center operators prioritize carbon intensity reduction through natural gas generator procurement.
China
Cloud computing expansion and semiconductor fabrication facility construction accelerate backup power requirements in eastern provinces. GB standards and dual carbon goals reshape procurement criteria toward lower-emission configurations. Yangtze River Delta manufacturing clusters deploy permanent installations with integrated fuel storage for process continuity.
India
Commercial construction growth and formal standby power mandates drive adoption across hospital and retail buildouts. CEA grid reliability requirements now obligate formal backup systems in buildings above specified load thresholds. Mumbai, Bangalore, and Hyderabad construction markets absorb the fastest capacity additions.
Singapore
Financial services data center concentration and tropical climate resilience requirements sustain premium generator specifications. Seismic-rated enclosures and fire suppression integration dominate procurement criteria. The city-state's metro cluster prioritizes sub-10-second startup capability for critical facility certification.
Commercial Standby Generator Sets Market Vendor Landscape
Listed leaders compete with private specialists across integrated manufacturing scale and aftermarket service reach. The vendor base separates into engine-alternator integrators, national service network operators, and modular packaging specialists. Three archetypes dominate: full-stack manufacturers controlling core component production, distribution-heavy players monetizing maintenance contracts, and regional fabricators serving project-specific requirements. Capacity expansion and strategic partnerships constitute the primary competitive vectors.
Within the full-stack manufacturing tier, Caterpillar and Cummins exemplify integrated production architectures. Caterpillar occupies a position defined by above-200 kW engineering complexity and captive engine-alternator manufacturing. Cummins anchors the service-intensive archetype through nationwide distributor networks. Generac represents the mid-range volume specialist competing aggressively in distributed retail and light industrial brackets.
| Leading Market Players |
|---|
| Caterpillar |
| Winco |
| Generac |
| MTU |
| Champion Power Equipment |
| Cummins |
| Briggs & Stratton |
| Honda |
| Kohler |
| Others |
Supply Flow & Price Mechanics
EPA Tier 4 Final certification gates both supplier qualification and price differentiation across the commercial standby generator sets market, compelling manufacturers to absorb selective catalytic reduction costs while OEMs with captive engine production command premium positioning. This regulatory threshold simultaneously filters tier-two assemblers from the above-200 kW bracket and stratifies pricing power among integrated manufacturers versus packaging specialists.
Pricing Analysis
Volume-discount tiering structures separate project-specific above-200 kW systems from standardized 51-100 kW packages, with premium pricing anchored in engineering complexity and site-specific customization. Price differentiation stems from EPA Tier 4 Final certification status and after-sales service bundling, where integrated engine-alternator manufacturers capture margin pools unavailable to third-party assemblers. Pricing pressure intensifies in the 50-150 kW diesel segment as battery storage substitutes erode runtime economics for four-hour applications. Healthcare systems exhibit the lowest price sensitivity due to Joint Commission compliance mandates, while distributed retail chains drive commoditization through fleet standardization.
Supply Chain Analysis
China and Germany anchor alternator copper winding and engine control module production, with tier-two suppliers in both countries feeding integrated manufacturers and independent packagers alike. Component sourcing draws from Chinese rare earth processing for permanent magnet alternators and German precision machining for fuel injection systems. Single-source vulnerability concentrates in semiconductor-based engine control modules subject to foundry allocation volatility. Distribution runs through authorized dealer networks for aftermarket service capture, with direct OEM relationships dominating hyperscale data center procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial standby generator sets represent an early-cycle expansion story as India's CEA grid reliability mandates formalize standby power adoption across commercial construction, accelerating penetration in markets previously reliant on informal backup solutions.
For Market Incumbents: Fortify aftermarket service attach rates by embedding predictive maintenance platforms into original equipment contracts before third-party integrators capture healthcare disintermediation. Deepen backward integration into alternator winding production to insulate margin pools from Chinese copper supply volatility. Prioritize EPA Tier 4 Final diagnostic certification across distributor networks to address field technician scarcity.
For New Entrants and Emerging Players: CE marking fast-track programs unlock European market access for modular containerized systems targeting remote mining operations in Kazakhstan and Chile. Bi-fuel architecture specialization penetrates hospital and university campuses where emissions compliance and fuel flexibility outweigh pure diesel density. Partner with telecom tower operators in India to displace diesel-only legacy installations under Department of Telecommunications carbon intensity targets.
For Investors and Strategic Acquirers: EPA Tier 4 Final compliance deadlines reshape the acquisition landscape toward targets with certified engine-alternator integration and established service networks. Long-term viability centers on dual-fuel R&D capabilities and software-defined load management architectures. Monitor lithium-ion battery cost curves as the critical signal for substitution threat intensity in sub-four-hour runtime segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Bi-Fuel Engine Certification | Unlocks hospital and data center procurement where emissions compliance reshapes vendor selection criteria. |
| Predictive Maintenance Platform Launch | Transforms passive insurance assets into active grid-interactive resources with recurring software revenue. |
| Containerized System Scale-Up | Captures remote mining and oil & gas extraction demand where permanent installation payback periods fail. |
| Hydrogen Combustion R&D Partnership | Positions product lines for EU Green Deal hydrogen backbone infrastructure deployment timelines. |
| Third-Party Service Integrator Acquisition | Recaptures maintenance revenue streams disintermediated by Texas and California healthcare procurement patterns. |
Methodological Framework
Desk research of customs trade databases, EIA power generation statistics, and EPA regulatory filings preceded structured interviews with data center facility engineers, hospital procurement directors, generator OEM product managers, and aftermarket service network heads. Primary fieldwork across Northern Virginia, Frankfurt, Mumbai, and Singapore metro clusters validated installation specifications and procurement criteria. Secondary triangulation incorporated FERC interconnection queue data, hyperscaler capex disclosures, and CEA mandate implementation timelines. Bottom-up unit economics and top-down market sizing converged through iterative reconciliation.
Variance decomposition across fuel type, power rating bracket, and installation mode anchored the analytical framework over the projection horizon. Segmentation modeling incorporated end-use redundancy architecture, regional emissions regulatory cluster, and service contract attachment rate as core dimensions. CAGRs derived from logistic diffusion curves fitted to historical penetration patterns in comparable infrastructure equipment categories. Forecast inputs included data center power density trends, natural gas pipeline expansion schedules, and battery storage cost trajectories.
Decision-makers should treat outputs as directional under base assumptions of sustained hyperscale data center construction and incremental emissions regulatory tightening; material deviation in either driver would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
North West Europe Diesel Generator Market
Generators
Industrial Generator Market
Generators
China Generator Sets Market
Generators
Gas Generator Sets Market
Generators
Generator Sales Market
Generators
Boiler, Turbine, and Generator (BTG) Market
Generators
Heat Recovery Steam Generator Sales Market
Generators
South America Portable Generator Market
Generators
Construction Prime Power Generators Market
Generators
Power Generator for Military Market
Generators
Hand Crank Power Generator Market
Generators
Portugal Gas Generator Market
Generators
Industrial Generator Sets Market
Generators
Europe Diesel Generator Market
Generators
Tri Fuel Generators Market
Generators
Residential Gas Generator Market