
 HVAC Electronically Commutated Motor (ECM) Market | 2026-2036
HVAC Electronically Commutated Motor (ECM) Market Size, Share, and Industry Trends Forecast 2026-2036
HVAC Electronically Commutated Motor (ECM) Market Intelligence
Copper winding material is rebalancing motor cost structures as manufacturers substitute aluminum in select radial ECM platforms to offset commodity volatility. ABB Ltd. leverages its permanent magnet synchronous technology leadership across European industrial ventilation installations. Nidec Corp. anchors high-volume production for residential HVAC systems through dedicated facilities in Mexico and China. ebm papst Mulfingen GmbH and Co. KG differentiates via proprietary sensorless control algorithms that reduce bill-of-materials complexity for plug-fan ECM variants.
An HVAC Electronically Commutated Motor (ECM) is a brushless DC motor with integrated electronic commutation circuitry, typically operating at 24V to 277V input with efficiency ratings exceeding 80% across variable speed ranges, designed to modulate airflow in heating, ventilation, and air conditioning equipment. Its primary commercial purpose is to replace permanent split capacitor motors, cutting energy consumption by half in blower and fan applications while enabling precise variable-speed control. Radial ECM units dominate commercial air handler installations where static pressure requirements are highest, while plug-fan ECM architectures capture expanding share in data center cooling as facility operators prioritize modular redundancy. Multi-phase ECM technology leads R&D investment intensity due to superior torque density for laboratory exhaust systems requiring rapid ramp rates.
The US Department of Energy furnace fan efficiency standards and the EU Ecodesign Directive jointly mandate minimum performance thresholds that eliminate conventional PSC motor sales in new equipment. China's GB standards for motor efficiency, administered by SAMR, require IE3-equivalent performance for motors above specified power thresholds, compressing market access for non-compliant imports. Building management firms and energy service companies must monitor regulatory divergence between jurisdictions to avoid stranded inventory and certification gaps.
Market Dynamics
The US Department of Energy furnace fan efficiency standards are compressing the installed base of permanent split capacitor motors and forcing OEMs to redesign air handler platforms around ECM architectures ahead of enforcement deadlines.
Growth Catalysts
- Building electrification mandates:State-level decarbonization requirements in California, New York, and Washington are accelerating furnace-to-heat-pump conversions that specify variable-speed ECM blowers for cold-climate performance.
- Utility rebate programs:Midwestern and Sun Belt utilities offer point-of-sale incentives for ECM-equipped HVAC systems, shortening payback periods for residential retrofits below three years.
- Sensorless control algorithms:Elimination of Hall-effect sensors from plug-fan ECM designs reduces component count and field failure rates in data center cooling modules.
Market Restraints
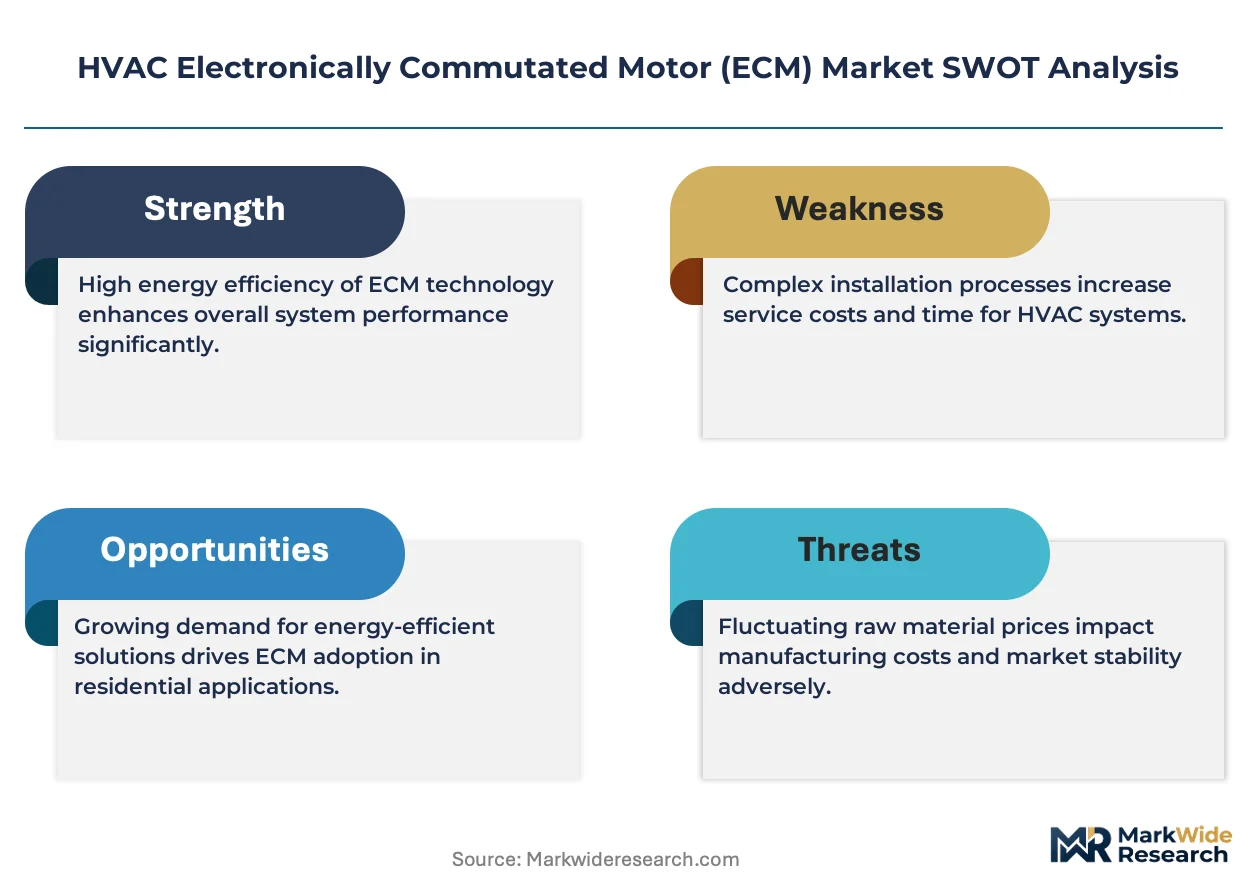
- Copper price volatility:Winding material cost swings above historical baselines compress gross margins for manufacturers maintaining aluminum-to-copper substitution flexibility.
- Rare earth magnet supply concentration:Neodymium and dysprosium sourcing dependence on Chinese processing infrastructure creates geopolitical exposure for permanent magnet synchronous motor platforms.
- PSC motor inventory overhang:Distributor stockpiles of pre-standard changeover equipment in secondary markets delay full ECM penetration in replacement channels.
Strategic Opportunities
- Data center modular cooling:Hyperscale operators in Northern Virginia and Frankfurt are specifying redundant plug-fan ECM arrays for hot-aisle containment retrofits.
- EU F-Gas Regulation phase-down:Refrigerant transition timelines are driving chiller OEMs toward variable-speed compressor-condenser fan integration with multi-phase ECM systems.
- Direct-to-contractor distribution:Bypass of traditional wholesaler channels via manufacturer portals captures margin and installation data for residential HVAC contractors.
Industry Challenges
- Power electronics skill scarcity:Field service technician training lags behind inverter-drive diagnostic requirements for ECM-equipped systems.
- Multi-jurisdiction certification fragmentation:Divergent efficiency test procedures between DOE furnace fan standards and EU Ecodesign Directive create redundant laboratory validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVAC Electronically Commutated Motor (ECM) Market |
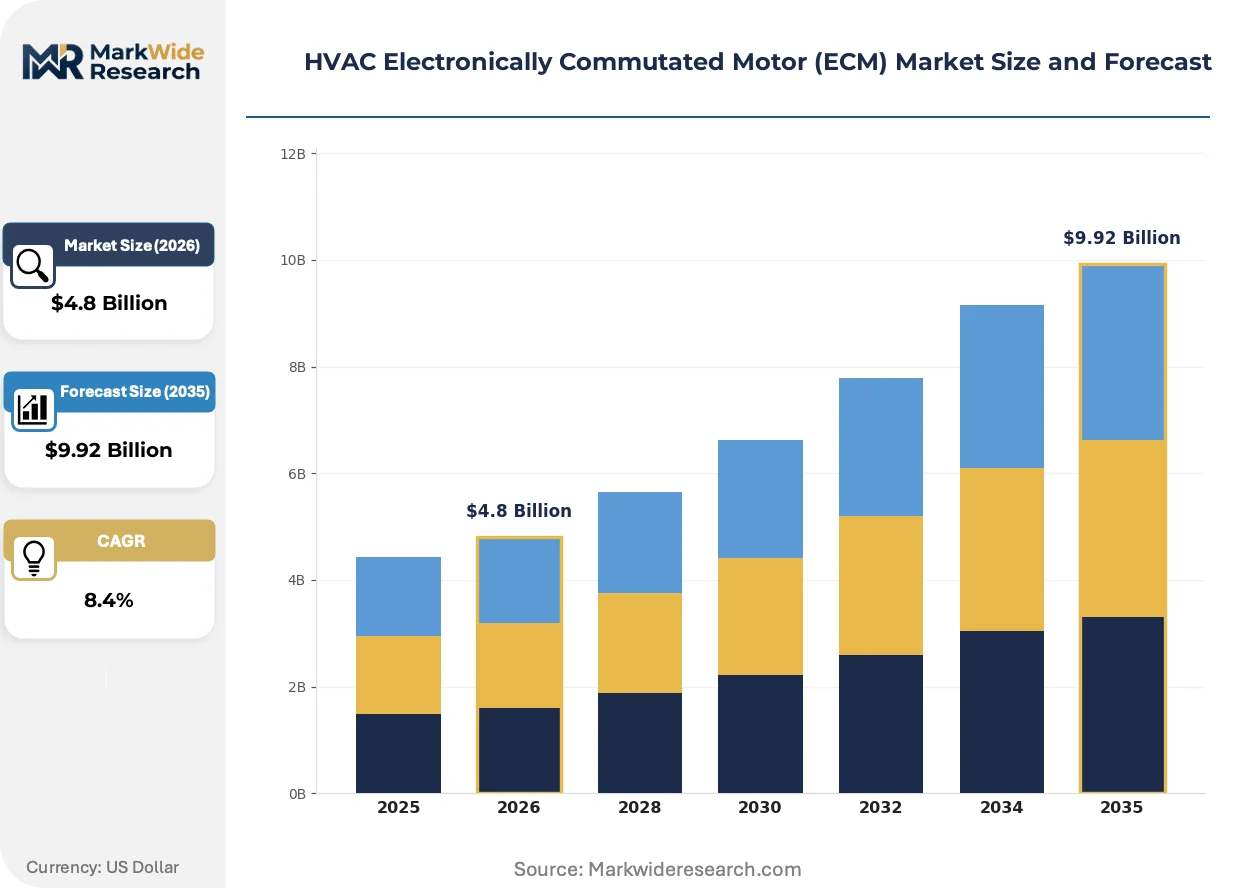
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial ECM, Tangential ECM, Multi-Phase ECM, Plug-Fan ECM, Universal ECM Technology: Brushless DC, Permanent Magnet Synchronous, Sensorless Control, Closed Loop Feedback, Variable Frequency Drive Application: Commercial Air Handlers, Residential HVAC Systems, Industrial Ventilation, Data Center Cooling, Laboratory Exhaust Systems End User: Building Management Firms, HVAC Equipment Manufacturers, Energy Service Companies, Facility Maintenance Providers |
| Companies Covered | Delta Electronics Inc., Parker Hannifin Corp., ABB Ltd., Regal Rexnord Corp., WEG S.A., Nidec Corp., ebm papst Mulfingen GmbH and Co. KG, Oriental Motor Co. Ltd., Johnson Electric Holdings Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVAC Electronically Commutated Motor (ECM) Market Strategic Shifts & Innovations
ECM technology trajectories center on magnetic material efficiency, embedded intelligence, and thermal management advances that reduce system-level energy intensity while expanding operational envelopes.
Multi-phase permanent magnet synchronous motor architectures are consolidating torque density advantages for laboratory exhaust and industrial ventilation applications requiring rapid ramp-to-speed sequences. Pharmaceutical manufacturing facilities and semiconductor cleanrooms specify these platforms for emergency purge scenarios. The technology is consolidating market share from single-phase ECM variants in static pressure-critical installations above two inches water column.
The EU Ecodesign Directive's 2019 fan efficiency requirements and subsequent tiered updates are eliminating backward-curved impeller designs paired with PSC motors from new equipment sales. Industrial ventilation OEMs serving European markets have retooled production lines to standardized ECM-impeller combinations. Affected product categories include kitchen exhaust systems and air handling units below 10 kilowatts rated power.
Specification authority is migrating from mechanical contractors to energy service companies and building automation integrators who bundle ECM-based HVAC upgrades with measurement-and-verification contracts. This procurement pattern concentrates decision-making in multi-site commercial portfolios and displaces traditional equipment-only bidding. The shift is most pronounced in Class-A office building retrofits across Chicago, Dallas, and Atlanta metropolitan markets.
HVAC Electronically Commutated Motor (ECM) Market Segmentation
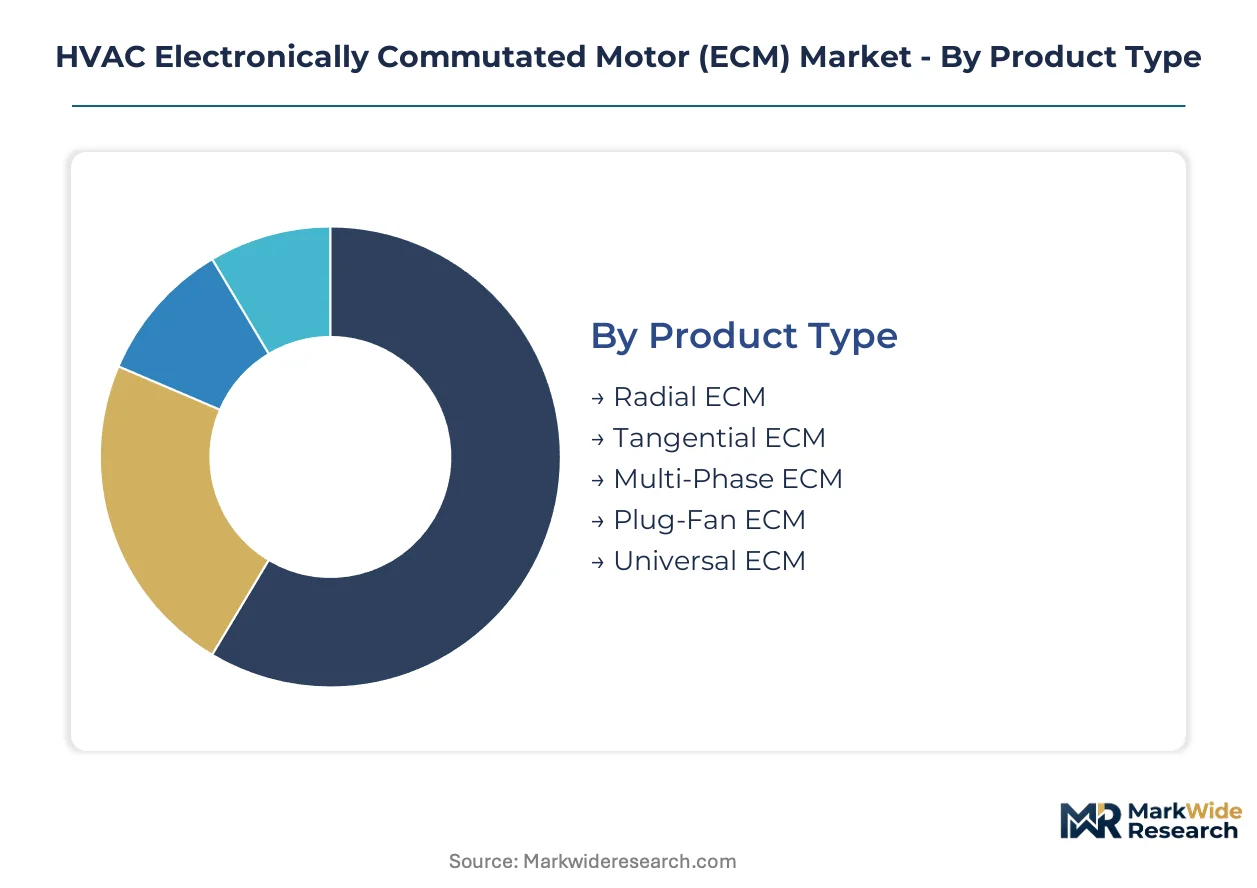
ECM segmentation reveals divergent technology paths across static pressure requirements and control sophistication. Product architecture choices cascade through efficiency certification tiers and end-use qualification barriers.
Product Type:
Volume concentrates in standardized radial platforms while premium capture shifts toward multi-phase and plug-fan architectures with embedded intelligence.
- Radial ECM:Backward-curved impeller integration dominates commercial air handler specifications above two inches water column static pressure. Midwestern mechanical contractors specify these for hospital and school retrofits where legacy PSC motor replacement deadlines are tightening.
- Multi-Phase ECM:Three-phase permanent magnet synchronous designs deliver torque density for laboratory exhaust systems requiring sub-10-second ramp to emergency purge speeds. Pharmaceutical manufacturing facilities in New Jersey and North Carolina specify these for containment-critical fume hood applications.
- Tangential ECM:Cross-flow blower configurations serve residential air curtain and PTAC unit manufacturers seeking compact form factors.
- Plug-Fan ECM:Modular array architectures capture data center cooling redundancy specifications in Northern Virginia and Frankfurt hyperscale developments.
- Universal ECM:Multi-voltage programmable platforms reduce distributor SKU complexity for residential HVAC service replacement channels.
Today's leader: Radial ECM. Tomorrow's challenger: Plug-Fan ECM.
Technology:
Control methodology separates commodity replacement motors from premium variable-speed platforms commanding specification authority.
- Brushless DC:Electronically commutated architectures with trapezoidal back-EMF detection form the baseline for residential furnace fan retrofits. DOE furnace fan efficiency standards are compressing PSC motor alternatives and accelerating platform transitions across Midwestern utility rebate territories.
- Sensorless Control:Elimination of Hall-effect position sensors reduces component count and field failure rates in data center plug-fan arrays. ebm papst proprietary algorithms enable this architecture across modular cooling deployments.
- Permanent Magnet Synchronous:Sinusoidal current control delivers efficiency above 85% for industrial ventilation above 5 horsepower.
- Closed Loop Feedback:Encoder-based speed verification serves pharmaceutical cleanroom pressurization requiring ±1% airflow tolerance.
- Variable Frequency Drive:Discrete inverter-motor pairings persist in chiller condenser fan retrofits where ECM integration costs exceed replacement economics.
Sensorless control is climbing the fastest. Brushless DC holds installed base dominance.
Application:
Building electrification mandates are reshaping demand concentration across climate zones and equipment replacement cycles.
- Residential HVAC Systems:Variable-speed blower motors for heat pump conversions specify ECM platforms for cold-climate coefficient of performance requirements. California and New York decarbonization timelines are accelerating furnace-to-heat-pump retrofits with integrated ECM air handlers.
- Data Center Cooling:Hot-aisle containment retrofits specify redundant plug-fan ECM arrays for modular capacity scaling. Northern Virginia hyperscale operators prioritize these for PUE reduction commitments.
- Commercial Air Handlers:Static pressure-optimized radial ECM dominates new construction and major renovation specifications.
- Industrial Ventilation:Heavy-duty multi-phase platforms serve manufacturing exhaust with intermittent high-load emergency purge requirements.
- Laboratory Exhaust Systems:Rapid-ramp multi-phase ECM specifies for semiconductor and pharmaceutical containment facilities requiring emergency ventilation protocols.
Residential HVAC Systems command volume leadership. Data Center Cooling shows steepest expansion trajectory.
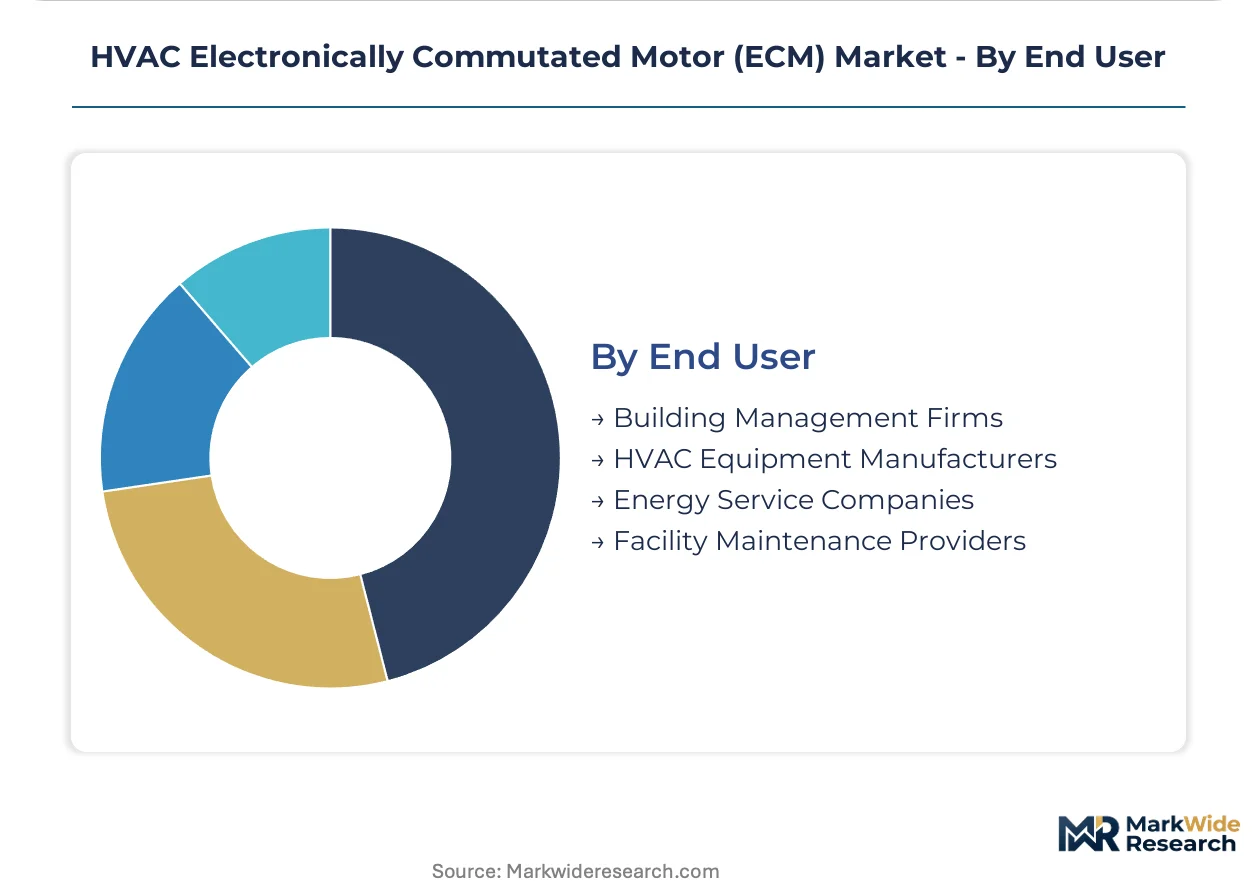
End User:
Procurement authority migration from mechanical contractors to energy service companies is restructuring specification influence.
- HVAC Equipment Manufacturers:OEM platform redesigns around ECM architectures respond to DOE furnace fan efficiency enforcement deadlines and EU Ecodesign Directive tiered requirements. Production line retooling for standardized ECM-impeller combinations is complete across major residential furnace producers.
- Energy Service Companies:Measurement-and-verification contract bundling concentrates decision-making for multi-site commercial portfolios. Chicago and Atlanta Class-A office retrofits increasingly specify ESCO-led ECM upgrades with guaranteed savings performance.
- Building Management Firms:Centralized procurement for commercial portfolios drives standardized ECM specifications across properties.
- Facility Maintenance Providers:Direct-to-contractor distribution channels are capturing installation data and margin from traditional wholesaler relationships.
HVAC Equipment Manufacturers anchor current volume. Energy Service Companies are gaining specification authority fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand concentration anchors regional patterns as building electrification mandates and utility rebate programs accelerate replacement cycles across Midwestern and Sun Belt metropolitan markets.
United States
State-level decarbonization requirements in California and New York are accelerating furnace-to-heat-pump conversions that specify variable-speed ECM blowers for cold-climate performance. DOE furnace fan efficiency standards are compressing permanent split capacitor motor alternatives ahead of enforcement deadlines. Northern Virginia hyperscale data center operators specify redundant plug-fan ECM arrays for hot-aisle containment retrofits and PUE reduction commitments.
China
GB standards administered by SAMR mandate IE3-equivalent motor efficiency performance above specified power thresholds, compressing market access for non-compliant imports. Dual carbon goals are driving industrial ventilation upgrades in manufacturing corridors. Yangtze River Delta pharmaceutical facilities specify multi-phase ECM platforms for laboratory exhaust systems requiring rapid emergency purge capabilities.
Germany
EU Ecodesign Directive tiered fan efficiency requirements are eliminating backward-curved impeller designs paired with PSC motors from new equipment sales. F-Gas Regulation phase-down timelines are driving chiller OEMs toward variable-speed compressor-condenser fan integration. Industrial ventilation producers serving European markets have retooled production lines to standardized ECM-impeller combinations.
Japan
METI efficiency programs and JIS standards are accelerating residential HVAC system retrofits with ECM-equipped heat pumps. Semiconductor cleanroom construction in Kyushu and Kansai regions specifies multi-phase permanent magnet synchronous motors for containment-critical fume hood applications. Building automation integrators are bundling ECM-based upgrades with measurement-and-verification contracts.
India
Bureau of Energy Efficiency mandates and state-level building codes are creating specification pressure for variable-speed motor platforms in commercial air conditioning. Maharashtra and Gujarat manufacturing corridors are seeing industrial ventilation OEM platform redesigns around ECM architectures. Data center construction in Bengaluru and Hyderabad is specifying modular plug-fan arrays for cooling redundancy.
HVAC Electronically Commutated Motor (ECM) Market Key Industry Players
Capacity expansion dominates the current landscape as manufacturers establish dedicated production facilities to serve regional demand clusters. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with permanent magnet motor portfolios, specialized ventilation component producers with proprietary control algorithms, and high-volume residential HVAC suppliers with Mexico and China manufacturing footprints. M&A activity and geographic expansion constitute the dominant competitive moves as players seek to capture utility rebate program specifications and data center cooling contracts.
Within the diversified industrial tier, ABB Ltd. and Regal Rexnord Corp. exemplify integrated motor-drive platform strategies spanning European and North American markets. Nidec Corp. occupies a position as a scale-driven supplier with dedicated high-volume production infrastructure. Among specialized ventilation component producers, ebm papst Mulfingen GmbH and Co. KG represents sensorless control algorithm differentiation for plug-fan architectures.
| Leading Market Players |
|---|
| Delta Electronics Inc. |
| Parker Hannifin Corp. |
| ABB Ltd. |
| Regal Rexnord Corp. |
| WEG S.A. |
| Nidec Corp. |
| ebm papst Mulfingen GmbH and Co. KG |
| Oriental Motor Co. Ltd. |
| Johnson Electric Holdings Ltd. |
| Others |
Cost & Logistics Intelligence
Backward integration into rare earth magnet processing anchors supply position and pricing power for permanent magnet synchronous motor platforms, with Chinese concentrate refining dominance forcing Western manufacturers to absorb cost volatility or pursue alternative magnetic material formulations under SAMR export licensing frameworks.
Pricing Analysis
Input-cost pass-through from copper winding materials and neodymium-dysprosium magnet pricing shapes transactional per-unit pricing across radial and plug-fan ECM tiers. Price differentiation separates IE3-certified premium platforms from standard-efficiency residential replacements, with brand premium and volume scale as secondary drivers. Cost compression in mid-tier radial ECM is intensifying because aluminum-to-copper substitution flexibility has narrowed. Residential HVAC contractors show highest price sensitivity; data center operators demonstrate lowest sensitivity due to PUE-driven total-cost-of-ownership procurement.
Supply Chain Analysis
Freight cost escalation from Asia-Pacific manufacturing hubs has compressed landed margins for European and North American OEMs sourcing wound stator assemblies. Geographic supply concentration centers on China, Mexico, and Germany for finished motor production, with China and Myanmar as primary rare earth oxide sources. Raw material dependencies rest on copper cathode, neodymium-iron-boron magnets, and silicon steel laminations. Single-source vulnerability in Chinese rare earth processing infrastructure poses structural supply chain risk. Distribution runs through authorized wholesaler networks and emerging direct-to-contractor manufacturer portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HVAC ECM market functions as a stable compounder, with regulatory efficiency mandates across multiple jurisdictions eliminating PSC motor alternatives and ensuring replacement-driven demand continuity.
For Market Incumbents: Extend sensorless control algorithm capabilities into plug-fan architectures to defend specification authority against emerging entrants with modular data center cooling offerings. Pursue backward integration into magnet material sourcing to offset Chinese processing concentration. Accelerate Mexico capacity expansion to capture Midwestern utility rebate program volumes.
For New Entrants and Emerging Players: Direct-to-contractor digital distribution channels offer lowest-friction entry into residential HVAC service replacement markets currently dominated by traditional wholesaler relationships. Target laboratory exhaust and pharmaceutical fume hood segments where multi-phase ECM torque density requirements create qualification barriers for commodity suppliers. Bundle installation training with equipment sales to overcome power electronics skill scarcity.
For Investors and Strategic Acquirers: Roll-up economics work for specialized ventilation component producers with proprietary control firmware because specification authority is migrating from mechanical contractors to energy service companies seeking bundled measurement-and-verification partners. Long-term viability rests on regulatory efficiency tier ratcheting across DOE, EU Ecodesign, and SAMR jurisdictions. Watch for F-Gas Regulation phase-down acceleration as inflection indicator for chiller OEM multi-phase ECM integration demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensorless Control Algorithm Development | Eliminates Hall-effect sensors and reduces field failure rates in data center plug-fan arrays. |
| Backward Integration into Magnet Processing | Offsets Chinese rare earth concentrate refining dominance and stabilizes input cost structures. |
| Direct-to-Contractor Distribution Launch | Captures margin and installation data from traditional wholesaler channels in residential HVAC. |
| Mexico Manufacturing Footprint Expansion | Positions production capacity to serve Midwestern and Sun Belt utility rebate program specifications. |
| Multi-Phase Platform Certification Investment | Qualifies torque-dense architectures for pharmaceutical and semiconductor laboratory exhaust systems. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with HVAC equipment manufacturer platform engineers, energy service company procurement directors, utility rebate program administrators, and aftermarket service contractor owners with secondary validation against DOE furnace fan standard filings, EU Ecodesign Directive tier updates, SAMR GB standard publications, and SEC 10-K disclosures from diversified motor producers. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Segment-weighting approaches distributed forecast contributions across product type, control technology, application, and end-user procurement authority dimensions throughout the projection horizon. CAGRs derived from regression analysis against regulatory enforcement timelines and replacement cycle maturation. Forecast inputs incorporated utility rebate program budget allocations, data center PUE reduction commitments, and building electrification mandate adoption curves.
The model assumes a particular technology adoption path; alternative pathways for rare earth-free magnetic materials would alter the outlook if ferrite or switched reluctance architectures achieve cost-competitive torque density. Forecasts reflect these assumptions alongside commodity price volatility and regulatory divergence risks. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Europe Electric Vehicle Chargers Market
Electric Vehicle Charging
Asia-Pacific Brushless DC Motors Market
Electric Vehicle Charging
Electric Vehicle Safe Charging Inlet Market
Electric Vehicle Charging
EV Charge Management Software Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Connector Market
Electric Vehicle Charging
Metals in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Belgium Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Europe Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
North America Wireless Charging Market
Electric Vehicle Charging
Electric Vehicle Grid Integration Solutions Market
Electric Vehicle Charging
Wireless Charging Market
Electric Vehicle Charging
North America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Engineered Polymers in Electric Charging Infrastructure Market
Electric Vehicle Charging
Global EV Charger Market
Electric Vehicle Charging
Automotive EV Charging Adapters Market
Electric Vehicle Charging
Electric Vehicle Charging Station Market