
 North America Generator Sets Market | 2026-2036
North America Generator Sets Market Size, Share, and Industry Trends Forecast 2026-2036
North America Generator Sets Market Analytics
EPA Tier 4 Final certification is reorganizing competitive access across the North America generator sets landscape, elevating compliance costs for smaller fabricators while cementing advantages for engineering-heavy incumbents. Caterpillar Inc. leverages its vertically integrated engine-aftertreatment architecture to dominate heavy industrial deployments above 200 kW. Cummins Inc. sustains cross-fuel leadership through parallel diesel and natural gas platform development. Generac Holdings Inc. anchors residential and light commercial channels with specialized air-cooled and liquid-cooled product families.
Generator sets are self-contained engine-alternator assemblies that convert mechanical energy into electrical power, typically rated from 5 kW to 3,000 kW and designed for prime, standby, or emergency service across grid-connected and isolated applications. Diesel configurations retain structural dominance in industrial and healthcare emergency segments due to energy density and rapid start capability, while natural gas units gain share in data center and commercial installations where emissions restrictions and pipeline access align. The above 200 kW power rating category captures concentrated margin pools as hyperscale buyers prioritize integrated paralleling switchgear and remote monitoring over unit cost alone.
The EPA enforces mobile and stationary engine emission thresholds that dictate aftertreatment architecture, while the Federal Energy Regulatory Commission and state public utility commissions shape interconnection rules for grid-tied backup systems. OSHA and NFPA 110 standards govern installation and testing protocols for healthcare and life-safety applications, creating specification lock-in for qualified suppliers. Stakeholders must monitor state-level renewable portfolio standards and natural gas pipeline capacity constraints as these determine whether dual-fuel or energy-storage hybrid configurations displace conventional genset-only designs in future procurement cycles.
Market Dynamics
Hyperscale data center construction across the United States is compressing procurement timelines and forcing generator set suppliers to pre-certify integrated paralleling architectures before construction starts.
Growth Catalysts
- EPA Tier 4 Final mandate:Stationary diesel engines above 25 horsepower must deploy selective catalytic reduction and diesel particulate filters, creating specification lock-in for compliant suppliers across Texas and Virginia data center clusters.
- Natural gas pipeline expansion:Permian Basin and Marcellus Shale infrastructure buildouts enable pipeline-fed prime power configurations for industrial facilities seeking fuel cost predictability.
- Healthcare infrastructure hardening:NFPA 110 Type 10 emergency power requirements for acute care hospitals drive replacement cycles of aging genset fleets in California and Florida.
Market Restraints
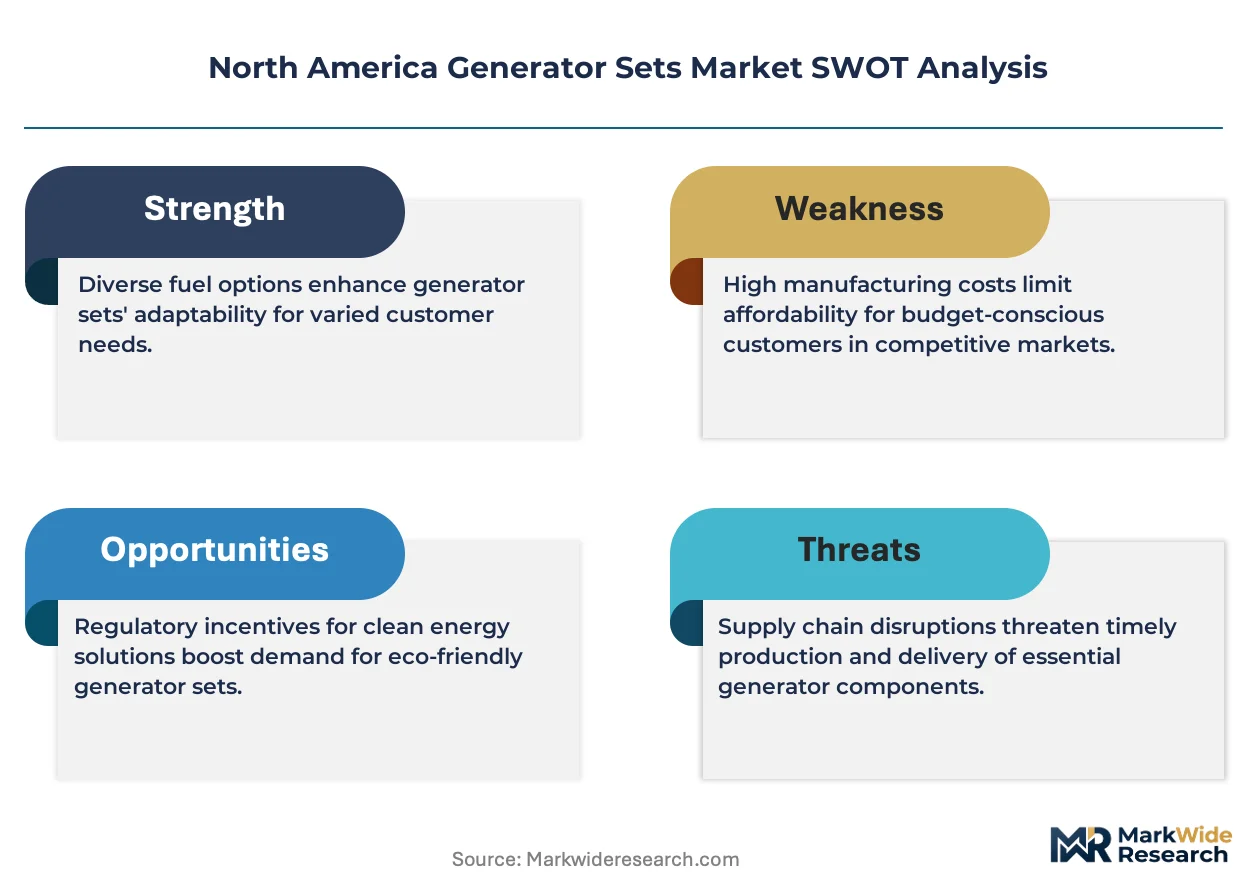
- Aftertreatment cost inflation:Diesel oxidation catalysts and urea dosing systems add 15-25% to engine package costs, squeezing margins on sub-200 kW units where price elasticity remains acute.
- Copper and rare earth concentration:Winding materials and permanent magnets for high-efficiency alternators depend on supply chains concentrated in Chile and China, exposing North American fabricators to input volatility.
- Interconnection queue delays:FERC Order 2023 implementation bottlenecks extend grid-tied backup system approval timelines by 18-24 months in ERCOT and PJM territories.
Strategic Opportunities
- Mexico nearshoring corridor:Monterrey and Querétaro industrial parks lack grid reliability comparable to US standards, creating demand for prime-rated natural gas gensets in automotive and electronics manufacturing.
- Dual-fuel retrofit kits:Conversion hardware enabling 70-90% natural gas substitution in existing diesel engines opens aftermarket revenue streams for fleet operators seeking emissions compliance without full replacement.
- Inflation Reduction Act credits:Investment tax credits for clean hydrogen production infrastructure position electrolyzer-integrated genset hybrids for early demonstration projects in Texas and Louisiana.
Industry Challenges
- EPA certification backlog:Engine family approvals for stationary emergency applications face 12-18 month review timelines, delaying product launches and freezing engineering resources.
- Paralleling switchgear integration:Synchronizing multiple gensets with utility-grade protective relaying requires specialized commissioning expertise that remains scarce in secondary US markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Generator Sets Market |
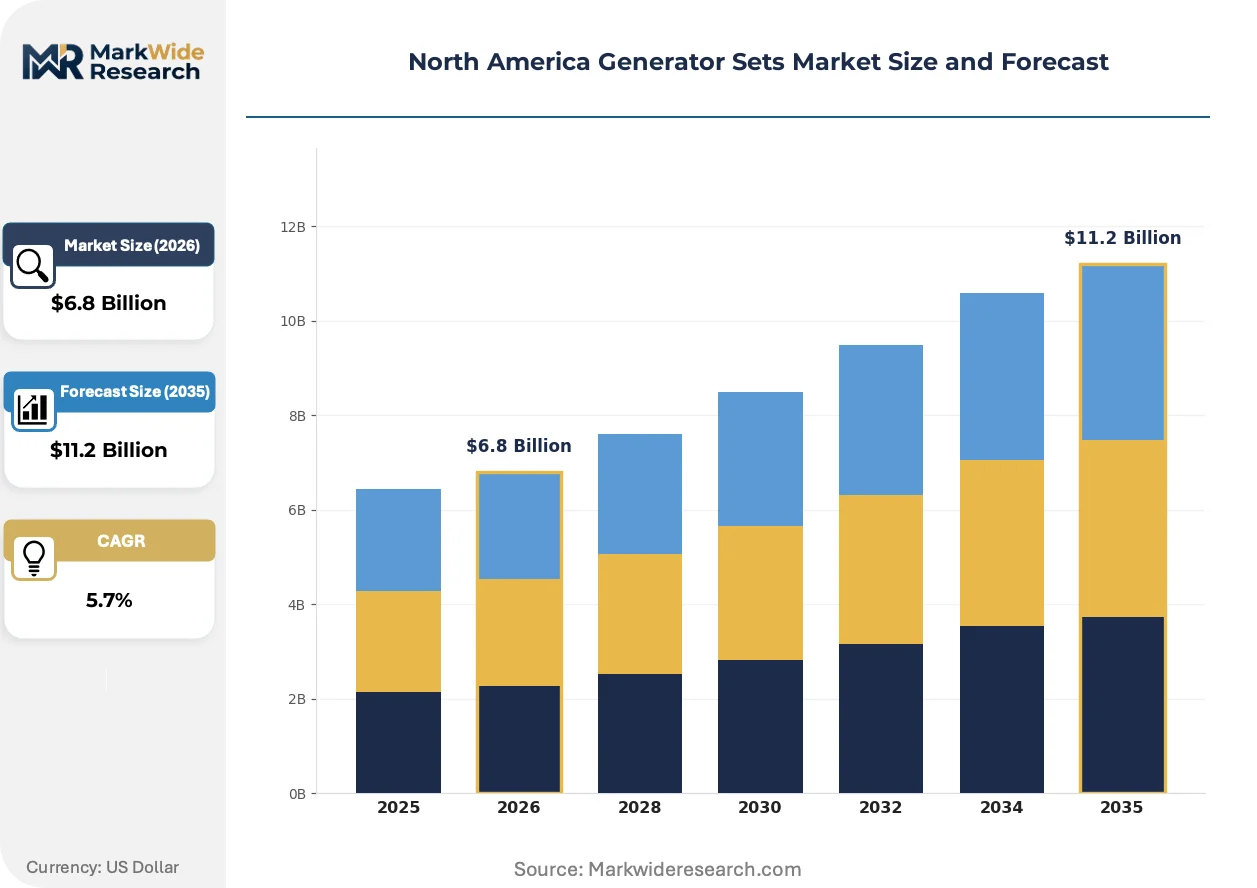
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Rating: Below 50 kW, 50-100 kW, 100-200 kW, Above 200 kW Fuel Type: Diesel, Natural Gas, Gasoline, Propane Application: Residential, Commercial, Industrial, Emergency End User: Healthcare, Data Centers, Construction, Hospitality |
| Companies Covered | Caterpillar Inc., Cummins Inc., Generac Holdings Inc., Kohler Co., Briggs & Stratton Corporation, Atlas Copco AB, Doosan Corporation, American Honda Motor Co., Inc., Ingersoll Rand, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Generator Sets Market Evolving Landscape
Diesel-centric backup architectures are fragmenting as data center operators weigh emissions compliance against capital efficiency, accelerating experimentation with alternative prime movers and hybrid configurations.
Modular battery energy storage systems paired with fast-start reciprocating engines are decomposing the traditional genset-only backup paradigm. Hyperscale operators in Arizona and Nevada are piloting 15-minute lithium-ion buffers that reduce required genset runtime from hours to minutes. This compression of engine operating hours is decomposing revenue models predicated on fuel consumption and maintenance contracts.
The EPA's Good Neighbor Plan and state-level ozone non-attainment designations are tightening nitrogen oxides limits for stationary engines in the Northeast and California. Manufacturers must now certify engines to both federal Tier 4 Final and more stringent state standards simultaneously. California Air Resources Board jurisdictions are responding with accelerated natural gas genset deployments and renewable natural gas offtake agreements.
Power-as-a-service contracting is displacing capital purchase models for commercial and light industrial buyers. Third-party operators in Texas and Georgia now own and maintain genset assets, selling guaranteed availability through 10-year service agreements. This shift concentrates fleet ownership with specialized providers and compresses OEM direct sales channels in the sub-500 kW segment.
North America Generator Sets Market Segmentation
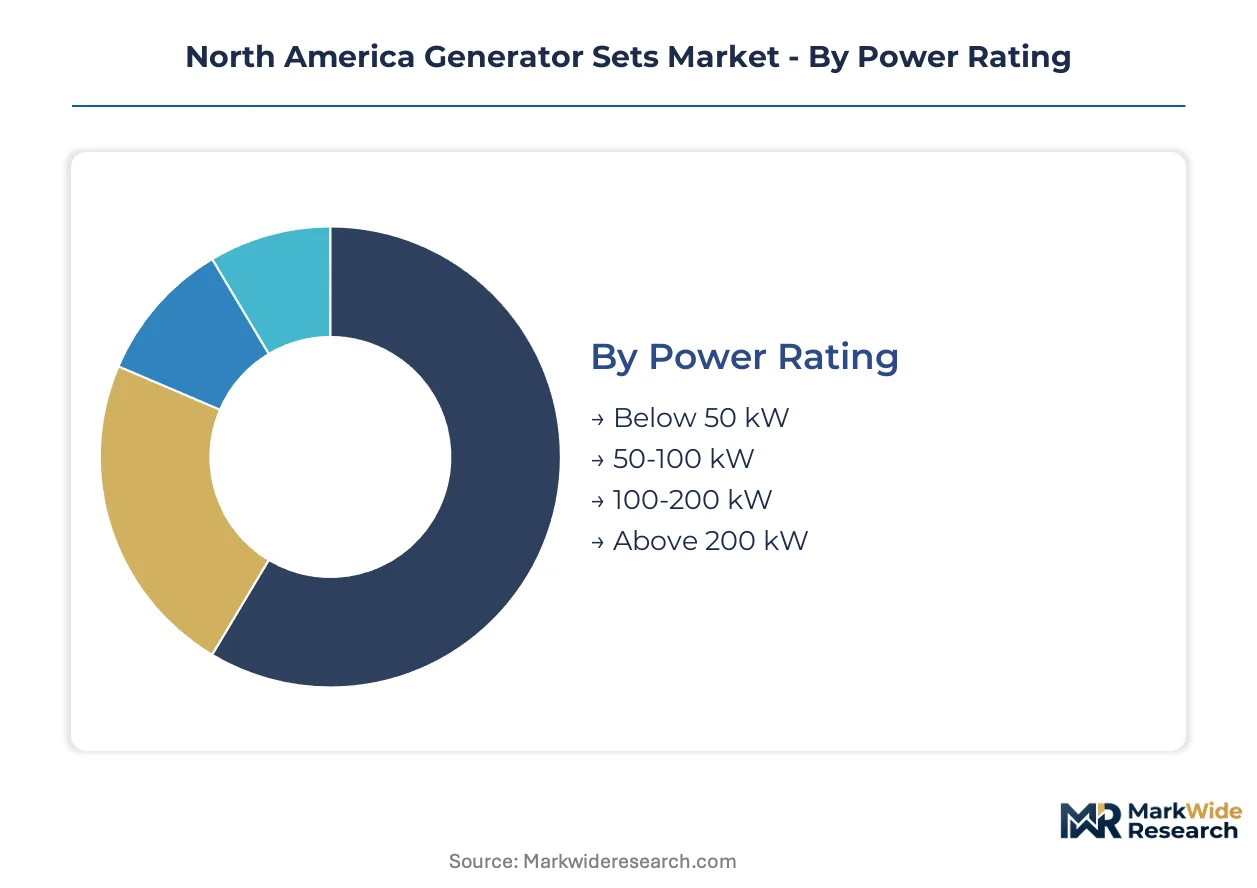
Generator set procurement patterns diverge sharply across power classes and fuel technologies, with EPA compliance costs and data center scale requirements fragmenting supplier economics. Understanding segment boundaries reveals where specification lock-in occurs versus where buyers retain negotiating leverage.
Power Rating:
Margin pools concentrate in the upper tiers where integrated switchgear and remote monitoring capabilities command premium pricing over unit costs alone.
- Below 50 kW:Air-cooled and liquid-cooled portable units serve residential backup and light commercial retail. Demand clusters in hurricane-prone Florida and Texas suburbs where grid reliability concerns drive homeowner investment.
- 50-100 kW:Small commercial footprints including restaurants and retail branches require compact enclosures with sub-75 dBA noise attenuation. California CARB jurisdictions favor natural gas variants to meet localized ozone limits.
- 100-200 kW:Mid-size healthcare clinics and municipal buildings specify these units for NFPA 110 compliance. The EPA Tier 4 Final aftertreatment burden falls heaviest here, compressing margins on price-sensitive bids.
- Above 200 kW:Hyperscale data center operators in Virginia and Arizona demand factory-integrated paralleling architectures with sub-10-second start times. These configurations bundle engine, alternator, and switchgear into single-source procurement, capturing concentrated margin pools.
Above 200 kW holds installed capacity. Below 50 kW is rotating up the share rankings.
Fuel Type:
Emissions compliance trajectories and pipeline infrastructure availability are reweighting fuel economics across the region.
- Diesel:Energy density and rapid cold-start capability sustain dominance in healthcare emergency and construction mobile applications. EPA Tier 4 Final mandates force selective catalytic reduction and diesel particulate filter integration, elevating package costs.
- Natural Gas:Pipeline-fed configurations gain share in Texas and Pennsylvania data center clusters where Permian Basin and Marcellus Shale infrastructure enables fuel cost predictability. Spark-ignited engines face lower NOx compliance burdens than diesel equivalents.
- Gasoline:Portable recreational and residential standby units dominate this segment. CARB evaporative emissions standards constrain carburetor architectures, pushing toward electronic fuel injection.
- Propane:Off-grid commercial and rural residential installations specify these where natural gas pipeline extension proves uneconomical. Storage tank footprint and refueling logistics limit deployment scale.
Diesel retains the largest installed base. Natural gas is climbing the fastest.
Application:
Service classification dictates runtime expectations, maintenance scheduling, and warranty structures that segment supplier economics.
- Residential:Standby power for single-family homes and small multi-tenant buildings. Automatic transfer switch integration and sub-30-second start requirements define specification standards.
- Commercial:Retail, office, and institutional facilities balance first cost against noise and emissions restrictions. Power-as-a-service contracting is displacing capital purchase models in Texas and Georgia.
- Industrial:Prime-rated continuous operation for manufacturing and processing facilities. Mexico nearshoring corridors in Monterrey and Querétaro drive demand for pipeline-fed natural gas units.
- Emergency:Life-safety applications under NFPA 110 Type 10 requirements mandate weekly testing and fuel quality monitoring. California and Florida acute care hospitals drive replacement cycles of aging fleets.
Emergency applications hold installed capacity. Industrial is expanding most quickly.
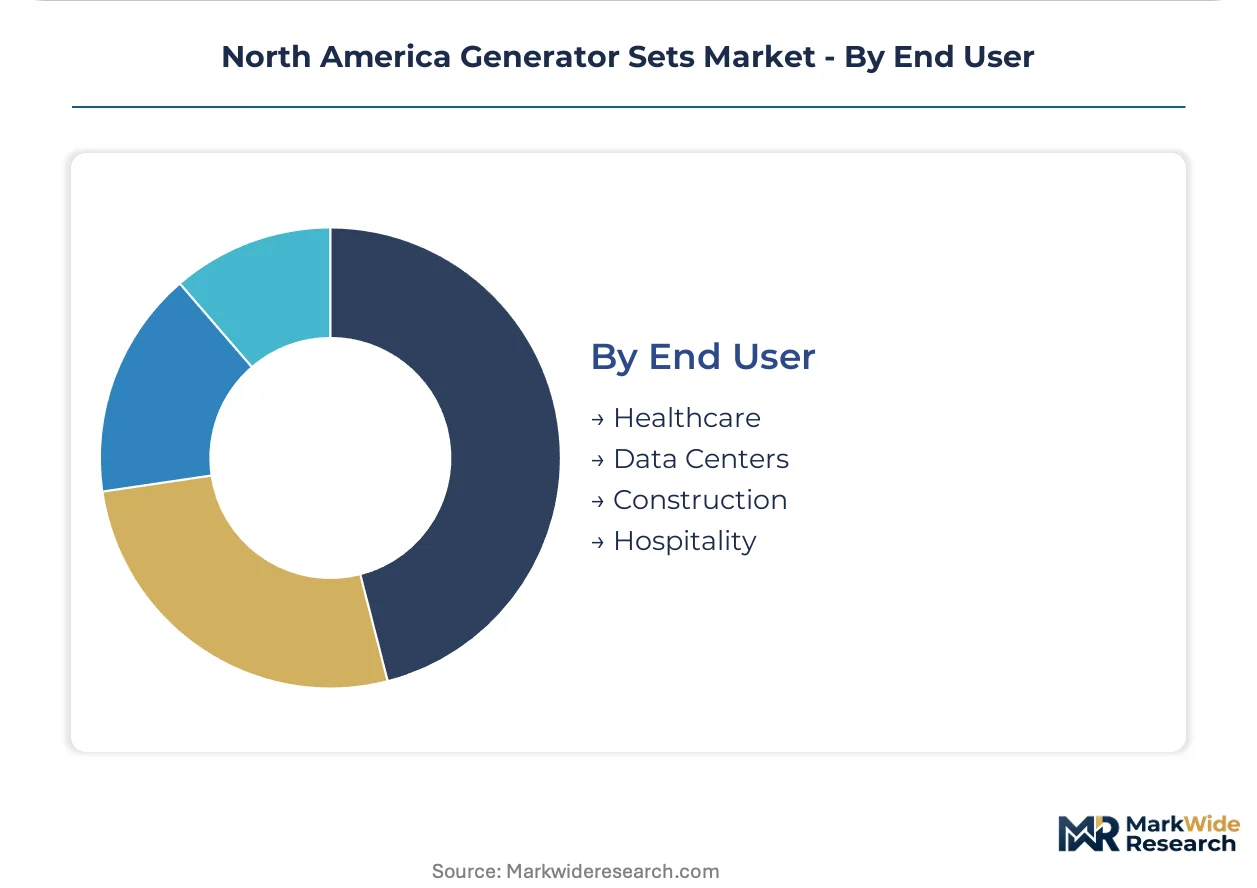
End User:
Procurement sophistication varies dramatically across buyer categories, from commodity bidding to engineered system integration.
- Healthcare:Acute care hospitals and outpatient surgery centers require NFPA 110 Type 10 compliance with 10-second automatic startup. Joint Commission accreditation audits enforce testing documentation standards.
- Data Centers:Hyperscale operators in Northern Virginia, Phoenix, and Dallas-Fort Worth compress procurement timelines and demand pre-certified paralleling architectures. Uptime Institute Tier certification requirements shape redundancy specifications.
- Construction:Mobile and towable units serve temporary power for building sites and infrastructure projects. Rental fleet operators in Texas and Florida dominate volume procurement.
- Hospitality:Hotels and resorts prioritize acoustic attenuation and aesthetic enclosure design. Caribbean-facing Florida properties specify corrosion-resistant coastal packages.
Healthcare holds installed capacity. Data centers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Inflation Reduction Act's clean hydrogen production credits and EPA emission mandates are redirecting generator set procurement toward compliant, lower-carbon configurations across North American industrial corridors.
United States
Hyperscale data center construction in Northern Virginia and Phoenix compresses procurement timelines for above-200 kW paralleling architectures. EPA Tier 4 Final enforcement locks in specification advantages for aftertreatment-equipped suppliers. Texas ERCOT grid instability drives backup power investment in Dallas-Fort Worth and Austin energy corridors.
Canada
Remote mining operations in Ontario's Ring of Fire and British Columbia's Golden Triangle require prime-rated natural gas units where pipeline extension proves uneconomical. Environment and Climate Change Canada stationary engine regulations parallel EPA thresholds, elevating compliance costs for diesel configurations. Alberta oil sands facilities deploy large-frame gensets for process-critical backup.
Mexico
Nearshoring manufacturing investment in Nuevo León and Querétaro outpaces grid infrastructure expansion, creating demand for pipeline-fed natural gas prime power. CFE interconnection queue delays extend 18-24 months for industrial facilities in Monterrey automotive parks. Bajío Region electronics assembly plants specify dual-fuel flexibility for operational continuity.
North America Generator Sets Market Competitive Landscape
Player mix skews toward vertically integrated engine manufacturers with captive aftertreatment capabilities. The supplier base concentrates around three strategic tiers: engineering-heavy incumbents with integrated engine-switchgear architectures, specialized natural gas platform developers, and residential-scale air-cooled specialists. Dominant competitive moves include backward integration into alternator winding operations and pre-certification of paralleling architectures for hyperscale data center procurement.
Among US-based engineering conglomerates, Caterpillar Inc., Cummins Inc., and Generac Holdings Inc. exemplify distinct competitive archetypes. Caterpillar Inc. anchors the heavy industrial tier through integrated engine-aftertreatment control. Cummins Inc. occupies a cross-fuel position spanning diesel and natural gas platform development. Generac Holdings Inc. represents the residential and light commercial specialization vector with dedicated air-cooled and liquid-cooled product families.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Cummins Inc. |
| Generac Holdings Inc. |
| Kohler Co. |
| Briggs & Stratton Corporation |
| Atlas Copco AB |
| Doosan Corporation |
| American Honda Motor Co., Inc. |
| Ingersoll Rand |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with Tier 4 Final pre-certified suppliers lock in both alternator winding access and price visibility for hyperscale data center operators across Virginia and Texas, compressing spot-market flexibility for smaller buyers.
Pricing Analysis
Certification level creates the primary spread across the North America generator sets landscape, with EPA Tier 4 Final-compliant packages commanding substantial premiums over non-certified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects bundling of paralleling switchgear, remote monitoring, and extended service agreements. Pricing pressure stems from aftertreatment cost inflation on diesel configurations below 200 kW. Healthcare and data center buyers demonstrate lowest price sensitivity, prioritizing 10-second start guarantees and Uptime Institute Tier certification over unit economics.
Supply Chain Analysis
Chile and China anchor copper cathode and rare earth magnet supply for high-efficiency alternator production. Winding materials and permanent magnets draw from concentrated mining and processing corridors, exposing North American fabricators to input volatility. Single-source vulnerability runs through Chinese rare earth separation capacity. Distribution runs through authorized dealer networks and direct OEM channels for above-200 kW industrial deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as EPA compliance costs and data center scale requirements bifurcate supplier economics, creating specialized niches for natural gas platform developers and aftermarket dual-fuel retrofit providers.
For Market Incumbents: Consolidate backward integration into alternator winding operations to secure copper and rare earth supply against Chilean and Chinese concentration risk. Deepen captive aftertreatment manufacturing capacity to defend margin position from Tier 4 Final certification backlogs. Lock in hyperscale data center procurement through pre-certified paralleling architectures before construction starts compress timelines.
For New Entrants and Emerging Players: Lead with dual-fuel retrofit kits targeting existing diesel fleets in Texas and Pennsylvania where natural gas pipeline expansion enables 70-90% fuel substitution. Target Mexico nearshoring corridors in Monterrey and Querétaro where CFE interconnection delays outpace grid infrastructure investment. Pursue power-as-a-service contracting models to displace capital purchase friction in commercial and light industrial segments.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized natural gas platform developers with captive EPA certification capabilities and established paralleling switchgear integration expertise. Long-term viability centers on suppliers capable of bridging diesel dominance in healthcare emergency applications with natural gas share gains in data center and industrial prime power. Watch FERC Order 2023 implementation velocity across ERCOT and PJM territories as inflection indicator for grid-tied backup system approval timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alternator Manufacturing | Captive supply of copper windings insulates against Chilean concentrate volatility and Chinese magnet processing concentration. |
| Dual-Fuel Retrofit Platform Development | Conversion hardware opens aftermarket revenue streams for fleet operators seeking emissions compliance without full replacement. |
| Pre-Certified Paralleling Architecture Launch | Factory-integrated switchgear bundles capture hyperscale data center procurement in Virginia and Arizona. |
| Power-as-a-Service Contracting Model | Third-party ownership concentrates fleet economics with specialized providers and compresses OEM direct sales channels. |
| Natural Gas Prime Power Expansion | Pipeline-fed configurations gain share in Texas and Pennsylvania where Permian Basin and Marcellus Shale infrastructure enables fuel cost predictability. |
Research Methodology
A spread of perspectives from data center infrastructure directors, healthcare facility engineers, EPC contractors, and EPA certification specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with aftermarket service heads and OEM procurement teams alongside secondary validation through FERC filings, EIA power plant databases, and state public utility commission interconnection queue records. Bottom-up unit economics triangulated against top-down market sizing across power rating, fuel type, and application segments.
Segmentation dimensions modeled include power rating tier, fuel technology, service classification, and end-user sophistication level across the projection horizon. CAGRs derived from shipment volume trajectories and average selling price evolution by configuration class. Forecast inputs incorporated EPA Tier 4 Final adoption curves, natural gas pipeline capacity expansion timelines, and hyperscale data center construction permitting velocity.
Forecasts assume regulatory continuity in EPA stationary engine standards and FERC interconnection rules; material policy shifts would require re-modeling. Supply chain disruptions in Chilean copper or Chinese rare earth processing represent primary revision triggers. Recalibration cycles align with material shifts in data center construction permitting, EPA certification backlog resolution, and Mexico CFE interconnection queue velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Kuwait Diesel Gensets Market
Generators
South America and Africa Diesel Generator Market
Generators
Africa Diesel Generator Market
Generators
South Africa Diesel Generator Market
Generators
Gas Generator Market
Generators
Boiler, Turbine, and Generator (BTG) Market
Generators
Asia-Pacific Diesel Generator Market
Generators
Asia-Pacific Gas Generator Market
Generators
Dual-Fuel Generator Market
Generators
India Diesel Generator Market
Generators
Telecom Generator Market
Generators
Commercial Generator Market
Generators
Global Diesel Gensets Market
Generators
Wind Turbine Alternator Market
Generators
Generator (Up to 20 Kva) Market
Generators
Middle East and Africa Gas Generator Market