
 Cosmetic Bioactive Ingredients Market | 2026-2036
Cosmetic Bioactive Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Bioactive Ingredients Market Analysis
ISO 16128 certification for natural and organic cosmetic ingredients is bifurcating the competitive landscape between qualified and non-qualified suppliers. BASF SE leverages its integrated biotechnology platforms to sustain high-purity peptide production at scale. Croda International PLC anchors its position through specialized lipid-based delivery systems that dominate premium serum formulations. Givaudan differentiates via botanical extraction expertise tied to traceable supply chains in Madagascar and Morocco.
Cosmetic bioactive ingredients comprise biologically active compounds including peptides, antioxidants, carotenoids, and polyphenols that interact with skin physiology at cellular levels, typically formulated at concentrations between 0.01% and 5% depending on molecular weight and penetration pathway. These ingredients serve primarily to modulate collagen synthesis, neutralize oxidative stress, or regulate melanin production in topical applications. Peptide-based actives command the deepest margin pools due to synthesis complexity and patent-protected sequences, while antioxidant demand accelerates fastest as brands respond to pollution-driven skin concern narratives. Anti-aging functionality retains the largest revenue base, though skin brightening is gaining share in Southeast Asian and Middle Eastern markets where melanin-modulating bioactives address distinct photoprotection and tone-evening needs.
EMA guidelines on cosmetic-drug borderline products, REACH substance restrictions, and the EU Green Deal's biodegradability mandates collectively tighten raw material qualification timelines and elevate testing costs for new bioactive introductions. FDA oversight of structure-function claims in cosmeceuticals creates additional compliance layers for peptide and retinoid-based formulations marketed with physiological effect language. Stakeholders must monitor regulatory divergence between jurisdictions where one region's cosmetic classification becomes another's drug premarket approval requirement.
Market Dynamics
Clean beauty mandates from prestige cosmetic houses are bifurcating supplier qualification protocols, forcing raw material vendors to absorb ISO 16128 certification costs or exit premium formulation pipelines entirely.
Growth Catalysts
- EU Green Deal biodegradability mandates:REACH substance restrictions accelerate reformulation cycles, creating replacement demand for qualified bioactive suppliers with established biodegradability dossiers.
- South Korean dermatology channel expansion:Medical aesthetic clinics now prescribe peptide-based homecare regimens, extending bioactive ingredient pull-through from professional to retail channels.
- Biotechnology platform maturation:Precision fermentation for high-purity peptide synthesis reduces batch-to-batch variability, enabling cosmetic brands to scale active concentrations without stability failures.
Market Restraints
- Raw material concentration risk:Madagascar vanilla and Moroccan argan supply chains face climate volatility, concentrating botanical extraction dependence on two geographies with limited agricultural diversification.
- REACH testing cost escalation:New bioactive substance registrations now require six-figure toxicology packages, structurally excluding mid-tier suppliers from EU market access.
- Retinoid regulatory friction:FDA structure-function claim scrutiny on cosmeceuticals forces peptide and retinoid marketers to either dilute physiological effect language or pursue drug premarket approval pathways.
Strategic Opportunities
- China domestic brand ecosystem:Local cosmetic houses prioritize traceable supply chains for consumer trust, opening partnership slots for extraction specialists with documented provenance systems.
- Microbiome modulation applications:Postbiotic bioactives targeting skin barrier function represent uncaptured white space as brands pivot from anti-aging to barrier repair narratives.
- ISO 16128 certification arbitrage:Suppliers achieving natural origin index thresholds command 40-60% price premiums in prestige channels, creating margin expansion for qualified versus non-qualified competitors.
Industry Challenges
- Peptide synthesis talent scarcity:Cross-disciplinary expertise spanning organic chemistry, dermatology, and regulatory science commands premium compensation, constraining R&D team scaling.
- Dual-use classification complexity:Cosmetic-drug borderline determinations vary by jurisdiction, forcing parallel dossier development for single bioactive ingredients across FDA, EMA, and NMPA submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Bioactive Ingredients Market |
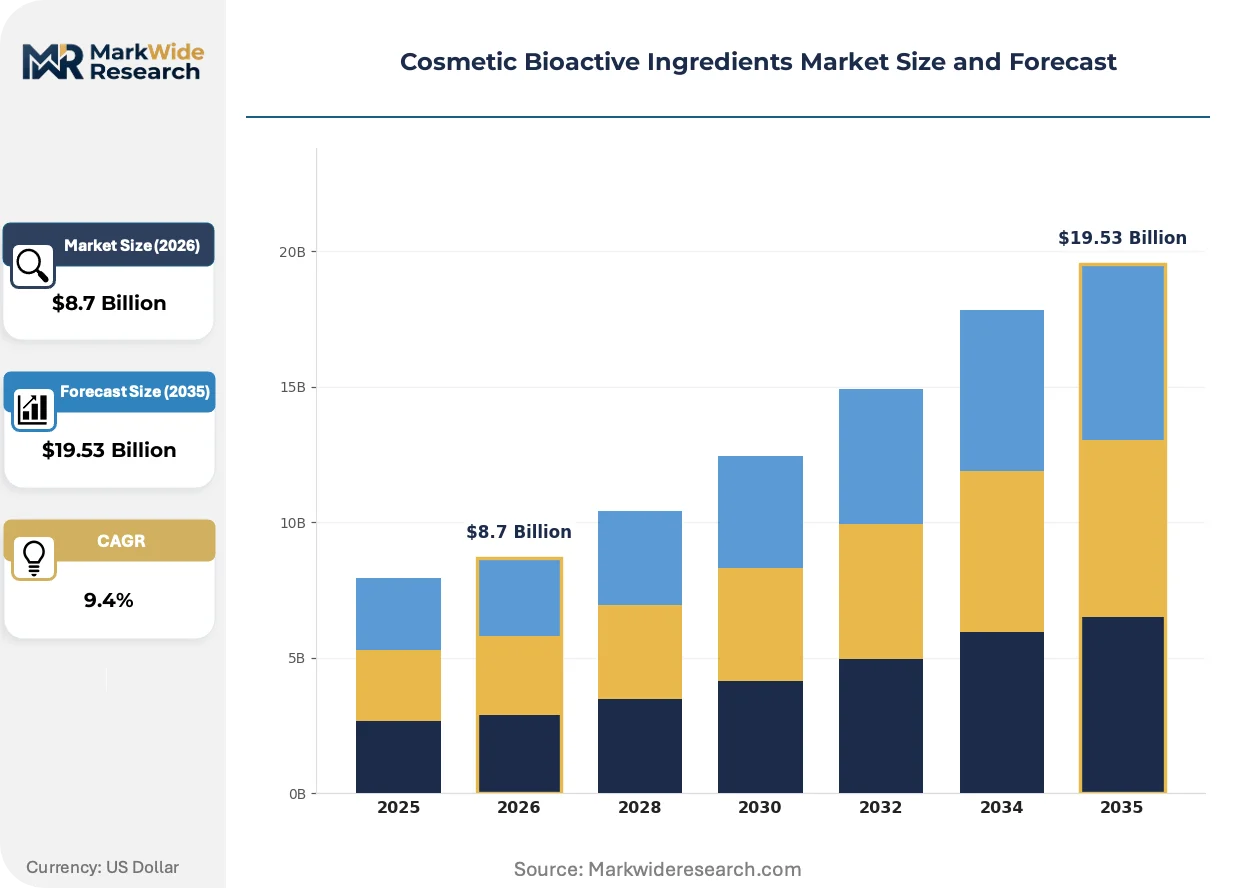
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Peptides, Antioxidants, Carotenoids, Polyphenols Functionality: Moisturizing, Anti-aging, Skin Brightening, Soothing Formulation Type: Emulsions, Gels, Creams, Serums End User: Personal Care, Cosmetic Brands, Dermatology, Spa & Wellness |
| Companies Covered | Symrise, Clariant, BASF SE, Ashland Global Holdings Inc, DSM-Firmenich, Croda International PLC, Givaudan, Lubrizol, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Bioactive Ingredients Market Emerging Trajectories
Biotechnology-derived bioactives are compressing traditional botanical extraction economics while regulatory fragmentation forces suppliers to maintain parallel compliance architectures across major cosmetic markets.
Precision fermentation for peptide production is displacing solid-phase synthesis for mid-length sequences under 50 amino acids. Prestige serum formulators now specify fermentation-derived actives for consistency advantages. This shift compresses margins for traditional chemical synthesis houses while rewarding integrated biotechnology platforms with captive strain libraries.
EMA guidelines on cosmetic-drug borderline products tighten ingredient classification uncertainty. Manufacturers face divergent premarket requirements where peptide concentrations trigger drug status in Europe but remain cosmetic in the United States. Multinational brands now maintain separate formulation variants to navigate jurisdictional classification splits.
Ingredient transparency mandates from retail buyers now require full supply chain mapping to raw material origin. Clean beauty retailers in California and France reject bioactives without documented extraction coordinates and labor certification. This behavioral shift advantages suppliers with established traceability infrastructure while excluding opaque trading houses from premium channel access.
Cosmetic Bioactive Ingredients Market Segmentation
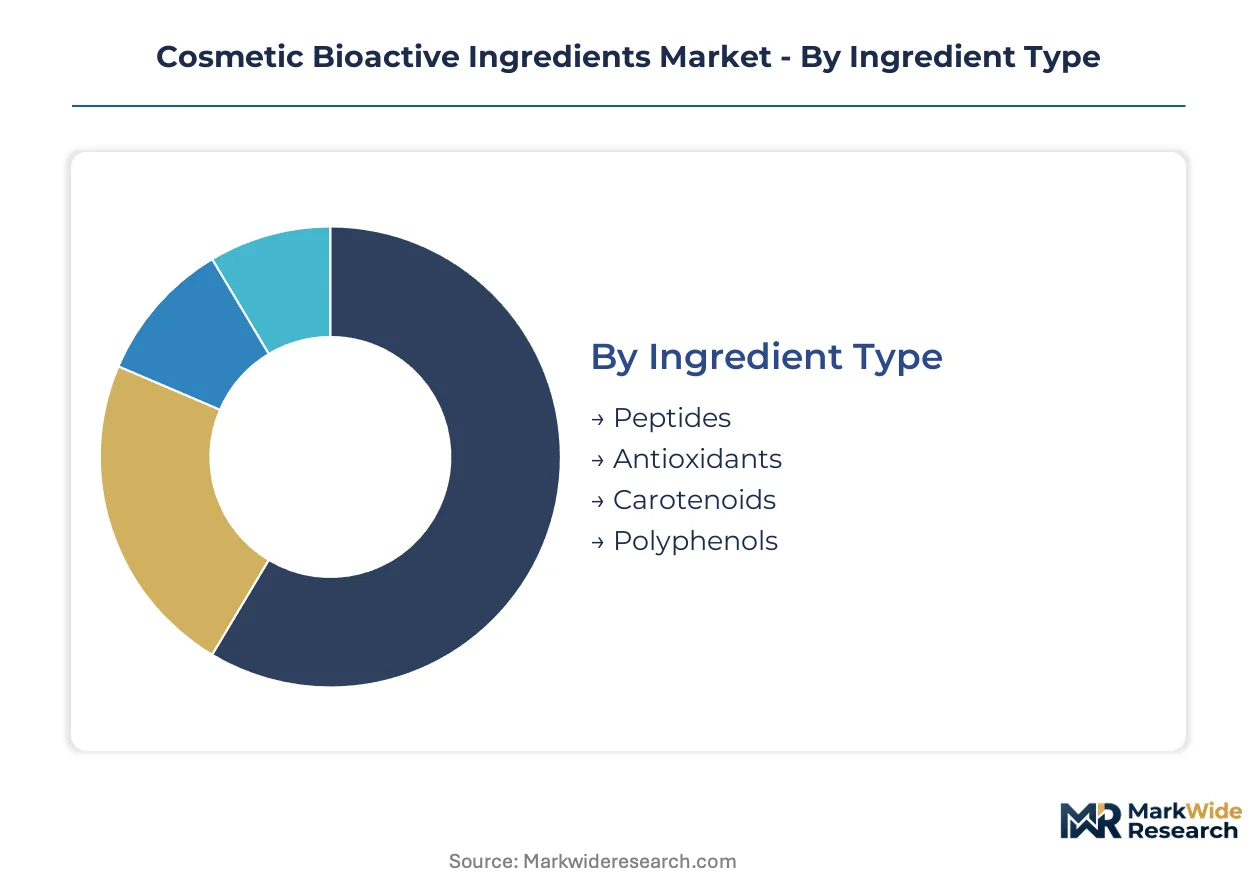
Segmentation in cosmetic bioactives determines supplier qualification pathways and margin capture. Ingredient type dictates synthesis complexity and patent exposure. Functionality shapes regulatory scrutiny intensity across jurisdictions.
Ingredient Type:
REACH substance restrictions and FDA structure-function claim scrutiny create divergent compliance burdens across molecular categories, with peptide sequences facing the most stringent toxicology dossier requirements.
- Peptides:Short-chain amino acid sequences typically under 50 residues, synthesized via precision fermentation or solid-phase chemistry. South Korean dermatology clinics prescribe peptide-based homecare regimens, extending professional channel pull-through into retail as medical aesthetic adoption accelerates. Patent-protected sequences command deepest margin pools due to synthesis complexity and exclusivity.
- Antioxidants:Free radical scavengers including vitamin derivatives, polyphenolic extracts, and enzymatic systems formulated at 0.5% to 3% concentrations. China's domestic brand ecosystem prioritizes pollution-defense antioxidant narratives, with traceable supply chains becoming non-negotiable for partnership access. Demand climbs fastest as urban skin concern positioning spreads beyond prestige into masstige tiers.
- Carotenoids:Lipid-soluble terpenoid pigments including beta-carotene and astaxanthin variants used for photoprotection signaling.
- Polyphenols:Plant-derived aromatic compounds from grape seed, green tea, and berry extraction targeting oxidative stress modulation.
Established volume favors peptides; emerging adoption favors antioxidants.
Functionality:
Cost tier stratification separates clinical-grade claims from basic cosmetic positioning, with anti-aging commanding premium formulation slots and skin brightening gaining traction in melanin-modulation markets.
- Anti-aging:Collagen synthesis modulation, wrinkle depth reduction, and cellular repair targeting through retinoid, peptide, and growth factor pathways. Retains the largest revenue base across prestige and professional channels as demographic aging concentrates spending power in mature skin segments.
- Skin Brightening:Melanin production regulation via tyrosinase inhibition and melanocyte modulation for tone evening and photoprotection. Southeast Asian and Middle Eastern markets drive expansion as distinct aesthetic preferences elevate melanin-modulating bioactives beyond traditional Western anti-aging narratives.
- Moisturizing:Barrier function support through ceramide, hyaluronic acid, and natural moisturizing factor supplementation.
- Soothing:Inflammation modulation for sensitive skin and post-procedure recovery applications.
Prestige channel concentration favors anti-aging; geographic expansion favors skin brightening.
Formulation Type:
Delivery system sophistication determines bioactive stability and penetration efficiency, with serum formats demanding the highest purity specifications and emulsion systems offering the broadest addressable market.
- Serums:Low-viscosity, high-actives-concentration vehicles designed for targeted delivery and rapid absorption. Premium serum formulators now specify fermentation-derived peptides for batch consistency, compressing margins for traditional chemical synthesis houses while rewarding integrated biotechnology platforms.
- Emulsions:Oil-in-water or water-in-oil dispersions enabling broader compatibility ranges and cost-efficient scaling. Mass-market and masstige brands favor emulsion vehicles for manufacturing flexibility and consumer familiarity, creating volume anchors for qualified suppliers.
- Creams:Higher-viscosity occlusive systems for barrier-intensive applications and mature skin preferences.
- Gels:Water-based, non-greasy vehicles targeting younger demographics and tropical climate positioning.
Margin capture concentrates in serums; volume scale concentrates in emulsions.
End User:
Customer type dictates regulatory exposure and claim substantiation depth, with dermatology channels requiring clinical evidence and cosmetic brands prioritizing marketing narrative flexibility.
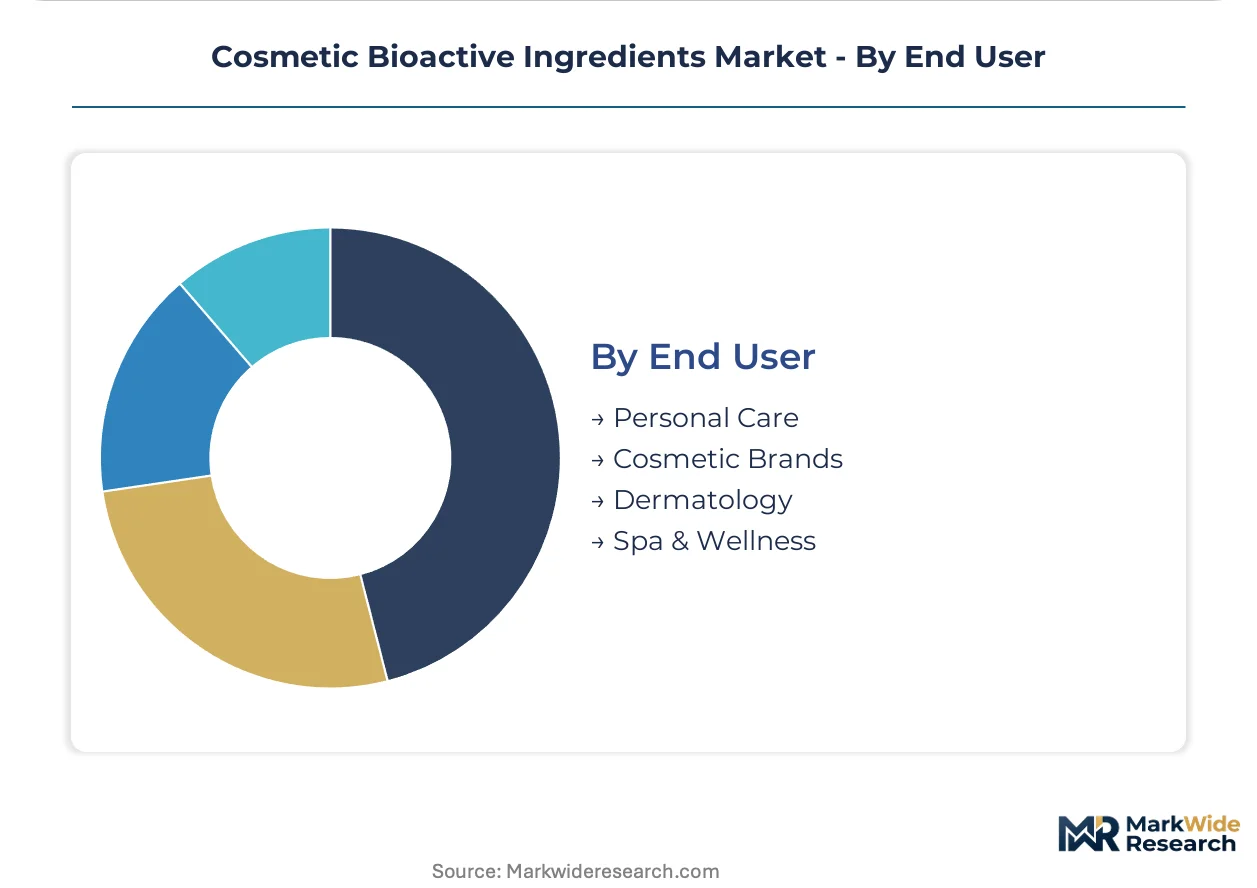
- Dermatology:Medical aesthetic clinics and prescription-adjacent channels demanding evidence-based efficacy documentation and professional endorsement protocols. South Korea's channel expansion now bridges professional treatment and homecare regimen prescription, creating qualified supplier pull-through from clinical into retail environments.
- Cosmetic Brands:Prestige and masstige houses subject to clean beauty mandates and ingredient transparency requirements from retail buyers. ISO 16128 certification becomes a binary qualifier, with non-certified suppliers exiting premium formulation pipelines entirely as qualification protocols bifurcate.
- Personal Care:Direct-to-consumer and specialty retail channels with varying substantiation thresholds.
- Spa & Wellness:Professional treatment environments emphasizing experiential delivery and immediate sensorial effects.
Compliance intensity peaks in dermatology; volume accessibility peaks in cosmetic brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal biodegradability mandates and South Korean dermatology channel expansion are redrawing regional supplier qualification maps, concentrating qualified bioactive production in jurisdictions with established regulatory dossier infrastructure.
South Korea
Medical aesthetic clinics in Seoul prescribe peptide-based homecare regimens, extending bioactive pull-through from professional to retail channels. MFDS cosmetic-drug borderline guidelines tighten ingredient classification protocols for melanin-modulating actives. The Pangyo biotech cluster hosts precision fermentation facilities supplying fermentation-derived peptides to domestic and export markets.
China
Domestic cosmetic houses in Shanghai and Hangzhou prioritize traceable supply chains for consumer trust, opening partnership slots for extraction specialists with documented provenance systems. NMPA cosmetic registration requirements for new bioactive substances extend qualification timelines. The Yangtze River Delta concentration of contract manufacturers drives volume demand for qualified antioxidant and peptide inputs.
United States
FDA structure-function claim scrutiny on cosmececeuticals forces peptide and retinoid marketers to dilute physiological effect language or pursue drug premarket approval pathways. California clean beauty retailers mandate full supply chain mapping to raw material origin. New Jersey and Pennsylvania chemical synthesis corridors maintain solid-phase peptide production capacity serving prestige cosmetic brands.
Germany
REACH substance restrictions and ECHA biodegradability mandates accelerate reformulation cycles, creating replacement demand for suppliers with established toxicology dossiers. BASF SE leverages integrated biotechnology platforms at Ludwigshafen for high-purity peptide production. The Rhine-Neckar metropolitan region anchors EU-wide distribution for qualified natural and organic cosmetic ingredients.
France
ANSM guidelines on cosmetic-drug borderline products tighten ingredient classification uncertainty for peptide concentrations triggering drug status. Paris-based prestige houses drive ISO 16128 certification requirements through supplier qualification protocols. The Provence-Alpes-Côte d'Azur region hosts botanical extraction specialists serving traceable supply chain mandates from retail buyers.
Cosmetic Bioactive Ingredients Market Vendor Landscape
Player mix skews toward integrated chemical conglomerates with captive biotechnology platforms alongside specialized lipid and botanical extraction houses. Market structure concentrates around suppliers capable of absorbing six-figure REACH toxicology package costs. Three archetypes dominate: precision fermentation specialists, traceable botanical extractors, and integrated peptide synthesis platforms. Competitive moves center on ISO 16128 certification arbitrage for natural origin index premiums and biotechnology platform maturation to displace traditional chemical synthesis.
Among integrated chemical conglomerates, BASF SE and Evonik Industries exemplify the fermentation-to-formulation archetype with captive strain libraries and scaled peptide production. Specialized players like Croda International PLC and Givaudan occupy positions tied to delivery system sophistication and traceable supply chain infrastructure respectively. DSM-Firmenich represents the merged entity archetype combining nutritional and cosmetic bioactive portfolios. These named companies anchor competitive positioning without constituting an exhaustive market map.
| Leading Market Players |
|---|
| Symrise |
| Clariant |
| BASF SE |
| Ashland Global Holdings Inc |
| DSM-Firmenich |
| Croda International PLC |
| Givaudan |
| Lubrizol |
| Evonik Industries |
| Others |
Supply Flow & Price Mechanics
Fermentation capacity utilization at 85% or above in South Korean and German biotechnology clusters creates scale economies that compress unit costs for peptide synthesis while elevating price floors for non-qualified suppliers. This concentration of production infrastructure bifurcates the market between ISO 16128-certified suppliers capturing premium positioning and uncertified competitors facing exclusion from prestige formulation pipelines.
Pricing Analysis
Certification level creates the primary spread, with ISO 16128-qualified suppliers commanding 40-60% premiums over non-certified alternatives in prestige channels. The dominant structure stratifies across premium certified, standard technical-grade, and economy commodity tiers, with differentiation resting on natural origin index thresholds and REACH dossier completeness. Cost compression in the standard tier is intensifying because mid-tier suppliers absorb six-figure toxicology package costs to maintain EU market access. Cosmetic brands with clean beauty mandates show lowest price sensitivity, while mass-market emulsion formulators negotiate aggressively on volume contracts.
Supply Chain Analysis
Germany and South Korea anchor precision fermentation capacity for high-purity peptide production, while Madagascar and Morocco supply botanical extraction feedstocks for traceable polyphenol and carotenoid inputs. The chain draws from amino acid precursors, specialized fermentation media, and certified organic agricultural raw materials. Single-source vulnerability concentrates in Madagascar vanilla and Moroccan argan supply chains exposed to climate volatility. Distribution runs through Rhine-Neckar metropolitan region hubs for EU-wide qualified ingredient distribution, with Yangtze River Delta contract manufacturers pulling volume for China's domestic brand ecosystem.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cosmetic bioactive ingredients market sits in early-cycle expansion as biotechnology platform maturation displaces traditional chemical synthesis and clean beauty adoption accelerates ingredient transparency requirements across prestige channels.
For Market Incumbents: Secure ISO 16128 certification arbitrage by accelerating natural origin index threshold achievement before qualification protocols fully bifurcate the supplier base. Defend margin position through captive strain libraries and integrated fermentation capacity that mid-tier competitors cannot replicate. Lock in long-term supply agreements with Madagascar and Moroccan extraction partners to mitigate climate-driven raw material concentration risk.
For New Entrants and Emerging Players: Postbiotic bioactives targeting skin barrier function represent the most penetrable white space as brands pivot from anti-aging to microbiome modulation narratives. Target China's domestic brand ecosystem with documented provenance systems that satisfy traceable supply chain mandates from Shanghai and Hangzhou cosmetic houses. Enter through partnership with Yangtze River Delta contract manufacturers seeking qualified antioxidant and peptide inputs.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision fermentation specialists with scaled peptide production and established REACH dossiers over traditional solid-phase synthesis houses facing margin compression. Long-term viability hinges on regulatory dossier infrastructure capable of navigating cosmetic-drug borderline determinations across FDA, EMA, and NMPA jurisdictions. Watch for MFDS and ANSM guideline tightening on melanin-modulating actives as inflection indicators for classification risk and reformulation demand.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 16128 Certification Achievement | Natural origin index thresholds unlock 40-60% price premiums in prestige channels. |
| Precision Fermentation Scale-Up | Biotechnology platforms displace solid-phase synthesis for mid-length peptide sequences under 50 residues. |
| Traceable Supply Chain Mapping | Documented provenance systems satisfy California and France clean beauty retailer mandates. |
| REACH Dossier Completion | Established toxicology packages preserve EU market access as substance restrictions tighten. |
| Postbiotic R&D Pipeline | Barrier function modulation captures uncaptured white space beyond saturated anti-aging segments. |
Methodological Framework
A standing panel of cosmetic formulators, regulatory affairs directors at ingredient suppliers, procurement leads at prestige brands, and dermatology clinic operators provided ongoing calibration across the study period. This primary input combined with secondary validation from ECHA substance restriction databases, MFDS cosmetic registration filings, REACH dossier repositories, and customs trade data for amino acid and botanical extract flows. Bottom-up volume modeling by ingredient type and functionality tier triangulated against top-down market sizing from production capacity and channel flow analysis.
Consistency checks validated volume and value outputs against external benchmarks including fermentation capacity utilization disclosures, contract manufacturer input demand patterns, and retail audit data for serum and emulsion launch velocities. The analytical framework segmented by ingredient type, functionality, formulation vehicle, and end-user channel across the projection horizon. CAGRs derived from regression analysis of adoption curves for biotechnology-derived actives, adjusted for regulatory approval timeline risk and substitution elasticity between peptide and antioxidant categories.
Forecasts assume regulatory continuity in EU REACH substance restrictions, FDA structure-function claim protocols, and NMPA cosmetic registration requirements; material policy shifts would require re-modeling. Specific risks include EMA cosmetic-drug borderline reclassification, Madagascar and Moroccan agricultural supply disruptions, and biotechnology platform scale-up failures. Recalibration cycles align with material shifts in clean beauty mandate adoption, precision fermentation yield improvements, and REACH substance restriction list updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Modified Soya Flour Market
Ingredients
Pea Fiber Market
Ingredients
South America Clean Ingredients Market
Ingredients
Cold Water-Soluble Creamer Market
Ingredients
Lupin Flour Market
Ingredients
Bangladesh Mustard Oil Market
Ingredients
Plant-Based API Market
Ingredients
Self-Rising Flour Market
Ingredients
Arrowroot Starch Market
Ingredients
Honey Powder Market
Ingredients
Global Malt Extracts and Ingredients Market
Ingredients
Cheese Powder Market
Ingredients
USA Yeast Extracts Market
Ingredients
Fruit Pectin Market
Ingredients
Asia-Pacific Lipids Market
Ingredients
Barley Malt Extract Market