
 Australia Soy Protein Market | 2026-2036
Australia Soy Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Soy Protein Market Outlook
Modular ingredient bundling is shifting how Australian food manufacturers procure soy protein, with buyers favoring pre-blended functional systems over single-ingredient sourcing. Cargill, Incorporated leverages its integrated supply chain to dominate bulk isolate and concentrate distribution across Oceania. Kerry Group plc specializes in customized textured soy protein solutions for plant-based meat applications. Archer Daniels Midland Company anchors its position through extensive crushing and processing infrastructure in the region.
Soy protein denotes protein extracted from dehulled, defatted soybean meal through aqueous or alkaline solubilization followed by isoelectric precipitation, yielding products with protein concentrations ranging from approximately fifty percent in flour to over ninety percent in isolate grades. The ingredient serves primarily as a functional emulsifier, gelling agent, and nutritional fortifier in formulated foods and animal nutrition. Isolate commands premium positioning due to superior emulsification capacity and neutral flavor profile in dairy alternatives. Textured soy protein experiences accelerated demand from food manufacturers developing whole-muscle analogues. Concentrate maintains volume leadership in processed meat extension applications where cost efficiency governs procurement.
Food Standards Australia New Zealand mandates minimum protein content thresholds and allergen labeling for soy-derived ingredients sold in Australian commerce. The Therapeutic Goods Administration oversees soy protein claims in nutraceutical applications, restricting therapeutic assertions to approved formulations. Biosecurity import regulations administered by the Department of Agriculture, Fisheries and Forestry govern raw soybean entry and influence domestic processing economics. Stakeholders must monitor evolving plant protein labeling standards and biosecurity protocol adjustments to sustain market access and formulation compliance.
Market Dynamics
Modular ingredient bundling is restructuring procurement patterns across Australian food manufacturing, with buyers abandoning single-ingredient contracts in favor of pre-blended functional systems that reduce formulation complexity and shorten product development cycles.
Growth Catalysts
- FSANZ protein content mandates:Food Standards Australia New Zealand's minimum protein thresholds for labeling claims compel manufacturers to fortify processed foods, directly stimulating isolate and concentrate demand.
- Plant-based meat manufacturing:Food processors in New South Wales and Victoria are expanding textured soy protein capacity to supply whole-muscle analogue production lines.
- Biosecurity protocol maturation:Department of Agriculture, Fisheries and Forestry import regulations have stabilized raw soybean entry pathways, improving processing economics for domestic crush operators.
Market Restraints
- Input cost volatility:Raw soybean prices fluctuate with Argentine and Brazilian harvest cycles, compressing margin predictability for Australian crush facilities.
- Supply concentration risk:Bulk isolate distribution concentrates among integrated traders with captive ocean freight capacity, limiting procurement alternatives for mid-tier manufacturers.
- Technical limitation:Isolate's superior emulsification capacity carries flavor masking requirements that extend formulation timelines for dairy alternative developers.
Strategic Opportunities
- Queensland and Western Australia penetration:Food processing clusters in these states remain underdeveloped relative to New South Wales and Victoria, offering first-mover positioning for textured protein suppliers.
- Therapeutic goods pathway:TGA approval frameworks for protein-based nutraceuticals create a regulated channel for isolate manufacturers seeking premium positioning beyond commodity food ingredients.
- Pulse-soy hybrid systems:Converging extrusion technologies enable protein blends that address allergen labeling constraints while maintaining functional performance in meat extension applications.
Industry Challenges
- Formulation talent scarcity:Food manufacturers face acute shortages of protein chemists capable of optimizing isolate functionality in neutral-flavor dairy alternatives.
- Certification timeline compression:FSANZ novel food approvals for new soy protein derivatives require 12-18 month evaluation windows that lag behind product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Soy Protein Market |
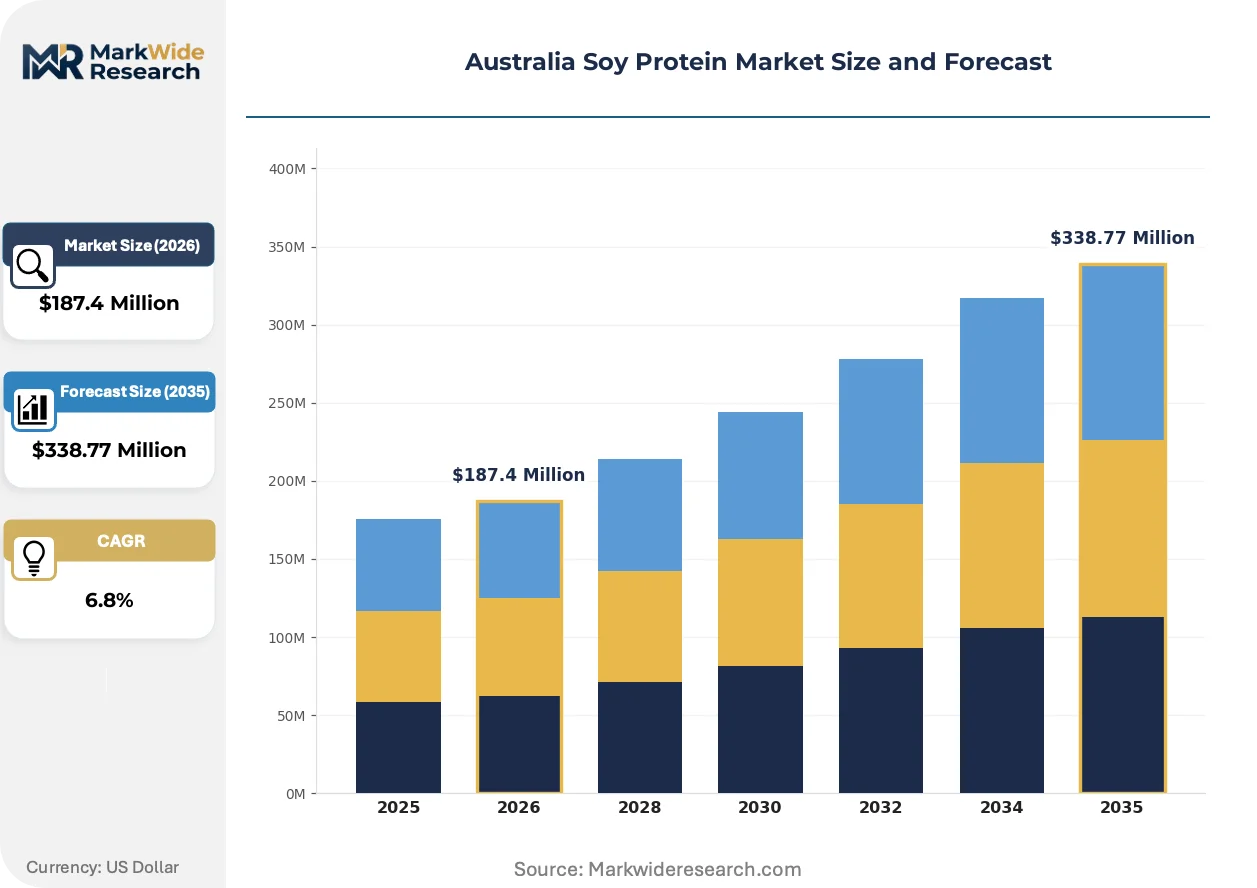
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Flour, Textured Soy Protein Application: Food & Beverages, Nutraceuticals, Animal Feed, Cosmetic Products End User: Households, Food Manufacturers, Restaurants, Health Clubs Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Food Stores |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Kerry Group plc, International Flavors & Fragrances Inc., Wilmar International Ltd, Bunge Limited, DuPont de Nemours, Inc., The Scoular Company, Danone SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Soy Protein Market Strategic Shifts
Extrusion technology advancement is compressing development timelines for whole-muscle analogues, while regulatory clarity around protein claims and biosecurity standardization reshape competitive requirements across the value chain.
High-moisture extrusion is consolidating functional protein development by enabling continuous fiber formation without post-texturization hydration. Plant-based meat manufacturers in Victoria and New South Wales are retrofitting production lines at accelerated pace. This capability compression is consolidating supplier relationships around equipment-integrated ingredient providers who deliver pre-calibrated protein systems.
FSANZ allergen labeling mandates now require explicit soy-derived ingredient declaration with prescribed precautionary statement formatting. Food manufacturers face reformulation costs to maintain clean-label positioning while complying. Dairy alternative producers are most affected, driving investment in flavor masking technologies that reduce detectable soy notes.
Ingredient procurement is consolidating around annual volume commitments with integrated suppliers who guarantee biosecurity-compliant raw material provenance. Mid-sized food manufacturers are abandoning spot-market purchasing in favor of contracted supply arrangements. This shift is most visible among processed meat extenders in Victoria seeking price predictability amid volatile crush margins.
Australia Soy Protein Market Segmentation
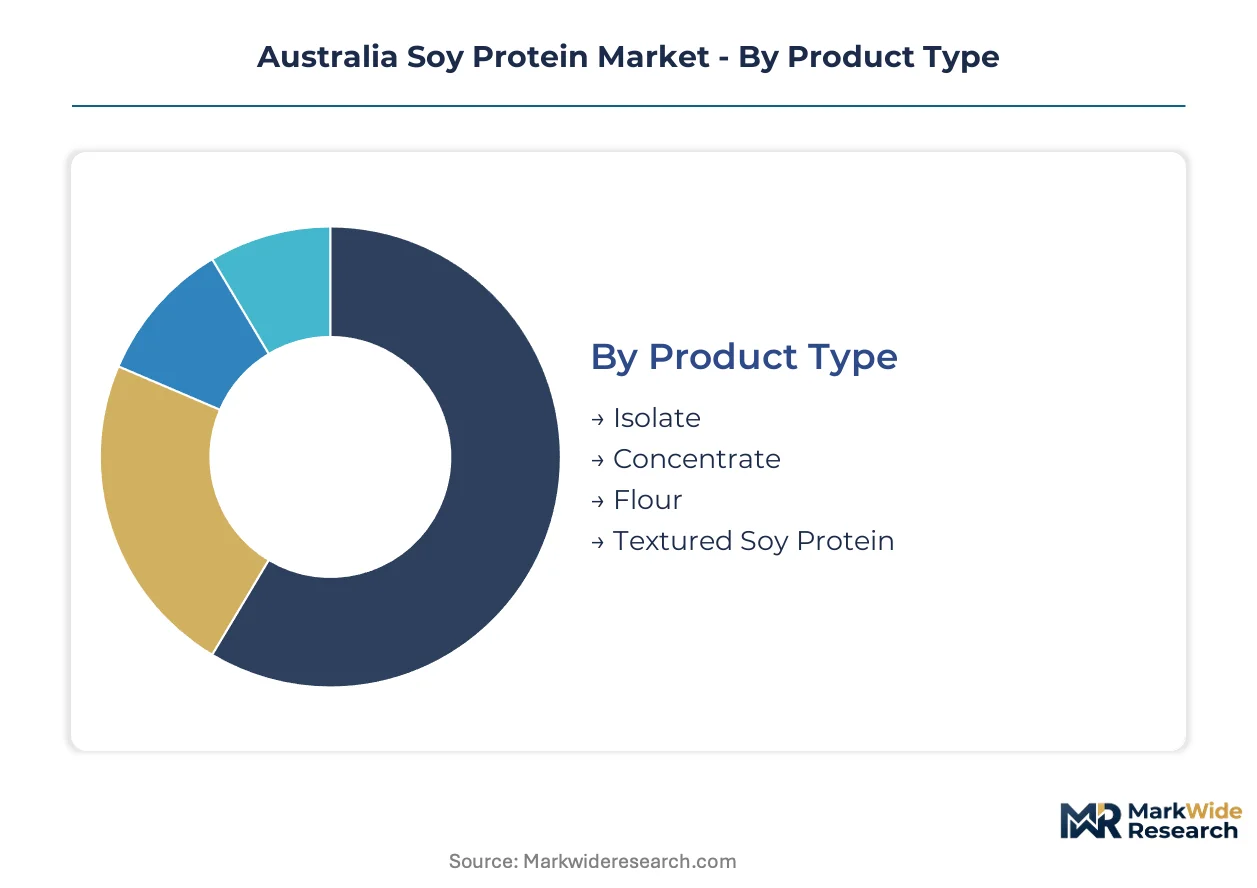
Soy protein procurement in Australia fragments across functional grades, end-use specifications, and channel structures that each carry distinct margin profiles and regulatory obligations. Understanding these segment boundaries clarifies where formulation complexity, price volatility, and supply concentration risks concentrate for buyers and suppliers alike.
Product Type:
Supply concentration among integrated crush operators with captive processing infrastructure governs availability and pricing dynamics across functional grades.
- Isolate:Protein concentrations exceed ninety percent through isoelectric precipitation and membrane filtration, yielding neutral flavor and superior emulsification. Demand concentrates among dairy alternative manufacturers in Victoria and New South Wales where FSANZ protein claim thresholds require minimum fortification levels. Premium positioning reflects extended formulation timelines for flavor masking.
- Concentrate:Mid-range protein levels between sixty and eighty percent retain more soluble carbohydrates and fiber than isolate grades. Processed meat extension applications in Victoria food processing clusters drive volume procurement where cost efficiency governs manufacturer decisions. Bulk distribution concentrates among traders with ocean freight integration.
- Flour:Full-fat or defatted meal with protein near fifty percent serves bakery fortification and animal nutrition formulations. Queensland feed compounders represent the primary demand concentration for standard-grade material.
- Textured Soy Protein:Extruded fibrous structures rehydrate into whole-muscle analogues for plant-based meat manufacturing. New South Wales and Victoria production line retrofits are accelerating procurement of pre-calibrated protein systems from equipment-integrated suppliers.
Today's leader: Concentrate. Tomorrow's challenger: Textured Soy Protein.
Application:
Cost tier differentiation separates commodity-grade feed applications from premium nutraceutical and cosmetic positioning where regulatory compliance costs escalate.
- Food & Beverages:Dairy alternatives, meat extensions, and bakery fortification dominate isolate and concentrate absorption. FSANZ allergen labeling mandates drive reformulation investment among manufacturers seeking clean-label positioning.
- Nutraceuticals:TGA-regulated protein claims restrict therapeutic assertions to approved formulations, creating a premium channel for isolate suppliers. Sports nutrition and clinical nutrition products in health club distribution carry compliance cost burdens that commodity food ingredients avoid.
- Animal Feed:Defatted soy meal serves aquaculture and livestock compounders with volume-driven, price-sensitive procurement. Biosecurity import regulations from the Department of Agriculture, Fisheries and Forestry influence domestic crush economics for feed-grade material.
- Cosmetic Products:Hydrolyzed soy protein derivatives enter hair and skin care formulations through specialty chemical distributors. Smaller volume demand concentrates among contract manufacturers serving premium beauty brands.
Food & Beverages commands current volume. Nutraceuticals offers the steepest expansion trajectory as TGA pathways mature.
End User:
Customer type determines order scale, technical service requirements, and contract structure preferences across the value chain.
- Food Manufacturers:Industrial-scale buyers in New South Wales and Victoria processing clusters favor annual volume commitments with integrated suppliers guaranteeing biosecurity-compliant provenance. Modular ingredient bundling reduces formulation complexity for plant-based meat developers.
- Restaurants:Foodservice operators procurement textured protein for menu development in quick-service and casual dining segments. Smaller lot sizes and irregular demand patterns limit direct supplier engagement.
- Health Clubs:Sports nutrition retail channels absorb isolate-based ready-to-drink and powder formulations. TGA compliance requirements filter supplier options to established nutraceutical ingredient providers.
- Households:Direct consumer purchases concentrate in online retail and health food store channels for home cooking and specialty diet adherence. Price sensitivity limits isolate adoption relative to concentrate and flour grades.
Food Manufacturers anchor procurement scale. Health Clubs are gaining share fastest as sports nutrition formats proliferate.
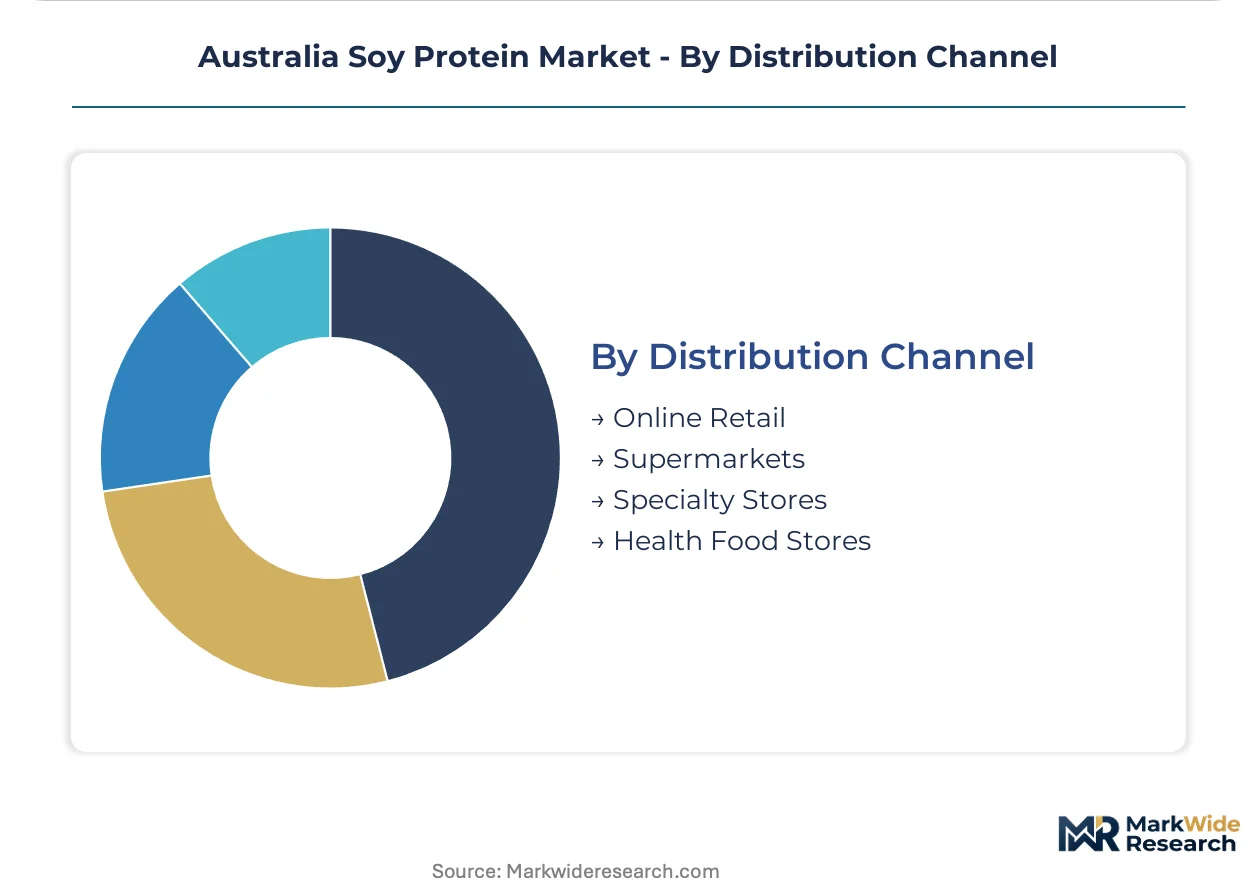
Distribution Channel:
Channel selection reflects customer technical sophistication, order urgency, and certification documentation requirements.
- Supermarkets:Mass retail distribution of consumer-packaged soy protein products concentrates in Coles and Woolworths private label programs. Volume concentration enables supplier negotiation leverage on specification compliance.
- Specialty Stores:Independent health food retailers and organic grocers serve allergen-conscious and diet-specific consumer segments. Higher service expectations and smaller order quantities support premium pricing for certified organic or non-GMO grades.
- Online Retail:Direct-to-consumer platforms and B2B marketplaces are displacing spot-market purchasing for mid-tier manufacturers seeking price transparency. Amazon Australia and specialty ingredient platforms aggregate demand from geographically dispersed buyers.
- Health Food Stores:Franchise networks and independent operators dominate sports nutrition and clinical nutrition product distribution. TGA registration requirements for therapeutic claims filter product assortment to compliant suppliers.
Supermarkets maintain volume leadership. Online Retail is climbing the fastest as procurement digitization accelerates among mid-sized manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Soy protein processing in Australia traces its industrial lineage to post-war crushing infrastructure expansion in Victoria, where defatted meal production first served export-oriented livestock feed markets before pivoting toward human food applications during the 1990s functional ingredients boom.
New South Wales
Food manufacturers in Sydney and Wollongong processing clusters drive isolate demand for dairy alternative fortification. FSANZ protein content thresholds compel minimum fortification levels in plant-based milk formulations. Parramatta-based extrusion facilities are retrofitting production lines for whole-muscle analogue manufacturing.
Victoria
Textured soy protein absorption concentrates among Melbourne meat alternative producers seeking cost-efficient protein extension. The Department of Agriculture, Fisheries and Forestry biosecurity protocols govern raw soybean import pathways through Port of Melbourne. Geelong crushing infrastructure anchors domestic isolate and concentrate supply for southeastern food processors.
Queensland
Aquaculture and livestock compounders in Brisbane and Townsville represent underdeveloped demand relative to southern states. State biosecurity administration intersects with federal DAFF regulations for imported meal certification. Gold Coast specialty food manufacturers are piloting pulse-soy hybrid systems for allergen-reduced meat extensions.
Western Australia
Perth-based nutraceutical formulators absorb isolate for sports nutrition and clinical nutrition products requiring TGA therapeutic claim compliance. Import logistics through Fremantle face extended lead times that compress working capital cycles for mid-tier manufacturers. Margaret River health food retail clusters are expanding distribution of certified organic soy protein grades.
Australia Soy Protein Market Competitive Environment
Premium-margin players sit above commodity-margin players across functional grade specialization and regulatory compliance depth. Integrated crush operators with captive ocean freight capacity dominate bulk isolate and concentrate distribution, while customized textured protein specialists capture value through equipment-integrated formulation support. Three archetypes populate the vendor landscape: multinational agricultural traders with backward processing control, ingredient technology specialists with extrusion equipment partnerships, and regional distributors with biosecurity certification depth. Competitive moves concentrate on annual volume commitment contracting and modular ingredient system bundling.
Within the integrated trader tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify scale-driven positions anchored by crushing infrastructure and ocean freight integration across Oceania. Kerry Group plc occupies a specialization vector focused on customized textured solutions for plant-based meat applications. These three entities represent distinct competitive postures: agricultural commodity depth versus functional ingredient technology versus equipment-integrated formulation support.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Kerry Group plc |
| International Flavors & Fragrances Inc. |
| Wilmar International Ltd |
| Bunge Limited |
| DuPont de Nemours, Inc. |
| The Scoular Company |
| Danone SA |
| Others |
Value Chain & Pricing Dynamics
FSANZ allergen labeling mandates gate qualified supply for premium-tier soy protein access, as manufacturers must demonstrate compliant provenance documentation to secure isolate and concentrate contracts above commodity feed-grade pricing. Buyers lacking certification depth face exclusion from dairy alternative and nutraceutical channels where TGA therapeutic claim pathways command substantial premia over standard food ingredient tiers.
Pricing Analysis
Three-tier pricing structure across premium isolate, standard concentrate, and economy flour levels stratifies procurement by protein concentration and certification burden. Price differentiation hinges on FSANZ compliance documentation depth and volume scale commitments, with annual contracted volumes securing predictable unit economics against spot-market volatility. Cost compression in concentrate tiers is intensifying because Argentine and Brazilian harvest fluctuations transmit directly into crush margin uncertainty. Mid-tier meat extension manufacturers exhibit highest price sensitivity, while TGA-registered nutraceutical formulators absorb isolate premia with minimal elasticity.
Supply Chain Analysis
Regional distribution centers in Melbourne and Sydney anchor hub-and-spoke patterns for southeastern food processing clusters, with Geelong crushing infrastructure feeding isolate and concentrate into Victoria manufacturing corridors. Raw soybean flows draw from Argentina, Brazil, and the United States, with biosecurity clearance at Port of Melbourne governing entry velocity. Single-source vulnerability concentrates in ocean freight capacity controlled by integrated agricultural traders, compressing procurement alternatives for manufacturers lacking contracted supply arrangements. Distribution runs through equipment-integrated ingredient providers who deliver pre-calibrated textured protein systems direct to plant-based meat production lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
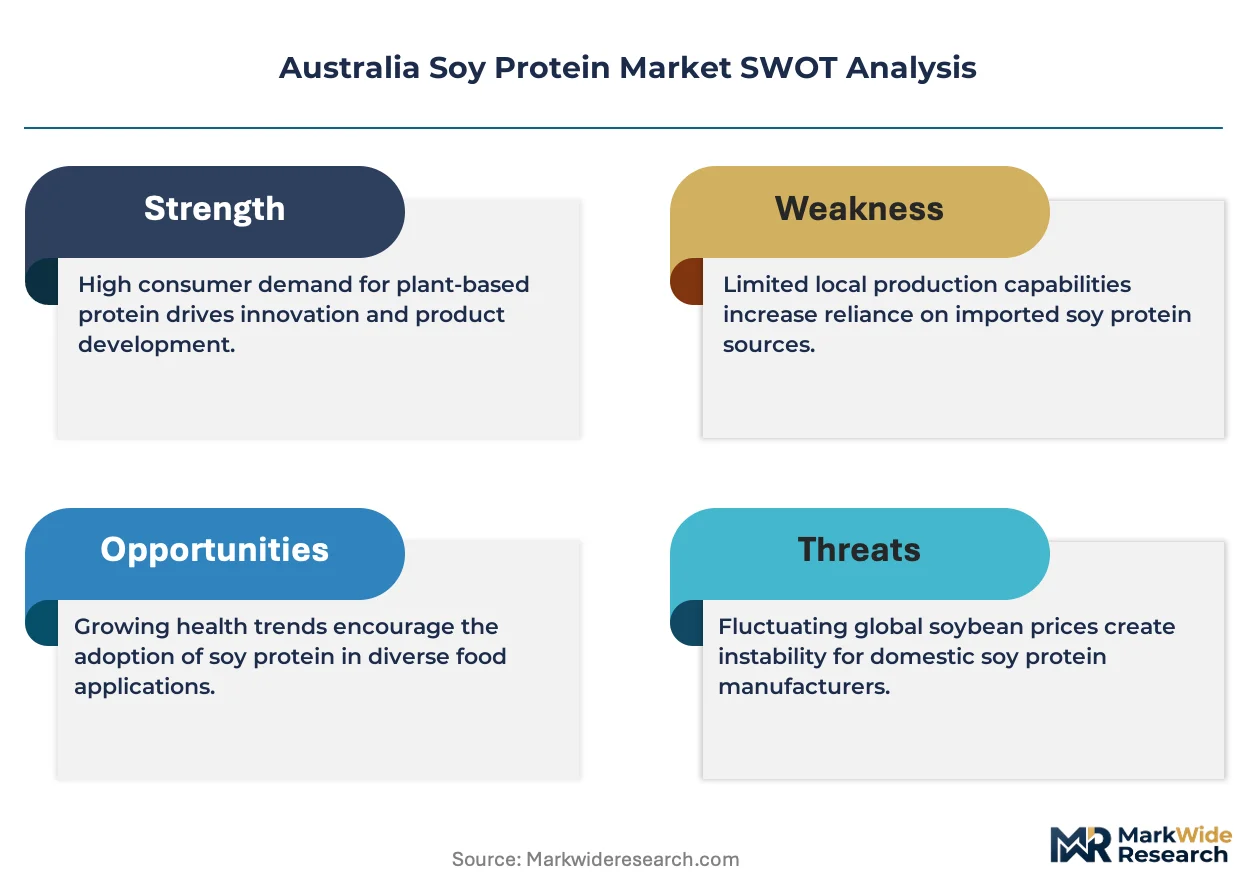
The Australia soy protein market reads as a late-cycle quality story, with isolate demand from TGA-registered nutraceutical applications and high-moisture extrusion capacity expansion shifting procurement toward specification-intensive premium tiers.
For Market Incumbents: To counter formulation talent scarcity eroding dairy alternative development timelines, anchor defensive positioning through backward integration into Geelong crushing assets and captive supply of biosecurity-certified raw material. Deepen equipment partnerships with extrusion technology providers to lock in textured protein system bundling relationships with New South Wales and Victoria plant-based meat manufacturers. For New Entrants and Emerging Players: Launch via online retail and B2B marketplace aggregation targeting Queensland and Western Australia food processing clusters where incumbent distribution coverage remains thin. Pulse-soy hybrid systems offer the most penetrable wedge for allergen-reduced meat extension applications, with Gold Coast specialty manufacturers piloting compliant formulations ahead of FSANZ novel food approval pathways. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors with biosecurity certification depth but limited extrusion equipment integration, as capability scarcity in formulation chemistry concentrates premium multiples among equipment-integrated specialists. Long-term viability hinges on isolate exposure to TGA-regulated nutraceutical channels rather than commodity concentrate volumes. The signal to watch is FSANZ novel food approval timeline compression accelerating product development cycle alignment with regulatory evaluation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crushing Assets | Captive supply of biosecurity-compliant raw soybean secures margin predictability against Argentine harvest volatility. |
| Equipment-Integrated Formulation Partnerships | Pre-calibrated textured protein systems reduce plant-based meat development timelines for Victoria manufacturers. |
| TGA Therapeutic Claim Pathway Investment | Isolate positioning in sports nutrition channels commands premium pricing above commodity food ingredient tiers. |
| Queensland Distribution Expansion | First-mover positioning in underdeveloped Brisbane and Townsville processing clusters captures volume ahead of incumbent response. |
| Pulse-Soy Hybrid System Development | Allergen-reduced formulations address FSANZ labeling constraints while maintaining meat extension functional performance. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with soy protein procurement managers at New South Wales and Victoria food manufacturers, crushing facility operations directors, TGA regulatory affairs consultants, and extrusion equipment technology specialists with secondary validation against FSANZ novel food approval databases, Department of Agriculture biosecurity import records, and Australian Bureau of Statistics trade flow data. Bottom-up volume modeling across isolate, concentrate, flour, and textured protein grades triangulated against top-down market sizing from crushing capacity utilization and end-use absorption rates.
Comparable-period anchoring linked historical reference data through established crush margin relationships and protein content claim adoption curves across the projection horizon. Segmentation dimensions modeled encompassed functional grade tier, application category spanning food and beverage through nutraceutical positioning, end-user scale and technical sophistication, and distribution channel structure. CAGRs derived from elasticity-adjusted absorption rates reflecting isolate demand from dairy alternative fortification requirements and textured protein retrofit acceleration in plant-based meat manufacturing corridors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under biosecurity protocol disruption or FSANZ labeling mandate acceleration. Forecasts reflect assumptions regarding crush capacity expansion timing, TGA approval pathway maturation, and extrusion technology adoption velocity without claiming certainty. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Distillers Grains Market
Ingredients
Self-Rising Flour Market
Ingredients
Resistant Starch Market
Ingredients
Global Personal Care Active Ingredients Market
Ingredients
Hydrolyzed Animal Protein Market
Ingredients
Animal and Marine Fats and Oils Market
Ingredients
Europe Gelatin Market
Ingredients
White Wheat Malt Market
Ingredients
Hydrolyzed Oat Protein Market
Ingredients
Mediterranean Marine Ingredients for Pet Health Market
Ingredients
Europe Alcohol Ingredients Market
Ingredients
South America Clean Ingredients Market
Ingredients
Cold Water Swelling Starch Market
Ingredients
South America Fermented Ingredients Market
Ingredients
Agar Market
Ingredients
Potato Granules Market