
 Hydrolyzed Pork Protein Market | 2026-2036
Hydrolyzed Pork Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrolyzed Pork Protein Market Insights
Food-grade hydrolysate specifications is reorganizing competitive dynamics across the hydrolyzed pork protein supply base. Gelita AG leverages its German manufacturing footprint to dominate pharmaceutical-grade collagen peptide output. Darling Ingredients Inc. anchors North American supply through its integrated rendering and protein processing network. Kerry Group plc differentiates via flavor-masked hydrolysate formulations targeting sports nutrition brands.
Hydrolyzed pork protein denotes enzymatically or acid-cleaved porcine collagen and muscle proteins reduced to peptide fractions typically below 10 kilodaltons, valued for high bioavailability, emulsification stability, and clean-label amino acid profiles in food and nutraceutical systems. Powdered forms occupy the largest volume share due to extended shelf stability and ease of dry-blending into premixes, while hydrolysate grades command premium positioning in clinical nutrition and infant formula adjacents where rapid absorption kinetics justify higher input costs. Sports nutrition and pet food end-user segments represent the fastest-growing demand pools, driven by humanization trends in companion animal diets and recovery-positioned protein products.
FDA GRAS self-affirmation pathways and USDA FSIS inspection requirements govern U.S. market access for porcine-derived food ingredients, while EFSA novel food consultations and REACH chemical safety dossiers shape European commercialization timelines. The EU MDR and ISO 13485 frameworks further constrain medical-grade collagen suppliers through biocompatibility and traceability mandates. Stakeholders must monitor evolving regulatory divergence between U.S. self-certification models and Europe's pre-market authorization regimes when allocating R&D and compliance budgets.
Market Dynamics
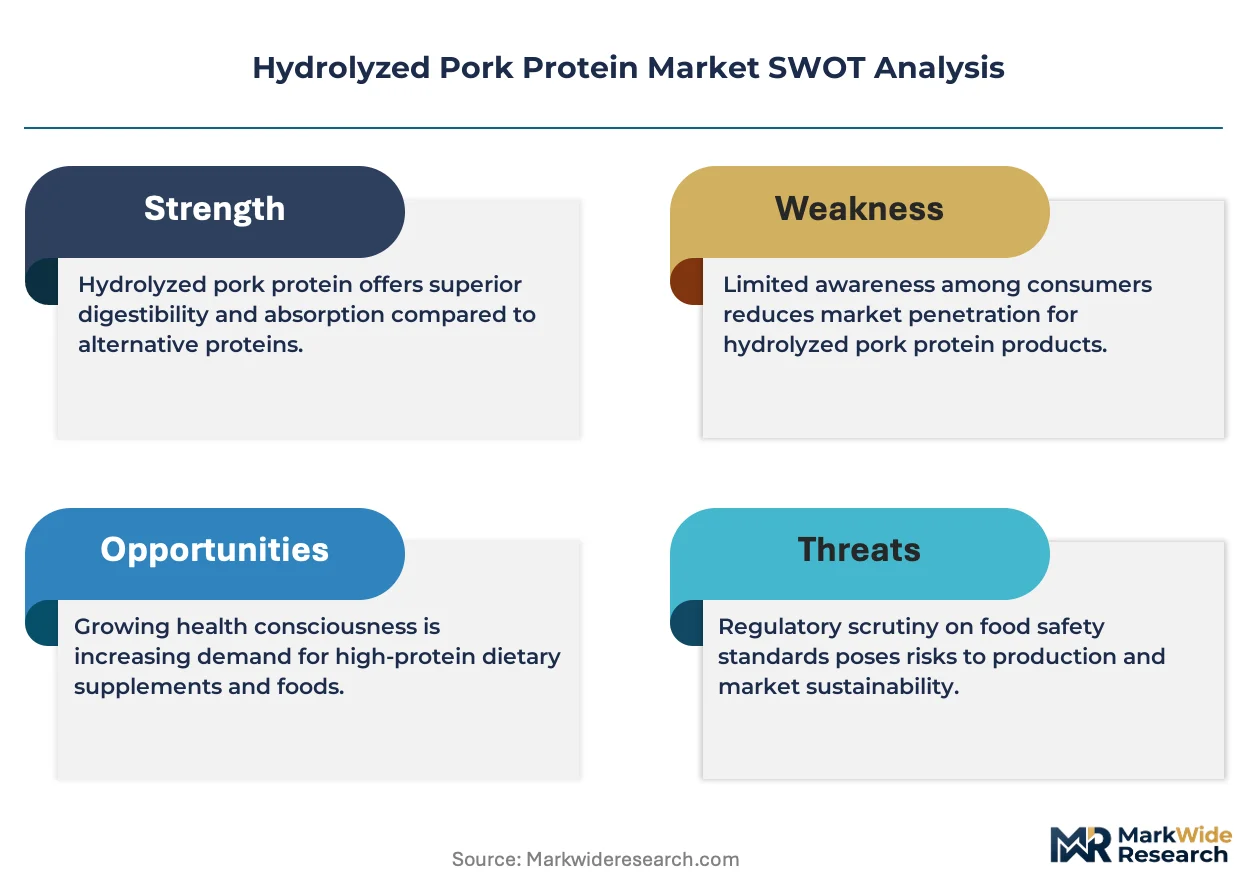
The hydrolyzed pork protein market is being restructured by tightening solvent recovery mandates under the EU F-Gas Regulation and REACH compliance frameworks, which are forcing capital reallocation toward closed-loop enzymatic hydrolysis systems and pressuring smaller European processors to consolidate or exit.
Growth Catalysts
- Sports nutrition procurement expansion:North American brands are accelerating purchases of fast-absorbing hydrolyzed pork protein isolates for recovery-positioned formulations, pulling volume from traditional whey and plant-based alternatives.
- REACH chemical safety dossiers:European regulatory clarity around porcine-derived peptide classifications is reducing commercialization uncertainty and enabling faster product registration timelines for compliant suppliers.
- Enzymatic hydrolysis advancement:Alcalase and flavourzyme enzyme cocktails are replacing acid hydrolysis in German processing clusters, improving peptide yield consistency and reducing downstream purification costs.
Market Restraints
- Raw material concentration risk:Rendering feedstock supply concentrates in Midwestern US packing house corridors and Northern European abattoir networks, creating geographic vulnerability to livestock disease outbreaks and transport disruptions.
- Collagen peptide substitution pressure:Marine and bovine collagen hydrolysates are capturing share in premium nutraceutical applications where porcine origin triggers religious dietary restrictions or clean-label hesitancy.
- EU MDR biocompatibility mandates:Medical-grade collagen suppliers face extended validation timelines and traceability infrastructure costs that compress margins on pharmaceutical-grade output.
Strategic Opportunities
- Pet food humanization tailwinds:Companion animal diet premiumization in Germany and the United States is opening formulation demand for hydrolyzed pork protein in veterinary therapeutic nutrition and high-end dry kibble.
- ISO 13485 certification arbitrage:Processors capable of bridging food-grade and medical-grade quality systems can capture margin expansion in wound care and surgical sealant applications where supply scarcity persists.
- Direct-to-brand procurement platforms:Sports nutrition and clinical nutrition formulators are bypassing traditional ingredient distributors, creating channel compression that rewards processors with technical service capabilities and formulation support.
Industry Challenges
- Peptide characterization expertise scarcity:Analytical chemists capable of molecular weight distribution profiling and bioactivity validation command premium compensation, constraining quality control scaling for mid-cap processors.
- Legacy acid hydrolysis asset stranding:European facilities with sunk capital in older reactor configurations face retrofit economics that disadvantage them against greenfield enzymatic plants in lower-cost jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrolyzed Pork Protein Market |
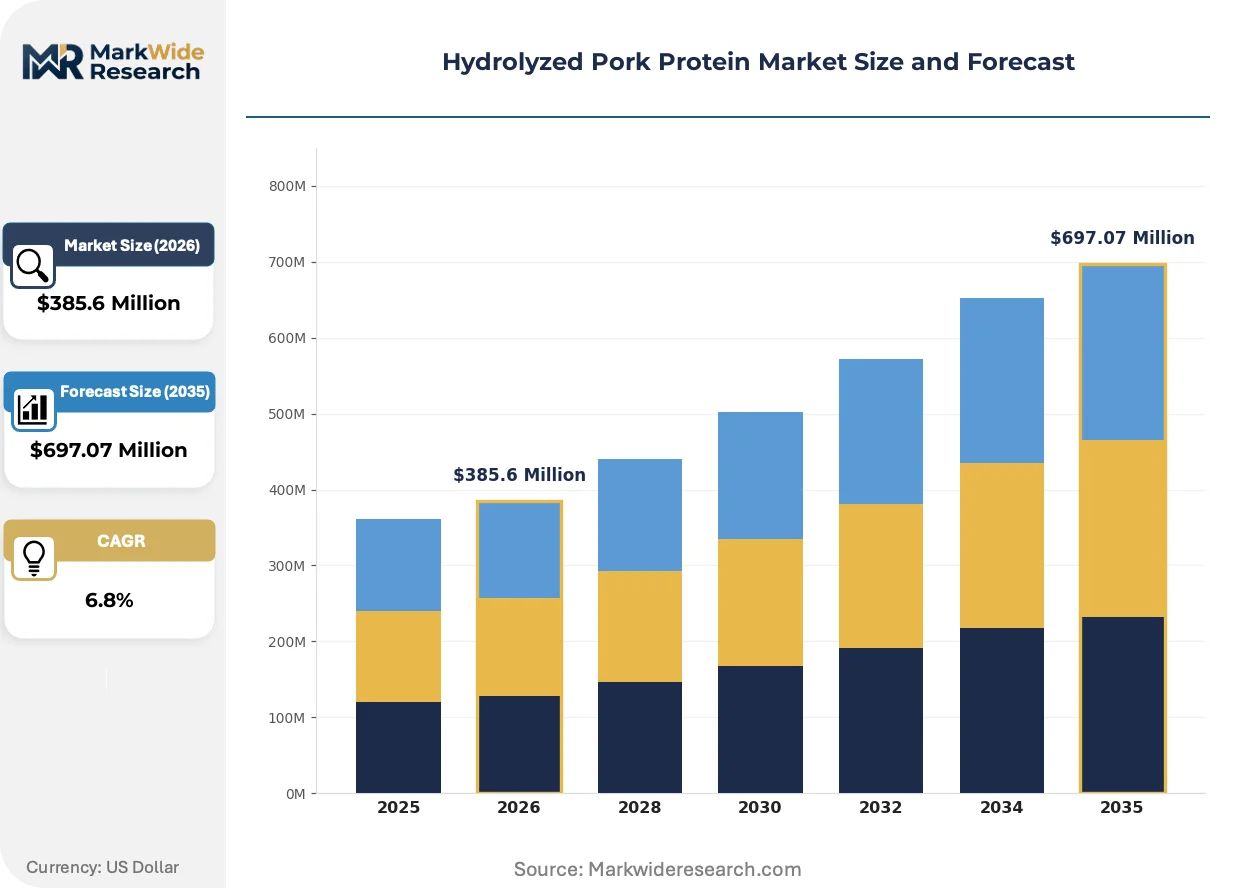
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Concentrate, Isolate, Hydrolysate End User: Food Industry, Nutraceuticals, Sports Nutrition, Pet Food Application: Meat Products, Dietary Supplements, Snacks, Soups Form: Liquid, Powdered, Ready-to-Use, Concentrated |
| Companies Covered | Gelita AG, Darling Ingredients Inc., A. Costantino & C. spa, GELNEX, Cargill, Smithfield Foods, Inc., Kerry Group plc, Tessenderlo Group, Saria SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrolyzed Pork Protein Market Trends and Innovations
Membrane filtration and precision enzymatic protocols are displacing legacy processing architectures across the hydrolyzed pork protein value chain, while regulatory data requirements and buyer procurement rationalization are compressing traditional commercialization timelines.
Ultrafiltration and nanofiltration membrane cascades are displacing solvent precipitation and centrifugation as the dominant peptide fractionation methodology. Sports nutrition formulators in Germany and the United States are specifying membrane-processed hydrolysates for their superior clarity and reduced ash content. This technology shift is displacing batch-oriented processing economics and favoring continuous manufacturing investments with higher throughput and lower labor intensity.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon solvents is forcing protein hydrolysis facilities to retrofit solvent recovery systems or switch to aqueous enzymatic protocols entirely. German processing clusters face the steepest compliance costs due to their concentration of large-scale collagen and gelatin operations. Facilities are responding by consolidating production into fewer, larger sites with integrated solvent capture and recycling infrastructure.
Long-term offtake contracting is displacing spot market purchasing for hydrolyzed pork protein isolates and peptides. North American sports nutrition brands are locking in multi-year supply agreements with processors capable of certifying amino acid profiles and heavy metal limits batch-to-batch. This procurement pattern shift is most visible in the United States, where brands are trading price flexibility for supply security and audit transparency in anticipation of FDA GRAS enforcement tightening.
Hydrolyzed Pork Protein Market Segmentation
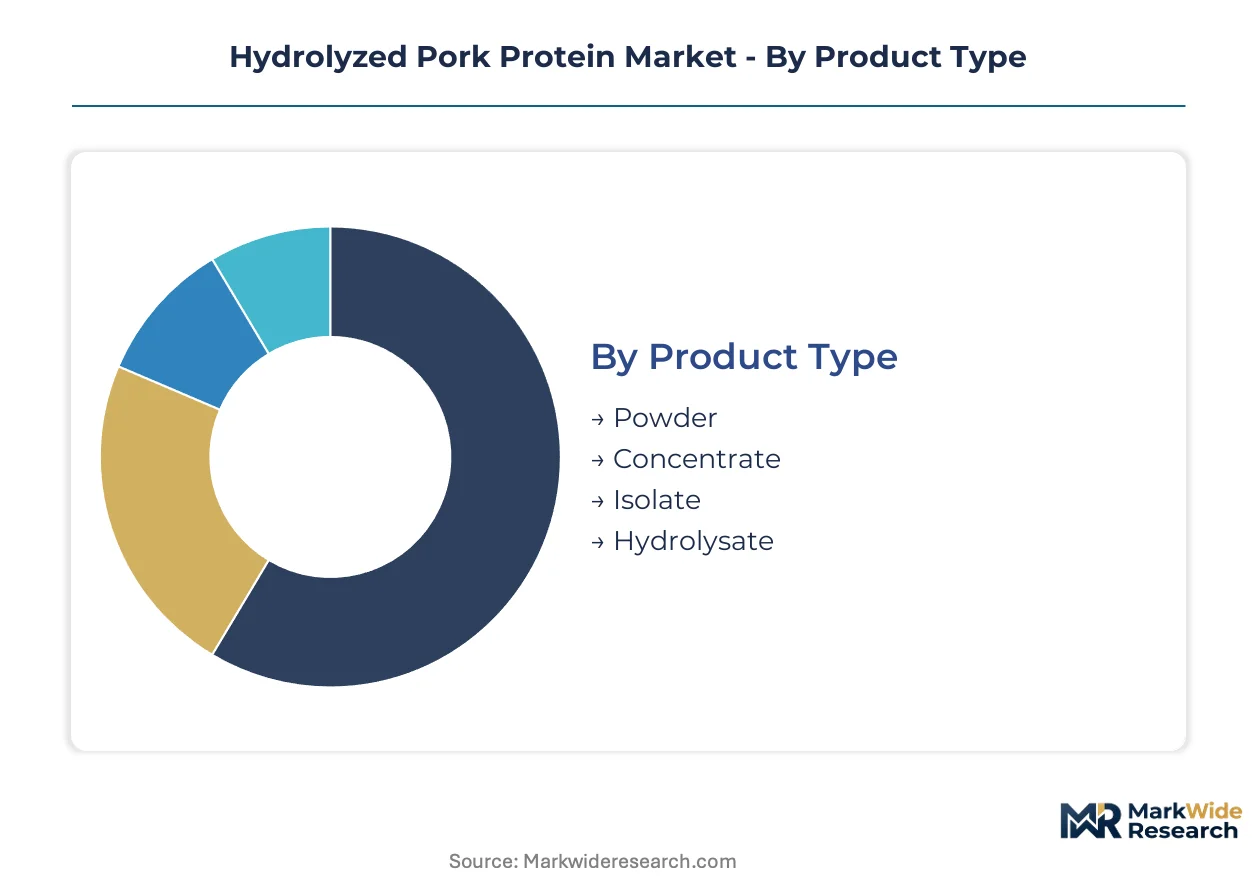
Hydrolyzed pork protein buyers select product grades based on absorption kinetics, formulation compatibility, and regulatory clearance requirements. Segmentation dynamics reflect divergent margin structures between commodity food applications and premium nutraceutical positioning.
Product Type:
Substitution pressure from marine and bovine collagen hydrolysates concentrates in premium peptide segments, forcing porcine suppliers to differentiate through cost efficiency and supply security.
- Powder:Spray-dried peptide fractions with moisture content below 5% enable extended shelf stability and dry-blending compatibility in premix manufacturing. Demand concentrates in German and United States food processing corridors where bulk handling infrastructure supports high-volume procurement. Powdered hydrolysates face limited substitution risk due to unmatched cost positioning in commodity applications.
- Hydrolysate:Low-molecular-weight peptide fractions below 3 kilodaltons engineered for rapid gastric emptying and clinical nutrition absorption. Sports nutrition formulators in North America specify hydrolysate grades for recovery-positioned products, absorbing premium pricing in exchange for documented bioavailability. Marine collagen hydrolysates threaten share in kosher and halal-sensitive formulations.
- Concentrate:Intermediate protein content grades serving cost-sensitive meat extension and processed food applications.
- Isolate:High-purity fractions for pharmaceutical and medical-grade collagen applications requiring enhanced traceability.
Powder retains volume leadership; hydrolysate holds the steepest expansion curve.
End User:
Cost tier stratification separates commodity food manufacturing from premium clinical and companion animal nutrition, with margin compression accelerating in mid-tier segments.
- Sports Nutrition:Recovery-positioned protein powders and ready-to-drink formulations demanding rapid amino acid availability. North American brands bypass traditional distributors to secure direct supply relationships with processors capable of batch-specific amino acid certification. Humanization trends in fitness culture elevate clean-label sourcing requirements.
- Pet Food:Veterinary therapeutic nutrition and premium dry kibble incorporating hydrolyzed pork protein for palatability and digestibility in companion animals. German and United States markets lead formulation demand as pet owners accept ingredient cost pass-through. Regulatory frameworks for animal feed additives constrain supplier qualification timelines.
- Food Industry:Meat extension, emulsification, and texture modification in processed products.
- Nutraceuticals:Capsule and tablet applications targeting joint health and skin elasticity positioning.
Food Industry retains volume leadership; Pet Food holds the steepest expansion curve.
Application:
Application maturity varies sharply, with legacy meat processing applications facing stagnation while functional nutrition formats attract reformulation investment.
- Dietary Supplements:Capsule, tablet, and powder delivery systems targeting amino acid supplementation and collagen synthesis support. German nutraceutical brands specify porcine-derived peptides for bioavailability claims, though EFSA health claim authorization constraints limit marketing latitude. Marine collagen substitution pressure is most acute in premium positioning.
- Snacks:Protein-fortified bars, chips, and extruded products incorporating hydrolyzed pork protein for texture and nutrition label enhancement. United States sports nutrition crossover brands drive formulation demand, requiring flavor-masked hydrolysates to overcome sensory challenges. Clean-label hesitation around porcine origin constrains expansion in certain demographic segments.
- Meat Products:Processed meat extension and binding applications in sausage and canned formats.
- Soups:Broth and bouillon applications leveraging emulsification stability and umami contribution.
Meat Products retains volume leadership; Snacks holds the steepest expansion curve.
Form:
Supply concentration in powdered processing infrastructure creates margin pressure for liquid and ready-to-use formats requiring specialized aseptic packaging investment.
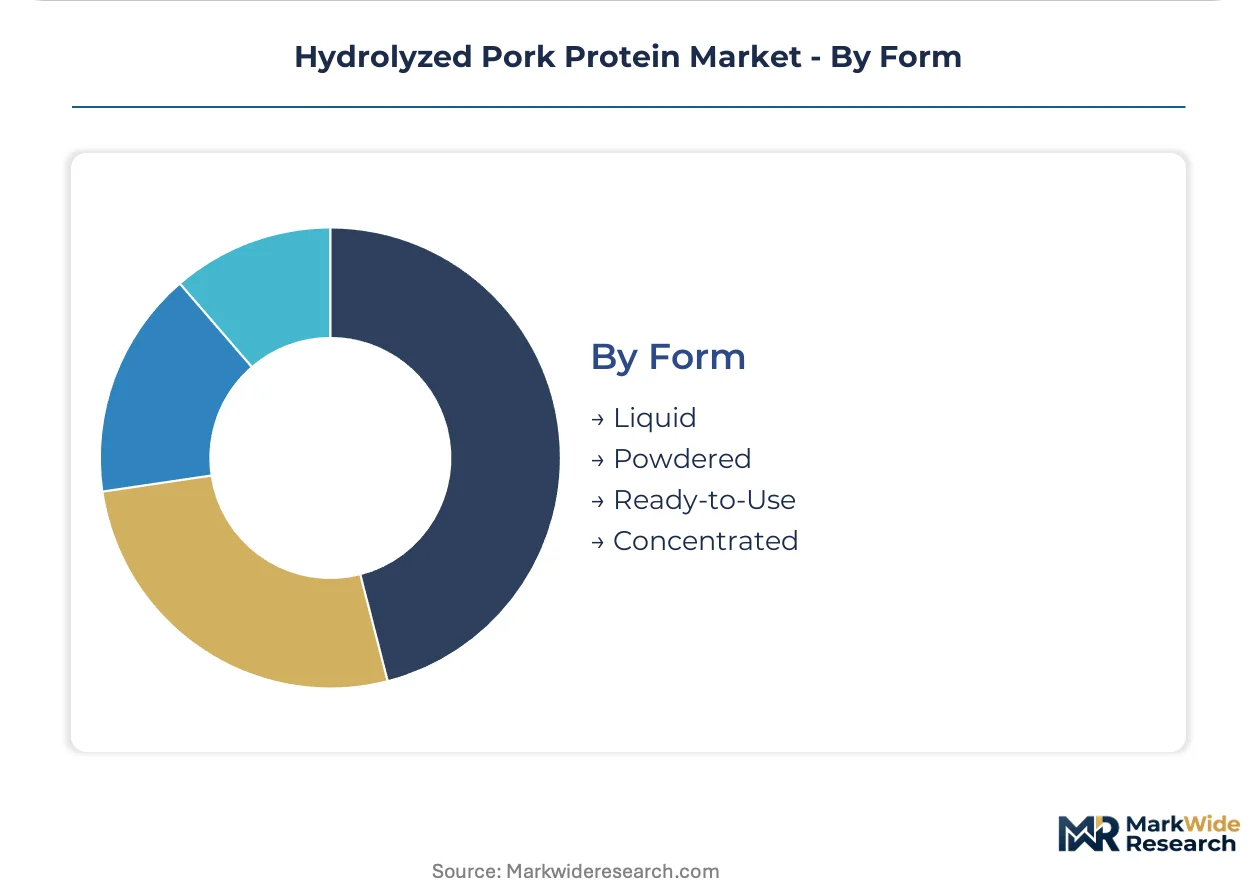
- Powdered:Dominant format occupying largest volume share through compatibility with existing food and supplement manufacturing infrastructure. German and United States processing clusters optimize spray-drying capacity for bulk export markets. Shelf stability and transport efficiency reinforce format dominance despite slower absorption kinetics versus liquid alternatives.
- Liquid:Ready-to-drink and shot-format applications in sports nutrition and clinical nutrition requiring minimal preparation. Aseptic processing and cold-chain distribution constraints limit supplier participation to integrated processors with beverage co-packing relationships. Premium positioning supports margin recovery against higher logistics costs.
- Ready-to-Use:Pre-hydrated formulations for institutional foodservice and healthcare settings.
- Concentrated:High-solids slurries for industrial meat processing and ingredient manufacturing.
Powdered retains volume leadership; Liquid holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rendering capacity and protein hydrolysis infrastructure cluster in specific geographies where pork processing density meets regulatory sophistication. Germany, the United States, and select European markets concentrate supply-side investment, while demand fragmentation pulls procurement toward sports nutrition and pet food formulators.
Germany
Sports nutrition brands and pharmaceutical collagen buyers drive procurement of enzymatically processed hydrolysates. The EU F-Gas Regulation mandates solvent recovery retrofits at protein hydrolysis facilities, accelerating capital reallocation. The Emsland region hosts Gelita AG and Tessenderlo Group operations serving medical-grade and food-grade peptide output.
United States
Midwestern packing house corridors supply rendering feedstock to integrated protein processors. FDA GRAS self-affirmation pathways and USDA FSIS inspection requirements govern porcine-derived ingredient commercialization. Iowa and Illinois processing clusters anchor North American hydrolyzed pork protein volume for sports nutrition and pet food applications.
Italy
Specialty gelatin and collagen peptide production serves pharmaceutical and nutraceutical formulators across Southern Europe. EFSA novel food consultation frameworks shape product registration timelines for hydrolyzed protein entrants. The Lombardy region maintains traditional rendering-to-hydrolysate processing capabilities with quality systems bridging food and medical grades.
China
Domestic pork processing scale supports expanding hydrolysate capacity for regional food and feed applications. SAMR food additive regulations and GB standards govern porcine-derived ingredient safety dossiers. Shandong Province processing clusters concentrate enzymatic hydrolysis investment targeting export-oriented peptide production.
Brazil
Growing pet food manufacturing base imports hydrolyzed protein specifications for companion animal nutrition formulations. ANVISA sanitary surveillance frameworks align with Mercosur technical regulations for animal-derived ingredients. São Paulo state industrial corridors integrate rendering output with protein hydrolysate processing for domestic and regional supply.
Hydrolyzed Pork Protein Market Competitive Landscape
Concentration sits with integrated rendering-to-hydrolysate processors and specialized collagen peptide manufacturers. The vendor base stratifies across three tiers: multinational ingredient conglomerates with backward integration into rendering, mid-cap enzymatic hydrolysis specialists, and regional processors serving commodity food applications. Dominant competitive moves include capacity consolidation in German processing clusters and direct-to-brand procurement platform development bypassing traditional distribution.
Within the integrated multinational tier, Gelita AG exemplifies pharmaceutical-grade collagen peptide positioning through German manufacturing scale. Darling Ingredients Inc. anchors North American supply architecture through captive rendering networks. Kerry Group plc occupies a formulation-services position, differentiating via technical support capabilities for sports nutrition brand customers.
| Leading Market Players |
|---|
| Gelita AG |
| Darling Ingredients Inc. |
| A. Costantino & C. spa |
| GELNEX |
| Cargill |
| Smithfield Foods, Inc. |
| Kerry Group plc |
| Tessenderlo Group |
| Saria SE & Co. KG |
| Others |
Pricing and Supply Chain Analysis
Marine collagen hydrolysate substitution in kosher and halal-sensitive formulations simultaneously redraws supply geography toward coastal processing clusters and compresses pricing power in premium peptide tiers. This displacement dynamic forces porcine suppliers to defend volume positions through cost efficiency while ceding margin-rich segments to alternative protein sources.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across European hydrolyzed pork protein output, separating membrane-processed enzymatic grades from legacy acid-hydrolyzed commodity positions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with ISO 13485 medical-grade commands absorbing the steepest premiums. Pricing pressure stems from REACH compliance retrofit costs passing through to buyers, while sports nutrition brands demonstrate lowest price sensitivity due to bioavailability-driven procurement.
Supply Chain Analysis
Strategic stockpile preferences dominate sports nutrition procurement, with North American brands locking multi-year offtake contracts to secure batch-traceable supply. Raw material sourcing concentrates in Germany, the United States, and China, drawing from Midwestern packing house corridors, Northern European abattoir networks, and Shandong Province rendering clusters. Feedstock supply rests on porcine byproduct streams, enzymatic processing reagents, and membrane filtration infrastructure. Single-source vulnerability in German pharmaceutical-grade collagen peptide output creates concentration risk. Distribution runs through direct-to-brand procurement platforms bypassing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as sports nutrition formulators bypass traditional distribution, creating niche entry points for processors with technical service capabilities and formulation support infrastructure.
For Market Incumbents: Fortify supply security through backward integration into rendering networks in Iowa and Illinois corridors, locking captive feedstock access against livestock disease outbreak disruptions. Deepen ISO 13485 certification coverage to defend pharmaceutical-grade margins against marine collagen substitution in wound care applications. For New Entrants and Emerging Players: Anchor in Brazilian pet food manufacturing expansion, where ANVISA frameworks create qualification barriers favoring processors with established quality systems. Target veterinary therapeutic nutrition formulations for companion animal humanization trends, leveraging direct procurement relationships with São Paulo state formulators seeking regional supply alternatives. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed enzymatic hydrolysis specialists in German processing clusters facing EU F-Gas Regulation retrofit capital demands. Long-term viability favors processors bridging food-grade and medical-grade quality systems with integrated solvent recovery infrastructure. Watch for FDA GRAS enforcement tightening as inflection indicator for procurement pattern shifts toward audit-transparent suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rendering | Iowa and Illinois corridor control secures feedstock against livestock disease disruptions. |
| ISO 13485 Certification Investment | Medical-grade quality systems unlock wound care and surgical sealant margin expansion. |
| Membrane Filtration Capacity Expansion | Ultrafiltration and nanofiltration cascades displace legacy solvent precipitation economics. |
| Direct-to-Brand Procurement Platform | Sports nutrition formulators bypass distributors for technical service and batch certification. |
| Enzymatic Hydrolysis Retrofit | Alcalase and flavourzyme protocols replace acid hydrolysis for peptide yield consistency. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, engaging protein hydrolysis plant managers, sports nutrition brand procurement leads, veterinary therapeutic nutrition formulators, and pharmaceutical collagen peptide buyers. Secondary validation drew from FDA GRAS filings, EFSA novel food consultation records, REACH chemical safety dossiers, and EU MDR biocompatibility submissions. Bottom-up volume triangulation across product grades, end-user segments, and regional processing clusters was cross-checked against top-down macroeconomic indicators.
Across the analysis window, the forecasting framework modeled hydrolyzed pork protein evolution through product type segmentation, end-user category dynamics, application maturity curves, and form factor substitution patterns. CAGRs were derived from regression analysis of historical procurement volumes and projected demand elasticity in sports nutrition and pet food verticals. Key inputs included enzymatic processing capacity expansion timelines, regulatory compliance cost pass-through assumptions, and marine collagen substitution rate trajectories in premium nutraceutical positioning.
Decision-makers should treat outputs as directional under stable regulatory enforcement and intact feedstock supply assumptions; material deviation would warrant model refresh. Specific risk factors include EU F-Gas Regulation phasedown acceleration, African swine fever resurgence in key rendering corridors, and FDA GRAS self-affirmation pathway modification. Revision becomes warranted when marine collagen cost parity crosses thresholds in clinical nutrition applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cold Water-Soluble Creamer Market
Ingredients
Anhydrous Caffeine Market
Ingredients
Global Egg Yolk Oil Market
Ingredients
Fish Peptones Market
Ingredients
Volatile Fatty Acids Market
Ingredients
Rennet Market
Ingredients
North America Vegetable Oils Market
Ingredients
Global Hydrolyzed Wheat Protein Market
Ingredients
Vegetable Extract Market
Ingredients
Guar Gum Market
Ingredients
Beetroot Powder Market
Ingredients
Oak Extract Market
Ingredients
Revivable Yeast Market
Ingredients
Europe Algae Omega-3 Ingredients Market
Ingredients
Potato Granules Market
Ingredients
Pet Food Premix Market