
 Demineralized Whey Powder Ingredient Market | 2026-2036
Demineralized Whey Powder Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Demineralized Whey Powder Ingredient Market Analysis
Buyer concentration among infant formula and clinical nutrition manufacturers is broadening as specialized dairy ingredient procurement extends beyond traditional dairy conglomerates. FrieslandCampina leverages integrated whey processing infrastructure across European dairy belts to secure consistent demineralized output. Arla Foods Ingredients anchors premium nutritional applications through advanced ion-exchange capabilities. Lactalis Ingredients competes on manufacturing scale, operating multiple demineralization lines serving both food and pharmaceutical channels.
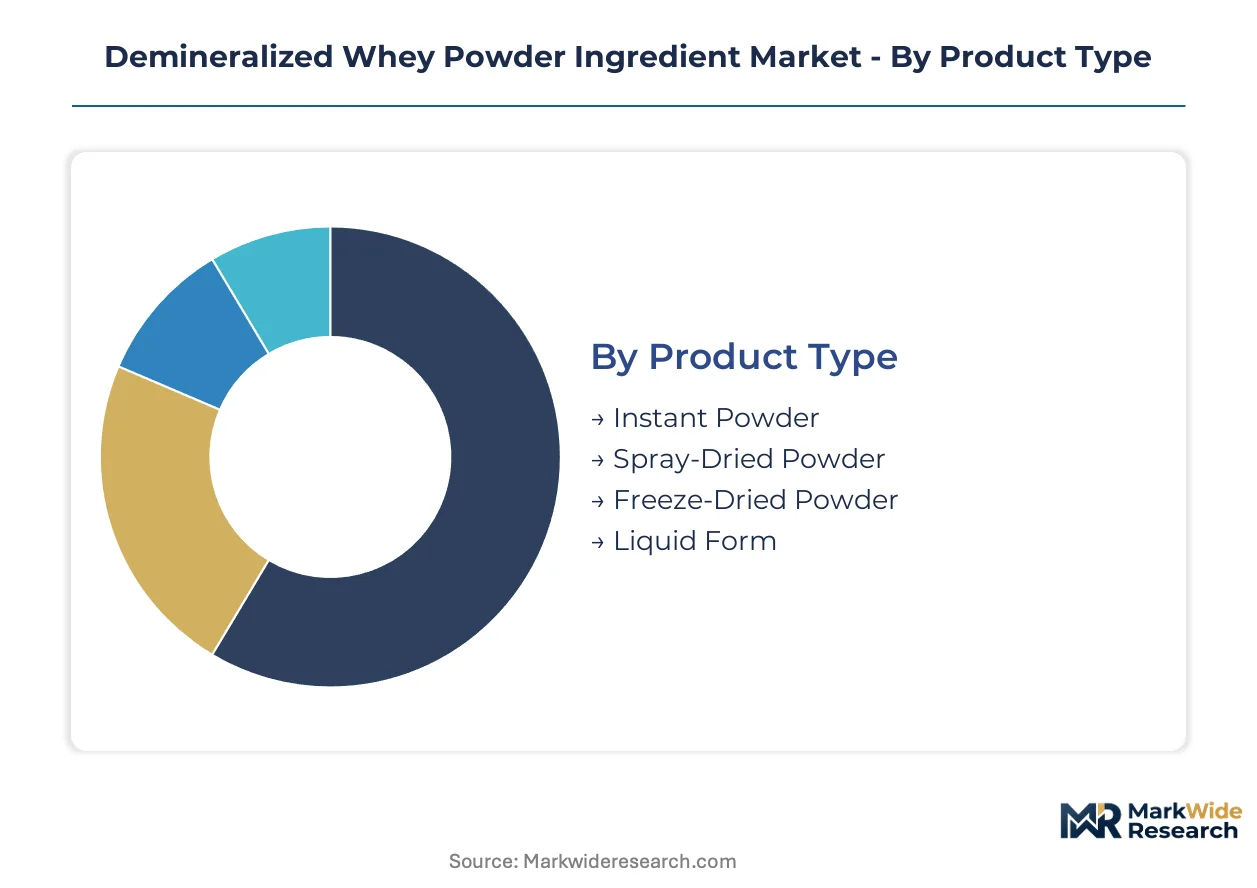
Demineralized whey powder ingredient refers to whey from which mineral salts—primarily calcium, sodium, potassium, and magnesium—have been substantially removed through electrodialysis or ion-exchange, typically achieving demineralization rates of 50% to 90% depending on intended application. The resulting low-ash, high-lactoprotein material serves as a functional base in infant nutrition, sports formulations, and pharmaceutical excipients where mineral load must be precisely controlled. Spray-dried powder commands the dominant production volume due to cost-efficient continuous processing and superior shelf stability for bulk ingredient distribution. Instant powder represents the fastest-growing structural category, as beverage and ready-to-mix nutritional manufacturers prioritize rapid dispersibility without clumping. Liquid form retains niche positioning within regional dairy processing hubs where just-in-time delivery to adjacent food manufacturing plants eliminates rehydration steps.
EU REACH and EFSA novel food frameworks govern mineral residue thresholds and protein quality claims across European formulations, while FDA GRAS determinations and FSMA preventive controls shape U.S. import and domestic production standards for infant-grade ingredients. These layered requirements elevate compliance costs for new entrants but reinforce incumbent positions among processors with established regulatory dossiers. Stakeholders must monitor evolving WHO Codex Alimentarius revisions on infant formula mineral specifications, as harmonization efforts between European and Asia-Pacific regulators could redirect competitive advantage toward processors with dual-continent certification capabilities.
Market Dynamics
EU REACH compliance on mineral content thresholds is compressing supplier margins while accelerating consolidation among ion-exchange capable processors serving infant formula channels.
Growth Catalysts
- Infant formula mineral specifications:WHO Codex Alimentarius revisions on sodium and potassium limits in infant nutrition formulations are mandating lower-ash whey derivatives across European production facilities.
- Electrodialysis efficiency gains:Advances in membrane stack configuration and polarity reversal protocols are reducing energy consumption per demineralization cycle by processors operating continuous lines.
- Germany:Dairy processing clusters around Bavaria and Lower Saxony concentrate specialized ingredient distributors serving Central European nutraceutical contract manufacturers.
Market Restraints
- Fresh whey supply volatility:Seasonal milk production fluctuations in the Netherlands and Denmark create raw material availability constraints for demineralization plants.
- Ion-exchange resin costs:Specialized chromatography media for selective mineral removal require periodic replacement, elevating operating expenditures versus electrodialysis alternatives.
- Plant protein substitutes:Pea and rice protein isolates with adjusted mineral profiles are penetrating sports nutrition applications previously served by demineralized whey.
Strategic Opportunities
- Clinical nutrition expansion:Renal-specific formulations requiring precisely controlled phosphorus and potassium loads represent an underdeveloped application segment for 90% demineralized grades.
- EU Green Deal bioeconomy incentives:Funding mechanisms for circular dairy processing are supporting capital deployment toward integrated whey valorization facilities.
- Instant powder dispersibility:Agglomeration technology convergence with lecithination processes is opening ready-to-mix beverage channels demanding rapid hydration without mechanical shear.
Industry Challenges
- Process analytical technology integration:Real-time mineral monitoring using inline conductivity and spectroscopic methods requires skilled automation engineers scarce in traditional dairy regions.
- Dual-certification timelines:Simultaneous EFSA novel food dossiers and FDA GRAS self-affirmations for new demineralization protocols extend commercialization cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Demineralized Whey Powder Ingredient Market |
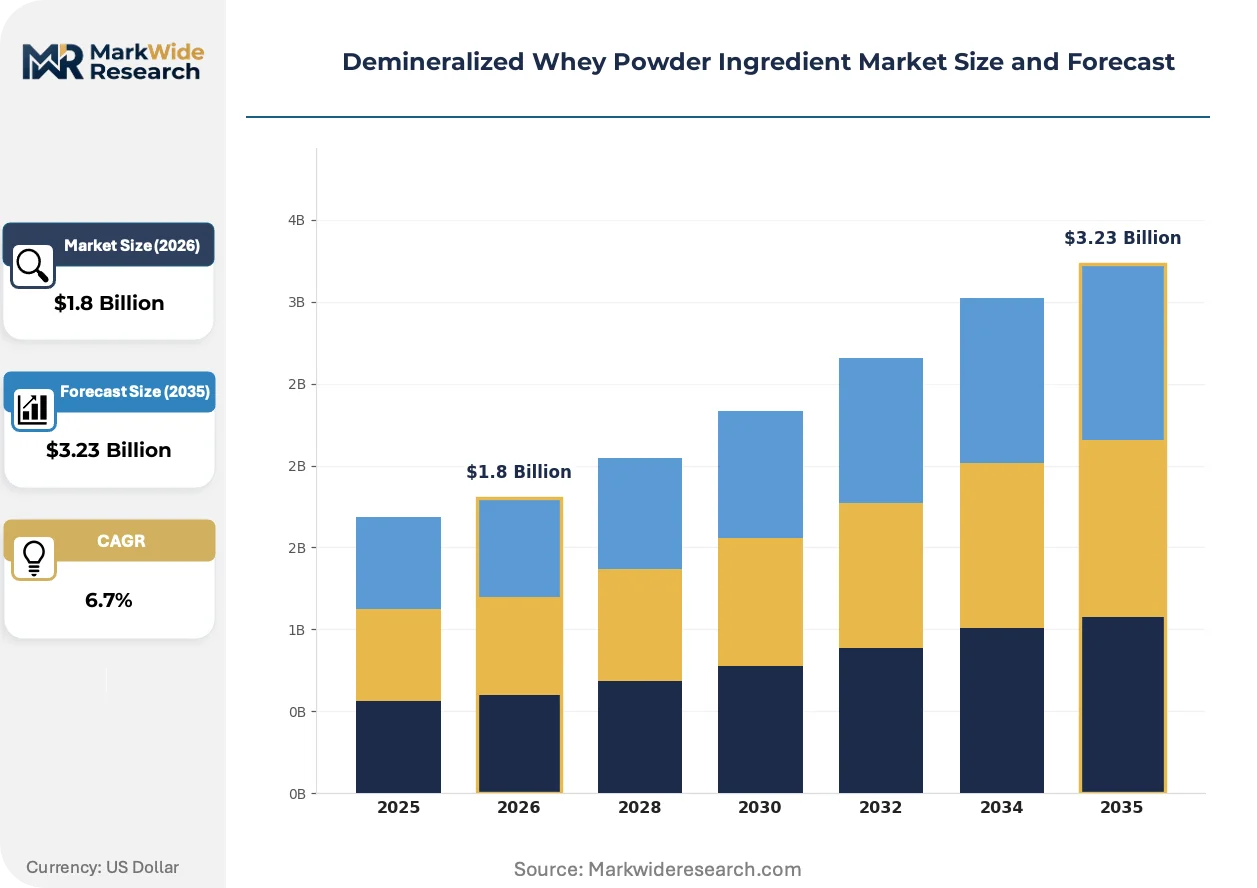
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Powder, Spray-Dried Powder, Freeze-Dried Powder, Liquid Form Application: Beverages, Dairy Products, Nutritional Supplements, Bakery Products End User: Food Manufacturers, Nutraceutical Companies, Pharmaceutical Firms, Sports Nutrition Distribution Channel: Online Retailers, Supermarkets, Wholesale Distributors, Specialty Stores |
| Companies Covered | FrieslandCampina, Arla Foods Ingredients, Lactalis Ingredients, Valio, Dairygold Food Ingredients, Euroserum, Fonterra, Glanbia Nutritionals, Saputo Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Demineralized Whey Powder Ingredient Market Emerging Trajectories
Processing technology convergence with precision nutrition requirements is redefining competitive advantage around mineral specificity rather than commodity whey sourcing.
Membrane filtration cascades preceding ion-exchange demineralization are integrating lactose crystallization and protein fractionation into unified continuous processing architectures. Infant formula manufacturers in the Netherlands and Ireland are adopting these hybrid lines to secure captive supply of 70-90% demineralized grades. This integration is compressing the traditional separation between commodity whey processors and specialized nutritional ingredient suppliers.
EFSA's evolving stance on protein quality claims in follow-on formula is tightening amino acid scoring requirements that indirectly favor whey protein concentrates with controlled mineral backgrounds. Manufacturers must now document essential amino acid profiles alongside ash content in regulatory submissions. German and French infant nutrition producers are responding by sourcing exclusively from processors with validated ion-exchange calibration protocols.
Long-term supply agreements with fixed mineral specification bands are displacing spot purchasing for critical infant-grade volumes. Multinational formula producers in Switzerland and the Netherlands are locking three-to-five year contracts with demineralization specialists, transferring price volatility risk onto processors. This shift is most visible among buyers serving Chinese import channels where mineral compliance documentation faces heightened customs scrutiny.
Demineralized Whey Powder Ingredient Market Segmentation
Demineralized whey powder ingredient procurement patterns diverge sharply across product formats and end-use channels, with mineral specification tolerances and dispersibility requirements driving distinct sourcing behaviors. Manufacturers segment supply strategies by processing technology, application criticality, and regulatory certification tiers rather than commodity pricing alone.
Product Type:
Standardization dominates powder categories where continuous processing achieves mineral consistency, while liquid forms retain customization through regional dairy hub proximity.
- Spray-Dried Powder:Continuous spray-drying towers achieve 50-90% demineralization rates through integrated electrodialysis-ion exchange sequences. Bulk infant formula manufacturers in the Netherlands and Germany anchor procurement volumes here, prioritizing shelf-stable intermediates with validated EFSA mineral dossiers.
- Instant Powder:Agglomeration and lecithination create rapid-dispersing particles for ready-to-mix beverage applications. Sports nutrition contract manufacturers in Ireland and Denmark are shifting procurement toward this format to eliminate mechanical shear requirements in protein shake formulations.
- Freeze-Dried Powder:Lyophilization preserves native protein structures for pharmaceutical excipient applications requiring minimal thermal degradation.
- Liquid Form:Tanker delivery within 200-kilometer dairy processing clusters eliminates rehydration steps for adjacent food manufacturing plants.
Most installed capacity flows through Spray-Dried Powder. Expansion is steepest in Instant Powder.
Application:
Application segmentation reflects mineral control stringency, with clinical-grade formulations commanding premium specification bands over commodity food uses.
- Nutritional Supplements:Infant formula and clinical nutrition drive 70-90% demineralization requirements with tight sodium-potassium bands. Swiss and Dutch manufacturers enforce three-to-five year supply agreements with fixed mineral specifications to secure Chinese import compliance documentation.
- Dairy Products:Standard 50-70% demineralized grades optimize protein fortification in yogurt and processed cheese without mineral precipitation issues.
- Beverages:Instant dispersibility demands dominate ready-to-drink protein formulations.
- Bakery Products:Cost-sensitive fortification applications tolerate wider mineral variance.
Revenue concentrates in Nutritional Supplements. Volume expansion runs fastest in Beverages.
End User:
End-user stratification separates regulatory-capable processors from commodity suppliers, with pharmaceutical and infant-grade channels erecting certification barriers.
- Nutraceutical Companies:Renal-specific and metabolic disorder formulations require precisely controlled phosphorus loads achievable only through validated ion-exchange calibration. German contract manufacturers are sourcing exclusively from processors with documented amino acid scoring protocols aligned to EFSA follow-on formula requirements.
- Pharmaceutical Firms:FDA GRAS self-affirmations and EMA excipient certifications demand dual-continent dossier capabilities extending commercialization timelines.
- Food Manufacturers:Bakery and dairy processors prioritize cost-efficient 50% demineralized grades with flexible spot purchasing.
- Sports Nutrition:Pea and rice protein substitution pressure is compressing whey share in mass-market formulations.
Procurement value pools deepest at Nutraceutical Companies. Certification investment is climbing fastest among Pharmaceutical Firms.
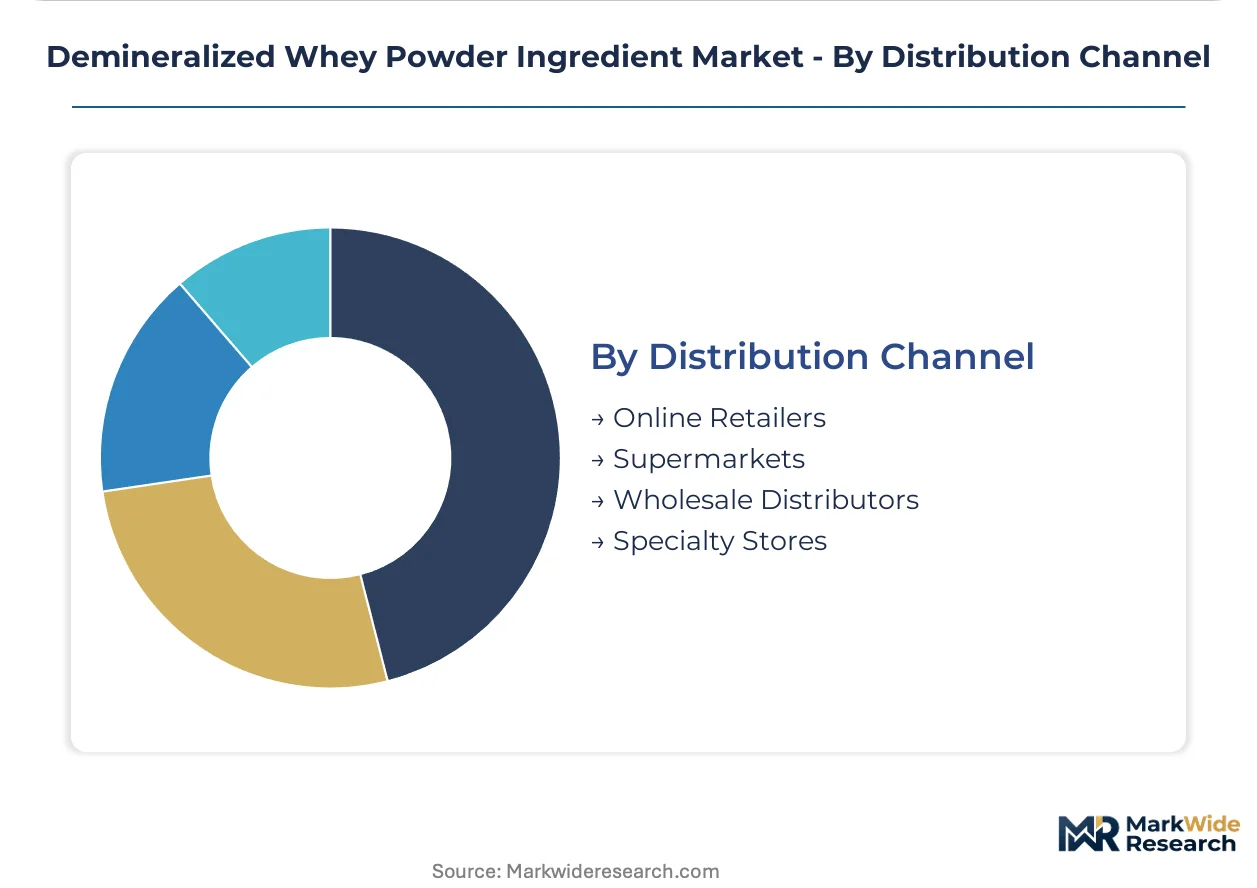
Distribution Channel:
Channel structure bifurcates between bulk ingredient logistics and specification-intensive direct procurement, with traceability requirements reshaping intermediary roles.
- Wholesale Distributors:Specialized dairy ingredient distributors in Bavaria and Lower Saxony consolidate Central European nutraceutical supply, offering lot-level mineral certification documentation.
- Online Retailers:E-commerce penetration remains marginal for bulk industrial volumes but serves small-scale sports nutrition and specialty food formulators.
- Supermarkets:Consumer-packaged finished goods dominate; raw ingredient sales are negligible.
- Specialty Stores:Niche positioning for artisan food producers requiring small-batch custom mineral specifications.
Volume flows predominantly through Wholesale Distributors. Digital procurement adoption is advancing most quickly among Online Retailers serving mid-scale formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany processes more demineralized whey volume than France and Italy combined, while the Netherlands concentrates infant-grade certification expertise in a narrow corridor between Utrecht and Zwolle.
Germany
Infant formula manufacturers in Bavaria and Lower Saxony anchor procurement volumes for 70-90% demineralized grades. EFSA novel food dossiers and REACH mineral thresholds shape processor compliance investments. Dairy processing clusters around Munich and Münster concentrate ion-exchange capable facilities serving Central European nutraceutical contract manufacturers.
Netherlands
Swiss and German formula producers source through Dutch processors for Chinese export compliance documentation. EU Green Deal bioeconomy incentives support integrated whey valorization facility upgrades. The Utrecht-Zwolle corridor hosts specialized distributors consolidating lot-level mineral certification for nutraceutical channels.
Switzerland
Multinational formula headquarters in Vevey and Baar lock three-to-five year supply agreements with fixed mineral specification bands. Swissmedic pharmaceutical excipient standards intersect with EFSA infant nutrition frameworks. The Basel-Zurich axis concentrates regulatory dossier expertise for dual-continent certification timelines.
United States
FDA GRAS self-affirmations and FSMA preventive controls elevate compliance costs for infant-grade ingredient imports. Sports nutrition contract manufacturers in Wisconsin and Idaho tolerate wider mineral variance for cost-sensitive applications. The Upper Midwest dairy belt supplies raw whey to regional demineralization plants with shorter distribution loops.
China
Domestic infant formula producers face heightened customs scrutiny on mineral compliance documentation for imported whey derivatives. SAMR and GB standards on protein quality claims tighten amino acid scoring requirements. Yangtze River Delta processing hubs develop captive ion-exchange capacity to reduce import dependency.
Demineralized Whey Powder Ingredient Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across mineral specification tiers, creating a bifurcated structure where scale-driven commodity processors serve food manufacturing while certification-intensive specialists capture infant and pharmaceutical channels. The vendor base clusters around three strategic archetypes: integrated dairy cooperatives with captive whey streams, independent demineralization specialists with validated ion-exchange protocols, and diversified nutrition platforms with backward integration into dairy processing. Competitive moves concentrate on long-term supply agreements with fixed mineral bands and M&A targeting regional ion-exchange capabilities.
Among European cooperative-based processors, FrieslandCampina and Arla Foods Ingredients exemplify the integrated archetype with upstream control over whey streams and downstream nutritional ingredient positioning. Valio represents the Nordic specialist tier with focused expertise in clinical-grade mineral specification. These three occupy positions where regulatory dossier depth and processing scale intersect, anchoring premium-tier procurement relationships with formula manufacturers requiring documented compliance across multiple jurisdictions.
| Leading Market Players |
|---|
| FrieslandCampina |
| Arla Foods Ingredients |
| Lactalis Ingredients |
| Valio |
| Dairygold Food Ingredients |
| Euroserum |
| Fonterra |
| Glanbia Nutritionals |
| Saputo Ingredients |
| Others |
Supply Flow & Price Mechanics
Membrane stack configuration advances in electrodialysis systems are compressing unit processing costs while simultaneously concentrating supply among ion-exchange capable processors serving infant formula channels. This technological transition rewards scale investments in Bavarian and Dutch dairy belts, where integrated facilities achieve mineral specification consistency that smaller regional operators cannot match.
Pricing Analysis
Capacity additions in the Netherlands and Germany are reshaping price floors for 70-90% demineralized grades as electrodialysis efficiency gains reduce energy costs per ton. Pricing stratifies across infant-grade certification tiers, pharmaceutical excipient standards, and commodity food applications, with EFSA novel food dossier requirements driving premium separation. Cost compression in standard 50-70% grades is intensifying because pea and rice protein substitutes erode whey share in sports nutrition. Food manufacturers represent the most price-sensitive buyers, while Swiss and Dutch infant formula producers lock long-term contracts with fixed mineral bands.
Supply Chain Analysis
Domestic-content mandates in China's Yangtze River Delta processing hubs are reshaping sourcing patterns for mineral-compliant whey derivatives. Supply concentrates in the Netherlands, Germany, and Denmark, where seasonal milk production fluctuations create raw material availability constraints for demineralization plants. Fresh whey streams, specialized ion-exchange resins, and electrodialysis membrane stacks anchor production dependencies. Single-source vulnerability runs through the Utrecht-Zwolle corridor, where specialized distributors consolidate lot-level mineral certification. Distribution runs through wholesale dairy ingredient networks serving Central European nutraceutical contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The demineralized whey powder ingredient market functions as a stable compounder anchored by regulatory tightening on infant formula mineral specifications that perpetually renew demand for certified low-ash grades.
For Market Incumbents: Deploy backward integration into captive whey streams to secure raw material availability against seasonal Dutch and Danish milk production fluctuations. Lock three-to-five year supply agreements with fixed mineral specification bands to transfer price volatility risk onto processors while building EFSA and FDA dual-certification dossiers that entrench competitive moats against emerging ion-exchange specialists. For New Entrants and Emerging Players: Enter via clinical nutrition applications requiring precisely controlled phosphorus and potassium loads, where 90% demineralized grades command specification premiums and incumbent capacity remains underdeveloped. Target German renal-specific formulation contract manufacturers sourcing exclusively from processors with validated amino acid scoring protocols, leveraging EU Green Deal bioeconomy incentives to fund integrated whey valorization facility capital deployment. For Investors and Strategic Acquirers: Valuations sit cheapest among independent demineralization specialists with validated ion-exchange protocols but underdeveloped regulatory dossier depth. The five-to-ten year viability window favors processors with dual-continent certification capabilities as WHO Codex Alimentarius harmonization efforts progress. Watch EFSA follow-on formula protein quality claim revisions as the inflection signal redirecting competitive advantage toward processors with documented amino acid scoring infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Swiss and Dutch formula producers lock fixed mineral bands to secure Chinese import compliance documentation. |
| Backward Integration | FrieslandCampina leverages integrated whey processing infrastructure across European dairy belts to secure consistent demineralized output. |
| Certification Investment | Dual-continent EFSA novel food and FDA GRAS dossiers extend commercialization timelines but entrench premium-tier positioning. |
| Capacity Expansion | Electrodialysis efficiency gains support continuous line upgrades reducing energy consumption per demineralization cycle. |
| Joint Venture | EU Green Deal bioeconomy incentives support circular dairy processing partnerships consolidating ion-exchange capabilities. |
Methodological Framework
Direct dialogue with infant formula procurement directors, dairy ingredient plant managers, ion-exchange technology specialists, and EFSA regulatory consultants grounded qualitative insights in operational reality. Secondary validation drew from EU REACH compliance filings, EFSA novel food register entries, FDA GRAS self-affirmation notices, and WHO Codex Alimentarius revision drafts. Bottom-up capacity assessments across Bavarian and Dutch processing facilities triangulated against top-down demand modeling from nutritional supplement and clinical nutrition channels.
Segment-level value and volume trajectories across the projection horizon reflect disaggregated modeling by demineralization rate tier, product format, application criticality, and end-user certification requirements. CAGRs were derived from installed capacity utilization rates, technology substitution curves for electrodialysis versus ion-exchange, and regulatory timeline assumptions for harmonized mineral specification standards. Forecast inputs incorporated seasonal whey availability patterns, resin replacement cost cycles, and plant protein substitution elasticity in sports nutrition applications.
Inputs from processor facility audits and distributor shipment records were available through the study window; gaps in real-time mineral specification transaction data introduce uncertainty bands around price trajectory assumptions. Forecasts reflect documented assumptions on regulatory harmonization pace and technology adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Blue Light Protection Ingredients Market
Ingredients
Microencapsulated Oil Market
Ingredients
Vegetable Fats Market
Ingredients
Agave Inulin Market
Ingredients
Global Pea Protein Ingredients Market
Ingredients
Hibiscus Extract Market
Ingredients
Salt Market
Ingredients
Cocoa Processing Market
Ingredients
Native Starch Market
Ingredients
Global Cocoa Products Market
Ingredients
Ingredients Market
Ingredients
Middle East and Africa Fermented Ingredients Market
Ingredients
Milk Mineral Concentrate Market
Ingredients
Asia-Pacific Yeast Market
Ingredients
Potato & Yam Derivatives Market
Ingredients
Heart Health Ingredients Market