
 Sugar Beet Pectin Market | 2026-2036
Sugar Beet Pectin Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar Beet Pectin Market Analytics
Market Dynamics
The capital-intensity divergence between extraction-scale specialists and formulation-centric distributors is redrawing competitive boundaries in sugar beet pectin supply. Cargill, Inc. leverages backward integration into beet sourcing to control raw material quality and cost consistency across North American operations. Herbstreith & Fox GmbH anchors European supply through decades of specialized pectin refining expertise centered in Germany. CP Kelco competes on biotechnology-driven process yields that lower unit production costs for high-volume food contracts.
Product and Application Structure
Sugar beet pectin is a complex polysaccharide extracted from beet cell walls, composed primarily of galacturonic acid units with varying degrees of methoxylation that determine its gelling behavior under calcium or acid-sugar conditions. Low-methoxyl pectin dominates pharmaceutical and nutraceutical applications where calcium-set gels enable controlled-release matrices without excessive sugar content. High-methoxyl pectin leads food and beverage volumes, particularly in acidified dairy and fruit preparations where rapid sugar-acid gelation drives throughput efficiency. Amidated variants command premium positioning in cosmetics, where modified rheology supports stable emulsions in skin-care formulations.
Regulatory Environment
EMA and EFSA frameworks govern pharmaceutical and food-grade pectin purity standards across Europe, while FDA regulations shape US market access through food additive and GRAS notification pathways. REACH compliance in the EU and emerging state-level chemical disclosure rules in California affect import qualification for non-European suppliers. Stakeholders must monitor evolving clean-label certification requirements and carbon-accounting rules that increasingly differentiate beet-derived against citrus-sourced pectin in procurement decisions.
Market Dynamics
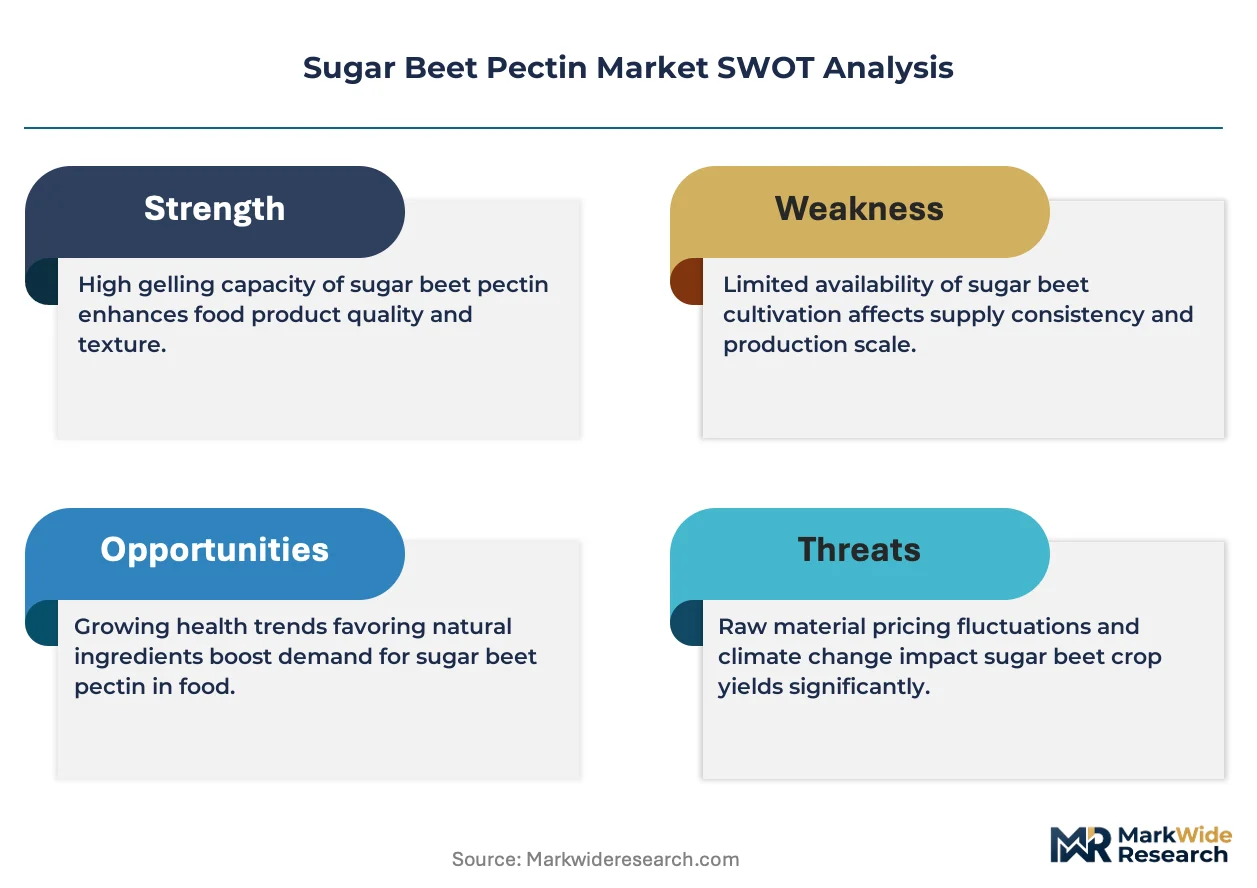
The EU Green Deal's bio-based materials mandate is compressing synthetic hydrocolloid demand while concentrating sugar beet pectin procurement around existing beet processing clusters in Germany, France, and Poland.
Growth Catalysts
- REACH compliance pressure:European formulators face substitution deadlines for petrochemical-derived thickeners, redirecting R&D budgets toward beet-derived alternatives with established safety dossiers.
- Clean-label dairy acceleration:Acidified yogurt and plant-based beverage manufacturers in Germany are reformulating with high-methoxyl pectin to eliminate modified starch from ingredient declarations.
- Beet processing infrastructure:Poland's sugar refineries are capturing pectin from molasses waste streams, lowering raw material costs for regional extractors against citrus-dependent competitors.
Market Restraints
- Raw material seasonality:Beet harvest concentration in autumn quarters creates nine-month inventory carry costs that citrus pectin producers avoid through year-round orange processing.
- Extraction yield variability:Cell wall polysaccharide content fluctuates with soil conditions and cultivar selection, complicating contract volume commitments to pharmaceutical buyers.
- Citrus pectin price anchoring:Established supply chains from Brazil and Mexico set benchmark pricing that beet-derived alternatives struggle to undercut at current scale.
Strategic Opportunities
- Amidated pectin cosmetics penetration:Modified rheology variants command premium positioning in French skin-care formulations where stable emulsions justify ingredient cost premiums.
- Carbon-accounting procurement rules:Emerging EU corporate sustainability reporting requirements differentiate beet-derived pectin with shorter transport distances against transatlantic citrus imports.
- Controlled-release pharmaceutical matrices:Low-methoxyl calcium-set gels enable tablet formulations without excessive sugar content, opening diabetic-friendly dosage form development.
Industry Challenges
- Specialized extraction engineering talent:Polysaccharide recovery process optimization requires expertise spanning food chemistry and membrane filtration that competes with broader biotech salary benchmarks.
- Pharmaceutical-grade certification timelines:EMA and FDA dual qualification for excipient-grade material extends validation cycles beyond typical working capital planning horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar Beet Pectin Market |
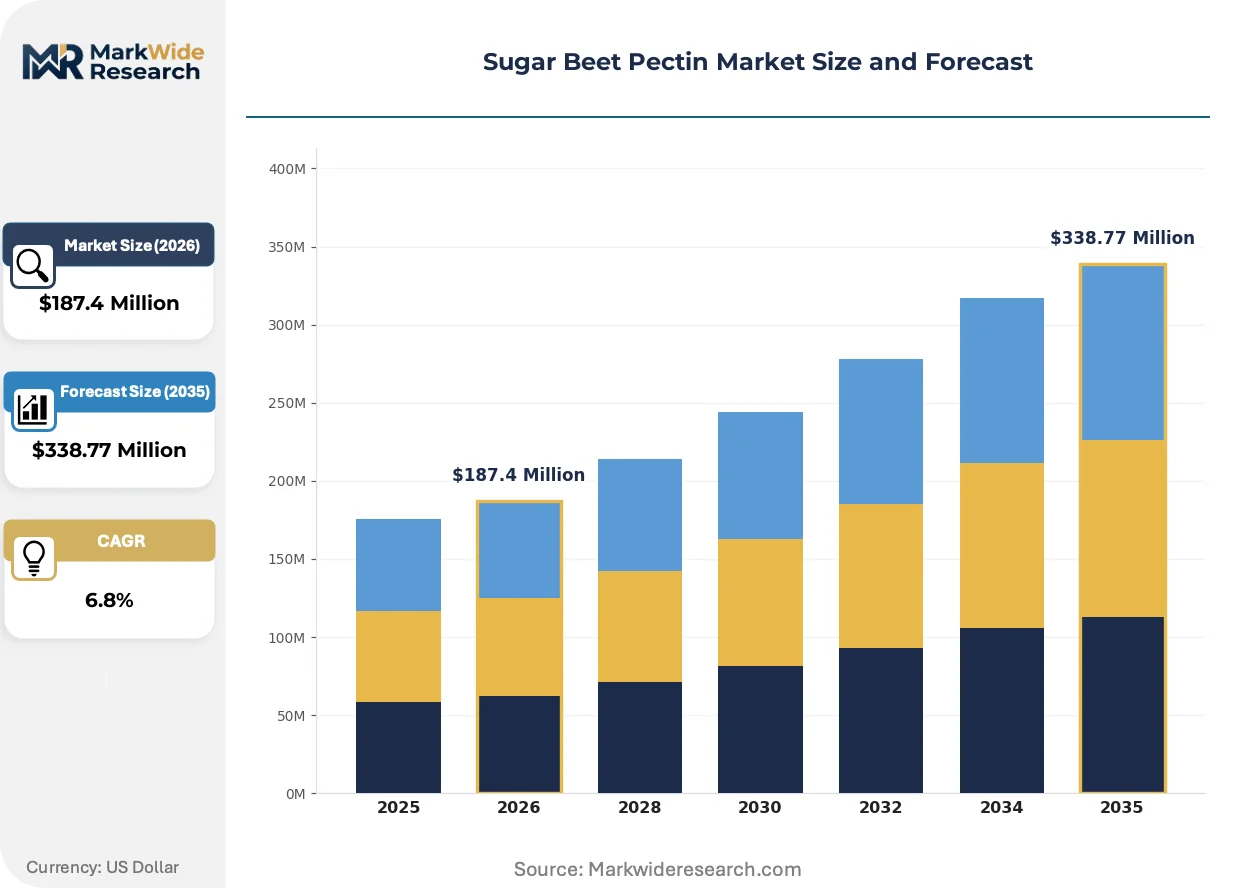
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Pectin, Low-Methoxyl Pectin, High-Methoxyl Pectin, Amidated Pectin Application: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Nutraceutical Providers Form: Powder, Granules, Liquid, Capsules |
| Companies Covered | DuPont, Cargill, Inc., Herbstreith & Fox GmbH, Naturex, Ingredion Incorporated, CP Kelco, Yantai Andre Pectin Co. Ltd., Koninklijke DSM N.V., International Flavors & Fragrances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar Beet Pectin Market Evolving Landscape
Enzymatic extraction protocols and precision methoxylation control are compressing production costs while expanding functional pectin variants beyond traditional food gelling applications.
Membrane filtration technology is miniaturizing extraction footprints. German equipment suppliers are deploying compact ceramic membrane systems that enable regional processors to achieve citrus-scale yields without centralized plant investments. This distributed processing model is compressing logistics costs for beet-growing cooperatives while maintaining pharmaceutical-grade purity standards.
EFSA's evolving clean-label guidance is tightening additive disclosure requirements. The framework pushes manufacturers toward single-ingredient stabilizers rather than blended hydrocolloid systems, directly benefiting sugar beet pectin's positioning as a recognizable plant-derived component. French and Dutch formulators are accelerating reformulation timelines to meet anticipated 2027 labeling standards.
Ingredient sourcing transparency is reshaping buyer-supplier relationships. Major European dairy processors now require batch-level carbon footprint documentation, favoring regional beet-derived supply over imported citrus alternatives. This verification burden is consolidating procurement around vertically integrated extractors with in-house sustainability accounting capabilities.
Sugar Beet Pectin Market Segmentation
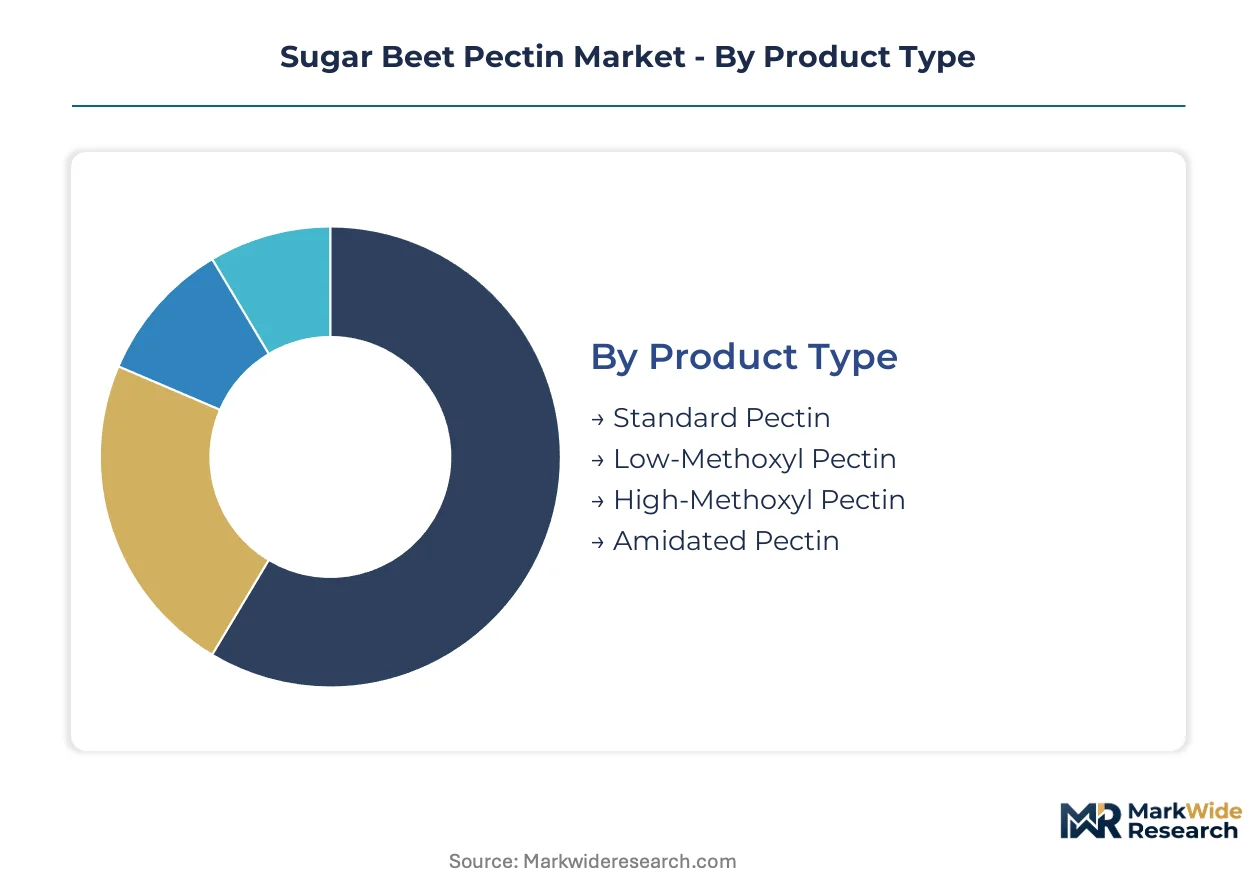
Sugar beet pectin's functional diversity creates distinct competitive arenas where substitution risk varies sharply by methoxylation chemistry and end-use specification. Manufacturers must align extraction investments with segment-specific purity requirements and formulation performance thresholds.
Product Type:
High-methoxyl grades face the most acute citrus pectin substitution pressure in commodity food applications, while specialized amidated and low-methoxyl variants defend position through technical differentiation.
- High-Methoxyl Pectin:Rapid sugar-acid gelation chemistry dominates acidified dairy and fruit preparation throughput in Germany. Polish sugar refineries extract this grade from molasses waste streams, achieving cost parity with Brazilian citrus imports for regional food manufacturers.
- Low-Methoxyl Pectin:Calcium-set gelation enables controlled-release pharmaceutical matrices without excessive sugar loading. EMA qualification timelines for excipient-grade material extend validation cycles, concentrating procurement among vertically integrated extractors with dedicated pharma facilities.
- Amidated Pectin:Modified rheology supports stable emulsions in French skin-care formulations where premium positioning justifies ingredient cost premiums.
- Standard Pectin:Unfractionated extraction output serves cost-sensitive industrial applications with lower functional specification requirements.
High-methoxyl pectin anchors the volume base while amidated pectin gains share at the steepest rate.
Application:
Cost tier separation between commodity food volumes and premium pharmaceutical margins dictates extraction scale economics and certification investment priorities.
- Food & Beverage:Acidified yogurt and plant-based beverage manufacturers in Germany and France are eliminating modified starch declarations through high-methoxyl pectin reformulation. Clean-label acceleration under EFSA guidance compresses blended hydrocolloid demand.
- Pharmaceuticals:Low-methoxyl calcium-set gels enable diabetic-friendly tablet formulations with controlled-release kinetics. Dual EMA-FDA excipient qualification requirements filter supplier participation to specialized refiners.
- Cosmetics:Amidated variants command premium positioning in French skin-care emulsions where stable rheology justifies ingredient cost premiums.
- Nutraceuticals:Functional fiber applications in dietary supplements leverage pectin's prebiotic properties with lower purity thresholds than pharmaceutical grades.
Food and beverage applications absorb the majority of extraction output, though pharmaceutical volumes carry margin premiums that justify dedicated production lines.
End User:
Customer type concentration around beet processing clusters in Germany, France, and Poland shapes regional procurement patterns and logistics optimization.
- Food Manufacturers:German dairy processors now require batch-level carbon footprint documentation, favoring regional beet-derived supply over transatlantic citrus alternatives.
- Pharmaceutical Firms:EMA and FDA dual qualification demands compress the qualified supplier base to extractors with dedicated pharma-grade facilities.
- Cosmetic Companies:French formulators drive amidated pectin demand through premium skin-care emulsion requirements.
- Nutraceutical Providers:Dietary supplement manufacturers source lower-specification grades with faster qualification timelines than pharmaceutical buyers.
Food manufacturers dominate procurement volumes, while pharmaceutical firms anchor the highest-margin contract segment.
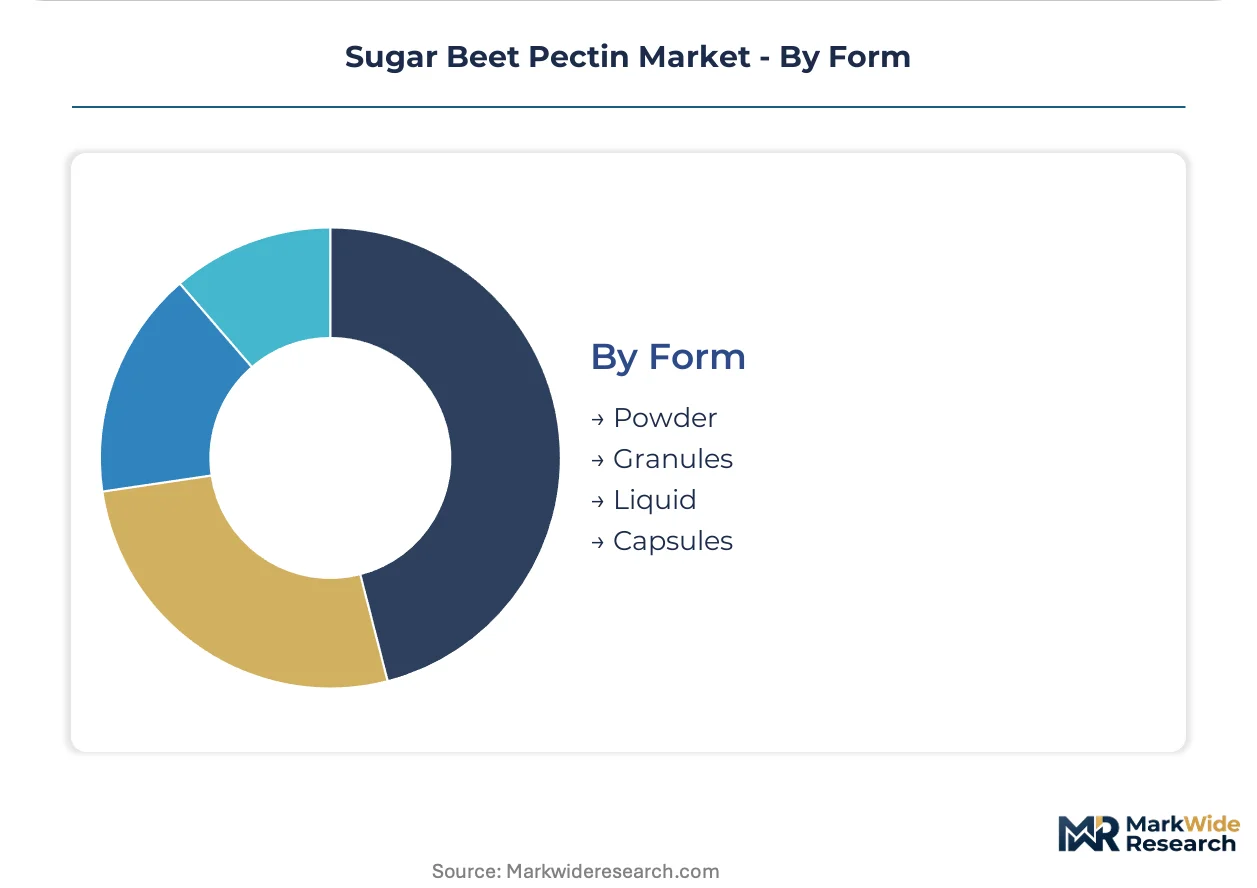
Form:
Supply concentration in powder processing reflects scale economies, while liquid and capsule differentiation serves niche formulation convenience requirements.
- Powder:Spray-dried output dominates bulk food and pharmaceutical procurement with extended shelf stability and standardised dissolution profiles.
- Liquid:Pre-hydrated concentrates reduce manufacturing step counts for cosmetics formulators with high-throughput emulsion production.
- Granules:Intermediate flow properties serve intermediate processing stages in regional extraction facilities without full spray-drying capability.
- Capsules:Pre-metered unit dosing addresses nutraceutical and specialized pharmaceutical convenience requirements with premium positioning.
Powder form commands the production base, though liquid concentrates are expanding most quickly in cosmetics applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical buyers in Germany accept premium pricing for certified grades, while Polish food manufacturers drive hard bargains on commodity volumes. This demand-elasticity contrast shapes regional procurement patterns across Europe's beet processing belt.
Germany
Acidified dairy reformulation dominates pectin consumption as manufacturers eliminate modified starch declarations. EFSA clean-label guidance accelerates high-methoxyl adoption in yogurt and plant-based beverages. The Baden-Württemberg and Lower Saxony clusters host specialized refiners serving pharmaceutical-grade contracts.
France
Premium cosmetics applications command amidated pectin volumes for stable skin-care emulsions. REACH compliance deadlines pressure petrochemical thickener substitution in personal care formulations. The Île-de-France region concentrates formulation R&D, while Hauts-de-France sugar refineries capture pectin from beet processing waste streams.
Poland
Sugar refineries extract pectin from molasses waste, achieving cost parity with Brazilian citrus imports for regional food manufacturers. EU Green Deal bio-based mandates redirect procurement budgets toward domestic beet-derived alternatives. The Greater Poland Voivodeship anchors extraction capacity expansion.
United States
FDA GRAS notification pathways shape market access for beet-derived hydrocolloids in acidified dairy and beverages. Clean-label momentum in yogurt reformulation mirrors European patterns with domestic sourcing preferences. Midwest beet-growing regions support backward-integrated processors controlling raw material quality.
China
SAMR food additive regulations govern import qualification for pharmaceutical and food-grade pectin. Domestic beet processing infrastructure remains limited, creating import dependence for specialized grades. Shandong Province hosts regional distributors serving coastal food manufacturers.
Sugar Beet Pectin Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics. Specialized German refiners anchor premium pharmaceutical-grade supply through decades of process expertise. Scale-driven North American agribusinesses leverage captive beet sourcing for commodity food volumes. Biotechnology-focused players compete on extraction yield optimization. Dominant competitive moves include backward integration into raw material control and regional capacity expansion near beet processing clusters.
Among established European specialists, Herbstreith & Fox GmbH exemplifies the premium-tier refiner archetype with concentrated expertise in pharmaceutical-grade certification. Cargill, Inc. occupies a position representing scale-driven, backward-integrated supply chain control across North American operations. CP Kelco sits within the biotechnology-optimization segment, competing on process yield improvements for high-volume contracts.
| Leading Market Players |
|---|
| DuPont |
| Cargill, Inc. |
| Herbstreith & Fox GmbH |
| Naturex |
| Ingredion Incorporated |
| CP Kelco |
| Yantai Andre Pectin Co. Ltd. |
| Koninklijke DSM N.V. |
| International Flavors & Fragrances |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between German dairy processors and beet processing cooperatives lock in nine-month inventory coverage against autumn harvest concentration, binding price visibility to raw material access across the EU Green Deal compliance window. Pharmaceutical buyers in Baden-Württemberg accept premium positioning for EMA-certified grades, while Polish food manufacturers leverage molasses waste stream pectin to compress regional supply costs.
Pricing Analysis
After-sales technical service and formulation support contracts drive lifetime value for specialized amidated pectin in French cosmetics applications. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade certifications anchors differentiation, with EMA-FDA dual qualification commanding substantial premiums over single-certified alternatives. Cost compression in high-methoxyl food volumes intensifies as Polish refineries achieve parity with Brazilian citrus imports. Food manufacturers exhibit acute price sensitivity, while pharmaceutical firms prioritize supply security over unit cost.
Supply Chain Analysis
Nine-month inventory carry requirements from autumn beet harvest concentration create working capital burdens that citrus competitors avoid through year-round orange processing. Supply concentrates in Germany, France, and Poland where existing sugar refineries capture pectin from molasses waste streams. Extraction depends on galacturonic acid feedstock from beet cell walls, ceramic membrane filtration equipment, and specialized polysaccharide recovery chemicals. Single-source vulnerability runs through German pharmaceutical-grade refiners with EMA-qualification capabilities. Distribution runs through regional distributors serving food manufacturers and direct contracts for pharmaceutical buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's bio-based materials mandate constitutes a structural inflection, compressing synthetic hydrocolloid demand while concentrating procurement around beet processing clusters with established carbon-accounting documentation capabilities.
For Market Incumbents: Fortify backward integration into captive beet sourcing to control raw material quality consistency against citrus pectin price anchoring. Expand ceramic membrane filtration capacity in Greater Poland Voivodeship to capture regional food volume growth while defending pharmaceutical-grade margins through dedicated EMA-qualified facilities in Baden-Württemberg. For New Entrants and Emerging Players: Lead with enzymatic extraction yield optimization to compete on unit economics against established citrus supply chains. Target nutraceutical prebiotic fiber applications where lower purity thresholds accelerate qualification timelines compared to pharmaceutical grades. Emphasize batch-level carbon footprint transparency as the go-to-market angle for EU dairy processor procurement mandates. For Investors and Strategic Acquirers: Specialized German refiners with decades of pharmaceutical-grade process expertise represent the most defensible acquisition archetype within a five-to-ten year viability window. Monitor EFSA clean-label guidance implementation as the signal to watch for reformulation acceleration timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Beet Sourcing | Cargill's captive supply model in North American Midwest regions ensures raw material quality control. |
| Pharmaceutical-Grade Certification Investment | EMA-FDA dual qualification filters supplier participation to specialized refiners with dedicated facilities. |
| Enzymatic Extraction Yield Optimization | CP Kelco's biotechnology-driven process improvements lower unit production costs for high-volume food contracts. |
| Regional Capacity Expansion | Polish sugar refineries capture pectin from molasses waste streams, achieving cost parity with citrus imports. |
| Carbon-Accounting Documentation Capability | German dairy processors now require batch-level verification, favoring regional beet-derived supply chains. |
Research Methodology
A standing panel of extraction plant managers, dairy processor procurement leads, pharmaceutical formulation scientists, and cosmetic R&D directors provided ongoing calibration across primary interview rounds. Secondary validation drew from EMA excipient qualification databases, EFSA additive guidance documents, EU customs trade data, and SEC filings of publicly traded agribusinesses. Bottom-up volume modeling triangulated against top-down market sizing from trade association statistics.
Consistency checks against external benchmarks validated projections across the analysis window. Segmentation dimensions modeled include methoxylation chemistry grade, end-use application, purity certification tier, and regional production hub. CAGRs were derived from segment-level volume trajectories weighted by price realization patterns, incorporating beet harvest yield variability and EMA qualification timeline assumptions as industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or significant citrus pectin supply disruption would require recalibration. Forecasts reflect documented assumptions regarding clean-label reformulation pace and pharmaceutical excipient demand growth. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Acetylated Starch Market
Ingredients
Meat Tenderizer Powder Market
Ingredients
Oak Extract Market
Ingredients
Corn Starch Market
Ingredients
North America Gums Market
Ingredients
RTD/High Strength Premixes Market
Ingredients
France Sodium Reduction Ingredients Market
Ingredients
Spain Fermentation Ingredients Market
Ingredients
Kairomones Market
Ingredients
Commercial Amino Acids Market
Ingredients
Textured Wheat Protein Market
Ingredients
Homecare Ingredients Market
Ingredients
Maracuja Oil Market
Ingredients
South America Fermented Ingredients Market
Ingredients
Halal Ingredients Market
Ingredients
Corn Oil Market