
 North America Whey Protein Ingredients Market | 2026-2036
North America Whey Protein Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
North America Whey Protein Ingredients Market Analytics
A capital-intensity divergence between integrated dairy processors and ingredient specialists is rotating competitive dynamics across the North America whey protein ingredients landscape. Glanbia plc leverages its vertically integrated supply chain from milk collection to finished isolate production. Hilmar Cheese Company anchors its position through captive whey streams generated at large-scale cheese manufacturing facilities in California.
Whey protein ingredients comprise protein fractions isolated from liquid whey, a cheese manufacturing byproduct, typically processed through ultrafiltration, ion exchange, or enzymatic hydrolysis to achieve protein concentrations ranging from 34% to 90% or higher. These ingredients serve primarily as functional nutrition inputs formulated into consumer products requiring specific amino acid profiles, emulsification properties, or rapid absorption characteristics. Isolate and hydrolysate categories command premium positioning due to higher protein purity and enhanced bioavailability, while concentrate maintains volume leadership across food and beverage applications where cost sensitivity shapes procurement decisions. Sports nutrition and nutritional supplements represent the most dynamic application channels, with protein bars and ready-to-drink formats experiencing accelerated formulation activity.
FDA food additive regulations and USDA organic certification standards govern product claims, manufacturing practices, and interstate commerce across the United States, while Health Canada and CFIA requirements apply north of the border. These frameworks dictate label accuracy, protein content verification methods, and permissible health claims, directly influencing R&D investment priorities and facility qualification costs. Stakeholders must monitor evolving clean-label expectations and potential shifts in dairy-derived protein classification under pending regulatory reviews.
Market Dynamics
Cheese production geography in the United States Midwest and California directly controls whey stream availability, concentrating supply-side leverage among integrated dairy processors with captive raw material access.
Growth Catalysts
- USDA Organic Certification:Premium positioning for certified whey isolates commands shelf-space allocation in natural retail channels across the United States and Canada.
- Sports Nutrition Formulation:Ready-to-drink protein beverages and functional bars absorb higher-value hydrolysate and isolate grades at accelerated rates.
- Midwest Dairy Belt Concentration:Wisconsin and New York cheese manufacturing generates abundant liquid whey feedstock for regional processing infrastructure.
Market Restraints
- Input Cost Volatility:Fluid milk pricing fluctuations and energy costs for ultrafiltration and spray-drying compress margin structures for non-integrated processors.
- Supply Concentration Risk:California and Wisconsin dominate liquid whey generation, creating geographic single-point vulnerability for ingredient specialists without multi-source contracts.
- Regulatory Friction:FDA protein content verification methods and label claim substantiation requirements extend product development timelines and qualification costs.
Strategic Opportunities
- Canada Expansion:Underpenetrated sports nutrition and active aging segments in Ontario and British Columbia offer white-space for isolate and hydrolysate positioning.
- Clinical Nutrition Applications:Medical foods and enteral nutrition formulations present emerging demand for high-purity whey protein with documented amino acid profiles.
- Clean-Label Distribution:Direct-to-consumer and specialty pharmacy channels reward transparent sourcing and minimal processing claims.
Industry Challenges
- Specialized Talent Scarcity:Food protein chemistry and membrane process engineering expertise concentrates at established dairy research institutions, constraining R&D scaling for mid-tier entrants.
- Organic Certification Timelines:USDA National Organic Program transition periods and third-party audit cycles delay market entry for new certified product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Whey Protein Ingredients Market |
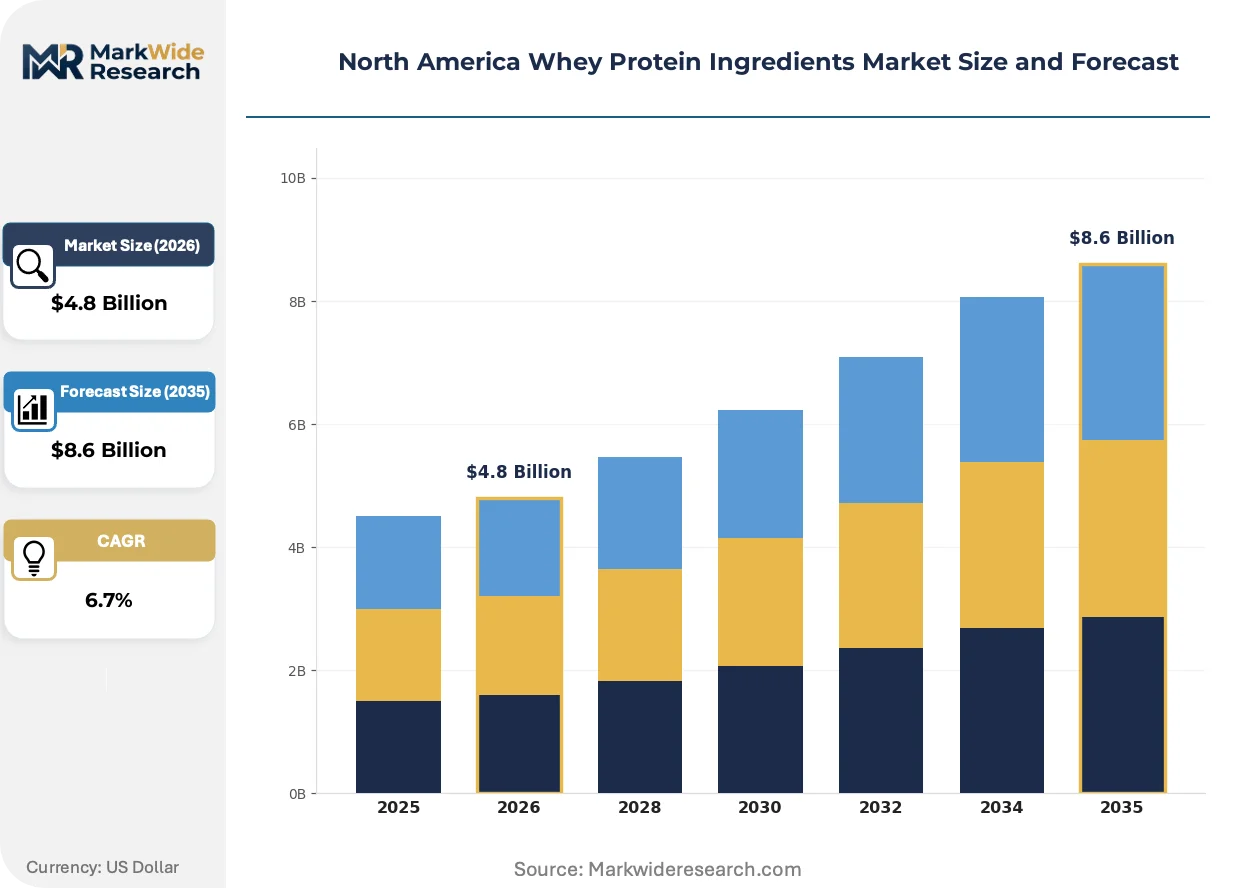
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Isolate, Hydrolysate, Blends Application: Food & Beverage, Nutritional Supplements, Sports Nutrition, Animal Feed Form: Powder, Liquid, Protein Bars, Ready-to-Drink End User: Health Conscious Consumers, Athletes, Bodybuilders, Retailers |
| Companies Covered | Glanbia plc, Fonterra Co-operative Group, Arla Foods, Hilmar Cheese Company, Agropur Dairy Cooperative, Leprino Foods Company, FrieslandCampina Ingredients, AMCO Proteins, Darigold, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Whey Protein Ingredients Market Evolving Landscape
Membrane filtration technology and precision fermentation alternatives are compressing traditional processing economics while regulatory clarity on novel protein sources reshapes competitive positioning across North American supply chains.
Cross-flow microfiltration systems with ceramic membrane arrays are miniaturizing plant footprints and energy intensity for whey protein isolate production. Mid-sized dairy cooperatives in Wisconsin and Minnesota are adopting these modular units to capture value from whey streams previously sold to commodity processors. The technology is miniaturizing capital barriers to isolate-grade production, enabling regional players to compete on purity metrics without billion-dollar facility investments.
FDA guidance on plant-based dairy alternatives and updated standards of identity for milk-derived products are tightening label claim boundaries for whey protein positioning against emerging substitutes. Sports nutrition brands must now substantiate comparative protein quality assertions through PDCAAS or DIAAS scoring methodologies. United States formulators are responding by emphasizing leucine content and rapid absorption kinetics in technical marketing rather than generic superiority claims.
Long-term supply agreements with cheese manufacturers are displacing spot-market whey procurement for major ingredient buyers. Concentrated ownership of fluid milk processing in the Upper Midwest and California Central Valley has compressed spot availability, forcing nutrition brands to secure multi-year offtake contracts. This contractual pivot is most visible among United States protein bar and RTD manufacturers seeking supply certainty for isolate and hydrolysate grades.
North America Whey Protein Ingredients Market Segmentation
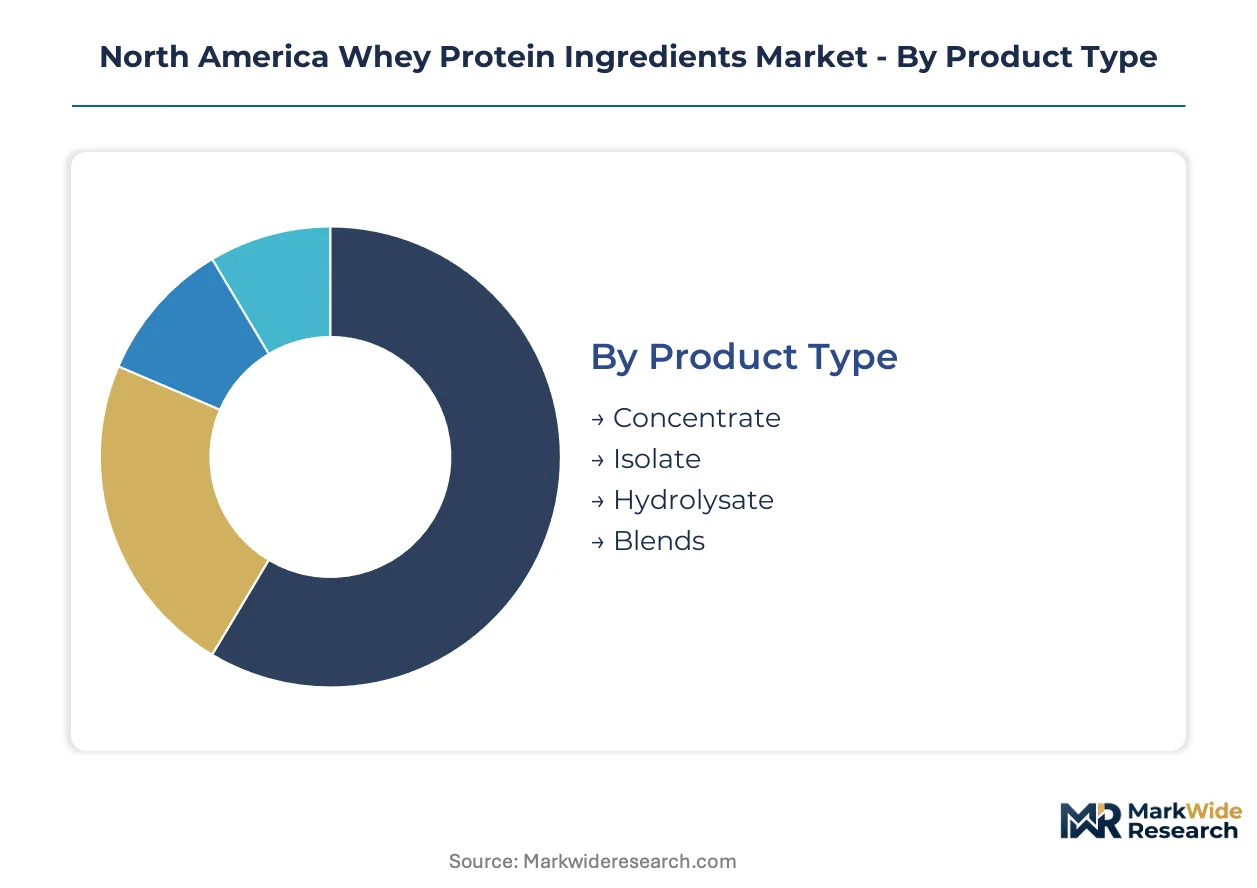
Whey protein ingredient procurement patterns diverge sharply across product purity grades, end-use applications, and delivery formats. Manufacturers optimize formulation strategies by matching protein concentration levels to specific functional requirements and consumer absorption expectations.
Product Type:
Margin pools concentrate at the high-purity end of the spectrum, where processing complexity creates defendable pricing power.
- Isolate:Protein fractions refined to 90% or higher concentration through ion exchange or cross-flow microfiltration. Sports nutrition brands in the United States absorb premium isolate volumes for post-workout formulations where rapid leucine absorption drives purchasing decisions.
- Hydrolysate:Enzymatically pre-digested proteins with reduced molecular weight for accelerated gastric emptying. Clinical nutrition applications in Canadian medical food channels are expanding offtake for hydrolysate grades with documented amino acid bioavailability profiles.
- Concentrate:Standard 34-80% protein fractions retaining lactose and lipid components. Baked goods and dairy-based beverages in the United States Midwest represent volume anchors for concentrate procurement.
- Blends:Custom-formulated combinations of concentrate, isolate, and hydrolysate targeting specific cost-performance ratios. Private-label sports nutrition manufacturers favor blended inputs for mid-tier protein bar positioning.
The dominant share belongs to Concentrate, while Isolate is closing the gap fastest.
Application:
Application-driven demand splits between performance-oriented consumption and functional food integration.
- Sports Nutrition:Protein powders, RTD beverages, and recovery formulations targeting gym enthusiasts and endurance athletes. United States CrossFit and boutique fitness studio partnerships are accelerating isolate and hydrolysate absorption rates.
- Nutritional Supplements:Standalone protein products and multivitamin-protein combinations for general wellness positioning. Canadian pharmacy and natural health product channels are expanding shelf space for organic-certified whey isolates.
- Food & Beverage:Protein fortification of yogurt, ice cream, bakery items, and savory snacks. Clean-label reformulations in the United States are displacing soy and pea protein with dairy-derived alternatives in premium positioned items.
- Animal Feed:Calf milk replacers and pet nutrition formulations utilizing whey permeate and lower-grade concentrates. Regional dairy cooperatives in Wisconsin monetize secondary streams through captive feed operations.
Sports Nutrition commands the largest revenue pool, though Nutritional Supplements is expanding most quickly through direct-to-consumer subscription models.
Form:
Format selection directly determines manufacturing partnerships and distribution infrastructure requirements.
- Powder:Bulk dry ingredients packaged for consumer reconstitution or industrial formulation. United States Amazon and specialty retail fulfillment centers handle substantial powder volume through automated picking systems.
- Ready-to-Drink:Pre-mixed beverages in shelf-stable or refrigerated formats. Cold-chain distribution investments by Canadian dairy processors are enabling RTD expansion into convenience store channels.
- Protein Bars:Extruded or cold-pressed solid formats with whey protein as binding or enrichment component. United States contract manufacturers in Utah and Colorado specialize in high-protein bar co-packing.
- Liquid:Unfinished protein solutions for downstream processing or foodservice dispensing. Regional dairy processors in New York supply liquid concentrate to bakery and confectionery manufacturers.
Powder retains the volume leadership position, while Ready-to-Drink shows the steepest expansion trajectory through fitness channel partnerships.
End User:
User archetypes segment by performance expectations, purchase frequency, and channel access patterns.
- Athletes:Competitive and recreational performers with protein intake protocols tied to training cycles. United States collegiate athletic programs and professional sports franchises drive institutional isolate procurement.
- Bodybuilders:Physique-focused consumers prioritizing leucine content and absorption speed metrics. Canadian independent supplement retailers cultivate loyalty through personalized hydrolysate recommendations.
- Health Conscious Consumers:General wellness seekers integrating protein into balanced nutrition approaches. United States natural and organic grocery channels capture this segment through transparent sourcing claims.
- Retailers:Private-label buyers and category managers optimizing margin and turnover metrics. Mass merchandisers in the United States Midwest negotiate long-term concentrate supply agreements for house brand positioning.
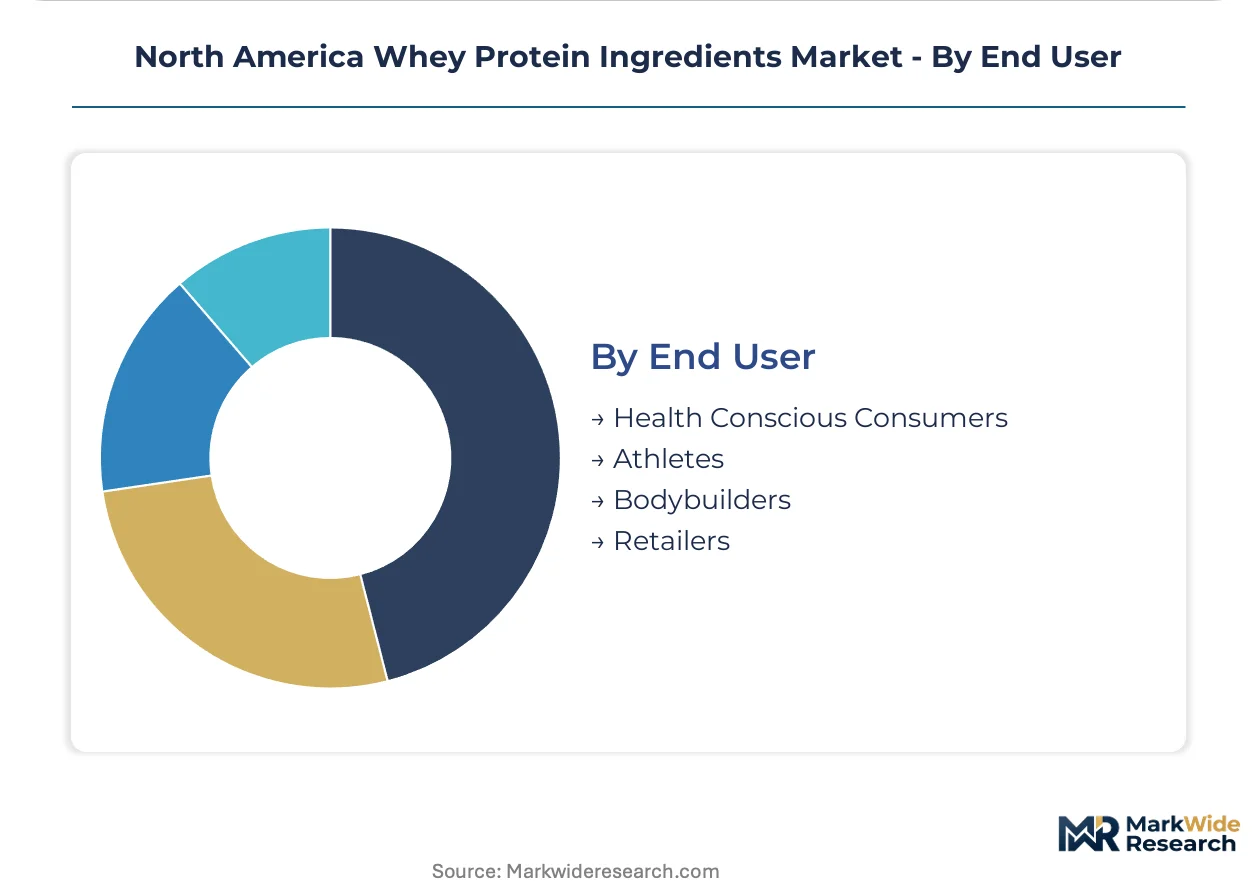
Health Conscious Consumers represent the broadest addressable base, while Athletes deliver the highest per-capita spending intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across North American geographies, with United States Midwest buyers exhibiting the highest cost sensitivity while Canadian coastal markets absorb premium isolates with minimal volume resistance.
United States
FDA protein content verification methods and USDA National Organic Program standards govern interstate commerce and label claims. Wisconsin and New York cheese manufacturing generates abundant liquid whey feedstock, concentrating processing infrastructure around regional dairy cooperatives.
Canada
Health Canada and CFIA requirements apply to protein supplement labeling and natural health product licensing. Ontario and British Columbia sports nutrition channels show underpenetrated isolate demand, creating expansion opportunities for certified organic positioning.
California
State-level agricultural regulations and water-use restrictions shape dairy processing economics in the Central Valley. Hilmar Cheese Company anchors large-scale whey stream capture, converting captive cheese byproduct into high-purity ingredient outputs.
Midwest Dairy Belt
USDA organic certification timelines and third-party audit cycles delay market entry for new certified product lines. Regional dairy cooperatives in Minnesota deploy cross-flow microfiltration systems to capture value from whey streams previously sold to commodity processors.
Mexico
Federal Commission for Protection against Sanitary Risk (COFEPRIS) regulations govern protein supplement importation and domestic manufacturing standards. Northern border states concentrate sports nutrition distribution infrastructure serving cross-border fitness retail channels.
North America Whey Protein Ingredients Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America whey protein ingredients landscape. Integrated dairy processors with captive whey streams command supply-side leverage, while ingredient specialists compete on purity metrics and formulation services. Two dominant strategic archetypes emerge: vertically integrated cheese manufacturers monetizing byproduct streams, and independent processors sourcing multi-origin whey through long-term contracts. Capacity expansion and strategic partnerships represent the primary competitive moves, with mid-sized cooperatives adopting modular membrane systems to bridge the scale gap.
Among integrated dairy processors, Glanbia plc and Hilmar Cheese Company occupy positions exemplifying contrasting geographic strategies. Glanbia represents the multinational archetype with vertically integrated supply chains spanning milk collection through finished isolate production. Hilmar Cheese Company anchors the regional specialist model, leveraging California Central Valley cheese manufacturing density for captive raw material access. Fonterra Co-operative Group exemplifies the cooperative ownership structure, representing farmer-aligned governance in global dairy ingredient trade.
| Leading Market Players |
|---|
| Glanbia plc |
| Fonterra Co-operative Group |
| Arla Foods |
| Hilmar Cheese Company |
| Agropur Dairy Cooperative |
| Leprino Foods Company |
| FrieslandCampina Ingredients |
| AMCO Proteins |
| Darigold |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements with cheese manufacturers lock in both whey stream access and forward price visibility for North American protein ingredient buyers, insulating integrated processors from spot-market volatility while compressing margin flexibility for non-integrated specialists sourcing across California and Wisconsin dairy belts.
Pricing Analysis
After-sales service revenue through technical formulation support and custom blending services drives lifetime value beyond commodity protein sales. Three-tier pricing structure across premium, standard, and economy levels stratifies by protein purity grade and USDA organic certification status, with isolate grades commanding substantial premiums over concentrate fractions. Cost compression in standard-grade concentrate is intensifying because fluid milk price volatility and energy-intensive ultrafiltration operations squeeze non-integrated processors. Mass-market food and beverage manufacturers exhibit highest price sensitivity, while clinical nutrition formulators absorb premium hydrolysate pricing with minimal volume resistance.
Supply Chain Analysis
Inventory lead times for high-purity isolate and hydrolysate grades extend substantially beyond concentrate availability due to complex membrane filtration and enzymatic processing requirements. Supply concentrates in the United States Midwest dairy belt and California Central Valley, with Wisconsin and New York cheese manufacturing generating abundant liquid whey feedstock. Raw material dependencies center on fluid milk supply, ceramic membrane arrays for microfiltration systems, and enzymatic hydrolysis reagents. Single-source vulnerability from geographic concentration of cheese production creates structural risk for ingredient specialists lacking multi-origin contracts. Distribution runs through bulk ingredient channels serving contract manufacturers, direct-to-consumer fulfillment centers, and clinical nutrition distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-based protein alternatives and precision fermentation technologies threaten to displace dairy-derived ingredients in sports nutrition applications, forcing incumbents to defend substitution risk through differentiated positioning and supply security investments.
For Market Incumbents: Secure captive whey stream access through equity stakes or exclusive offtake arrangements with cheese manufacturers in Wisconsin and California, eliminating spot-market exposure. Deepen backward integration into fluid milk collection networks to control input cost volatility, while investing in cross-flow microfiltration capacity to maintain purity leadership against emerging precision fermentation substitutes.
For New Entrants and Emerging Players: USDA National Organic Program certification fast-track programs in the Upper Midwest enable rapid market entry for isolate-grade positioning in underpenetrated Canadian sports nutrition channels. Target Ontario and British Columbia white-space through direct-to-consumer subscription models emphasizing transparent sourcing claims, leveraging modular membrane systems to minimize capital barriers against established billion-dollar facilities.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-sized dairy cooperatives with installed membrane filtration infrastructure and established organic certification pipelines, offering acquisition platforms with immediate revenue scale and regional brand equity. Monitor FDA guidance evolution on dairy-derived protein classification standards as the critical inflection signal for long-term viability assessment across the analysis window.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluid Milk Supply | Captive raw material access eliminates spot-market whey price volatility for isolate producers. |
| USDA Organic Certification Investment | Premium shelf-space allocation in natural retail channels commands margin expansion across United States and Canada. |
| Cross-Flow Microfiltration Capacity Addition | Regional cooperatives in Minnesota and Wisconsin bridge scale gaps against billion-dollar integrated processors. |
| Long-Term Supply Agreement with Cheese Manufacturers | Multi-year offtake contracts insulate protein bar and RTD manufacturers from supply concentration risk. |
| Direct-to-Consumer Channel Development | Specialty pharmacy and subscription platforms reward transparent sourcing with customer lifetime value expansion. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cheese manufacturing executives, whey processing plant managers, sports nutrition brand formulators, and membrane filtration equipment specialists. Secondary validation drew from FDA food additive filings, USDA National Organic Program certification databases, Health Canada natural health product licensing records, and SEC 10-K disclosures from publicly traded dairy processors. Bottom-up volume estimates from regional whey stream generation data were triangulated against top-down protein ingredient consumption surveys across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning protein purity grade, end-use application channel, delivery format, and geographic regulatory cluster. CAGRs were derived through regression analysis of historical whey stream availability against protein ingredient price formation, incorporating fluid milk pricing volatility indices and energy cost trajectories for spray-drying operations as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained cheese production levels in the Midwest dairy belt and California; material deviation in dairy herd sizes or water-use restrictions would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
South America Insoluble Dietary Fibers Market
Ingredients
Coconut Cream Powder Market
Ingredients
Freeze-Dried Pea Isolates Market
Ingredients
Ben Oil Market
Ingredients
Omega Ingredients Market
Ingredients
Canola Meal Market
Ingredients
Citrus Pectin Market
Ingredients
North America Corn Starch Market
Ingredients
Mediterranean Women’s Cycle Support Ingredient Systems Market
Ingredients
Egg Replacement Ingredients Market
Ingredients
Red Orange Anthocyanin Extract Ingredients Market
Ingredients
Cocoa Derivatives Market
Ingredients
Soy Hydrolysates Market
Ingredients
Canola Protein Market
Ingredients
Plant Extracts Market
Ingredients
Global Dry Yeast Market