
 Rendered Products Market | 2026-2036
Rendered Products Market Size, Share, and Industry Trends Forecast 2026-2036
Rendered Products Market Intelligence
Premium-grade tallow specifications are reorganizing procurement patterns across the rendered products value chain. Tyson Foods Inc. leverages vertical integration from slaughterhouse to finished fat to secure supply continuity for biodiesel off-takers. Darling Ingredients Inc. anchors North American rendering infrastructure through large-scale collection and processing networks. JBS S.A. competes on geographic breadth, operating rendering assets across multiple protein-producing regions.
Rendered products derive from the thermal and mechanical processing of animal by-products including fat trimmings, bones, blood, and feathers, yielding specified tallow with free fatty acid content below 15 percent for industrial acceptance. These materials serve as essential inputs for animal nutrition, oleochemical manufacturing, and renewable fuel production. Tallow and meat and bone meal dominate volume flows, with tallow commanding stronger margins through biodiesel and oleochemical channels while feather meal posts faster growth rates driven by aquaculture feed formulation trends. Fish meal occupies a premium niche constrained by raw material scarcity and competing omega-3 extraction demands.
The EPA oversees rendering facility emissions and wastewater discharge under Clean Water Act provisions, while FDA regulations govern the safety of animal feed ingredients including specified risk materials. Biodiesel tax credit structures through the IRA influence tallow demand allocation between fuel and chemical applications. Feed manufacturers and industrial chemical producers must monitor regulatory shifts in feed safety classification and renewable fuel certification standards to align procurement and product positioning decisions.
Market Dynamics
Integrated meat processors are consolidating rendering capacity within slaughterhouse complexes, compressing merchant rendering margins while securing captive supply chains for tallow and protein meal outputs. This backward integration into by-product processing is redrawing competitive boundaries between independent renderers and protein packers.
Growth Catalysts
- IRA Biodiesel Tax Credits:The Inflation Reduction Act's renewable fuel incentives are reallocating tallow flows from oleochemical channels toward renewable diesel production, tightening industrial fat availability.
- Aquaculture Feed Formulation:Fish meal scarcity is accelerating rendered feather meal adoption in shrimp and salmon diets across Southeast Asian and Latin American farming operations.
- China:Centralized livestock processing mandates under the country's agricultural modernization program are expanding industrial rendering infrastructure in Henan and Sichuan provinces.
Market Restraints
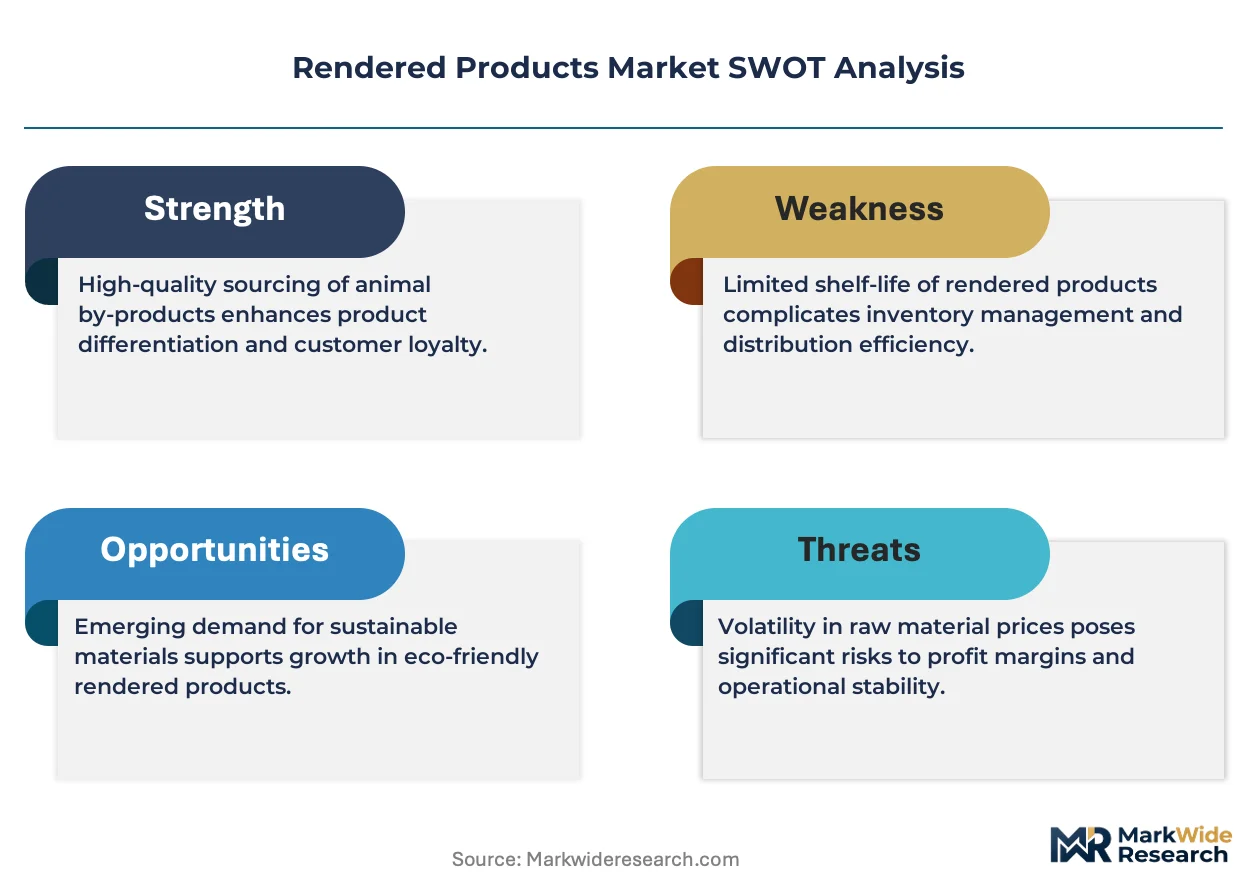
- Raw Material Cost Volatility:Cattle slaughter rates fluctuate with drought cycles and herd liquidation phases, creating unpredictable fat and bone meal input costs for independent processors.
- Supply Concentration Risk:Brazil's protein processing sector concentrates rendering output among three integrated packers, limiting merchant access to specified risk material streams.
- Technical Limitation:Feather meal processing requires hydrolysis temperatures above 140°C to achieve digestible amino acid profiles, constraining small-scale facility economics.
Strategic Opportunities
- India:FSSAI feed safety regulations are formalizing animal by-product processing standards, opening organized sector investment in currently informal rendering operations.
- Regulatory Tailwind:The EU Green Deal's circular economy action plan is mandating food waste valorization, accelerating rendering infrastructure grants in France and Germany.
- Technology Convergence:Anaerobic digestion and rendering process integration is enabling biogas co-production from wastewater streams, improving facility energy economics.
Industry Challenges
- Skilled Operator Shortage:Pressure vessel certification and HACCP system management require specialized technicians that rural rendering facilities struggle to recruit and retain.
- Capex Intensity:Continuous cooker replacement cycles and emissions control upgrades demand capital allocations that independent renderers cannot access at competitive rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rendered Products Market |
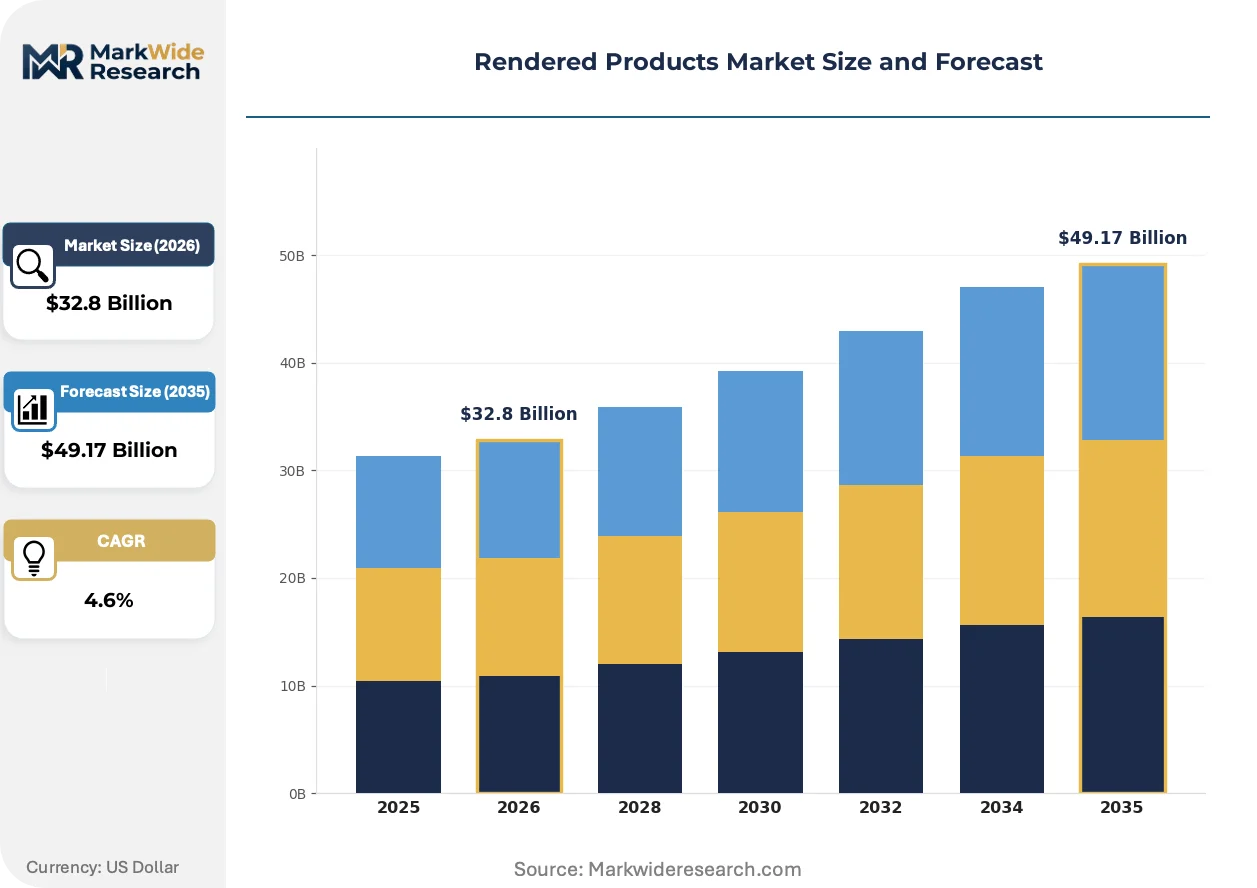
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $49.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tallow, Bone Meal, Feather Meal, Fish Meal, Blood Meal, Meat and Bone Meal Application: Animal Feed, Biodiesel Production, Personal Care, Soap Making, Fertilizer End User: Livestock Farmers, Feed Manufacturers, Industrial Chemical Producers, Cosmetic Companies Distribution Channel: Direct Sales, Distributors, Online Platforms, Wholesale Suppliers |
| Companies Covered | Cargill, Maple Leaf Foods, Tyson Foods Inc., Valley Proteins Inc., Sanimax, JBS S.A., Smithfield Foods, Seaboard Corporation, Darling Ingredients Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rendered Products Market Strategic Shifts & Innovations
Processing technology evolution and regulatory reclassification are compressing traditional rendering margins while opening adjacent revenue streams in bioenergy and specialty feed ingredients. Competitive positioning now hinges on regulatory compliance speed and co-product extraction efficiency.
Continuous dry rendering systems with integrated heat recovery are fragmenting the installed base of batch cookers across North American facilities. Poultry processors with high-volume feather and offal streams are adopting these systems fastest. The technology shift is fragmenting equipment vendor relationships and compressing maintenance service contract values as integrated packers bring specialized engineering in-house.
EPA effluent limitation guidelines under the Clean Water Act are tightening phosphorus discharge standards for rendering facility wastewater. Plants in Nebraska and Iowa face capital-intensive biological nutrient removal upgrades. The regulation is compressing independent renderer margins most severely in watersheds with total maximum daily load designations.
Buyer concentration among aquafeed compounders is compressing spot market liquidity for premium-grade fish meal alternatives. Large salmon feed producers in Norway and Chile are negotiating direct offtake agreements with rendering facilities, displacing traditional broker-mediated procurement. This channel consolidation is most visible in Scottish and Norwegian aquaculture supply chains where three compounders control majority volume.
Rendered Products Market Segmentation
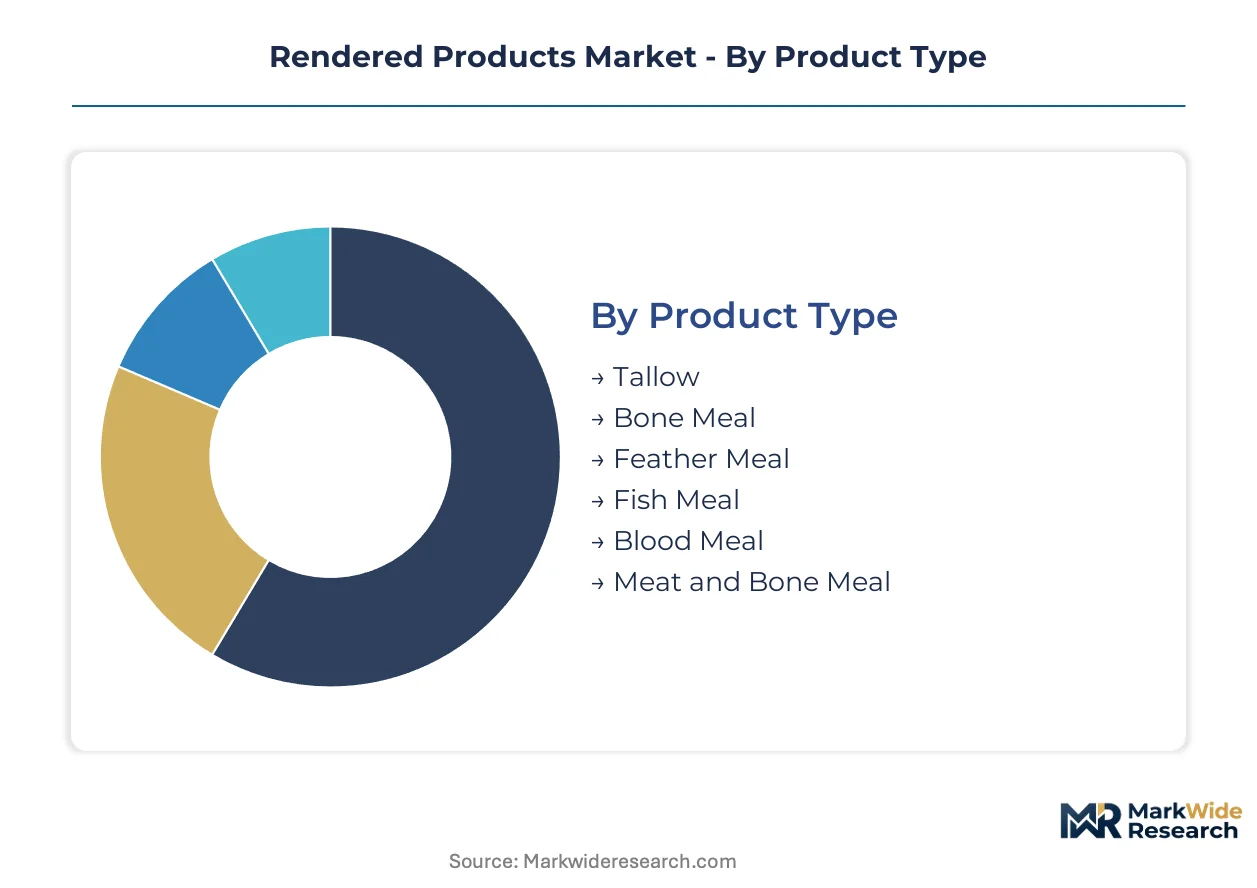
Margin capture in rendered products hinges on specification grade and end-use certification tiers. Procurement patterns diverge sharply between commodity feed channels and premium oleochemical or renewable fuel applications.
Product Type:
Tallow and protein meals anchor divergent margin pools, with industrial fat specifications commanding premiums over standard feed grades.
- Tallow:Rendered bovine fat with free fatty acid content below 15 percent meets biodiesel and oleochemical specifications. Demand concentrates in US renewable diesel facilities under IRA tax credit structures, tightening edible-grade availability for soap manufacturers.
- Fish Meal:Dried and ground whole fish or trimmings retain premium amino acid profiles for aquaculture feeds. Norwegian and Chilean salmon producers negotiate direct offtake agreements, displacing spot market liquidity.
- Feather Meal:Hydrolyzed poultry feathers at temperatures exceeding 140°C yield digestible keratin for shrimp diets.
- Bone Meal:Steamed or rendered bone residue supplies calcium-phosphorus balance in poultry and swine rations.
- Blood Meal:Spray-dried or flash-dried animal blood provides high-protein supplementation with lysine concentration.
- Meat and Bone Meal:Combined rendering of soft tissues and bone generates standardized protein-fat blends for ruminant feed exclusions.
Tallow holds installed capacity. Feather meal is rotating up the share rankings.
Application:
Volume flows concentrate in animal nutrition, while value extraction concentrates in energy and chemical transformation.
- Animal Feed:Protein meals and rendered fats supply amino acid and energy density in poultry, swine, and aquaculture formulations. Southeast Asian shrimp producers accelerate feather meal adoption amid fish meal scarcity.
- Biodiesel Production:Specified tallow with low moisture and impurity levels qualifies for renewable diesel hydrotreating. US Gulf Coast refineries expand tallow offtake under IRA credit mechanisms.
- Personal Care:Cosmetic-grade tallow derivatives emulsify skincare formulations with strict peroxide value limits.
- Soap Making:Saponification-grade tallow provides hardness and lather stability in bar soap manufacturing.
- Fertilizer:Bone meal and blood meal supply organic nitrogen and phosphorus for soil amendment markets.
Animal feed maintains volume dominance. Biodiesel production is climbing the fastest.
End User:
Customer scale determines contract structure, with compounders consolidating procurement against fragmented livestock operations.
- Feed Manufacturers:Aquafeed compounders in Norway, Chile, and Vietnam negotiate multi-year protein meal agreements. Three salmon feed producers control majority volume in Scottish and Norwegian supply chains.
- Industrial Chemical Producers:Oleochemical manufacturers source specified tallow for fatty acid and glycerin production.
- Livestock Farmers:Backyard and small-scale operations purchase bagged bone meal and blood meal through distributor networks.
- Cosmetic Companies:Personal care formulators require cosmetic-grade tallow with enhanced color and odor specifications.
Feed manufacturers hold installed capacity. Industrial chemical producers are gaining share fastest.
Distribution Channel:
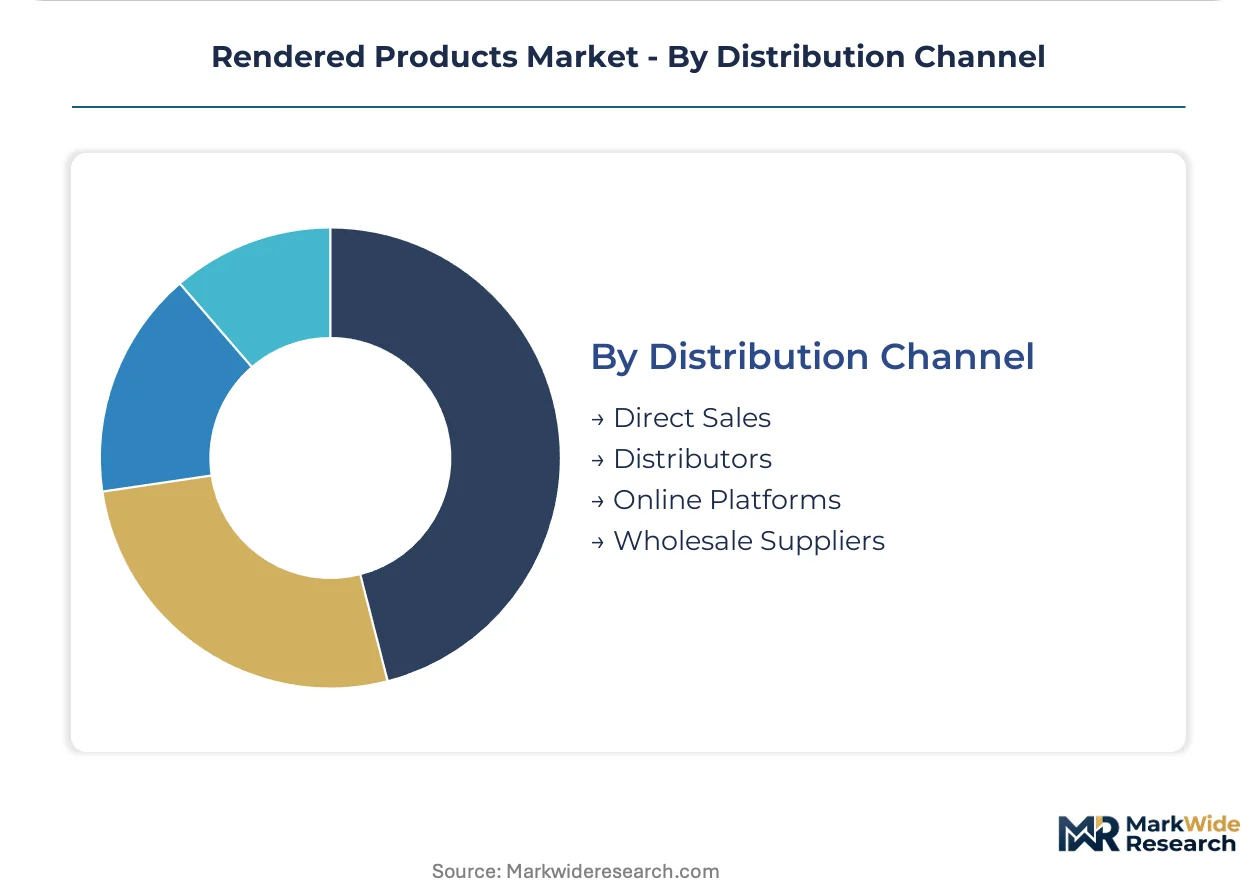
Channel selection tracks shipment scale and specification sensitivity, with bulk tallow favoring direct logistics.
- Direct Sales:Integrated packers deliver tanker-load tallow directly to biodiesel refineries and oleochemical plants. Tyson Foods and JBS leverage captive rendering capacity for supply continuity.
- Distributors:Regional feed ingredient distributors aggregate protein meals for mid-sized compounders.
- Wholesale Suppliers:Commodity traders intermediate spot market flows for standard-grade bone meal and meat and bone meal.
- Online Platforms:E-commerce channels serve small-scale organic fertilizer and specialty pet food ingredient buyers.
Direct sales holds installed capacity. Distributors is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances for rendered tallow and protein meals tilt toward surplus positions in major livestock-producing nations, while industrial fat deficits concentrate in renewable diesel hubs. Trade flows respond to biodiesel tax credit differentials and aquaculture feed formulation shifts.
United States
Integrated meatpackers in the Midwest and Southeast dominate captive rendering capacity, supplying Gulf Coast renewable diesel facilities under IRA credit structures. The EPA enforces Clean Water Act effluent standards that compress independent processor margins in Nebraska watersheds. Rendering clusters concentrate in Iowa, Kansas, and Texas where Tyson Foods and JBS operate slaughterhouse-adjacent facilities.
Brazil
Protein processing consolidation among three integrated packers limits merchant access to specified risk material streams for export. ANVISA feed safety regulations govern animal by-product classification for international shipment eligibility. São Paulo and Mato Grosso host the densest rendering infrastructure tied to beef and poultry slaughter complexes.
China
Centralized livestock processing mandates under agricultural modernization programs expand industrial rendering capacity in Henan and Sichuan provinces. The country's national agricultural regulator enforces waste-to-feed conversion standards that displace informal processing operations. Yangtze River Delta clusters absorb premium tallow flows for oleochemical manufacturing.
Germany
The EU Green Deal's circular economy action plan accelerates rendering infrastructure grants for food waste valorization projects. EFSA feed safety classifications determine cross-border protein meal acceptance for aquaculture compounders. Rendering facilities concentrate in Lower Saxony and North Rhine-Westphalia near dense livestock operations.
India
FSSAI feed safety regulations formalize animal by-product processing standards, opening organized sector investment in currently informal rendering operations. Poultry sector expansion in Telangana and Tamil Nadu generates feather meal supply for shrimp feed exporters. Gujarat and Maharashtra clusters develop toward export-oriented tallow refining.
Rendered Products Market Key Industry Players
Concentration sits with integrated protein packers that have captured rendering capacity within slaughterhouse complexes. Independent merchant renderers face compressed margins as captive supply chains lock up tallow and protein meal flows. Three archetypes define competitive positioning: integrated meatpackers with backward integration into by-product processing, specialized rendering operators with collection network scale, and diversified ingredients companies spanning multiple protein conversion technologies. Dominant competitive moves include capacity consolidation through asset acquisitions and geographic expansion into emerging livestock processing regions.
Among North American integrated packers, Tyson Foods Inc. and JBS S.A. exemplify the slaughterhouse-to-rendered-product model, while Darling Ingredients Inc. occupies a position as a specialized renderer with collection infrastructure spanning multiple protein-producing regions. These three anchors illustrate how scale and supply chain control differentiate competitive outcomes.
| Leading Market Players |
|---|
| Cargill |
| Maple Leaf Foods |
| Tyson Foods Inc. |
| Valley Proteins Inc. |
| Sanimax |
| JBS S.A. |
| Smithfield Foods |
| Seaboard Corporation |
| Darling Ingredients Inc. |
| Others |
Cost & Logistics Intelligence
Thirty-to-forty-five day tallow inventory cycles at US Gulf Coast renewable diesel facilities concentrate pricing power among integrated packers with slaughterhouse-adjacent rendering assets. This lead-time compression amplifies margin capture for Tyson Foods and JBS while squeezing independent merchant renderers unable to match supply continuity guarantees.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with specified tallow grades commanding premiums over standard feed-fat tiers based on free fatty acid certification and renewable fuel qualification under IRA mechanisms. Price differentiation hinges on biodiesel tax credit eligibility and oleochemical purity specifications. Cost compression in commodity bone meal channels is intensifying because Brazilian protein packers lock up risk material streams for captive processing. Aquafeed compounders show least price sensitivity due to fish meal scarcity, while small-scale organic fertilizer buyers exhibit highest sensitivity to bagged protein meal fluctuations.
Supply Chain Analysis
Strategic stockpile preferences dominate tallow procurement, with renewable diesel refineries maintaining 60-90 day coverage against cattle slaughter volatility and drought-driven herd liquidation cycles. Supply concentrates in the United States, Brazil, and China where integrated meatpackers control rendering infrastructure. Raw material flows draw from fat trimmings, poultry feathers, and bovine bones tethered to protein processing volumes. Single-source vulnerability concentrates in Brazilian rendering output among three dominant packers. Distribution runs through direct tanker logistics for industrial tallow and regional distributor networks for protein meals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IRA biodiesel tax credits have transformed rendered tallow into a strategic energy feedstock, creating asymmetric growth exposure for processors with renewable diesel refinery relationships.
For Market Incumbents: Shield margin pools by deepening backward integration into poultry and beef slaughter complexes before independent renderers consolidate. Prioritize EPA effluent compliance investments in Nebraska and Iowa watersheds to preempt regulatory displacement. Lock multi-year offtake agreements with Gulf Coast renewable diesel facilities to secure volume commitments against emerging merchant competitors. For New Entrants and Emerging Players: Differentiate on aquaculture feed certification by building hydrolyzed feather meal capacity in Telangana and Tamil Nadu to serve shrimp feed exporters. Target India's organized sector rendering gap created by FSSAI formalization mandates. Pursue direct sales relationships with Norwegian and Chilean salmon feed compounders bypassing traditional broker channels. For Investors and Strategic Acquirers: Long-term, this sits as a circular-economy infrastructure play because EU Green Deal food waste valorization mandates and China's agricultural modernization program structurally expand addressable rendering capacity. Acquisition candidates include regional collection-network operators with EPA-compliant facilities in underserved watersheds. Monitor IRA tax credit renewal negotiations as the critical policy inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Slaughterhouse Rendering | Tyson Foods and JBS secure captive tallow supply for biodiesel offtakers, compressing merchant competitor access. |
| Anaerobic Digestion Process Integration | Darling Ingredients and Sanimax improve facility energy economics through biogas co-production from wastewater streams. |
| Direct Offtake Agreements with Aquafeed Compounders | Three Norwegian salmon feed producers negotiate multi-year feather meal contracts, displacing spot market liquidity. |
| EPA Biological Nutrient Removal Upgrades | Independent renderers in Nebraska and Iowa face capital-intensive compliance investments under Clean Water Act phosphorus standards. |
| India Organized Sector Rendering Investment | FSSAI feed safety regulations open acquisition targets among informal processors in Telangana poultry clusters. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with rendering plant managers, renewable diesel procurement officers, aquafeed formulation specialists, and EPA compliance consultants; and secondary validation through FDA feed ingredient filings, EPA effluent limitation guidelines, customs trade data on tallow exports, and SEC 10-K disclosures from integrated protein packers. Bottom-up capacity assessments triangulated against top-down demand modeling across animal nutrition, biodiesel, and oleochemical end-uses.
Across the projection horizon, the analytical framework segmented volume and value outputs by product type, application tier, end-user scale, and distribution channel structure. CAGRs derived from regression analysis against cattle slaughter cycles, aquaculture feed formulation shifts, and renewable fuel policy trajectories. Industry-specific forecast inputs incorporated IRA tax credit mechanics and EFSA cross-border protein meal acceptance protocols.
The analysis sits within stated boundaries; outcomes outside sustained biodiesel tax credit structures or accelerated aquaculture demand would require recalibration. Forecasts reflect documented assumptions regarding regulatory stability and raw material availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Spain Sodium Reduction Ingredient Market
Ingredients
Fermentation Ingredient Market
Ingredients
Dark Yeast Extract Market
Ingredients
Ingredients Market
Ingredients
Global Egg Yolk Oil Market
Ingredients
Grape Seed Extracts Market
Ingredients
Hops Derivative Market
Ingredients
Bone and Joint Health Ingredients Market
Ingredients
Truffle Oil Market
Ingredients
Bangladesh Mustard Oil Market
Ingredients
Pea Fiber Market
Ingredients
Cocoa Derivatives Market
Ingredients
Pea Hull Fiber Market
Ingredients
United States Whey Protein Ingredients Market
Ingredients
Edible Oils and Fats Market
Ingredients
Low-Odor Fish Protein Hydrolysates from Med Species Market