
 India Cane Sugar Market | 2026-2036
India Cane Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
India Cane Sugar Market Foresight
Market Context
The F-Gas Regulation is recalibrating capital allocation across India's sugar processing infrastructure by tightening environmental compliance benchmarks for cooling and extraction systems. Balrampur Chini Mills leverages its integrated distillery network to capture ethanol revenue streams alongside crystal sugar output. Bajaj Hindusthan Sugar sustains one of the largest crushing capacities in Uttar Pradesh through continuous mill modernization programs. Shree Renuka Sugars anchors its operations in Karnataka and Maharashtra with port-adjacent refineries serving export channels.
Technical Definition and Segment Structure
India cane sugar denotes sucrose extracted from Saccharum officinarum stalks grown across tropical and subtropical agro-climatic zones, processed through tandem milling, clarification, evaporation, and crystallization stages to yield centrifugal sugar with polarimetric purity exceeding 99.5 percent for refined grades. White sugar dominates institutional procurement from the food industry and beverage industry where standardization and shelf stability command premium contract terms. Brown sugar and jaggery occupy distinct margin pools in retail and e-commerce channels, capitalizing on regional taste preferences and perceived nutritional differentiation in southern and eastern Indian markets.
Regulatory Framework and Outlook
BIS certification mandates govern saccharide purity labeling and food safety protocols, while the CEA and state-level sugar commissioners administer cane pricing floors and ethanol offtake quotas that directly determine mill profitability. DGFT export policies and PLI scheme incentives for biofuel infrastructure are redirecting long-term capacity decisions toward integrated sugar-ethanol complexes. Stakeholders must monitor forthcoming revisions to the national biofuel policy and state ethanol purchase agreements to calibrate crushing schedules and capital deployment across the crop cycle.
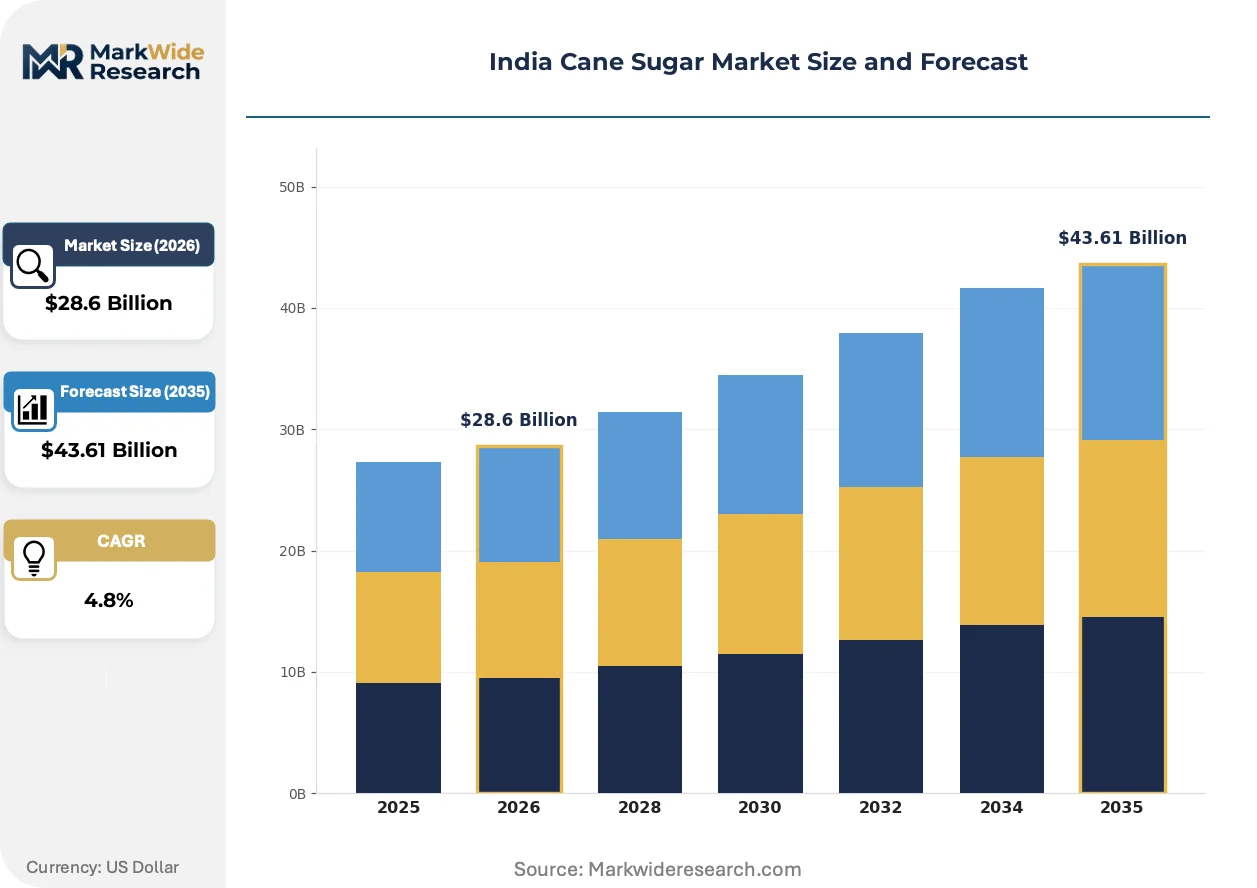
Market Dynamics
Ethanol-blending mandates under India's national biofuel policy are redirecting crushing capacity toward dual-output sugar-ethanol complexes, reshaping mill economics and procurement priorities across Maharashtra and Uttar Pradesh cane belts.
Growth Catalysts
- PLI scheme incentives:Central government production-linked incentives for biofuel infrastructure accelerate distillery capacity additions at integrated sugar complexes.
- F&B institutional procurement:Packaged food manufacturers and beverage bottlers in western India lock in long-term refined sugar contracts for formulation standardization.
- Saccharum officinarum yield improvements:Clonal seed varieties and drip irrigation adoption in tropical agro-climatic zones lift recoverable sucrose per hectare.
Market Restraints
- State-advised cane price floors:CEA-mandated minimum support prices for sugarcane procurement compress mill margins when global sugar prices decline.
- Monsoon dependency:Southwest monsoon variability across the Deccan Plateau and Gangetic plains creates raw material supply instability.
- Jaggery and khandsari substitution:Unrefined traditional sweeteners retain price-sensitive rural demand in eastern and southern Indian markets.
Strategic Opportunities
- Northeastern India penetration:Assam and Bihar cane belts remain underdeveloped for integrated sugar-ethanol infrastructure relative to western India.
- E20 blending timeline:The 2025-2026 ethanol blending target creates assured offtake channels for molasses and grain-based feedstock.
- Port-adjacent refining:Coastal Karnataka and Maharashtra locations enable direct bulk export to Middle East and Southeast Asian buyers.
Industry Challenges
- BIS certification timelines:Polarimetric purity testing and saccharide labeling compliance create batch release bottlenecks for small-scale mills.
- Distillery integration complexity:Legacy sugar-only facilities face capex burdens and process engineering gaps when retrofitting for ethanol output.
- Cane payment arrears:Working capital cycles stretch farmer-mill relationships and disrupt crushing season scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Cane Sugar Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Sugar, Brown Sugar, Organic Sugar, Jaggery End User: Food Industry, Beverage Industry, Confectionery, Bakery Distribution Channel: Wholesale, Retail, E-Commerce, Direct Sales Application: Sweetening, Fermentation, Food Preservation, Culinary Use |
| Companies Covered | Balrampur Chini Mills Ltd, Bajaj Hindusthan Sugar Ltd, Shree Renuka Sugars Ltd, EID Parry India Ltd, Dhampur Sugar Mills Ltd, Triveni Engineering & Industries Ltd, Dalmia Bharat Sugar & Industries Ltd, DCM Shriram Consolidated Limited, Mawana Sugars Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Cane Sugar Market Shifts & Advancements
Automation in clarification and evaporation stages is compressing energy intensity while digital crop monitoring platforms are optimizing harvest-to-crush logistics across dispersed cane collection networks.
Membrane filtration technology is integrating into juice clarification circuits, replacing traditional sulphitation and carbonation steps with cross-flow microfiltration systems. Mid-sized Uttar Pradesh mills adopt these units to reduce lime consumption and improve colour profile consistency. The shift is integrating downstream refinery specifications into front-end milling operations, collapsing quality variance between raw and refined output streams.
The F-Gas Regulation is tightening compliance benchmarks for cooling systems in extraction and crystallization stages, pressuring mills to retrofit refrigeration circuits with lower-global-warming-potential refrigerants. European equipment suppliers now bundle F-Gas-compliant chiller packages with new tandem mill installations. Maharashtra processors face the steepest retrofit timelines given their concentration of vintage crystallization plants.
Food and beverage manufacturers are consolidating supplier bases around integrated sugar-ethanol complexes capable of certifying carbon intensity scores. Large bakery and confectionery chains in Mumbai and Delhi now specify BIS-certified refined sugar with documented ethanol co-product revenue. This procurement consolidation is squeezing standalone raw sugar mills without distillery capacity or third-party carbon accounting.
India Cane Sugar Market Segmentation
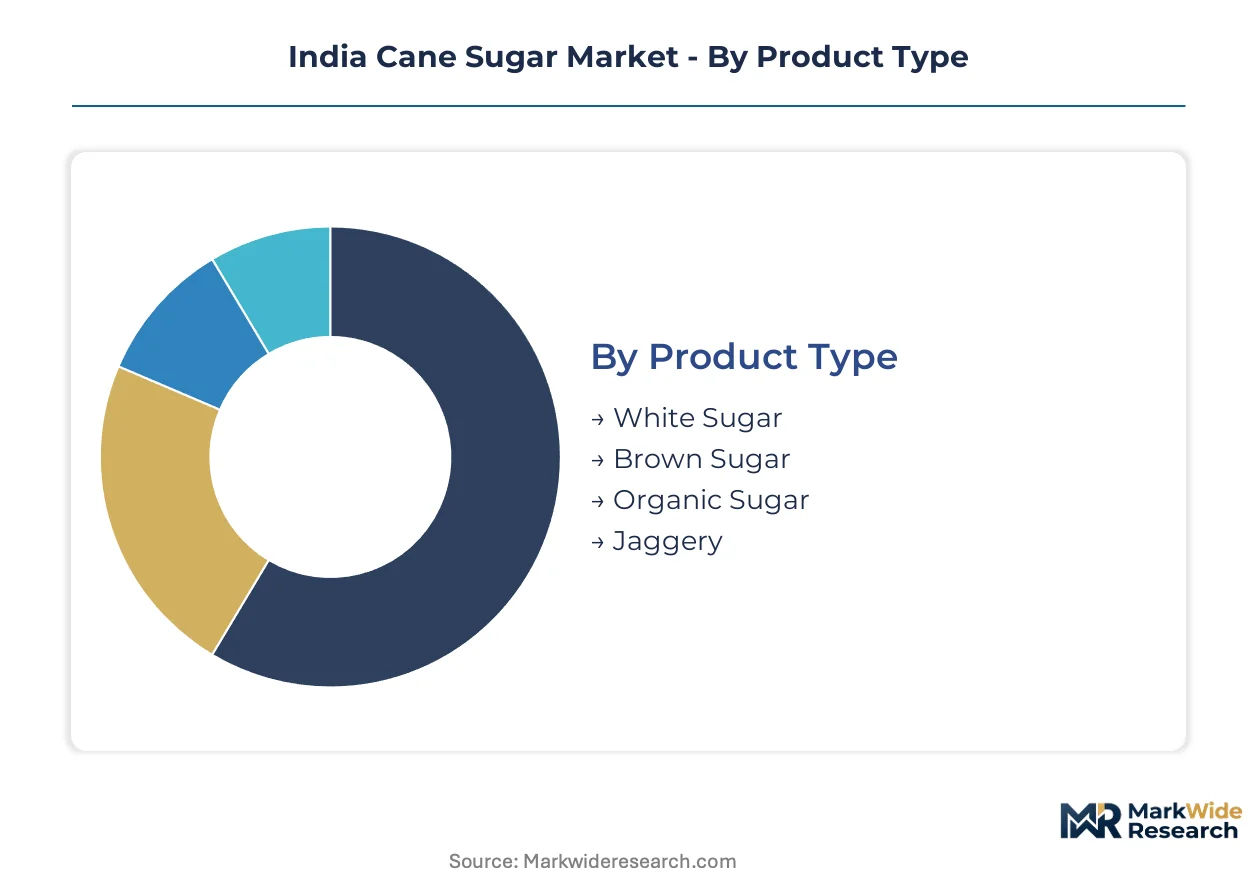
Sugar processors in Maharashtra and Uttar Pradesh configure milling output streams around distinct purity grades and buyer procurement specifications. Segment differentiation determines margin capture, with institutional contracts commanding premiums over spot retail sales.
Product Type:
Buyers in this category separate on formulation requirements and certification standards rather than price sensitivity alone.
- White Sugar:Centrifugal sugar with polarimetric purity exceeding 99.5 percent serves institutional food and beverage manufacturers requiring batch consistency. Maharashtra's integrated sugar-ethanol complexes dominate supply to western India bakery and confectionery chains under long-term contracts.
- Brown Sugar:Retains molasses film coating for moisture retention and caramel flavor notes. Demand concentrates in southern Indian retail channels where consumers perceive nutritional differentiation, though BIS labeling mandates now require explicit sucrose content disclosure.
- Organic Sugar:Cultivated from certified pesticide-free cane with traceable supply chains. Premium positioning targets export channels and urban e-commerce platforms in Delhi and Mumbai.
- Jaggery:Traditional unrefined solid concentrate from open-pan boiling. Eastern India rural markets sustain consumption despite compression from packaged white sugar penetration.
White sugar leads volumes today; organic sugar is gaining share fastest.
End User:
Volume concentration and contract duration vary sharply across buyer categories, with some locking annual procurement and others purchasing spot.
- Food Industry:Packaged food manufacturers in Gujarat and Maharashtra standardize on BIS-certified refined grades for sauce, condiment, and dairy product formulation. Procurement runs through annual tenders with penalty clauses for polarimetric variance.
- Beverage Industry:Soft drink bottlers and fruit juice processors require low-color, low-ash sugar for clarity stability. Uttar Pradesh mills with membrane filtration retrofits capture disproportionate share of this quality-sensitive segment.
- Confectionery:Hard candy and chocolate manufacturers demand specific crystal size distributions for texture control. Smaller batch sizes favor direct mill relationships over wholesale intermediaries.
- Bakery:Bread and biscuit producers balance cost against fermentation performance, with western India industrial bakeries consolidating supplier bases around integrated complexes.
Food industry procurement anchors volume; beverage industry contracts show the steepest expansion trajectory.
Distribution Channel:
Channel selection determines working capital intensity and price realization, with direct relationships capturing margin otherwise lost to intermediaries.
- Wholesale:Aggregators in Kolhapur and Muzaffarnagar mandis consolidate small-lot cane and broker raw sugar to regional refiners. Price discovery follows CEA-advised floor rates with seasonal volatility.
- Retail:Kirana stores and modern trade outlets in tier-2 cities stock 1-5 kg packaged grades. Brand loyalty remains weak; shelf placement and promotional pricing drive selection.
- E-Commerce:Quick commerce platforms in Bangalore and Hyderabad now deliver jaggery and organic specialty grades within hours. Premium positioning offsets logistics costs for low-volume, high-margin SKUs.
- Direct Sales:Large food manufacturers contract directly with mill distilleries for BIS-certified bulk supply. Eliminates intermediary margins and enables carbon intensity documentation for sustainability reporting.
Wholesale channels handle peak volume; direct sales are climbing the fastest.
Application:
Functional requirements in downstream processing create divergent specification demands that mills address through crystallization circuit tuning.
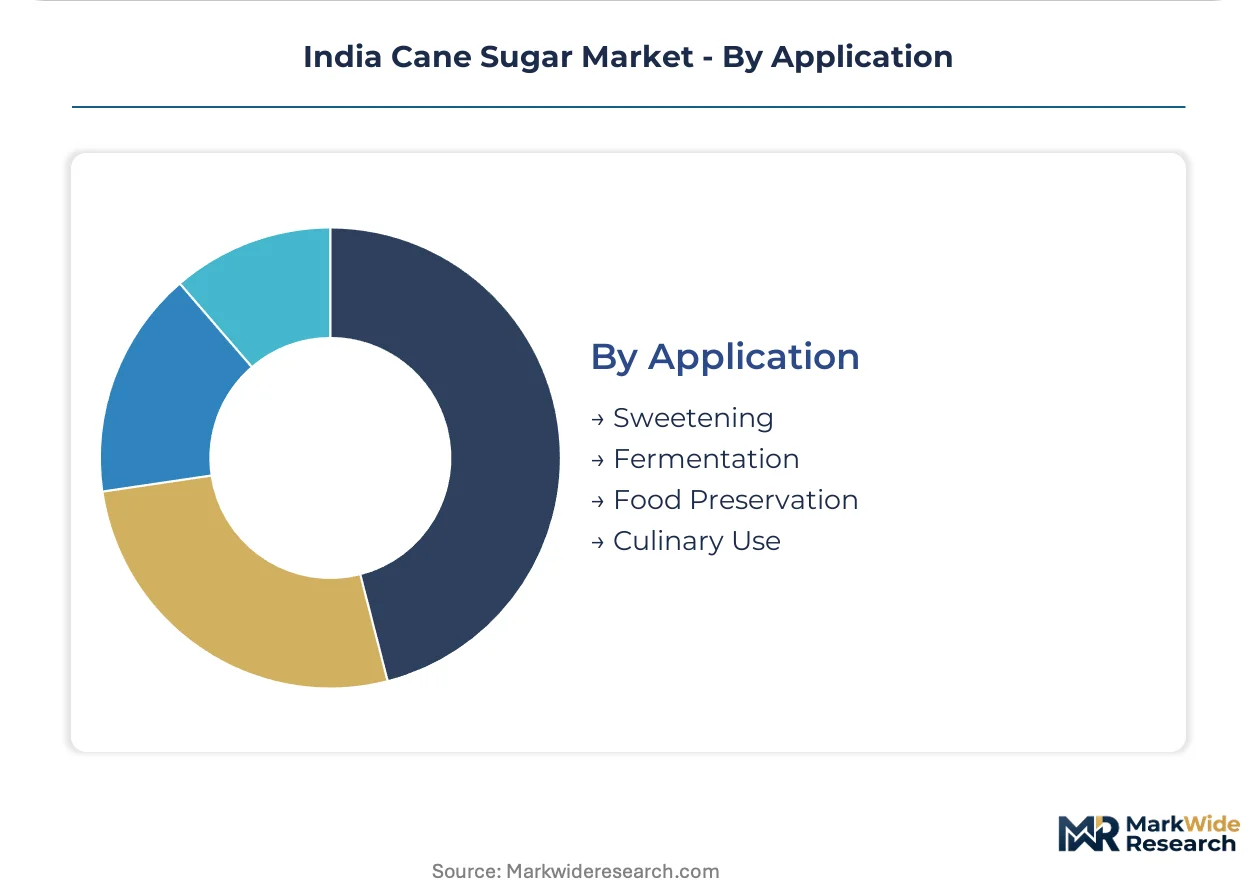
- Sweetening:Standard caloric contribution dominates consumption across all product types. White sugar's neutral flavor profile permits universal deployment without taste interference.
- Fermentation:Ethanol distilleries and yeast manufacturers require specific reducing sugar ratios. Integrated sugar-ethanol complexes in Maharashtra optimize molasses diversion for this captive demand.
- Food Preservation:High osmotic pressure from concentrated sucrose inhibits microbial growth in jams and marmalades. BIS purity mandates ensure consistent preservation performance.
- Culinary Use:Household cooking and traditional sweet preparation sustain jaggery and brown sugar demand. Regional taste preferences in Tamil Nadu and West Bengal resist standardization pressure.
Sweetening applications dominate tonnage; fermentation demand expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sugar processing in India traces its industrial lineage to the British colonial era, when mills first scaled across the Gangetic plains and Deccan plateau. Today the sector concentrates in cane-growing belts where state-level ethanol policies and BIS certification infrastructure determine regional competitiveness.
Maharashtra
Western Maharashtra's sugar belt anchors India's integrated sugar-ethanol complex density, with Kolhapur and Sangli districts hosting the highest concentration of distillery-attached mills. The state's ethanol purchase agreements under its biofuel policy redirect molasses toward fuel-blending offtake. Pune-based processors leverage proximity to Mumbai's food manufacturing corridor for direct institutional supply contracts.
Uttar Pradesh
The Ganga-Yamuna doab sustains India's largest crushing capacity, where Muzaffarnagar and Meerut districts cluster legacy mills modernizing for dual-output models. CEA-mandated state advised prices for cane procurement structure mill-farmer payment cycles. Lucknow's regulatory orbit shapes compliance timelines for polarimetric purity certification across northern plains operations.
Karnataka
Tropical agro-climatic conditions in Belagavi and Mandya districts yield recoverable sucrose rates exceeding northern averages. The state's port-adjacent refineries at Mangalore enable direct bulk export to Middle Eastern buyers. Bangalore's quick-commerce platforms drive e-commerce penetration for organic and specialty grade distribution.
Gujarat
Surat and Vadodara industrial corridors anchor food industry demand, with packaged food manufacturers standardizing on BIS-certified refined grades for sauce and dairy formulation. The state's chemical processing infrastructure supports fermentation-grade sugar output for pharmaceutical applications. Ahmedabad's procurement offices consolidate annual tender volumes from western India mills.
Tamil Nadu
Traditional jaggery production in Cuddalore and Villupuram districts resists standardization pressure from packaged white sugar penetration. Regional taste preferences sustain brown sugar demand through retail kirana networks. Chennai's modern trade outlets experiment with quick-commerce delivery for specialty unrefined grades targeting urban consumers.
India Cane Sugar Market Competitive Landscape
The competitive structure tilts toward integrated sugar-ethanol complexes with distillery capacity and BIS certification infrastructure. Large-scale Uttar Pradesh and Maharashtra operators squeeze standalone raw sugar mills through procurement consolidation around carbon-documented supply chains. Two archetypes dominate: vertically integrated mill-distillery complexes and regionally concentrated raw sugar specialists. Competitive moves center on distillery retrofit capex cycles and direct contract relationships with food manufacturers.
Among Uttar Pradesh-based operators, Balrampur Chini Mills Ltd and Bajaj Hindusthan Sugar Ltd exemplify the integrated complex archetype with distillery networks capturing ethanol revenue streams. Shree Renuka Sugars Ltd anchors the coastal refinery position with port-adjacent operations serving export channels. These three represent divergent geographic and operational strategies within the sector's consolidation trajectory.
| Leading Market Players |
|---|
| Balrampur Chini Mills Ltd |
| Bajaj Hindusthan Sugar Ltd |
| Shree Renuka Sugars Ltd |
| EID Parry India Ltd |
| Dhampur Sugar Mills Ltd |
| Triveni Engineering & Industries Ltd |
| Dalmia Bharat Sugar & Industries Ltd |
| DCM Shriram Consolidated Limited |
| Mawana Sugars Limited |
| Others |
Supply & Pricing Matrix
Food and beverage manufacturers in western India anchor procurement volume and enforce contract-based long-term offtake pricing with penalty clauses for polarimetric variance, compressing spot market premiums and squeezing standalone mills without distillery capacity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified refined grades from membrane-filtered beverage-grade sugar and unstandardized raw output. Price differentiation hinges on certification tier and volume scale, with institutional buyers locking annual tenders at fixed rates. Cost compression in economy-tier raw sugar is intensifying because jaggery substitution retains price-sensitive rural demand. Small-scale khandsari producers show highest price sensitivity; integrated sugar-ethanol complexes with carbon documentation command least.
Supply Chain Analysis
Single-source vulnerability sits with Maharashtra and Uttar Pradesh cane belts, where over two-thirds of crushing capacity clusters within 200 kilometers of Kolhapur and Muzaffarnagar districts. Raw material flows draw from clonal seed varieties and drip-irrigated Saccharum officinarum plantations tethered to monsoon-dependent water availability. Logistics chokepoint risk concentrates at state-mandated cane collection centers during peak crushing windows. Distribution runs through wholesale mandi aggregators for spot sales and direct mill relationships for institutional contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India cane sugar has entered a late-cycle quality phase where BIS-certified refined grades with documented ethanol co-product revenue capture expanding share from food manufacturers consolidating supplier bases.
For Market Incumbents: Lock in direct procurement relationships with Mumbai and Delhi bakery chains before membrane filtration retrofits diffuse quality advantages across Uttar Pradesh competitors. Prioritize distillery capacity additions to defend against standalone raw sugar mills facing margin compression from procurement consolidation. Channel control through port-adjacent refining positions serves export offtake to Middle Eastern buyers. For New Entrants and Emerging Players: The premium-to-economy price gap in northeastern Assam and Bihar cane belts offers white-space entry with underdeveloped integrated sugar-ethanol infrastructure relative to western India. Target quick-commerce distribution for organic and jaggery specialty grades in Bangalore and Hyderabad urban corridors. Go-to-market leverage rests on traceable supply chains certifying pesticide-free cultivation for export channels. For Investors and Strategic Acquirers: Food and beverage conglomerates with downstream formulation operations are the most active acquirer in this space, seeking backward integration into captive sucrose supply. Long-term viability favors integrated mill-distillery complexes with existing BIS certification infrastructure and ethanol purchase agreements under state biofuel policies. Watch E20 blending timeline adherence as inflection signal for molasses offtake channel security.| Strategic Initiative | Industry Significance |
|---|---|
| Distillery Capacity Expansion | Captures ethanol revenue streams alongside crystal sugar output under PLI scheme incentives. |
| Membrane Filtration Retrofit | Reduces lime consumption and improves colour profile consistency for beverage industry contracts. |
| Direct Sales Channel Development | Eliminates intermediary margins and enables carbon intensity documentation for sustainability reporting. |
| Port-Adjacent Refining Investment | Positions bulk export capability to Middle Eastern and Southeast Asian buyers through Mangalore. |
| Clonal Seed Variety Adoption | Lifts recoverable sucrose per hectare across tropical agro-climatic zones in Karnataka and Maharashtra. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with sugar mill operations managers, CEA regulatory officers, food industry procurement leads, and wholesale mandi aggregators with secondary validation from BIS certification records, DGFT export policy circulars, state sugar commissioner crushing data, and CEA-advised price notifications. Bottom-up mill capacity aggregation and top-down ethanol blending target reconciliation anchored volume estimates.
Historical reference periods spanning pre- and post-PLI scheme implementation anchored the forecast window to capture policy-driven capacity reallocation. Segmentation modeling addressed product type purity grades, end-user contract structures, distribution channel working capital intensity, and regional ethanol policy frameworks. CAGRs derived from fitted trend extrapolation moderated by cane payment cycle volatility and monsoon deviation patterns across the Deccan Plateau and Gangetic plains.
The model assumes a particular technology adoption path; alternative pathways for membrane filtration diffusion or F-Gas Regulation compliance retrofit timelines would alter the outlook. Forecasts reflect assumptions on state-advised cane price floor stability and national biofuel policy continuity, with monsoon variability and export policy shifts as primary revision triggers. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Dry Molasses Market
Sweeteners
Sugar-Free Syrups Market
Sweeteners
Sucrose Esters Market
Sweeteners
Stevia Market
Sweeteners
Starch Glucose Syrup Market
Sweeteners
South Korea Allulose Market
Sweeteners
Global Alternative Sweeteners Market
Sweeteners
Europe Sugar Substitute Market
Sweeteners
Australia Allulose Market
Sweeteners
Corn Syrup Market
Sweeteners
China Food Sweetener Market
Sweeteners
Natural Sweetener Blends Market
Sweeteners
Europe Plant-Derived and Synthetic Sugar Market
Sweeteners
Monk Fruit Sugar Market
Sweeteners
Isomaltulose Market
Sweeteners
Compressible Sugar Market